
 Brazil POS Terminal Market | 2026-2036
Brazil POS Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil POS Terminal Market Outlook
Food service and hospitality is realigning Brazil's POS terminal procurement priorities as tableside payment and delivery-app integration become standard expectations. Gertec Brasil leverages its domestic manufacturing footprint to compete on cost and local service responsiveness. PAX Technology specializes in Android-based terminal architectures that support rapid software customization for Brazilian payment rails. Stone anchors its position through vertical integration into merchant acquiring, bundling terminals with transaction processing contracts.
A POS terminal is an electronic device combining secure encryption modules, card-reading interfaces, and network connectivity to authenticate and route payment transactions at the point of sale, typically processing data through PCI-certified hardware with tamper-evident enclosures. Mobile POS and NFC-enabled terminals are capturing disproportionate growth as micro-merchants and street vendors adopt low-cost, smartphone-connected readers; fixed POS remains the margin pool for enterprise deployments in retail and grocery, where durability and multi-lane throughput justify higher hardware investment. Tablet POS is gaining traction in hospitality for its flexibility in splitting checks and integrating with kitchen display systems.
ANVISA regulates electromagnetic emissions and safety certifications for electronic payment devices sold in Brazil, while the Central Bank of Brazil governs PIX interoperability standards and terminal compliance mandates that shape hardware refresh timelines. The Lei Geral de Proteção de Dados imposes data-handling obligations on transaction processors, indirectly influencing terminal encryption and local-storage specifications. Stakeholders must monitor whether open-banking APIs and emerging central bank digital currency pilots will require fundamental architecture changes in terminal software stacks.
Market Dynamics
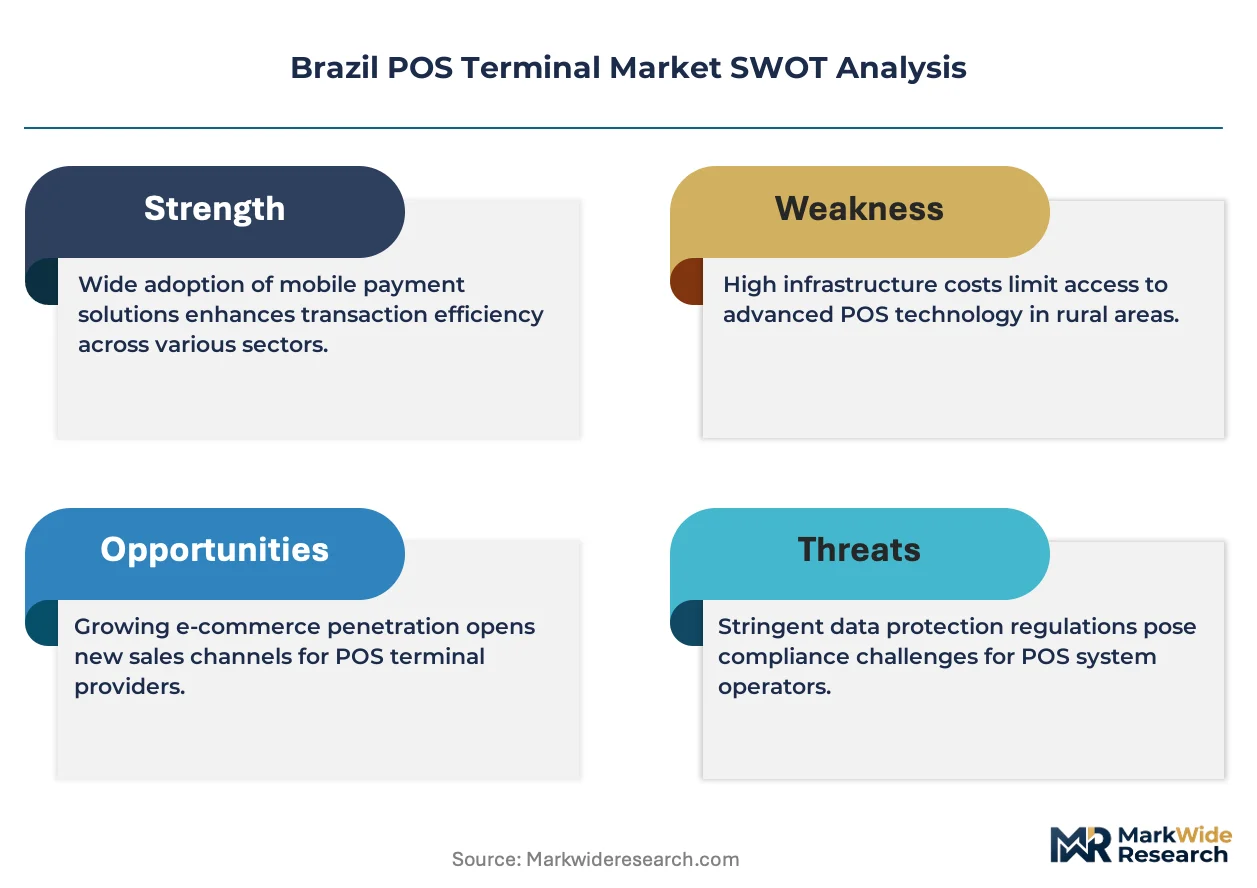
PIX instant payment integration mandated by Brazil's central bank is compressing hardware replacement cycles and forcing terminal architecture redesigns across merchant acquiring networks. This regulatory pressure is restructuring competitive positioning among domestic manufacturers and international suppliers.
Growth Catalysts
- PIX Mandate:Brazil's central bank interoperability requirements are accelerating terminal refresh timelines among mid-sized retailers upgrading from legacy magstripe systems.
- Contactless Infrastructure:Supermarket and hypermarket chains are expanding NFC-enabled checkout lanes across São Paulo and Rio de Janeiro metropolitan corridors.
- Street Vendor Digitization:Micro-merchants are adopting smartphone-connected mobile POS readers to accept instant payments without traditional banking relationships.
Market Restraints
- Import Dependency:Secure encryption module supply concentrates among Asian semiconductor foundries, exposing Brazilian assemblers to shipping volatility and currency fluctuation.
- Certification Bottleneck:ANVISA electromagnetic emissions testing and Central Bank PIX compliance create extended approval timelines that delay product launches by quarters.
- Hardware Margin Compression:Low-cost Android terminal architectures are commoditizing fixed POS equipment, squeezing profitability for enterprise-grade manufacturers.
Strategic Opportunities
- Northeast Penetration:Underbanked regions outside the Southeast corridor present expansion potential for mobile POS deployment among informal commerce clusters.
- Open Banking Convergence:Emerging central bank digital currency pilots and API standardization may require fundamental software stack redesigns, creating service revenue pools.
- Hospitality Vertical:Tableside payment and delivery-app integration are becoming standard expectations in food service, driving tablet POS demand for check-splitting flexibility.
Industry Challenges
- Firmware Integration Complexity:Legacy terminal estates require costly middleware development to bridge PIX protocols with existing merchant management systems.
- Specialized Engineering Scarcity:PCI-certified hardware design and local data-handling expertise under Lei Geral de Proteção de Dados outpaces domestic talent pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil POS Terminal Market |
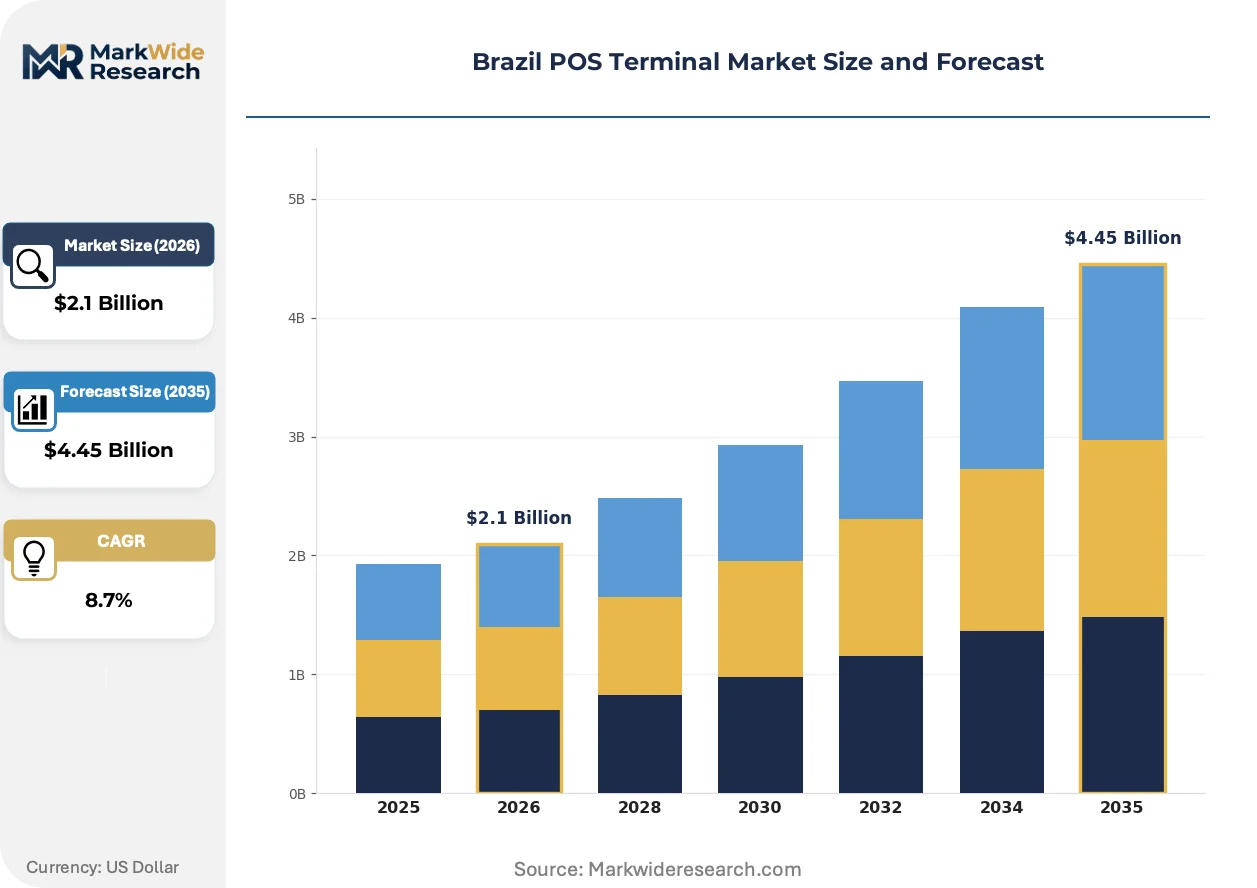
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed POS, Mobile POS, Tablet POS, Self-Service Kiosk Technology: Magstripe, Chip & PIN, NFC, QR Code End User: Retail, Hospitality, Entertainment, Healthcare Deployment: On-Premise, Cloud-Based, Hybrid, Proprietary |
| Companies Covered | Gertec Brasil, NEC Corporation, NCR Corporation, Castles Technology, Worldline, Ingenico, PAX Technology, Stone, VeriFone, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil POS Terminal Market Strategic Shifts
Software-defined payment architectures are displacing fixed-function hardware across Brazilian merchant tiers. Terminal vendors are racing to embed PIX-native processing and cloud-managed security updates before open-banking APIs reshape integration requirements.
Android-based terminal operating systems are rewriting how payment applications deploy in Brazil. Food service operators and retail chains are adopting these platforms for rapid customization of loyalty programs and split-payment workflows. The flexibility is compressing traditional hardware refresh cycles from five years to under thirty-six months.
Lei Geral de Proteção de Dados enforcement is tightening data-handling obligations on transaction processors. Terminal manufacturers must now engineer local-storage encryption and audit-log capabilities directly into hardware specifications. Mid-sized retailers in the Southeast are prioritizing certified devices to avoid penalty exposure.
Merchant acquiring bundles are displacing standalone terminal procurement across Brazilian retail. Stone and competing acquirers are subsidizing hardware costs in exchange for long-term processing commitments. Micro-merchants and street vendors in São Paulo are the primary conversion segment, accepting locked-in contracts for zero upfront equipment investment.
Brazil POS Terminal Market Segmentation
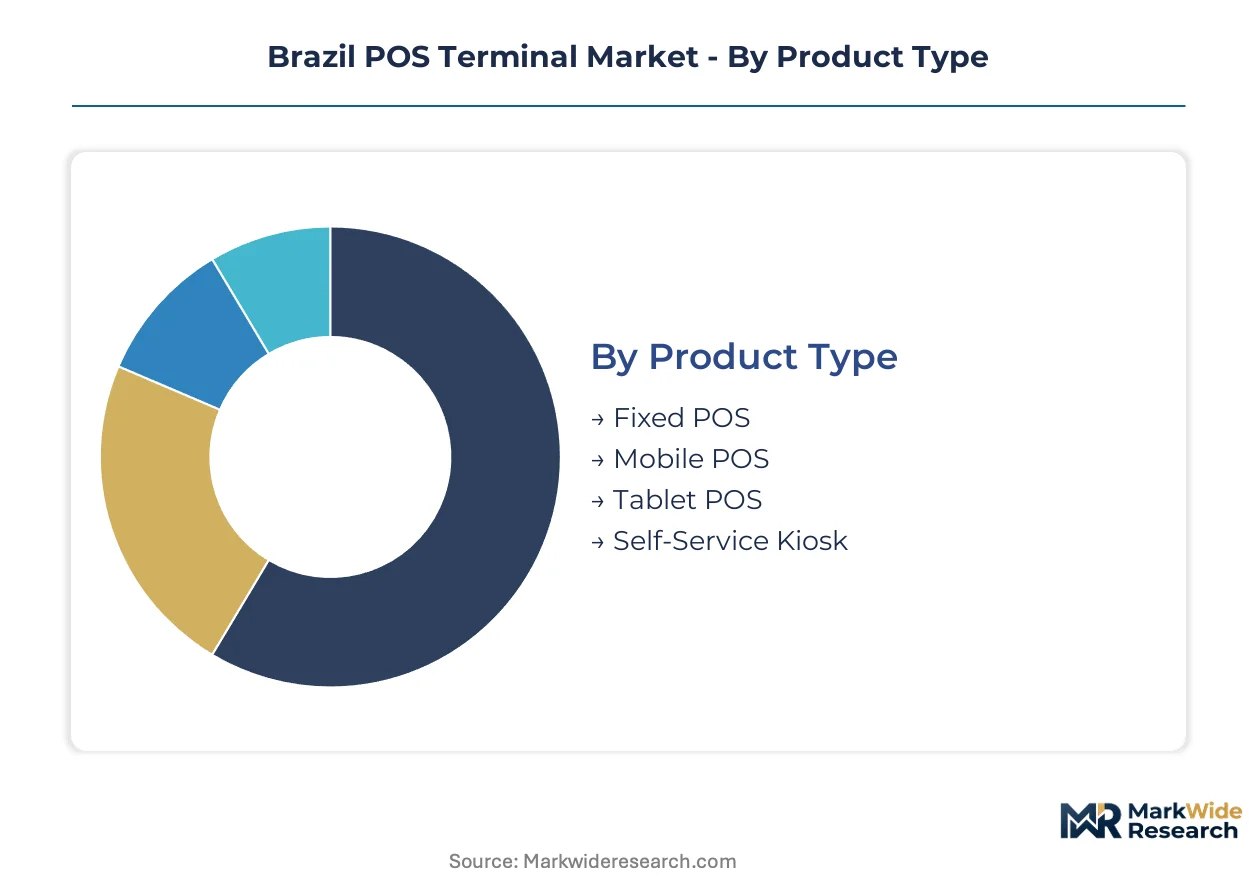
Segmentation in Brazil's POS terminal market reveals how payment infrastructure fragments across merchant tiers and technical requirements. Understanding these divisions exposes where PIX mandates, contactless adoption, and software-defined architectures concentrate commercial leverage.
Product Type:
Standalone countertop units dominate high-volume checkout lanes, while smartphone-connected and embedded systems serve micro-merchant mobility requirements.
- Fixed POS:Ruggedized terminals with tamper-evident enclosures process multi-lane throughput in São Paulo supermarket chains. Grocery and hypermarket operators in Rio de Janeiro prioritize these units for durability under continuous operation, though five-year refresh cycles now compress to thirty-six months under PIX compliance pressure.
- Mobile POS:Compact readers tether to smartphones via Bluetooth, enabling street vendors in informal commerce clusters to accept instant payments without traditional banking relationships. Northeast penetration lags Southeast adoption, creating expansion headroom among underbanked merchant populations.
- Tablet POS:Flexible Android-based platforms support check-splitting workflows and kitchen display integration for food service operators.
- Self-Service Kiosk:Unattended terminals deploy in entertainment venues and transit hubs for queue reduction.
Fixed POS leads volumes today; Mobile POS is gaining share fastest.
Technology:
Authentication methods stratify by security certification tier and merchant risk exposure under Central Bank of Brazil oversight.
- Magstripe:Legacy swipe-reading interfaces persist in budget-conscious merchant estates but face accelerated replacement under PIX interoperability mandates. Mid-sized retailers across the Southeast corridor are retiring these systems to avoid compliance penalties.
- Chip & PIN:EMV-compliant contact insertion dominates enterprise retail for transaction security and chargeback protection. Supermarket chains upgrading from magstripe infrastructure prioritize these terminals for PCI-certified hardware requirements.
- NFC:Contactless tap-to-pay interfaces expand across São Paulo and Rio de Janeiro metropolitan checkout lanes.
- QR Code:Camera-based PIX authentication enables zero-hardware payment acceptance for micro-merchants.
Chip & PIN holds the largest installed base; NFC shows the steepest expansion trajectory.
End User:
Vertical-specific workflows dictate terminal form factor priorities and software integration depth.
- Retail:High-throughput fixed terminals with barcode scanning and inventory system integration serve grocery and department store operators. Southeast region concentration drives procurement volume, with merchant acquiring bundles displacing standalone hardware purchases.
- Hospitality:Tableside payment expectations and delivery-app integration reshape procurement toward tablet POS flexibility. Food service operators prioritize split-check capabilities and kitchen display system connectivity.
- Entertainment:Self-service kiosks and mobile readers serve event venues and cinema chains.
- Healthcare:Encrypted terminals with audit-log capabilities address Lei Geral de Proteção de Dados compliance for patient payment processing.
Retail commands the greatest terminal volume; Hospitality is climbing the fastest.
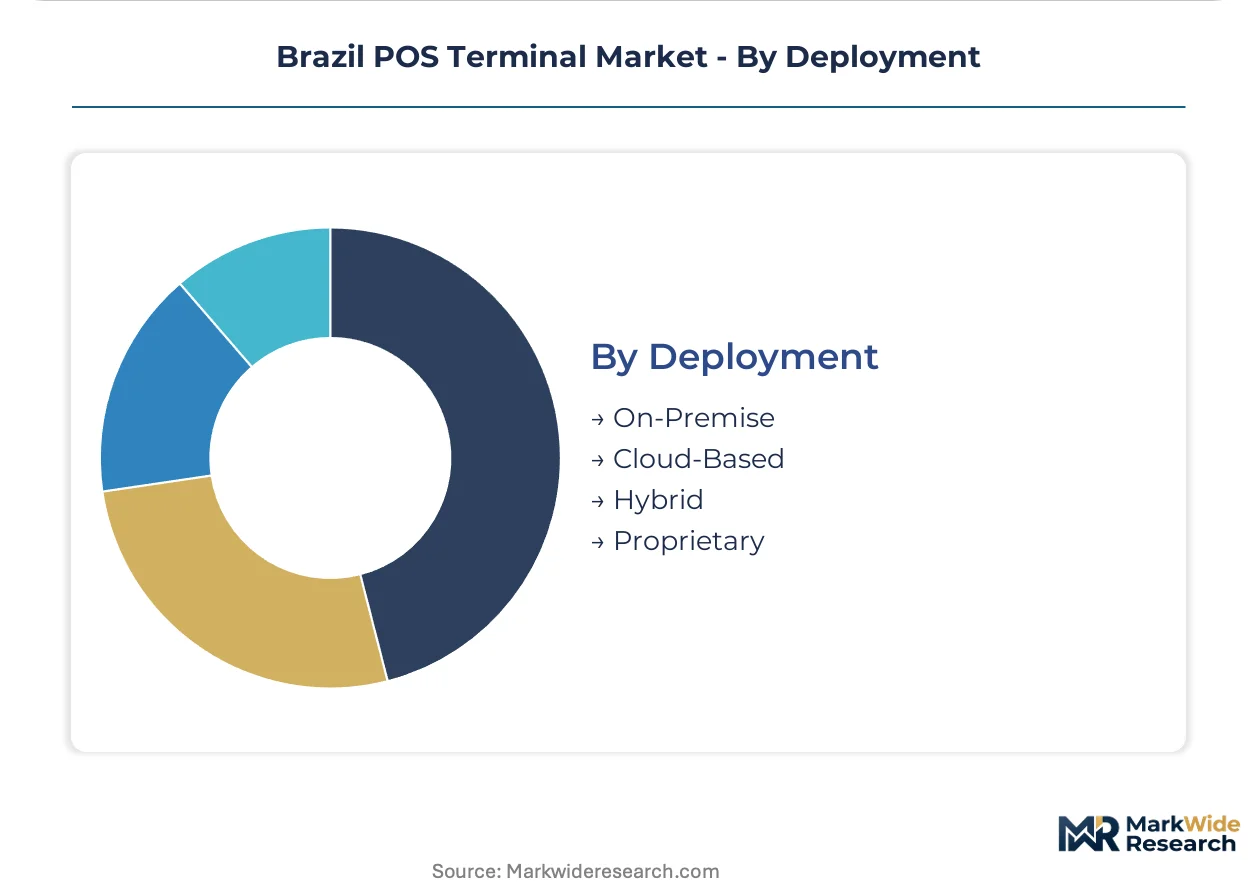
Deployment:
Infrastructure control models separate merchants requiring data sovereignty from those prioritizing operational flexibility.
- On-Premise:Local server architectures retain transaction data within merchant facilities, satisfying Lei Geral de Proteção de Dados local-storage obligations. Mid-sized retailers in the Southeast prioritize these deployments for penalty avoidance.
- Cloud-Based:Remote-managed terminals enable rapid software updates and PIX protocol patches without on-site intervention. Micro-merchants and street vendors favor zero-upfront subscription models bundled with acquiring services.
- Hybrid:Split architectures process sensitive authentication locally while routing reporting to cloud infrastructure.
- Proprietary:Closed-system deployments serve large merchants with captive IT development resources.
On-Premise retains the dominant share; Cloud-Based is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration within Brazil tracks regulatory cost differentials between states. ANVISA certification timelines and Central Bank PIX compliance burdens concentrate assembly in manufacturing zones with established testing infrastructure, while procurement demand clusters in high-transaction-density metropolitan corridors.
São Paulo
Supermarket and hypermarket chains drive fixed POS terminal procurement across the metropolitan region. ANVISA electromagnetic emissions testing facilities in São Paulo state accelerate product approval timelines for domestic assemblers. The São Paulo-Rio de Janeiro corridor concentrates merchant acquiring bundle distribution, with Stone and competing processors subsidizing hardware deployment among mid-sized retailers upgrading from magstripe systems.
Rio de Janeiro
Contactless checkout infrastructure expansion in Rio de Janeiro's retail corridors fuels NFC-enabled terminal demand. The Central Bank of Brazil's PIX interoperability mandates compress hardware refresh cycles among hospitality operators in Copacabana and Ipanema beachfront zones. Tablet POS adoption accelerates in food service clusters where tableside payment and delivery-app integration have become standard expectations.
Minas Gerais
Belo Horizonte's commercial centers anchor fixed POS deployment among regional retail chains. LGPD data-handling obligations shape terminal encryption specifications for healthcare payment processing in the state's hospital network. Manufacturing subcontractors in the state's industrial parks assemble encryption modules for Southeast corridor distribution.
Rio Grande do Sul
Porto Alegre's merchant base exhibits above-average mobile POS penetration among street vendors and informal commerce clusters. Micro-merchants adopt smartphone-connected readers to accept PIX instant payments without traditional banking relationships. The state's southern location creates logistics advantages for hardware importation through Rio Grande port facilities.
Bahia
Northeast underpenetration presents expansion headroom for mobile POS deployment in Salvador's informal commerce zones. ANVISA certification bottlenecks delay product launches in regions distant from Southeast testing infrastructure. Street vendor digitization campaigns concentrate in coastal tourism corridors where instant payment acceptance reduces cash-handling risk.
Brazil POS Terminal Market Competitive Environment
Merchant acquiring bundle subsidies dominate the current landscape as processors capture terminal procurement decisions through processing contract lock-in. The vendor base stratifies across three tiers: domestic manufacturers with ANVISA-certified assembly lines, international hardware specialists with Android-based architectures, and vertically integrated acquirers bundling hardware with transaction processing. Strategic archetypes include cost-competitive local assemblers, software-flexible platform providers, and acquiring-integrated full-stack operators. M&A activity and backward integration into captive hardware supply chains represent the dominant competitive moves reshaping positioning.
Among domestic manufacturers, Gertec Brasil occupies the cost-responsive archetype through its Brazilian assembly footprint and local service infrastructure. PAX Technology exemplifies the software-flexible platform provider, specializing in Android-based terminal architectures that support rapid customization for Brazilian payment rails. Stone anchors the acquiring-integrated tier through merchant acquiring bundles that subsidize terminal costs in exchange for long-term processing commitments.
| Leading Market Players |
|---|
| Gertec Brasil |
| NEC Corporation |
| NCR Corporation |
| Castles Technology |
| Worldline |
| Ingenico |
| PAX Technology |
| Stone |
| VeriFone |
| Others |
Value Chain & Pricing Dynamics
Lei Geral de Proteção de Dados enforcement gates qualified supply and premium-tier pricing access, as terminal manufacturers must embed local-storage encryption and audit-log capabilities to serve mid-sized retailers in the Southeast corridor. This compliance burden stratifies vendor tiers, with ANVISA-certified domestic assemblers commanding price premiums over import-dependent competitors exposed to currency fluctuation.
Pricing Analysis
Distributor margins compress as merchant acquiring bundles displace standalone terminal procurement across Brazilian retail. Three-tier pricing structure across premium, standard, and economy levels separates PCI-certified fixed POS from Android-based mobile readers and QR-code-only acceptance solutions. Price differentiation hinges on certification grade and volume scale, with enterprise grocery chains least sensitive and street vendors most responsive to upfront equipment subsidies. Pricing pressure stems from low-cost Android terminal architectures commoditizing hardware, squeezing profitability for manufacturers serving the enterprise tier.
Supply Chain Analysis
Workforce availability in São Paulo state's industrial parks anchors domestic assembly, while secure encryption module production concentrates in Taiwan and South Korea. Brazilian terminal manufacturing draws from Asian semiconductor foundries for encryption chips, domestic plastics molding for enclosures, and regional logistics hubs for Southeast corridor distribution. Single-source vulnerability in encryption module supply exposes assemblers to shipping volatility and currency fluctuation. Distribution runs through merchant acquiring networks that bundle hardware subsidies with processing contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's POS terminal market functions as a stable compounder, with PIX mandate-driven replacement cycles ensuring sustained hardware refresh demand across merchant tiers.
For Market Incumbents: Acquire software development capabilities to bridge PIX protocol integration with legacy merchant management systems. Stone and competing acquirers should deepen backward integration into captive encryption module supply chains to offset Asian foundry dependency. Certification investment in ANVISA testing infrastructure defends position against import-dependent challengers facing approval bottlenecks. For New Entrants and Emerging Players: Begin with mobile POS deployment in Salvador's informal commerce zones, where Northeast underpenetration and street vendor digitization campaigns create expansion headroom. Target micro-merchants accepting locked-in processing contracts for zero-upfront equipment investment. Partner with local fintechs for PIX-native software stacks rather than building proprietary middleware. For Investors and Strategic Acquirers: Roll-up economics work for domestic assembly specialists because ANVISA certification timelines and Central Bank compliance burdens create defensive moats against international competitors. Five-to-ten year viability rests on open-banking API convergence and potential central bank digital currency pilots requiring software stack redesigns. Watch for central bank digital currency pilot announcements as inflection indicators for terminal architecture investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Encryption Modules | Reduces Asian foundry dependency for Gertec Brasil and domestic assemblers. |
| Android Platform Standardization | Enables PAX Technology to support rapid PIX customization for Brazilian payment rails. |
| Merchant Acquiring Bundle Expansion | Stone captures terminal procurement decisions through processing contract lock-in. |
| Cloud-Managed Security Updates | Accelerates PIX protocol patches without on-site intervention for micro-merchants. |
| Northeast Regional Penetration | Addresses underbanked merchant populations in Salvador's informal commerce clusters. |
Study Parameters
Multiple input streams — primary interviews with payment hardware executives, regulatory affairs specialists at the Central Bank of Brazil, and merchant acquiring operations leads — were reconciled against secondary validation from ANVISA certification databases, Central Bank PIX interoperability filings, and customs import records for encryption modules. Conversations with food service operators in Rio de Janeiro and retail procurement managers in São Paulo informed demand-side segmentation. Bottom-up unit deployment estimates and top-down transaction volume analysis were triangulated to anchor market sizing.
Data-stream reconciliation across product type, technology authentication tier, end-user vertical, and deployment model dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from replacement cycle compression under PIX mandates and contactless infrastructure expansion trajectories. Forecast inputs incorporated ANVISA approval timeline distributions and merchant acquiring bundle penetration rates by retailer size tier.
Several conditions sit outside the modeled scope, including potential central bank digital currency architecture requirements, open-banking API standardization delays, and semiconductor supply disruptions beyond currency fluctuation. Forecasts reflect assumptions about PIX mandate enforcement continuity and LGPD penalty implementation severity. Material deviation in central bank digital currency pilot timelines or encryption module export restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Estonia POS Terminal Market
Payments
Bill Splitting Apps Market
Payments
Mexico Real Time Payments Market
Payments
Saudi Arabia Gift Card and Incentive Card Market
Payments
Saudi Arabia Mobile Payments Market
Payments
In-Vehicle Payment System Market
Payments
United States Clearing Houses and Settlements Market
Payments
P2P Payment Market
Payments
Fingerprint Payment Market
Payments
Digital Payment in Healthcare Market
Payments
Thailand Mobile Payments Market
Payments
Canada Gift Card and Incentive Card Market
Payments
Payment Orchestration Platform Market
Payments
India Real Time Payments Market
Payments
Global Accounts Payable Software Market
Payments
Mobile Card Reader Market