
 Singapore Payments Market | 2026-2036
Singapore Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Payments Market Analytics
Cross-border remittance fee pools is rewriting profit allocation between traditional correspondent banking and blockchain-enabled corridors. DBS Bank Ltd anchors retail payment dominance through its digibank platform integration across ASEAN corridors. Grab Holdings Ltd leverages super-app ecosystem lock-in to sustain merchant acquisition momentum. Wise differentiates on transparent FX pricing to compete against legacy wire transfer margins.
Singapore Payments denotes electronic value transfer systems encompassing card networks, mobile wallets, account-to-account transfers, and embedded finance rails operating through SG FAST, NETS, and international scheme protocols with settlement latency under sixty seconds for real-time instruments. The architecture serves commercial clearing, consumer purchasing, and treasury management across Southeast Asian trade corridors. Mobile wallet penetration among retail consumers leads transaction volume growth as QR code standardization displaces cash handling costs. Credit card interchange pools remain the most mature revenue layer, while bank transfer volumes accelerate fastest among corporates optimizing working capital cycles. FinTech firms as service providers capture expanding margin share by embedding payment acceptance into vertical software stacks.
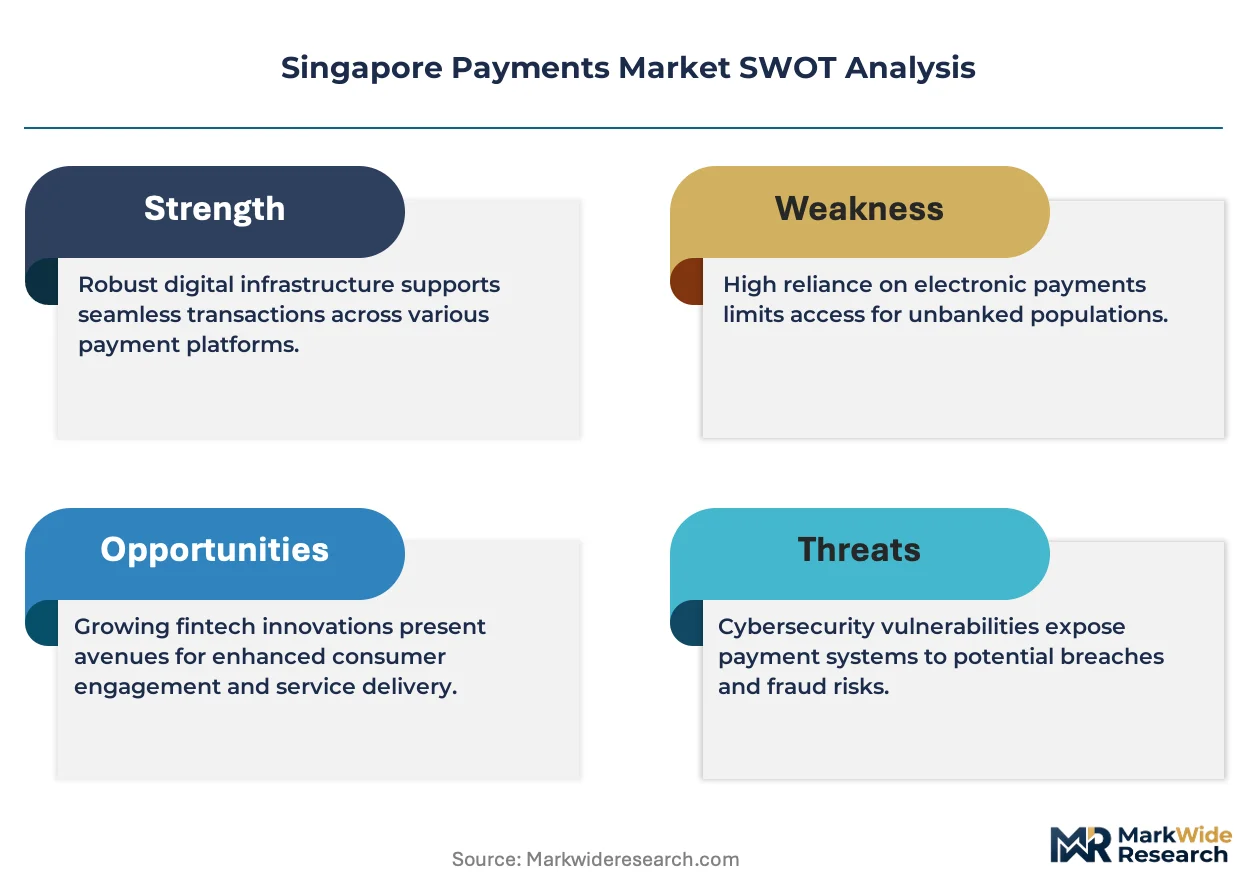
Monetary Authority of Singapore licensing under the Payment Services Act shapes market access through tiered capital requirements and technology risk management standards. Association of Banks Singapore operational guidelines enforce fraud liability allocation and customer authentication protocols across member institutions. Personal Data Protection Commission consent frameworks constrain data monetization architectures. Stakeholders must monitor regulatory divergence between Singapore's payment token frameworks and neighboring ASEAN licensing regimes to preserve cross-border product portability.
Market Dynamics
Real-time settlement infrastructure is compressing transaction latency from days to seconds, forcing incumbent banks to reprice correspondent banking services while non-bank payment institutions capture margin from legacy wire transfers.
Growth Catalysts
- Monetary Authority of Singapore Payment Services Act:Tiered licensing frameworks lowered capital barriers for digital payment token service providers, expanding the licensed entity pool beyond traditional deposit-taking institutions.
- E-commerce merchant onboarding:Embedded finance APIs enable vertical software platforms to integrate payment acceptance without standalone merchant acquiring contracts, accelerating SME adoption.
- SG FAST rail expansion:Account-to-account transfer volumes surge as corporates optimize intraday liquidity management across ASEAN treasury operations.
Market Restraints
- Technology risk capital requirements:Monetary Authority of Singapore mandates minimum base capital and security deposits that strain early-stage payment token service providers during licensing.
- Cross-border regulatory divergence:Divergent ASEAN licensing regimes for payment tokens fragment product portability, forcing multi-jurisdictional compliance architectures.
- Fraud liability concentration:Association of Banks Singapore operational guidelines allocate authentication failure costs to originating institutions, elevating operational risk reserves.
Strategic Opportunities
- QR code standardization across ASEAN:Singapore's NETS QR specifications enable merchant acceptance network expansion into Malaysia, Thailand, and Indonesia corridors.
- Personal Data Protection Commission consent frameworks:Explicit consent requirements for data monetization create competitive differentiation for privacy-preserving payment analytics platforms.
- Blockchain-enabled remittance corridors:Distributed ledger settlement rails offer transparent FX pricing to displace opaque correspondent banking fee structures in Indonesia and Philippines corridors.
Industry Challenges
- Legacy core banking integration:Incumbent institutions face multi-year system migration timelines to connect real-time payment rails with batch-oriented ledger architectures.
- Certification timeline compression:Monetary Authority of Singapore technology risk management audits extend licensing cycles, delaying product launch schedules for applicant firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Payments Market |
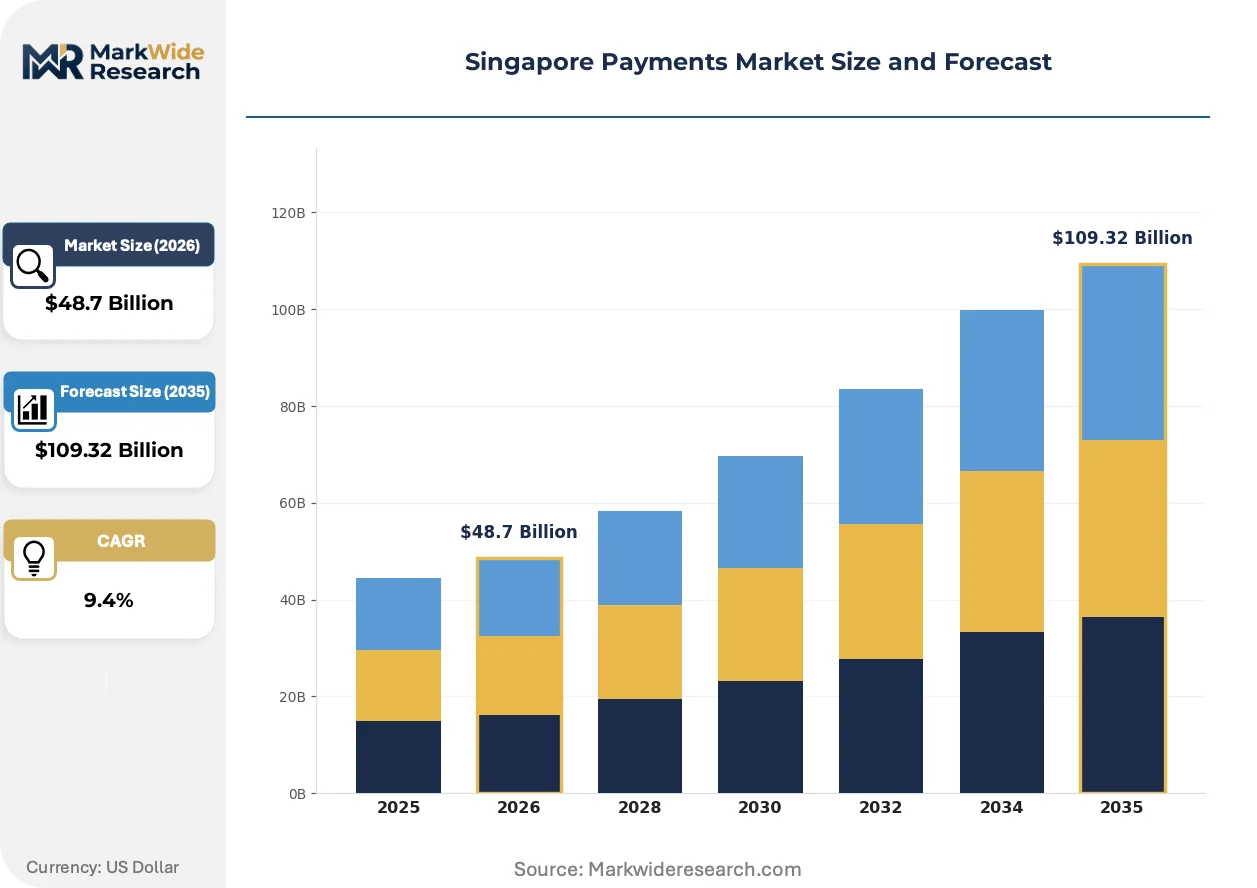
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $109.32 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Credit Card, Debit Card, Mobile Wallet, Bank Transfer End User: Retail Consumers, E-commerce Platforms, Small Businesses, Corporates Technology: Contactless Payments, QR Code Payments, Online Banking, NFC Service Provider: Banks, Payment Processors, FinTech Firms, Telecom Operators |
| Companies Covered | Grab Holdings Ltd, Apple Inc., DBS Bank Ltd, Wise, Adyen, Visa, PayPal Holdings, Inc., Airwallex, Mastercard, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Payments Market Evolving Landscape
Payment infrastructure is fragmenting across specialized rails as merchants demand settlement speed, cost transparency, and embedded financial services that traditional card networks cannot deliver.
Host card emulation technology enables smartphone-based contactless transactions without physical secure elements, is rendering obsolete the dominance of plastic card issuance for retail point-of-sale acceptance. Challenger banks and super-apps deploy software-only payment credentials to bypass card network interchange pools. This compression of authentication hardware requirements accelerates merchant self-onboarding outside traditional acquiring relationships.
Monetary Authority of Singapore's framework for digital payment token services imposes segregated custody and technology risk management standards on stablecoin issuers. Licensed entities must maintain reserves in specified low-risk instruments and submit to annual cybersecurity audits. Payment token service providers now compete on compliance architecture rather than token design alone, favoring institutions with existing risk management infrastructure.
Merchant procurement of payment acceptance is consolidating through vertical software platforms that bundle payments with inventory, payroll, and lending functions. Food delivery aggregators and ride-hailing platforms in Singapore embed payment rails as loss-leading infrastructure to capture transaction data for credit underwriting. This channel shift compresses standalone payment processor margins while expanding total addressable revenue per merchant relationship.
Singapore Payments Market Segmentation
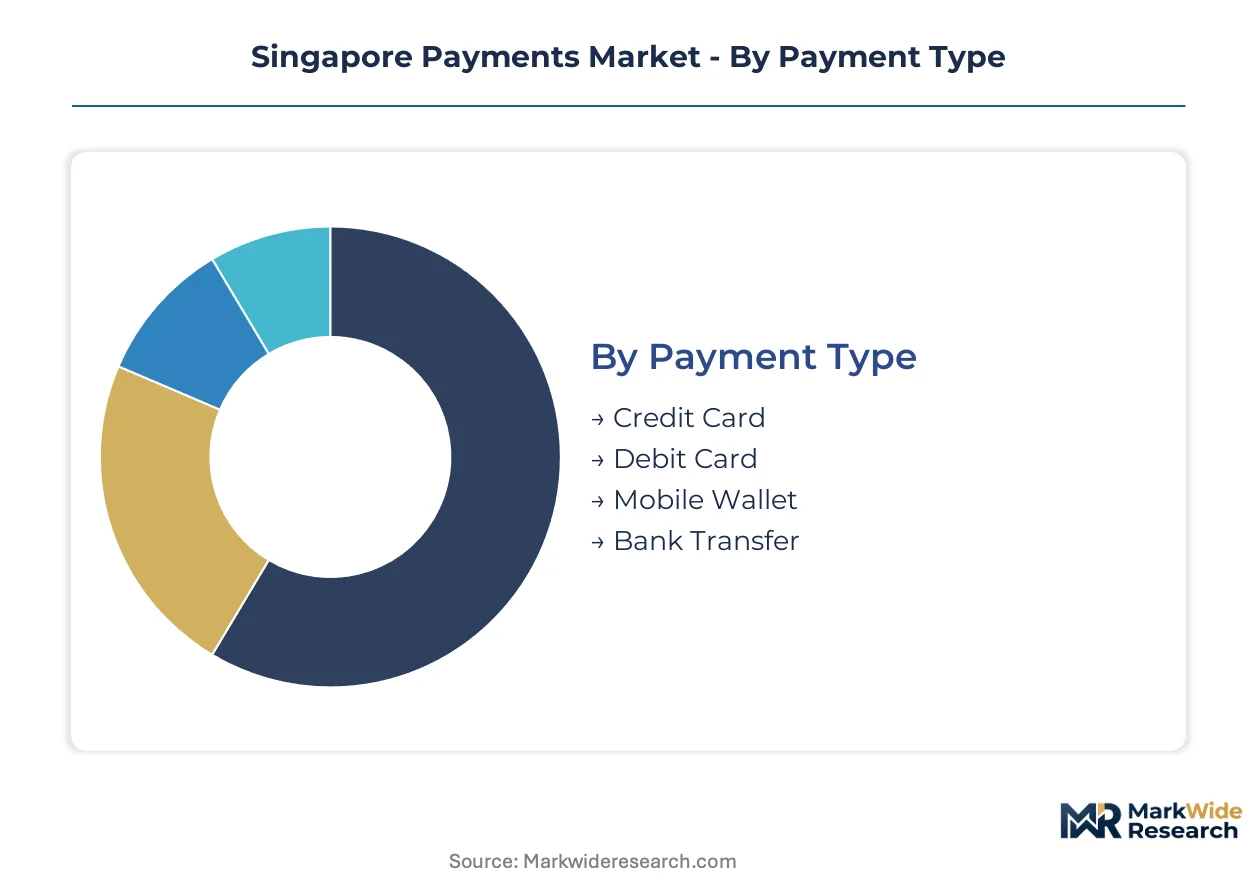
Payment segmentation in Singapore reveals how infrastructure investment and regulatory licensing reshape competitive boundaries across transaction rails. Distinct technology and provider categories expose where capital requirements and customer authentication standards concentrate margin capture.
Payment Type:
After-sales service intensity varies sharply across payment instruments, with mobile wallets demanding continuous app updates and fraud monitoring versus the passive infrastructure of card networks.
- Credit Card:Revolving credit instruments processed through international scheme networks with interchange fee pools funding issuer rewards programs. Singapore retail consumers and corporates concentrate demand here for chargeback protection and extended credit terms, though interchange compression from real-time alternatives constrains margin expansion.
- Mobile Wallet:Smartphone-based stored value systems leveraging host card emulation and QR code standards for merchant acceptance. E-commerce platforms and food delivery aggregators drive accelerating adoption as embedded finance APIs enable self-onboarding outside traditional acquiring relationships.
- Debit Card:Direct-linked payment instruments drawing on deposit account balances with lower interchange rates than credit products. Demand concentrates among budget-conscious retail consumers and SMEs seeking transaction cost discipline.
- Bank Transfer:Account-to-account value movement through SG FAST rails with sub-sixty-second settlement latency. Corporates optimizing intraday liquidity management across ASEAN treasury operations generate fastest volume acceleration.
Credit card interchange pools hold the largest share; momentum sits with bank transfer volumes.
End User:
Cost tier differentiation separates enterprise-grade treasury management solutions from mass-market mobile payment interfaces.
- Retail Consumers:Individual transaction initiators migrating from card-present to mobile-first habits through super-app ecosystems. Singapore's high smartphone penetration and NETS QR standardization accelerate cash displacement.
- E-commerce Platforms:Online merchants procuring payment acceptance through embedded finance APIs rather than standalone acquiring contracts. Vertical software integration reduces onboarding friction for SME marketplace vendors.
- Small Businesses:Merchant acquirers seeking consolidated payment, inventory, and payroll functions through single-platform relationships. Food delivery aggregators embed payment rails as infrastructure to capture transaction data for credit underwriting.
- Corporates:Treasury departments optimizing working capital cycles through real-time account-to-account transfers and multi-currency liquidity management across ASEAN corridors.
Retail consumers dominate transaction volumes; corporates drive steepest expansion trajectory for real-time infrastructure.
Technology:
Application context determines whether contactless hardware or software-only credentials prove economically viable for merchant acceptance.
- Contactless Payments:Near-field communication protocols enabling tap-to-transact functionality at physical point-of-sale terminals. Singapore retail and transit environments concentrate deployment.
- QR Code Payments:Visual scan-to-pay standards through NETS specifications enabling merchant acceptance network expansion into Malaysia, Thailand, and Indonesia corridors. Low hardware requirements accelerate micro-merchant onboarding.
- Online Banking:Browser and application-based account access facilitating bill payment and fund transfers. Corporate treasury adoption concentrates here for batch payment automation.
- NFC:Short-range wireless communication enabling smartphone-based transactions without physical secure elements. Host card emulation technology renders plastic card issuance increasingly obsolete.
Contactless payments hold established infrastructure share; QR code deployments gain share fastest through ASEAN standardization.
Service Provider:
Margin concentration follows licensing tier, with Payment Services Act capital requirements filtering competitive entry.
- Banks:Deposit-taking institutions with existing risk management infrastructure and MAS licensing compliance. DBS Bank anchors retail dominance through digibank platform integration.
- Payment Processors:Merchant acquirers and gateway operators managing transaction routing and settlement. Interchange compression from real-time alternatives forces repricing of legacy wire transfer services.
- FinTech Firms:Technology-native providers embedding payment acceptance into vertical software stacks and competing on compliance architecture rather than token design. Grab Holdings leverages super-app lock-in for merchant acquisition.
- Telecom Operators:Mobile network carriers with subscriber billing relationships and distribution infrastructure. Limited direct payment licensing constrains standalone market position.
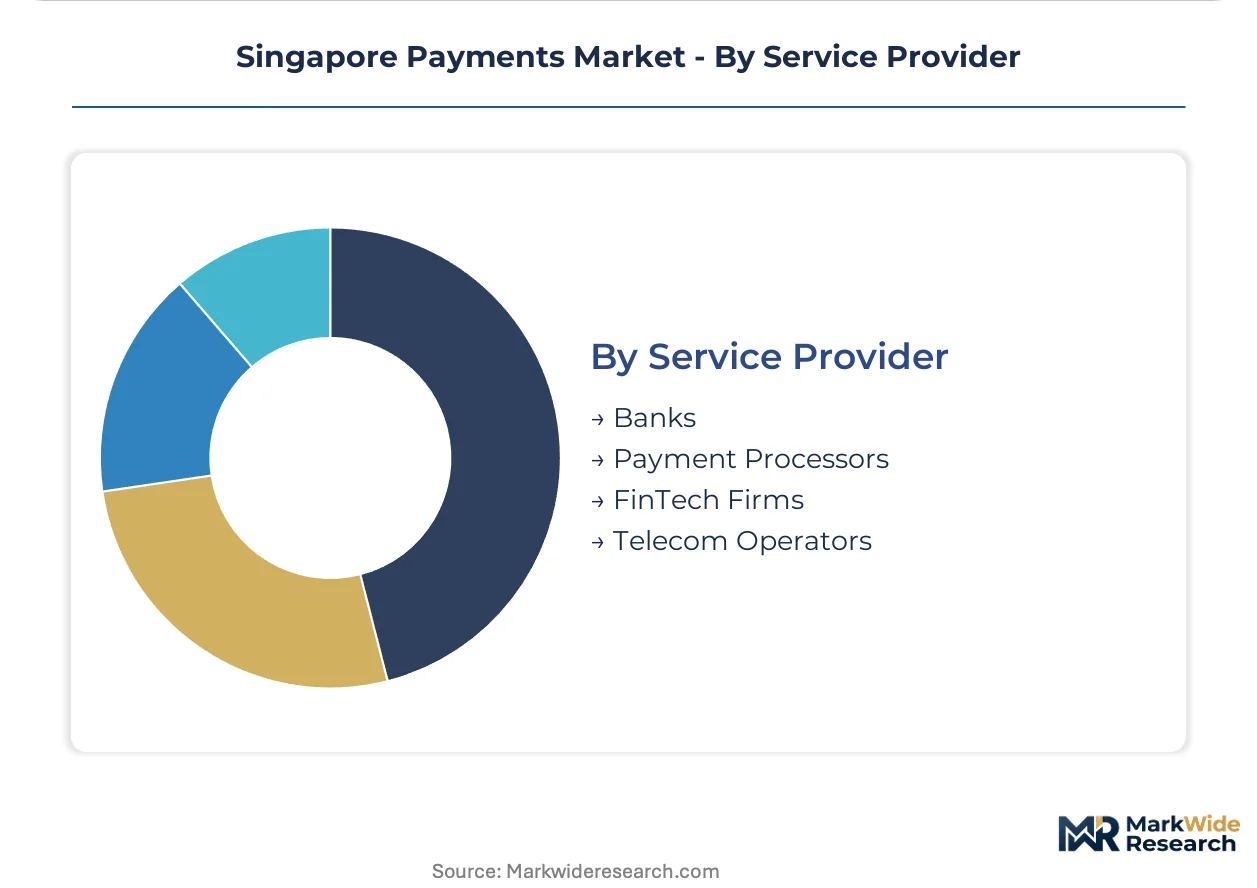
Banks retain largest licensed entity pool; FinTech firms climb fastest through embedded finance API distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail consumers across Southeast Asia show divergent price sensitivity, with Indonesian and Philippine corridors demanding lowest-cost remittance rails while Singaporean corporates prioritize settlement speed over transaction fees.
Malaysia
Cross-border merchant acquiring demand accelerates through NETS QR interoperability agreements enabling Singapore-based retailers to accept payments at Malaysian point-of-sale terminals. Bank Negara Malaysia's regulatory sandbox for payment token services creates parallel licensing pathways to Singapore's Payment Services Act. Kuala Lumpur's financial district concentrates ASEAN treasury operations for multinational corporates migrating liquidity management to real-time rails.
Thailand
PromptPay network integration with SG FAST corridors drives surging account-to-account volumes for Thai-Singapore trade settlement. Bank of Thailand's cross-border QR payment memoranda with the Monetary Authority of Singapore standardize merchant acceptance protocols. Bangkok's e-commerce logistics clusters embed payment acceptance into delivery platform infrastructure, compressing standalone processor margins.
Indonesia
Blockchain-enabled remittance corridors capture fee-sensitive diaspora workers sending value from Singapore to Indonesian archipelago destinations. Bank Indonesia's payment system roadmap mandates real-time gross settlement compatibility with ASEAN neighbors by regulatory deadline. Jakarta's fintech licensing backlog forces applicants into multi-year compliance timelines, advantaging Singapore-licensed entities with existing risk management infrastructure.
Philippines
Overseas worker remittance volumes from Singapore concentrate demand for transparent FX pricing against legacy correspondent banking fee structures. Bangko Sentral ng Pilipinas' digital payments transformation roadmap accelerates mobile wallet interoperability with Singapore-issued credentials. Metro Manila's business process outsourcing clusters procure corporate treasury services through Singapore-based banks optimizing intraday liquidity.
Vietnam
Manufacturing supply chain payments between Singapore parent entities and Vietnamese subsidiaries migrate from documentary credits to real-time account-to-account settlement. State Bank of Vietnam's pilot program for foreign payment service providers tests regulatory tolerance for Singapore-licensed firms. Ho Chi Minh City's industrial zones concentrate demand for embedded finance APIs integrating payment acceptance with customs clearance platforms.
Singapore Payments Market Competitive Landscape
Capability concentration sits with licensed banks possessing existing risk management infrastructure; scale advantage sits with technology-native platforms distributing through super-app ecosystems. The market structures around three tiers: deposit-taking institutions with Payment Services Act compliance, merchant acquirers managing transaction routing, and embedded finance providers integrating acceptance into vertical software. Dominant competitive moves include strategic partnerships between banks and e-commerce platforms, plus portfolio diversification into adjacent lending and insurance products.
Within the licensed banking tier, DBS Bank Ltd anchors retail payment dominance through digibank platform integration across ASEAN corridors. Grab Holdings Ltd and Wise occupy positions at the technology-native end, with the former leveraging super-app ecosystem lock-in for merchant acquisition momentum and the latter differentiating on transparent FX pricing against legacy wire transfer margins.
| Leading Market Players |
|---|
| Grab Holdings Ltd |
| Apple Inc. |
| DBS Bank Ltd |
| Wise |
| Adyen |
| Visa |
| PayPal Holdings, Inc. |
| Airwallex |
| Mastercard |
| Others |
Value Network & Pricing Analysis
Overcapacity in traditional card-present acquiring infrastructure across Southeast Asian corridors drives merchant acquirers toward aggressive repricing of interchange-dependent services while compressing margins for legacy wire transfer corridors. This utilization imbalance forces payment service providers to reallocate capital toward real-time rail integration and embedded finance APIs that capture higher lifetime value per merchant relationship.
Pricing Analysis
After-sales service revenue from fraud monitoring and merchant analytics subscriptions drives lifetime value differentiation among payment service providers. Transaction-based pricing stratifies across premium real-time settlement tiers, standard batch-processing corridors, and economy remittance rails with extended settlement windows. Price differentiation hinges on SG FAST integration depth and Monetary Authority of Singapore licensing tier, with licensed banks commanding premium positioning over payment token service providers. Pricing pressure stems from Wise and other non-bank institutions compressing FX margins on cross-border corridors. E-commerce platforms exhibit lowest price sensitivity due to embedded finance bundling, while micro-merchants in food delivery aggregators demand zero-cost acceptance infrastructure.
Supply Chain Analysis
Export-control regimes on semiconductor components for payment terminal manufacturing limit hardware supply flows from Taiwan and South Korea into Singapore's POS deployment channels. Core banking software licensing draws from concentrated vendor pools in the United States and India, while cloud infrastructure for payment processing rests on hyperscaler capacity in Singapore and Australia. Single-source vulnerability in host card emulation chipsets creates procurement risk for mobile wallet providers scaling QR-code acceptance networks. Distribution runs through vertical software platforms that bundle payment acceptance with inventory management, displacing standalone processor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent payment institutions face substitution pressure from blockchain-enabled remittance corridors that displace correspondent banking fee structures across Indonesia and Philippines corridors. Defense requires entrenching merchant relationships before real-time infrastructure commoditizes transaction routing.
For Market Incumbents: Entrench merchant lock-in through digibank platform integration across ASEAN treasury operations and deepen SG FAST rail connectivity for corporate liquidity management. Prioritize certification investment under Payment Services Act technology risk management standards to extend licensing advantages over early-stage payment token applicants. Counter Grab Holdings' super-app ecosystem expansion by embedding lending and insurance products into existing merchant relationships. For New Entrants and Emerging Players: Mid-market corporates in Vietnam and Thailand with fragmented treasury operations represent the most penetrable entry point for real-time account-to-account settlement solutions. Blockchain-enabled remittance corridors for Indonesian diaspora workers offer white-space positioning against opaque correspondent banking fee structures. Target go-to-market partnerships with vertical software platforms that bundle payment acceptance with customs clearance and logistics functions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across payment token service licensing as Monetary Authority of Singapore mandates escalate technology risk management reserves. Long-term viability favors acquiring licensed entities with existing compliance infrastructure rather than de novo licensing pathways. Watch for inflection signals in SG FAST volume acceleration across ASEAN corridor integration milestones.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | DBS Bank's digibank ASEAN expansion consolidates retail payment dominance through unified treasury interfaces. |
| Strategic Partnership | Grab Holdings' super-app merchant acquisition leverages food delivery data for embedded credit underwriting. |
| Regulatory Approval Pathway | Payment Services Act licensing tiers filter competitive entry through capital and technology risk standards. |
| Geographic Expansion | NETS QR standardization enables Singapore-based acquirers to capture Malaysian and Thai merchant acceptance. |
| Acquisition of Specialist Firm | Vertical software platforms embedding payment APIs displace standalone processor relationships in SME segments. |
Research Methodology
Initial hypotheses were tested against primary input from payment technology executives, merchant acquiring heads, regulatory compliance officers, and corporate treasury managers and refined through secondary validation against Monetary Authority of Singapore licensing disclosures, Association of Banks Singapore operational guidelines, SG FAST volume statistics, and Payment Services Act regulatory filings. Bottom-up merchant adoption modeling and top-down ASEAN corridor flow analysis were triangulated to establish volume and value estimates.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning payment instrument type, end-user category, technology protocol, and service provider licensing tier. CAGRs were derived from trend extrapolation of real-time rail adoption curves and e-commerce merchant onboarding velocity, incorporating corporate treasury optimization behavior and cross-border remittance corridor shifts as industry-specific forecast inputs.
Practitioners should monitor regulatory divergence between Singapore's payment token frameworks and neighboring ASEAN licensing regimes for early signals of product portability constraints. Forecasts reflect assumptions regarding SG FAST corridor expansion timelines and super-app ecosystem consolidation trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
Crypto Payment Gateway Market
Payments
Digital Payment Market
Payments
LAMEA Crypto Payment Gateway Market
Payments
Malta POS Terminal Market
Payments
Mexico Digital Wallet Market
Payments
United States Payments Market
Payments
Face-Swiping Payment Market
Payments
B2B Payments Platform Market
Payments
Mobile Payment Security Software Market
Payments
Middle East Gift Card and Incentive Card Market
Payments
Smart POS System Market
Payments
Electronic Payment System for Transportation Market
Payments
UAE POS Terminal Market
Payments
Greece POS Terminals Market
Payments
Latin America Payment Gateway Market