
 Global Accounts Payable Automation Market | 2026-2036
Global Accounts Payable Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Accounts Payable Automation Market Foresight
CSRD is decoupling compliance readiness from enterprise scale by requiring granular emissions and financial traceability across supply chains. SAP leverages its embedded ERP footprint to anchor automated invoice reconciliation within existing enterprise workflows. Basware competes through deep specialization in e-invoicing interoperability across European tax authorities.
Accounts payable automation encompasses software platforms that digitize invoice capture, validation, approval routing, and payment execution through optical character recognition, machine learning-based data extraction, and API-driven ERP integration. Its primary commercial purpose is to eliminate manual data entry, reduce payment cycle times, and enforce spend controls across organizational hierarchies. Cloud-based deployment leads solution uptake among organizations prioritizing rapid implementation and minimal infrastructure overhead, while invoice processing commands the largest solution-type revenue pool due to its position at the entry point of every payable workflow. Payment processing represents the fastest-expanding segment as real-time rails and virtual card programs displace legacy check and ACH methods.
FDA 21 CFR Part 11, EU GDPR, and India's CEA data-localization directives shape product architecture by mandating audit trails, consent management, and sovereign data residency in regulated deployments. The SEC's climate disclosure rules extend these requirements to supplier payment data as scope 3 emissions tracking penetrates procurement functions. Stakeholders must evaluate whether their automation stack satisfies emerging cross-border tax transparency mandates before vendor consolidation accelerates.
Market Dynamics
Real-time payment rails and AI-driven data extraction are compressing invoice processing cycles from weeks to hours, forcing vendors to rebuild platforms around API-first architectures rather than batch-oriented legacy systems.
Growth Catalysts
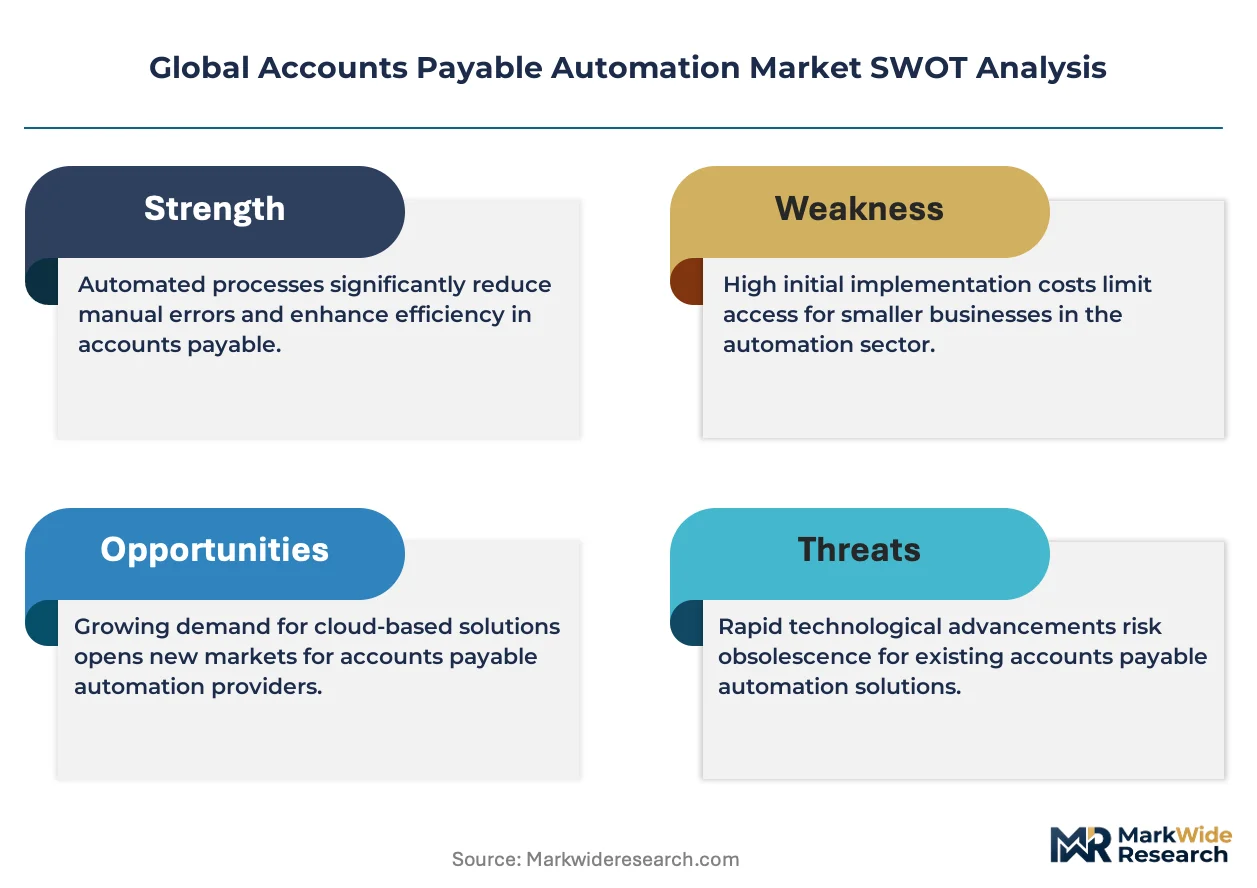
- EU AI Act:Mandates auditable algorithmic decision-making in financial workflows, accelerating procurement of transparent ML-based invoice validation tools across German and French enterprises.
- Optical character recognition:Next-generation OCR engines with handwriting recognition capabilities are unlocking automation in construction and healthcare verticals previously blocked by non-standard invoice formats.
- India's digital tax infrastructure:The GST e-invoicing mandate and Invoice Registration Portal integration are compelling mid-market manufacturers to adopt end-to-end payable automation for compliance.
Market Restraints
- Cloud infrastructure concentration:Hyperscaler dominance in Western Europe and North America creates sovereign data residency risks for CFOs navigating India's CEA localization directives and EU GDPR cross-border transfer rules.
- Legacy ERP entrenchment:Decades-old on-premise financial systems in Japanese and German manufacturing conglomerates impose prohibitive integration costs and extended deployment timelines.
- Check-based payment persistence:The US retains substantial B2B check volume due to supplier banking fragmentation and float-dependent treasury practices, delaying full payment automation adoption.
Strategic Opportunities
- Brazil's PIX real-time payment network:Instant settlement infrastructure creates greenfield demand for automated payment execution and reconciliation platforms among São Paulo-based multinationals.
- Scope 3 emissions tracking:The SEC's climate disclosure rules and EU CSRD are embedding carbon accounting into supplier payment data, opening adjacent revenue streams for automation vendors with ESG reporting modules.
- Embedded finance convergence:The intersection of AP automation with virtual card issuance and supply chain financing is enabling new transaction-fee monetization models for platform providers.
Industry Challenges
- ML model governance:Finance teams lack sufficient data science expertise to validate machine learning extraction accuracy, audit bias, and manage retraining pipelines for document processing models.
- Multi-ERP integration complexity:Enterprises running heterogeneous SAP, Oracle, and Workday instances face fragmented master data management and approval hierarchy synchronization across business units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Accounts Payable Automation Market |
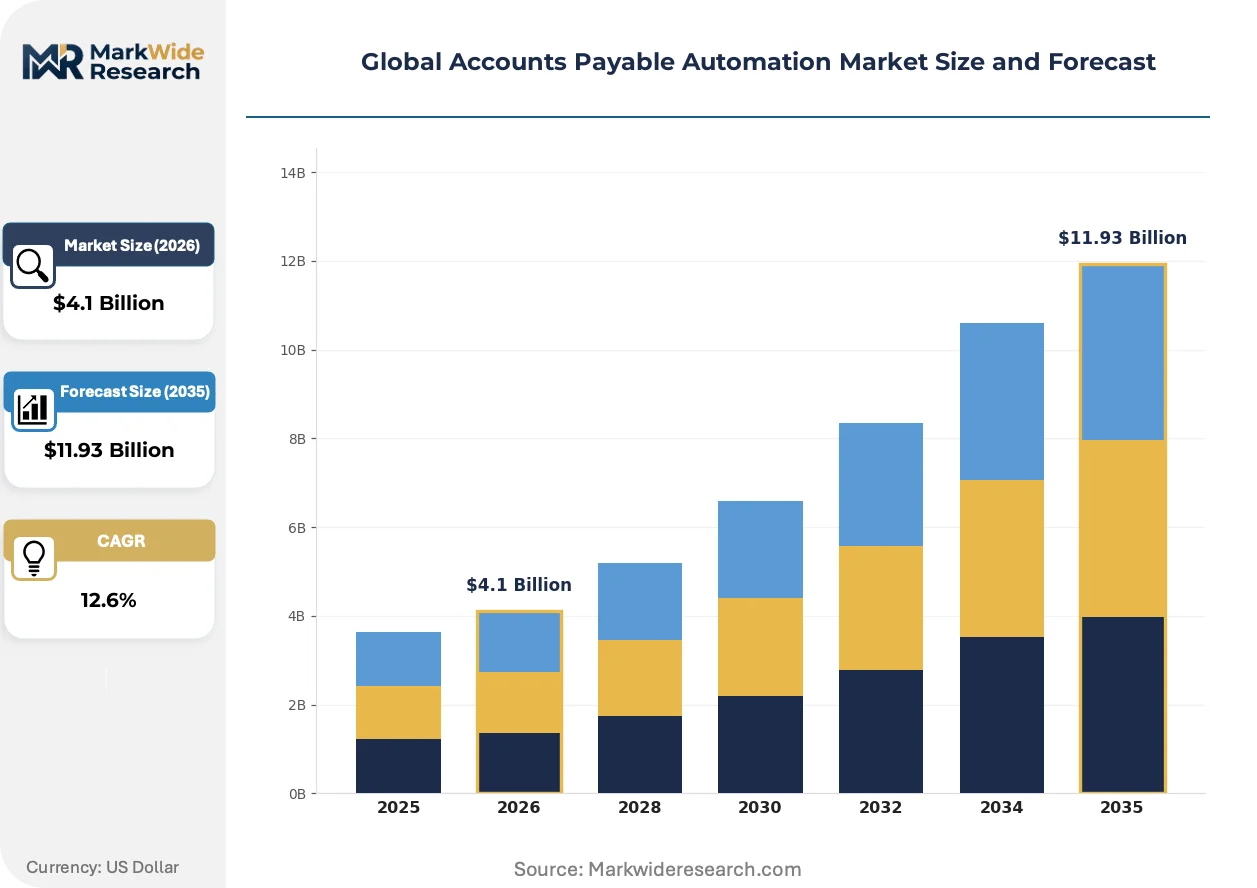
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $11.93 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, Managed Services Solution Type: Invoice Processing, Expense Management, Payment Processing, Vendor Management, Reporting & Analytics Use Case: Small Business Finance, Mid-Sized Enterprise Procurement, Large Corporation Treasury, Non-Profit Financial Operations End User Industry: Manufacturing Firms, Technology Providers, Educational Institutions, Government Agencies, Telecommunications |
| Companies Covered | Coupa Software Inc., Tipalti Inc., Basware, SAP, Oracle NetSuite, Sage Group plc, Zycus, Bottomline Technologies, Inc., Bill.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Accounts Payable Automation Market Shifts & Advancements
Document intelligence and payment orchestration layers are converging into unified platforms, eroding the boundary between invoice processing and treasury execution while embedding compliance checkpoints at every workflow stage.
Intelligent document processing is modularizing. Computer vision pipelines with transformer-based architectures now parse unstructured supplier documents including packing slips and customs declarations. Mid-sized distributors in the Netherlands and Australia are deploying these tools within eight-week implementation windows. The technology is modularizing platform architectures, allowing CFOs to swap extraction engines without reconfiguring approval workflows or ERP connectors.
The EU CSRD is extending sustainability reporting obligations to private companies above 250 employees. This directive forces procurement departments to capture supplier emissions data at the point of invoice receipt and payment authorization. German automotive suppliers and French retail chains are now requiring ESG data fields in their AP automation RFPs, prioritizing vendors with pre-built carbon accounting integrations.
Virtual card programs are displacing traditional procurement cards and check payments in US healthcare and professional services. CFOs at hospital networks and law firms are consolidating supplier payment methods onto single-use virtual cards to capture rebates and improve spend visibility. This behavioral shift is most pronounced in Texas and California, where real-time payment rails from regional banks accelerate virtual card settlement cycles.
Global Accounts Payable Automation Market Segmentation
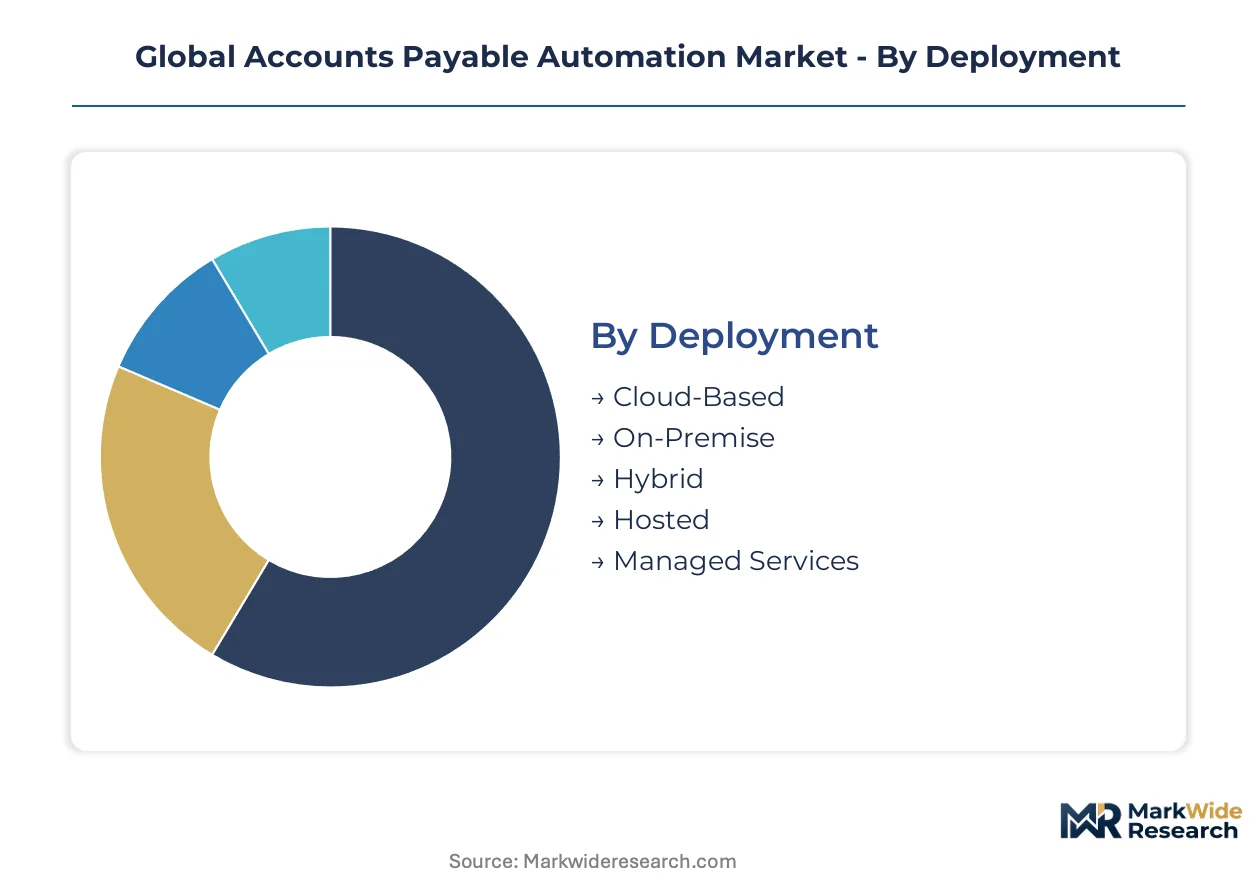
Deployment architecture determines compliance burden and data sovereignty obligations across multinational implementations. Solution specialization dictates integration complexity with existing ERP footprints. Understanding segment boundaries reveals where vendor consolidation will accelerate versus where niche specialists retain pricing power.
Deployment:
Cloud-based configurations trigger EU GDPR cross-border transfer assessments and India's CEA localization directives. On-premise deployments face FDA 21 CFR Part 11 audit trail mandates in regulated healthcare and pharmaceutical environments.
- Cloud-Based:Multi-tenant SaaS architectures with API-first ERP connectors dominate mid-market procurement in Germany and India. German automotive suppliers prioritize these deployments to satisfy EU AI Act algorithmic transparency requirements without infrastructure overhead.
- On-Premise:Single-tenant installations within client data centers persist in Japanese manufacturing conglomerates with decades-old SAP R/3 entrenchment. These deployments impose twelve-to-eighteen month implementation timelines but satisfy sovereign data residency demands from national regulators.
- Hybrid:Split architectures process sensitive payment data on-premise while routing analytics workloads to cloud infrastructure. US hospital networks deploy hybrid models to isolate HIPAA-protected supplier information while leveraging cloud-based reporting dashboards.
- Hosted:Dedicated private cloud instances within third-party data centers serve French and German enterprises navigating GDPR Article 44 transfer mechanism complexities. These configurations offer cloud agility without multi-tenant security exposure.
- Managed Services:Outsourced platform operation with vendor-assumed compliance responsibility appeals to Australian mid-market distributors lacking internal IT security expertise. Providers assume liability for CEA, GDPR, and SOX control maintenance.
Leading the category by volume: Cloud-Based. Growing fastest: Managed Services.
Solution Type:
Invoice processing commands the entry-point position in every payable workflow, capturing upstream document intelligence value. Payment processing solutions face the steepest architectural disruption from real-time rail proliferation.
- Invoice Processing:OCR and ML-based extraction engines digitize supplier documents from capture through validation. Dutch distributors deploy transformer-based computer vision pipelines to parse unstructured packing slips within eight-week implementation windows.
- Payment Processing:Virtual card issuance and real-time rail execution displace legacy check and ACH methods. Texas and California hospital networks consolidate supplier payments onto single-use virtual cards to capture rebates and accelerate settlement cycles.
- Expense Management:Corporate card reconciliation and travel expense workflows integrate with AP platforms for unified spend visibility. Professional services firms in São Paulo leverage these tools alongside Brazil's PIX instant settlement infrastructure.
- Vendor Management:Supplier onboarding, master data synchronization, and performance scorecarding reduce procurement cycle friction. French retail chains now require ESG data capture capabilities within these modules to satisfy CSRD scope 3 reporting obligations.
- Reporting & Analytics:Cash flow forecasting and spend analytics layers embed compliance checkpoints at workflow stages. German enterprises prioritize these tools for EU AI Act-mandated algorithmic decision auditability in financial operations.
Invoice processing generates the largest revenue pool. Payment processing exhibits the steepest expansion trajectory as real-time infrastructure matures.
Use Case:
Enterprise scale dictates approval hierarchy complexity and multi-ERP integration requirements. Small business deployments prioritize rapid implementation over customization depth.
- Small Business Finance:Streamlined invoice capture and payment execution with minimal configuration overhead. Indian GST e-invoicing mandates drive adoption among mid-market manufacturers previously reliant on manual processes.
- Mid-Sized Enterprise Procurement:Automated workflow routing across distributed business units with standardized approval matrices. These organizations accelerate adoption fastest as digital tax reporting mandates tighten in the United States, Germany, and India.
- Large Corporation Treasury:Global payment orchestration with multi-currency netting and intercompany settlement capabilities. Heterogeneous SAP, Oracle, and Workday instances create fragmented master data management challenges.
- Non-Profit Financial Operations:Grant compliance tracking and donor-restricted fund segregation within payable workflows. These deployments emphasize audit trail completeness for IRS Form 990 and charity regulator examinations.
Mid-Sized Enterprise Procurement anchors category volume. Large Corporation Treasury climbs fastest as multinational complexity intensifies.
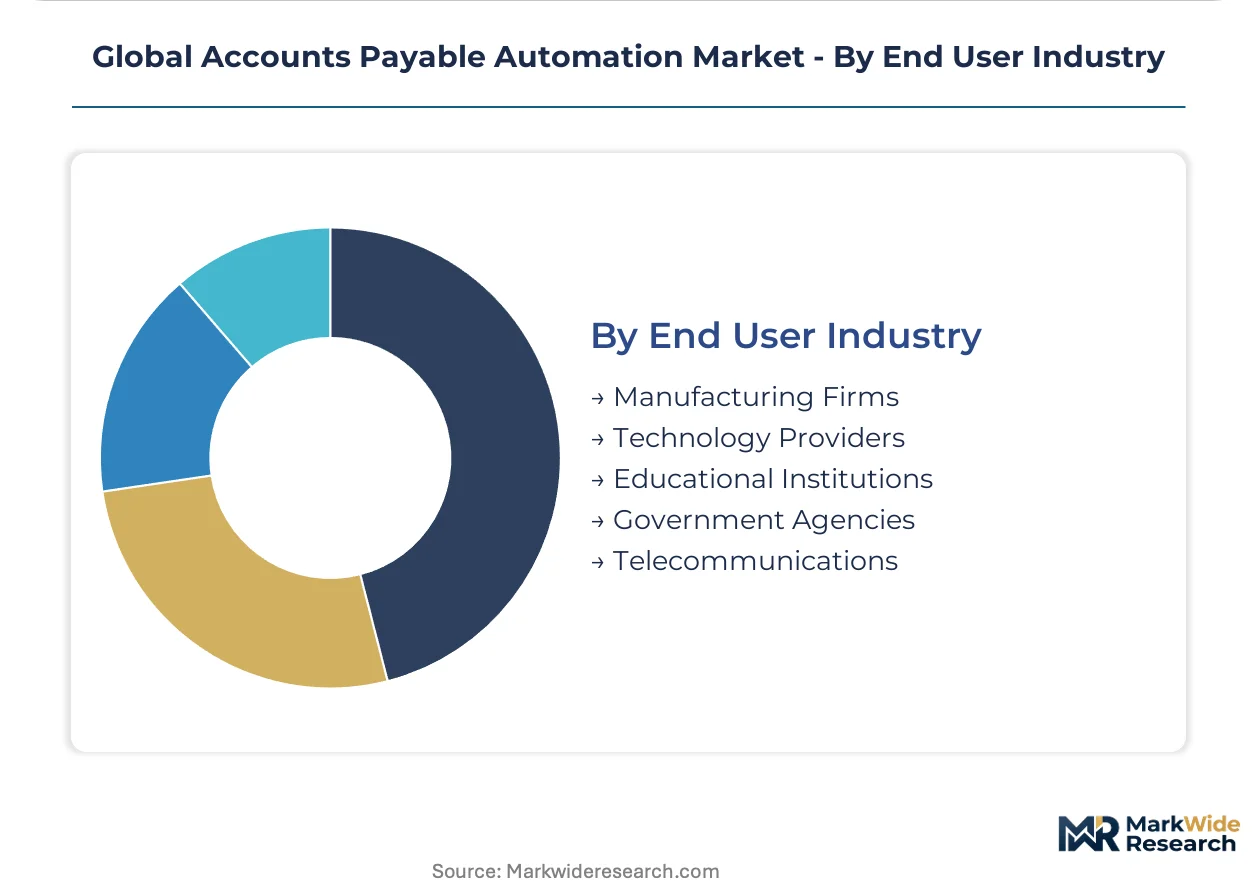
End User Industry:
Manufacturing verticals face the most complex supplier document variety, from standard invoices to customs declarations and packing slips. Government deployments impose the strictest audit trail and competitive bidding transparency requirements.
- Manufacturing Firms:High-volume supplier networks with diverse document formats including handwritten delivery receipts. Next-generation OCR engines with handwriting recognition unlock automation in construction-adjacent manufacturing previously blocked by non-standard inputs.
- Technology Providers:Rapid scaling vendor bases with international contractor payment complexity. These firms prioritize API-first architectures for seamless integration with existing financial operations stacks.
- Educational Institutions:Grant-funded procurement with restricted-use compliance and research supplier diversity requirements. Public university systems navigate state procurement regulations alongside federal funding mandates.
- Government Agencies:Competitive bidding workflows with public record transparency and anti-corruption control requirements. These deployments demand immutable audit trails satisfying inspector general examination protocols.
- Telecommunications:Infrastructure vendor management with complex milestone-based payment terms and regulatory filing coordination. Tower construction and spectrum acquisition workflows require specialized project accounting integration.
Manufacturing Firms dominate segment volume. Technology Providers gain share fastest as vendor scaling complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for accounts payable automation concentrates in the United States, Germany, and India where digital tax reporting mandates are tightening procurement compliance requirements. Mid-sized enterprises in these markets are accelerating adoption of automated invoice-to-payment workflows ahead of regulatory deadlines. Each geography presents distinct integration challenges shaped by legacy ERP entrenchment and sovereign data residency rules.
United States
Hospital networks in Texas and California consolidate supplier payments onto single-use virtual cards to capture rebates and accelerate settlement cycles. The SEC's climate disclosure rules extend audit trail requirements to supplier payment data as scope 3 emissions tracking penetrates procurement functions. Check-based payment persistence due to supplier banking fragmentation delays full automation adoption despite real-time rail availability.
Germany
Automotive suppliers prioritize cloud-based deployments to satisfy EU AI Act algorithmic transparency requirements without infrastructure overhead. The CSRD mandates granular emissions traceability across supply chains, forcing procurement departments to capture supplier emissions data at invoice receipt. Manufacturing conglomerates in Baden-Württemberg and Bavaria face twelve-to-eighteen month implementation timelines due to decades-old SAP R/3 entrenchment.
India
Mid-market manufacturers accelerate adoption following GST e-invoicing mandates and Invoice Registration Portal integration requirements. The CEA data-localization directives impose sovereign data residency obligations that complicate hyperscaler cloud deployments. Industrial clusters in Maharashtra and Gujarat drive volume as distributors deploy transformer-based computer vision pipelines within compressed implementation windows.
Brazil
São Paulo-based multinationals create greenfield demand for automated payment execution platforms leveraging the PIX real-time settlement infrastructure. Professional services firms integrate expense management tools with PIX instant settlement for unified spend visibility. The national instant payment network displaces legacy methods and enables new transaction-fee monetization models for platform providers.
Netherlands
Dutch distributors deploy modular document intelligence tools to parse unstructured packing slips and customs declarations within eight-week implementation windows. GDPR Article 44 transfer mechanism complexities drive hosted private cloud configurations among enterprises seeking agility without multi-tenant exposure. Mid-market procurement teams prioritize rapid implementation over customization depth.
Global Accounts Payable Automation Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions in e-invoicing interoperability and ERP integration depth. The vendor base spans consolidated platform providers with embedded finance capabilities alongside niche document intelligence specialists. Three archetypes dominate: cloud-native payment orchestrators, legacy ERP-embedded incumbents, and regional tax compliance specialists. Competitive moves center on API-first architecture rebuilds and ESG reporting module expansion rather than vertical integration.
Within the ERP-embedded tier, SAP and Oracle NetSuite represent incumbents leveraging existing enterprise footprints to anchor automated invoice reconciliation within financial workflows. Basware occupies a position among European specialists competing through deep e-invoicing interoperability across tax authorities. Among cloud-native payment orchestrators, Tipalti exemplifies providers targeting mid-market scaling complexity with virtual card and real-time rail execution capabilities.
| Leading Market Players |
|---|
| Coupa Software Inc. |
| Tipalti Inc. |
| Basware |
| SAP |
| Oracle NetSuite |
| Sage Group plc |
| Zycus |
| Bottomline Technologies, Inc. |
| Bill.com |
| Others |
Supply & Pricing Matrix
The EU CSRD mandates granular emissions traceability across supply chains, gating qualified supplier access for AP automation vendors and establishing premium-tier pricing for platforms with pre-built carbon accounting modules. Buyers lacking ESG-ready systems face compliance-driven replacement cycles that compress negotiation leverage and elevate contract values for certified providers.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid deployment capabilities, with eight-week implementation windows commanding twenty-to-thirty percent premiums over standard twelve-week delivery schedules. SaaS-tiered subscription models dominate, with price differentiation anchored in ERP integration depth and AI Act audit trail certification. Cost compression in mid-market tiers intensifies as Indian GST mandates and German digital reporting deadlines accelerate competitive procurement. Small business finance teams exhibit highest price sensitivity, while large corporation treasury functions prioritize compliance assurance over unit economics.
Supply Chain Analysis
Warehouse-distribution layer consolidation centers on regional data residency requirements, with hosted private cloud instances proliferating across French and German facilities to satisfy GDPR Article 44 transfer mechanisms. Software development concentrates in the United States, India, and Ireland, drawing from specialized ML engineering talent pools and API infrastructure ecosystems. Single-source vulnerability in transformer-based computer vision components creates exposure to semiconductor supply constraints. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels with implementation partner networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic transparency mandates erect a cost-of-compliance barrier that favors incumbents with existing audit infrastructure and regulatory affairs capacity, marginalizing entrants lacking ML governance tooling.
For Market Incumbents: Acquire specialized document intelligence firms with transformer-based extraction engines to close capability gaps against cloud-native challengers. Consolidate ESG reporting module development through backward integration into carbon accounting data providers, defending position against SAP and Oracle NetSuite's embedded ERP advantage. For New Entrants and Emerging Players: Premium-to-economy pricing gaps in mid-sized enterprise procurement create white-space entry points for API-first platforms with rapid deployment positioning. Target Indian GST compliance automation and Brazilian PIX payment orchestration as underpenetrated geographies with regulatory tailwinds. Pursue channel partnerships with regional systems integrators as the primary go-to-market angle. For Investors and Strategic Acquirers: German automotive suppliers issuing RFPs with mandatory ESG data fields is the leading indicator that carbon-accounting-integrated AP automation commands durable pricing power. Long-term viability favors platforms with multi-ERP connector libraries and sovereign cloud deployment options. Monitor SEC climate disclosure rule implementation timelines as the critical inflection signal for scope 3 tracking demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Rebuild | Real-time payment rail integration displaces batch-oriented legacy systems across German and Brazilian deployments. |
| ESG Reporting Module Expansion | CSRD-compliant carbon accounting integrations satisfy French retail chain and German automotive supplier procurement requirements. |
| Regional Data Center Expansion | Hosted private cloud instances in Frankfurt and Mumbai address India's CEA localization and EU GDPR cross-border constraints. |
| Specialist Firm Acquisition | Transformer-based computer vision capabilities compress document processing implementation timelines to eight-week windows. |
| Virtual Card Program Launch | Single-use card issuance captures rebate revenue from Texas and California hospital network supplier payment consolidation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across CFOs, procurement directors, ERP integration specialists, and compliance officers at mid-sized enterprises and large corporations. Bottom-up and top-down triangulation validated deployment architecture and solution-type segmentation, drawing from EU AI Act implementation guidance, SEC climate disclosure drafts, and Indian GST e-invoicing portal statistics.
Granularity-level modeling addressed deployment mode, solution specialization, enterprise scale, and end-user industry across the projection horizon, with additional dimensioning for regulatory jurisdiction clusters and real-time payment rail availability. CAGRs derived from invoice processing volume trajectories and payment execution technology substitution curves, incorporating ML model accuracy improvement rates and virtual card program adoption patterns as industry-specific forecast inputs.
Inputs from hyperscaler infrastructure disclosures and EU regulatory consultation documents were available through the study window; gaps in private mid-market enterprise spend data introduce uncertainty bands around adoption timing assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Norway Mobile Payments Market
Payments
Electronic Payment Processing Software Market
Payments
Forex Cards Market
Payments
Norway Payments Market
Payments
Social Media Payment Solution Market
Payments
Electronic Cash Register Market
Payments
Credit Card Payments Market
Payments
Vehicle Toll Collection and Access System Market
Payments
Thailand Mobile Payments Market
Payments
United States POS Terminals Market
Payments
Ireland POS Terminals Market
Payments
Global Point of Sale Terminals Market
Payments
Medical Payment Fraud Detection Market
Payments
Hong Kong Credit Cards Market
Payments
Philippines Remittance Market
Payments
Italy Gift Cards Market