
 India Gift Card and Incentive Card Market | 2026-2036
India Gift Card and Incentive Card Market Size, Share, and Industry Trends Forecast 2026-2036
India Gift Card and Incentive Card Market Foresight
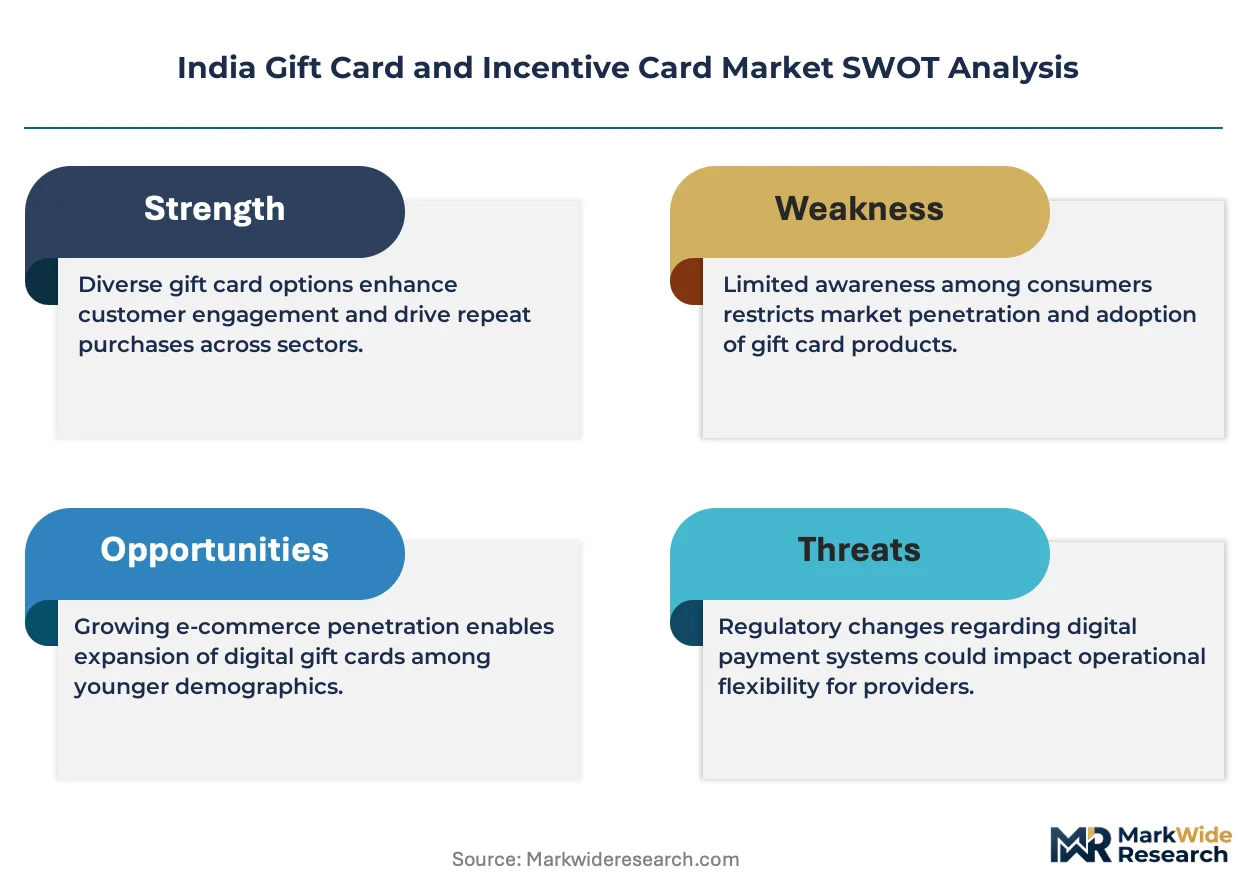
BIS certification for prepaid payment instruments is reorganizing issuer eligibility and platform interoperability standards across India. QwikCilver leverages its enterprise-grade API infrastructure to anchor corporate incentive card distribution for Fortune 500 employers. Woohoo sustains brand dominance in experiential gifting through curated marketplace partnerships with hospitality and lifestyle merchants. Pine Labs competes via its point-of-sale terminal network that extends closed-loop gift card acceptance to tier-two and tier-three retail counters.
India gift cards and incentive cards constitute prepaid stored-value instruments issued in physical or digital form, typically bearing a magnetic stripe, EMV chip, or tokenized credential redeemable across affiliated merchant networks for goods, services, or experiential benefits. These instruments function as non-cash payment mechanisms designed to transfer purchasing power from giver to recipient while enabling issuers to capture float revenue and merchant commission streams. Digital gift cards are recording the steepest volume trajectory as UPI-linked issuance eliminates plastic production costs and enables real-time delivery. Corporate incentive cards occupy the deepest margin pool given bulk enterprise procurement contracts and recurring annual redemption cycles. Retail gift cards remain the most mature segment, dominated by seasonal festivals and wedding-gifting customs that concentrate redemption spikes around Diwali and marriage calendars.
RBI's Prepaid Payment Instruments regulations, BIS data security standards, and the Digital Personal Data Protection Act collectively govern issuer licensing, customer KYC thresholds, and transaction liability frameworks. RBI mandates full KYC for PPI balances exceeding specified thresholds, pushing platforms toward Aadhaar-linked onboarding and biometric verification that shapes customer acquisition costs and platform architecture. Stakeholders must monitor how the central bank's evolving e-Rupee roadmap intersects with private gift-card float models, as sovereign digital currency distribution could displace closed-loop stored value or alternatively provide a settlement rail that reduces issuer working-capital requirements.
Market Dynamics
RBI's Prepaid Payment Instruments guidelines are compressing issuer operating models while UPI infrastructure expansion unlocks real-time digital issuance at zero marginal cost, forcing platform consolidation around API-first architectures.
Growth Catalysts
- BIS certification mandates:The Bureau of Indian Standards data-security protocols are filtering out undercapitalized issuers, concentrating volume among compliant platforms with enterprise-grade infrastructure.
- Corporate HR digitization:Human-resources departments at IT and financial-services employers are replacing cash bonuses with reloadable incentive cards, creating recurring bulk procurement contracts.
- Mumbai-Pune corridor density:Maharashtra's fintech concentration and employer clustering generate network effects that accelerate merchant acceptance and consumer redemption velocity.
Market Restraints
- Full KYC cost burden:RBI mandates for biometric verification and Aadhaar-linked onboarding inflate customer-acquisition costs for sub-threshold transaction users.
- Float capital intensity:Issuers must prefund merchant settlements while bearing redemption liability, locking working capital in low-yield stored-value pools.
- e-Rupee substitution risk:The central bank's sovereign digital currency roadmap threatens to displace private closed-loop float models with programmable central-bank liabilities.
Strategic Opportunities
- Tier-two retail penetration:Karnataka's tier-two cities and Gujarat's merchant corridors remain underserved by digital gift-card acceptance infrastructure.
- UPI-QR convergence:Integration of tokenized gift-card credentials with merchant QR codes eliminates terminal dependency and extends reach to kirana stores.
- PLI scheme alignment:Production-linked incentive schemes for electronics manufacturing could subsidize domestic EMV chip and card production, reducing import dependency.
Industry Challenges
- API interoperability complexity:Enterprise clients demand seamless integration with existing HRMS and payroll systems, stretching platform engineering resources.
- Fraud liability allocation:Ambiguity in RBI guidelines regarding unauthorized transaction responsibility between issuer, merchant, and cardholder creates legal exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Gift Card and Incentive Card Market |
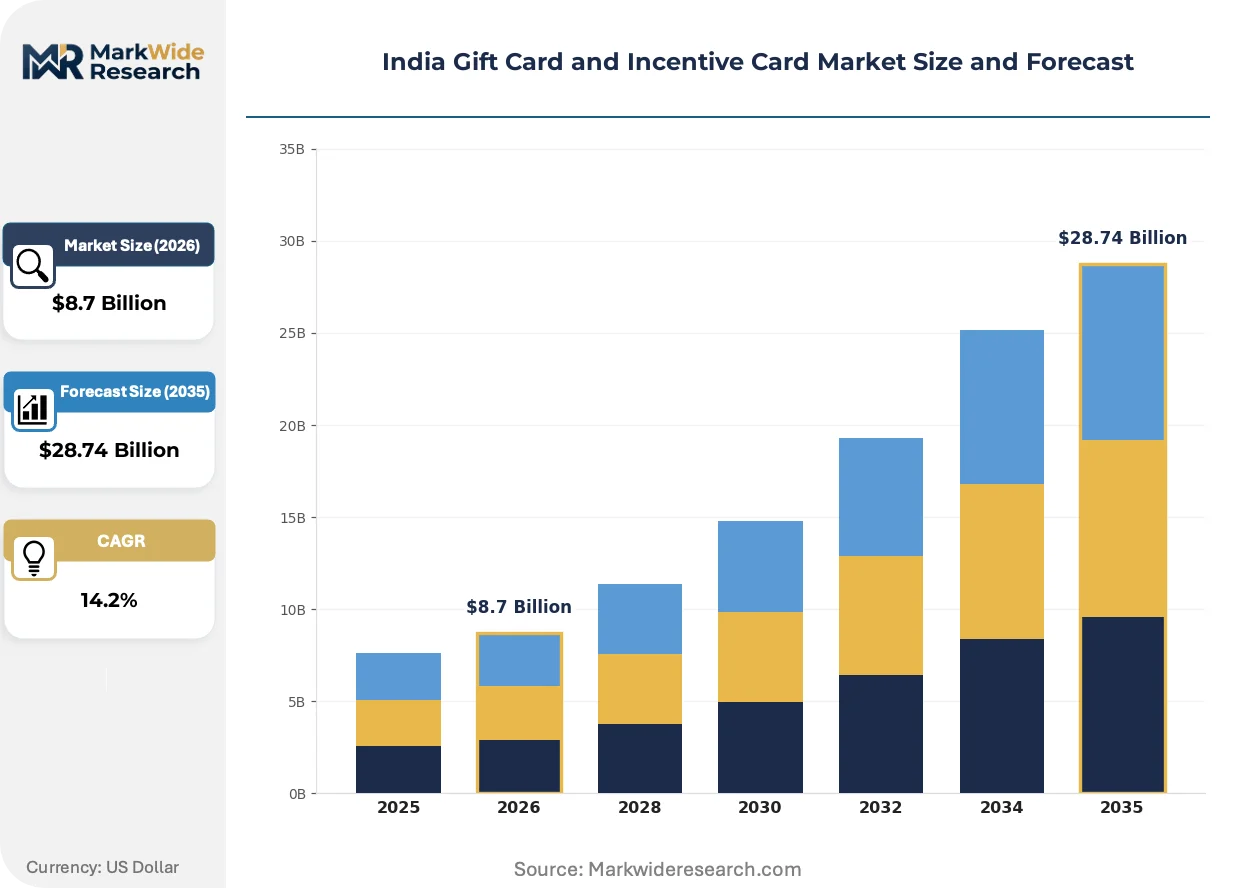
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Retail Gift Cards, Corporate Incentive Cards, Digital Gift Cards, Prepaid Cards Usage Scenario: Employee Benefits, Personal Gifting, Promotional Offers, Customer Loyalty Target Audience: Individuals, Corporates, Retailers, Non-Profits Distribution Channel: Online Platforms, Retail Outlets, Corporate Sales, Mobile Apps |
| Companies Covered | QwikCilver, Woohoo, Amazon Pay, IGP, EbixCash, Flipkart, GyFTR, Pine Labs, Paytm, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Gift Card and Incentive Card Market Shifts & Advancements
Tokenized credential architectures are collapsing issuance costs while regulatory pressure on data localization is reshaping platform infrastructure decisions across the issuer base.
Dynamic tokenization is fragmenting the traditional magnetic-stripe and EMV chip paradigm by replacing static card credentials with cryptographically generated single-use tokens. Fintech platforms and neobank issuers are deploying tokenized gift-card APIs at scale, enabling real-time issuance through messaging apps and email. This technology is fragmenting merchant acceptance networks by allowing any UPI-enabled counter to process closed-loop stored value without proprietary terminal hardware.
RBI's evolving PPI guidelines are tightening customer-protection frameworks while clarifying issuer liability boundaries. The regulatory push toward full KYC digitization and transaction monitoring is forcing platforms to rebuild core systems around Aadhaar authentication and centralized fraud registries. Smaller issuers lacking compliance infrastructure are exiting, concentrating market activity among scaled players with dedicated regulatory-technology stacks.
Enterprise procurement of incentive cards is displacing traditional cash and merchandise rewards across IT services and banking employers. Human-resources departments are consolidating vendor relationships around platforms offering integrated redemption analytics and tax-compliant disbursement reporting. This shift is most pronounced in Bengaluru's technology corridor, where employer concentration and competitive talent markets normalize non-cash compensation structures.
India Gift Card and Incentive Card Market Segmentation
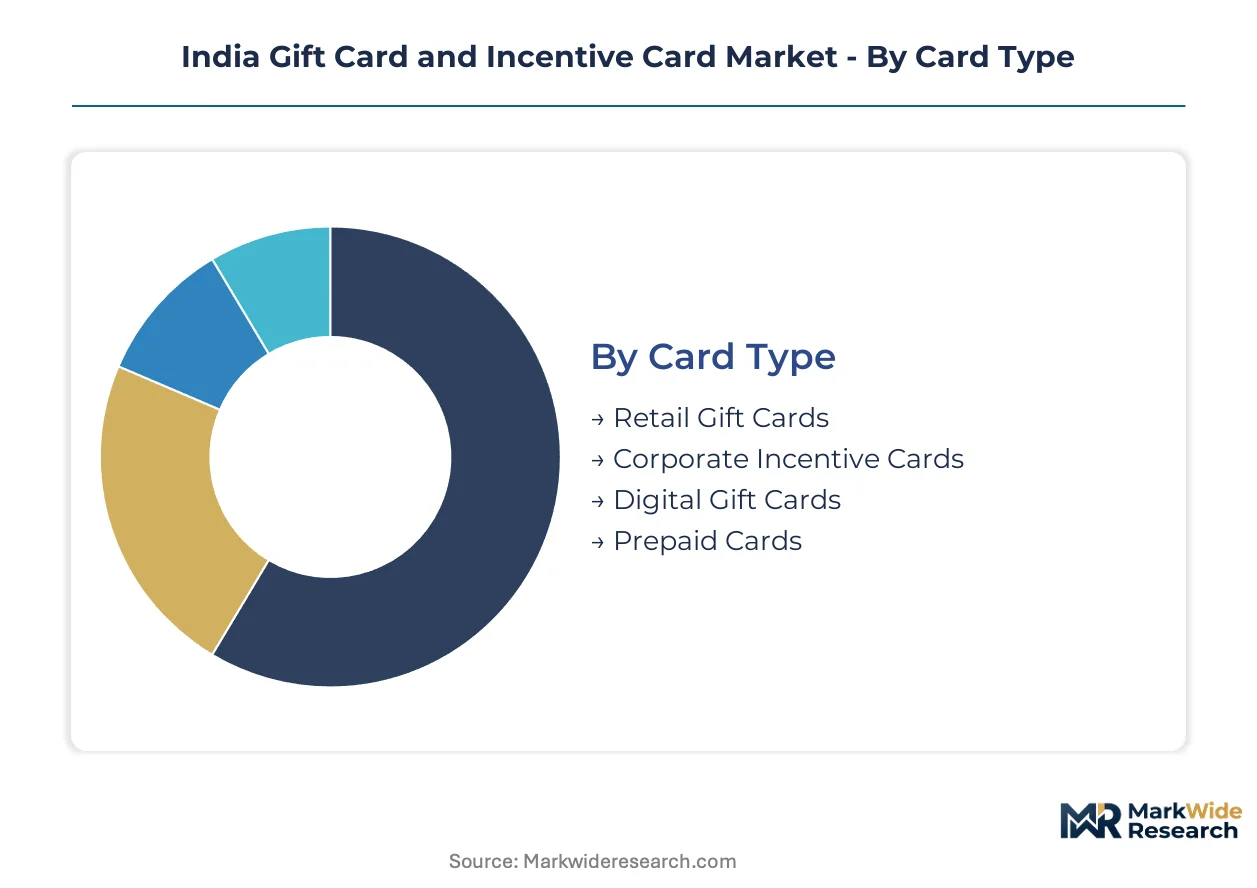
Segmentation in India's gift card market reveals how regulatory architecture and distribution economics allocate margin pools across issuer types. Understanding these divisions clarifies where RBI compliance costs bite deepest and which channels escape float capital intensity.
Card Type:
Margin concentration flows toward instruments capturing enterprise procurement volume and recurring redemption cycles, while plastic-dependent formats absorb compliance overhead.
- Retail Gift Cards:Physical and digital instruments redeemable across affiliated merchant networks for consumer goods and services. Maharashtra's Mumbai-Pune corridor generates dense circulation around Diwali and wedding calendars, though seasonal spikes strain working capital. The dominant share belongs to Retail Gift Cards, while Digital Gift Cards is closing the gap fastest.
- Corporate Incentive Cards:Reloadable stored-value instruments issued through bulk HR procurement contracts with integrated tax reporting and redemption analytics. Bengaluru's IT employer concentration normalizes non-cash compensation structures, creating recurring annual contracts with superior margin profiles.
- Digital Gift Cards:Tokenized credentials delivered via messaging apps and email, eliminating plastic production costs through UPI-linked real-time issuance.
- Prepaid Cards:General-purpose reloadable instruments regulated under RBI PPI guidelines with full KYC requirements and biometric verification thresholds.
Enterprise procurement instruments command premium economics, while consumer-facing formats compete on distribution reach.
Usage Scenario:
Application patterns trace employer digitization maturity and merchant promotional intensity across India's urban corridors.
- Employee Benefits:Tax-compliant disbursement instruments replacing cash bonuses and merchandise rewards. Karnataka's technology corridor drives standardization as competitive talent markets normalize card-based compensation.
- Personal Gifting:Occasion-driven transfer of purchasing power through festivals, weddings, and celebrations concentrated in western and southern states.
- Promotional Offers:Campaign-linked stored value issued by merchants to acquire customers and clear inventory, common in apparel and electronics retail.
- Customer Loyalty:Points-conversion instruments retaining high-frequency purchasers through reloadable reward balances.
Employee-directed applications absorb the deepest compliance investment, while promotional usage tolerates lighter KYC tiers.
Target Audience:
Customer-type segmentation exposes divergent acquisition economics and lifecycle value profiles across issuer portfolios.
- Corporates:HR and procurement departments at IT services, banking, and financial services employers demanding API integration with existing payroll systems. Bulk contracts amortize platform development costs across high-volume redemption.
- Individuals:End consumers purchasing for personal gifting or self-use, requiring frictionless onboarding but generating lower per-account revenue.
- Retailers:Merchant networks accepting closed-loop instruments and capturing commission revenue on redemption.
- Non-Profits:Charitable disbursement programs utilizing prepaid instruments for beneficiary transfers with audit-compliant transaction trails.
Corporate relationships anchor issuer profitability, while individual accounts scale through digital onboarding automation.
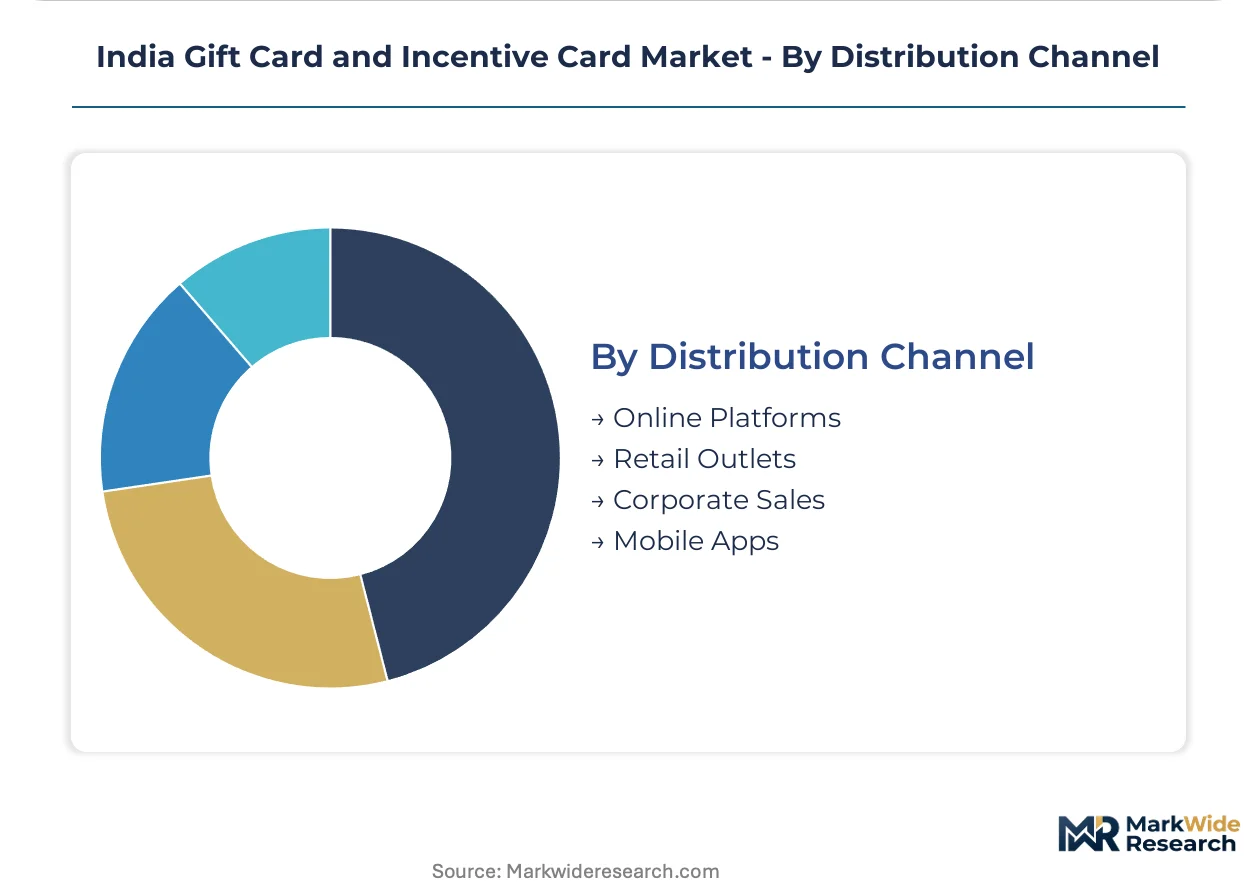
Distribution Channel:
Channel economics reflect terminal infrastructure requirements and the accelerating displacement of physical distribution by API-first architectures.
- Online Platforms:Web-based issuance portals enabling real-time credential delivery without inventory carrying costs. UPI integration eliminates settlement friction and extends reach beyond metro boundaries.
- Retail Outlets:Physical counters requiring EMV terminal acceptance and plastic inventory management, concentrated in tier-one malls and department stores.
- Corporate Sales:Direct B2B procurement relationships with integrated HRMS connectivity and bulk fulfillment logistics.
- Mobile Apps:Smartphone-native distribution leveraging biometric authentication and tokenized credential storage for immediate redemption.
Terminal-dependent channels face compression as UPI-QR convergence enables kirana store acceptance without proprietary hardware investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RBI's PPI guidelines and UPI infrastructure expansion are concentrating gift card circulation in India's fintech-dense corridors where corporate employer clustering generates network effects.
Maharashtra
Mumbai-Pune corridor anchors the densest gift card circulation through IT employer concentration and banking sector procurement. BIS certification mandates filter issuer eligibility toward compliant platforms. Mumbai's fintech ecosystem accelerates merchant acceptance velocity across Diwali and wedding gifting calendars.
Karnataka
Bengaluru's technology corridor normalizes non-cash compensation structures through competitive talent markets. RBI full KYC requirements shape platform onboarding architecture. The city's enterprise procurement density creates recurring annual contracts with superior margin economics.
Gujarat
Ahmedabad-Surat merchant corridors remain underserved by digital gift card acceptance infrastructure. PLI schemes for electronics manufacturing could subsidize domestic EMV chip production. Surat's textile and diamond trading networks present untapped closed-loop instrument opportunities.
Delhi-NCR
Government procurement and public sector HR digitization drive incentive card adoption across Noida and Gurugram. Digital Personal Data Protection Act compliance reshapes platform data localization decisions. The region's retail mall density concentrates physical gift card distribution.
Telangana
Hyderabad's pharmaceutical and IT services employers expand prepaid instrument adoption for employee rewards. UPI-QR convergence extends tokenized credential acceptance to tier-two retail counters. The city's startup ecosystem incubates API-first issuance platforms.
India Gift Card and Incentive Card Market Competitive Landscape
Listed leaders compete with private specialists across API infrastructure and merchant network dimensions, creating a tiered structure where scale advantages concentrate among RBI-compliant platforms. Enterprise-grade players anchor corporate procurement relationships while experiential gifting specialists dominate consumer-facing distribution. Three archetypes define positioning: API-first B2B infrastructure providers, curated marketplace operators, and point-of-sale terminal network extenders. Competitive moves center on UPI integration partnerships and tier-two retail penetration strategies.
Within the enterprise infrastructure tier, QwikCilver and Pine Labs occupy positions shaped by their technical architectures, while Woohoo exemplifies the curated marketplace archetype through hospitality and lifestyle merchant partnerships. These three represent distinct competitive vectors—API distribution, terminal network extension, and experiential curation—that collectively span the value chain from issuance through redemption.
| Leading Market Players |
|---|
| QwikCilver |
| Woohoo |
| Amazon Pay |
| IGP |
| EbixCash |
| Flipkart |
| GyFTR |
| Pine Labs |
| Paytm |
| Others |
Supply & Pricing Matrix
API infrastructure scale economies among RBI-compliant platforms compress per-unit issuance costs while concentrating margin capture among scaled issuers with dedicated regulatory-technology stacks. This scale dynamic elevates price floors for undercapitalized entrants and rewards enterprise-grade players with bulk procurement leverage across Mumbai-Pune and Bengaluru corridors.
Pricing Analysis
Certification level under BIS data-security protocols creates the primary spread between premium enterprise-grade issuers and marginal operators. Pricing stratifies across API-integrated corporate platforms, curated marketplace operators, and terminal-dependent retail distributors. Cost compression in plastic-dependent formats intensifies as UPI-linked digital issuance eliminates production overhead. Corporate HR departments exhibit lowest price sensitivity given tax compliance and analytics integration requirements, while individual consumers drive commoditization through app-based comparison shopping.
Supply Chain Analysis
Inventory cycles for EMV chip cards and magnetic-stripe plastic stretch 6-12 weeks against real-time digital credential delivery. Hardware components draw from Taiwan semiconductor foundries, Chinese plastic card manufacturers, and domestic BIS-certified personalization facilities. Single-source vulnerability concentrates in EMV chip imports subject to DGFT licensing and PLI scheme eligibility. Distribution runs through API-first B2B platforms, retail terminal networks, and direct corporate sales channels with diverging working capital intensity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corporate HR digitization across IT and financial services employers signals early-cycle expansion with penetration depth still below saturation in tier-two merchant corridors.
For Market Incumbents: Fortify API infrastructure moats through deeper HRMS integration and biometric authentication stack investment. Defensive consolidation should prioritize acquiring tier-two terminal network operators before UPI-QR convergence eliminates hardware dependency. The e-Rupee roadmap presents substitution threat requiring float model diversification into analytics and loyalty services. For New Entrants and Emerging Players: BIS certification fast-track through domestic EMV personalization partnerships unlocks regulatory barrier clearance. White-space concentration sits in Gujarat's Ahmedabad-Surat merchant corridors and Hyderabad's pharmaceutical employer clusters. Go-to-market should anchor on kirana store UPI-QR integration bypassing terminal infrastructure requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among corporate incentive card platforms with annual contract renewal cycles and embedded payroll system integration. Long-term viability favors issuers with regulatory-technology autonomy and float management discipline. Acquisition target archetype combines API infrastructure with underserved geography penetration. Monitor RBI e-Rupee pilot expansion as inflection signal for private float model displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| UPI-QR Integration Partnership | Extends tokenized credential acceptance to kirana stores without proprietary terminal hardware investment. |
| BIS Certification Acceleration | Filters competitor eligibility while concentrating volume among compliant platforms with enterprise-grade infrastructure. |
| Corporate HRMS Platform Integration | Locks in recurring bulk procurement contracts through embedded payroll system connectivity and tax reporting automation. |
| Tier-Two Retail Network Expansion | Captures underserved merchant density in Gujarat and Karnataka secondary cities before terminal-dependent entrants. |
| Domestic EMV Personalization Capacity | Reduces import dependency and PLI scheme alignment through captive chip production and BIS-compliant facilities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with corporate HR procurement leads, fintech platform engineers, RBI compliance officers, and merchant network managers. Secondary validation drew from RBI PPI circulars, BIS certification registries, UPI transaction disclosures, and PLI scheme notifications. Bottom-up issuer volume estimates triangulated against top-down corporate incentive spend benchmarks.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation across card type, usage scenario, target audience, and distribution channel dimensions. CAGRs derived from regression analysis of historical issuance velocity against UPI infrastructure expansion curves and corporate HR digitization indices. Industry-specific inputs incorporated float yield assumptions and merchant commission rate evolution.
Underlying assumptions cover RBI regulatory stability, UPI penetration continuity, and corporate incentive policy persistence, with deviation risk concentrated in e-Rupee substitution timing and BIS certification enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Mpos Terminals Market
Payments
Payment Security Market
Payments
Japan Credit Cards Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
Bus Card Reader Market
Payments
Europe Prepaid Card Market
Payments
Asia Pacific Real Time Payment Market
Payments
Convergent Billing Market
Payments
India Real Time Payments Market
Payments
Europe Accounts Payable Automation Market
Payments
Accelerator Card Market
Payments
France Buy Now Pay Later Services Market
Payments
3D Secure Payment Authentication Market
Payments
China Payments Market
Payments
APAC Mobile Payments Market
Payments
UAE Card Payments Market