
 Global Automated Algo Trading Market | 2026-2036
Global Automated Algo Trading Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Algo Trading Market Analysis
Singapore's financial infrastructure build-out is rewriting competitive dynamics for automated execution platforms in Asia-Pacific. VIRTU Financial Inc. leverages its proprietary market-making technology across multiple asset classes globally. AlgoTrader sustains its open-source architecture advantage for quantitative hedge funds seeking customization flexibility. Tata Consultancy Services Limited anchors enterprise deployments through its consulting-led implementation model for tier-one banks.
Automated algo trading encompasses software systems that execute orders using pre-programmed instructions accounting for timing, price, and volume parameters, typically achieving sub-millisecond response times through direct market access connectivity. These systems serve primarily to minimize market impact, capture arbitrage opportunities, and manage risk across fragmented liquidity venues. Cloud-based deployment models represent the fastest-expanding segment as buy-side firms migrate from legacy on-premises installations to elastic compute environments. Statistical arbitrage strategies occupy the deepest margin pools among trading strategy segments due to infrastructure intensity and talent scarcity. Execution venue fragmentation across ECNs and dark pools continues to drive demand for smart order routing sophistication.
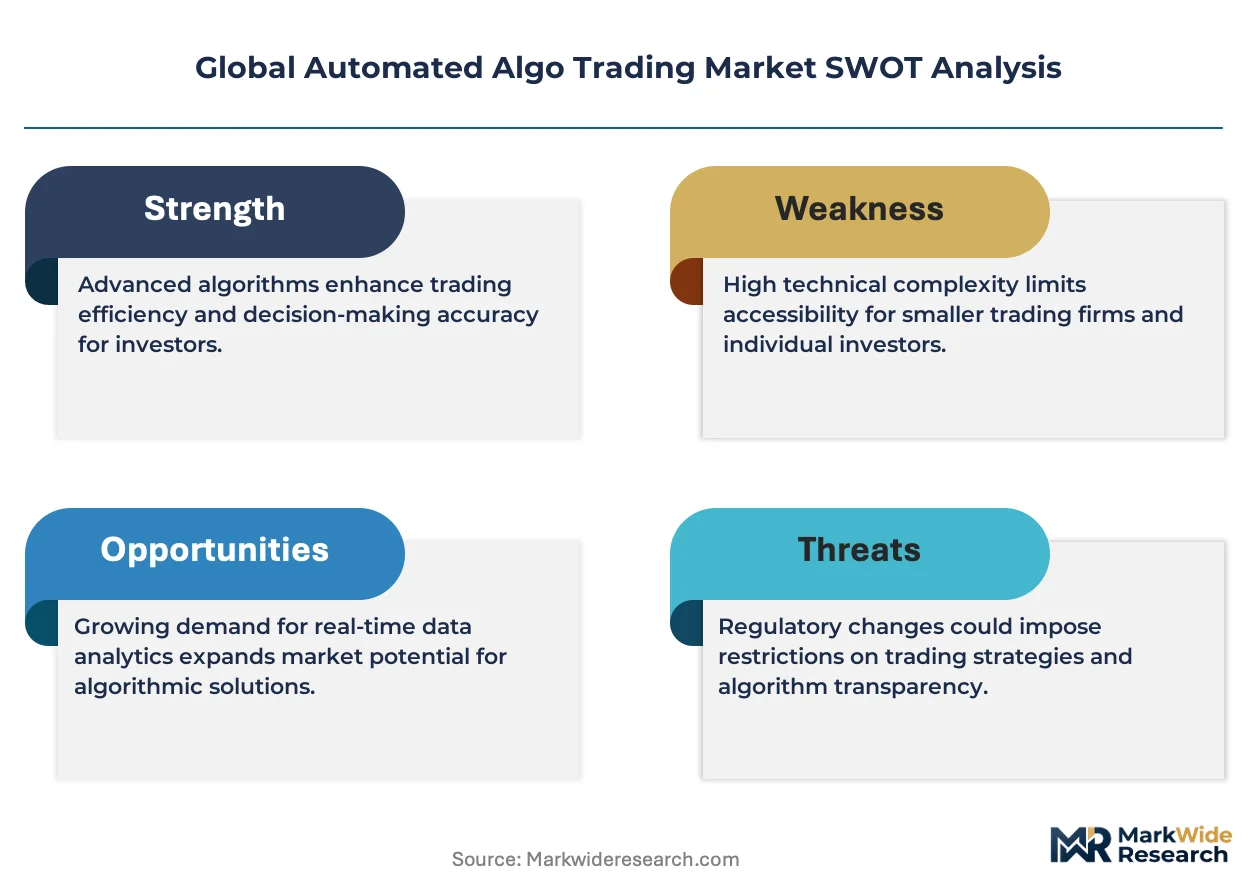
The SEC's Regulation SCI mandates system resiliency standards for equity trading infrastructure, while the EU's MiFID II framework imposes algorithm testing and kill-switch requirements across European venues. Singapore's Monetary Authority enforces technology risk management guidelines that shape vendor qualification processes for regional banks. Stakeholders must monitor evolving cross-border data localization requirements that threaten to fragment cloud-based platform architectures.
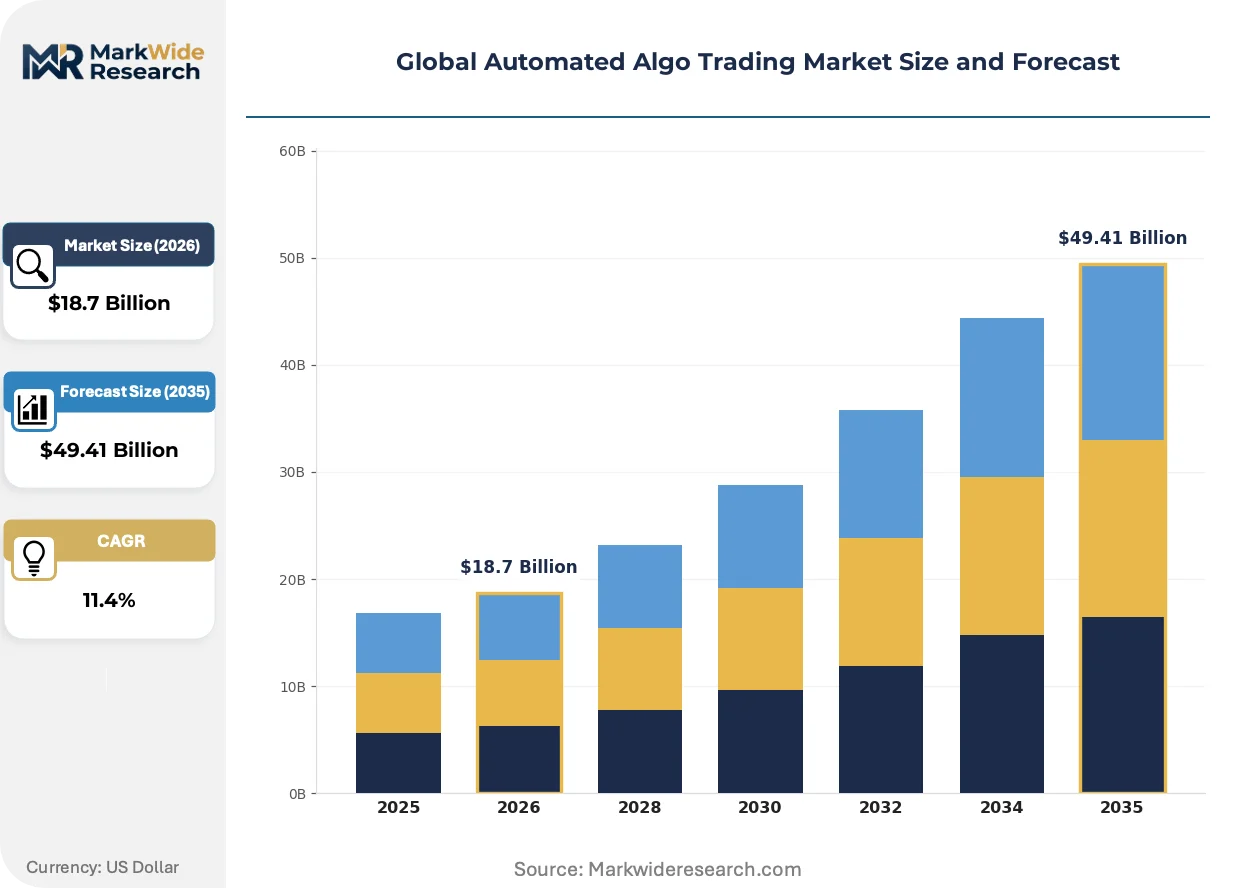
Market Dynamics
Cloud migration is compressing infrastructure ownership cycles as buy-side firms abandon captive data centers for elastic compute environments, while regulatory fragmentation across jurisdictions forces parallel compliance architectures.
Growth Catalysts
- SEC Regulation SCI:Mandates for system resiliency and disaster recovery are forcing trading venues to upgrade matching engine infrastructure, creating replacement demand for low-latency connectivity solutions.
- Smart order routing:Fragmentation across ECNs and dark pools in the United States is driving sophistication requirements for execution algorithms that optimize across multiple liquidity venues simultaneously.
- Singapore's MAS guidelines:Technology risk management standards for regional banks are accelerating vendor qualification processes and standardizing procurement criteria for automated platforms.
Market Restraints
- Co-location cost inflation:Premium pricing for physical proximity to exchange matching engines in financial centers is squeezing margins for smaller quantitative funds.
- Sub-millisecond latency floors:Physics limitations on fiber-optic transmission speeds between London and New York are creating hard performance ceilings for cross-venue arbitrage strategies.
- EU MiFID II kill-switch mandates:Pre-trade risk controls and algorithm testing requirements are extending deployment timelines and raising compliance overhead for European deployments.
Strategic Opportunities
- Brazil's B3 exchange modernization:Upgrades to the São Paulo exchange's derivatives infrastructure are creating first-mover advantages for foreign automated trading vendors entering Latin America.
- Machine learning convergence:Integration of reinforcement learning with traditional statistical arbitrage models is opening alpha generation in less efficient emerging market venues.
- API-first distribution:Direct connectivity to broker-dealer execution platforms is disintermediating traditional vendor-installed software models for mid-sized hedge funds.
Industry Challenges
- FPGA programming scarcity:Specialized hardware acceleration for tick-to-trade latency requires talent pools concentrated at a handful of technology firms and proprietary trading shops.
- Multi-venue certification complexity:Each exchange's unique market data protocols and order entry specifications demand bespoke integration engineering for cross-platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Algo Trading Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Trading Strategy: Statistical Arbitrage, Trend Following, Market Making, Mean Reversion Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Hedge Funds, Investment Banks, Retail Traders, Asset Managers Execution Venue: Exchanges, ECNs, Dark Pools, OTC Markets |
| Companies Covered | VIRTU Financial Inc., AlgoTrader, Argo Software Engineering, InfoReach, Inc., Kuberre Systems, Inc., MetaQuotes Ltd., Tata Consultancy Services Limited, 63 moons technologies limited, Trading Technologies International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Algo Trading Market Emerging Trajectories
Execution infrastructure is bifurcating between ultra-low-latency co-located systems and cloud-native elastic architectures, with regulatory technology spending consuming an expanding share of technology budgets.
Field-programmable gate arrays are hybridizing software-defined trading logic with hardware-accelerated execution paths. Tier-one banks and high-frequency trading firms are deploying FPGA-based tick-to-trade pipelines for options market-making and futures arbitrage. This convergence is compressing the viable latency window for purely software-based competitors and concentrating infrastructure investment among capital-rich participants.
The EU's AI Act is imposing transparency and risk management obligations on algorithmic trading systems that deploy machine learning components. Firms must document training data provenance and maintain human oversight mechanisms for autonomous execution decisions. Buy-side asset managers with European fund domiciles are restructuring model governance frameworks to satisfy documentation and audit trail requirements.
Consolidated tape fragmentation is forcing buy-side firms to subscribe to multiple proprietary data feeds rather than relying on single-source market data. Multi-venue execution desks in the United States are unbundling market data procurement from execution services and negotiating direct exchange agreements. This disintermediation is eroding traditional broker-dealer value propositions built on consolidated data resale.
Global Automated Algo Trading Market Segmentation
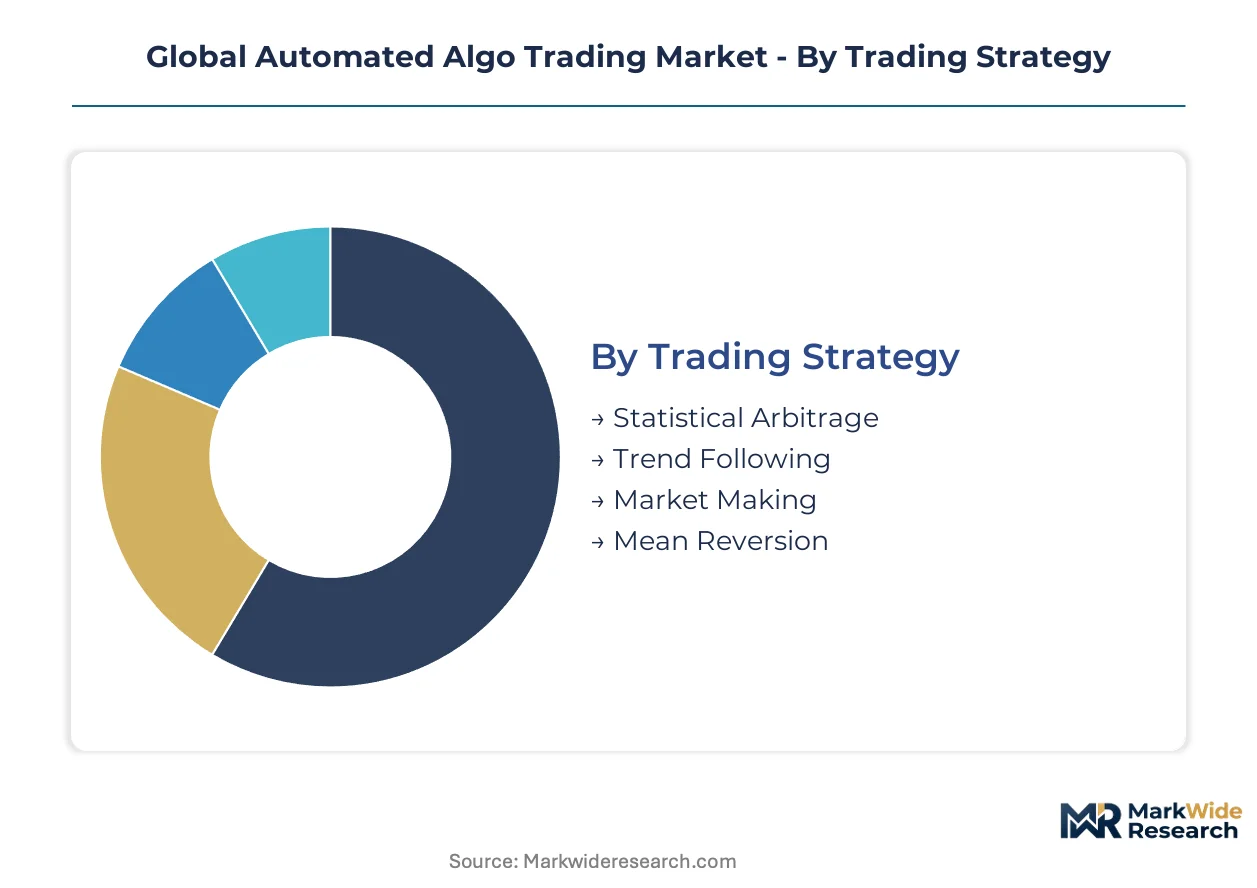
Automated algo trading systems fragment across execution methodology, infrastructure ownership, client sophistication, and liquidity venue type. Each segmentation dimension carries distinct margin profiles and regulatory exposure. Vendor positioning requires matching technical architecture to the specific operational constraints of each segment combination.
Trading Strategy:
Application focus determines infrastructure intensity and talent requirements across the strategy spectrum.
- Statistical Arbitrage:Multi-factor models exploit price divergences between correlated instruments, demanding co-located servers and microwave networks for inter-venue latency arbitrage. Hedge funds in Chicago and London concentrate deployment here, constrained by physics limitations on cross-Atlantic transmission speeds.
- Market Making:Continuous two-sided quoting across options and futures requires FPGA-accelerated tick-to-trade pipelines and real-time Greek calculations. Proprietary trading firms dominate this segment, facing compressed spreads from exchange maker-taker fee competition.
- Trend Following:Momentum-based systematic strategies operate on longer holding periods with lower infrastructure sensitivity. Commodity trading advisors favor this approach for capacity scalability across futures markets.
- Mean Reversion:Counter-trend models identify temporary price dislocations, common in equity pairs trading and fixed-income basis trades. Asset managers deploy these for risk-adjusted return enhancement in constrained mandates.
Statistical Arbitrage holds installed capacity. Market Making is rotating up the share rankings.
Deployment Model:
Cost tier stratification separates capital-intensive ownership from operational expenditure models.
- Cloud-Based:Elastic compute environments enable burst capacity for backtesting and strategy deployment without captive data center investment. Buy-side firms migrating from legacy installations drive demand, though exchange co-location requirements limit pure-cloud adoption for latency-sensitive strategies.
- On-Premises:Dedicated hardware in captive or third-party facilities maintains sub-microsecond control for high-frequency strategies. Tier-one banks sustain these deployments despite maintenance overhead and depreciation cycles.
- Hybrid:Split architectures combine cloud-based analytics with co-located execution engines, balancing cost efficiency with latency performance. Mid-sized quantitative funds favor this model for regulatory reporting flexibility.
- SaaS:Vendor-managed platforms reduce engineering headcount requirements through standardized APIs and pre-built strategy templates. Retail aggregators and smaller asset managers access institutional-grade execution without infrastructure investment.
On-Premises retains the largest installed base. Cloud-Based is climbing the fastest.
End User:
Customer type dictates pricing power, customization demands, and sales cycle duration.
- Hedge Funds:Discretionary and systematic managers prioritize alpha generation infrastructure, driving demand for bespoke algorithm development and direct market access customization. Fee compression across the industry is forcing technology budget consolidation.
- Investment Banks:Sell-side execution desks require multi-asset coverage and client algorithm customization for corporate and institutional order flow. Regulatory capital requirements are constraining proprietary risk-taking capacity.
- Asset Managers:Long-only institutions emphasize transaction cost analysis and best execution documentation for fiduciary compliance. MiFID II and SEC best execution obligations shape procurement criteria.
- Retail Traders:Individual investors access algorithmic execution through broker-provided smart order routing and copy-trading platforms. Zero-commission brokerage models have democratized entry-level automated trading tools.
Hedge Funds command vendor attention. Asset Managers are gaining procurement influence.
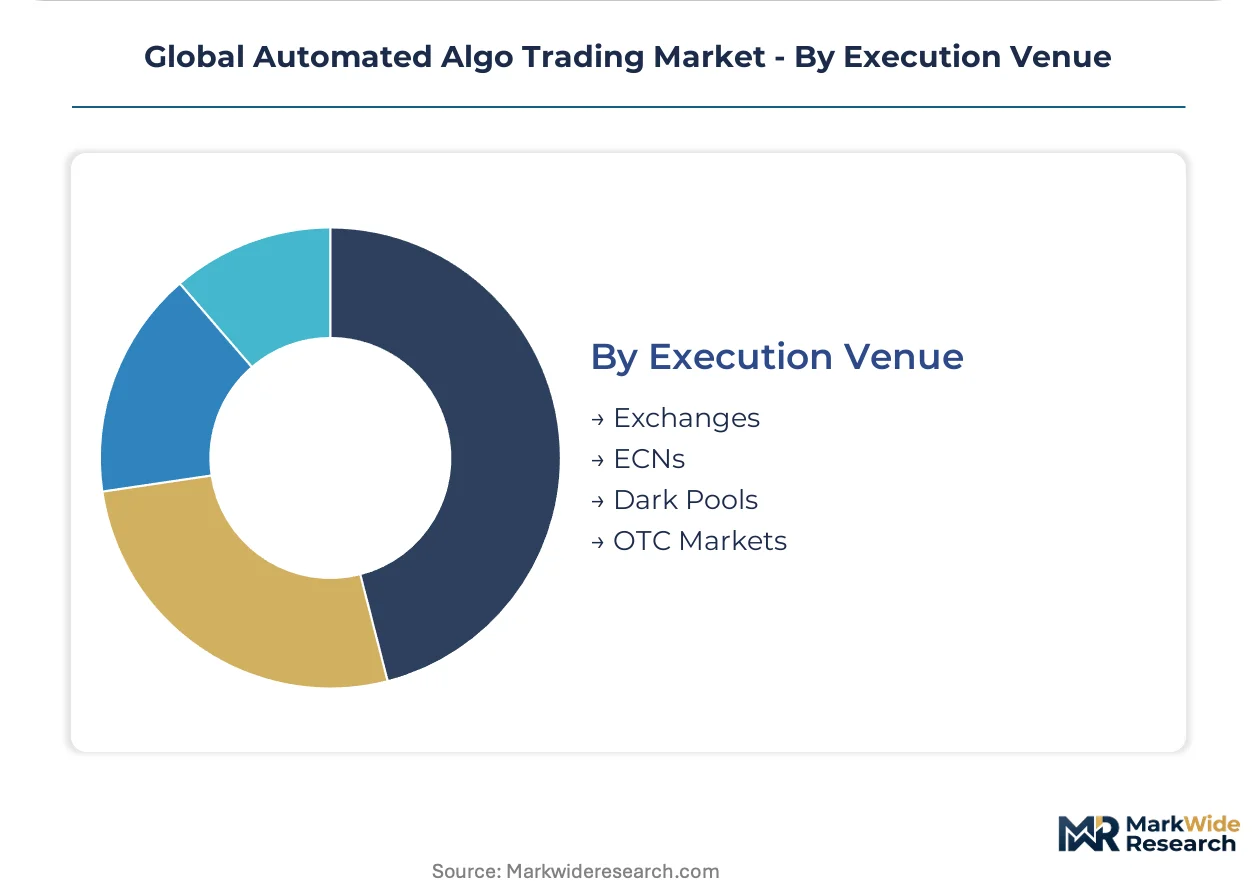
Execution Venue:
Venue fragmentation creates complexity premiums for connectivity and smart order routing sophistication.
- Exchanges:Central limit order books with transparent price discovery and regulatory oversight remain the foundation for listed derivatives and equity trading. Singapore Exchange and Brazil's B3 are modernizing matching engines to attract foreign automated flow.
- Dark Pools:Non-displayed venues minimize market impact for large institutional orders through midpoint crossing and conditional order types. Regulatory pressure on minimum price improvement is constraining volume growth.
- ECNs:Electronic communication networks fragment liquidity across competing price centers in US equities, demanding sophisticated order routing to access protected quotes. Consolidated tape limitations force multi-feed subscriptions.
- OTC Markets:Bilateral negotiation and request-for-quote protocols dominate fixed income, foreign exchange, and bespoke derivatives. Post-trade reporting mandates under MiFID II and Dodd-Frank increase operational overhead.
Exchanges retain structural volume dominance. Dark Pools are defending share against lit venue innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The CME-Singapore Exchange fiber link underwrites Asia-Pacific's execution velocity, while transatlantic microwave networks between London and New York anchor inter-venue arbitrage capacity.
United States
SEC Regulation SCI mandates system resiliency standards that force trading venues to upgrade matching engine infrastructure. The consolidated tape limitations under SEC oversight push multi-venue desks toward direct exchange agreements. Chicago's derivatives cluster concentrates co-located server farms for futures arbitrage strategies.
Singapore
Monetary Authority of Singapore technology risk management guidelines accelerate vendor qualification processes for regional banks. The Singapore Exchange matching engine modernization attracts foreign automated flow seeking Asia-Pacific liquidity access. Marina Bay's financial district hosts expanding data center capacity for low-latency connectivity.
United Kingdom
FCA and Bank of England supervisory frameworks impose operational resilience requirements on trading infrastructure. EU MiFID II algorithm testing and kill-switch mandates extend deployment timelines for cross-border platforms. London's Canary Wharf cluster sustains microwave network termini for sub-millisecond European connectivity.
Germany
BaFin enforcement of MiFID II pre-trade risk controls raises compliance overhead for automated platform deployments. Eurex's derivatives infrastructure upgrades create replacement demand for connectivity solutions. Frankfurt's TaunusTurm data center anchors co-location capacity for continental European execution.
Brazil
B3 exchange modernization in São Paulo creates first-mover advantages for foreign automated trading vendors entering Latin America. CVM regulatory frameworks shape algorithm governance requirements for domestic asset managers. The city's financial district concentrates emerging market execution infrastructure investment.
Global Automated Algo Trading Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the latency-optimization stack. The vendor base stratifies between capital-intensive infrastructure owners and software-defined solution providers. Three archetypes dominate: exchange-facing market makers, cloud-native platform vendors, and consulting-led enterprise deployers. Consolidation pressure favors acquisition of specialized connectivity firms, while geographic expansion targets emerging exchange modernizations.
Among North American market makers, VIRTU Financial Inc. exemplifies multi-asset execution infrastructure at scale. AlgoTrader occupies a position within the open-source customization tier for quantitative hedge funds. Tata Consultancy Services Limited anchors the consulting-led implementation archetype for tier-one banking deployments.
| Leading Market Players |
|---|
| VIRTU Financial Inc. |
| AlgoTrader |
| Argo Software Engineering |
| InfoReach, Inc. |
| Kuberre Systems, Inc. |
| MetaQuotes Ltd. |
| Tata Consultancy Services Limited |
| 63 moons technologies limited |
| Trading Technologies International, Inc. |
| Others |
Supply Flow & Price Mechanics
Chicago's derivatives infrastructure cluster concentrates FPGA programming talent and co-located server capacity, creating scarcity premiums that cascade into tier-one bank procurement budgets and mid-sized fund cost compression.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates vendor offerings, with premium tiers capturing latency-sensitive hedge funds through sub-microsecond guarantees and dedicated support, while economy SaaS tiers serve retail aggregators via standardized APIs. Price differentiation hinges on certification level under SEC Regulation SCI and customization depth for multi-venue connectivity. Pricing pressure stems from cloud migration enabling elastic compute alternatives to captive infrastructure. Retail traders exhibit highest price sensitivity, whereas systematic hedge funds prioritize performance over cost.
Supply Chain Analysis
Contract manufacturing for specialized hardware acceleration concentrates among Taiwan Semiconductor Manufacturing and select domestic foundries serving FPGA vendors and microwave network equipment providers. Component sourcing draws from Taiwan, South Korea, and the United States for semiconductors and optical transmission gear. Single-source vulnerability around advanced FPGA fabrication creates procurement risk. Distribution runs through direct vendor relationships with tier-one banks and proprietary trading firms, supplemented by cloud marketplace channels for SaaS tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native platform architectures are disrupting traditional installed-software models, with the EU AI Act's transparency mandates accelerating vendor consolidation around compliant governance frameworks.
For Market Incumbents: Pre-empt margin erosion from API-first distribution by acquiring specialized connectivity firms with proven multi-venue certification expertise. Lock in tier-one bank relationships through backward integration into co-location facility ownership, securing physical proximity to exchange matching engines that cloud competitors cannot replicate. The kill-switch compliance overhead under MiFID II and EU AI Act documentation requirements favor capital-rich incumbents with dedicated regulatory technology teams.
For New Entrants and Emerging Players: Build out machine learning convergence offerings for emerging market venues where traditional statistical arbitrage infrastructure is underdeployed. Brazil's B3 exchange modernization presents the most penetrable geography for foreign automated trading vendors seeking first-mover positioning. Target mid-sized quantitative funds through hybrid deployment models combining cloud analytics with co-located execution engines, emphasizing regulatory reporting flexibility as the primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platform vendors with SaaS distribution models, offering superior cash-flow predictability versus project-based implementation services. Long-term viability favors vendors with demonstrated cross-border regulatory compliance capabilities spanning SEC, FCA, and MAS frameworks. Acquisition priority rests on FPGA-accelerated tick-to-trade technology specialists. Monitor quarterly exchange modernization announcements from Singapore Exchange and Brazil's B3 as inflection indicators for regional demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates fragmented smart order routing across ECN and dark pool connectivity under unified APIs. |
| Acquisition of Specialist Firm | Captures FPGA programming talent pools concentrated at proprietary trading shops and technology vendors. |
| Geographic Expansion | Establishes presence in São Paulo ahead of B3 exchange derivatives infrastructure upgrades. |
| Product Launch | Introduces reinforcement learning modules for emerging market statistical arbitrage alpha generation. |
| Strategic Partnership | Secures direct exchange agreements bypassing consolidated tape limitations under SEC oversight. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, exchange infrastructure disclosure documents, and regulatory technology vendor procurement databases. Interviews with quantitative hedge fund CTOs, sell-side execution desk heads, exchange connectivity engineers, and regulatory compliance officers at tier-one banks informed demand-side validation. Secondary sources include FCA operational resilience guidance, MAS technology risk management circulars, and Eurex infrastructure upgrade announcements. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the analysis window.
Forecast inputs span deployment model migration rates, co-location capacity expansion, and regulatory compliance spending as percentage of technology budgets. Segmentation dimensions modeled include trading strategy intensity, infrastructure ownership tier, client sophistication level, and liquidity venue fragmentation. CAGRs derive from elasticity-adjusted adoption curves calibrated to observed cloud migration patterns in adjacent financial technology markets. Machine learning integration timelines and emerging exchange modernization schedules serve as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud providers into financial services verticals would shift outcomes materially. Model assumptions incorporate gradual regulatory fragmentation rather than harmonization. Quarterly review of exchange matching engine upgrade announcements, co-location pricing disclosures, and AI Act implementation guidance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Currency Exchange Bureau Software Market
Financial Services
Commodity Trade Finance Market
Financial Services
Global Treasury Software Market
Financial Services
Australia Gift Card and Incentive Card Market
Financial Services
Spain E-Brokerage Market
Financial Services
Canada Credit Cards Market
Financial Services
Germany E-Brokerage Market
Financial Services
Global Executive Search (Headhunting) Market
Financial Services
Benefits Consulting Service Market
Financial Services
Liquidation Service Market
Financial Services
Hyperinflation System Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
ATM Software Market
Financial Services
White Glove Services Market
Financial Services
China Factoring Services Market