
 United States POS Terminals Market | 2026-2036
United States POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
United States POS Terminals Market Analytics
Quick-service restaurant deployment of integrated payment hardware is hardening across franchise networks. Toast Inc. leverages cloud-native architecture to sustain its position in hospitality-centric verticals. NCR Voyix Corporation anchors its competitive stance through legacy banking channel control and broad retail coverage. Block Inc. differentiates via software-integrated hardware ecosystems that extend beyond pure transaction processing into merchant services.
POS terminals constitute electronic payment acceptance devices combining secure card readers, PIN entry modules, and network connectivity interfaces to process debit, credit, and digital wallet transactions at the point of sale. These systems employ tamper-resistant security modules and end-to-end encryption protocols to safeguard cardholder data during transmission to payment processors. Mobile terminals and integrated terminals command structural attention, with the former capturing growth from pop-up retail and delivery-centric hospitality formats, while the latter consolidates payment, inventory, and customer management into single-platform deployments that command premium positioning. Desktop terminals remain a mature revenue pool sustained by cost-sensitive independent merchants and legacy banking channel distribution.
The Federal Reserve Board oversees payment system stability and influences terminal network access standards, while PCI Security Standards Council mandates govern hardware encryption and data protection compliance across all deployed devices. NIST cybersecurity frameworks additionally shape firmware authentication requirements for connected terminal ecosystems. Stakeholders must monitor evolving PCI DSS version transitions and FedNow real-time payment integration demands to calibrate hardware refresh timelines and certification investments.
Market Dynamics
PCI DSS version transitions are compressing hardware refresh cycles across merchant networks. FedNow real-time payment integration demands are forcing terminal architecture redesigns ahead of legacy sunset timelines.
Growth Catalysts
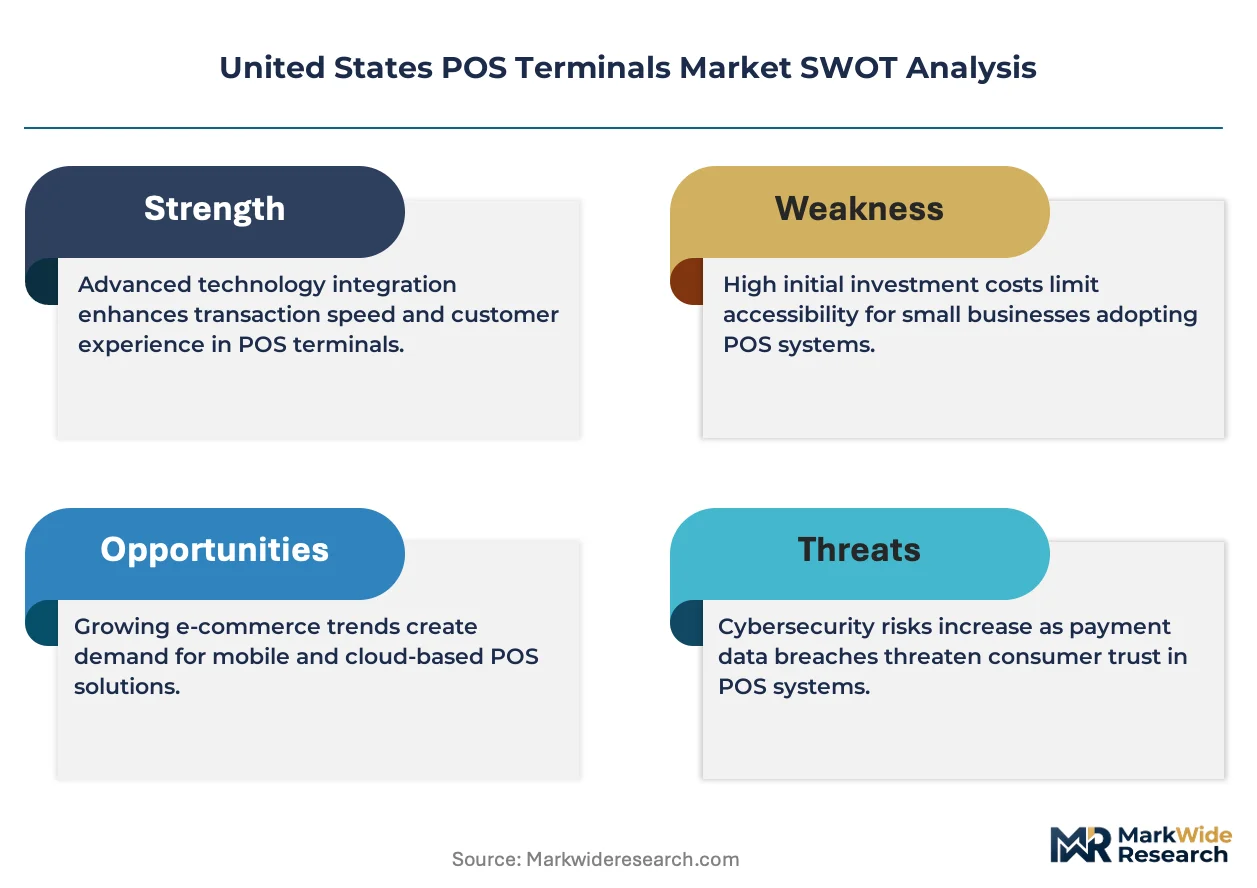
- PCI DSS 4.0 compliance deadlines:Merchant processors face mandated encryption upgrades that accelerate terminal replacement schedules across franchise networks and independent retail locations.
- Quick-service restaurant digitization:Drive-through and delivery-optimized formats demand integrated payment-inventory systems that consolidate transaction processing with kitchen display coordination.
- California merchant density:The state's concentration of high-volume retailers generates disproportionate hardware procurement volumes that sustain manufacturer certification investments.
Market Restraints
- Semiconductor supply concentration:Secure element chip fabrication relies on a limited supplier base concentrated in East Asian foundries, exposing terminal manufacturers to input volatility.
- Firmware certification friction:NIST cybersecurity framework compliance adds 6-12 month validation timelines that delay product launches and compress revenue recognition windows.
- Mobile wallet substitution pressure:Smartphone-based tap-to-pay reduces merchant dependency on dedicated terminal hardware in low-volume retail environments.
Strategic Opportunities
- Texas and Florida underpenetration:These high-growth state economies exhibit lower terminal density per merchant capita than coastal markets, presenting expansion whitespace for integrated platform vendors.
- Software-integrated hardware ecosystems:Convergence of payment processing with payroll, inventory, and loyalty management creates subscription revenue streams beyond terminal sale margins.
- IRA small business technology incentives:Federal tax credits for merchant technology upgrades accelerate procurement decisions among cost-sensitive independent retailers.
Industry Challenges
- EMV certification backlog:Laboratory testing capacity constraints extend time-to-market for new terminal models, forcing manufacturers to sequence regional launches.
- Legacy system integration complexity:Banking core modernization lags require terminal vendors to maintain backward compatibility with decades-old authorization protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States POS Terminals Market |
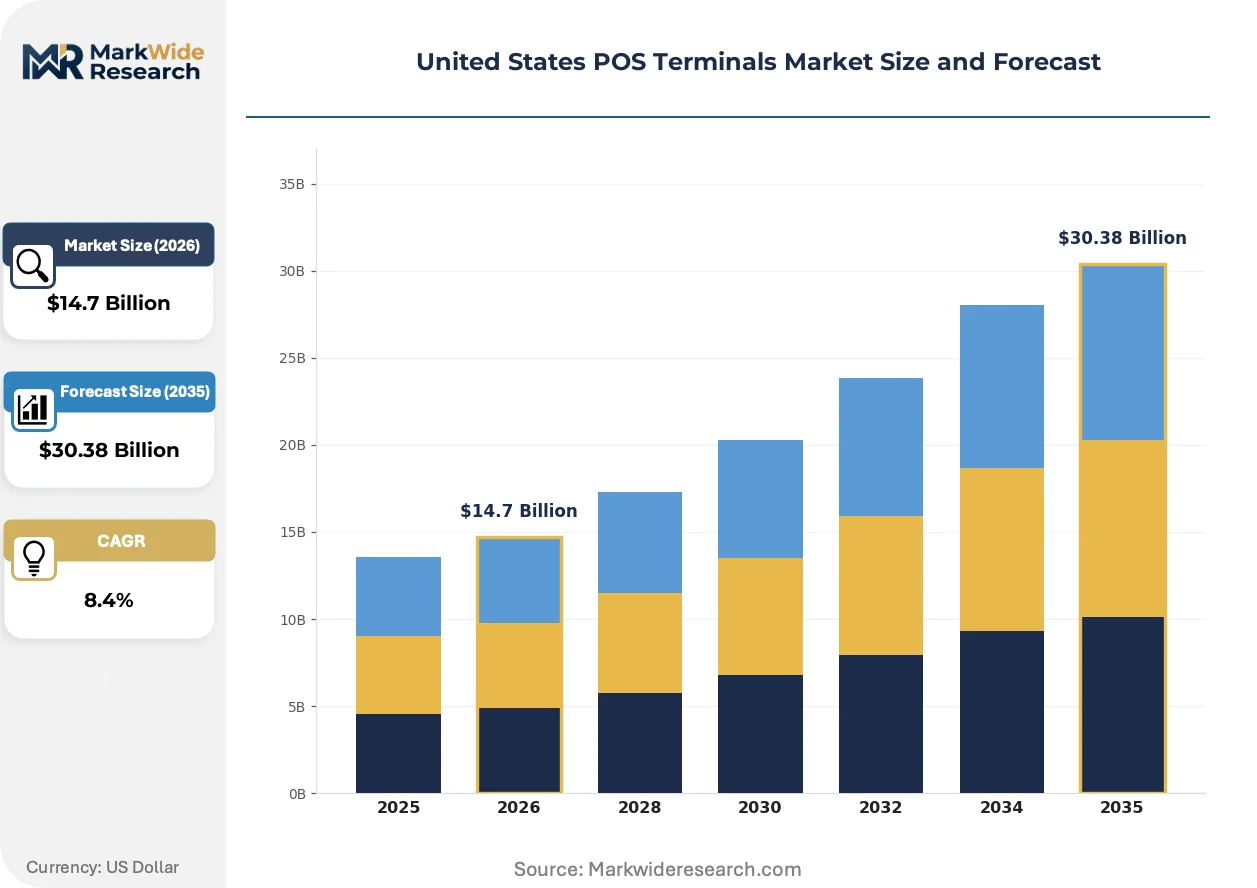
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.38 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Terminals, Desktop Terminals, Integrated Terminals, Self-Service Kiosks Technology: Contactless Payments, EMV, NFC, QR Code End User: Retail, Hospitality, Healthcare, Entertainment Sales Channel: Direct Sales, Online Retail, Distributors, Value-Added Resellers |
| Companies Covered | VeriFone Systems Inc., Ingenico Inc., NCR Voyix Corporation, PAX Technology Inc., Block Inc., Toast Inc., Clover Network LLC, BBPOS Limited, Castles Technology Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States POS Terminals Market Evolving Landscape
Cloud-native terminal architectures are displacing on-premise payment stacks. Software-defined functionality enables rapid feature deployment without hardware replacement.
Tap-to-pay on Android and iOS is rewriting merchant acquisition economics. Small retailers in urban corridors adopt smartphone-based acceptance without dedicated terminal investment. This compression threatens low-end hardware margins while pushing manufacturers toward integrated software-service bundles.
FedNow real-time payment standards are reshaping terminal network requirements. The Federal Reserve Board's instant settlement mandate forces processor gateway upgrades. Quick-service restaurants and grocery chains face the steepest compliance timelines as transaction volume thresholds trigger early adoption deadlines.
Merchant procurement patterns favor subscription-based hardware provisioning. Independent retailers in secondary metros lease terminals with bundled software licenses rather than capitalizing equipment purchases. Texas and Arizona markets exhibit this shift most prominently, with payment facilitators capturing relationship control from traditional banking channels.
United States POS Terminals Market Segmentation
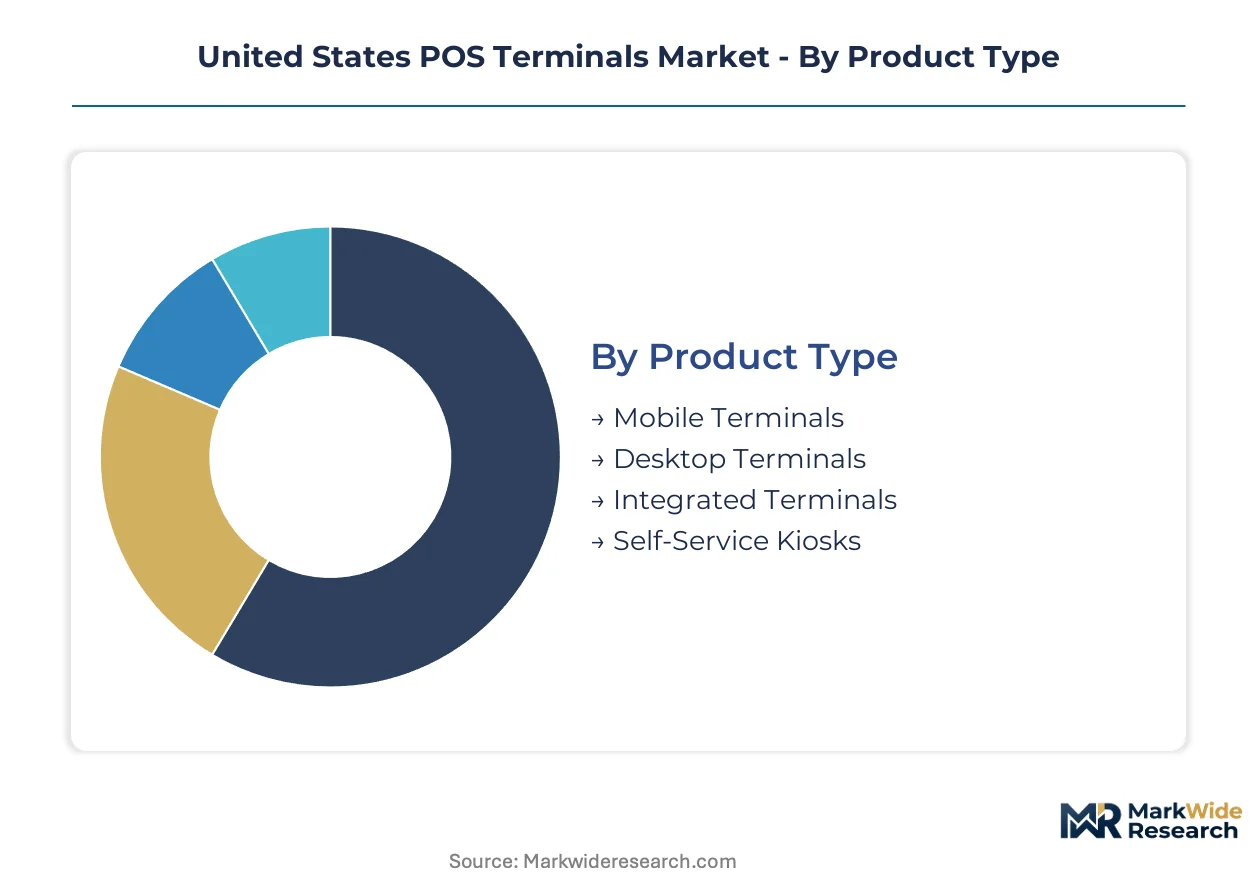
POS terminal segmentation reveals divergent capital requirements across hardware categories, with integrated systems demanding substantial upfront platform investment while mobile alternatives enable lower-barrier entry. Technology choices further stratify deployment economics, as contactless infrastructure and EMV compliance impose distinct certification burdens on merchant networks.
Product Type:
Integrated terminals command the highest capital intensity, requiring unified hardware-software platforms that consolidate payment processing with operational management systems.
- Mobile Terminals:Battery-powered wireless devices with cellular or Wi-Fi connectivity enable transaction acceptance beyond fixed counter locations. Pop-up retail in Texas and delivery-optimized quick-service restaurants in Florida are absorbing these units fastest, driven by FedNow real-time payment integration mandates that favor flexible deployment architectures.
- Desktop Terminals:Countertop card readers with PIN pads and receipt printers represent the mature hardware baseline. Cost-sensitive independent merchants in secondary California metros sustain procurement volumes here, though PCI DSS 4.0 encryption upgrades are compressing replacement cycles across legacy banking channels.
- Integrated Terminals:Single-platform systems combining payment, inventory, kitchen display, and customer management into unified deployments. Premium positioning in quick-service restaurant franchise networks justifies substantial upfront investment.
- Self-Service Kiosks:Customer-facing ordering and payment stations with embedded card readers and touchscreen interfaces. Grocery chains and entertainment venues in New York are piloting these for labor cost containment.
Desktop terminals absorb the bulk of installed capacity; mobile terminals are expanding most quickly.
Technology:
Certification timelines and hardware retrofit requirements create sharp cost tier differentiation across payment protocols.
- Contactless Payments:Tap-to-transact protocols using radio frequency communication eliminate physical card insertion. California merchant density drives disproportionate deployment, with smartphone wallet proliferation accelerating terminal refresh decisions.
- EMV:Chip-card authentication standards mandating dynamic data encryption for counterfeit fraud prevention. Laboratory testing backlogs at certification facilities extend time-to-market for new hardware models.
- NFC:Near-field communication enabling proximity data exchange between terminals and enabled devices. Quick-service restaurant drive-through optimization favors this low-latency protocol.
- QR Code:Optical scanning-based payment initiation linking to digital wallet applications. Low-volume urban retailers adopt this without dedicated terminal investment.
EMV compliance absorbs the bulk of certification resources; contactless capabilities are climbing the fastest.
End User:
Transaction volume thresholds and customer throughput requirements shape procurement scale across vertical markets.
- Retail:High-frequency transaction environments spanning grocery, convenience, and specialty merchandise. California and New York merchant ecosystems generate concentrated hardware procurement volumes.
- Hospitality:Restaurants, bars, and hotels requiring payment-inventory-kitchen coordination. Quick-service digitization is hardening reliance on integrated systems across franchise networks.
- Healthcare:Clinics and pharmacies with HIPAA-compliant payment processing needs. Patient-facing terminals require enhanced data protection architectures.
- Entertainment:Venues, stadiums, and theaters with seasonal demand spikes and mobile concession requirements.
Retail commands the greatest installed base; hospitality is gaining share fastest.
Sales Channel:
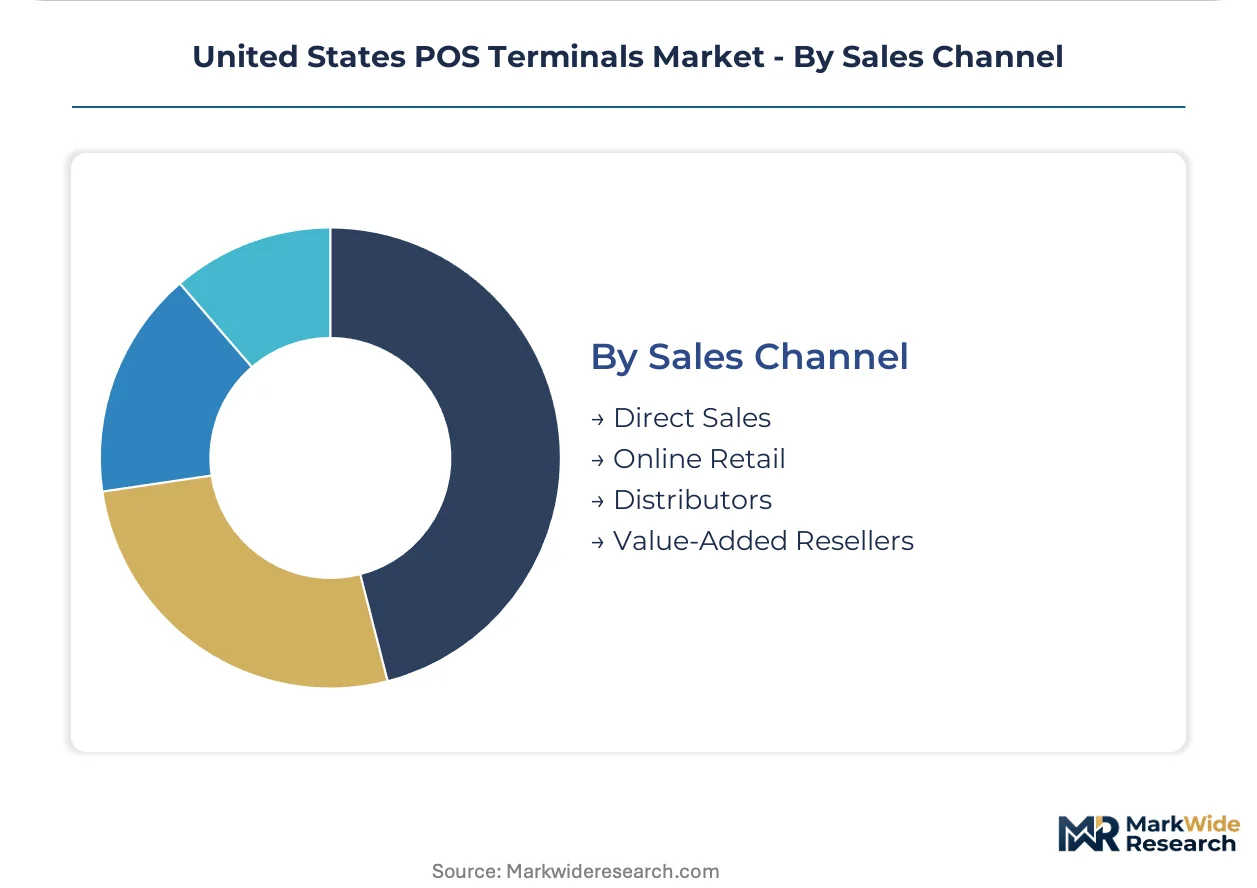
Relationship control and margin capture vary substantially across distribution architectures.
- Direct Sales:Manufacturer-to-merchant relationships enabling customized platform integration. Enterprise hospitality chains favor this channel for multi-location standardization.
- Online Retail:E-commerce procurement with self-service configuration and rapid fulfillment. Independent retailers in Texas secondary markets increasingly adopt this low-friction path.
- Distributors:Wholesale intermediaries aggregating multiple manufacturer lines for regional reseller networks. Legacy banking channels maintain substantial reliance here.
- Value-Added Resellers:Solution providers bundling hardware with software, installation, and ongoing support. Subscription-based provisioning models favor this relationship-intensive channel.
Distributors retain the bulk of legacy volume; value-added resellers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Terminal production concentrates in coastal manufacturing corridors, while consumption spreads across merchant-dense metropolitan zones. The Federal Reserve Board's payment system oversight and PCI DSS mandates shape deployment timelines unevenly across state jurisdictions.
California
Silicon Valley hardware engineering and Los Angeles merchant density generate concentrated procurement volumes. The California Consumer Privacy Act imposes data handling standards that exceed baseline federal requirements. San Francisco's quick-service restaurant clusters absorb integrated terminals fastest, with cloud-native platforms dominating franchise network refresh cycles.
Texas
Houston energy sector payroll integration and Dallas-Fort Worth retail expansion drive hardware demand. The Texas Department of Banking regulates money services businesses affecting terminal network access standards. Austin's startup ecosystem incubates mobile-first payment facilitators that bypass traditional banking channels.
New York
Manhattan financial services infrastructure and Brooklyn hospitality density sustain premium terminal positioning. The New York Department of Financial Services enforces cybersecurity regulations that accelerate encryption upgrade schedules. Long Island grocery chains pilot self-service kiosk deployments for labor cost containment.
Florida
Miami tourism sector seasonal spikes and Orlando entertainment venue concentration favor flexible terminal provisioning. The Florida Office of Financial Regulation oversees payment processor licensing affecting merchant acquisition economics. Tampa's quick-service restaurant networks adopt mobile terminals for delivery-optimized formats.
Illinois
Chicago logistics hub transaction volumes and Midwest manufacturing payroll integration sustain desktop terminal procurement. The Illinois Department of Financial and Professional Regulation shapes payment facilitator compliance frameworks. Rockford's independent retail corridors exhibit subscription-based hardware leasing adoption.
United States POS Terminals Market Competitive Landscape
Top-tier vendors anchor enterprise hospitality and banking channels, while mid-tier specialists capture independent merchant segments through software-integrated bundles. The vendor base stratifies across cloud-native platforms, legacy hardware incumbents, and payment facilitator ecosystems. Three archetypes dominate: integrated software-hardware providers, banking channel-dependent manufacturers, and smartphone-based acceptance disruptors. Consolidation pressure intensifies through strategic partnerships and vertical capability acquisitions.
Within the cloud-native platform tier, Toast Inc. exemplifies hospitality-centric vertical integration, while Block Inc. occupies a position spanning software-integrated hardware and merchant services expansion. NCR Voyix Corporation anchors legacy banking channel control with broad retail coverage. These three entities represent divergent strategic postures: vertical software stack ownership, ecosystem breadth, and incumbent channel leverage.
| Leading Market Players |
|---|
| VeriFone Systems Inc. |
| Ingenico Inc. |
| NCR Voyix Corporation |
| PAX Technology Inc. |
| Block Inc. |
| Toast Inc. |
| Clover Network LLC |
| BBPOS Limited |
| Castles Technology Co. Ltd. |
| Others |
Value Network & Pricing Analysis
PCI DSS 4.0 compliance deadlines are compressing procurement timelines across merchant networks, forcing terminal manufacturers to expedite secure element sourcing and certification workflows that inflate input costs and compress margin structures at the mid-tier.
Pricing Analysis
Short lead-time premiums dominate pricing differentiation in the terminal market, with FedNow-mandated architecture upgrades commanding expedited fulfillment rates. Three-tier pricing structure across premium, standard, and economy levels stratifies by EMV certification grade and after-sales service bundling. Cost compression in economy desktop terminals is intensifying because smartphone tap-to-pay substitution erodes dedicated hardware demand among low-volume merchants. Independent retailers in secondary Texas metros exhibit highest price sensitivity, while enterprise hospitality chains in California absorb premium integrated system positioning with minimal negotiation.
Supply Chain Analysis
Workforce availability constraints in Taiwan and South Korea are tightening secure element chip fabrication capacity, extending order backlogs for terminal manufacturers. Production draws from East Asian foundries for cryptographic processors, with secondary assembly concentrating in Mexico and Vietnam for North American market proximity. Single-source vulnerability in TSMC-adjacent packaging facilities exposes supply continuity to geopolitical friction. Distribution runs through banking channel intermediaries and value-added reseller networks, with direct manufacturer-to-merchant relationships capturing enterprise hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secure element chip fabrication capacity represents the binding constraint propping terminal pricing, with foundry slot allocation favoring volume commitments from tier-one vendors and marginalizing mid-tier competitors.
For Market Incumbents: Cement channel control through exclusive certification partnerships with FedNow gateway providers, locking out competitor terminal interoperability. Deepen backward integration into firmware development to compress NIST cybersecurity validation timelines and accelerate product launch velocity against cloud-native disruptors.
For New Entrants and Emerging Players: Launch via subscription-based hardware provisioning targeting independent retailers in Florida and Arizona secondary markets, bypassing entrenched banking channel relationships. Texas underpenetration in integrated terminal density presents whitespace for software-integrated platform vendors with payroll-inventory bundling capabilities.
For Investors and Strategic Acquirers: The window for entry favors cloud-native platform specialists with hospitality vertical penetration and recurring revenue architecture. Cloud-native terminal vendors with demonstrated FedNow integration timelines represent priority acquisition targets. Monitor PCI DSS laboratory testing capacity expansion as the inflection signal for hardware refresh cycle normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| FedNow Gateway Certification | Federal Reserve Board compliance mandates force processor architecture upgrades ahead of legacy sunset timelines. |
| Cloud-Native Platform Migration | Software-defined functionality enables rapid feature deployment without hardware replacement cycles. |
| Secure Element Supply Agreement | Long-term foundry commitments insulate against East Asian fabrication capacity volatility. |
| Vertical Software Stack Acquisition | Payroll-inventory-loyalty bundling creates subscription revenue beyond terminal sale margins. |
| Subscription Hardware Provisioning | Payment facilitators capture relationship control from traditional banking channels in Texas markets. |
Research Methodology
Multi-period observation of terminal shipment volumes, certification timeline backlogs, and merchant procurement patterns anchored the trend analysis, supplemented by interviews with payment processor executives, terminal manufacturer product managers, ISO certification laboratory directors, and franchise network technology officers. Secondary validation drew from Federal Reserve Board payment system reports, PCI Security Standards Council compliance bulletins, NIST cybersecurity framework documentation, and SEC filings from publicly traded terminal vendors. Bottom-up merchant demand modeling and top-down payment industry revenue triangulation converged on segment-level estimates.
Input-output matrices mapped secure element chip supply to terminal production capacity, with demand-side variables including PCI DSS compliance deadlines, FedNow integration mandates, and quick-service restaurant digitization trajectories across the analysis window. Segmentation modeling captured product type, payment technology protocol, end-user vertical, and sales channel dynamics. CAGRs were derived from curve-fitting observed replacement cycles against mandated upgrade timelines, with sensitivity testing around semiconductor supply volatility and mobile wallet substitution rates.
Semiconductor supply disruption, FedNow timeline acceleration, and mobile wallet penetration spikes are the dominant revision risks to terminal demand forecasts. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Money Transfer Agencies Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
LAMEA Payment Gateway Market
Payments
Hungary POS Terminal Market
Payments
Wearable Payments Market
Payments
Middle East Gift Card and Incentive Card Market
Payments
Clearing Houses and Settlements Market
Payments
Philippines Remittance Market
Payments
Europe Accounts Payable Automation Market
Payments
Remote Mobile Payment Market
Payments
Mobile Card Reader Market
Payments
M Commerce Payment Market
Payments
B2B Payments Market
Payments
United Arab Emirates Real Time Payments Market
Payments
Cyprus POS Terminals Market
Payments
Europe POS Terminal Market