
 Europe POS Terminal Market | 2026-2036
Europe POS Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Europe POS Terminal Market Analysis
Market Context
GDPR is consolidating the cost-of-entry calculus for POS terminal vendors serving European merchants. Worldline S.A. leverages its banking-grade infrastructure to anchor compliance-heavy contracts across France and Benelux. Ingenico S.A. sustains R&D intensity in secure payment modules, while SumUp Payments Limited competes aggressively on hardware-as-a-service models for micro-merchants.
Technical Definition and Structural Segments
A POS terminal is an electronic device that captures payment card data through integrated chip readers, NFC antennas, and magnetic stripe heads, processing transactions via encrypted communication with acquiring banks and payment networks. The primary commercial purpose is to authenticate and settle consumer payments at the point of purchase while generating transaction records for merchant reconciliation. Mobile POS leads volume growth among product types as street vendors and pop-up retailers abandon fixed counter installations, while Smart POS captures margin pools by integrating inventory software and customer analytics that command subscription premiums. Contactless technology dominates transaction throughput across European end users, though QR Code adoption accelerates in hospitality settings where tableside payment reduces staff touchpoints.
Regulatory Frame and Outlook
EMA payment directives, EU GDPR requirements, and CE marking standards collectively shape terminal encryption protocols, data residency obligations, and hardware safety certifications that vendors must satisfy before market entry. The European Banking Authority's strong customer authentication rules under PSD2 force continuous firmware updates that extend vendor service relationships beyond initial hardware sales. Stakeholders must monitor whether the EU AI Act's risk classification system will sweep transaction-analytics algorithms into compliance scopes that demand explainability documentation.
Market Dynamics
PSD2's strong customer authentication mandates are forcing continuous firmware refresh cycles across Europe's installed terminal base, converting one-time hardware sales into recurring service relationships that reshape vendor economics.
Growth Catalysts
- Contactless transaction thresholds:EU-wide contactless payment limits now exceed 50 euros in most member states, accelerating tap-to-pay velocity at quick-service restaurants and transit operators.
- GDPR-compliant data architecture:Terminal vendors embedding privacy-by-design encryption capture merchant contracts requiring banking-grade data residency guarantees.
- Street commerce digitization:Mobile POS adoption among German and French pop-up retailers and food truck operators displaces cash-only operations.
Market Restraints
- Semiconductor supply concentration:Secure element chip fabrication concentrates among Asian foundries, exposing European terminal assemblers to lead-time volatility.
- CE marking complexity:Radio equipment directive compliance testing extends product launch timelines by four to six months for NFC-enabled devices.
- Smartphone payment substitution:Soft-POS applications on merchant-owned devices threaten dedicated hardware attach rates among micro-enterprises.
Strategic Opportunities
- Eastern European penetration gaps:Poland, Romania, and Bulgaria retain substantial cash transaction share, creating first-mover terrain for contactless infrastructure deployment.
- EU AI Act compliance services:Transaction-analytics algorithms face emerging explainability requirements, opening advisory revenue streams for vendors with documentation capabilities.
- Hospitality software convergence:Smart POS integration with kitchen display systems and reservation platforms commands subscription premiums from full-service restaurants.
Industry Challenges
- Firmware engineering talent scarcity:Embedded systems developers with payment security expertise command premium compensation, constraining vendor R&D scaling.
- Legacy terminal migration friction:German and Italian merchants operate decade-old dial-up devices requiring complete infrastructure replacement rather than upgrade paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe POS Terminal Market |
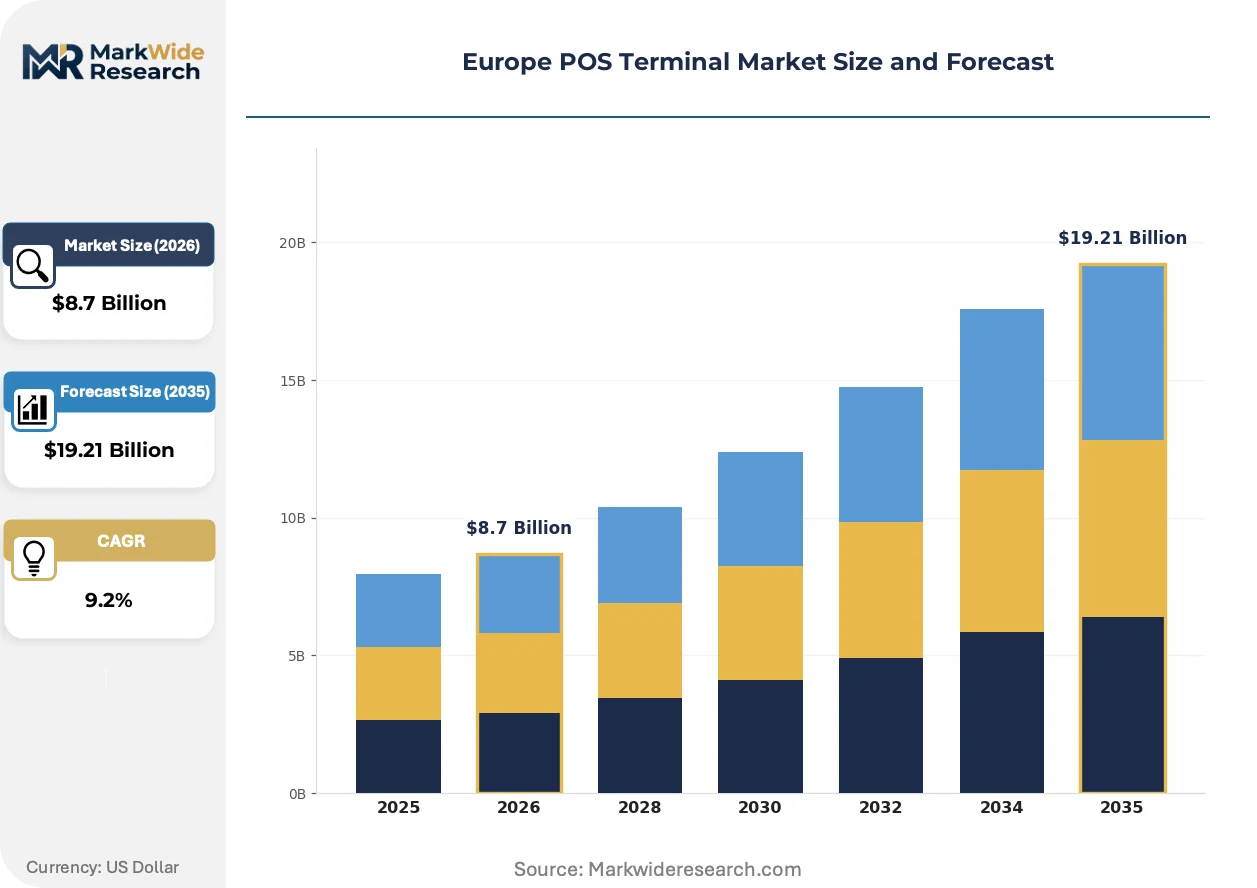
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile POS, Fixed POS, Smart POS, Terminal Management System End User: Retail Stores, Restaurants, Hotels, Service Providers Technology: Contactless, Chip & PIN, QR Code, NFC Distribution Channel: Direct Sales, Online Retail, Resellers, Distributors |
| Companies Covered | PAX Technology Limited, Diebold Nixdorf AG, Worldline S.A., Vectron Systems AG, SumUp Payments Limited, Ingenico S.A., NCR Corporation, Aures Technologies SA, Verifone Systems, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe POS Terminal Market Emerging Trajectories
Payment infrastructure across Europe is bifurcating between stripped-down mobile acceptance for transient commerce and software-rich Smart POS ecosystems for established retail, with regulatory compliance acting as the forcing function for vendor consolidation.
Biometric authentication modules are automating cardholder verification at European point-of-sale locations. Large-format grocery and pharmacy chains in France and the Netherlands pilot fingerprint-linked payment authorization to eliminate PIN entry friction. This convergence of physical identity with transaction settlement is automating checkout throughput while compressing fraud dispute resolution timelines.
The EU AI Act's risk classification framework is sweeping transaction-analytics algorithms into high-risk system categories requiring conformity assessments. Terminal vendors must now document algorithmic decision logic for customer scoring and dynamic pricing functions. French and German hospitality chains deploying behavioral analytics face immediate compliance obligations, driving procurement preference toward vendors with established AI governance documentation.
Merchant acquisition models are fragmenting across hardware-as-a-service and pure software licensing. Micro-merchants in Spain and Portugal favor zero-upfront terminal subscriptions bundled with payment processing, while mid-market retailers in Belgium and Austria negotiate unbundled software licenses for multi-location inventory synchronization. This bifurcation is most visible in the Benelux corridor where distributor relationships determine contract terms.
Europe POS Terminal Market Segmentation
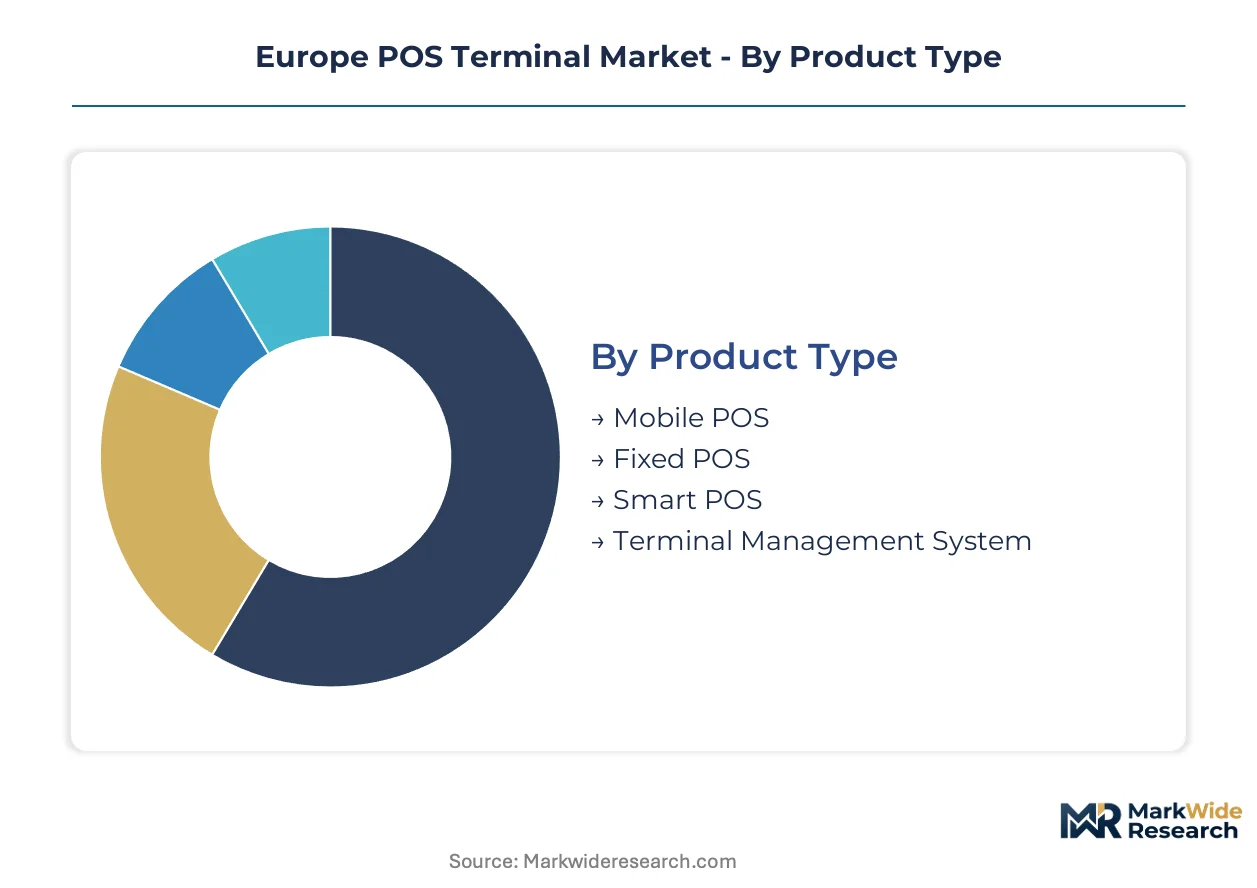
POS terminal segmentation in Europe reflects divergent capital deployment strategies across merchant tiers. Hardware specifications, compliance architectures, and service integration levels create distinct procurement patterns that vendors must navigate.
Product Type:
Capital intensity varies sharply across hardware categories, with embedded software stacks and banking-grade security modules driving upfront investment differentials.
- Mobile POS:Compact battery-powered units with Bluetooth or cellular connectivity enable street vendors and pop-up retailers to process payments without fixed infrastructure. German food truck operators and French market stall merchants are displacing cash operations fastest in this segment, though battery life and thermal printer durability constrain field reliability.
- Smart POS:Android-based terminals with integrated touchscreens, inventory applications, and customer analytics command subscription premiums from mid-market retailers. Benelux hospitality chains and Austrian full-service restaurants prioritize these units for kitchen display system integration and dynamic menu pricing capabilities.
- Fixed POS:Countertop devices with tethered connectivity serve high-volume supermarket and pharmacy checkout lanes.
- Terminal Management System:Remote firmware update and estate monitoring platforms extend vendor service relationships beyond hardware sales.
Smart POS absorbs the bulk of installed capacity; Mobile POS is expanding most quickly.
End User:
Application environments dictate terminal specification priorities, with transaction velocity and staff mobility requirements shaping hardware selection.
- Restaurants:Tableside payment acceptance and tip-adjustment workflows demand portable units with long battery cycles and intuitive interfaces. French bistros and Spanish tapas bars are deploying QR Code-enabled terminals to reduce staff touchpoints and accelerate table turns during peak service windows.
- Retail Stores:High-throughput grocery and convenience operations prioritize contactless speed and multi-lane synchronization. Large-format chains in the Netherlands and Denmark are piloting biometric authentication modules to eliminate PIN entry friction at self-checkout stations.
- Hotels:Front-desk and poolside payment acceptance requires ruggedized, tip-adjustable terminals with property management system integration.
- Service Providers:Plumbers, electricians, and mobile healthcare workers favor lightweight, receipt-capable devices for on-site billing.
Retail Stores dominate procurement volumes; Restaurants are climbing the fastest.
Technology:
Payment authentication methods are stratifying by fraud risk tolerance and consumer convenience expectations across European merchant categories.
- Contactless:NFC-enabled tap-to-pay protocols now process the majority of European card transactions, with EU-wide limits exceeding 50 euros in most member states. Quick-service restaurants and transit operators in the United Kingdom and Germany have achieved near-complete contactless penetration, though higher-value transactions still trigger PIN fallback requirements.
- NFC:Near-field communication antennas embedded in terminals and smartphones enable wallet-based acceptance without physical card presentation. Dutch and Swedish merchants are leveraging NFC for loyalty program enrollment and receipt digitization alongside payment settlement.
- Chip & PIN:EMV-compliant card insertion with offline PIN verification persists for high-value transactions and regulatory fallback scenarios.
- QR Code:Camera-based payment initiation accelerates in hospitality settings where tableside billing reduces server steps.
Contactless handles the transaction majority; QR Code is gaining share fastest.
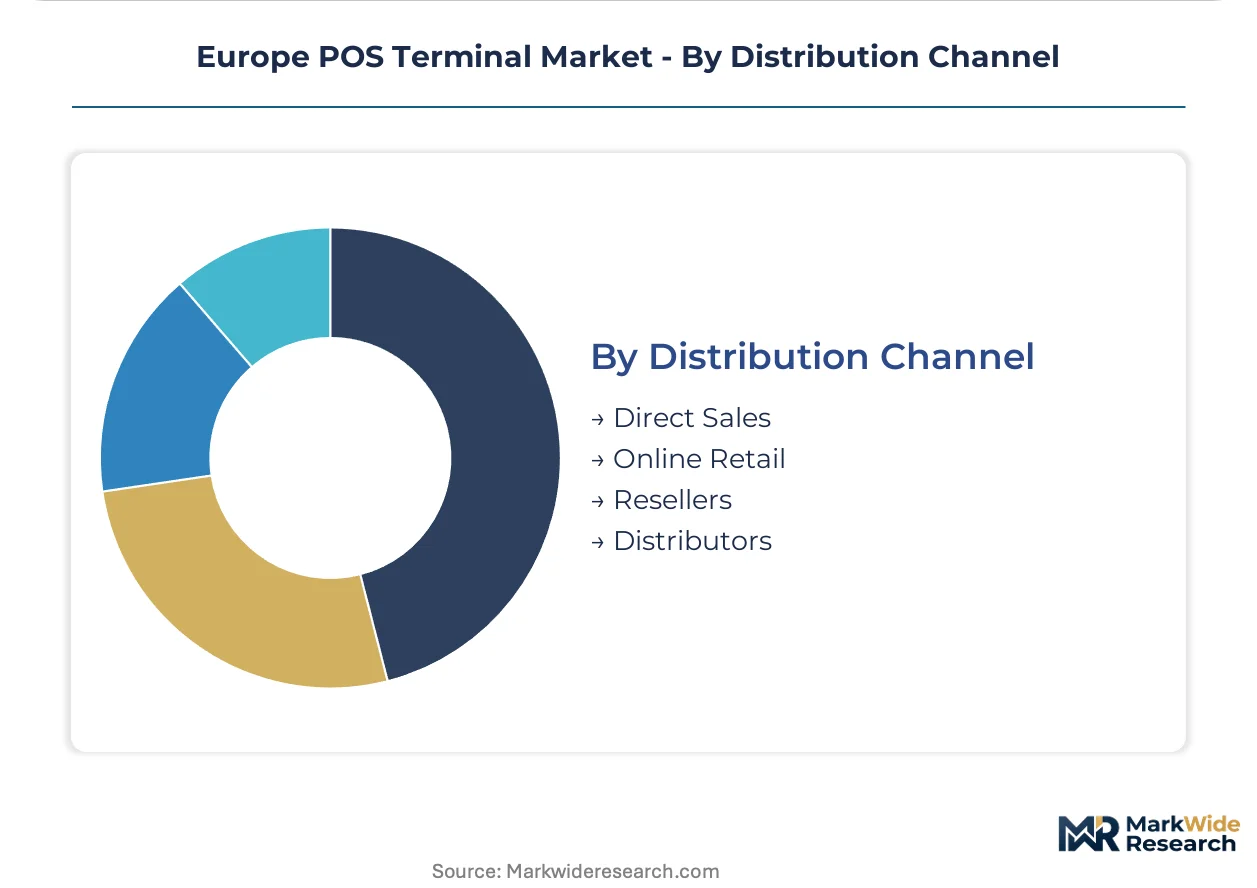
Distribution Channel:
Channel economics reflect merchant scale and service bundling preferences, with contract structures diverging across micro-enterprise and enterprise procurement patterns.
- Resellers:Regional payment service providers bundle terminal provisioning with merchant acquiring contracts, dominating micro-merchant acquisition in Spain and Portugal. These intermediaries absorb compliance complexity and provide localized support that pure hardware vendors cannot match.
- Direct Sales:Vendor field teams negotiate multi-location enterprise contracts with customized software integration and dedicated account management. Belgian and Austrian mid-market retailers favor direct relationships for unbundled software licensing across distributed store networks.
- Distributors:Wholesale electronics channels serve independent retail and hospitality operators with standardized hardware configurations.
- Online Retail:E-commerce procurement attracts tech-savvy sole proprietors seeking transparent pricing and rapid delivery.
Resellers capture the broadest merchant base; Direct Sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Benelux corridor operates as a special economic zone for payment infrastructure, with Luxembourg's financial services incentives and Amsterdam's fintech cluster concentrating terminal R&D and compliance operations. Merchant acquisition density here exceeds continental averages by substantial margins.
Germany
German quick-service restaurants and transit operators drive contactless terminal deployment, with tap-to-pay penetration reaching saturation in urban centers. The Federal Financial Supervisory Authority enforces PSD2 strong customer authentication through continuous firmware mandates. Berlin's fintech cluster hosts multiple terminal-as-a-service providers targeting micro-merchant digitization.
France
French hospitality chains prioritize Smart POS integration with kitchen display systems and dynamic menu pricing capabilities. The CNIL enforces GDPR privacy-by-design requirements that reshape terminal data architecture specifications. Paris-based Worldline S.A. anchors compliance-heavy contracts across the national merchant base.
United Kingdom
UK retailers and transport operators have achieved near-complete contactless infrastructure penetration, with biometric authentication pilots accelerating at self-checkout stations. The Financial Conduct Authority coordinates PSD2 implementation timelines with EU regulatory frameworks. London's Square Mile concentration of acquiring banks drives terminal specification standardization.
Netherlands
Dutch merchants leverage NFC-enabled terminals for loyalty program enrollment and receipt digitization alongside core payment settlement. The Dutch Central Bank supervises payment system stability and terminal security certification requirements. Amsterdam's fintech corridor attracts hardware-as-a-service providers targeting cross-border merchant operations.
Poland
Polish retail and hospitality sectors retain substantial cash transaction share, creating first-mover terrain for contactless infrastructure deployment. The Polish Financial Supervision Authority aligns national payment regulations with EU directive implementation schedules. Warsaw's emerging fintech cluster concentrates terminal distribution networks serving Eastern European expansion.
Europe POS Terminal Market Vendor Landscape
French and Benelux producers anchor the premium compliance tier; Asian fabricators hold volume manufacturing positions. The vendor structure stratifies across banking-grade infrastructure providers, hardware-as-a-service specialists, and mobile-first challengers. Three archetypes dominate: compliance-integrated platform operators, subscription-model micro-merchant enablers, and scale-driven manufacturing assemblers. Competitive moves concentrate on firmware service relationship extension and hospitality software convergence partnerships.
Within the compliance-integrated tier, Worldline S.A. and Ingenico S.A. occupy positions shaped by GDPR and PSD2 regulatory architecture. SumUp Payments Limited exemplifies the hardware-as-a-service archetype targeting micro-merchant segments with zero-upfront subscription models. These three anchors illustrate how vendor economics convert from one-time hardware sales toward recurring service relationships under European regulatory pressure.
| Leading Market Players |
|---|
| PAX Technology Limited |
| Diebold Nixdorf AG |
| Worldline S.A. |
| Vectron Systems AG |
| SumUp Payments Limited |
| Ingenico S.A. |
| NCR Corporation |
| Aures Technologies SA |
| Verifone Systems, Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up terminal specialists across France and Germany enforce pricing discipline through captive firmware service relationships while consolidating component procurement volumes. This ownership structure compresses supplier margins at the secure-element tier while embedding recurring revenue premiums into merchant contracts.
Pricing Analysis
Premium pricing for short lead times dominates procurement negotiations as CE marking delays extend product launch windows. Three-tier pricing structure across banking-grade, standard retail, and micro-merchant economy levels reflects certification burden and after-sales service bundling. Cost compression in the economy tier is intensifying because smartphone-based soft-POS alternatives erode dedicated hardware attach rates. Micro-merchants in Spain and Portugal exhibit highest price sensitivity, while Benelux hospitality chains prioritize compliance guarantees over unit economics.
Supply Chain Analysis
Freight cost volatility from Asian fabrication centers to European assembly plants compresses margin buffers for NFC antenna and secure element procurement. Secure element chip fabrication concentrates in Taiwan and South Korea, while terminal final assembly localizes in Poland and Romania. The supply chain draws from specialized semiconductor foundries, thermal printer mechanisms, and tamper-resistant hardware modules. Single-source vulnerability in secure element supply exposes vendors to lead-time volatility. Distribution runs through regional payment service providers and direct vendor field teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where firmware engineering capabilities and banking-grade compliance infrastructure determine long-term viability. Players are pursuing backward integration into secure element sourcing and forward integration into merchant acquiring services.
For Market Incumbents: Cement service relationship extension through continuous PSD2 firmware mandates while acquiring distressed Eastern European distribution networks. The soft-POS substitution threat demands defensive certification investment in biometric authentication modules. Capacity addition in Polish assembly plants reduces exposure to Asian logistics chokepoints. For New Entrants and Emerging Players: Reseller partnerships in Romanian and Bulgarian cash-heavy retail corridors offer lowest competitive density. Polish independent grocers and Bulgarian hospitality operators represent the most penetrable merchant base. Hardware-as-a-service bundling with zero-upfront subscription models accelerates micro-merchant acquisition against legacy dial-up terminal displacement. For Investors and Strategic Acquirers: Distressed-cycle entries favor firmware engineering specialists with GDPR documentation capabilities in the German fintech corridor. Long-term viability hinges on recurring service revenue conversion rather than hardware shipment volumes. Watch for EU AI Act conformity assessment deadlines as inflection indicators for compliance-integrated platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secure Element Sourcing | Captive supply of Taiwan-fabricated chips insulates vendors from lead-time volatility under EBA supervision. |
| Firmware-as-a-Service Platform Launch | Continuous PSD2 update mandates convert one-time hardware sales into recurring revenue streams. |
| Biometric Authentication Module Certification | CNIL-compliant fingerprint verification eliminates PIN friction for French grocery and pharmacy chains. |
| Eastern European Distribution Network Acquisition | Polish and Romanian cash-heavy retail corridors offer first-mover terrain for contactless infrastructure. |
| Hospitality Software Convergence Partnership | Smart POS integration with kitchen display systems commands subscription premiums from Belgian full-service restaurants. |
Methodological Framework
Independent corroboration across terminal vendor executives, merchant acquiring specialists, and embedded systems engineers underwrites the qualitative findings. Primary interviews with payment security architects, firmware development leads, and hospitality procurement managers combined with secondary validation from SEC filings of listed terminal manufacturers, EBA payment system reports, and CE marking directive databases. Bottom-up merchant deployment estimates and top-down vendor shipment data triangulate market sizing.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, end-user vertical, authentication technology, and distribution channel. CAGRs derive from fitted growth curves applied to installed base replacement cycles and new merchant acquisition rates. Modeled inputs include PSD2 strong customer authentication compliance timelines and GDPR privacy-by-design implementation intensity across national regulatory clusters.
Several conditions sit outside the modeled scope, including potential EU AI Act algorithmic risk reclassifications and geopolitical disruptions to Asian semiconductor supply. Forecasts reflect assumptions about merchant digitization velocity and regulatory enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Cryptocurrency Payment Apps Market
Payments
B2B Payments Platform Market
Payments
Luxembourg POS Terminals Market
Payments
Indonesia Payments Infrastructure Market
Payments
China Real Time Payments Market
Payments
Social Media Payment Solution Market
Payments
Philippines Remittance Market
Payments
Italy Payments Market
Payments
Europe Fuel Cards Market
Payments
Direct Carrier Billing Market
Payments
Argentina Mobile Wallet Market
Payments
Convergent Billing Market
Payments
Direct Carrier Billing Platform Market
Payments
Mobile Point of Sale (POS) Market
Payments
United States POS Terminals Market
Payments
P2P Payment Market