
 Mobile Wallet Market | 2026-2036
Mobile Wallet Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Wallet Market Analysis
Developer talent scarcity in embedded finance and tokenization engineering is reorganizing how mobile wallet platforms scale across emerging markets. PayPal leverages its two-sided network density to sustain merchant acquisition costs below industry averages. Visa anchors global interoperability through its token service infrastructure, while Adyen competes on unified commerce APIs that bridge online and in-store wallet acceptance.
A mobile wallet is a software-based payment system that stores encrypted payment credentials, identity tokens, and loyalty instruments on portable devices, typically employing NFC field generation of 13.56 MHz or QR code payload structures for transaction initiation. Its primary commercial purpose is to disintermediate physical card presentment while enabling real-time authorization through host card emulation or secure element architectures. Open wallets and semi-closed wallets command the dominant transaction volume pools, as regulatory licensing requirements restrict closed wallet issuance to non-bank entities in most jurisdictions. NFC technology leads in-store proximity payments, though QR code deployments dominate in emerging markets where device hardware costs constrain merchant acceptance infrastructure.
The US Consumer Financial Protection Bureau supervises wallet provider compliance under Regulation E, while India's RBI mandates two-factor authentication and tokenization for all wallet transactions exceeding specified thresholds. The EU AI Act imposes algorithmic transparency requirements on fraud detection systems embedded in wallet platforms, directly affecting product development roadmaps. Stakeholders must monitor how central bank digital currency interoperability standards will reshape wallet architecture decisions and partnership strategies across major economies.
Market Dynamics
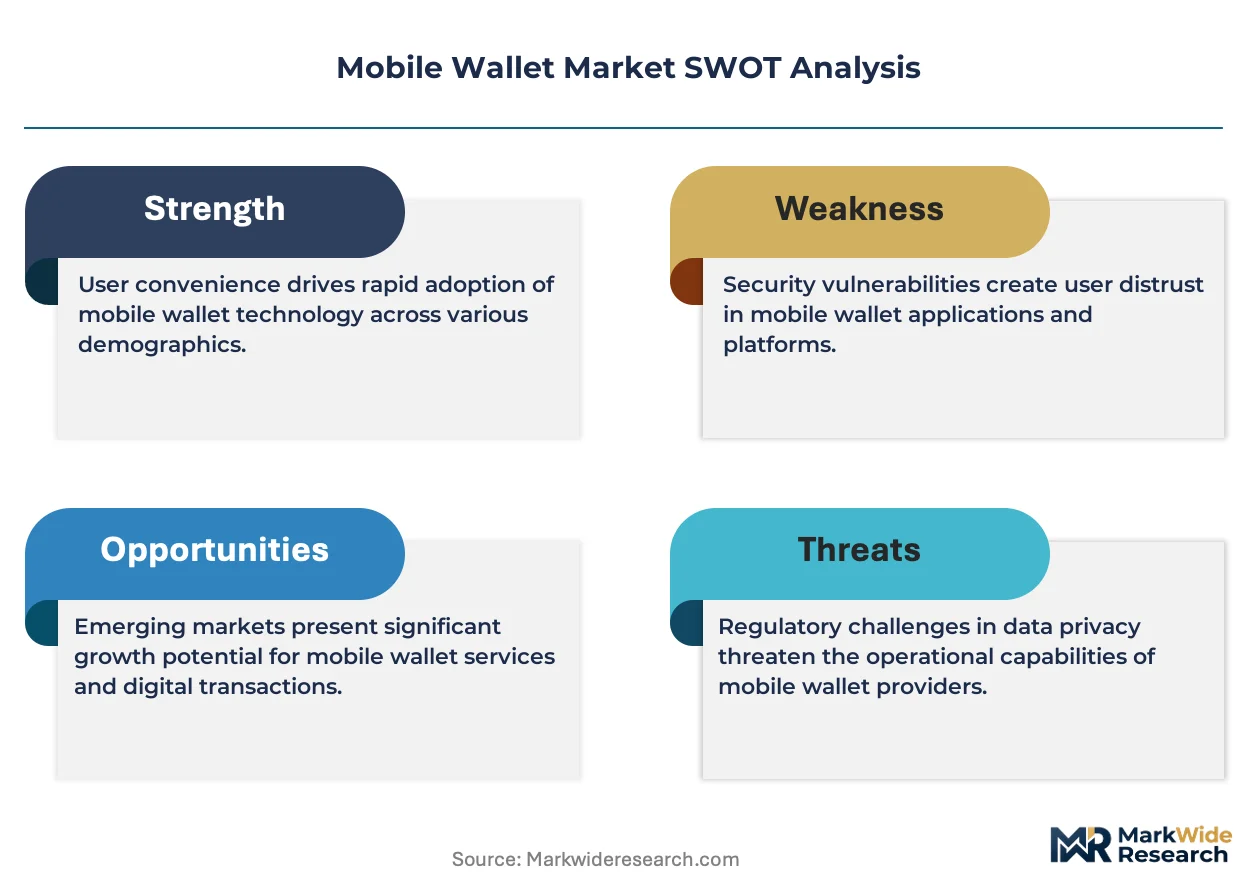
Embedded finance talent scarcity is forcing mobile wallet platforms to restructure engineering teams and partnership strategies, while central bank digital currency interoperability mandates are rewriting core architecture roadmaps across major economies.
Growth Catalysts
- UPI Infrastructure Expansion:India's real-time payment rails are extending wallet penetration into tier-two and tier-three urban centers, creating new merchant acceptance density.
- EU AI Act Compliance:Algorithmic transparency requirements for fraud detection systems are accelerating investment in explainable machine learning stacks.
- Contactless Preference Shift:Retail consumer behavior in physical commerce is driving NFC field generation adoption at point-of-sale terminals.
Market Restraints
- Tokenization Engineering Shortage:Scarcity of developers skilled in secure element architectures and host card emulation is inflating platform build costs.
- GDPR Data Localization:EU data handling protocols impose infrastructure duplication requirements that compress margin structures for cross-border wallet operators.
- QR Code Hardware Constraints:Emerging market merchant acceptance infrastructure remains limited by device cost floors in rural and semi-urban deployment zones.
Strategic Opportunities
- CBDC Interoperability Standards:Central bank digital currency integration protocols are creating first-mover advantages for wallet providers with modular core architectures.
- Semi-Closed Wallet Licensing:Regulatory frameworks in multiple jurisdictions are opening non-bank issuance pathways for prepaid instrument providers.
- Loyalty Instrument Convergence:Tokenized identity and rewards unification is enabling new revenue streams in transit and municipal service verticals.
Industry Challenges
- Two-Factor Authentication Latency:RBI-mandated verification steps for threshold transactions are creating friction in high-velocity payment corridors.
- Secure Element Supply Bottlenecks:Component sourcing for NFC-enabled devices is concentrating among limited semiconductor foundry capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Wallet Market |
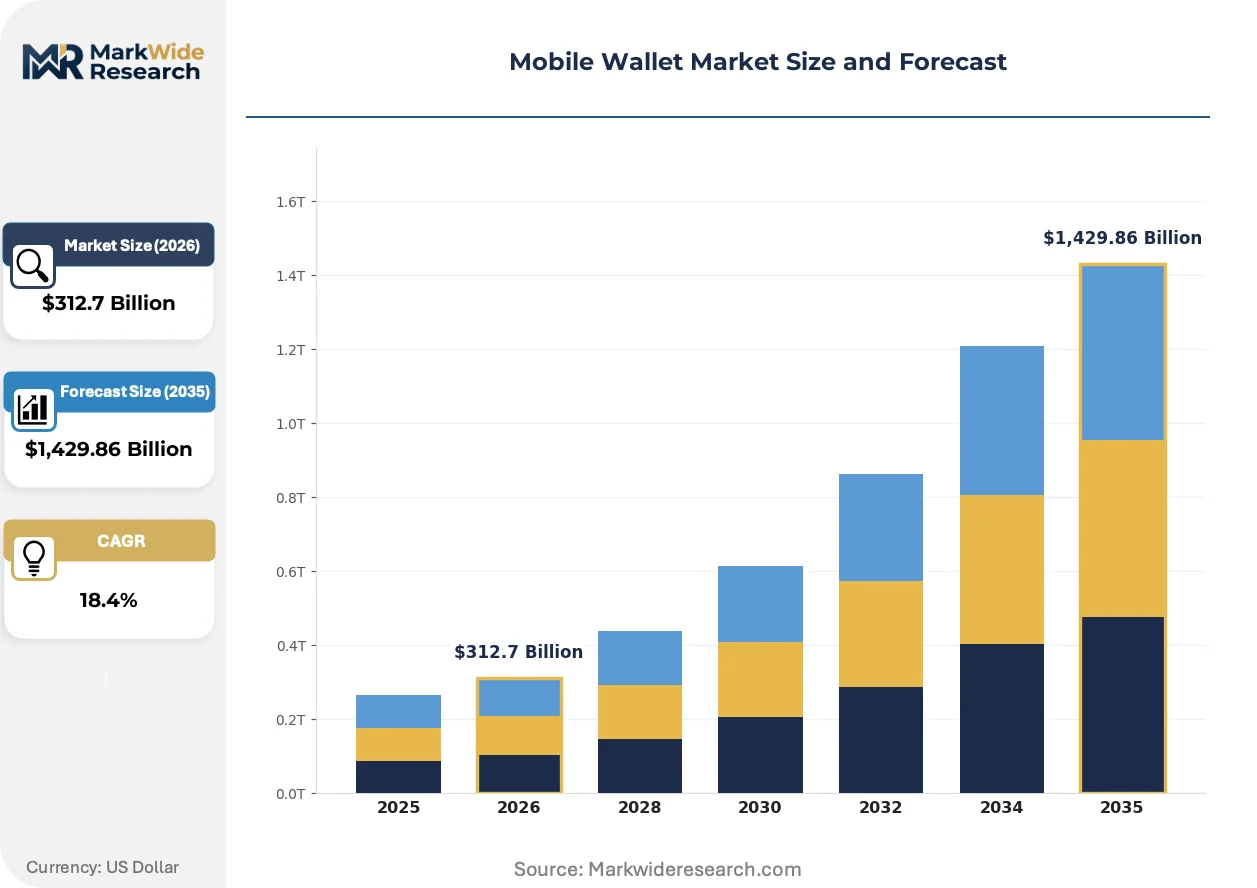
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $1,429.86 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Wallets, Open Wallets, Semi-Closed Wallets, Mobile Banking Technology: NFC, QR Code, Blockchain, BLE End User: Retail Consumers, Enterprises, E-Commerce Platforms, Banks Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based |
| Companies Covered | Visa, PayPal, Stripe, Revolut, Adyen, Global Payments, Mastercard, Wise, Nu Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Wallet Market Emerging Trajectories
Token service infrastructure is fragmenting competitive moats as interoperability standards democratize access to core payment rails, while regulatory pressure on algorithmic decision-making is reshaping product development priorities.
Biometric authentication stacks are fragmenting identity verification workflows across wallet platforms. Fingerprint and facial recognition modules are penetrating mid-tier device segments faster than hardware cost curves projected. This convergence is compressing password-based security architectures into niche legacy use cases.
The EU AI Act imposes documentation requirements on automated fraud scoring systems used in transaction authorization. Wallet providers must now maintain algorithmic audit trails that satisfy national supervisory authorities. European platforms are responding by restructuring machine learning pipelines around interpretable model architectures.
Merchant acquisition models are rotating from hardware-dependent toward software-only onboarding. Small retailers in India and Southeast Asia are adopting QR-based acceptance without terminal investment. This channel shift is visible most acutely in food delivery and urban transit verticals where integration speed outweighs feature depth.
Mobile Wallet Market Segmentation
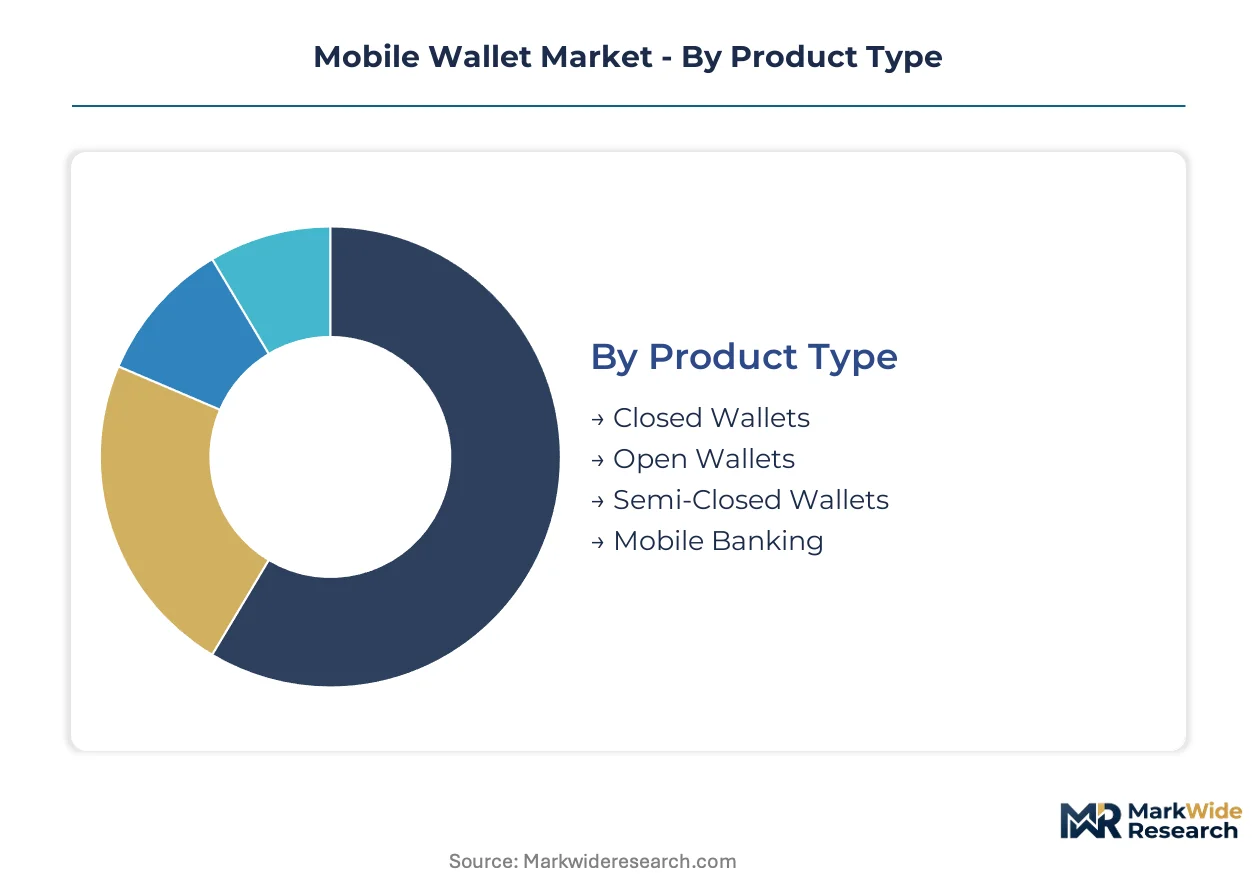
Wallet architecture choices determine which transaction corridors platforms can access. Product type and technology selections lock in regulatory pathways, merchant acceptance costs, and interoperability reach across payment networks.
Product Type:
Channel mix varies sharply by wallet openness—closed instruments route through proprietary merchant networks while open wallets ride on card rails.
- Open Wallets:These instruments link directly to bank accounts or card credentials, enabling transactions at any merchant accepting the underlying payment network. Demand clusters in India and the EU where interoperability mandates force platform neutrality. RBI and EU AI Act compliance requirements favor this architecture for cross-border scalability.
- Semi-Closed Wallets:Prepaid instruments usable at multiple contracted merchants but without full cash-out privileges. Growth concentrates in Southeast Asian transit and municipal service verticals where loyalty instrument convergence creates sticky user bases. Licensing frameworks in multiple jurisdictions now permit non-bank issuance.
- Closed Wallets:Single-merchant instruments restricted to issuer ecosystems. These dominate ride-hailing and food delivery apps in emerging markets where merchant acquisition cost compression outweighs interoperability needs.
- Mobile Banking:Bank-native applications with wallet functionality. European banks leverage these to defend deposit relationships against fintech disintermediation.
Open wallets dominate installed base. Semi-closed wallets are where expansion concentrates.
Technology:
Hardware cost floors and merchant infrastructure density determine which field generation methods achieve critical mass.
- QR Code:Optical payload structures requiring only camera-enabled devices. Deployment concentrates in India, Indonesia, and Brazil where terminal cost barriers exclude NFC adoption in tier-two and tier-three urban centers. RBI's UPI infrastructure natively supports this modality.
- NFC:13.56 MHz field generation enabling tap-to-pay at point-of-sale terminals. EU and US retail corridors drive demand where merchant acceptance infrastructure already exists. Secure element supply bottlenecks constrain device availability in mid-tier segments.
- Blockchain:Distributed ledger settlement layers for cross-border remittance and CBDC interoperability. Pilots concentrate in China's digital yuan ecosystem and European wholesale settlement experiments.
- BLE:Bluetooth Low Energy proximity detection for transit gate and automotive payment contexts. Adoption remains niche outside Japanese and Korean transit authorities.
QR code dominates transaction volume in emerging markets. NFC is climbing the fastest in mature retail corridors.
End User:
Customer type dictates authentication complexity, transaction velocity requirements, and fraud tolerance thresholds.
- Retail Consumers:Individual users demanding friction-minimized checkout. Contactless preference shifts in physical commerce are accelerating biometric authentication stack penetration.
- Enterprises:Corporate treasury and expense management use cases requiring granular spend controls and reconciliation automation.
- E-Commerce Platforms:Marketplace operators integrating checkout-as-a-service. These demand unified commerce APIs bridging online and in-store acceptance.
- Banks:Financial institutions white-labeling wallet infrastructure or deploying proprietary mobile banking frontends. EU AI Act algorithmic transparency requirements reshape their vendor selection criteria.
Retail consumers anchor transaction volume. E-commerce platforms are gaining share fastest as merchant acquisition models rotate software-only.
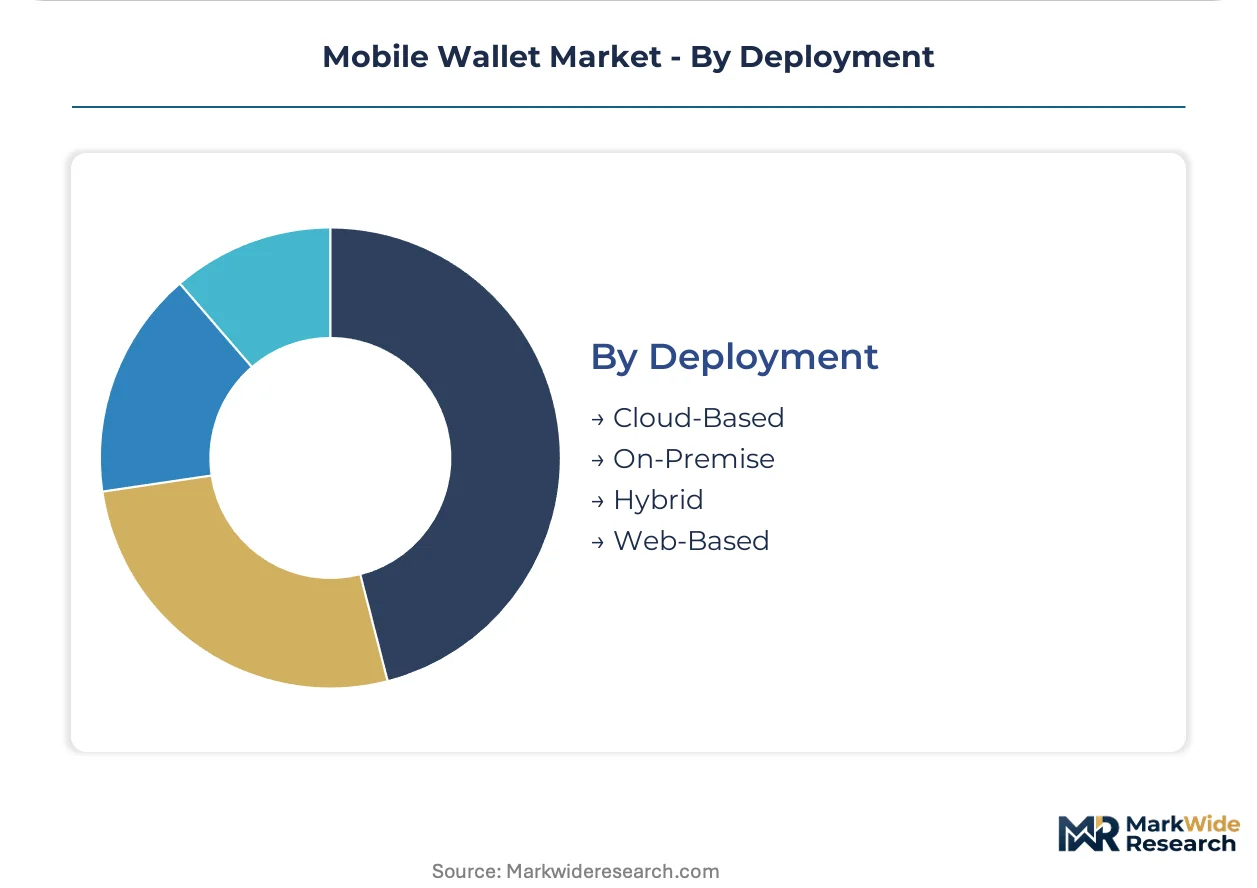
Deployment:
Infrastructure location decisions trade latency against data sovereignty compliance and operational control.
- Cloud-Based:Multi-tenant hosted architectures enabling rapid scaling. GDPR data localization requirements force EU-specific instance duplication for cross-border operators.
- On-Premise:Dedicated hardware installations for tier-one banks and government payment processors. High capital intensity limits adoption outside regulated incumbents.
- Hybrid:Split architectures with sensitive authentication on-premise and transaction processing cloud-resident. This configuration satisfies RBI two-factor authentication mandates while preserving elasticity.
- Web-Based:Browser-accessible wallets without native app dependency. These serve feature phone users in rural India and Africa where smartphone penetration lags.
Cloud-based deployments dominate new platform launches. Hybrid architectures are expanding most quickly among regulated financial institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India processes mobile wallet transactions through QR code interfaces at densities unmatched in mature economies, while European consumers favor NFC tap-to-pay at point-of-sale terminals. This consumption-mix differential reflects hardware cost floors in emerging markets against legacy merchant infrastructure in developed corridors.
United States
Retail contactless preference is accelerating biometric authentication stack penetration among mid-tier device segments. The Consumer Financial Protection Bureau supervises wallet provider compliance under Regulation E, mandating error resolution and disclosure protocols. Merchant acquisition models in New York and San Francisco corridors are rotating toward software-only onboarding without terminal investment.
India
UPI infrastructure expansion is extending wallet penetration into tier-two and tier-three urban centers beyond metropolitan cores. The Reserve Bank of India mandates two-factor authentication and tokenization for transactions exceeding specified thresholds. Hyderabad and Bengaluru clusters are witnessing dense merchant acceptance infrastructure deployment through QR-based modalities.
Germany
Bank-native mobile banking applications are defending deposit relationships against fintech disintermediation through integrated wallet functionality. The EU AI Act imposes algorithmic transparency requirements on fraud detection systems embedded in wallet platforms. The Frankfurt-Rhine-Main financial cluster is restructuring machine learning pipelines around interpretable model architectures.
Brazil
Semi-closed prepaid instruments are concentrating growth in transit and municipal service verticals where loyalty instrument convergence creates sticky user bases. The central bank's regulatory framework permits non-bank issuance pathways for prepaid instrument providers. São Paulo's urban transit authorities are deploying QR-based acceptance across metro and bus corridors.
United Kingdom
E-commerce platform integration of checkout-as-a-service is driving unified commerce API adoption bridging online and in-store acceptance. GDPR data handling protocols impose infrastructure duplication requirements that compress margin structures for cross-border operators. London's fintech corridor is witnessing merchant acquisition cost compression through software-only onboarding models.
Mobile Wallet Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in mobile wallet infrastructure provision. Network density advantages sustain below-average merchant acquisition costs for scaled platforms, while modular core architectures enable rapid adaptation to central bank digital currency interoperability standards. Two strategic archetypes dominate: payment network incumbents anchoring token service infrastructure, and unified commerce API specialists bridging online and in-store acceptance. Competitive moves concentrate on strategic partnerships for regulatory licensing and technology licensing for secure element architectures.
Within the network infrastructure tier, Visa and Mastercard occupy positions anchoring global interoperability through token service infrastructure. PayPal exemplifies the two-sided network density archetype, sustaining merchant acquisition economics below industry averages through user base scale. Adyen represents the unified commerce API specialist, bridging online and in-store wallet acceptance for e-commerce platform integration.
| Leading Market Players |
|---|
| Visa |
| PayPal |
| Stripe |
| Revolut |
| Adyen |
| Global Payments |
| Mastercard |
| Wise |
| Nu Holdings |
| Others |
Supply Flow & Price Mechanics
Platform scale economies in token service infrastructure compress unit economics for tier-one providers while fragmenting pricing power among regional specialists. India's UPI rails and the EU's GDPR compliance requirements create divergent cost floors that reshape where wallet operators can compete profitably.
Pricing Analysis
Long-term offtake contracts between payment networks and merchant acquirers anchor pricing stability, while spot transactional fees for QR-based acceptance in emerging markets introduce volatility. Three-tier pricing structure across premium tokenization services, standard API access, and economy QR-code processing reflects certification levels for PCI-DSS compliance and RBI two-factor authentication mandates. Pricing pressure stems from software-only onboarding models that eliminate terminal hardware margins. Small merchants in Southeast Asian transit corridors exhibit highest price sensitivity; tier-one banks deploying mobile banking frontends show lowest.
Supply Chain Analysis
Secure element foundry capacity in Taiwan, South Korea, and Germany constitutes the primary chokepoint for NFC-enabled device deployment. Component sourcing draws from specialized semiconductor fabrication for host card emulation chips, cryptographic co-processors, and biometric sensor modules. Single-source vulnerability concentrates in advanced node production for tamper-resistant hardware. Distribution runs through OEM device manufacturers and payment terminal deployers before reaching merchant acceptance points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in mobile wallets have reached an inflection where network density advantages compound faster than feature differentiation, particularly as CBDC interoperability standards force architectural convergence.
For Market Incumbents: Consolidate token service infrastructure partnerships to defend merchant acquisition economics against unified commerce API specialists. Deepen backward integration into secure element supply chains to mitigate Taiwan foundry concentration risk. Anchor regulatory licensing advantages in India and the EU before semi-closed wallet frameworks mature elsewhere.
For New Entrants and Emerging Players: Anchor in QR-code merchant acceptance corridors of tier-two Indian cities and Brazilian transit verticals where infrastructure cost barriers exclude NFC incumbents. Target semi-closed prepaid instrument licensing pathways now opening to non-bank issuers in Southeast Asian municipal service ecosystems. Lead with software-only onboarding velocity rather than feature depth.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular core architectures capable of rapid CBDC protocol adaptation over monolithic legacy stacks. Long-term viability hinges on first-mover capture of central bank digital currency interoperability standards. Monitor RBI tokenization mandate expansion and EU AI Act enforcement intensity as inflection signals for platform valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Token Service Infrastructure Partnership | Visa and Mastercard interoperability anchors global merchant acceptance density for wallet operators. |
| CBDC Protocol Integration | Modular architecture investment captures first-mover advantage as China's digital yuan and European pilots expand. |
| Semi-Closed Wallet Licensing | Non-bank issuance pathways in Brazil and Southeast Asia unlock transit and municipal service verticals. |
| Biometric Authentication Stack Deployment | Fingerprint and facial recognition modules penetrate mid-tier devices faster than projected hardware cost curves. |
| Software-Only Merchant Onboarding | QR-based acceptance eliminates terminal investment barriers for small retailers in Indian tier-two urban centers. |
Methodological Framework
Cross-validation between primary executive interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Wallet platform CTOs, merchant acquirer partnership leads, RBI compliance officers, EU regulatory affairs specialists, and transit authority procurement managers provided operational perspective. Secondary sources include SEC 10-K disclosures from payment networks, ECB and RBI circulars on tokenization mandates, EU AI Act implementation guidance, and UPI transaction volume reports from India's National Payments Corporation. Bottom-up merchant acceptance density estimates triangulate against top-down payment network revenue segmentation.
Sensitivity analysis around CBDC interoperability timelines and secure element supply constraints shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include wallet architecture type, field generation technology, end-user category, and deployment infrastructure location. CAGRs derive from fitted growth curves against historical UPI penetration patterns and NFC terminal deployment rates in comparable regulatory environments. Forecast inputs incorporate RBI two-factor authentication threshold adjustments and EU AI Act algorithmic audit compliance cost estimates.
Decision-makers should treat outputs as directional under assumptions of stable UPI infrastructure expansion and continued GDPR data localization requirements; material deviation in central bank digital currency launch timelines would warrant model refresh. Practitioners should keep alternative scenarios live as semiconductor foundry capacity allocation and EU AI Act enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Utility Billing Software Market
Payments
UAE POS Terminal Market
Payments
India Payment Gateway Market
Payments
Belgium POS Terminals Market
Payments
Romania POS Terminals Market
Payments
China Forex Cards Market
Payments
Middle East and Africa Real Time Payments Market
Payments
Point-Of-Sale [POS] Terminal Market
Payments
Japan Real Time Payment Market
Payments
Direct Carrier Billing Platform Market
Payments
Cyprus POS Terminals Market
Payments
Epayment System Market
Payments
France Payments Market
Payments
Croatia POS Terminals Market
Payments
Saudi Arabia Mobile Payments Market
Payments
Mobile Payment Security Software Market