
 Tokenization Solution Market | 2026-2036
Tokenization Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Tokenization Solution Market Analytics
Modular service bundling is restructuring how enterprises procure tokenization capabilities, shifting from standalone security modules to integrated payment-protection suites. Visa Inc. leverages its network infrastructure to embed tokenization directly into transaction flows. Mastercard Inc. sustains competitive pressure through specialized token vault architectures. Protegrity USA Inc. anchors its position in data-centric security with format-preserving token variants.
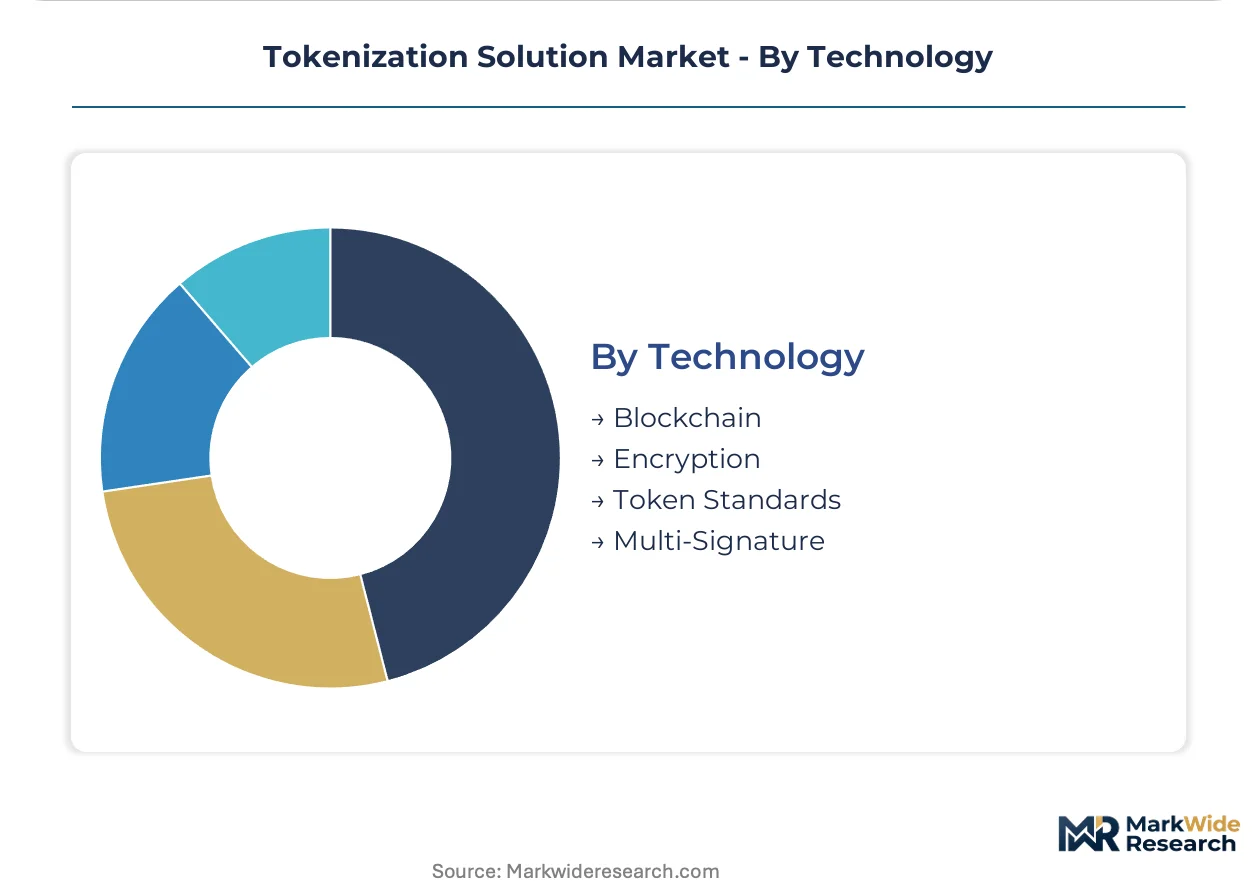
Tokenization solutions replace sensitive data elements with non-sensitive equivalents using randomized or deterministic token generation algorithms, typically operating within PCI DSS Level 1 certified environments to eliminate raw cardholder data exposure in merchant systems. Payment Processing applications dominate value capture as real-time transaction volumes escalate across digital commerce channels. Cloud deployment exhibits the steepest trajectory among infrastructure models, while On-Premise configurations retain preference among tier-one banks with legacy core banking dependencies. Blockchain technology integration represents an emerging architectural layer, though Encryption-based tokenization maintains current production dominance.
PCI DSS mandates from the PCI Security Standards Council govern product certification requirements for payment tokenization vendors operating in the United States. The EU AI Act and GDPR frameworks from European regulators shape data residency and algorithmic transparency obligations for tokenization services processing personal identifiers. Stakeholders must monitor evolving central bank digital currency specifications, as sovereign payment architectures will redefine token vault interoperability standards and competitive access conditions.
Market Dynamics
PCI DSS Level 1 certification requirements are compressing vendor margins while simultaneously elevating technical barriers to entry, forcing solution providers to absorb compliance costs or exit merchant-facing segments entirely.
Growth Catalysts
- PCI DSS compliance mandates:The PCI Security Standards Council's updated data protection protocols in the United States require raw cardholder data elimination from merchant systems, accelerating token vault deployments across retail payment infrastructure.
- Real-time payment volumes:Digital commerce transaction processing in India, Germany, and the United States is overwhelming legacy encryption architectures, creating structural pull for deterministic token generation algorithms.
- Cloud infrastructure maturation:Banking infrastructure modernization across North American financial institutions is displacing on-premise token vaults with API-integrated cloud tokenization services.
Market Restraints
- Format-preserving token R&D costs:Cryptographic engineering talent scarcity in the United States and Germany is inflating development expenditures for vendors maintaining backward compatibility with legacy payment message formats.
- Centralized cloud provider concentration:Hyperscaler infrastructure dependencies in North America create systemic resilience risks for multi-tenant token vault architectures serving tier-two banks.
- Quantum computing threat horizon:NIST post-quantum cryptographic standards remain incomplete, freezing long-term token algorithm roadmaps for vendors serving government payment processors.
Strategic Opportunities
- Central bank digital currency interoperability:Sovereign payment architecture specifications from the United States Federal Reserve and European Central Bank will redefine token vault access conditions for qualified infrastructure providers.
- Healthcare data tokenization:HIPAA-covered entities in the United States are extending payment tokenization architectures to protect patient identifiers in revenue cycle management systems.
- Blockchain-native token standards:Convergence between ERC-3643 security token frameworks and traditional payment tokenization is opening compliance-aligned digital asset custody applications.
Industry Challenges
- PCI DSS Level 1 audit timelines:Certification body capacity constraints in the United States are extending vendor qualification cycles to 14-18 months, delaying product launches.
- Core banking integration complexity:ISO 8583 message format heterogeneity across Indian and German legacy systems is fragmenting token vault deployment architectures.
- Cross-border data residency enforcement:GDPR Article 44 transfer mechanism uncertainties are complicating token vault replication strategies for US-based vendors serving European merchants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tokenization Solution Market |
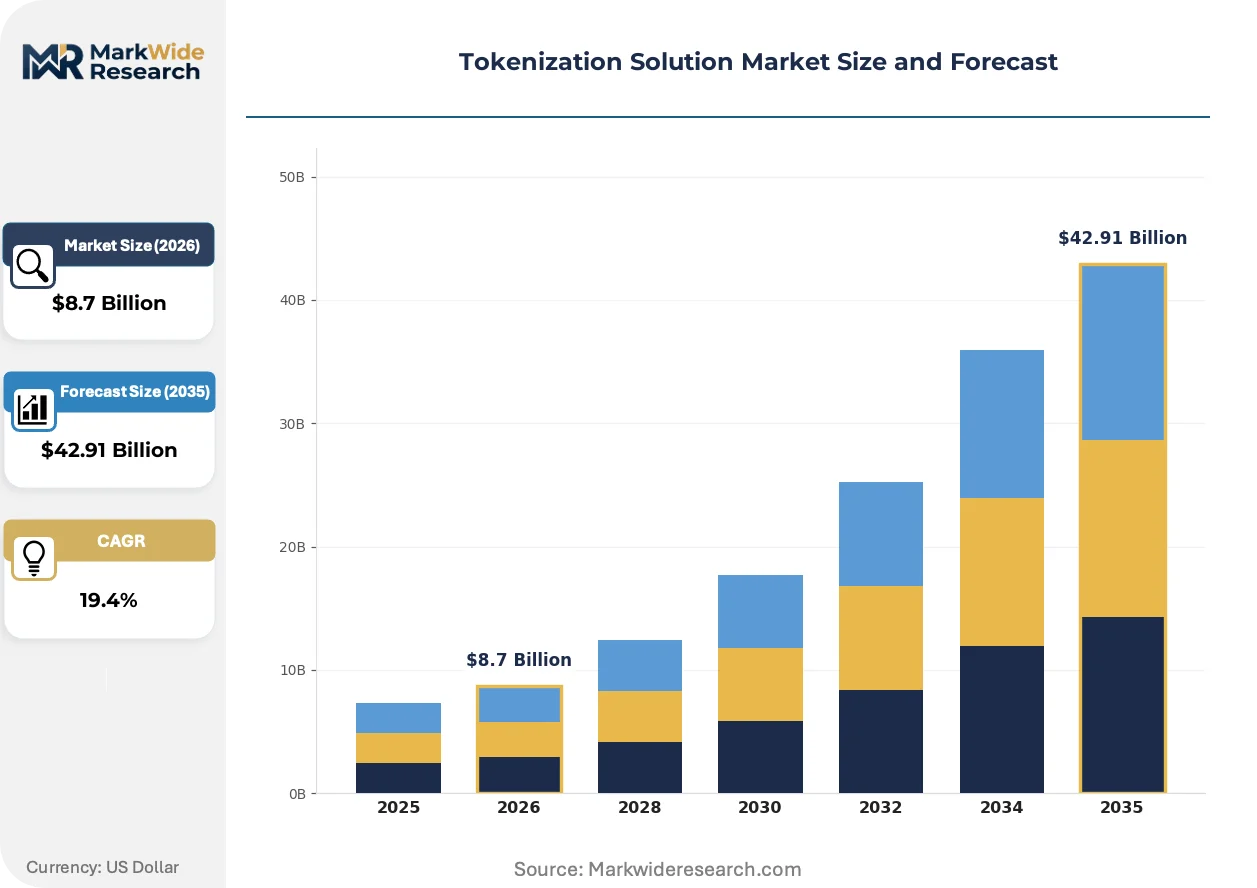
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud, Hybrid, Edge Application: Payment Processing, Digital Identity, Data Security, Compliance Management Industry Vertical: Retail, Healthcare, Financial Services, Travel Technology: Blockchain, Encryption, Token Standards, Multi-Signature |
| Companies Covered | Thales Group, Broadcom Inc., Visa Inc., Mastercard Inc., Fiserv Inc., Worldpay LLC, PayPal Holdings Inc., American Express Company, Protegrity USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tokenization Solution Market Evolving Landscape
Deterministic token generation architectures are displacing randomized approaches as merchants demand reversibility for chargeback processing and reconciliation workflows without vault lookups.
Blockchain-based tokenization is expanding into high-value cross-border settlement corridors where immutable audit trails reduce correspondent banking reconciliation costs. Major payment networks in Singapore and Switzerland are piloting hybrid architectures combining traditional vault security with distributed ledger transparency. This convergence is compressing settlement windows from T+2 to near-real-time while maintaining PCI DSS compliance boundaries.
The EU AI Act's algorithmic transparency requirements are reshaping token generation audit protocols for European payment processors. Automated decision-making documentation mandates now extend to token vault access logging and fraud scoring integration points. German and French acquiring banks are restructuring vendor contracts to embed compliance attestation clauses directly into service level agreements.
Merchant procurement patterns are fragmenting as mid-market retailers abandon bundled gateway-tokenization contracts in favor of best-of-breed vault-as-a-service arrangements. Independent software vendors in the United States are embedding white-label tokenization APIs directly into vertical SaaS platforms for hospitality and healthcare. This disintermediation is compressing pricing power for traditional payment gateway incumbents while elevating technical integration requirements for specialized token vault providers.
Tokenization Solution Market Segmentation

Tokenization solution procurement patterns diverge sharply across deployment models, application contexts, and compliance requirements. Vendors must architect modular platforms that span legacy banking infrastructure, cloud-native fintech stacks, and emerging sovereign payment rails simultaneously.
Deployment:
Upgrade cycles from legacy vault architectures to API-integrated alternatives are compressing procurement timelines across tier-one financial institutions.
- Cloud:Multi-tenant vault architectures deliver elastic capacity for real-time transaction spikes without capital-intensive hardware provisioning. North American banking infrastructure modernization is displacing on-premise configurations fastest here, with tier-two institutions abandoning captive data centers for managed service arrangements.
- On-Premise:Dedicated hardware security modules maintain air-gapped environments for raw cardholder data processing within PCI DSS Level 1 certified facilities. Tier-one banks with legacy core banking dependencies in the United States and Germany retain preference for this model despite higher total cost of ownership.
- Hybrid:Split architectures route sensitive token vault operations on-premise while pushing analytics and reporting to cloud substrates.
- Edge:Distributed vault nodes process tokenization closest to transaction origination points for latency-sensitive use cases.
Volume placements concentrate in Cloud; the faster expansion belongs to Hybrid as institutions seek risk-calibrated migration paths.
Application:
Cost tier differentiation separates commodity payment protection from premium compliance-integrated suites commanding higher per-transaction fees.
- Payment Processing:Real-time card tokenization eliminates raw PAN exposure across merchant acceptance points through randomized or deterministic generation algorithms. Digital commerce transaction volumes in India, Germany, and the United States are overwhelming legacy encryption architectures, creating structural demand pull for scalable vault services.
- Digital Identity:Biometric and credential tokenization protects citizen identifiers in government service delivery and workforce authentication contexts. GDPR Article 44 transfer mechanism uncertainties are complicating cross-border vault replication strategies for European implementations.
- Data Security:Format-preserving token variants enable backward compatibility with legacy message standards while eliminating sensitive data exposure.
- Compliance Management:Integrated audit logging and attestation documentation streamlines PCI DSS and HIPAA certification maintenance for regulated entities.
Revenue concentration sits with Payment Processing; steepest expansion trajectory belongs to Digital Identity as sovereign digital ID programs accelerate.
Industry Vertical:
Customer type segmentation reveals divergent procurement authority structures, with centralized IT governance in financial services contrasting distributed purchasing in retail.
- Financial Services:Banks, payment networks, and insurance carriers deploy token vaults for cardholder data protection, securities settlement, and claims processing. PCI DSS mandates from the PCI Security Standards Council in the United States require raw cardholder data elimination from merchant systems, accelerating deployments across retail payment infrastructure.
- Healthcare:HIPAA-covered entities extend payment tokenization architectures to protect patient identifiers in revenue cycle management and clinical trial data systems.
- Retail:Merchant acquirers and direct retailers integrate vault services into point-of-sale and e-commerce checkout flows.
- Travel:Airlines, hospitality chains, and booking platforms tokenize loyalty credentials and payment instruments across fragmented distribution channels.
Procurement scale concentrates in Financial Services; Healthcare is climbing the fastest as revenue cycle digitization intersects with privacy enforcement.
Technology:
Maturity gradients separate production-dominant encryption methods from emerging blockchain-native standards still awaiting interoperability certification.
- Encryption:AES-256 and format-preserving cryptographic schemes maintain production dominance for token generation and vault protection. NIST post-quantum cryptographic standards remain incomplete, freezing long-term algorithm roadmaps for vendors serving government payment processors.
- Blockchain:Distributed ledger architectures provide immutable audit trails for high-value cross-border settlement corridors. Major payment networks in Singapore and Switzerland are piloting hybrid architectures combining traditional vault security with distributed ledger transparency.
- Token Standards:ERC-3643 and equivalent frameworks enable compliance-aligned security token issuance and custody applications.
- Multi-Signature:Threshold cryptographic schemes distribute vault access across multiple authorization parties for institutional custody use cases.
Transaction volume concentrates in Encryption; Blockchain is gaining share fastest as settlement window compression demands immutable reconciliation records.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokenization solution production concentrates in payment network infrastructure hubs while consumption spreads across merchant-acquiring markets with divergent compliance maturity. The United States generates the largest share of cloud tokenization service revenue, though deployment velocity in India and Germany is compressing implementation timelines.
United States
PCI DSS Level 1 certification mandates from the PCI Security Standards Council are eliminating raw cardholder data from merchant systems across retail payment infrastructure. Federal Reserve CBDC interoperability specifications are reshaping token vault access conditions for qualified infrastructure providers. New York and San Francisco financial technology clusters host the densest concentrations of API-integrated cloud tokenization deployments.
Germany
ISO 8583 message format heterogeneity in legacy core banking systems is fragmenting token vault deployment architectures for tier-one institutions. The EU AI Act's algorithmic transparency requirements extend to token vault access logging and fraud scoring integration points. Frankfurt's banking infrastructure hub sustains preference for on-premise configurations despite higher total cost of ownership.
India
Real-time payment volumes across digital commerce channels are overwhelming legacy encryption architectures and creating structural demand for deterministic token generation. Reserve Bank of India guidelines on data localization are mandating domestic token vault residency for payment processors. Mumbai and Bangalore fintech corridors are displacing on-premise configurations with managed cloud service arrangements fastest.
Singapore
Hybrid architectures combining traditional vault security with distributed ledger transparency are piloting in high-value cross-border settlement corridors. The Monetary Authority of Singapore's digital asset framework is enabling compliance-aligned security token custody applications. The city-state's payment network infrastructure serves as the regional hub for blockchain-native token standard experimentation.
Switzerland
Immutable audit trail requirements for correspondent banking reconciliation are driving blockchain-based tokenization into production pilots. FINMA guidelines on digital asset custody are clarifying token vault regulatory boundaries for institutional providers. Zurich's private banking cluster is restructuring vendor contracts to embed compliance attestation clauses directly into service level agreements.
Tokenization Solution Market Competitive Landscape
The competitive structure tilts toward payment network incumbents with embedded infrastructure advantages. Consolidation around network-scale token vault operators contrasts with fragmentation among specialized data-security vendors serving regulated verticals. Three archetypes dominate: payment network-integrated providers, standalone token vault specialists, and vertical SaaS-embedded API vendors. Strategic moves concentrate on M&A for compliance certification acceleration and strategic partnerships for core banking system integration.
Within the payment network tier, Visa Inc. and Mastercard Inc. occupy positions shaped by direct transaction flow embedding. Protegrity USA Inc. exemplifies the data-centric security archetype with format-preserving token variants. Thales Group anchors the hardware security module segment for air-gapped environments. These three represent distinct competitive vectors rather than overlapping market contestation.
| Leading Market Players |
|---|
| Thales Group |
| Broadcom Inc. |
| Visa Inc. |
| Mastercard Inc. |
| Fiserv Inc. |
| Worldpay LLC |
| PayPal Holdings Inc. |
| American Express Company |
| Protegrity USA Inc. |
| Others |
Value Network & Pricing Analysis
Cryptographic engineering talent scarcity in the United States and Germany feeds directly into tiered pricing structures that separate PCI DSS Level 1 certified vault providers from uncertified alternatives. Cloud infrastructure hyperscaler fees in North America create cost passthrough pressure that concentrates margin compression among mid-market token vault operators serving tier-two banks.
Pricing Analysis
Margin tightening in mid-market cloud tokenization reflects hyperscaler infrastructure passthrough costs and certification audit fee inflation. Three-tier pricing structure across premium, standard, and economy levels separates PCI DSS Level 1 certified providers with dedicated HSM backing from API-only alternatives. Price differentiation rests on certification grade and geographic data residency compliance. Tier-one banks with legacy core banking dependencies exhibit lowest price sensitivity; mid-market retailers adopting vault-as-a-service arrangements show highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for hardware security module semiconductor fabrication. Token vault hardware draws from specialized cryptographic chip foundries, PCI DSS certification body capacity, and cloud hyperscaler compute infrastructure. Tariff exposure on HSM components creates procurement timeline risk for air-gapped deployment configurations. Distribution runs through direct enterprise sales for tier-one financial institutions and API marketplace integrations for fintech-embedded alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tokenization solution providers are racing to capture upstream cryptographic engineering talent and downstream payment network integration channels as vertical-integration levers reshape competitive economics.
For Market Incumbents: Anticipate deterministic token generation algorithm commoditization by accelerating format-preserving token R&D investment and acquiring specialized certification bodies to compress PCI DSS Level 1 audit timelines. Consolidation around core banking system integration expertise in Germany and India defends against fintech API disintermediation. For New Entrants and Emerging Players: Blockchain-native token standards for central bank digital currency interoperability represent the most penetrable white-space wedge. Target healthcare revenue cycle management in the United States where HIPAA-covered entities extend payment architectures to patient identifiers. Embed white-label tokenization APIs directly into vertical SaaS platforms for hospitality and healthcare as the primary go-to-market angle. For Investors and Strategic Acquirers: Federal Reserve CBDC interoperability specification releases are the leading indicator that sovereign payment architecture access conditions will consolidate around qualified infrastructure providers. Long-term viability favors vendors with dual capability in traditional vault security and distributed ledger transparency. Target acquisition archetype: specialized token vault providers with existing PCI DSS Level 1 certification and healthcare vertical penetration.| Strategic Initiative | Industry Significance |
|---|---|
| PCI DSS Level 1 Certification Acceleration | Compresses vendor qualification cycles from 18 months to 12 months for faster product launches. |
| Core Banking System Integration Partnership | Resolves ISO 8583 message format heterogeneity across Indian and German legacy infrastructure. |
| Healthcare Vertical SaaS Embedding | Captures HIPAA-covered entity demand for patient identifier protection in revenue cycle systems. |
| CBDC Interoperability Specification Alignment | Positions token vaults for Federal Reserve and European Central Bank sovereign payment access. |
| Blockchain-Native Token Standard Development | Enables ERC-3643 convergence for compliance-aligned digital asset custody applications. |
Research Methodology
PCI Security Standards Council documentation, SEC 10-K filings from payment network operators, and central bank digital currency specification releases formed the secondary backbone. Primary interviews with token vault product managers, PCI DSS certification auditors, healthcare CIOs, and fintech platform engineers combined with secondary validation. Bottom-up and top-down triangulation anchored market sizing across deployment models and application contexts.
Bottom-up modeling traced individual token vault deployment costs through merchant-acquiring volumes and banking infrastructure upgrade cycles. Segmentation dimensions span deployment architecture, application context, industry vertical, and technology maturity tier. CAGRs were derived from transaction volume elasticity to digital commerce penetration and regulatory compliance mandate timelines. Forecast inputs include real-time payment volume trajectories in India, Germany, and the United States, plus cloud infrastructure modernization capex disclosures from North American financial institutions.
Several conditions sit outside the modeled scope, including NIST post-quantum cryptographic standard finalization timelines and quantum computing threat realization horizons. Forecasts reflect documented assumptions about PCI DSS certification body capacity expansion and GDPR Article 44 transfer mechanism resolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Blockchain Distributed Ledger Market
Digital Assets and Cryptocurrency Finance
Virtual Currency Market
Digital Assets and Cryptocurrency Finance
US Cryptocurrency Payment Apps Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Crypto Automated Teller Machine Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Platform Market
Digital Assets and Cryptocurrency Finance
Digital Asset Transaction Market
Digital Assets and Cryptocurrency Finance
Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Bitcoin Trading Software Market
Digital Assets and Cryptocurrency Finance
Blockchain Finance Market
Digital Assets and Cryptocurrency Finance
Online Microtransaction Market
Digital Assets and Cryptocurrency Finance
NFT Analytics Tools Market
Digital Assets and Cryptocurrency Finance
Global Smart Contracts Market
Digital Assets and Cryptocurrency Finance
Digital Collectibles Platform Market
Digital Assets and Cryptocurrency Finance
Europe Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Music NFT Market