
 Direct Carrier Billing Platform Market | 2026-2036
Direct Carrier Billing Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Direct Carrier Billing Platform Market Intelligence
The divergence in platform investment, separating globally compliant systems from regional specialists, is rotating competitive dynamics. Bango plc leverages its extensive network of direct mobile network operator connections to serve large digital merchants. In contrast, Boku, Inc. focuses on mobile identity and payment solutions for a wide array of online services. Fonix PLC specializes in carrier billing and messaging services primarily within the UK market, demonstrating a focused geographic strategy.
A direct carrier billing platform is a financial technology infrastructure allowing consumers to charge digital purchases directly to their mobile phone bill. These platforms function through secure API integrations with telecommunications operators, managing transaction authorization, settlement, and reconciliation processes without requiring credit cards. Within applications, digital content and gaming represent the largest revenue streams for platform providers. While the core payment gateway remains the foundational solution, fraud management modules are gaining significant traction as transaction values and regulatory scrutiny increase.
Regulatory frameworks such as the EU's GDPR dictate strict data handling and consent requirements for user information. In parallel, national bodies like India's TRAI and the US FCC enforce rules on telecommunication-based financial transactions, impacting market access and operational protocols. Platform operators must continuously decide between investing in deep, direct integrations with major telecommunications operators or achieving broader reach through aggregator partnerships.
Market Dynamics
The central tension shaping the market is the strategic choice between pursuing deep, high-cost direct integrations with major mobile network operators for better margins, versus leveraging third-party aggregators for faster, broader, but less profitable market access.
Growth Catalysts
- 5G Network Expansion:The rollout of 5G technology enables faster and more reliable transactions, supporting the sale of higher-value digital goods and services like cloud gaming and high-definition video streaming.
- Mobile Gaming Growth:Proliferation of mobile gaming, particularly for in-app purchases, creates a significant demand pipeline for seamless, one-click payment solutions integrated directly into the gaming experience.
- Financial Inclusion:In markets with large unbanked populations like India, DCB provides a critical payment mechanism for digital services, bypassing the need for traditional bank accounts or credit cards.
Market Restraints
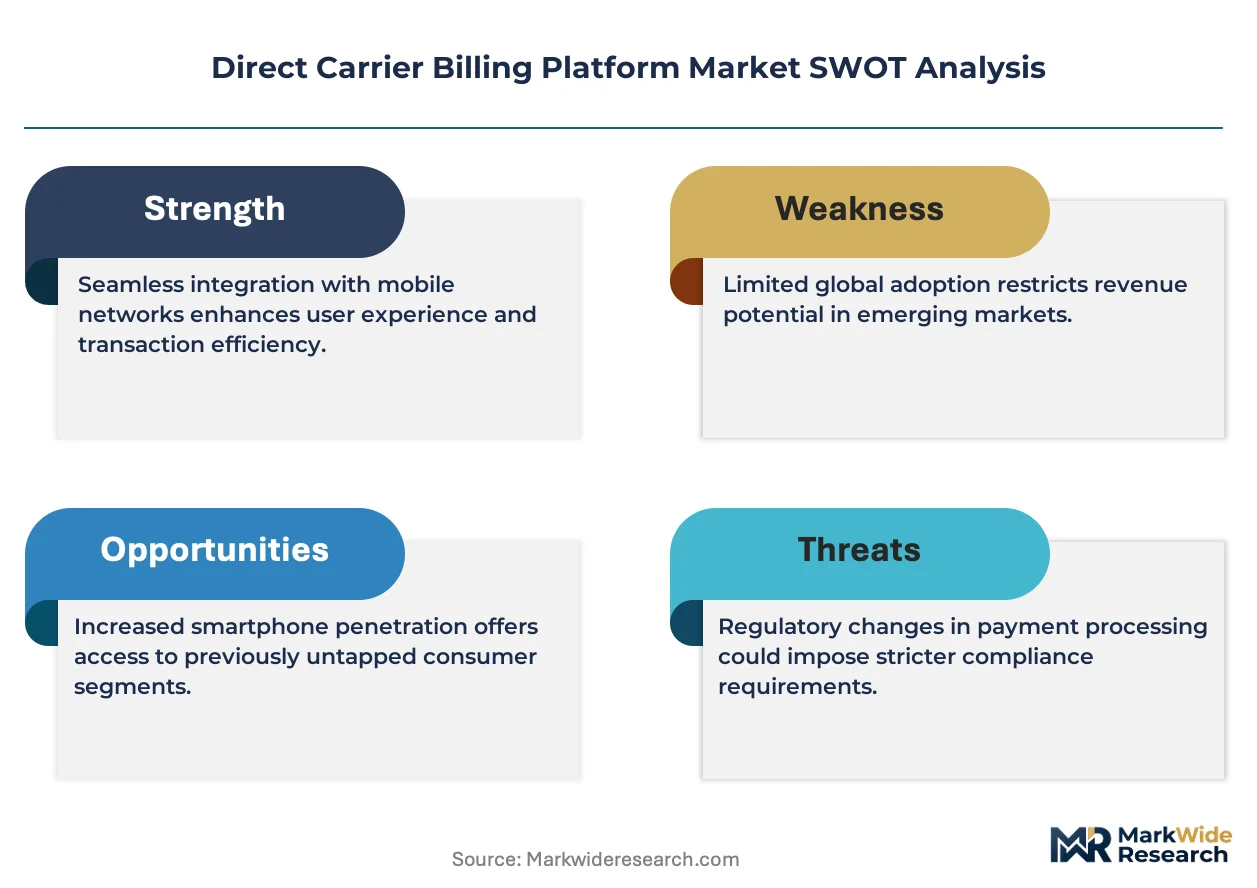
- Regulatory Burdens:Stringent data privacy laws, such as the EU's GDPR, impose significant compliance costs and operational complexity regarding user consent and data handling for financial transactions.
- MNO Integration Complexity:Establishing direct API connections with individual mobile network operators is a resource-intensive and time-consuming process, creating a high barrier for new platform entrants.
- Mobile Wallet Competition:The rapid rise of feature-rich mobile wallets and super-apps presents a strong substitution threat, offering a competing and often preferred digital payment method for many consumers.
Strategic Opportunities
- IoT Micropayments:The growth of Internet of Things devices and connected vehicles opens new revenue streams for automated, low-value transactions for services like smart parking, tolls, or device-based subscriptions.
- Southeast Asian Markets:Countries such as Indonesia and Vietnam, with high mobile penetration and low credit card usage, represent significant untapped markets for DCB expansion beyond digital content.
- Mobile Identity Integration:Combining DCB with mobile identity services allows platforms to offer enhanced security, fraud prevention, and user verification, creating a premium, value-added service offering.
Industry Challenges
- Sophisticated Fraud Schemes:Platform operators face a constant challenge in developing and scaling effective fraud management systems to combat evolving threats like premium rate scams and identity theft across multiple geographies.
- Fragmented Compliance:Navigating the diverse and often conflicting telecommunication and financial regulations from bodies like the US FCC and India's TRAI requires continuous legal and technical investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct Carrier Billing Platform Market |
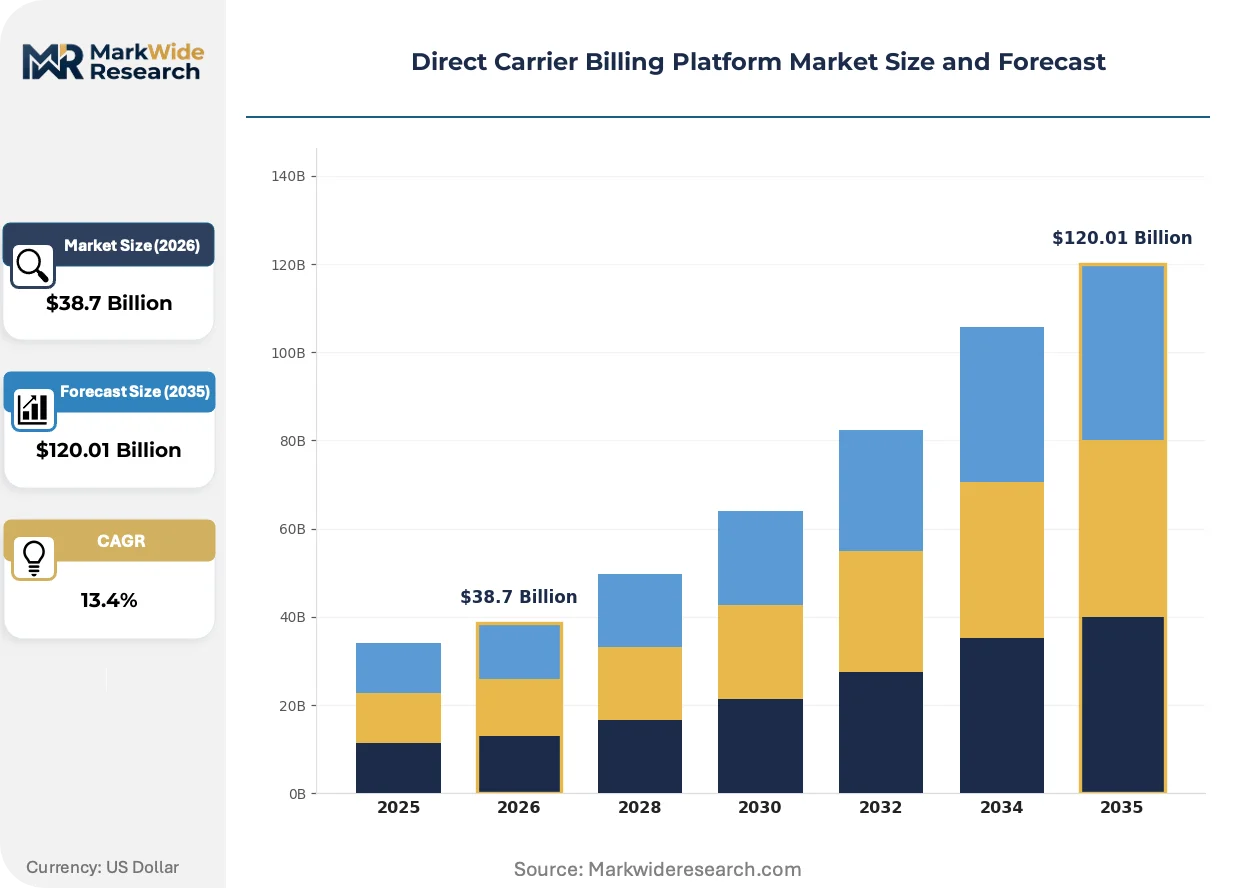
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $120.01 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-Premises, Hybrid, SaaS, Hosted Solution Type: Payment Gateway, Fraud Management, User Authentication, Transaction Analytics, Customer Support Application: Digital Content, E-Commerce, Gaming, Mobile Apps, Utilities Billing End User Industry: Telecommunications Operators, Digital Service Providers, OTT Platforms, Financial Institutions, Merchant Networks |
| Companies Covered | Comviva Technologies Limited, Digital Virgo Group, Bango plc, Fortumo OÜ, Fonix PLC, Boku, Inc., DIMOCO Payments GmbH, netMobile AG, Centili Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct Carrier Billing Platform Market Strategic Shifts & Innovations
Platform capabilities are evolving beyond simple payment processing. The market is shifting toward integrated fintech solutions that combine payment gateways with advanced fraud analytics and identity verification tools to support higher-value transactions and comply with increasing regulatory scrutiny.
AI-powered fraud management modules provide real-time behavioral analysis to detect anomalous transactions. Digital merchants in high-risk sectors like gaming and streaming are rapidly adopting these systems to reduce chargebacks. This advanced analytical capability is displacing older, static rule-based fraud engines that are less effective against coordinated attacks and produce higher rates of false positives.
The EU's General Data Protection Regulation (GDPR) forces a fundamental shift in data governance. It mandates explicit, granular user consent for processing personal data, impacting every transaction involving an EU resident. Global platform operators are most affected, often implementing GDPR's privacy-by-design principles across their entire infrastructure to maintain a single, compliant system for all users.
A clear shift from one-time purchases to subscription-based models is changing billing requirements. This trend disrupts the simple transaction model by necessitating robust systems for recurring payments, dunning management, and subscription lifecycle tracking. This evolution is most prominent in the digital entertainment and cloud services sectors, particularly in North America and Western Europe.
Direct Carrier Billing Platform Market Segmentation
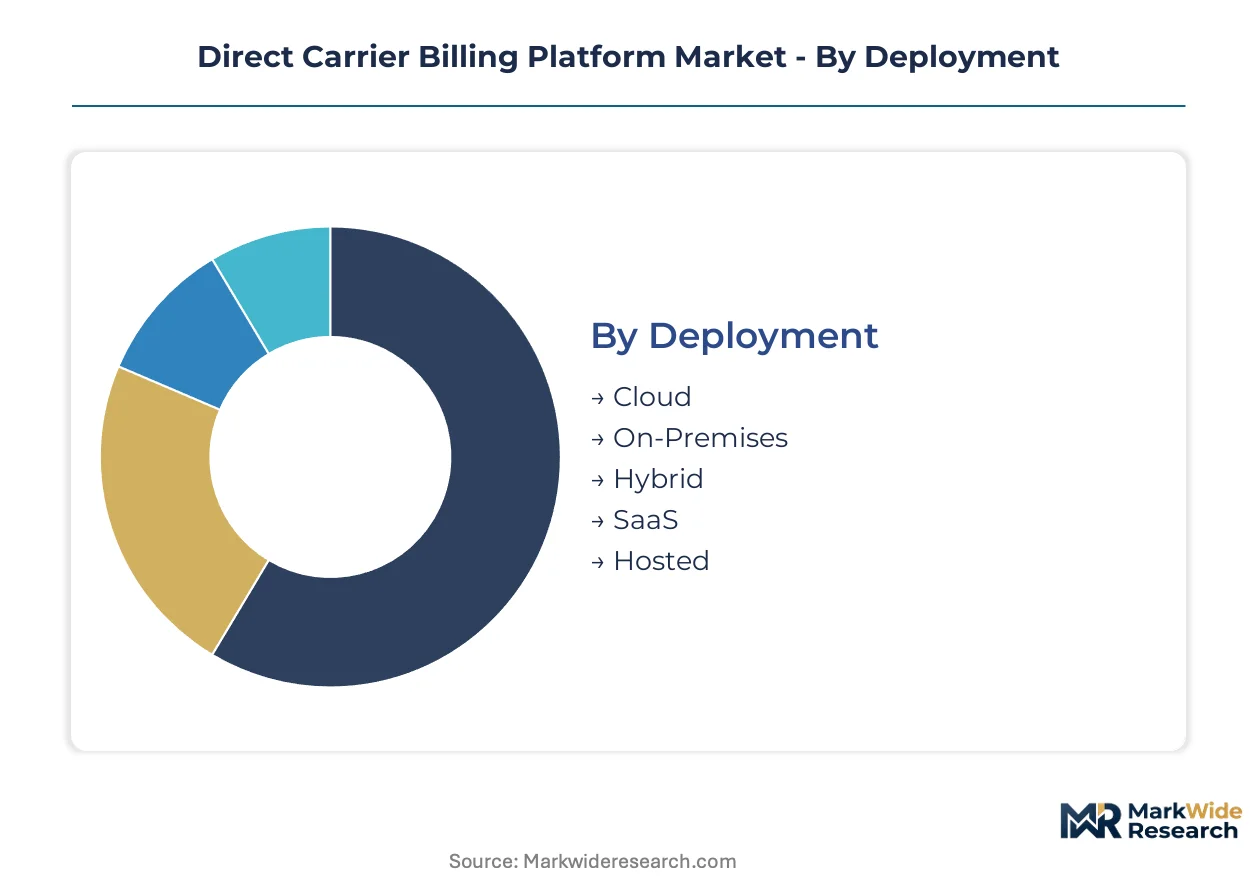
The Direct Carrier Billing Platform market segments across various deployment models, solution types, applications, and end-user industries, each reflecting distinct operational priorities and revenue streams. Understanding these segments is crucial for identifying areas of concentrated demand and strategic investment within the evolving digital payment ecosystem.
Deployment:
The choice of deployment model often reflects a platform's geographic reach and regulatory compliance requirements, differentiating between localized control and global scalability.
- Cloud:Cloud-based platforms offer extensive scalability and flexibility, enabling rapid deployment and global market penetration for digital merchants. This model reduces initial capital expenditure and supports agile service expansion into new countries.
- On-Premises:On-premises deployments are favored by large telecommunications operators in regions with strict data sovereignty laws, providing maximum control over infrastructure and data security. This model allows for deep customization and direct integration with existing legacy systems.
- Hybrid:Hybrid solutions combine the flexibility of cloud resources with the enhanced security and control of on-premises infrastructure.
- SaaS:Software-as-a-Service models deliver direct carrier billing capabilities via subscription, streamlining access for businesses without extensive IT resources.
- Hosted:Hosted platforms are managed by third-party providers on their servers, offering a balance between operational control and reduced internal management burden.
On-Premises commands the established base. The steepest expansion runs through Cloud.
Solution Type:
The functional components of direct carrier billing platforms address distinct operational needs, ranging from core transaction processing to advanced fraud prevention and customer support mechanisms.
- Payment Gateway:This foundational solution facilitates the core transaction processing, connecting digital merchants directly with mobile network operators. It handles authorization, settlement, and reconciliation for a wide array of digital purchases.
- Fraud Management:Advanced fraud management modules utilize AI-powered analytics to detect and prevent illicit transactions, mitigating financial losses and ensuring regulatory compliance. This capability directly addresses the increasing sophistication of global fraud schemes.
- User Authentication:User authentication services verify consumer identity, enhancing transaction security and meeting stringent regulatory requirements.
- Transaction Analytics:These tools provide comprehensive insights into payment patterns, user behavior, and revenue performance for platform operators and merchants.
- Customer Support:Dedicated customer support services assist users with billing inquiries, transaction disputes, and general service issues.
Payment Gateway remains the core offering, while Fraud Management solutions are experiencing significant demand growth.
Application:
Direct carrier billing finds diverse use across various digital consumption categories, with specific applications driving significant revenue for platform providers.
- Gaming:Mobile gaming represents the largest revenue stream for DCB platforms, driven by high volumes of in-app purchases, subscriptions, and virtual item sales. The proliferation of mobile gaming, particularly in India, fuels demand for seamless, one-click payment solutions.
- Digital Content:This segment encompasses streaming services, music, e-books, and news subscriptions, leveraging DCB for convenient one-time and recurring purchases. Expansion of 5G networks supports higher-value digital content sales within this category.
- E-Commerce:DCB is integrated into e-commerce platforms to simplify checkout processes, especially for lower-value goods and impulse purchases.
- Mobile Apps:Various mobile applications utilize DCB for premium feature unlocks, subscription models, and in-app content purchases across diverse categories.
- Utilities Billing:This application allows consumers to pay for essential services such as electricity, water, or internet directly through their mobile phone bill.
Gaming currently holds the largest share, and Digital Content applications are expanding rapidly.
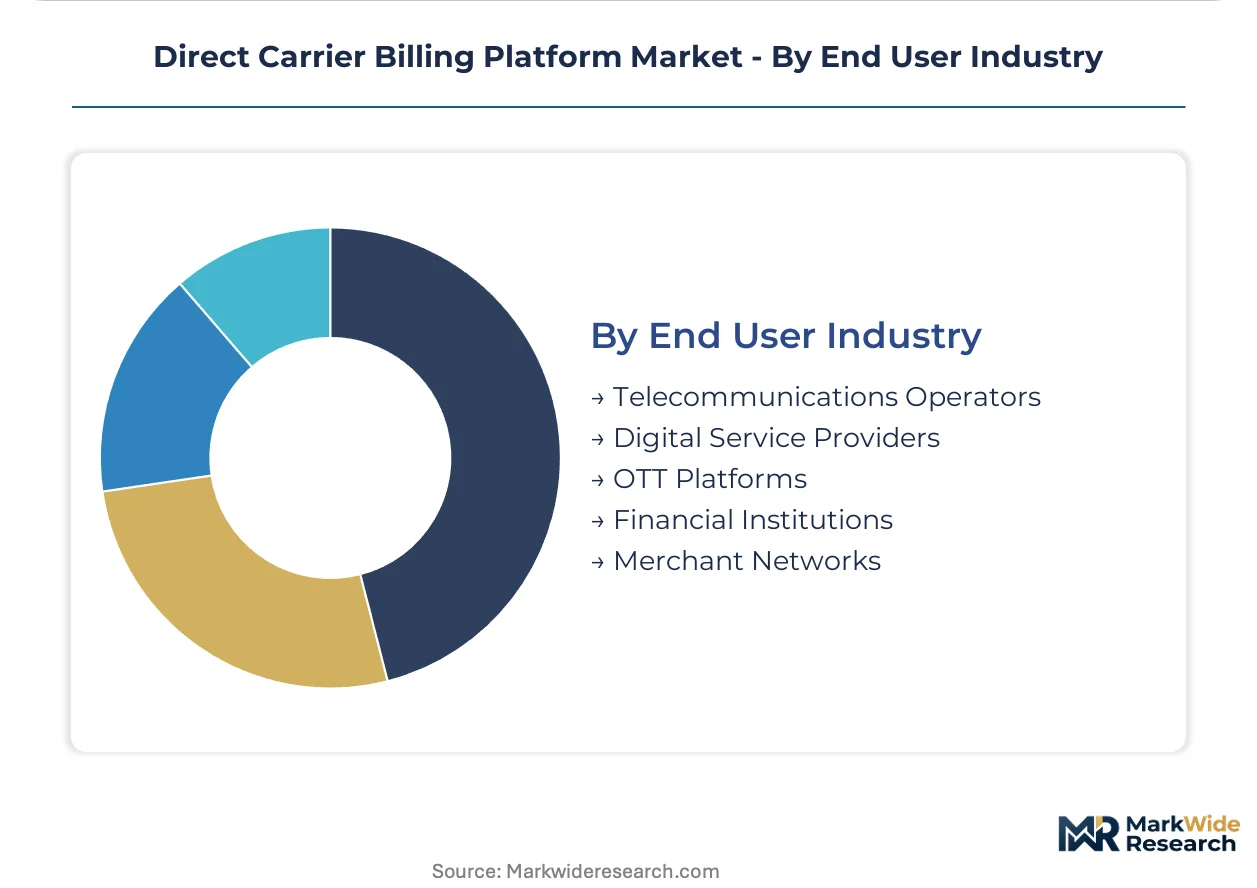
End User Industry:
The adoption of direct carrier billing platforms spans multiple industry verticals, each with specific integration requirements and business models for digital transactions.
- Telecommunications Operators:These entities act as foundational partners for DCB platforms, providing the essential billing infrastructure and direct access to their extensive customer bases. They leverage DCB to monetize network assets and enhance customer loyalty through convenient payment options.
- Digital Service Providers:A wide array of digital service providers utilize DCB to offer frictionless payment options for their online products, expanding market reach to unbanked populations. This category includes content providers, online education platforms, and various subscription services.
- OTT Platforms:Over-The-Top platforms employ DCB for subscription payments for streaming video, audio, and other digital entertainment content.
- Financial Institutions:Financial institutions explore DCB for micro-payments, financial inclusion initiatives, and as an alternative payment channel in certain markets.
- Merchant Networks:Diverse merchant networks integrate DCB to simplify payment processes, catering to customers who prefer mobile bill payments over traditional banking methods.
Telecommunications Operators are fundamental enablers, and Digital Service Providers are actively expanding their DCB integrations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for direct carrier billing platforms exhibits regional asymmetry, notably between high-growth markets like India and mature digital economies such as the United States. Developed markets prioritize advanced features and regulatory compliance, while emerging regions focus on financial inclusion and basic transaction volume. This divergence influences investment and operational strategies across different geographies.
India
India's market for direct carrier billing platforms expands rapidly due to high mobile gaming uptake and a large unbanked population. The Telecom Regulatory Authority of India (TRAI) enforces specific rules on telecommunication financial transactions. Mumbai's fintech hub drives innovation in mobile-first payment solutions.
United States
The United States market sees demand for direct carrier billing platforms driven by high-value digital content and recurring subscription services. The Federal Communications Commission (FCC) regulates telecommunication-based financial transactions, ensuring consumer protection. Silicon Valley companies integrate DCB solutions for cloud gaming and premium streaming content.
Germany
Germany's direct carrier billing market is propelled by demand for digital entertainment and convenient mobile application purchases. The EU's General Data Protection Regulation (GDPR) dictates strict data handling and consent requirements. Berlin's dynamic startup ecosystem fosters new DCB applications for mobile commerce and content subscriptions.
Indonesia
Indonesia presents significant opportunity for direct carrier billing platforms due to high mobile penetration and limited credit card adoption. The Ministry of Communication and Information Technology (Kominfo) oversees telecommunication services, impacting operational protocols. Jakarta's digital economy hub integrates DCB solutions for various mobile-first services.
United Kingdom
The United Kingdom market maintains steady demand for carrier billing and messaging services, alongside increasing digital content consumption. Ofcom, the UK's communications regulator, enforces rules on telecommunication-based financial transactions. London's fintech sector explores integrating sophisticated fraud management and identity verification tools with DCB platforms.
Direct Carrier Billing Platform Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the direct carrier billing platform market. The market exhibits a tiered structure, separating global platform providers from regional specialists. These archetypes include those pursuing deep mobile network operator integrations, those leveraging aggregator partnerships, and others focused on niche geographic markets. Geographic expansion and strategic partnerships are dominant competitive moves.
Within the global platform provider archetype, Bango plc represents entities leveraging extensive direct mobile network operator connections to serve large digital merchants. Boku, Inc. exemplifies a focus on mobile identity and payment solutions for a wide array of online services, emphasizing broader reach. UK-based Fonix PLC sits within the regional specialist category, demonstrating a focused geographic strategy for carrier billing and messaging services primarily within the UK market. These companies illustrate the diverse investment strategies currently shaping the competitive dynamics.
| Leading Market Players |
|---|
| Comviva Technologies Limited |
| Digital Virgo Group |
| Bango plc |
| Fortumo OÜ |
| Fonix PLC |
| Boku, Inc. |
| DIMOCO Payments GmbH |
| netMobile AG |
| Centili Limited |
| Others |
Cost & Logistics Intelligence
Significant economies of scale in platform development and MNO integration shape both supply concentration and the underlying price floors for direct carrier billing services.
Pricing Analysis
Customization premiums for specialized fraud management modules drive higher pricing for platform operators, contrasting with standard transactional fees for basic payment gateways. The dominant pricing model remains per-unit transactional, often supplemented by subscription tiers for advanced analytics and identity verification services. Solution complexity and geographic reach are primary price differentiation drivers. Pricing softness emerges from intense competition with mobile wallets, particularly for low-value transactions. Small mobile app developers exhibit the highest price sensitivity, while large digital merchants prioritize feature sets over marginal cost savings.
Supply Chain Analysis
Regulatory compliance costs, akin to inbound logistics hurdles, significantly influence the operational supply chain for direct carrier billing platforms. Supply concentration for critical MNO integrations centers on major telecommunications operators in India, the United States, and Western Europe. Key component dependencies include secure API frameworks and advanced fraud analytics software. Regulatory fragmentation across diverse national bodies, such as India's TRAI and the EU's GDPR, presents a notable structural risk. Distribution runs through direct integrations with MNOs and strategic partnerships with regional aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense, as the rapid proliferation of mobile wallets and super-apps presents a significant threat to incumbents.
For Market Incumbents: Consolidate direct mobile network operator integrations to secure better margins and enhance service reliability for high-value digital content. Invest in advanced AI-powered fraud management modules to combat sophisticated schemes and reduce chargebacks, a critical lever against regulatory scrutiny. Expand mobile identity integration capabilities to offer enhanced security and user verification, differentiating from generic payment methods.
For New Entrants and Emerging Players: Anchor in underserved Southeast Asian markets, such as Indonesia and Vietnam, leveraging high mobile penetration and low credit card adoption. Focus on niche applications like IoT micropayments, which represent significant white-space opportunities for automated, low-value transactions. Utilize aggregator partnerships for faster, broader market access, targeting unbanked populations with simplified payment solutions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platforms successfully transitioning from transactional models to subscription-based services, indicating long-term viability. Target acquisition profiles include companies with integrated fintech solutions combining payment gateways with advanced fraud analytics and identity verification. The signal to watch is the successful monetization of 5G-enabled high-value digital content, indicating accelerated market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen MNO Integrations | Secures higher transaction margins and improves service reliability for large digital merchants. |
| Invest in AI Fraud Management | Reduces financial losses from evolving threats and ensures compliance with global regulations. |
| Expand Mobile Identity Services | Enhances security and user verification, creating premium value-added offerings for platforms. |
| Target Emerging Markets | Unlocks significant growth in regions with high mobile penetration and limited traditional banking access. |
| Develop IoT Micropayment Solutions | Captures new revenue streams from automated, low-value transactions in connected ecosystems. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings of this study. This approach involved engaging with CTOs, product managers, regulatory affairs leads, and MNO partnership managers. Secondary data sources included telecommunications operator reports, fintech publications, national regulatory body guidelines, and publicly available company financial statements. Bottom-up and top-down triangulation refined market size and growth projections.
Sensitivity analysis forms the foundation of the forecast framework, evaluating market dynamics across the modeling period. The analytical framework segmented the market by deployment model, solution type, application, end-user industry, and regional regulatory compliance. Compound annual growth rates were derived through regression analysis, incorporating industry-specific inputs such as mobile penetration rates and digital content consumption trends.
Material uncertainties — unforeseen regulatory shifts, rapid mobile wallet evolution, or MNO policy changes — sit outside the modeled envelope of this analysis. Forecasts reflect assumptions documented within the study. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
United Kingdom Payment Market
Payments
Estonia POS Terminal Market
Payments
Social Media Payment Solution Market
Payments
France Payments Market
Payments
China Payments Market
Payments
Poland Payments Market
Payments
UAE POS Terminal Market
Payments
China Virtual Cards Market
Payments
Biometric Payment Market
Payments
Epayment System Market
Payments
France Buy Now Pay Later Services Market
Payments
China Forex Cards Market
Payments
India Payments Market
Payments
New Zealand Payments Market
Payments
Spain Payment Gateway Market
Payments
France Mobile Payment Market