
 Cloud Billing Market | 2026-2036
Cloud Billing Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Billing Market Analysis
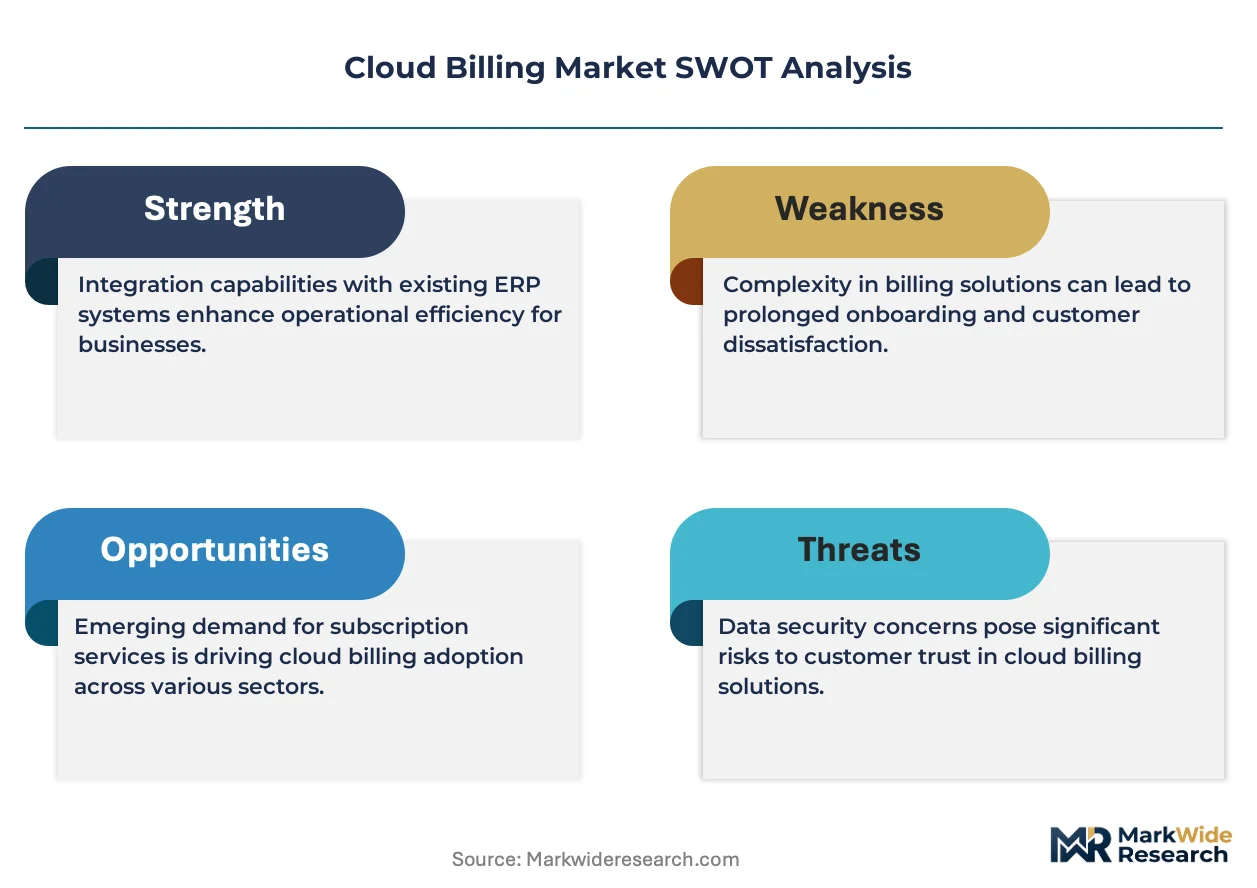
Telecommunications is pivoting toward cloud-native billing systems to manage 5G network slicing and dynamic service catalogs. Amazon Web Services anchors this shift through its native metering and cost management APIs. Microsoft Corporation differentiates via enterprise-grade subscription lifecycle tools integrated with Azure. Oracle Corporation sustains relevance through specialized telecom billing modules that handle complex rating engines.
Cloud billing encompasses software platforms that automate metering, rating, invoicing, and revenue recognition for cloud service consumption, typically operating through API-driven architectures that process millions of usage events per hour with sub-second latency. Public cloud deployment leads volume due to hyperscaler ecosystem lock-in, while usage-based billing captures the fastest expansion as enterprises abandon fixed commitments for consumption-aligned pricing. Subscription billing remains the mature margin pool where professional services attach rates run highest.
GDPR and the EU AI Act impose audit trail and data residency requirements that reshape platform architecture decisions across Europe. The SEC's climate disclosure rules and HIPAA security standards in the United States add compliance layers that favor vendors with certified multi-tenant controls. Stakeholders must evaluate whether their billing infrastructure can adapt to emerging cross-border data localization mandates without fragmenting operational scale.
Market Dynamics
Telecommunications providers are forcing a wholesale architecture rewrite as 5G network slicing and dynamic service catalogs demand real-time rating engines that legacy on-premise systems cannot deliver.
Growth Catalysts
- EU AI Act Compliance Mandates:Enterprises across Germany, France, and Italy must deploy auditable billing architectures with immutable transaction logs. Vendors offering certified multi-tenant controls capture replacement cycles.
- 5G Network Slicing:Telecommunications carriers require usage-based billing platforms that meter millions of concurrent service instances. This technical imperative accelerates cloud-native migrations.
- Sovereign Cloud Buildouts:India, the United States, and Germany are constructing national cloud infrastructure. Domestic billing platform procurement follows data localization requirements.
Market Restraints
- Hyperscaler Ecosystem Lock-in:Public cloud deployment concentration creates dependency on Amazon Web Services, Microsoft Azure, and Google Cloud Platform metering APIs. Migration costs escalate.
- GDPR Data Residency Friction:Cross-border transaction processing requires fragmented operational architecture. European enterprises face latency penalties and duplicated infrastructure spend.
- Legacy System Technical Debt:Mainframe-based rating engines at incumbent telecommunications operators resist API abstraction. Integration timelines extend 18-36 months.
Strategic Opportunities
- Edge Computing Convergence:Billing platforms that integrate Kubernetes-based edge orchestration with real-time metering capture industrial IoT deployments. Manufacturing and energy verticals show early adoption.
- India's Digital Public Infrastructure:The country's sovereign cloud initiative creates procurement windows for billing vendors with BIS-certified data centers. Domestic system integrators seek platform partnerships.
- Subscription-Usage Hybrid Models:Enterprise software vendors demand flexible pricing engines that blend committed spend with burst consumption. Professional services attach rates expand.
Industry Challenges
- Real-Time Rating Engineering Talent Scarcity:Sub-second latency requirements for millions of usage events demand specialized distributed systems expertise. Compensation premiums exceed 40% for qualified architects.
- Multi-Tenant Security Certification Complexity:SOC 2 Type II, ISO 27001, and HIPAA compliance audits require 12-18 month validation cycles. Smaller vendors struggle with audit resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Billing Market |
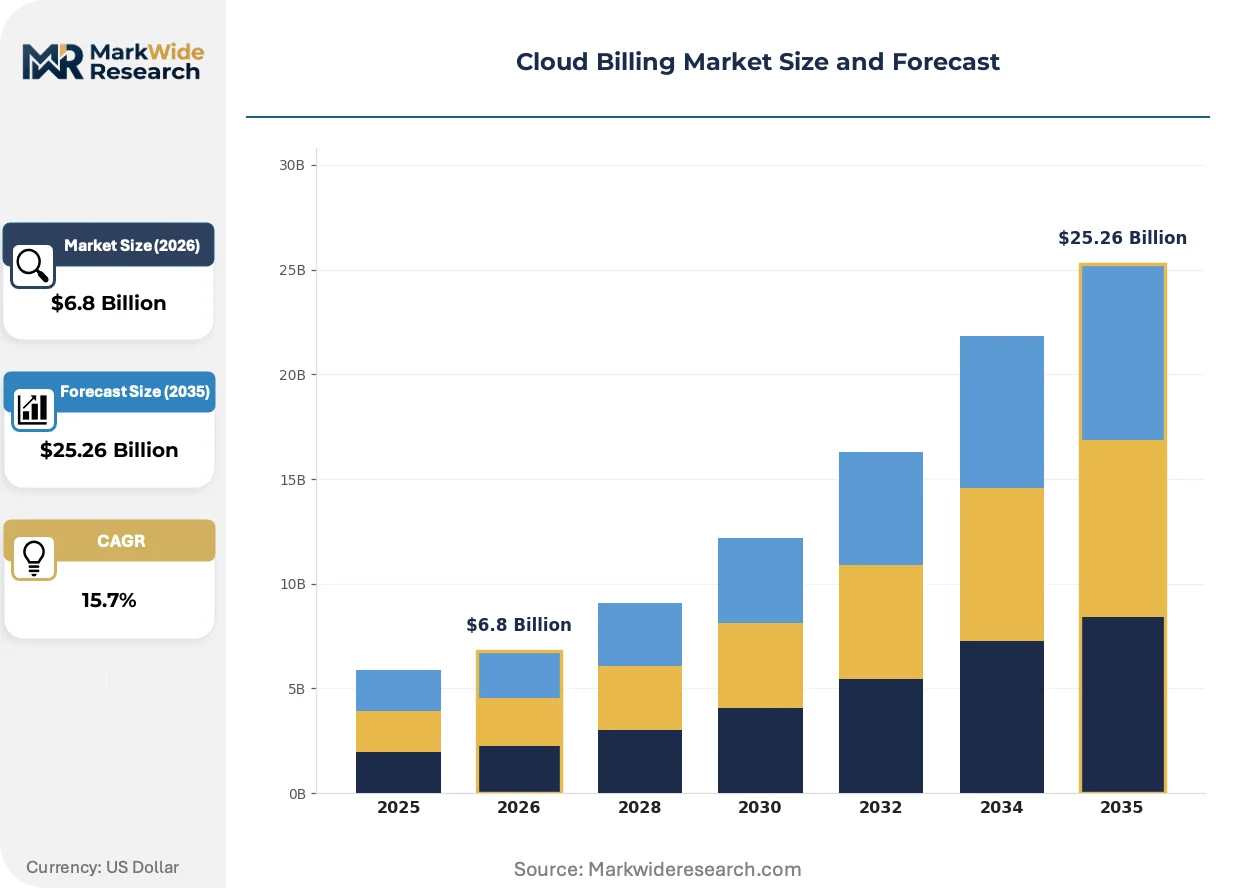
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $25.26 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Billing Type: Usage-Based Billing, Subscription Billing, Tiered Billing, Flat-Rate Billing End User: SMBs, Enterprises, Government, Non-Profit Service Type: Managed Services, Professional Services, Support Services, Consulting |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Google Cloud Platform, Oracle Corporation, SAP SE, Salesforce, Zuora, BillingPlatform, Aria Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Billing Market Emerging Trajectories
Event-driven billing architectures are displacing batch processing as enterprises demand instantaneous cost visibility. This shift compresses rating engine latency requirements and reshapes platform competitive positioning.
Event streaming infrastructure built on Apache Kafka and cloud-native event buses is electrifying how telecommunications carriers process 5G usage records. Deutsche Telekom and Verizon are deploying these architectures for sub-100-millisecond rating. The technology is compressing competitive differentiation around latency benchmarks rather than feature breadth.
GDPR's Article 30 record-keeping requirements and the EU AI Act's audit trail mandates are forcing architectural investments in immutable ledger integration. Billing platforms must now embed cryptographic proof chains for every transaction. European financial services and healthcare verticals are prioritizing vendors with pre-certified compliance modules.
FinOps organizational adoption is restructuring how enterprises procure cloud billing capabilities. Centralized cloud cost management teams are displacing decentralized DevOps purchasing. This concentration is most visible in United States technology and financial services sectors, where dedicated FinOps headcount has tripled since 2022.
Cloud Billing Market Segmentation
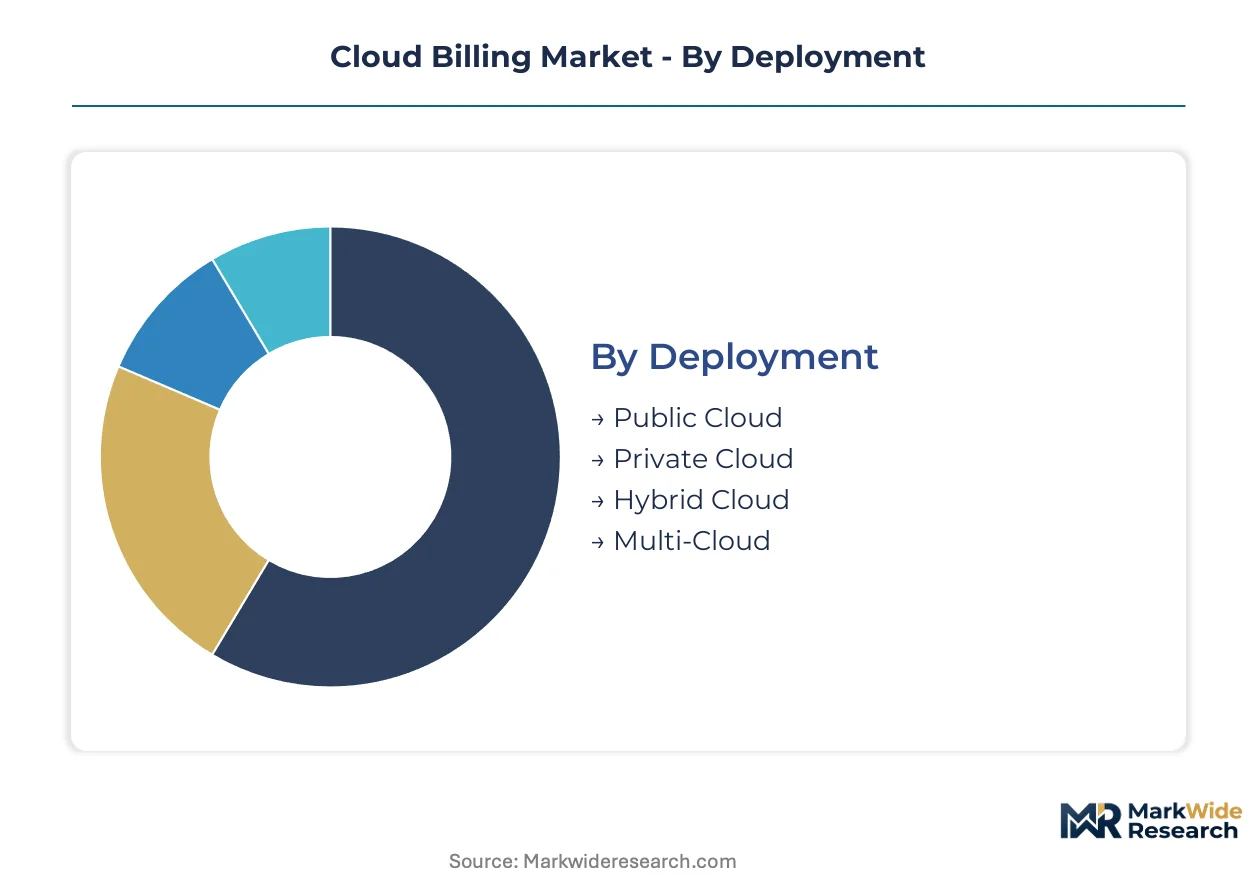
Cloud billing segmentation reveals how compliance architecture, pricing model complexity, and operational scale reshape procurement patterns. Deployment choices determine certification pathways, while billing type selection reflects enterprise maturity in consumption-based commercial models.
Deployment:
Public Cloud deployments carry the lightest certification burden with shared SOC 2 Type II and ISO 27001 coverage, while Private Cloud and Multi-Cloud configurations demand dedicated HIPAA, GDPR, and BIS audits per tenant instance.
- Public Cloud:Shared infrastructure with hyperscaler-native metering APIs. Demand concentrates among United States technology startups and mid-market SaaS vendors seeking immediate scalability without capital deployment. SOC 2 Type II coverage transfers from the underlying platform provider.
- Private Cloud:Dedicated tenant environments with isolated data residency controls. German financial services and Indian public sector procurement drive adoption, compelled by GDPR Article 30 record-keeping requirements and BIS data localization mandates. Certification cycles extend 14-18 months.
- Hybrid Cloud:Split workload architectures spanning on-premise and cloud-native rating engines. Manufacturing verticals in Germany and energy sector deployments in the United States favor this model for legacy ERP integration.
- Multi-Cloud:Distributed metering across AWS, Azure, and Google Cloud Platform instances. Large United States enterprises with FinOps teams adopt this to avoid hyperscaler lock-in, though cross-cloud reconciliation complexity elevates professional services attach rates.
Public Cloud sits at the top of the volume ranking, with Multi-Cloud climbing the fastest as enterprises fragment workload placement across competing hyperscalers.
Billing Type:
Revenue recognition complexity and audit trail requirements vary sharply across models, with Usage-Based Billing demanding the most sophisticated distributed systems architecture and Subscription Billing carrying the most mature compliance tooling.
- Usage-Based Billing:Event-driven metering with sub-second latency requirements for millions of concurrent transactions. Telecommunications carriers in Germany and the United States deploy this for 5G network slicing, where Deutsche Telekom and Verizon require sub-100-millisecond rating precision.
- Subscription Billing:Fixed-period recurring revenue recognition with established ASC 606 and IFRS 15 compliance pathways. Enterprise software vendors in the United States favor this for predictable revenue forecasting and lower engineering overhead.
- Tiered Billing:Volume-discounted pricing thresholds with automated entitlement management. Indian SaaS providers targeting SMB segments adopt this for price accessibility without custom negotiation overhead.
- Flat-Rate Billing:Simplified unlimited consumption models with capped liability exposure. Non-profit organizations and small government agencies in the United States select this for budget certainty despite margin compression.
Subscription Billing generates the highest margin pool through professional services integration, while Usage-Based Billing expands most quickly as telecommunications and industrial IoT deployments accelerate.
End User:
Procurement sophistication and compliance stringency separate segments, with Government and Enterprise end users imposing multi-tenant certification requirements that SMBs and Non-Profit organizations rarely demand.
- Enterprises:Centralized FinOps teams with dedicated cloud cost management headcount. United States technology and financial services sectors show tripled FinOps staffing since 2022, concentrating procurement authority.
- SMBs:Decentralized purchasing through DevOps teams with limited billing platform evaluation resources. Indian and United States SaaS startups favor pre-integrated solutions with minimal configuration.
- Government:Sovereign cloud mandates with BIS, FedRAMP, or GDPR Article 44 transfer mechanism compliance. India and Germany lead procurement volume for domestic data center requirements.
- Non-Profit:Grant-funded budget cycles with restricted overhead allocation. United States healthcare non-profits face HIPAA security standards that limit vendor eligibility despite lower contract values.
Enterprises dominate current revenue concentration, with Government procurement expanding fastest behind sovereign cloud infrastructure buildouts.
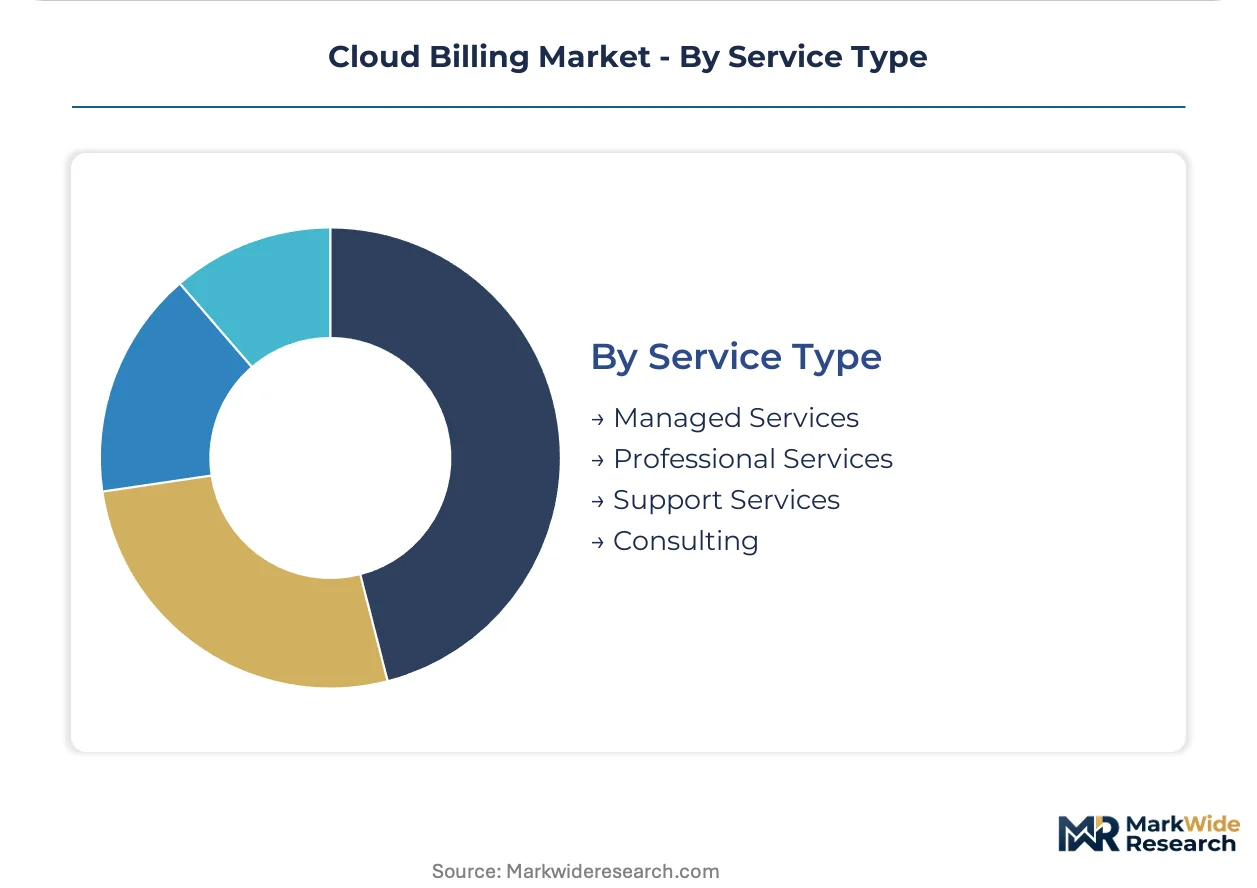
Service Type:
Margin structure and delivery model differentiation separate segments, with Professional Services capturing the highest attach rates and Managed Services offering the most predictable recurring revenue streams.
- Professional Services:Custom integration, data migration, and revenue recognition configuration. Complex rating engine deployments for telecommunications carriers in Germany and the United States require 18-36 month implementation timelines.
- Managed Services:Ongoing platform operation, patch management, and compliance monitoring. Indian system integrators partner with billing vendors to deliver BIS-certified operations for domestic sovereign cloud clients.
- Support Services:Tiered response time guarantees with dedicated technical account management. Enterprise contracts in the United States mandate 15-minute severity-1 response commitments.
- Consulting:FinOps organizational design and cloud cost optimization advisory. United States technology sector demand concentrates among companies centralizing previously decentralized DevOps purchasing authority.
Professional Services commands the highest contract values, with Managed Services gaining share fastest as sovereign cloud operators seek operational outsourcing partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping cloud billing procurement as enterprises migrate workloads toward jurisdictions with clearer compliance cost structures. The United States, Germany, and India are capturing disproportionate platform investment due to sovereign cloud infrastructure buildouts and divergent data localization enforcement timelines.
United States
FinOps team proliferation drives centralized billing platform procurement among technology and financial services enterprises. SEC climate disclosure rules and HIPAA security standards impose multi-tenant certification requirements that favor established vendors. Seattle and San Francisco Bay Area hyperscaler headquarters anchor metering API development and cost management tool innovation.
Germany
GDPR Article 30 record-keeping mandates and EU AI Act audit trail requirements accelerate replacement of legacy on-premise billing systems. Deutsche Telekom's 5G network slicing deployment demands sub-100-millisecond rating precision from cloud-native platforms. Munich and Frankfurt financial services clusters prioritize vendors with pre-certified compliance modules.
India
BIS-certified data center requirements and sovereign cloud procurement policies create domestic vendor partnership opportunities. TRAI regulations on telecommunications billing transparency push carriers toward auditable usage-based platforms. Bangalore and Hyderabad technology corridors concentrate system integrator activity seeking billing platform alliances.
United Kingdom
Post-Brexit data adequacy negotiations with the EU complicate cross-border transaction processing architectures. Financial services firms in the City of London demand hybrid cloud billing solutions that reconcile legacy ERP with cloud-native rating engines. Manchester and Leeds emerging technology hubs show early FinOps organizational adoption.
Japan
METI industrial digitization incentives support cloud billing adoption among manufacturing enterprises transitioning to usage-based service models. Tokyo and Osaka metropolitan areas concentrate telecommunications carrier headquarters pursuing 5G monetization platform upgrades. Domestic system integrators seek partnerships with international billing vendors for localized deployment support.
Cloud Billing Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscaler-native platforms commanding public cloud deployment volume while independent software vendors capture private cloud and multi-cloud configurations. The vendor base concentrates around three strategic archetypes: infrastructure-anchored metering services, enterprise subscription lifecycle specialists, and telecommunications-focused rating engine providers. Competitive dynamics center on compliance certification velocity and strategic partnerships with system integrators serving sovereign cloud buildouts.
Among infrastructure-anchored providers, Amazon Web Services, Microsoft Corporation, and Oracle Corporation exemplify distinct positioning vectors. Amazon Web Services represents the metering API standard for public cloud deployment concentration. Microsoft Corporation occupies a position emphasizing enterprise-grade subscription lifecycle integration. Oracle Corporation anchors the telecommunications vertical through specialized rating engine heritage.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| Google Cloud Platform |
| Oracle Corporation |
| SAP SE |
| Salesforce |
| Zuora |
| BillingPlatform |
| Aria Systems |
| Others |
Supply Flow & Price Mechanics
Hyperscaler-native metering API providers anchor pricing discipline through ecosystem lock-in, while private-equity-rolled-up billing specialists compete on implementation velocity and professional services attach rates. This ownership structure concentrates supply bargaining power among AWS, Microsoft Azure, and Google Cloud Platform, compressing margins for independent software vendors serving multi-cloud and private cloud configurations.
Pricing Analysis
Direct-to-enterprise subscription tiers dominate cloud billing procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating by compliance certification depth and API call volume thresholds. Price differentiation hinges on SOC 2 Type II audit inclusion and sub-100-millisecond latency guarantees for telecommunications carriers. Cost compression in the mid-market tier is intensifying because Indian SaaS providers and United States technology startups demand pre-integrated solutions with minimal configuration overhead. Government and enterprise segments show least price sensitivity due to sovereign cloud mandates and FinOps team procurement centralization.
Supply Chain Analysis
Apache Kafka and cloud-native event streaming infrastructure rests on United States, Germany, and India-based system integrators and hyperscaler data center footprints. Rating engine development draws from distributed systems engineering talent pools, cryptographic ledger technology providers, and BIS-certified domestic data center operators. Single-source vulnerability concentrates in hyperscaler metering API dependencies, where migration costs escalate and cross-cloud reconciliation complexity elevates professional services spend. Distribution runs through direct enterprise sales teams, domestic system integrator partnerships in India, and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in usage-based billing platforms as telecommunications carriers abandon fixed commitments for consumption-aligned pricing, compressing professional services delivery costs through Kubernetes-based edge orchestration standardization.
For Market Incumbents: To counter hyperscaler ecosystem lock-in threatening independent software vendor relevance, deepen API abstraction layers for legacy mainframe integration and accelerate SOC 2 Type II plus ISO 27001 certification velocity to capture European GDPR and EU AI Act replacement cycles. Capacity addition in BIS-certified Indian data centers secures sovereign cloud procurement windows. For New Entrants and Emerging Players: The price-point gap between premium compliance-certified tiers and economy SaaS offerings opens white-space in Indian SMB segments and United States mid-market SaaS vendors seeking immediate scalability without capital deployment. Target manufacturing verticals in Germany and energy sector deployments in the United States with hybrid cloud billing solutions reconciling legacy ERP integration. Go-to-market leverage rests on Kubernetes-based edge orchestration partnerships for industrial IoT deployments. For Investors and Strategic Acquirers: Valuations sit cheapest among telecommunications-focused rating engine providers with sub-second latency expertise and pre-certified GDPR compliance modules. Long-term viability framing centers on event-driven architecture displacement of batch processing and FinOps team proliferation restructuring procurement authority. Acquisition target archetypes include billing platforms with immutable ledger integration and cryptographic proof chain capabilities. The signal to watch is Deutsche Telekom and Verizon latency benchmark announcements as competitive differentiation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding Kubernetes-based edge orchestration captures industrial IoT deployments in German manufacturing. |
| Strategic Partnership | Domestic system integrator alliances in India secure BIS-certified sovereign cloud procurement windows. |
| Acquisition of Specialist Firm | Rating engine providers with sub-100-millisecond latency expertise address 5G network slicing demands. |
| Geographic Expansion | Munich and Frankfurt financial services clusters prioritize vendors with pre-certified GDPR compliance modules. |
| Product Launch | Subscription-usage hybrid pricing engines blend committed spend with burst consumption for enterprise software vendors. |
Methodological Framework
Bottom-up enterprise and telecommunications carrier modeling reconciled against top-down hyperscaler metering API deployment tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and FinOps team leads combine with secondary validation against SEC filings, hyperscaler capex disclosures, and TRAI telecommunications billing transparency regulations. Triangulation across these sources ensures segmentation integrity across deployment models, billing types, and service tiers.
Historical trendline analysis of public cloud adoption velocity and sovereign cloud infrastructure buildouts informs the projection framework across the analysis window. Segmentation dimensions modeled include deployment architecture, billing type complexity, end user procurement sophistication, and service type margin structure. CAGRs derive from usage-based billing expansion rates in telecommunications and industrial IoT verticals, subscription billing maturity in enterprise software, and professional services attach rate trajectories.
Caveats apply where EU AI Act audit trail mandate enforcement timelines or cross-border data localization rulings could materially shift the outlook. Forecasts reflect assumptions around hyperscaler ecosystem lock-in persistence and real-time rating engineering talent scarcity compensation premiums. A small set of named triggers—including Deutsche Telekom latency benchmark announcements, BIS certification velocity in India, and FinOps team headcount trajectories—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Nigeria Mobile Money Market
Payments
India Forex Cards Market
Payments
Forex Cards Market
Payments
India POS Terminals Market
Payments
Credit Card Payments Market
Payments
Singapore Payments Market
Payments
Germany Payment Gateway Market
Payments
Japan Virtual Cards Market
Payments
Smart Bands Payments Market
Payments
South Africa Gift Card and Incentive Card Market
Payments
Middle East and Africa Buy Now Pay Later Services Market
Payments
Netherlands Mobile Payments Market
Payments
Europe Credit Cards Market
Payments
Latin America Payment Gateway Market
Payments
Middle East and Africa Payment Gateway Market
Payments
Middle East and Africa Payments Market