
 Japan Virtual Cards Market | 2026-2036
Japan Virtual Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Virtual Cards Market Insights
Enterprise procurement in Japan is consolidating around virtual card programs as large corporates centralize travel and vendor spend under unified digital payment rails. Mitsui Sumitomo Card leverages its domestic merchant network to anchor corporate card issuance for mid-market enterprises. American Express competes on cross-border expense management tools, while Stripe extends its platform infrastructure to Japanese SaaS companies seeking programmatic card generation.
Virtual cards constitute digitally issued payment credentials with single-use or limited-use tokenized numbers, typically provisioned through APIs and integrated with enterprise resource planning systems for automated reconciliation. Japan's virtual card infrastructure relies heavily on EMV tokenization standards and contactless payment protocols to ensure interoperability with domestic POS networks. Corporate cards dominate current issuance volume as large enterprises prioritize spend control, while mobile wallet-linked virtual credentials represent the fastest-growing segment due to PayPay's platform expansion and Rakuten Group's ecosystem integration. Prepaid virtual instruments for online retailers show mature growth patterns with thinner margin pools concentrated among payment processors.
Japan's Financial Services Agency enforces strict anti-money laundering protocols and fund settlement laws that shape issuer licensing requirements and customer verification workflows. METI promotes cashless payment adoption through subsidy programs that indirectly expand virtual card acceptance infrastructure. Industry participants must monitor evolving JIS standards for financial data security and anticipate how the central bank's digital currency experiments could reshape tokenized payment architectures.
Market Dynamics
Japan's virtual card ecosystem is consolidating around API-first issuance platforms as large enterprises abandon legacy plastic programs in favor of tokenized credentials integrated directly with ERP systems. This infrastructure shift compresses reconciliation cycles from weeks to hours while tightening spend controls.
Growth Catalysts
- FSA Payment Services Act revisions:The Financial Services Agency's updated guidelines on electronic payment instruments mandate stricter issuer compliance, which accelerates institutional investment in secure tokenization infrastructure.
- Manufacturing SME belt demand:Osaka's precision manufacturing clusters are adopting virtual cards for vendor payments to reduce invoice fraud exposure and streamline procurement workflows.
- EMV tokenization standards:Japan's domestic POS networks now universally support contactless virtual credentials, eliminating interoperability friction that previously slowed merchant acceptance.
Market Restraints
- Issuer licensing concentration:Only three domestic banking consortia hold principal member status with JCB and Visa Japan, creating a supply bottleneck for new market entrants seeking direct issuance capabilities.
- Legacy system integration costs:Enterprises running on-premises SAP or Oracle installations face six-figure middleware investments to enable real-time virtual card provisioning.
- Cash preference inertia:Japan's remaining cash transaction volume, particularly in rural prefectures and among aging demographics, limits merchant incentive to upgrade acceptance infrastructure.
Strategic Opportunities
- Kyushu semiconductor corridor:Fukuoka and Kumamoto's expanding chip fabrication facilities generate unmet demand for programmable procurement cards tied to capital equipment purchasing cycles.
- METI cashless subsidy extension:The Ministry of Economy, Trade and Industry's point-rebate programs for small merchants indirectly expand virtual card acceptance by reducing terminal deployment friction.
- API-wallet convergence:Integration between enterprise virtual card APIs and PayPay's consumer wallet infrastructure enables novel B2B2C payment flows for platform businesses.
Industry Challenges
- Token lifecycle management:Issuers struggle to maintain real-time visibility across millions of ephemeral card numbers, complicating fraud detection and customer support operations.
- Cross-border reconciliation complexity:Multi-currency virtual card programs require harmonization between Japan's fund settlement laws and correspondent banking networks in Southeast Asian trade corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Virtual Cards Market |
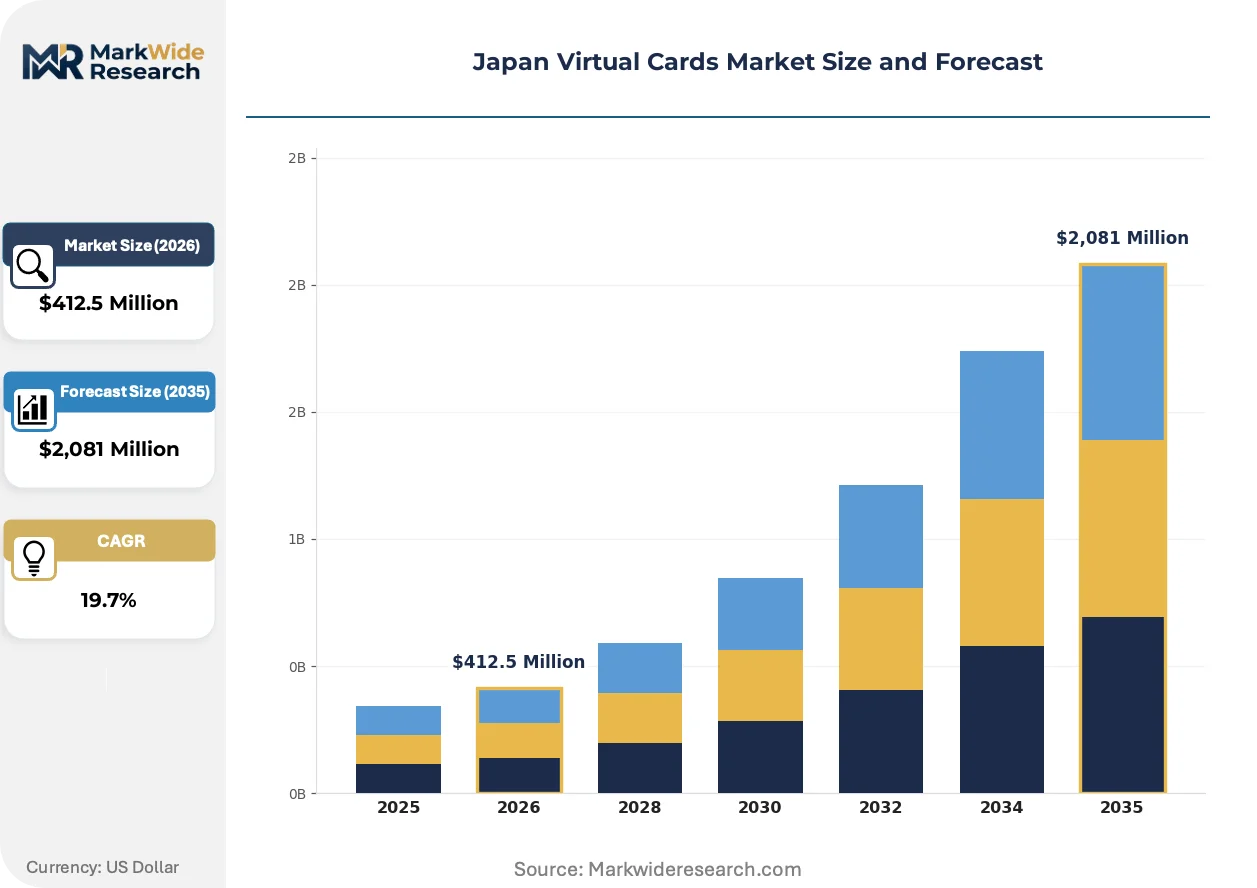
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $2,081 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepaid Cards, Debit Cards, Credit Cards, Corporate Cards End User: Corporates, SMEs, Individual Consumers, Online Retailers Technology: Tokenization, Contactless Payments, Mobile Wallets, EMV Standards Distribution Channel: Online Platforms, Banks, Financial Institutions, Payment Processors |
| Companies Covered | JPMorgan Chase & Co., Mitsui Sumitomo Card, American Express, PayPay, Rakuten Group, Visa Inc., Citigroup Inc., Stripe, Mastercard, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Virtual Cards Market Trends and Innovations
API-native issuance platforms are compressing time-to-market for virtual card programs while eroding the traditional dominance of bank-direct relationships. This infrastructure democratization enables non-financial platforms to embed payment credentials directly into operational software.
Dynamic CVV2 tokenization is overtaking static virtual card numbers as the preferred security architecture for high-value B2B transactions. Corporate treasury teams at Tokyo-headquartered trading houses are adopting rotating security codes for vendor payments exceeding one million yen. This technology is compressing fraud loss ratios while extending credential validity periods beyond the single-use norm.
METI's revised guidelines on electronic payment instrument security are mandating biometric authentication for virtual card transactions above specified thresholds. The regulation forces issuers to retool mobile enrollment workflows and upgrade token vault security architectures. Corporate card programs face the steepest compliance burden as they manage thousands of employee credentials across fragmented device fleets.
Platform-embedded procurement is displacing standalone corporate card portals as the primary interface for virtual card management. Japanese SaaS vendors serving construction and logistics verticals are integrating card generation APIs directly into project management dashboards. This shift is most visible in Tokyo's PropTech and ConTech startup clusters where spend authorization now triggers automatic credential issuance.
Japan Virtual Cards Market Segmentation
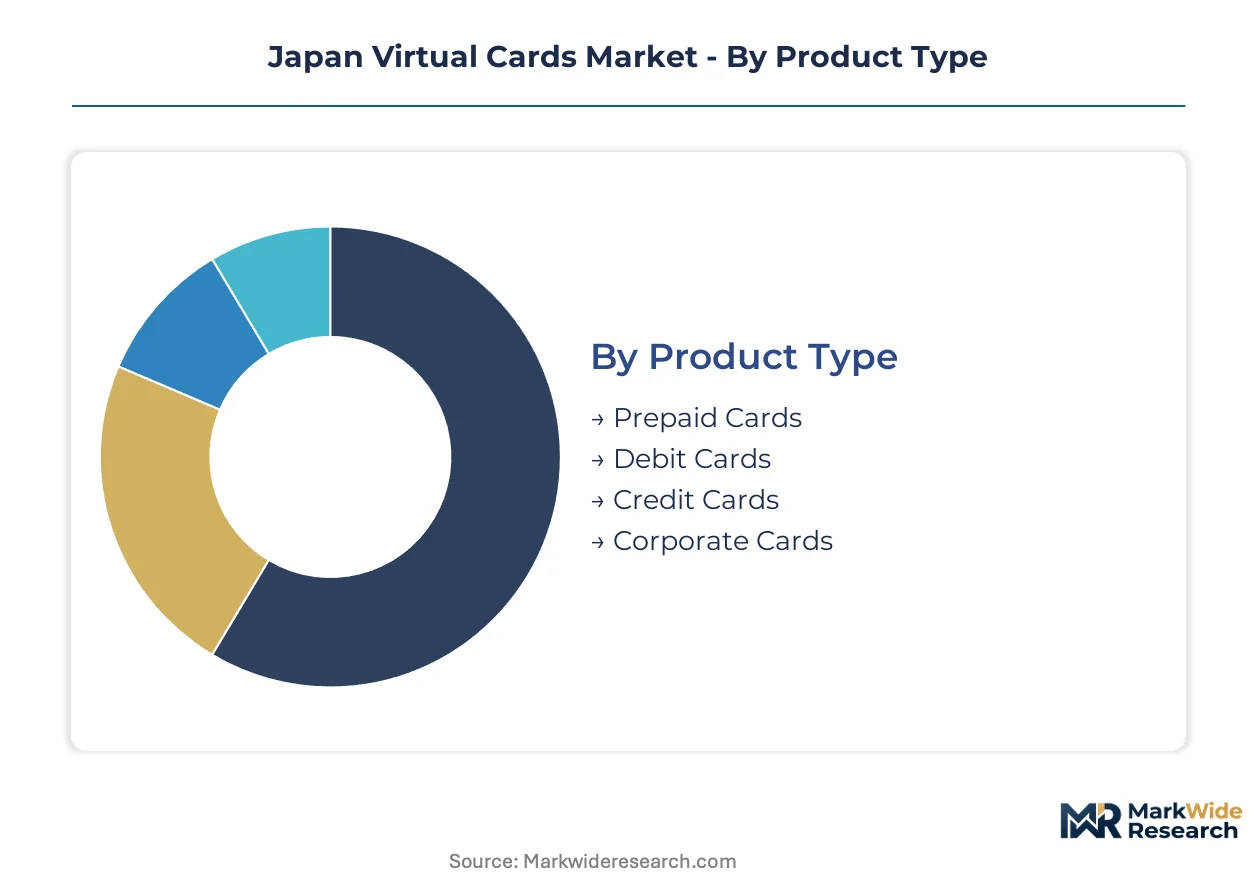
Virtual card architectures in Japan fragment across payment rails, credential types, and issuance channels. Each segmentation axis reveals distinct margin structures and compliance burdens that shape issuer strategy.
Product Type:
Payment credential specifications determine token lifecycle, liability allocation, and integration complexity with domestic ERP systems.
- Corporate Cards:Multi-employee credential programs with centralized spend controls and automated reconciliation against procurement workflows. Tokyo-headquartered trading houses and Osaka manufacturing clusters drive concentration as these entities prioritize vendor payment automation and fraud reduction.
- Credit Cards:Revolving credit instruments with virtual issuance through banking APIs, carrying interchange revenue models and stricter FSA underwriting requirements. Demand concentrates among mid-market enterprises seeking working capital optimization without plastic distribution costs.
- Prepaid Cards:Stored-value instruments with fixed funding limits, prevalent in gift card and employee benefit applications.
- Debit Cards:Direct-linked deposit accounts with real-time settlement, gaining traction among fintech-native SMEs.
Corporate cards lead on scale; credit cards lead on momentum.
End User:
Customer archetypes dictate feature requirements from API sophistication to mobile interface design.
- Corporates:Large enterprises with centralized treasury functions requiring thousands of concurrent virtual credentials, multi-currency support, and SAP/Oracle integration. Tokyo's fintech corridor houses the densest concentration as headquarters operations demand programmatic card generation for travel and procurement.
- Online Retailers:E-commerce platforms and marketplace sellers utilizing virtual cards for supplier payments and customer refunds. Osaka's SME manufacturing belt shows expanding adoption as these merchants seek alternatives to traditional invoice-based vendor settlements.
- SMEs:Small and mid-sized enterprises with lighter integration needs and price-sensitive procurement patterns.
- Individual Consumers:Personal users accessing virtual credentials through mobile wallets and bank apps.
Corporates anchor revenue concentration; online retailers show the steepest expansion trajectory.
Technology:
Security and interoperability specifications shape issuer infrastructure investments and merchant acceptance rates.
- Tokenization:EMV-compliant credential substitution replacing primary account numbers with ephemeral tokens, the foundational architecture for all virtual issuance. Japan's domestic POS networks now universally support these protocols, eliminating friction that previously constrained merchant adoption.
- Mobile Wallets:Smartphone-integrated credential storage with biometric authentication, expanding most quickly through PayPay's platform dominance and Rakuten's ecosystem integration.
- Contactless Payments:NFC-enabled tap-to-pay functionality for physical merchant acceptance.
- EMV Standards:Chip-based security specifications governing interoperability and liability rules.
Tokenization underpins all issuance; mobile wallets gain share fastest.
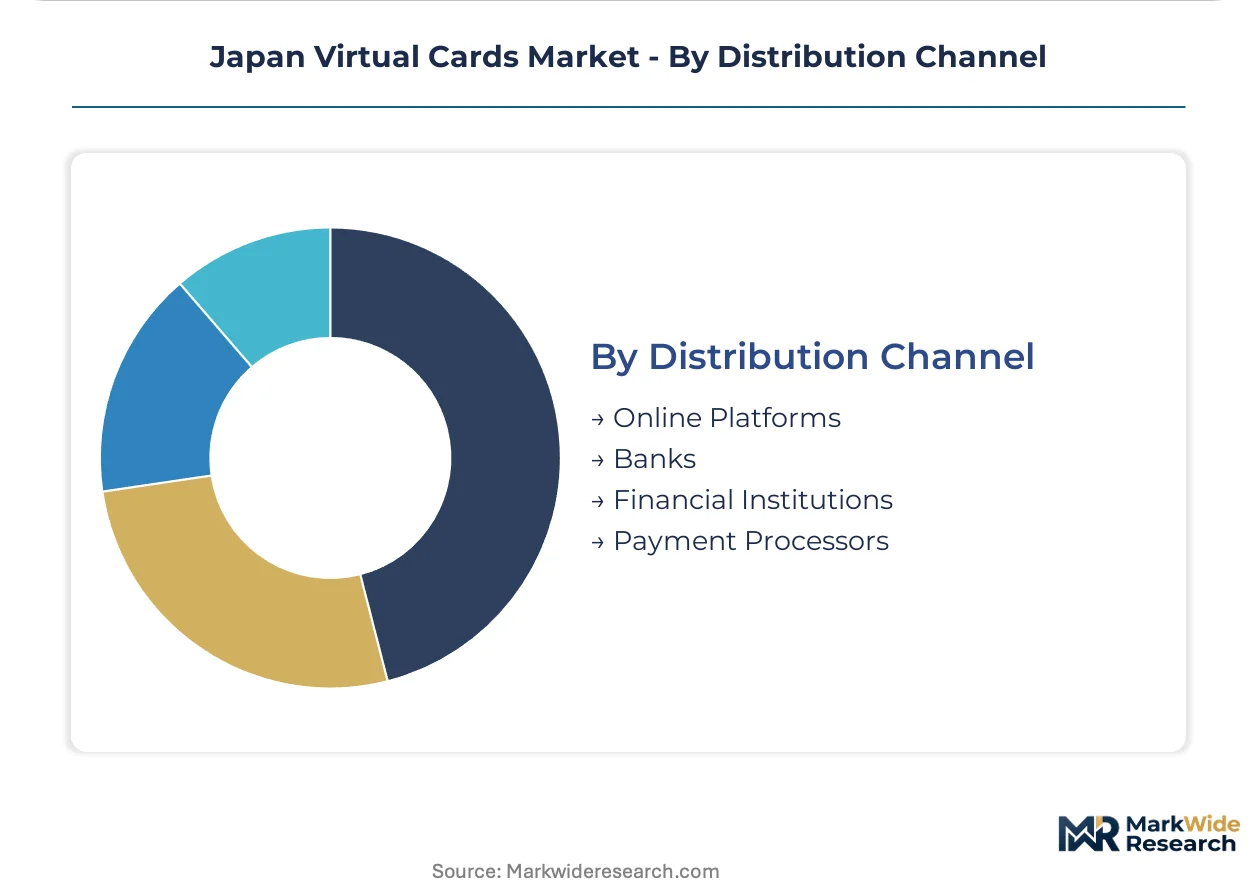
Distribution Channel:
Channel economics determine customer acquisition costs and servicing margins across the issuance value chain.
- Online Platforms:API-first issuance infrastructure enabling direct enterprise integration without intermediary banking relationships. SaaS vendors in Tokyo's PropTech and ConTech clusters embed these capabilities directly into project management dashboards.
- Banks:Traditional financial institutions with existing corporate relationships and regulatory licenses, constrained by legacy core systems requiring middleware investments for real-time provisioning.
- Financial Institutions:Non-bank lenders and specialized payment companies with niche licensing arrangements.
- Payment Processors:Technology providers handling transaction routing and settlement without direct issuance authority.
Online platforms concentrate innovation velocity; banks retain relationship depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's virtual card infrastructure outpaces South Korea's adoption curve despite both markets sharing advanced POS networks and mobile wallet penetration. Germany and the United Kingdom exhibit slower corporate migration from plastic programs due to entrenched banking relationships and legacy ERP dependencies.
United States
Enterprise procurement teams at Fortune 500 headquarters drive API-first virtual card issuance for travel and vendor spend automation. The Federal Reserve's real-time payment infrastructure investments indirectly support tokenized credential settlement velocity. Silicon Valley fintech clusters and New York financial services corridors concentrate platform development activity for programmatic card generation.
United Kingdom
Mid-market enterprises adopt virtual cards to streamline cross-border supplier payments within post-Brexit trade frameworks. The Financial Conduct Authority's electronic money regulations shape issuer licensing requirements and customer verification protocols. London's fintech corridor houses the densest concentration of API-native issuance platforms serving European corporate treasuries.
Germany
Industrial manufacturing clusters utilize virtual cards for capital equipment procurement and maintenance spend control. The Bundesbank's oversight of payment systems and BaFin's licensing frameworks enforce strict tokenization security standards. Munich and Frankfurt financial centers anchor corporate card program management for DAX-listed conglomerates.
Singapore
Regional headquarters of multinational corporations deploy virtual cards for Southeast Asian subsidiary expense management and intra-group liquidity optimization. The Monetary Authority of Singapore's payment services licensing regime accelerates compliant issuer market entry. Marina Bay fintech clusters concentrate API infrastructure providers serving cross-border B2B payment flows.
Australia
Resource sector enterprises adopt virtual cards for remote site procurement and contractor payment automation. The Australian Prudential Regulation Authority's banking supervision and ASIC's payment facility rules govern issuer conduct and consumer protection. Sydney and Melbourne financial centers house corporate treasury functions driving programmatic credential issuance.
Japan Virtual Cards Market Competitive Landscape
Japanese banking consortia anchor the domestic issuance tier; US-based payment networks and fintech platforms hold the cross-border and API infrastructure tier. The vendor structure concentrates around licensed principal members with direct scheme connectivity, creating a supply bottleneck for new entrants. Three strategic archetypes dominate: legacy banking groups with merchant network depth, global payment networks with corporate expense expertise, and API-native platforms embedding card generation into operational software. Competitive moves center on middleware partnerships for ERP integration and biometric authentication upgrades for compliance with evolving security mandates.
Within the banking archetype, Mitsui Sumitomo Card occupies a position representing domestic merchant network leverage for mid-market corporate programs. Among global network providers, American Express and Visa Inc. exemplify cross-border expense management and tokenization infrastructure respectively. At the API-native tier, Stripe sits within the platform-embedded issuance segment serving SaaS companies seeking programmatic credential generation.
| Leading Market Players |
|---|
| JPMorgan Chase & Co. |
| Mitsui Sumitomo Card |
| American Express |
| PayPay |
| Rakuten Group |
| Visa Inc. |
| Citigroup Inc. |
| Stripe |
| Mastercard |
| Others |
Pricing and Supply Chain Analysis
SWIFT messaging fee benchmarks and EMV tokenization licensing costs cascade through Japan's virtual card issuance stack, compressing margins for API-native platforms while entrenching pricing power among the three domestic banking consortia holding principal member status with JCB and Visa Japan. This cost architecture stratifies pricing tiers between high-volume corporate programs with negotiated interchange rates and SME-facing products carrying standardized processor markups.
Pricing Analysis
Capacity additions in Singapore's fintech corridor are reshaping price floors for cross-border virtual card issuance across Asia-Pacific, forcing Japanese issuers to compress SaaS-tiered subscription fees for enterprise procurement platforms. Three-tier pricing structure across premium API access, standard dashboard provisioning, and economy prepaid instruments separates Tokyo-headquartered trading houses from Osaka manufacturing clusters and individual mobile wallet users. Cost compression in the mid-market tier is intensifying because Stripe and similar platforms are disintermediating traditional bank-direct relationships. SME procurement teams show highest price sensitivity; large corporate treasury functions prioritize integration depth over per-transaction economics.
Supply Chain Analysis
Direct-to-enterprise API channels handle hyperscale buyer demand from Tokyo's fintech corridor and Osaka's manufacturing belt, while bank-intermediated distribution serves relationship-dependent corporates with legacy ERP installations. Token vault infrastructure concentrates in Japan, Singapore, and the United States, with EMVCo-certified security modules drawing from specialized semiconductor foundries in Taiwan and South Korea. Single-source vulnerability runs through the three domestic banking consortia controlling principal scheme membership, creating issuance bottlenecks for new market entrants. Distribution runs through licensed financial institutions with FSA electronic payment instrument authorization, supplemented by technology partners lacking direct issuance authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's virtual card market functions as a regulatory-arbitrage play where FSA electronic payment instrument licensing requirements create artificial scarcity in direct issuance capacity, rewarding early movers with principal member status while forcing later entrants into higher-cost processor-dependent models.
For Market Incumbents: Anchor defensive positions by deepening API-wallet convergence partnerships with PayPay's consumer infrastructure before platform-embedded procurement displaces standalone corporate portals. Prioritize biometric authentication certification investments to preempt METI security guideline compliance burdens. Threat of API-native platform disintermediation demands middleware control over SAP and Oracle integration channels. For New Entrants and Emerging Players: Kyushu semiconductor corridor procurement teams represent an underserved buyer archetype with unmet demand for programmable capital equipment purchasing cards tied to fabrication facility expansion cycles. White-space concentration in Fukuoka and Kumamoto manufacturing clusters offers lowest competitive density against entrenched Tokyo-Osaka issuance networks. Go-to-market angle should emphasize project-based credential generation integrated with construction and logistics SaaS platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with API-native issuance platforms possessing direct EMV tokenization infrastructure and existing FSA licensing, as regulatory barriers compound scarcity value. Long-term viability favors acquirers targeting middleware providers bridging legacy ERP systems to real-time provisioning capabilities. Signal to watch is METI cashless subsidy extension announcements affecting terminal deployment friction and merchant acceptance expansion.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Expansion | Compression of time-to-market for virtual card programs erodes traditional bank-direct relationship dominance. |
| Biometric Authentication Upgrade | METI security guideline compliance forces retooling of mobile enrollment workflows and token vault architectures. |
| ERP Middleware Partnership | Six-figure integration investments for on-premises SAP and Oracle installations create sticky enterprise relationships. |
| Kyushu Geographic Expansion | Fukuoka and Kumamoto chip fabrication facilities generate unmet demand for programmable procurement instruments. |
| Cross-Border Reconciliation Infrastructure | Harmonization between Japan's fund settlement laws and Southeast Asian correspondent banking networks reduces friction. |
Research Methodology
Multiple input streams — primary interviews with virtual card program managers, enterprise treasury directors, and FSA regulatory specialists, alongside secondary validation from JCB and Visa Japan scheme disclosures, METI cashless payment subsidy documentation, and EMVCo tokenization standard publications — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured procurement workflow automation priorities at Tokyo-headquartered trading houses and Osaka manufacturing clusters. Secondary sources included Financial Services Agency electronic payment instrument licensing records, Payment Services Act revision filings, and corporate ERP integration case studies from SaaS vendors in PropTech and ConTech verticals.
Data-stream reconciliation across issuance volume metrics, API transaction velocity, and merchant acceptance infrastructure deployment yielded value and volume outputs across the projection horizon. Segmentation dimensions modeled encompassed product type architecture, end-user procurement sophistication, tokenization technology tier, and distribution channel integration depth. CAGRs were derived through trend extrapolation of corporate card program adoption curves and mobile wallet-linked credential growth trajectories. Industry-specific forecast inputs incorporated FSA compliance investment cycles and METI subsidy program extensions affecting terminal deployment economics.
Underlying measurement precision varies by segment; corporate card programs with centralized treasury reporting carry tighter precision than fragmented SME prepaid instrument adoption. Forecasts reflect assumptions regarding EMV tokenization standard continuity, FSA licensing regime stability, and PayPay platform expansion velocity. Periodic stress-testing of base assumptions is recommended against regulatory revision timelines and central bank digital currency experiment outcomes that could reshape tokenized payment architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Real-Time Payments Market
Payments
Latin America Mobile Payment Market
Payments
B2C Payment Market
Payments
Mobile Card Reader Market
Payments
Contactless Payment Market
Payments
Saudi Arabia Payments Market
Payments
India POS Terminals Market
Payments
South Africa Real Time Payments Market
Payments
Europe Mobile Payment Market
Payments
Global Gift Card Market
Payments
P2P Payment Market
Payments
United Arab Emirates Mobile Payments Market
Payments
Sweden POS Terminals Market
Payments
France Mobile Payment Market
Payments
In-Vehicle Payment System Market
Payments
Epayment System Market