
 Canada Prepaid Cards Market | 2026-2036
Canada Prepaid Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Prepaid Cards Market Outlook
The Financial Consumer Agency of Canada's enhanced prepaid product disclosure guidelines is repositioning issuer obligations toward fee transparency and consumer protection. Neo Financial leverages its digital-first infrastructure to compete on user experience and reward integration. Peoples Trust Company anchors its position through regulated deposit-taking status and partnership-based card issuance. Mastercard Inc. sustains network dominance by controlling interchange frameworks and tokenization standards across Canadian prepaid programs.
Prepaid cards in Canada are payment instruments funded in advance of use, bearing card network branding and operating on domestic or international payment rails without extending credit to the cardholder. They function through stored-value mechanisms processed via EMV chip or NFC contactless protocols, serving purposes from payroll disbursement to travel expenditure containment. Open-loop cards occupy the largest share of transaction volume by enabling universal merchant acceptance, while reloadable products capture the fastest growth trajectory as recurring funding habits displace single-use alternatives. The budgeting usage purpose sits at the center of fintech marketing strategies, though corporate end-user segments generate superior interchange economics and program stickiness.
OSFI's capital and liquidity requirements for deposit-taking institutions shape prepaid program economics, while the Payment Card Networks Act constrains network fee structures and merchant routing options. FINTRAC's anti-money laundering reporting obligations for prepaid product distributors add compliance layers that favor scaled issuers over niche entrants. Stakeholders must monitor the Department of Finance's open banking implementation timeline and its potential to disintermediate prepaid value propositions through direct account-to-account payment alternatives.
Market Dynamics
The Bank of Canada's retail payment oversight framework is compressing issuer operating margins while mandating fee transparency disclosures that reshape program economics across the prepaid card value chain.
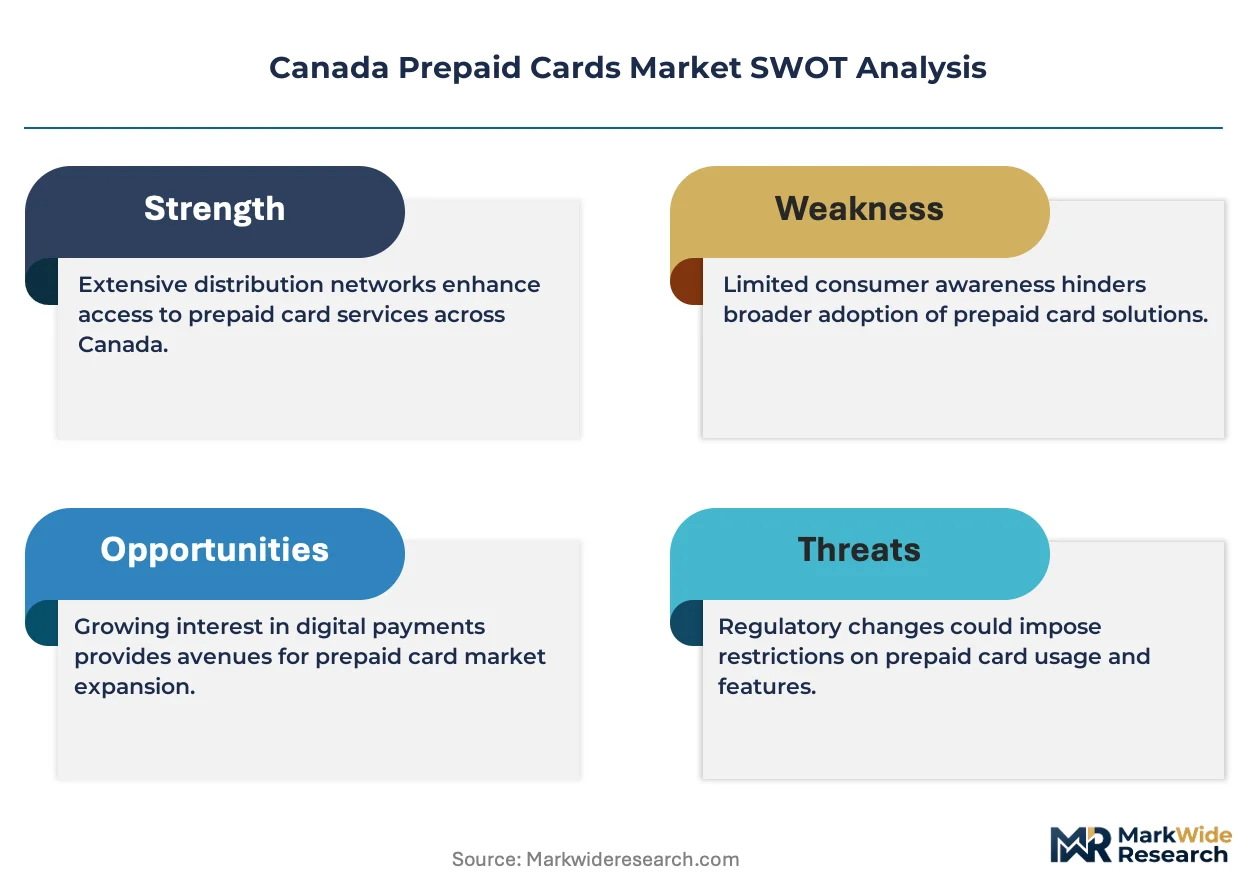
Growth Catalysts
- Open banking implementation:The Department of Finance's consumer-directed finance framework enables account-to-account funding rails that reduce prepaid load friction and expand addressable use cases beyond traditional banking exclusion.
- Corporate expense management:Enterprise payroll and travel disbursement programs are migrating from cheques to reloadable prepaid instruments, driven by reconciliation automation and spend control requirements.
- Contactless infrastructure density:Interac Flash and NFC terminal penetration in Ontario and British Columbia merchant networks is accelerating open-loop prepaid transaction velocity at point-of-sale.
Market Restraints
- OSFI capital requirements:Deposit-taking status mandates for prepaid program managers elevate minimum viable scale and exclude non-bank fintechs from direct issuance without partnership structures.
- Interchange compression risk:The Payment Card Networks Act constrains network fee schedules and merchant routing options, limiting issuer revenue per transaction.
- Account-to-account substitution:Real-time payment rails threaten prepaid value propositions for budgeting and controlled spending segments.
Strategic Opportunities
- Quebec and Prairie provinces:Underpenetrated markets outside Ontario and British Columbia offer first-mover positioning as digital payment infrastructure expands.
- Embedded finance convergence:Prepaid card APIs integrated with gig economy platforms and neobank super-apps create distribution channels beyond traditional retail.
- FINTRAC compliance automation:Anti-money laundering reporting obligations favor scaled issuers with automated KYC infrastructure, creating acquisition opportunities for niche program managers.
Industry Challenges
- EMV tokenization expertise:Mastercard's network security standards require specialized engineering talent scarce in Canadian fintech labor markets.
- Legacy core banking integration:Prepaid program managers face API fragmentation when connecting to chartered bank deposit infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Prepaid Cards Market |
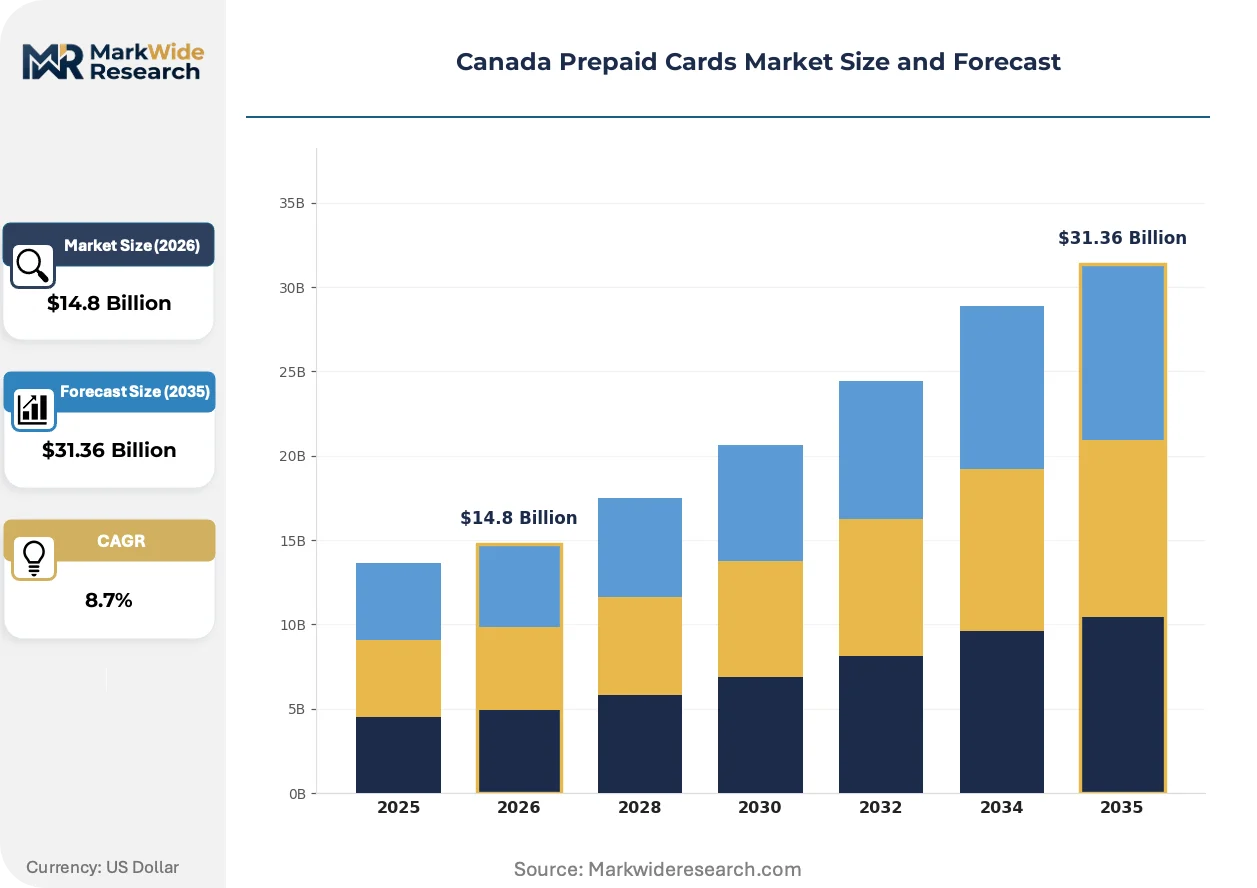
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Open-loop, Closed-loop, Reloadable, Single-use End User: Consumers, Corporates, Government, Non-profits Distribution Channel: Online, Retail, Banks, Supermarkets Usage Purpose: Travel, Gifting, Budgeting, Online Shopping |
| Companies Covered | Neo Financial, Peoples Trust Company, Visa Inc., EQ Bank, Blackhawk Network, Mastercard Inc., Wealthsimple, Carta Worldwide, KOHO Financial, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Prepaid Cards Market Strategic Shifts
Tokenization architectures and regulatory disclosure mandates are compressing issuer technology stacks while expanding consumer-facing feature differentiation across Canadian prepaid programs.
Network tokenization is unifying card-not-present security standards across e-commerce and mobile wallet environments. Merchants in Toronto and Vancouver are adopting Mastercard's token vault infrastructure at accelerated pace. This convergence is unifying fraud liability frameworks and reducing chargeback rates for reloadable prepaid products.
FINTRAC's enhanced due diligence guidelines for prepaid product distributors are extending compliance obligations to non-bank load network participants. Issuers must now implement real-time transaction monitoring across third-party retail agents. Corporate program managers face the steepest compliance cost escalation as they reconcile batch payroll loads against individual beneficiary verification requirements.
Gig economy workers are consolidating disbursement preferences onto single instruments with integrated reward redemption. Food delivery and ride-hail platforms in Calgary and Montreal are displacing separate fuel and meal cards with unified prepaid products. This consolidation is most visible in urban markets where platform density supports instrument-specific merchant partnership networks.
Canada Prepaid Cards Market Segmentation
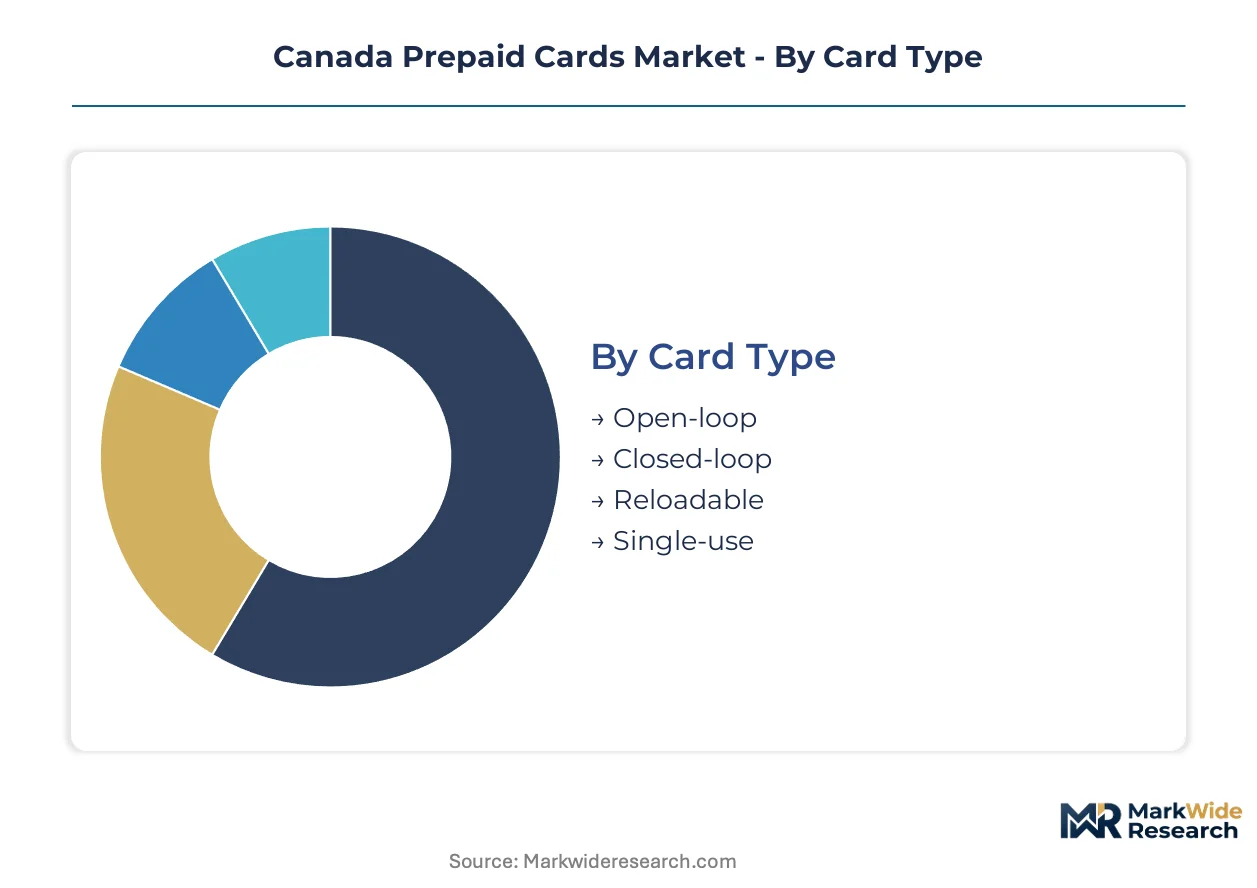
Segmentation in the Canada Prepaid Cards Market reveals how distinct buyer priorities—merchant acceptance breadth, corporate control requirements, and channel convenience—shape product design and issuer economics. Understanding these divides exposes where interchange revenue concentrates and where fintechs can bypass incumbent deposit-taking advantages.
Card Type:
Buyers choose card types based on where they need to spend and how often they reload, not on issuer branding.
- Open-loop:Network-branded instruments processed through Interac or international schemes enable universal merchant acceptance across Canada. Corporate travel programs in Toronto and Vancouver drive volume concentration, though interchange compression under the Payment Card Networks Act squeezes per-transaction economics for program managers.
- Reloadable:Stored-value products allowing repeated funding via direct deposit, bank transfer, or cash load networks. Gig economy platforms in Calgary and Montreal are consolidating disbursement onto single reloadable instruments, displacing separate fuel and meal cards through integrated reward structures.
- Closed-loop:Merchant-specific instruments redeemable only at issuing retailer or affiliated network. Grocery chains and fuel retailers deploy these for loyalty lock-in and breakage revenue capture.
- Single-use:Non-reloadable instruments with fixed initial value, commonly deployed for gifting and promotional disbursement. Limited ongoing engagement reduces program stickiness for issuers.
Open-loop leads on scale; reloadable leads on momentum.
End User:
Revenue per card and compliance burden vary sharply across customer types, with corporates delivering superior interchange economics.
- Corporates:Enterprise payroll, travel, and expense management programs require automated reconciliation and spend controls. FINTRAC's enhanced due diligence guidelines impose steepest compliance costs here as batch payroll loads must reconcile against individual beneficiary verification.
- Consumers:Individual users seeking budgeting discipline, banking exclusion alternatives, or reward integration. Neo Financial targets this segment through digital-first user experience and reward convergence.
- Government:Social benefit disbursement and emergency relief distribution. Provincial programs in Ontario and British Columbia favor prepaid instruments for unbanked recipient reach.
- Non-profits:Humanitarian aid and restricted-purpose giving. Smaller scale limits direct issuance economics, favoring partnership models with chartered deposit-takers.
Corporates dominate revenue concentration; consumers show steepest expansion trajectory.
Distribution Channel:
Channel selection determines customer acquisition cost and load network economics, with digital channels compressing physical infrastructure requirements.
- Online:Direct-to-consumer issuance through issuer websites and mobile applications. Fintech density in Ontario enables lowest customer acquisition costs here.
- Retail:Third-party agent networks including convenience stores and money service businesses. FINTRAC's extended compliance obligations to non-bank load network participants elevate monitoring costs.
- Banks:Chartered institution branches and digital platforms leveraging deposit-taking trust. OSFI capital requirements exclude non-bank fintechs from direct issuance without partnership structures.
- Supermarkets:Mass-merchant checkout integration for gift and general-purpose reloadable products. Seasonal demand spikes around holidays concentrate volume.
Banks anchor trust and scale; online channels gain share fastest.
Usage Purpose:
Purpose-driven marketing shapes feature differentiation, though actual transaction economics often diverge from stated user intent.
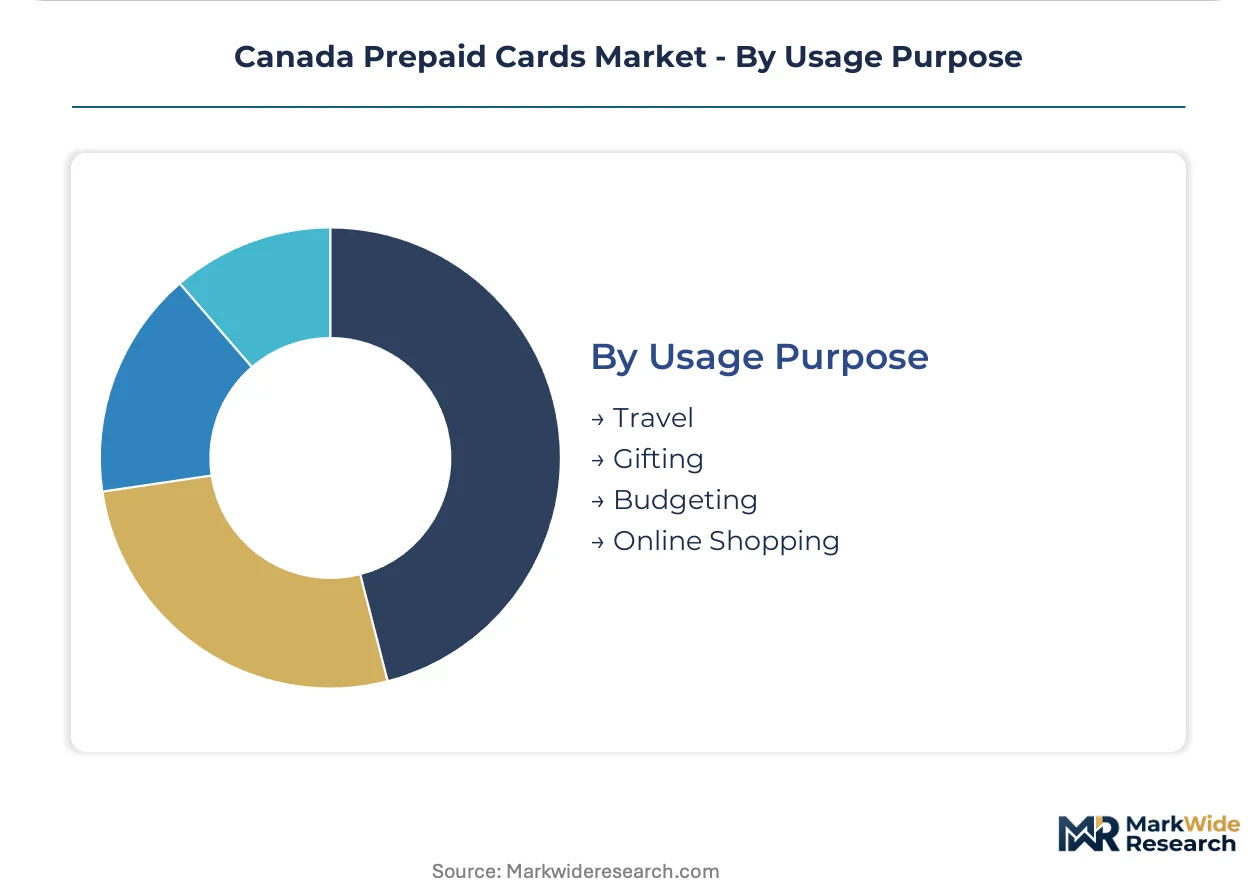
- Budgeting:Controlled spending instruments with transaction alerts and category blocking. Fintech marketing emphasizes this use case despite corporate segments generating superior program stickiness.
- Travel:Multi-currency and foreign exchange-optimized products for cross-border expenditure. Merchant acceptance breadth drives open-loop dominance here.
- Gifting:Occasion-based instruments with fixed value and limited post-purchase engagement. Breakage revenue and dormancy fees sustain issuer economics.
- Online Shopping:Card-not-present optimized products with tokenized security and virtual card generation. Network tokenization architectures from Mastercard reduce fraud liability for reloadable products.
Budgeting captures marketing investment; travel delivers highest per-transaction value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fintech talent density in Toronto and Vancouver anchors prepaid card innovation, with regulatory frameworks from the Bank of Canada and provincial governments shaping sub-regional deployment patterns across the country.
Ontario
Corporate payroll migration and expense management automation drive prepaid adoption in Toronto's financial district. The Financial Consumer Agency of Canada's disclosure guidelines impose fee transparency obligations on issuers headquartered here. Fintech clusters in downtown Toronto concentrate digital-first card issuance platforms competing on user experience.
British Columbia
Contactless infrastructure density and gig economy platform growth accelerate open-loop transaction velocity in Vancouver. OSFI capital requirements for deposit-taking institutions elevate compliance costs for program managers operating from this province. Neo Financial and KOHO Financial anchor Vancouver's prepaid innovation corridor with reward-integrated products.
Quebec
Underpenetrated digital payment infrastructure creates first-mover positioning opportunities in Montreal's emerging fintech ecosystem. The Autorité des marchés financiers coordinates with federal regulators on prepaid product oversight harmonization. Corporate travel programs in Montreal are displacing cheques with reloadable instruments for expense containment.
Alberta
Energy sector payroll disbursement and remote workforce management fuel corporate prepaid demand in Calgary. FINTRAC's anti-money laundering reporting obligations extend to oil patch money service businesses serving as load network agents. Platform density in Calgary supports gig economy consolidation onto unified prepaid products.
Prairie Provinces
Banking exclusion in rural communities sustains government benefit disbursement demand for prepaid instruments. Provincial social programs in Manitoba and Saskatchewan favor reloadable cards for unbanked recipient reach. Retail load networks in Winnipeg and Regina face elevated compliance monitoring costs under extended FINTRAC guidelines.
Canada Prepaid Cards Market Competitive Environment
Capital-heavy deposit-taking institutions compete with asset-light fintech designers for prepaid program economics, creating a tiered structure where regulatory status determines direct issuance capability. The market fragments across three strategic archetypes: chartered banks leveraging trust advantages, fintechs competing on digital experience, and network operators controlling interchange frameworks. Dominant competitive moves include partnership structures that bypass OSFI capital requirements and embedded finance integrations that capture gig economy distribution channels.
Within the fintech tier, Neo Financial, KOHO Financial, and Wealthsimple exemplify digital-first positioning that displaces traditional banking relationships through reward convergence and mobile-native interfaces. Peoples Trust Company anchors the regulated deposit-taker archetype with partnership-based issuance infrastructure. Mastercard Inc. and Visa Inc. occupy the network operator position, with Carta Worldwide representing the program management specialist segment that enables non-bank fintechs to access payment rails.
| Leading Market Players |
|---|
| Neo Financial |
| Peoples Trust Company |
| Visa Inc. |
| EQ Bank |
| Blackhawk Network |
| Mastercard Inc. |
| Wealthsimple |
| Carta Worldwide |
| KOHO Financial |
| Others |
Value Chain & Pricing Dynamics
Interchange fee benchmarks from Mastercard and Visa cascade through Canadian prepaid program economics, compressing issuer margins at the network layer while forcing differentiation through unbundled service tiers downstream.
Pricing Analysis
The bundled-versus-unbundled service split defines Canadian prepaid pricing architecture. Corporate program managers pay premium rates for integrated payroll reconciliation and spend-control APIs, while consumer-facing fintechs compete on stripped-down subscription models with transaction-based add-ons. Price differentiation rests on FINTRAC compliance automation and tokenization security tiers. Pricing pressure intensifies as open banking rails threaten load-fee revenue streams. Government disbursement programs show highest price sensitivity; corporate travel managers prioritize control features over unit cost.
Supply Chain Analysis
Warehouse-distribution layer concentration in Toronto and Vancouver anchors physical card fulfillment, with regional distribution centers serving Prairie provinces through hub-and-spoke patterns. Card manufacturing draws from China, South Korea, and domestic Ontario facilities for EMV chip embedding. Supply chain risk centers on single-source vulnerability for NFC antenna components and magnetic stripe substrates. Distribution runs through chartered bank deposit infrastructure, with Peoples Trust Company and EQ Bank controlling core banking API access that fintech issuers must lease.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canadian prepaid economics favor margin expansion through automated compliance cost reduction and premium-tier corporate program migration away from manual reconciliation.
For Market Incumbents: Lock in corporate travel and payroll relationships through embedded finance API integrations that raise switching costs. Acquire FINTRAC-automated KYC specialists to neutralize compliance cost advantages held by scaled deposit-takers. Threat from account-to-account payment rails demands preemptive positioning as disbursement orchestration platforms rather than stored-value instruments. For New Entrants and Emerging Players: Quebec government benefit administrators represent an underserved buyer archetype with fragmented incumbent coverage and harmonization gaps between federal and Autorité des marchés financiers oversight. Prairie province rural banking exclusion programs offer parallel white-space with less fintech density. Go-to-market leverage should center on provincial procurement channel partnerships rather than direct consumer acquisition. For Investors and Strategic Acquirers: Consolidation pressure builds where OSFI capital requirements exclude non-bank fintechs from direct issuance without expensive partnership structures. Long-term viability favors program managers with automated compliance infrastructure and chartered bank deposit relationships. Watch for open banking implementation velocity as inflection signal—accelerated account-to-account adoption compresses prepaid addressable market faster than modeled.| Strategic Initiative | Industry Significance |
|---|---|
| FINTRAC Compliance Automation | Reduces per-transaction monitoring costs for scaled issuers below niche competitor breakeven. |
| Embedded Finance API Integration | Captures gig economy platform distribution channels beyond traditional retail load networks. |
| Chartered Bank Partnership Structure | Bypasses OSFI capital requirements that exclude direct fintech issuance capability. |
| Network Tokenization Investment | Aligns with Mastercard security standards to reduce card-not-present fraud liability exposure. |
| Quebec and Prairie Geographic Expansion | Secures first-mover positioning in underpenetrated markets as digital payment infrastructure extends. |
Study Parameters
Direct dialogue with prepaid program managers, compliance officers at deposit-taking institutions, corporate treasury leads, and FINTRAC regulatory specialists grounded qualitative findings. Secondary validation drew from Bank of Canada payment system reports, OSFI regulatory filings, Interac network disclosure documents, and Financial Consumer Agency of Canada consumer protection guidelines. Bottom-up transaction volume modeling triangulated against top-down payment industry aggregate data.
Top-down macroeconomic anchoring informed segment-level scaling across the projection horizon. Segmentation dimensions modeled include card type, end user category, distribution channel, and usage purpose, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derived from historical payment instrument substitution patterns and corporate disbursement automation adoption curves. Forecast inputs incorporated open banking implementation timeline scenarios and interchange fee schedule sensitivity.
Underlying measurement precision varies by segment; corporate and government end-user categories carry tighter precision than consumer and non-profit segments due to disclosure requirements. Forecasts reflect documented assumptions regarding regulatory implementation velocity and payment rail substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Finland Payments Market
Payments
Denmark Mobile Payments Market
Payments
Vietnam Mobile Payments Market
Payments
LAMEA Payment Gateway Market
Payments
Sweden POS Terminals Market
Payments
Global Utility Billing Software Market
Payments
Global Gift Card Market
Payments
B2C Payment Market
Payments
Mobile Money Market
Payments
Japan Payments Market
Payments
Payment Processing Solutions Market
Payments
Third Party Payment Market
Payments
Latin America Retail Cash Management Market
Payments
United States POS Terminals Market
Payments
Asia-Pacific Payment Gateway Market
Payments
United States Electronic Toll Collection Market