
 Asia Pacific Capital Exchange Ecosystem Market | 2026-2036
Asia Pacific Capital Exchange Ecosystem Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Capital Exchange Ecosystem Market Insights
Shanghai's clearing infrastructure is shifting toward real-time gross settlement systems. The Shanghai Stock Exchange leverages its STAR Market technology board to anchor domestic semiconductor listings. Tokyo Stock Exchange sustains liquidity depth through its hybrid auction-continuous trading architecture. Hong Kong Stock Exchange competes for secondary listings of mainland technology issuers seeking offshore capital access.
The Asia Pacific Capital Exchange Ecosystem encompasses interconnected trading venues, clearinghouses, depository systems, and regulatory frameworks that facilitate capital formation across equity, debt, derivatives, and alternative instruments. Real-time risk engines process margin calculations in sub-millisecond cycles to prevent systemic counterparty failures during volatility spikes. Equity and derivatives segments dominate transaction velocity, while private equity and hedge fund asset classes capture expanding margin pools from family office allocations. Brokerage and advisory service models face compression as algorithmic execution displaces traditional commission structures.
Japan's Financial Services Agency, the Securities and Exchange Board of India, and the Monetary Authority of Singapore enforce divergent disclosure standards that fragment cross-border issuance protocols. China's National Association of Financial Market Institutional Investors coordinates interbank bond market access quotas for qualified foreign institutions. Stakeholders must monitor whether ASEAN regulatory harmonization initiatives overcome existing passporting limitations before committing to unified trading infrastructure investments.
Market Dynamics
Real-time gross settlement infrastructure across Asia Pacific exchanges is compressing clearing cycles from T+2 toward T+0, forcing simultaneous upgrades to risk engines, collateral management systems, and cross-border messaging protocols.
Growth Catalysts
- SEBI's retail derivatives framework:India's Securities and Exchange Board of India streamlined option contract specifications and margin requirements, unleashing participation from tier-2 and tier-3 cities through mobile-first brokerage platforms.
- Cross-border depository linkages:Stock Connect programs between Shanghai, Shenzhen, and Hong Kong clearinghouses enable northbound capital flows without duplicate settlement infrastructure, reducing custody fragmentation for qualified foreign institutional investors.
- Cloud-native matching engines:Tokyo Stock Exchange and Singapore Exchange deployments of distributed ledger-compatible order management systems cut latency below 50 microseconds while supporting carbon footprint tracking for ESG-mandated portfolios.
Market Restraints
- Silicon wafer supply concentration:Taiwan Semiconductor Manufacturing and Samsung Electronics dominate advanced node production for exchange hardware, creating single-source vulnerability for matching engine chipsets during geopolitical stress.
- ASEAN passporting fragmentation:Divergent disclosure standards between Monetary Authority of Singapore, Securities Commission Malaysia, and Indonesia Financial Services Authority force duplicate documentation for cross-listed instruments.
- Legacy COBOL settlement systems:Australian Securities Exchange and several ASEAN central depositories maintain 1980s-era batch processing architectures that resist real-time API integration with modern portfolio management systems.
Strategic Opportunities
- Vietnam's Ho Chi Minh Stock Exchange:The bourse's pending upgrade to a central counterparty clearing model creates first-mover advantage for infrastructure vendors capable of delivering T+1 settlement capability before regional competitors.
- Carbon credit derivatives convergence:Linkage between Singapore's Climate Impact X registry and Australian Carbon Credit Units enables standardized futures contracts on regional emissions benchmarks, attracting sovereign wealth fund hedging demand.
- India's Unified Payments Interface integration:NPCI's real-time retail payment rail now connects directly to NSE and BSE fund transfer systems, enabling instantaneous margin top-ups from non-bank payment aggregators.
Industry Challenges
- Quantitative risk modeling talent scarcity:Exchanges in Sydney, Mumbai, and Bangkok compete for PhD-level stochastic calculus specialists capable of calibrating intraday margin models for volatile cryptocurrency-linked structured products.
- Multi-jurisdiction compliance orchestration:Sell-side firms operating across Hong Kong SFC, Japan FSA, and Australia ASIC regimes must maintain parallel surveillance systems with incompatible trade reporting timestamps and alert thresholds.
- Post-trade API standardization delays:ISO 20022 message format adoption varies between Japan's JASDEC, India's NSDL, and Singapore's CDP, forcing expensive message translation layers for cross-border institutional workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Capital Exchange Ecosystem Market |
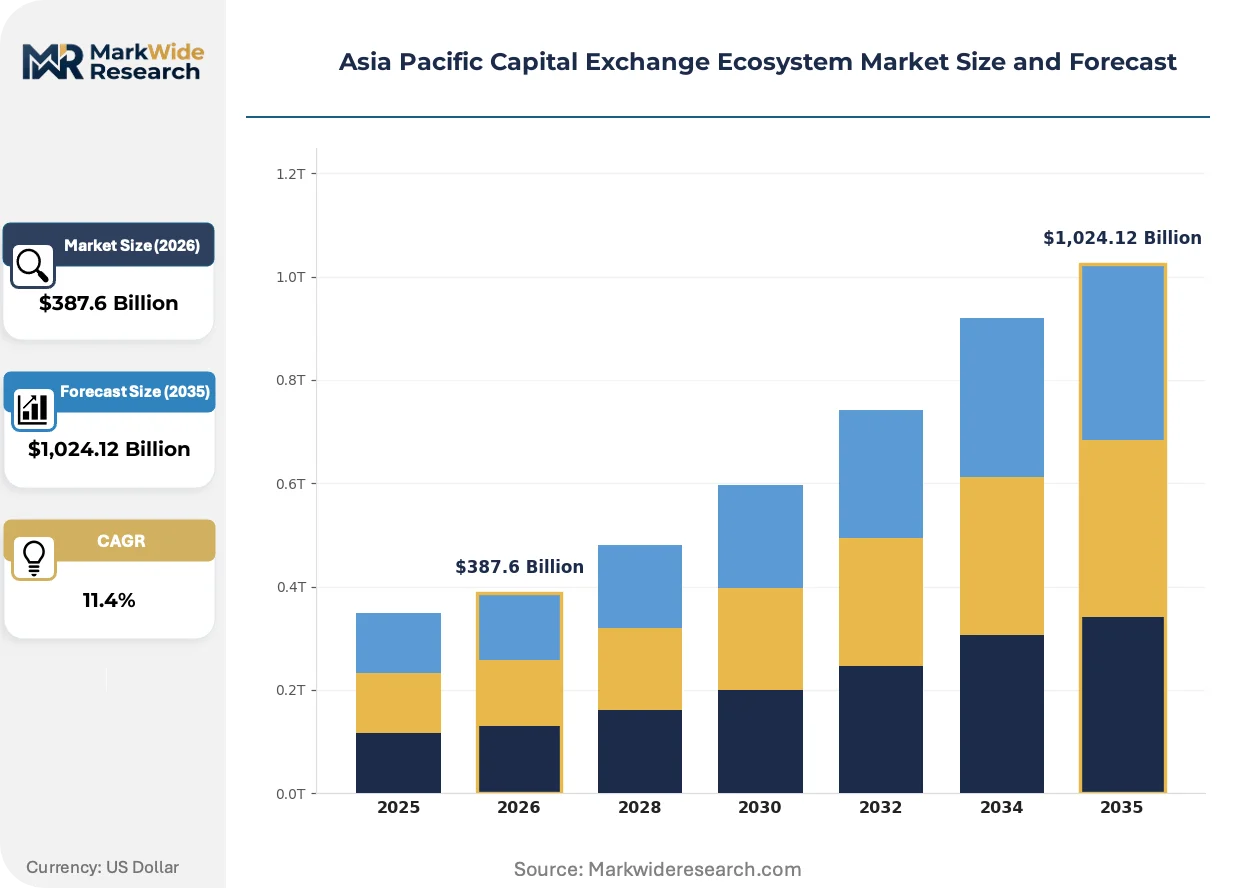
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Type: Equity, Debt, Derivatives, Mutual Funds Asset Class: Real Estate, Commodities, Private Equity, Hedge Funds Service Model: Brokerage, Advisory, Custodial, Market Making Participant Type: Institutional Investors, Retail Investors, Family Offices, Wealth Managers |
| Companies Covered | Shanghai Stock Exchange, Tokyo Stock Exchange, Hong Kong Stock Exchange, Bombay Stock Exchange, National Stock Exchange, Shenzhen Stock Exchange, Korea Exchange, Taiwan Stock Exchange, Singapore Exchange, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Capital Exchange Ecosystem Market Trends and Innovations
Distributed ledger infrastructure is migrating from pilot programs to production settlement layers, while regulatory technology mandates in India and Singapore accelerate the obsolescence of manual compliance workflows across the region's capital markets.
Blockchain-based delivery-versus-payment mechanisms are consolidating fragmented settlement silos across ASEAN bond markets. Thailand's Bond Electronic Exchange and Malaysia's Electronic Trading Platform have adopted Hyperledger Fabric nodes for government securities clearing, cutting settlement failure rates while compressing reconciliation staffing requirements. Regional banks now route secondary market trades through shared ledger infrastructure rather than bilateral messaging.
Japan's Financial Services Agency revised its Stewardship Code to mandate granular voting disclosure from asset managers, forcing Tokyo Stock Exchange-listed issuers to upgrade proxy solicitation systems. The regulation compresses the window between shareholder meetings and vote tabulation, requiring real-time blockchain verification for institutional block votes. Domestic trust banks are consolidating legacy proxy advisory relationships into integrated governance technology stacks.
Family office direct indexing is displacing bundled mutual fund allocations across Singapore and Hong Kong wealth channels. Ultra-high-net-worth investors now construct custom benchmarks through fractional share ownership platforms, stripping out manager fees while retaining tax-loss harvesting automation. Private banks respond by unbundling custody from investment advisory, pricing each component separately for portfolios exceeding SGD 50 million in AUM.
Asia Pacific Capital Exchange Ecosystem Market Segmentation
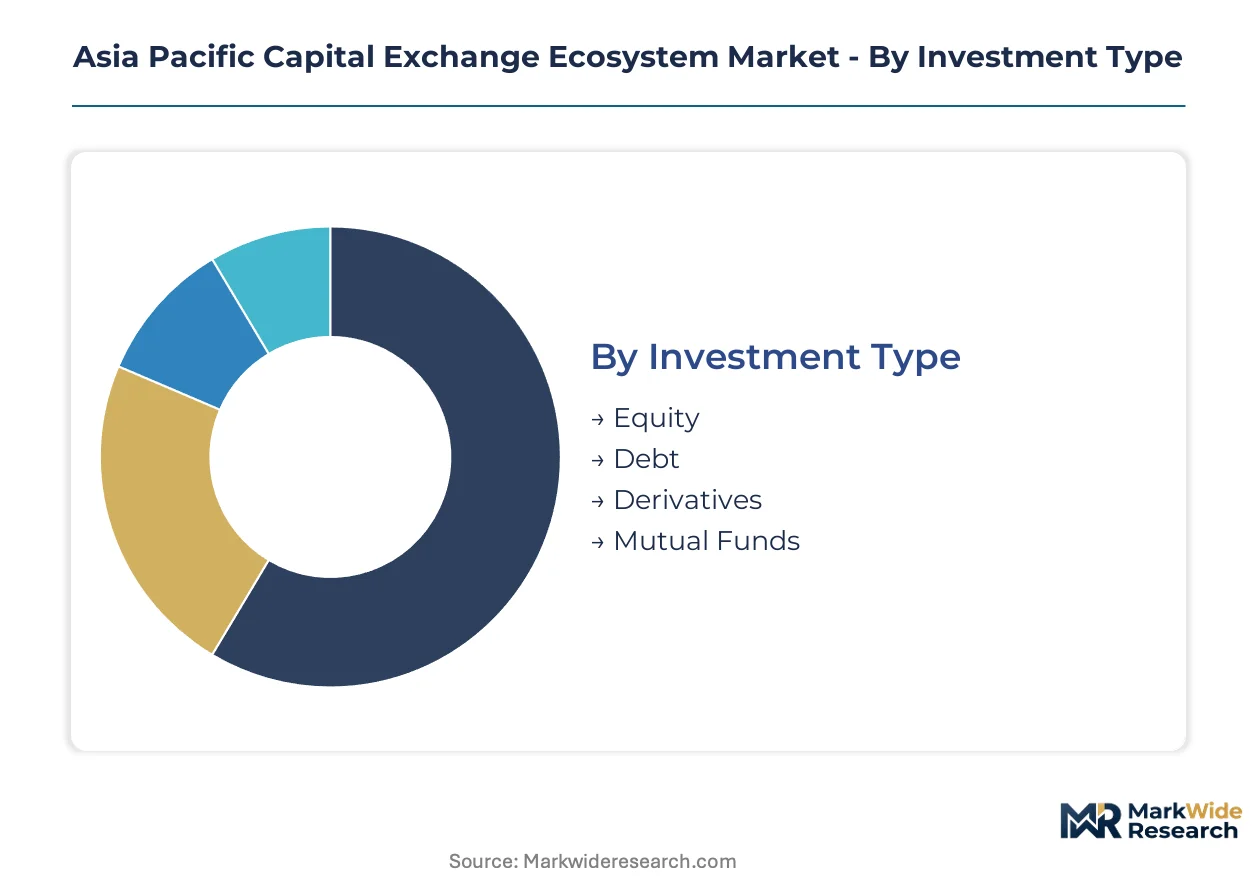
The Asia Pacific Capital Exchange Ecosystem fragments across four distinct dimensions that determine technology investment priorities and regulatory compliance burdens. Each segmentation axis reveals divergent margin structures and infrastructure requirements that shape vendor competitive positioning.
Investment Type:
Equity and derivatives segments capture the highest transaction velocity, while debt and mutual funds concentrate institutional AUM in longer-duration positions.
- Equity:Common and preferred share trading across primary issuance and secondary markets dominates exchange revenue through transaction fees and listing charges. Retail participation in India's cash equity segment through mobile brokerage apps is compressing traditional commission schedules.
- Debt:Government bonds, corporate paper, and convertible instruments trade through dealer networks and electronic platforms with lower velocity but larger ticket sizes. China's interbank bond market access quotas for qualified foreign institutions concentrate demand in sovereign and policy bank issuance.
- Derivatives:Futures and options contracts on equity indices, interest rates, and commodities require real-time margin calculation engines. SEBI's streamlined option specifications for Indian retail participants are expanding contract volumes beyond institutional hedging demand.
- Mutual Funds:Pooled investment vehicles distribute through bank channels and direct-to-consumer platforms with NAV-based pricing. Singapore's fund passporting frameworks enable cross-border UCITS-equivalent distribution across ASEAN markets.
Today's leader: Equity. Tomorrow's challenger: Derivatives.
Asset Class:
Alternative assets capture expanding allocations from family offices seeking uncorrelated returns, while traditional real estate and commodities maintain institutional hedging functions.
- Real Estate:REITs and direct property exposure trade through exchange-listed vehicles and private placement structures. Japan's Tokyo Stock Exchange REIT segment anchors Asia Pacific property securitization with J-REITs commanding premium liquidity.
- Commodities:Precious metals, energy, and agricultural contracts clear through regional bourses and over-the-counter swaps. Singapore Exchange's iron ore and rubber futures serve as regional price discovery benchmarks for physical procurement.
- Private Equity:Unlisted company stakes trade through secondary markets and fund-of-funds structures with extended lock-up periods. Hong Kong's proposed SPAC framework and special purpose vehicles are channeling family office capital into pre-IPO growth equity.
- Hedge Funds:Absolute return strategies deploy through managed accounts and fund platforms with performance fee structures. Australia's wholesale investor exemptions enable offshore hedge fund distribution to sophisticated retail segments.
Alternative assets are gaining share fastest as wealth concentration drives demand for bespoke portfolio construction.
Service Model:
Execution-only brokerage faces compression while integrated advisory and custody services defend margin through relationship pricing.
- Brokerage:Order routing and trade execution services compete on latency and commission rates with algorithmic platforms displacing voice trading. Tokyo Stock Exchange's arrowhead system and Singapore Exchange's matching engines process orders in sub-50 microsecond cycles.
- Advisory:Portfolio construction and asset allocation services price through basis points on AUM or fixed retainer structures. India's SEBI-registered investment advisers are migrating from product commissions to fee-only models under regulatory pressure.
- Custodial:Asset safekeeping, corporate action processing, and income collection require sub-custody networks across fragmented settlement systems. Hong Kong's central clearing and settlement system competes with Singapore's CDP for regional fund domiciliation.
- Market Making:Liquidity provision through continuous two-sided quoting absorbs inventory risk in exchange for bid-ask spread capture. Designated market makers on Korea Exchange and Taiwan Stock Exchange stabilize order book depth during volatility episodes.
Integrated custody-advisory bundles currently dominate institutional RFPs. Unbundled component pricing is emerging as the challenger model.
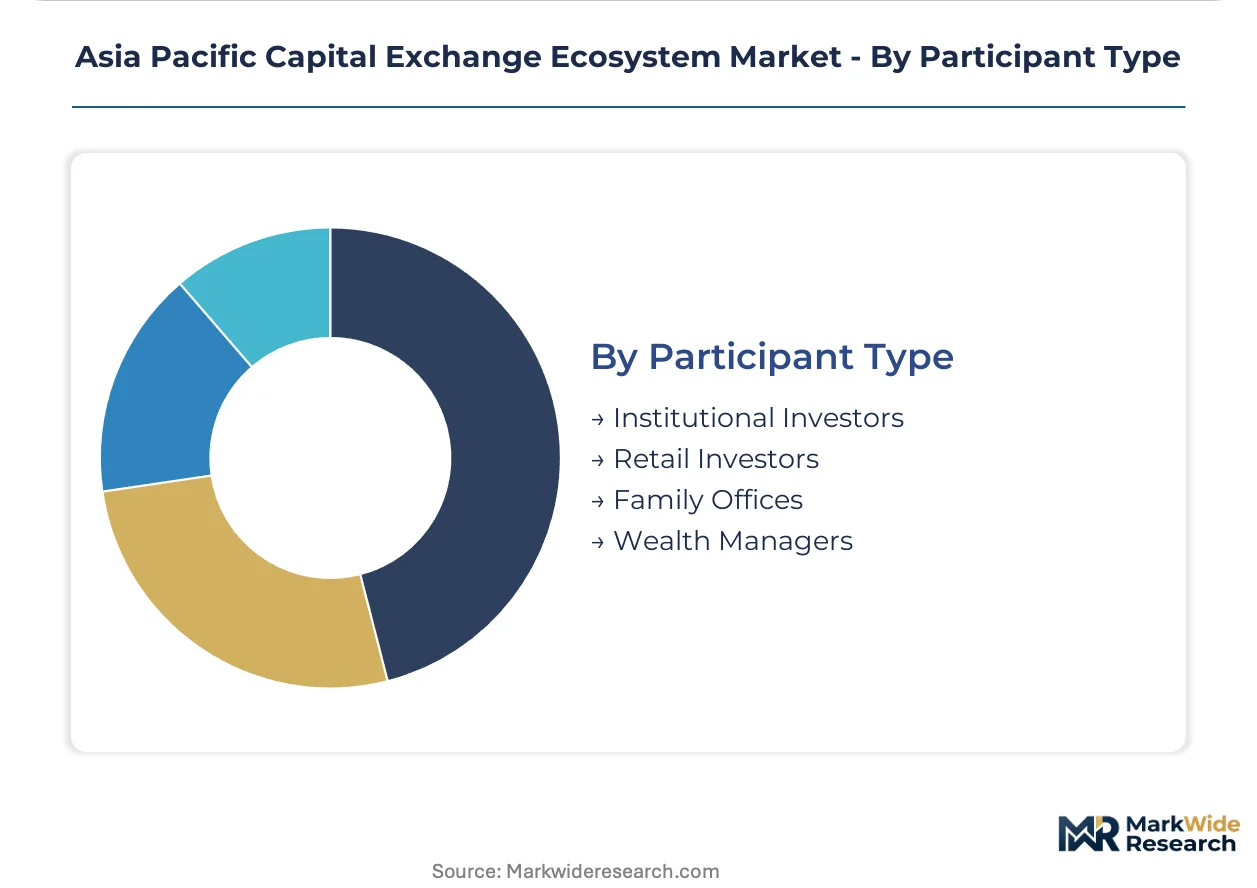
Participant Type:
Institutional flows provide volume foundation while retail and family office segments drive platform technology investments.
- Institutional Investors:Pension funds, insurance companies, and sovereign wealth funds execute block trades with low-touch algorithms and direct market access. Australia's superannuation funds and Japan's Government Pension Investment Fund anchor regional equity and bond demand.
- Retail Investors:Individual accounts through discount brokerages and mobile-first platforms generate high-velocity, small-ticket transactions. India's tier-2 and tier-3 city participants are expanding through regional language interfaces and UPI-funded margin accounts.
- Family Offices:Single-family and multi-family investment vehicles deploy direct indexing and private deal co-investment with bespoke governance requirements. Singapore's variable capital company structure and Hong Kong's family office tax concessions are attracting regional wealth migration.
- Wealth Managers:Private banks and independent advisers construct multi-asset portfolios with discretionary and non-discretionary mandates. Australia's financial adviser standards and ethics authority regime is reshaping licensee compliance costs.
Institutional investors anchor current infrastructure capacity. Family offices are expanding most quickly as the next platform investment priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping capital formation flows across Asia Pacific, with exchanges in lower-compliance-cost jurisdictions capturing listing migrations from more stringent disclosure regimes. Singapore and Hong Kong compete aggressively for secondary listings through streamlined dual-class share frameworks. Infrastructure modernization cycles are compressing settlement timelines from T+2 toward T+0 across ASEAN markets.
China
Shanghai's STAR Market technology board anchors domestic semiconductor capital formation, with the Shanghai Stock Exchange processing real-time gross settlement through upgraded clearing infrastructure. The country's National Association of Financial Market Institutional Investors coordinates interbank bond market access quotas for qualified foreign institutions. The Yangtze River Delta cluster concentrates exchange technology vendors serving both Shanghai and Shenzhen bourses.
Japan
Tokyo Stock Exchange sustains liquidity depth through hybrid auction-continuous trading architecture, while the Financial Services Agency mandates granular voting disclosure under revised Stewardship Code requirements. Japan's Government Pension Investment Fund anchors regional equity demand through passive allocation strategies. The Kanto/Tokyo metropolitan area houses domestic trust banks consolidating legacy proxy advisory relationships into integrated governance technology stacks.
India
SEBI's streamlined option contract specifications and margin requirements have unleashed retail derivatives participation from tier-2 and tier-3 cities through mobile-first brokerage platforms. The National Payments Corporation of India's Unified Payments Interface now connects directly to NSE and BSE fund transfer systems. Mumbai's financial district concentrates algorithmic trading infrastructure vendors serving expanding retail order flow.
Singapore
The Monetary Authority of Singapore enforces disclosure standards that position the Singapore Exchange to compete for regional fund domiciliation against Hong Kong's central clearing system. Variable capital company structures attract family office wealth migration through tax concessions and streamlined governance frameworks. The city-state's Climate Impact X registry enables standardized carbon credit derivatives convergence with Australian benchmarks.
Australia
The Australian Securities Exchange maintains legacy COBOL settlement systems that resist real-time API integration with modern portfolio management systems, creating infrastructure vulnerability. Wholesale investor exemptions enable offshore hedge fund distribution to sophisticated retail segments. Sydney's quantitative risk modeling talent pool competes with Mumbai and Bangkok for PhD-level stochastic calculus specialists calibrating intraday margin models.
Asia Pacific Capital Exchange Ecosystem Market Competitive Landscape
Established exchanges occupy the standard tier; emerging entrants pursue adjacent fintech infrastructure and regulatory technology services. The market structure consolidates around national champion bourses with natural monopoly characteristics in clearing and settlement. Three archetypes dominate: legacy exchange operators with government-conferred franchises, technology infrastructure vendors supplying matching engines and risk systems, and cross-border depository linkage providers enabling Stock Connect-style capital flows. Competitive moves center on cloud-native platform migrations and strategic partnerships with distributed ledger consortia.
Among Asia Pacific exchange operators, Shanghai Stock Exchange, Tokyo Stock Exchange, and Singapore Exchange represent the tier of established national champions with integrated trading, clearing, and depository functions. These entities exemplify the government-affiliated archetype where regulatory authority and commercial operations intertwine, occupying positions that resist direct competitive entry. Hong Kong Stock Exchange sits within the offshore gateway specialization, capturing secondary listings of mainland technology issuers seeking capital access outside domestic regulatory frameworks.
| Leading Market Players |
|---|
| Shanghai Stock Exchange |
| Tokyo Stock Exchange |
| Hong Kong Stock Exchange |
| Bombay Stock Exchange |
| National Stock Exchange |
| Shenzhen Stock Exchange |
| Korea Exchange |
| Taiwan Stock Exchange |
| Singapore Exchange |
| Others |
Pricing and Supply Chain Analysis
Cloud-native matching engine deployments across Tokyo Stock Exchange and Singapore Exchange are compressing latency below 50 microseconds while simultaneously concentrating vendor ecosystems around three infrastructure specialists. This technology transition elevates capital expenditure requirements for exchanges while fragmenting pricing power between legacy hardware incumbents and software-defined challengers.
Pricing Analysis
Exchange technology licensing fees stratify across premium, standard, and economy tiers based on throughput capacity and disaster recovery redundancy levels. Pricing pressure stems from open-source alternatives encroaching on middleware layers, forcing proprietary vendors to bundle implementation services. Tier-2 exchanges in Vietnam and Indonesia exhibit highest price sensitivity, while Singapore and Hong Kong anchor premium pricing through regulatory credibility.
Supply Chain Analysis
Dual-sourcing mandates from Monetary Authority of Singapore and Japan Financial Services Agency require exchanges to qualify redundant chipset suppliers for matching engine hardware. Taiwan and South Korea anchor advanced semiconductor fabrication for exchange infrastructure, with Japan and USA contributing specialized networking components. Single-source vulnerability concentrates in Taiwan Semiconductor Manufacturing's 5nm node production. Distribution runs through systems integrators with exchange-specific certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
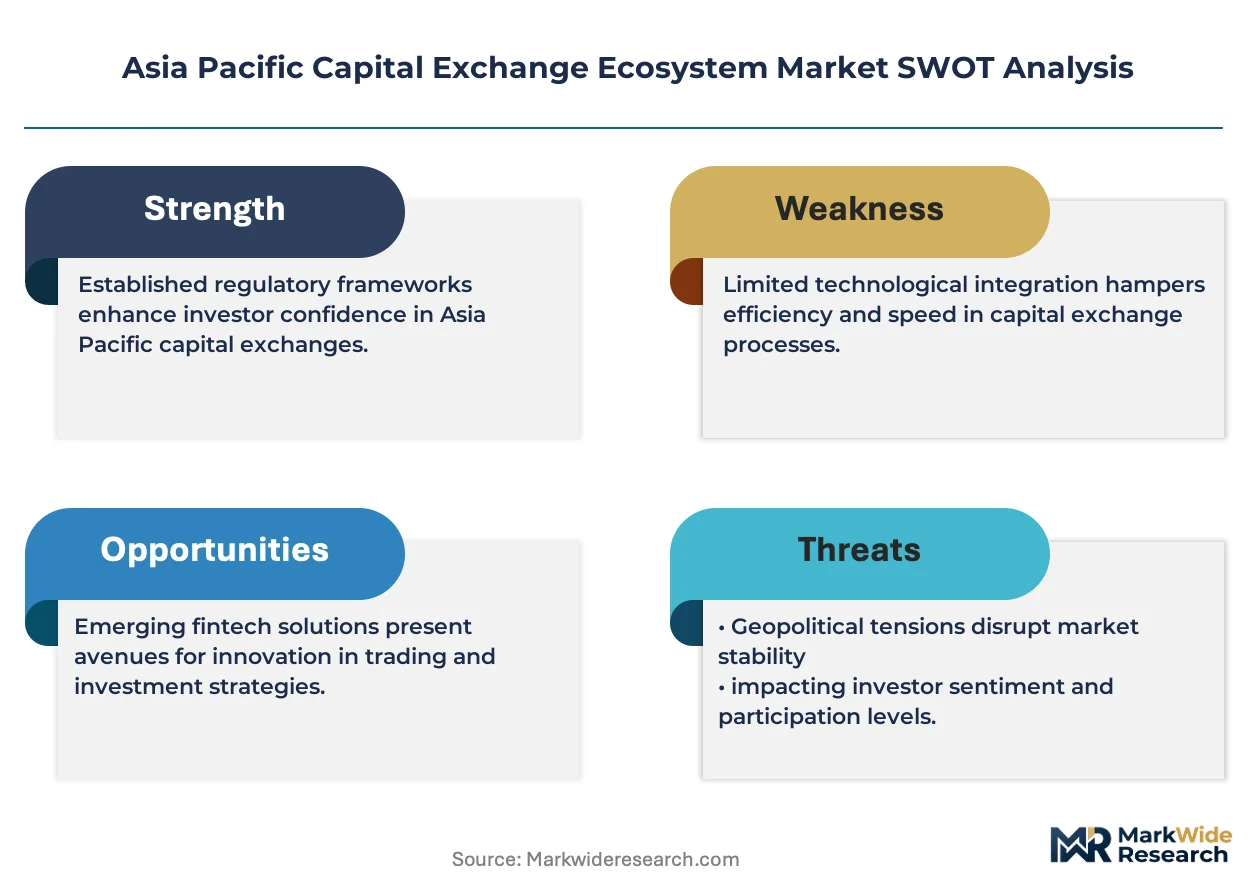
This market functions as a geographic-arbitrage play where regulatory compliance costs in Hong Kong run substantially below Tokyo's granular Stewardship Code enforcement, enabling margin capture for secondary listing venues.
For Market Incumbents: Anticipate margin compression from distributed ledger consortia by accelerating cloud-native platform migrations before 2026 infrastructure refresh cycles. Defend clearing monopoly positions through vertical integration into collateral management software, neutralizing fintech challengers targeting T+0 settlement gaps. For New Entrants and Emerging Players: Launch via regulatory technology service layers targeting ASEAN passporting fragmentation pain points. Vietnam's Ho Chi Minh Stock Exchange upgrade timeline presents the most penetrable infrastructure replacement window. Prioritize carbon credit derivatives convergence as the go-to-market anchor linking Singapore's Climate Impact X with Australian registry systems. For Investors and Strategic Acquirers: Valuations sit cheapest among legacy COBOL-dependent settlement system operators facing forced modernization. Long-term viability hinges on successful API-layer transformation enabling real-time integration. Watch for SEBI derivatives framework expansion into commodity options as the inflection signal for Indian infrastructure demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Matching Engine Migration | Tokyo Stock Exchange's Arrowhead system upgrade cuts latency below 50 microseconds while embedding carbon tracking. |
| Cross-Border Depository Linkage Expansion | Stock Connect program extensions between Shanghai, Shenzhen and Hong Kong reduce custody fragmentation for qualified foreign institutions. |
| Real-Time Gross Settlement Infrastructure | India's T+0 pilot at NSE and BSE forces simultaneous risk engine and collateral management system upgrades. |
| Carbon Credit Derivatives Standardization | Singapore's Climate Impact X registry linkage with Australian Carbon Credit Units enables sovereign wealth fund hedging instruments. |
| Retail Derivatives Platform Localization | SEBI's tier-2 and tier-3 city expansion through regional language interfaces unlocks India's mobile-first brokerage growth. |
Research Methodology
Coverage spans China, Japan, India, Singapore, Australia and ASEAN markets, with primary inputs from each jurisdiction's exchange operators and regulators. The analysis combines structured interviews with exchange technology officers, clearinghouse risk managers, SEBI and Monetary Authority of Singapore regulatory leads, and institutional brokerage heads with secondary validation against exchange annual disclosures, central securities depository filings, and securities regulator enforcement reports. Bottom-up transaction volume modeling triangulates against top-down GDP-correlated capital formation projections.
Granularity extends to investment type, asset class, service model and participant type dimensions, with additional modeling depth on settlement cycle compression timelines across the analysis window. CAGRs derive from logistic adoption curves fitted to infrastructure upgrade announcements and regulatory mandate effective dates. Forecast inputs incorporate cloud migration capex disclosures and distributed ledger pilot program outcomes.
Several conditions sit outside the modeled scope, including geopolitical suspension of Stock Connect programs and abrupt semiconductor export restrictions affecting matching engine hardware procurement. Forecasts assume continuous regulatory harmonization momentum across ASEAN jurisdictions. Deviation in SEBI's retail derivatives margin framework or Japan's Stewardship Code enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
US Securities Brokerage Market
Capital Markets and Securities
Special Purpose Vehicle Market
Capital Markets and Securities
Algorithmic Trading Market
Capital Markets and Securities
North America Mutual Fund Market
Capital Markets and Securities
Foreign Exchange Market
Capital Markets and Securities
Stock Trading Affiliate Programs Market
Capital Markets and Securities
Securities Trading Software Market
Capital Markets and Securities
South America ETF Market
Capital Markets and Securities
GCC Mutual Fund Market
Capital Markets and Securities
Armenia Stock Market
Capital Markets and Securities
US Capital Exchange Ecosystem Market
Capital Markets and Securities
China Capital Exchange Ecosystem Market
Capital Markets and Securities
Middle East and Africa ETF Market
Capital Markets and Securities
Hong Kong Capital Exchange Ecosystem Market
Capital Markets and Securities
Shadow Banking Market
Capital Markets and Securities
Exchange Traded Fund Market