
 Hong Kong Payments Market | 2026-2036
Hong Kong Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Payments Market Foresight
Software-defined API orchestration is repositioning how payment infrastructure gets monetized in Hong Kong. Airwallex leverages cloud-native treasury stacks to capture cross-border B2B flows. HSBC anchors its position through extensive merchant acquiring networks and real-time gross settlement access. Octopus competes by extending its stored-value facility from transit into retail and online checkout environments.
Hong Kong payments encompass electronic fund transfer systems, card networks, mobile wallets, and real-time clearing infrastructure that facilitate commercial and consumer transactions through standardized messaging protocols and encrypted tokenization. The primary purpose is to reduce settlement friction, mitigate counterparty risk, and enable programmable money movement across domestic and offshore corridors. Mobile wallet adoption among millennials outpaces other customer segments due to super-app integration and loyalty program bundling. Cross-border peer-to-peer channels linking mainland China represent the fastest-growing transaction type, while in-store card acceptance remains the dominant value pool for incumbent banks.
The Hong Kong Monetary Authority governs licensing, systemic risk, and stored-value facility oversight through its Fintech Supervisory Sandbox and virtual banking framework. The Securities and Futures Commission coordinates with the HKMA on payment tokenization and digital asset settlement boundaries. Stakeholders must monitor how mainland China's digital yuan interoperability trials and Hong Kong's e-HKD pilot reshape clearing infrastructure investment priorities.
Market Dynamics
The Hong Kong Monetary Authority's Faster Payment System and virtual banking framework are compressing settlement timelines while fragmenting deposit-taking authority across non-traditional entrants.
Growth Catalysts
- Faster Payment System:The HKMA's real-time gross settlement infrastructure reduces interbank clearing friction from T+1 to immediate finality, pulling transaction volume from legacy card networks into account-based rails.
- Transit-to-retail wallet extension:Octopus Card's stored-value facility migration from MTR corridors into convenience stores and online checkout environments is absorbing cash displacement volume.
- Cross-border RMB corridors:Mainland China's payment system interoperability trials with Hong Kong clearing banks are accelerating remittance flow velocity through licensed e-wallet providers.
Market Restraints
- Core banking system replacement costs:Legacy mainframe architectures at incumbent deposit-taking institutions require capital outlays exceeding virtual bank license application thresholds, freezing technology refresh cycles.
- Concentrated cloud infrastructure:AWS and Azure dominance over Hong Kong data center capacity creates single-point-of-failure exposure for new entrants dependent on outsourced compute.
- Basel III liquidity coverage ratios:The HKMA's stringent stable funding requirements constrain payment float monetization strategies that rely on overnight money market placement.
Strategic Opportunities
- e-HKD pilot program:The central bank digital currency wholesale layer trials offer programmable settlement infrastructure for securities tokenization and atomic delivery-versus-payment.
- Greater Bay Area integration:WeChat Pay and AlipayHK interoperability with mainland wallets remains underpenetrated for merchant acquiring outside Shenzhen and Guangzhou corridors.
- API-led banking:Open banking mandates under the HKMA's Fintech Supervisory Sandbox are enabling account aggregation services that bundle payments with credit and insurance distribution.
Industry Challenges
- Embedded finance engineering talent:Shortage of full-stack developers capable of integrating treasury APIs with enterprise resource planning systems is extending implementation timelines for B2B platforms.
- Multi-jurisdiction licensing:Money service operator permits across Hong Kong, Singapore, and UK jurisdictions create compliance complexity for cross-border payment aggregators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Payments Market |
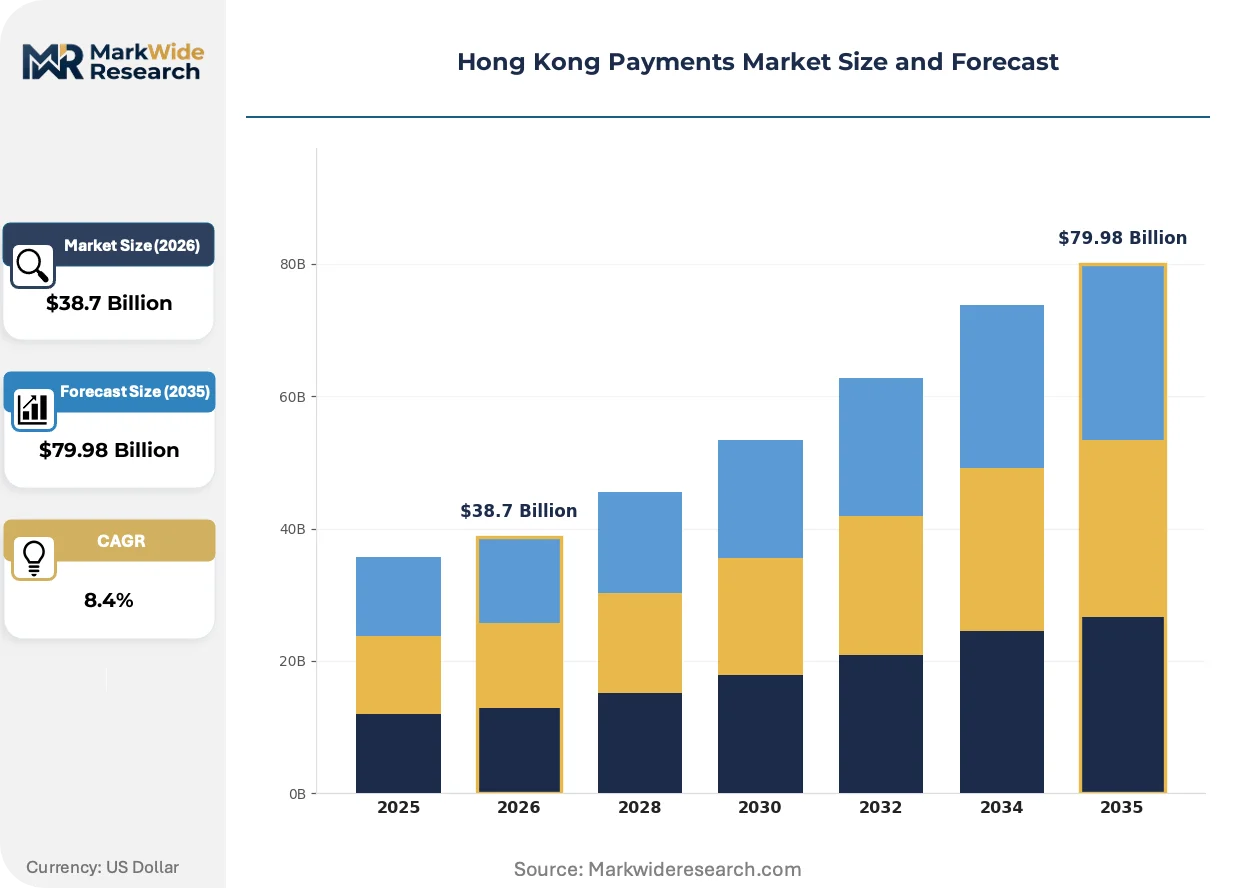
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Wallet, Cash Transaction Type: In-Store, Online, Peer-to-Peer, Bill Payments Customer Segment: Millennials, Business Owners, Tourists, Retail Customers Platform Type: Web, Mobile App, POS System, Third-Party Services |
| Companies Covered | The Bank of East Asia Limited, Airwallex, The Hongkong and Shanghai Banking Corporation Limited, Stripe, Octopus, Bank of China (Hong Kong) Limited, Citibank (Hong Kong) Limited, PayPal, Standard Chartered Bank (HK) Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Payments Market Shifts & Advancements
Software-defined payment orchestration is collapsing the distinction between domestic clearing and cross-border treasury management, forcing infrastructure providers to rebuild around API-first architectures.
Tokenized settlement rails are absorbing high-value corporate payment flows that previously required correspondent banking relationships. Multinational treasury departments in Hong Kong are piloting programmable escrow through smart contract layers, compressing documentary trade settlement from days to minutes. This shift is enabling non-bank platforms to capture working capital management services historically anchored by HSBC and Standard Chartered.
The HKMA's Fintech Supervisory Sandbox 2.0 framework is compressing licensing timelines for stored-value facility operators from 18 months to 6 months. This regulatory acceleration is pulling venture deployment into payment infrastructure startups that previously bypassed Hong Kong for Singapore licensing. Virtual banks are responding by launching white-label payment processing for e-commerce marketplaces.
Merchant acquiring contracts are shortening from 3-year terms to annual renewals with performance-linked interchange rebates. Small and medium retailers in Mong Kok and Causeway Bay districts are switching providers based on real-time settlement speed rather than hardware subsidies. This behavioral compression is forcing acquirers to unbundle terminal leasing from transaction processing fees.
Hong Kong Payments Market Segmentation
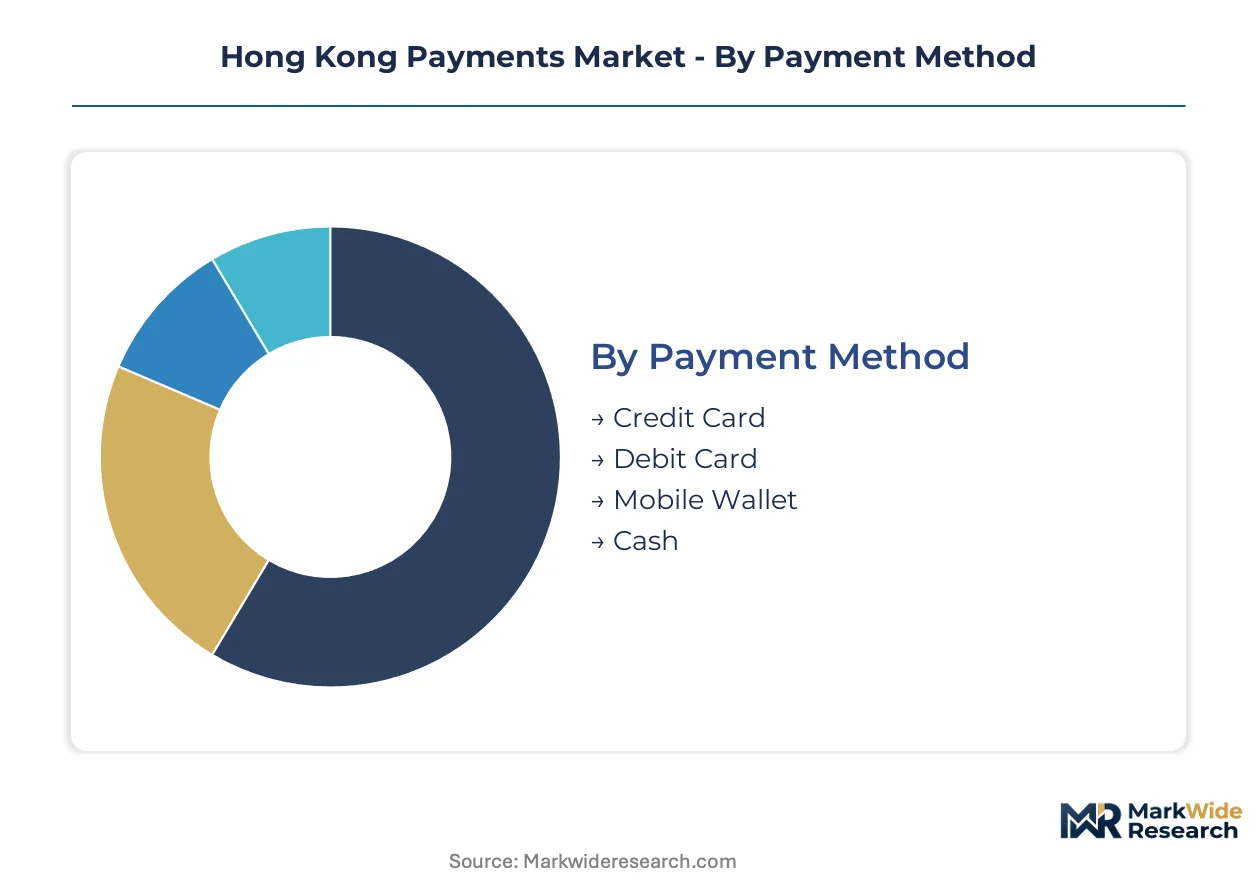
Payment method fragmentation in Hong Kong reflects divergent settlement speeds, merchant acceptance costs, and demographic adoption curves. Transaction type segmentation reveals how real-time infrastructure is compressing legacy clearing timelines. Platform architecture choices determine whether providers capture interchange revenue or cede margin to infrastructure aggregators.
Payment Method:
Mobile wallets command transaction volume leadership while credit cards retain premium-value capture.
- Credit Card:Revolving credit instruments with tiered interchange schedules ranging from 1.5% to 3.2% on merchant-present transactions. Demand concentrates among high-ticket retail in Central and Tsim Sha Tsui districts where rewards program arbitrage drives card selection. The HKMA's stored-value facility licensing framework constrains non-bank credit issuance, preserving incumbent bank dominance.
- Mobile Wallet:Stored-value facilities operating through NFC, QR code, or in-app tokenization with sub-second authorization. Octopus Card's transit-to-retail migration and AlipayHK's super-app bundling are absorbing cash displacement volume among millennials in Mong Kok and Causeway Bay corridors. This segment climbs the fastest as Faster Payment System interoperability removes friction from account funding.
- Debit Card:Direct account-linked instruments clearing through EPSCO and UnionPay networks with fixed per-transaction fees rather than percentage interchange. Demand localizes among cost-sensitive SMEs and older demographics preferring spend-limited instruments.
- Cash:Physical currency settlement concentrated in wet markets, small-value street commerce, and cross-border remittance hand-carry corridors. The HKMA's coin collection program and merchant cash-handling cost pressures are compressing viable use cases.
Today's leader: Mobile Wallet. Tomorrow's challenger: Credit Card.
Transaction Type:
Settlement finality speed separates high-margin treasury services from commoditized payment routing.
- In-Store:Merchant-present transactions through contactless terminals, QR displays, or biometric verification at physical point-of-sale. Retail density in Sham Shui Po and Wan Chai drives terminal deployment competition among acquirers. Legacy EMV chip processing retains volume leadership but real-time account-to-account rails are gaining share fastest.
- Peer-to-Peer:Account-to-account transfers through FPS, e-wallet balances, or messaging-app embedded settlement. Cross-border RMB corridors linking mainland China wallets represent the steepest expansion trajectory as HKMA interoperability trials accelerate.
- Online:Card-not-present transactions through hosted checkout pages, tokenized wallet buttons, or direct bank debits. E-commerce marketplace integration determines provider selection more than interchange pricing.
- Bill Payments:Recurring utility, telecom, and property management settlements through direct debit mandates or autopay arrangements. Low-margin volume concentrated among incumbent banks with established merchant acquiring relationships.
In-store transactions anchor current revenue pools. Peer-to-peer channels are restructuring tomorrow's competitive map.
Customer Segment:
Generational digital fluency separates super-app adopters from branch-dependent relationship holders.
- Millennials:Cohort aged 25-40 with highest mobile wallet penetration, loyalty program sensitivity, and cross-border commerce participation. Demand clusters in food delivery, ride-hailing, and subscription service payments.
- Business Owners:SME proprietors and corporate treasury managers requiring working capital optimization, multi-currency settlement, and ERP integration. B2B platform adoption concentrates in logistics and professional services verticals.
- Tourists:Transient visitors from mainland China, Southeast Asia, and Western markets with wallet interoperability and foreign exchange spread sensitivity. Spending localizes in luxury retail and hospitality corridors.
- Retail Customers:Mass-market consumers across age spectrums with heterogeneous payment preferences and low switching costs. Branch proximity and brand trust retain deposit relationships even as transaction behavior fragments.
Millennials currently dominate transaction velocity. Business owners are emerging as the highest lifetime-value cohort.
Platform Type:
Control over user interface layer determines whether providers capture data monetization or surrender margin to aggregators.
- Mobile App:Native iOS and Android applications with biometric authentication, push notification marketing, and embedded financial services. Super-app consolidation favors platforms bundling payments with commerce and social functions.
- POS System:Terminal hardware and software stacks managing in-store acceptance, inventory integration, and merchant analytics. Shortening contract terms from three years to annual renewals are compressing hardware subsidy recovery.
- Web:Browser-based checkout experiences through redirect flows, hosted fields, or embedded iframes. Conversion optimization and fraud scoring determine merchant platform selection.
- Third-Party Services:White-labeled payment processing, gateway aggregation, and orchestration layers abstracting underlying rail complexity. API-first architectures enable non-financial brands to embed financial services without licensing.
Mobile apps command current engagement metrics. Third-party services are restructuring distribution economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's payment infrastructure modernization outpaces Hong Kong in cross-border API standardization, while Hong Kong retains denser merchant acquiring coverage in transit-to-retail wallet migration.
Singapore
Corporate treasury centralization and sovereign wealth fund procurement drive payment platform adoption. The Monetary Authority of Singapore's Project Orchid CBDC trials establish programmable settlement standards. Fintech clusters in One-North and Marina Bay concentrate API-first infrastructure providers competing for ASEAN corridor flows.
South Korea
Super-app ecosystem dominance and contactless transit payment heritage accelerate mobile wallet penetration. The Financial Services Commission's open banking mandates under the MyData initiative force incumbent banks to expose transaction APIs. Seoul's Gangnam and Yeouido districts host concentrated fintech development labs partnering with Hong Kong clearing banks.
United Kingdom
Cross-border B2B settlement demand and regulatory sandbox precedents attract Hong Kong payment infrastructure investment. The Financial Conduct Authority's authorization framework for e-money institutions creates licensing pathway clarity. London's Canary Wharf and Shoreditch clusters host treasury management platforms integrating with Hong Kong Faster Payment System rails.
Australia
Real-time payment infrastructure maturity and superannuation fund scale create institutional payment service demand. The Australian Prudential Regulation Authority's restricted ADI licensing compresses neobank entry timelines. Sydney's Barangaroo and Melbourne's Docklands districts concentrate payment orchestration startups targeting Asia-Pacific corridor expansion.
United Arab Emirates
Free zone commercial licensing and Islamic finance treasury requirements attract payment infrastructure regionalization. The Central Bank of the UAE's instant payment platform (Aani) mandates interoperability standards affecting Hong Kong corridor providers. Dubai International Financial Centre clusters host payment aggregators bridging MENA and Greater Bay Area settlement flows.
Hong Kong Payments Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with licensed deposit-taking institutions commanding merchant acquiring relationships while API-native platforms capture cross-border B2B flows. The vendor base concentrates around three strategic archetypes: incumbent banks with real-time gross settlement access, transit-origin stored-value facility operators, and cloud-native treasury stack providers. Competitive moves center on Faster Payment System interoperability certification and white-label payment processing partnerships with e-commerce marketplaces.
Among Hong Kong-based deposit-taking institutions, The Hongkong and Shanghai Banking Corporation Limited, Bank of China (Hong Kong) Limited, and Standard Chartered Bank (HK) Limited occupy positions within the incumbent bank archetype, anchoring merchant acquiring networks and real-time clearing access. Octopus represents the transit-to-retail wallet extension model, while Airwallex exemplifies the cloud-native cross-border treasury platform segment. Stripe and PayPal sit within the international payment aggregator tier, leveraging global infrastructure to capture online commerce volume.
| Leading Market Players |
|---|
| The Bank of East Asia Limited |
| Airwallex |
| The Hongkong and Shanghai Banking Corporation Limited |
| Stripe |
| Octopus |
| Bank of China (Hong Kong) Limited |
| Citibank (Hong Kong) Limited |
| PayPal |
| Standard Chartered Bank (HK) Limited |
| Others |
Supply & Pricing Matrix
API-first orchestration capability divergence separates premium treasury platforms from commodity payment routers, with that capability gap manifesting in both interchange capture rates and cloud infrastructure sourcing decisions across Hong Kong clearing corridors.
Pricing Analysis
Capacity additions in Singapore and Sydney are reshaping price floors for cross-border B2B settlement services, compressing margins on legacy correspondent banking corridors. Three-tier pricing structure across premium API orchestration, standard gateway services, and economy payment routing dominates merchant acquiring contracts. Price differentiation hinges on real-time settlement speed and HKMA sandbox certification tier. Pricing pressure stems from virtual banks unbundling processing fees from hardware subsidies. SME retailers in Mong Kok and Causeway Bay exhibit highest price sensitivity, while multinational treasury departments prioritize latency over cost.
Supply Chain Analysis
Full-stack developer scarcity in Hong Kong and Shenzhen is constraining deployment velocity for embedded finance platforms. Cloud infrastructure concentrates in AWS and Azure data centers across Singapore, Hong Kong, and Tokyo. Raw material dependencies span encrypted tokenization modules, biometric authentication hardware, and regulatory compliance software layers. Single-source vulnerability runs through concentrated hyperscaler compute capacity. Distribution runs through direct API integration with enterprise ERP systems and white-label partnerships with e-commerce marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hong Kong payments operate as a late-cycle quality story where merchant demand is shifting toward sub-second settlement finality as a baseline specification rather than a premium feature.
For Market Incumbents: Extend Faster Payment System interoperability certification into white-label payment processing for virtual banks and e-commerce marketplaces. Deepen merchant acquiring relationships through real-time settlement guarantees that match cloud-native competitor speeds. Anchor defensive positioning against Airwallex and Stripe by leveraging HKMA real-time gross settlement access that non-bank platforms cannot replicate.
For New Entrants and Emerging Players: SME treasury managers in logistics and professional services verticals remain underserved by incumbent working capital solutions. Capture share through API-first treasury stacks integrating with NetSuite and SAP systems. Penetrate via embedded finance partnerships with vertical SaaS platforms rather than direct merchant acquiring competition.
For Investors and Strategic Acquirers: Consolidation pressure builds where virtual bank license holders lack proprietary payment infrastructure and must acquire technology stacks to achieve unit economics. Long-term viability favors platforms with HKMA stored-value facility licensing and cross-border RMB corridor access. Monitor e-HKD pilot program expansion as the inflection signal for programmable settlement infrastructure investment.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables non-financial brands to embed HKMA-licensed payment services without regulatory burden. |
| Cross-Border RMB Corridor Expansion | Captures remittance velocity from mainland China interoperability trials through licensed e-wallet partnerships. |
| Real-Time Settlement Infrastructure | Compresses merchant acquiring contract terms from multi-year to annual renewals based on speed performance. |
| Virtual Bank White-Label Partnership | Extends payment processing reach into deposit-taking institutions lacking proprietary technology stacks. |
| e-HKD Programmable Settlement Development | Positions infrastructure providers for atomic delivery-versus-payment in securities tokenization corridors. |
Research Methodology
Bottom-up merchant acquiring volume modeling reconciled against top-down clearing infrastructure tracking forms the analytical core. Primary interviews with payment platform CTOs, HKMA regulatory affairs leads, merchant acquiring relationship managers, and enterprise treasury directors combined with secondary validation against HKMA statistical bulletins, Faster Payment System transaction disclosures, virtual bank licensing records, and cloud hyperscaler capex filings. Triangulation across stakeholder perspectives and data sources ensures segmentation integrity.
Input-output matrices map transaction volume flows across payment method, transaction type, customer segment, and platform architecture dimensions throughout the forecast period. CAGRs derive from trend extrapolation of FPS adoption curves, mobile wallet penetration cohort analysis, and cross-border corridor velocity modeling. Industry-specific inputs include HKMA sandbox licensing timelines, virtual bank deposit growth trajectories, and Greater Bay Area interoperability trial progressions.
Inputs from HKMA regulatory disclosures and clearing infrastructure operators were available through the study window; gaps in real-time merchant-level transaction data introduce uncertainty bands around mobile wallet share estimates. Forecasts reflect assumptions regarding e-HKD pilot expansion and mainland China digital yuan interoperability timelines. Material deviation in HKMA regulatory acceleration or cross-border corridor policy shifts warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Bitcoin Payments Market
Payments
South Korea Payments Market
Payments
China Forex Cards Market
Payments
Europe Credit Cards Market
Payments
Southeast Asia POS Terminal Market
Payments
Global Virtual Cards Market
Payments
Netherlands Mobile Payments Market
Payments
Belgium POS Terminals Market
Payments
Buy Now Pay Later (BNPL) Services Market
Payments
Proximity Mobile Payment Market
Payments
Poland POS Terminal Market
Payments
Philippines Remittance Market
Payments
Mexico Digital Wallet Market
Payments
Japan Payments Market
Payments
Asia Pacific POS Terminal Market
Payments
UAE Buy Now Pay Later Services Market