
 United Kingdom Mobile Payments Market | 2026-2036
United Kingdom Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Mobile Payments Market Analytics
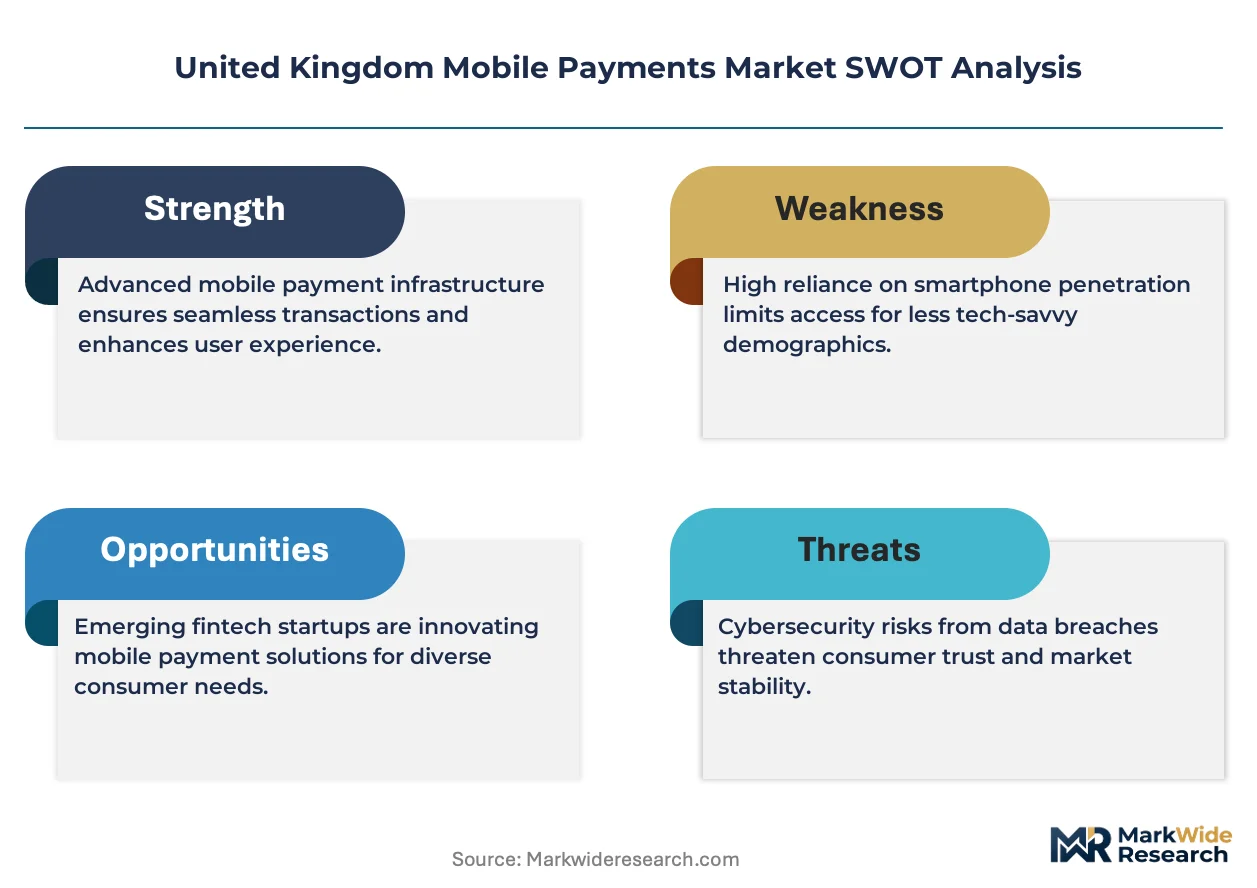
Embedded finance and banking-as-a-service arrangements are rewriting competitive entry conditions for UK mobile payment providers. Revolut Ltd leverages its multi-currency infrastructure to sustain cross-border transaction volumes. Adyen N.V. anchors enterprise merchant relationships through unified commerce platforms. Worldpay UK Limited dominates physical retail terminal integration across British grocery and hospitality chains.
United Kingdom mobile payments encompass digital fund transfers initiated through portable connected devices, typically employing near-field communication protocols, tokenized credentials, and biometric authentication layers to execute transactions under the Faster Payments Service rails. E-wallet methods capture substantial transaction flow as consumers migrate from physical card tapping to app-based authentication, while wearable device types gain traction among fitness-integrated payment experiences. Gen Z user demographics exhibit the steepest adoption curve, though high-value transaction segments retain concentrated margin pools in B2B and luxury retail channels.
The Financial Conduct Authority enforces operational resilience and customer safeguarding standards, while the Payment Systems Regulator mandates fair access and competition across UK payment infrastructure. Open banking rules from the Competition and Markets Authority require incumbent banks to share account data, directly enabling account-to-account mobile payment proliferation. Stakeholders must weigh regulatory compliance investments against the strategic imperative of embedding real-time payment capabilities into merchant software stacks.
Market Dynamics
The Faster Payments Service infrastructure is compressing transaction settlement windows from days to seconds, forcing incumbent processors to overhaul legacy batch-processing architectures or cede ground to real-time specialists.
Growth Catalysts
- PSR Access Mandates:The Payment Systems Regulator's fair access requirements are dismantling incumbent control over UK payment rails, enabling challenger providers to route transactions directly through Faster Payments infrastructure.
- Biometric Authentication Standards:Fingerprint and facial recognition protocols embedded in smartphone hardware are eliminating friction at checkout terminals across British grocery and hospitality sectors.
- London Fintech Density:Concentrated venture capital deployment around Shoreditch and Canary Wharf is accelerating pilot-to-scale timelines for contactless payment innovations.
Market Restraints
- Merchant Acquirer Concentration:Terminal hardware supply chains depend heavily on single-source chip manufacturers in East Asian fabrication facilities, creating input vulnerability.
- FCA Operational Resilience Deadlines:Mandatory business continuity investments are imposing six-figure compliance burdens on mid-tier payment service providers before revenue thresholds justify spend.
- Account-to-Account Substitution:Open banking-enabled direct bank transfers are eroding card network fee pools in recurring bill payment verticals.
Strategic Opportunities
- Manchester Professional Services Corridor:Corporate expense management platforms remain underpenetrated among mid-market legal and consulting firms outside London.
- Wearable-Fitness Convergence:Smartwatch payment credential provisioning is unlocking contactless adoption among health-conscious demographics in Edinburgh and Glasgow.
- CMA Open Banking Extensions:Scheduled data-sharing mandate expansions beyond current account scope will enable mortgage and savings product integration within payment apps.
Industry Challenges
- Legacy Core Banking Integration:Mainframe-era settlement systems at tier-two UK banks require expensive API middleware development to support real-time mobile payment clearing.
- SCA Compliance Complexity:Strong Customer Authentication rules under PSD2 implementation are triggering transaction abandonment spikes when biometric verification fails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Mobile Payments Market |
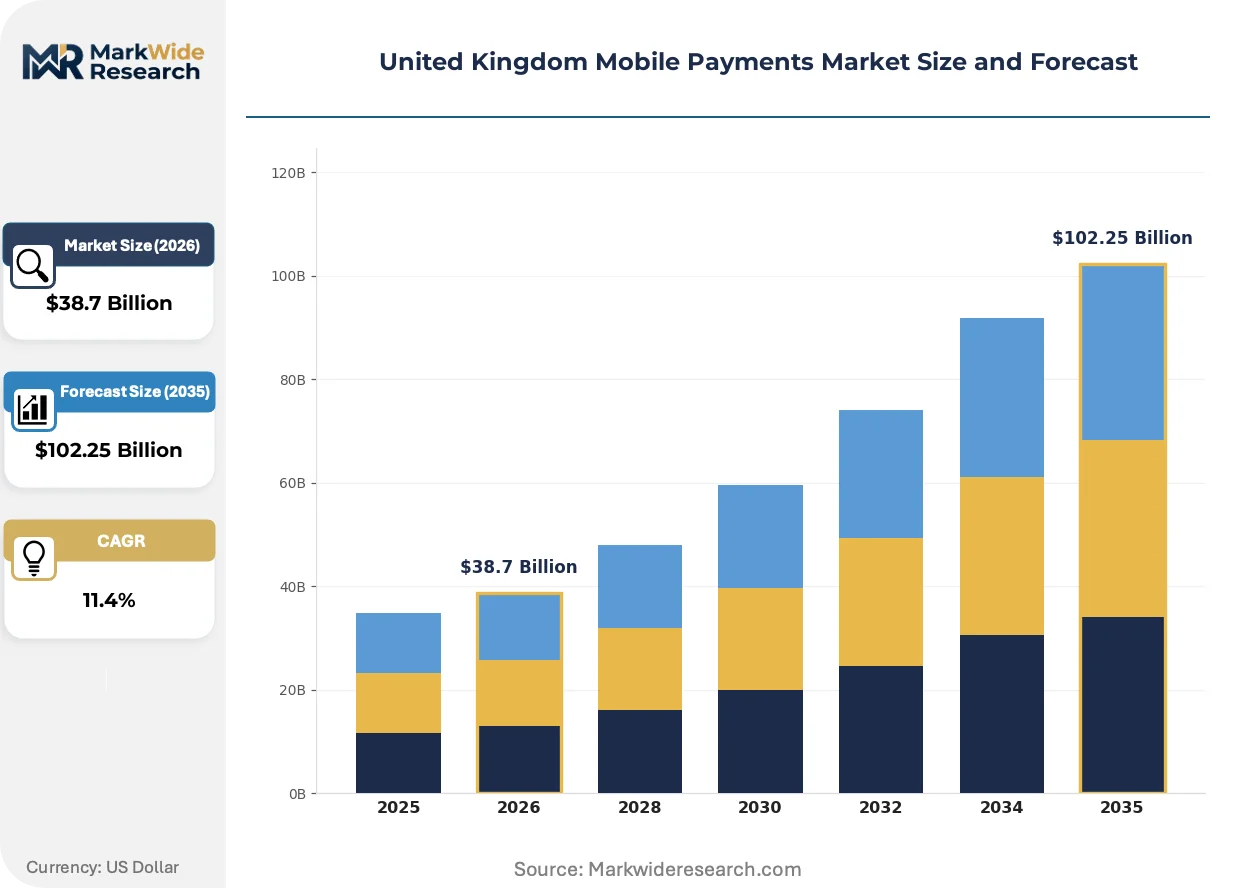
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, E-Wallet, Bank Transfer Device Type: Smartphone, Tablet, Wearable, POS Terminal User Demographic: Millennials, Gen Z, Professionals, Seniors Transaction Size: Low Value, Medium Value, High Value, Subscription |
| Companies Covered | Apple Inc, Google LLC, PayPal Holdings Inc, Samsung Electronics Co Ltd, Worldpay UK Limited, Revolut Ltd, Klarna Bank AB, Adyen N.V., SumUp Payments Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Mobile Payments Market Evolving Landscape
Tokenization architectures and embedded finance distribution models are dissolving traditional boundaries between payment acceptance, lending, and treasury services.
Host card emulation technology is collapsing the distinction between physical and virtual payment credentials. Major British supermarket chains are deploying software-based point-of-sale terminals that accept smartphone-initiated transactions without dedicated hardware. This compression is eliminating terminal manufacturer margins while accelerating merchant onboarding velocity.
The Financial Conduct Authority's consumer duty regulations are reshaping fee disclosure requirements across UK payment products. Providers must now demonstrate fair value assessments for transaction services previously buried in interchange schedules. High-frequency micro-merchant segments are responding by demanding simplified, all-inclusive pricing structures.
Subscription bundling is redefining how British consumers evaluate payment service value. Challenger banks are packaging travel insurance, cryptocurrency access, and multi-currency accounts into single monthly fees, displacing standalone payment apps. This consolidation is most visible among Gen Z professionals in London's technology and creative sectors.
United Kingdom Mobile Payments Market Segmentation
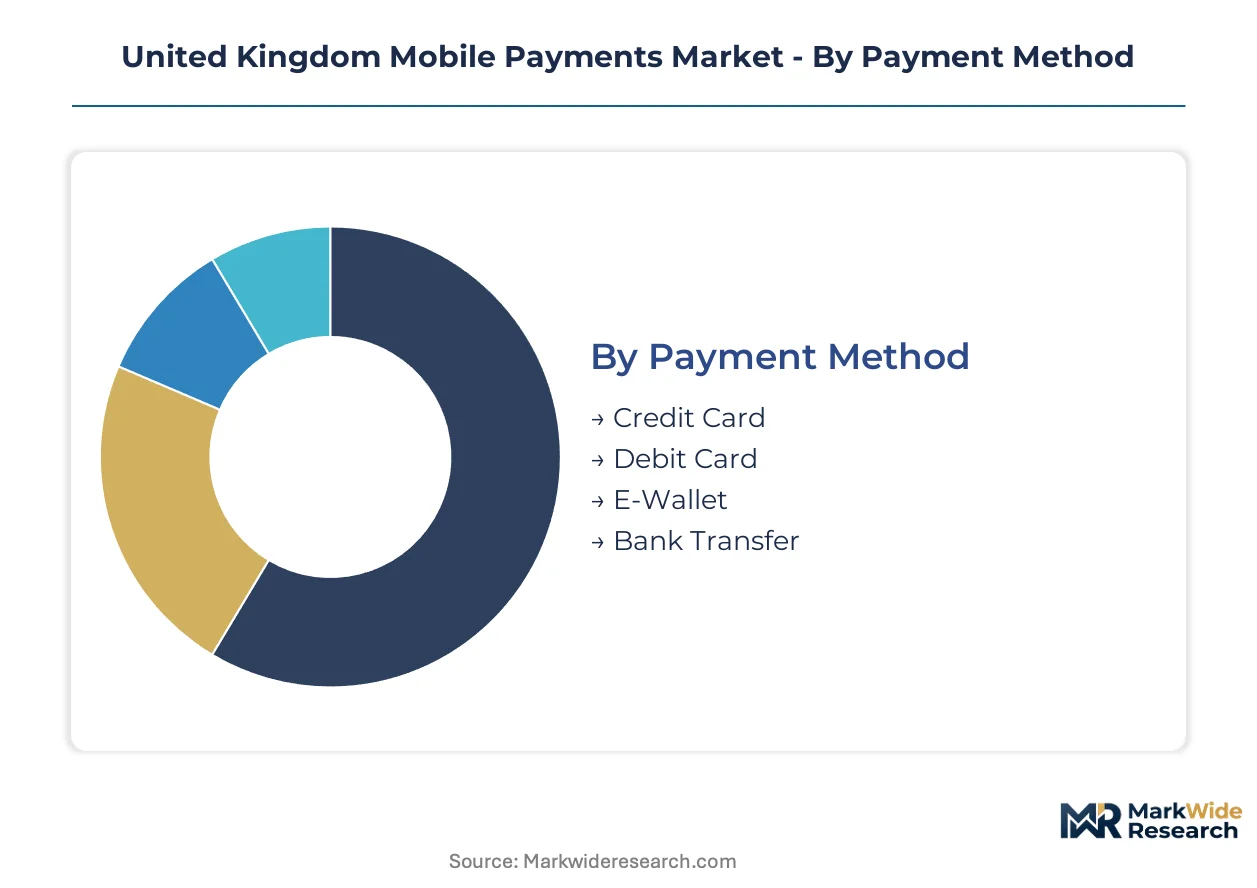
Mobile payment segmentation in the United Kingdom reveals distinct technology adoption curves across payment rails, hardware form factors, and user cohorts. Each dimension carries divergent regulatory exposure and margin profiles that shape provider strategy.
Payment Method:
Mature card-based rails dominate transaction volume while account-to-account infrastructure emerges as the disruptive layer.
- Credit Card:Revolving credit instruments tokenized within Apple Pay and Google Pay wallets sustain interchange fee economics for issuing banks. Demand concentrates among London-based professionals financing discretionary purchases, though Strong Customer Authentication friction triggers abandonment at checkout.
- Debit Card:Direct account-linked credentials capture everyday spending through Faster Payments settlement rails. British grocery chains and transport networks route the majority of contactless volume through this channel, with real-time balance verification reducing overdraft exposure.
- E-Wallet:Closed-loop stored value systems from fintech challengers bypass traditional card networks entirely.
- Bank Transfer:Open banking-enabled account-to-account payments displace card rails in recurring bill settlements.
Debit card rails handle the majority of throughput; bank transfer is expanding most quickly on share.
Device Type:
Hardware distribution reflects consumer lifestyle integration patterns from pocket to wrist to point-of-sale.
- Smartphone:Host card emulation technology transforms iOS and Android devices into universal payment terminals. Manchester and Edinburgh urban corridors exhibit near-ubiquitous adoption among working-age populations, with biometric authentication eliminating PIN entry friction.
- Wearable:Smartwatch and fitness band credential provisioning unlocks contactless acceptance during exercise and transit. Edinburgh health-conscious demographics drive adoption, with gym-integrated payment experiences gaining traction among subscription bundling providers.
- Tablet:Larger-screen devices serve merchant-facing and in-home commerce scenarios.
- POS Terminal:Software-based terminals eliminate dedicated hardware requirements for micro-merchants.
Smartphone deployment saturates urban Britain; wearable credentialing climbs the fastest among form factors.
User Demographic:
Generational digital fluency creates tiered adoption velocities across age and professional strata.
- Gen Z:Native digital payment users exhibit steepest adoption curves for cryptocurrency-integrated wallets and social commerce checkout. London technology and creative sectors concentrate demand, with subscription bundling displacing standalone payment apps.
- Millennials:Established fintech users balance convenience with credit optimization across multiple payment rails.
- Professionals:Corporate expense management requirements concentrate among legal and consulting firms in Manchester and Birmingham corridors.
- Seniors:Simplified interface demands and fraud sensitivity shape product design for aging populations.
Millennials anchor current revenue pools; Gen Z wallet provisioning gains share fastest across cohorts.
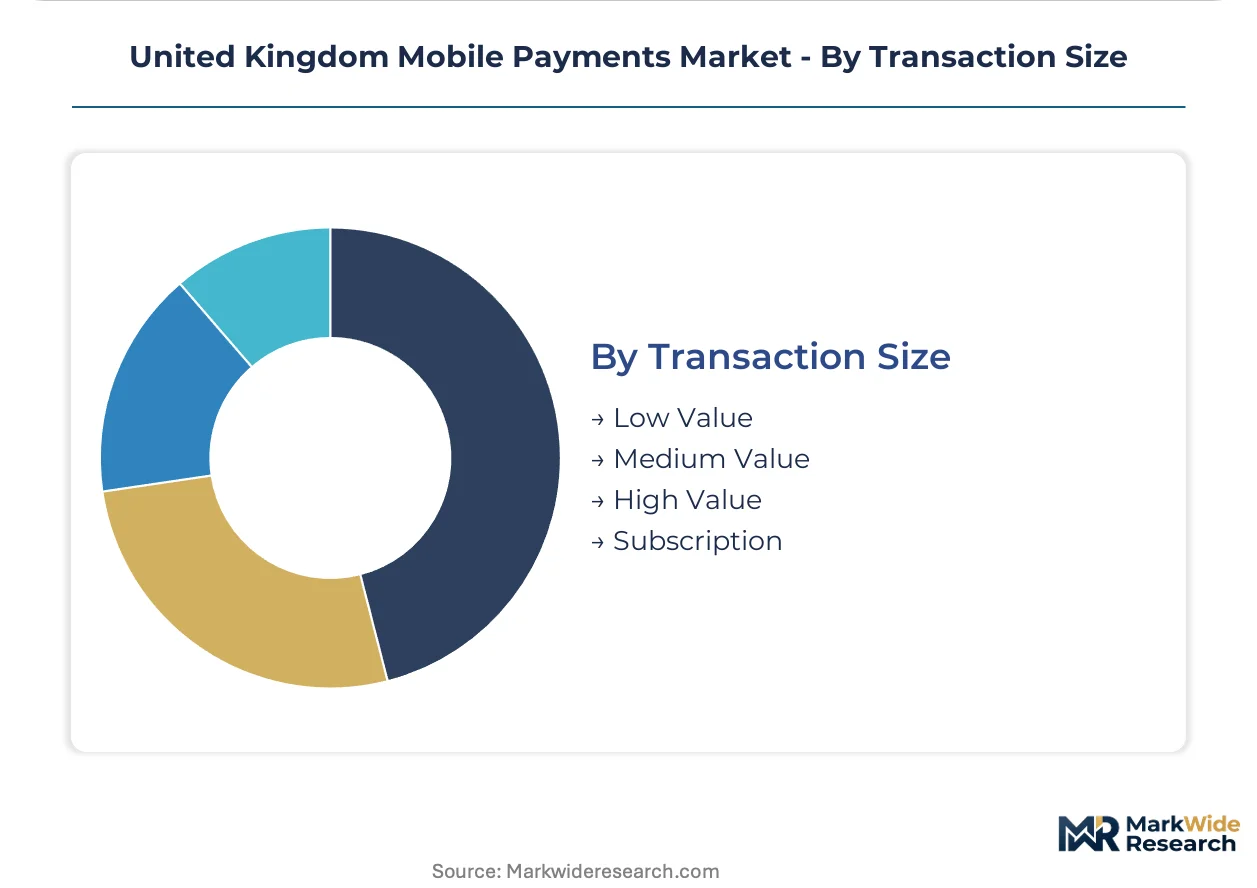
Transaction Size:
Value thresholds determine settlement infrastructure, authentication intensity, and provider margin capture.
- High Value:Luxury retail and B2B corridors concentrate margin pools despite lower frequency. London premium merchants deploy enhanced verification protocols, with biometric layering satisfying Financial Conduct Authority safeguarding requirements.
- Subscription:Recurring revenue models reshape provider economics through predictable interchange streams. British utility and media services migrate from direct debit to tokenized card-on-file arrangements, reducing churn through seamless credential updates.
- Low Value:Micropayment aggregation enables contactless acceptance below traditional interchange floors.
- Medium Value:Everyday commerce spans grocery, hospitality, and transport verticals.
Medium value transactions carry the majority of throughput; subscription billing demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom mobile payments sector operates as a net importer of terminal hardware and semiconductor components, while exporting fintech software architecture and regulatory frameworks to Commonwealth and European markets. London's position as a clearing hub generates substantial cross-border transaction fee flows, offsetting hardware procurement deficits from East Asian supply chains.
London and the Southeast
Shoreditch fintech clusters and Canary Wharf banking headquarters concentrate venture deployment for contactless innovation. The Financial Conduct Authority's consumer duty regulations mandate enhanced fee transparency across payment products. Revolut Ltd and Adyen N.V. anchor development pipelines here, scaling real-time payment infrastructure for European merchant networks.
Midlands
Birmingham corporate corridors drive expense management platform demand among mid-market professional services firms. The Payment Systems Regulator's fair access mandates enable challenger providers to route directly through Faster Payments rails. Worldpay UK Limited maintains terminal integration partnerships with grocery and hospitality chains across the West Midlands conurbation.
North England
Manchester's legal and consulting sectors exhibit underpenetrated corporate payment automation relative to London benchmarks. Open banking rules from the Competition and Markets Authority require incumbent data sharing that benefits regional fintech entrants. SumUp Payments Limited targets micro-merchant acquisition in Greater Manchester's retail and food service verticals.
Scotland
Edinburgh and Glasgow health-conscious demographics accelerate wearable payment credential adoption through fitness-integrated experiences. The FCA's operational resilience deadlines impose compliance investments on Edinburgh-based payment service providers. Klarna Bank AB pursues buy-now-pay-later wallet penetration among Scottish subscription bundling consumers.
Wales and Northern Ireland
Cardiff and Belfast urban centers lag national contactless penetration rates, presenting greenfield merchant onboarding opportunities. Strong Customer Authentication rules under PSD2 implementation create transaction friction that local providers must engineer around. Google LLC and Apple Inc deploy smartphone host card emulation to capture late-adopter segments in these markets.
United Kingdom Mobile Payments Market Competitive Landscape
On the supply side, the industry is bifurcated between consolidated card network incumbents and fragmented fintech challengers, with middleware processors occupying a contested middle tier. Three strategic archetypes dominate: technology platform licensors, merchant acquirer-integrators, and neobank wallet operators. Competitive intensity manifests through API partnership ecosystems and real-time settlement capability races rather than price-based rivalry alone.
Within the technology platform tier, Apple Inc and Google LLC exemplify hardware-software integration strategies that collapse payment credential distribution into operating system defaults. Samsung Electronics Co Ltd occupies a position bridging device manufacture and financial services licensing. Among merchant-facing specialists, PayPal Holdings Inc and Worldpay UK Limited anchor alternative archetypes—digital wallet origination versus physical terminal dominance—while Revolut Ltd represents the neobank vector bundling multi-currency infrastructure with payment initiation.
| Leading Market Players |
|---|
| Apple Inc |
| Google LLC |
| PayPal Holdings Inc |
| Samsung Electronics Co Ltd |
| Worldpay UK Limited |
| Revolut Ltd |
| Klarna Bank AB |
| Adyen N.V. |
| SumUp Payments Limited |
| Others |
Value Network & Pricing Analysis
East Asian semiconductor fabrication concentration determines both terminal hardware cost tier spreads and UK payment provider procurement vulnerability. Single-source chip dependencies force British acquirers to absorb input volatility through premium-economy pricing stratification across merchant segments.
Pricing Analysis
Enterprise merchant acquirers anchor pricing structures through subscription-tiered SaaS arrangements bundled with terminal hardware leases. Three-tier pricing structure across premium API-integrated, standard turnkey, and economy self-serve levels differentiates by customization depth and settlement speed guarantees. Pricing pressure stems from open banking-enabled account-to-account rails eroding interchange-dependent card economics. Micro-merchants in Greater Manchester and Cardiff exhibit highest price sensitivity, while London premium retailers prioritize real-time settlement over rate minimization.
Supply Chain Analysis
Upstream secure element and NFC controller fabrication feeds from Taiwan, South Korea, and mainland Chinese foundries. Semiconductor wafers, EMV-certified chip modules, and terminal-grade biometric sensors constitute critical input dependencies. Single-source vulnerability concentrates in advanced node secure microcontrollers from TSMC-affiliated packaging facilities. Distribution runs through tier-one terminal OEMs—Ingenico and Verifone European hubs—into Worldpay UK Limited and Adyen N.V. merchant integration pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom mobile payments sector sits at a regulatory inflection where Faster Payments infrastructure and open banking mandates are compressing incumbent processor margins while enabling challenger real-time settlement models.
For Market Incumbents: Entrench core banking relationships through API middleware investments that bridge legacy mainframe settlement systems to real-time rails. Prioritize certification for Financial Conduct Authority operational resilience deadlines ahead of challenger compliance gaps. Defensive consolidation around Faster Payments direct access licenses protects against Payment Systems Regulator-mandated rail disintermediation. For New Entrants and Emerging Players: Build out wearable-fitness credential provisioning capabilities targeting Edinburgh and Glasgow health-conscious demographics where penetration lags London benchmarks. White-space concentration sits in Manchester corporate expense management platforms for mid-market legal and consulting firms. Go-to-market leverage rests on subscription bundling that displaces standalone payment apps through travel insurance and multi-currency account packaging. For Investors and Strategic Acquirers: The market sits at a infrastructure consolidation phase that favors middleware processors with Faster Payments direct access and open banking API portfolios. Long-term viability over the next decade hinges on real-time settlement capability rather than card network dependency. Monitor Competition and Markets Authority data-sharing mandate expansions beyond current accounts as signal for mortgage and savings product integration inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Faster Payments Direct Access License | Eliminates intermediary processor fees for challengers routing through UK settlement rails. |
| Open Banking API Platform Integration | Enables account-to-account payment initiation that bypasses card network economics entirely. |
| Biometric Authentication Certification | Satisfies Financial Conduct Authority Strong Customer Authentication mandates reducing abandonment. |
| Wearable Credential Provisioning Partnership | Captures Edinburgh and Glasgow fitness-integrated payment adoption ahead of saturation. |
| Merchant Software Stack Embedding | Locks in recurring revenue through unified commerce platform consolidation at Adyen N.V. scale. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Financial Conduct Authority authorization registers, Payment Systems Regulator market reviews, and Competition and Markets Authority open banking implementation reports. Primary interviews engaged payment service provider executives, merchant acquirer technology leads, retail chain procurement directors, and fintech platform engineers. Secondary validation drew from Faster Payments Service volume disclosures, UK Finance consumer payment surveys, and SEC filings of listed payment processors. Bottom-up transaction volume modeling triangulates against top-down GDP-attributed payment flow estimates.
Forecast inputs incorporate payment method migration curves, device type adoption velocities, and regulatory compliance cost burdens across the projection horizon. Segmentation dimensions span payment rails, hardware form factors, user demographics, and transaction value tiers. CAGRs derive from regression analysis against Faster Payments infrastructure expansion timelines and open banking account-to-account share capture trajectories. Industry-specific inputs include Payment Systems Regulator access mandate implementation pace and Financial Conduct Authority consumer duty enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by neobank wallet operators or Big Tech platform entrants would shift outcomes beyond modeled ranges. Cross-checking against UK Finance annual payment market reports and Bank of England payment system oversight assessments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
Saudi Arabia Buy Now Pay Later Services Market
Payments
Japan Retail Cash Management Market
Payments
US Virtual Cards Market
Payments
China Forex Cards Market
Payments
Retail POS Terminals Market
Payments
Japan Mobile Payments Market
Payments
Nigeria Mobile Money Market
Payments
Cross-Border Payment Platform Market
Payments
United Arab Emirates Payment Market
Payments
United Kingdom Real Time Payments Market
Payments
Payment Processing Solutions Market
Payments
Global Digital Wallets Market
Payments
Spain Real Time Payments Market
Payments
Global Gift Card Market
Payments
Asia-Pacific Digital Remittance Market