
 Vehicle Toll Collection and Access System Market | 2026-2036
Vehicle Toll Collection and Access System Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Toll Collection and Access System Market Analytics
Project finance and availability-based concession structures is tilting competitive dynamics toward firms with balance-sheet capacity for long-term infrastructure commitments. Kapsch TrafficCom AG leverages its integrated systems pedigree across European and North American deployments. Siemens anchors its position through captive manufacturing of roadside units and back-office platforms. TransCore competes aggressively on U.S. federal and state procurement contracts.
Vehicle toll collection and access systems comprise roadside sensors, onboard transponders, and centralized clearing software that process vehicle identification and payment without traffic interruption, typically achieving read rates above 99 percent in multi-lane free-flow configurations. RFID and ANPR technologies lead current installed bases, while DSRC and mobile payment segments are expanding fastest as jurisdictions phase out cash collection. Cloud-based and hybrid deployments are capturing margin pools from legacy on-premises installations as operators seek operational flexibility.
The U.S. Federal Highway Administration, the European Union's F-Gas Regulation for roadside equipment climate compliance, and India's Ministry of Road Transport and Highways each shape equipment standards and procurement eligibility across their respective jurisdictions. Compliance with CE marking and local spectrum allocation rules determines market access for transponder and reader manufacturers. Stakeholders must monitor evolving interoperability mandates between state and national toll networks as fragmentation in payment protocols creates both risk and partnership opportunity.
Market Dynamics
Open-road tolling mandates from the Federal Highway Administration and parallel agencies in Germany and Japan are dismantling legacy plaza infrastructure. This regulatory convergence is compressing deployment timelines and forcing capital reallocation toward free-flow architectures.
Growth Catalysts
- Urban Congestion Charging Pilots:Cities in the United States, China, and India are operationalizing zone-based pricing schemes that require interoperable back-office platforms and multi-lane detection systems.
- F-Gas Regulation:The European Union's climate compliance rules for roadside equipment are accelerating replacement cycles of legacy refrigeration-dependent tolling hardware.
- DSRC Spectrum Allocation:Dedicated short-range communications protocols are securing dedicated frequency bands in multiple jurisdictions, enabling vehicle-to-infrastructure payment authentication without transponder dependency.
Market Restraints
- Silicon Supply Concentration:Semiconductor fabrication for RFID readers and onboard units remains concentrated in East Asian foundries, exposing deployment schedules to geopolitical disruption.
- Interoperability Fragmentation:The absence of unified transponder standards across state and national borders forces operators to maintain redundant clearing systems.
- Copper and Rare Earth Volatility:Antenna arrays and magnetic loop detectors depend on commodity inputs subject to extraction licensing constraints.
Strategic Opportunities
- Mobile Payment Convergence:Smartphone-based tolling applications are penetrating markets where transponder distribution infrastructure remains underdeveloped, particularly in India.
- Cloud-Native Clearing Platforms:Hybrid deployments are capturing margin pools from on-premises installations as operators seek operational flexibility without full capital displacement.
- CE Marking Alignment:Equipment manufacturers achieving harmonized certification across EU member states are securing preferential procurement eligibility in adjacent North African deployments.
Industry Challenges
- Legacy System Integration:Plaza-based cash collection infrastructure must operate in parallel with free-flow installations during transition periods, doubling maintenance overhead.
- RF Engineering Talent Scarcity:Spectrum optimization and antenna design expertise required for multi-lane read-rate performance commands premium compensation in constrained labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Toll Collection and Access System Market |
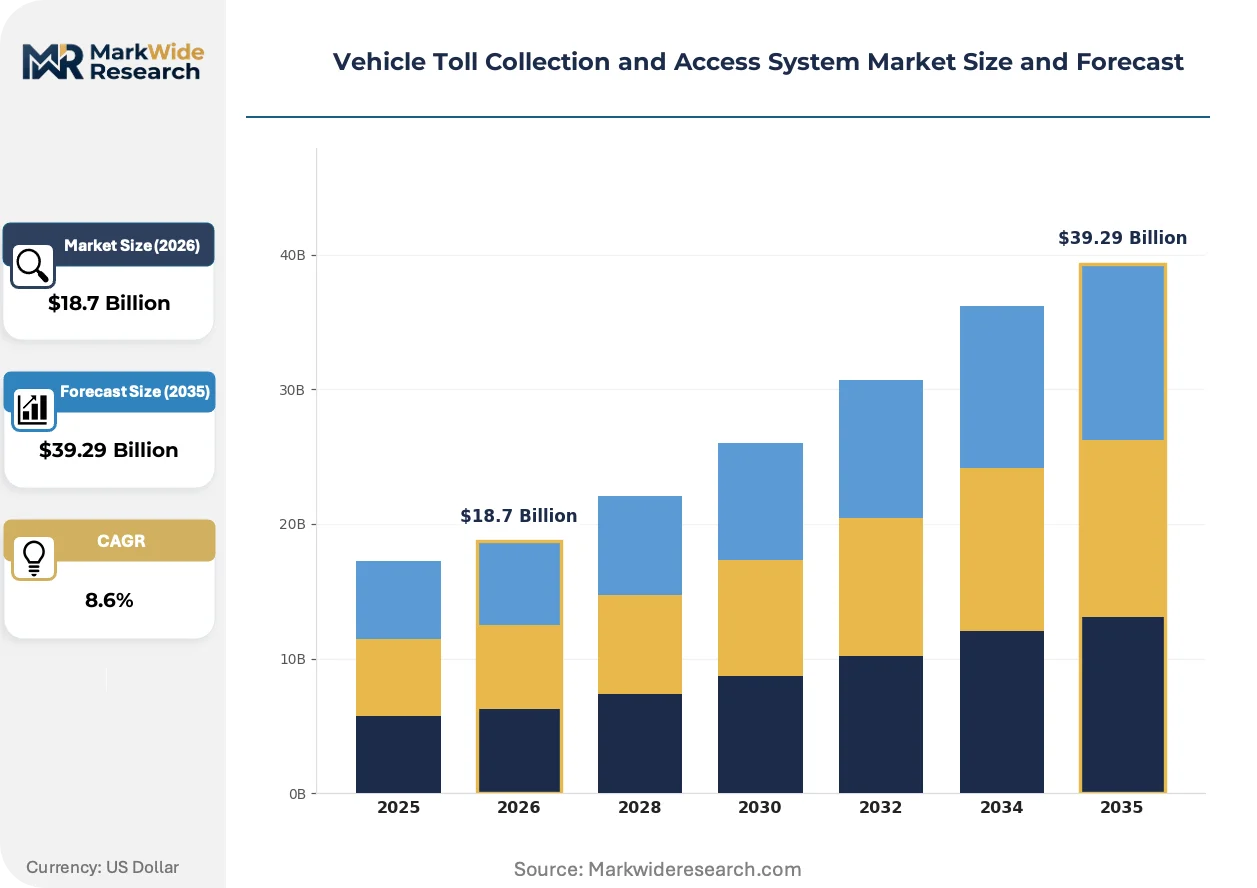
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: ANPR, RFID, DSRC, Mobile Payment Deployment: On-premises, Cloud-based, Hybrid, Edge Computing End User: Government Agencies, Private Operators, Toll Road Authorities, Fleet Operators Application: Urban Tolling, Highway Tolls, Congestion Charging, Access Control |
| Companies Covered | Kapsch TrafficCom AG, Conduent, Thales, Siemens, TransCore, Verra Mobility, Cubic Transportation Systems, EFKON, Q-Free, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Toll Collection and Access System Market Evolving Landscape
Technology trajectories in vehicle toll collection are compressing hardware replacement cycles while expanding software-defined functionality. Three developments are restructuring competitive positioning.
Multi-protocol roadside units capable of simultaneous RFID, DSRC, and ANPR detection are collapsing the distinction between transponder-dependent and camera-only tolling architectures. State departments of transportation in the United States are specifying these hybrid readers for new procurements, eliminating the need for parallel infrastructure lanes and reducing right-of-way requirements.
The European Union's F-Gas Regulation is mandating climate-compliant refrigerants and sealed cooling systems in roadside equipment enclosures. Manufacturers are redesigning thermal management subsystems to maintain processor performance in ambient temperature extremes without legacy compressor-based cooling. This compliance burden falls most heavily on suppliers of gantry-mounted equipment in Southern European deployments.
Fleet operators are consolidating toll account management through third-party logistics platforms that aggregate payments across multiple jurisdictions. These intermediaries are disintermediating direct relationships between vehicle owners and toll authorities, capturing transaction data and negotiating volume discounts. This consolidation is most advanced in long-haul trucking corridors spanning the United States interstate system.
Vehicle Toll Collection and Access System Market Segmentation
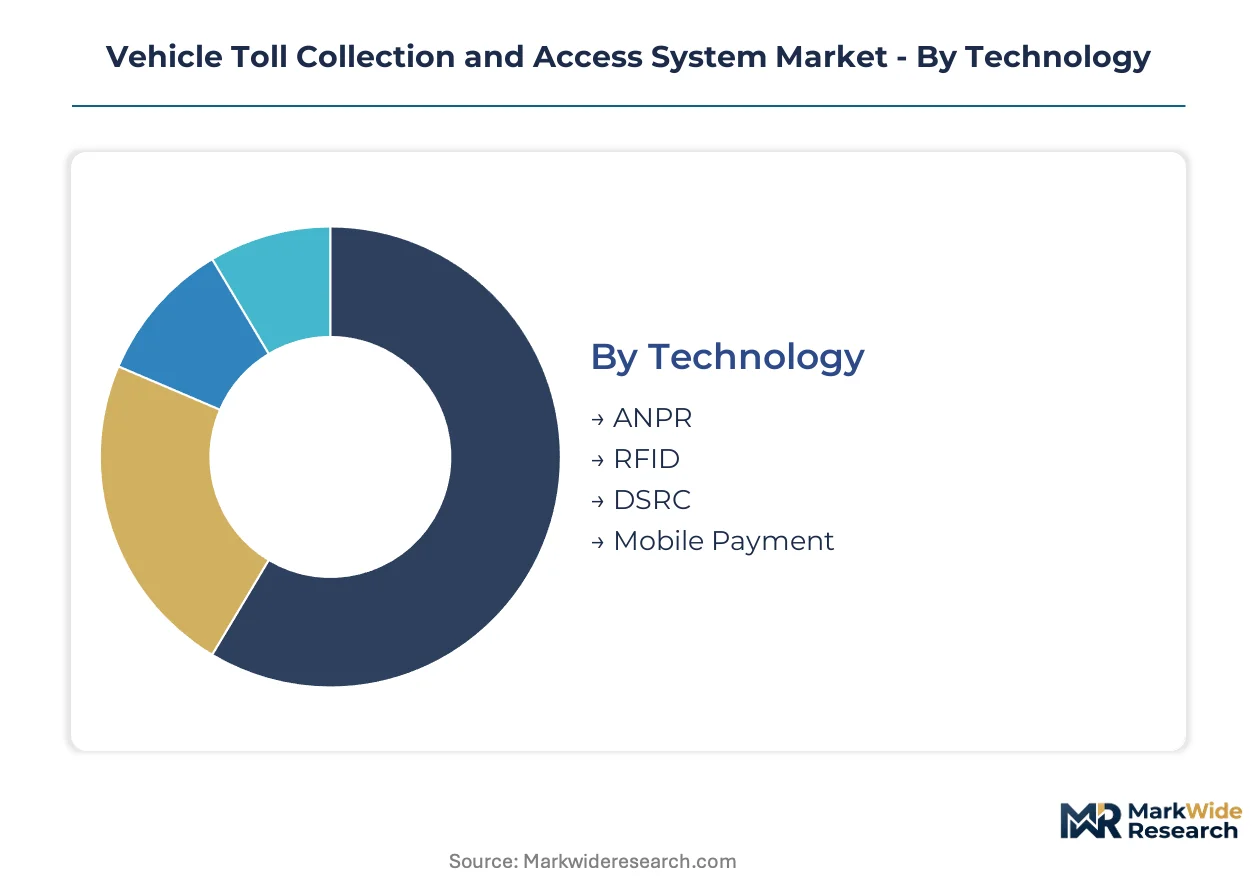
Segmentation in vehicle toll collection reveals divergent replacement cycles across hardware and software layers. Technology choices determine infrastructure longevity while deployment models reshape capital allocation between upfront investment and recurring operational expenditure.
Technology:
RFID and ANPR systems operate on decade-long refresh cycles tied to roadside hardware depreciation, whereas DSRC and mobile payment platforms iterate faster through software updates and smartphone penetration curves.
- ANPR:Camera-based optical character recognition systems capture license plates at highway speeds without vehicle-mounted equipment. Demand concentrates in Germany and the United Kingdom where retrofitting legacy plazas with camera gantries avoids transponder distribution logistics. The F-Gas Regulation is accelerating enclosure redesigns for thermal management in Southern European deployments.
- RFID:Dedicated short-range transponder systems achieve 99 percent read rates in multi-lane free-flow configurations through windshield-mounted tags. United States state departments of transportation specify RFID for interstate compatibility, though India's Ministry of Road Transport and Highways is piloting hybrid RFID-mobile architectures to bypass transponder infrastructure gaps in rural corridors.
- DSRC:Vehicle-to-infrastructure protocols enable direct authentication without physical transponders through dedicated 5.9 GHz spectrum allocation.
- Mobile Payment:Smartphone-based tolling applications leverage existing cellular networks and GPS geofencing for zone-based charging.
RFID anchors the volume base while mobile payment gains share at the steepest rate.
Deployment:
Cost tier stratification separates capital-intensive on-premises installations from subscription-model cloud services, with hybrid architectures capturing mid-tier budgets seeking staged migration paths.
- On-premises:Legacy server installations within toll authority data centers require dedicated IT staffing and five-to-seven-year hardware depreciation schedules. Toll road authorities in Japan maintain on-premises clearing platforms for transaction sovereignty, though earthquake resilience requirements are driving redundant site investments.
- Cloud-based:Fully managed SaaS platforms eliminate capital expenditure for compute infrastructure while exposing operators to recurring subscription costs. Fleet operators across United States interstate corridors are consolidating onto cloud-native platforms to unify multi-jurisdiction account management.
- Hybrid:Split architectures process time-sensitive detection at the edge while delegating payment clearing to remote data centers.
- Edge Computing:Distributed processing units embedded within roadside gantries enable sub-100-millisecond transaction completion for congestion charging enforcement.
On-premises deployments retain the largest installed base though hybrid configurations are expanding most quickly as operators balance control requirements against flexibility demands.
End User:
Procurement patterns diverge sharply between public-sector budget cycles and private operator return-on-equity timelines, with fleet intermediaries introducing aggregated purchasing power.
- Government Agencies:Federal and state transportation departments operate on multi-year appropriations with stringent competitive bidding requirements. The U.S. Federal Highway Administration mandates interoperability standards that constrain vendor selection for state-level deployments.
- Private Operators:Concession-based toll road companies prioritize availability-based revenue models with 25-30 year contract horizons. European private operators are specifying climate-compliant equipment to preempt F-Gas Regulation enforcement actions.
- Toll Road Authorities:Special-purpose government entities with dedicated revenue streams balance public accountability against operational autonomy.
- Fleet Operators:Trucking and logistics companies managing thousands of vehicles are consolidating toll account administration through third-party platforms.
Government agencies dominate procurement volume while fleet operators are driving the steepest expansion in integrated account management services.
Application:
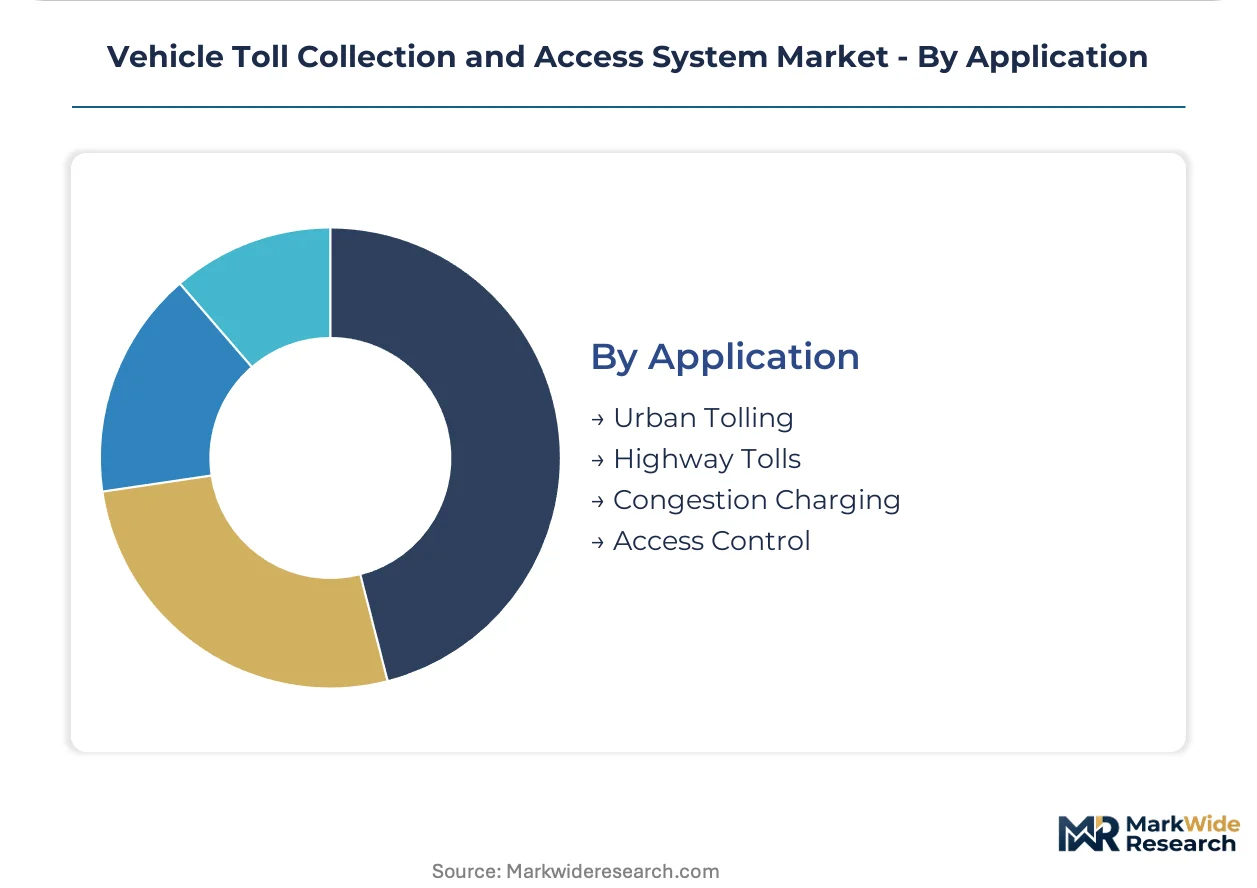
Geographic deployment density varies dramatically between sparse highway corridors and concentrated urban zones, with congestion charging requiring the most intensive infrastructure per lane-kilometer.
- Urban Tolling:City-center cordon schemes demand dense gantry networks with sub-second vehicle identification for zone entry enforcement. Singapore's Land Transport Authority operates the most mature urban system, while pilot programs in New York City and Milan are scaling camera-only architectures to avoid transponder penetration gaps.
- Highway Tolls:Intercity corridor charging spans hundreds of kilometers with widely spaced detection points. China's Ministry of Transport completed national highway ETC network integration, achieving province-to-province interoperability through standardized OBU specifications.
- Congestion Charging:Time-of-day pricing schemes require real-time traffic state monitoring integrated with payment authentication.
- Access Control:Campus and facility entry systems repurpose tolling hardware for parking and security applications.
Highway tolls anchor the revenue base while congestion charging is climbing the fastest as metropolitan air quality mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal mandates for open-road tolling architectures are compressing deployment timelines across multiple jurisdictions. The United States, China, and India concentrate demand through congestion charging pilots and national highway integration programs. Regulatory fragmentation in transponder standards continues to shape procurement eligibility and vendor selection.
United States
State departments of transportation specify multi-protocol roadside units for interstate compatibility. The Federal Highway Administration mandates interoperability standards that constrain vendor selection. California and New York Metro lead urban congestion charging pilots requiring dense gantry networks.
China
The Ministry of Transport completed national highway ETC network integration achieving province-to-province interoperability. Standardized OBU specifications govern equipment procurement across 29 provincial jurisdictions. Yangtze River Delta and Pearl River Delta clusters concentrate manufacturing capacity for roadside units.
Germany
Camera-based ANPR systems dominate retrofitting of legacy plazas to avoid transponder distribution logistics. The F-Gas Regulation accelerates replacement cycles for climate-compliant roadside equipment. Bavaria and Baden-Württemberg host deployment corridors for multi-lane free-flow configurations.
India
The Ministry of Road Transport and Highways pilots hybrid RFID-mobile architectures bypassing transponder infrastructure gaps. PLI scheme incentives support domestic manufacturing of onboard units. Maharashtra and Gujarat concentrate deployment along the Delhi-Mumbai Industrial Corridor.
Japan
Earthquake resilience requirements drive redundant site investments for on-premises clearing platforms. METI oversees spectrum allocation for DSRC vehicle-to-infrastructure protocols. Kanto and Kansai regions anchor the national ETC network with standardized back-office specifications.
Vehicle Toll Collection and Access System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. The vendor base organizes around three strategic archetypes: integrated systems providers with captive manufacturing, federal procurement specialists, and cloud-native platform operators. Consolidation pressure favors firms with balance-sheet capacity for 25-30 year concession commitments. Dominant competitive moves include strategic partnerships for interoperability certification and portfolio diversification into congestion charging software.
Among European-integrated systems providers, Kapsch TrafficCom AG and Siemens occupy positions spanning roadside hardware and back-office platforms. TransCore exemplifies the federal procurement specialist archetype competing aggressively on U.S. state and federal contracts. These three firms represent contrasting approaches to long-term infrastructure commitment and technology integration depth.
| Leading Market Players |
|---|
| Kapsch TrafficCom AG |
| Conduent |
| Thales |
| Siemens |
| TransCore |
| Verra Mobility |
| Cubic Transportation Systems |
| EFKON |
| Q-Free |
| Others |
Value Network & Pricing Analysis
East Asian semiconductor foundries anchor RFID reader and onboard unit production, concentrating margin capture in transponder assembly and back-office software layers where European and North American vendors retain pricing leverage. This upstream concentration forces downstream operators into long-term supply agreements that lock in component costs while cloud-native platform providers extract recurring revenue through subscription models.
Pricing Analysis
Certification level creates the primary spread between CE-marked European equipment and uncertified alternatives in emerging deployments. Three-tier pricing structure across premium, standard, and economy levels reflects thermal management complexity and interoperability testing depth. Cost compression in mid-tier roadside units is intensifying because F-Gas Regulation compliance adds enclosure redesign expenses. Government agencies exhibit highest price sensitivity due to competitive bidding mandates, while private concession operators prioritize availability guarantees over unit economics.
Supply Chain Analysis
Foundry capacity at Taiwan Semiconductor Manufacturing and Samsung Electronics feeds processor demand for multi-protocol roadside units. Antenna arrays draw from copper suppliers in Chile and rare earth processors in China, while gantry steel fabrication centers on South Korean and German metalworking clusters. Single-source vulnerability in DSRC chipset supply threatens deployment timelines for jurisdictions mandating vehicle-to-infrastructure protocols. Distribution runs through systems integrators who bundle hardware procurement with installation and maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
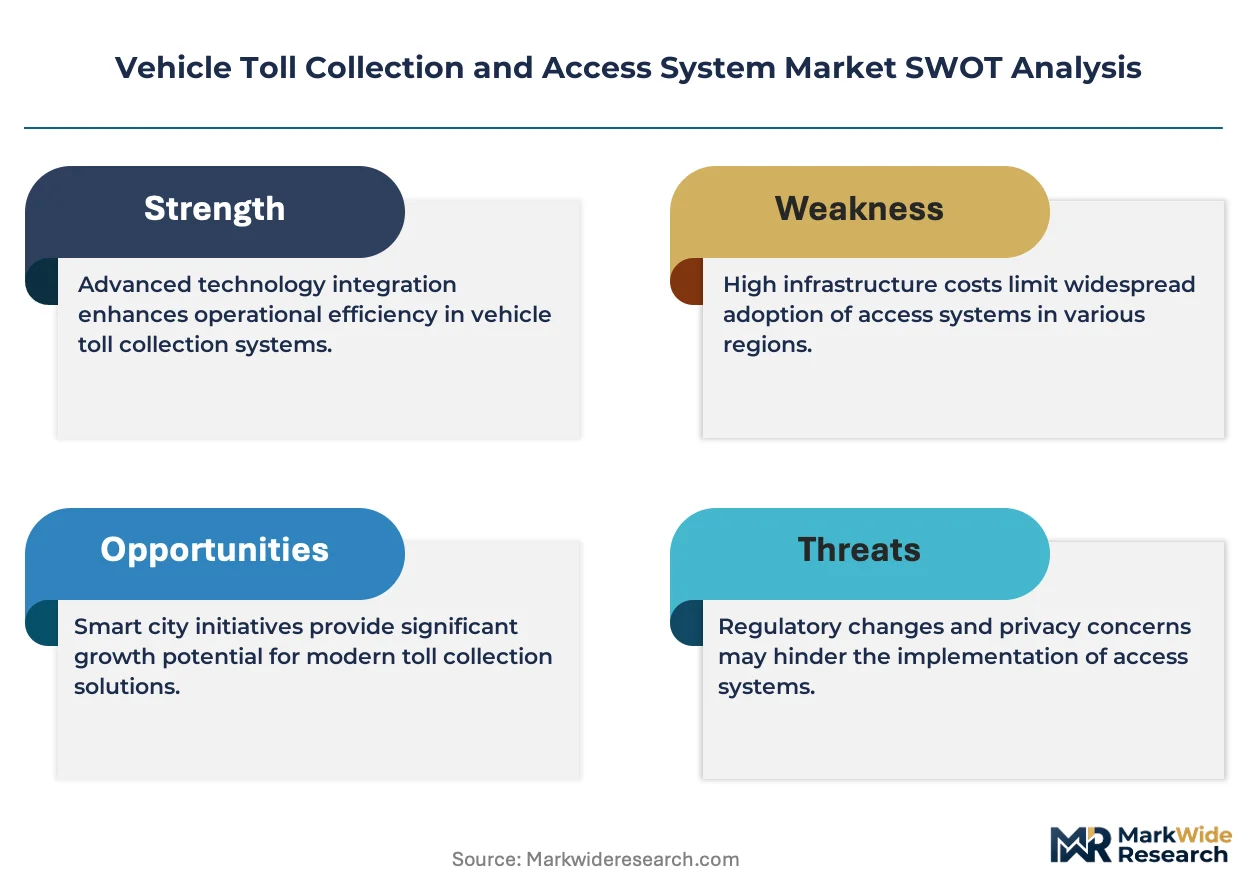
The vehicle toll collection market exhibits defensive moat characteristics through regulatory entrenchment, as Federal Highway Administration interoperability mandates and EU F-Gas compliance create certification barriers that compound over concession lifecycles.
For Market Incumbents: Harden market position through captive manufacturing of climate-compliant roadside enclosures and exclusive partnerships with state departments of transportation for multi-protocol reader certification. Cloud-native platform entrants threaten back-office margin pools; vertical integration into edge computing hardware preserves control over transaction latency performance. Kapsch TrafficCom and Siemens demonstrate this model through integrated thermal management and clearing software stacks. For New Entrants and Emerging Players: Mid-tier toll authorities in India and Southeast Asia represent the most penetrable entry point, where transponder infrastructure gaps favor mobile payment architectures over RFID-heavy incumbent solutions. Smartphone-based tolling applications bypass capital-intensive gantry deployment while capturing fleet operator account consolidation demand. Partner with domestic manufacturing incentives under India's PLI scheme to neutralize cost disadvantages against established European suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed toll road concessionaires holding 25-30 year availability contracts with embedded equipment refresh obligations. Five-to-ten year viability hinges on conversion from plaza-based to free-flow architectures without revenue interruption. Monitor DSRC spectrum allocation decisions by METI and the FCC as inflection indicators for transponder-obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Reader Certification | Federal Highway Administration interoperability mandates lock in vendor eligibility for state procurement contracts. |
| Climate-Compliant Enclosure Redesign | F-Gas Regulation compliance secures preferential positioning in Southern European and North African deployments. |
| Cloud-Native Clearing Platform Migration | Fleet operator account consolidation shifts margin pools from capital expenditure to recurring SaaS revenue. |
| Mobile Payment Architecture Development | Smartphone-based tolling penetrates markets where transponder distribution infrastructure remains underdeveloped. |
| DSRC Spectrum Allocation Securement | Dedicated 5.9 GHz band access enables vehicle-to-infrastructure authentication without physical transponder dependency. |
Research Methodology
Operator-level perspectives from toll authority procurement directors, fleet logistics managers, roadside systems engineers, and back-office platform architects anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through Federal Highway Administration procurement databases, EU F-Gas Regulation implementation reports, and national ETC network interoperability specifications. Bottom-up equipment deployment counts triangulated against top-down infrastructure investment flows from transportation ministry budget disclosures.
Scenario-bracketing framed low, base, and high cases across the projection horizon based on congestion charging pilot adoption velocity and DSRC spectrum allocation timing. Segmentation dimensions modeled include technology protocol, deployment architecture, end-user procurement type, and application density. CAGRs derived from equipment refresh cycle analysis and software penetration curves, with inputs from gantry installation rates and transponder shipment data.
Practitioners should monitor silicon supply disruption indicators and interoperability mandate acceleration for early signals of forecast revision. Quarterly review of foundry utilization rates and state-level procurement award timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Bulgaria POS Terminals Market
Payments
India Forex Cards Market
Payments
Poland Payments Market
Payments
Wearable Payments Market
Payments
North America Payment Analytics Software Market
Payments
France Virtual Cards Market
Payments
Tanzania Mobile Money Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
Canada Payment Gateway Market
Payments
Medical Payment Fraud Detection Market
Payments
LAMEA Crypto Payment Gateway Market
Payments
Latin America Retail Cash Management Market
Payments
Master Recharge API Market
Payments
North America Mobile Payments Market
Payments
Smart POS System Market
Payments
Norway Payments Market