
 Gulf Corporation Council Cement Market | 2026-2036
Gulf Corporation Council Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Gulf Corporation Council Cement Market Foresight
Grade 52.5N high-strength cement specification is collapsing the traditional commodity pricing model across the Gulf Corporation Council. Saudi Cement Company leverages captive limestone quarries and integrated clinker capacity to dominate supply into Neom and Red Sea Project zones. Yanbu Cement Company anchors western Saudi demand through deepwater port access and bulk export flexibility. Qatar National Cement Company competes on sulphate-resistant formulations tailored to coastal and saline soil conditions.
Gulf Corporation Council cement comprises hydraulic binding materials manufactured from calcined limestone, clay, and corrective additives fired in rotary kilns at approximately 1450°C, primarily serving structural concrete production for building and civil works. Ordinary Portland Cement retains volume leadership across residential and commercial applications, though blended cement incorporating pozzolanic materials is gaining share as specifications harden around embodied carbon limits. Infrastructure Projects represents the fastest-expanding application channel, driven by giga-project concrete demand, while Direct Sales controls the margin pool through long-term offtake agreements with government-backed developers.
Saudi Standards, Metrology and Quality Organization (SASO), Emirates Authority for Standardization and Metrology (ESMA), and Gulf Standardization Organization (GSO) collectively enforce compressive strength, chemical composition, and environmental compliance thresholds that determine product access and premium positioning. These frameworks increasingly incorporate carbon intensity benchmarks and alternative fuel utilization requirements that reshape kiln technology investment decisions. Stakeholders must monitor how evolving green procurement mandates across member states redirect capacity allocation between conventional and low-carbon cement streams.
Market Dynamics
Grade 52.5N high-strength cement specification is collapsing the traditional commodity pricing model across the Gulf Corporation Council. Saudi Cement Company leverages captive limestone quarries and integrated clinker capacity to dominate supply into Neom and Red Sea Project zones.
Growth Catalysts
- Saudi Vision 2030 giga-projects:Neom, Red Sea Project, and Qiddiya are accelerating concrete procurement volumes and pulling specialty cement grades into mass production.
- ESMA green building codes:The Emirates Authority for Standardization and Metrology is redirecting product mix toward blended formulations with lower embodied carbon.
- Alternative fuel kiln retrofits:Refuse-derived fuel and biomass co-processing are cutting fossil energy intensity and qualifying producers for green procurement preferences.
Market Restraints
- Limestone reserve depletion:High-calcium limestone suitable for Grade 52.5N clinker is concentrating in fewer captive quarries, raising extraction costs.
- Natural gas price volatility:Kiln fuel represents the largest variable cost component, and GCC pipeline supply disruptions compress operating margins unpredictably.
- Sulphate-resistant cement substitution:Geopolymer and alkali-activated binder trials in Qatar and UAE coastal projects threaten long-term volume for traditional SR formulations.
Strategic Opportunities
- Oman underpenetration:Duqm Special Economic Zone and port infrastructure lack integrated clinker capacity, creating import-substitution openings for Saudi and UAE producers.
- Carbon capture retrofit incentives:Saudi Energy Efficiency Center and UAE Ministry of Energy are piloting capital grants for post-combustion capture on aging kilns.
- Direct-to-project bulk logistics:Dedicated pneumatic discharge terminals at Neom and Red Sea Project sites are bypassing traditional distributor networks.
Industry Challenges
- Kiln process engineering talent:Alternative fuel combustion optimization and clinker chemistry adjustment require skills scarce across GCC technical institutes.
- SASO certification timelines:Saudi Standards, Metrology and Quality Organization product approval delays for novel blended formulations extend commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gulf Corporation Council Cement Market |
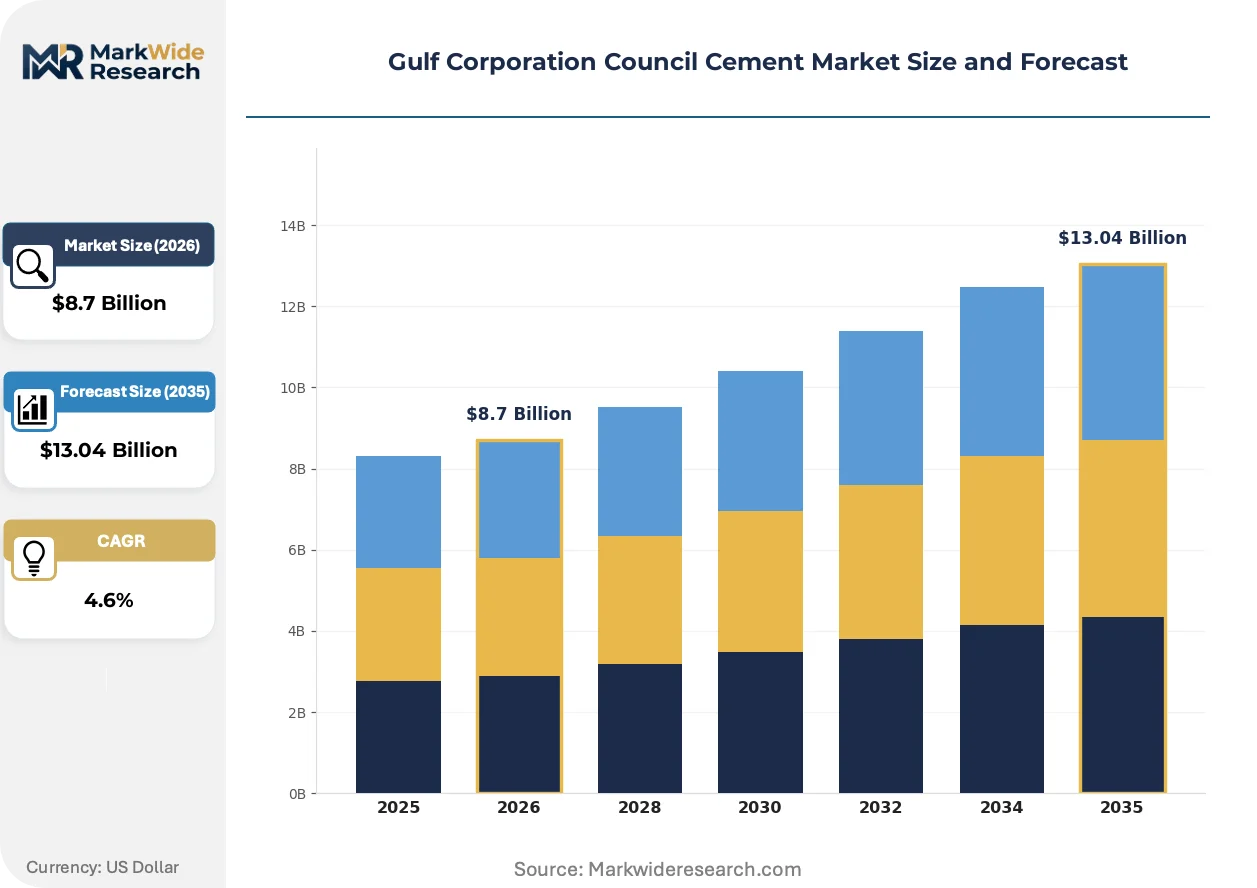
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ordinary Portland Cement, Blended Cement, Sulphate Resistant Cement, White Cement Application: Residential Construction, Commercial Buildings, Infrastructure Projects, Industrial Works Distribution Channel: Direct Sales, Retail Outlets, Online Sales, Wholesale End User: Government Projects, Private Contractors, Construction Companies, Real Estate Developers |
| Companies Covered | Saudi Cement Company, Yanbu Cement Company, Qatar National Cement Company, Oman Cement Company, Kuwait Cement Company, Gulf Cement Company, Emirates Steel Arkan, Lafarge Emirates Cement Company, Cemex UAE, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gulf Corporation Council Cement Market Shifts & Advancements
Calcined clay and limestone filler technologies are compressing clinker factors and redefining performance benchmarks across GCC specification regimes. These innovations intersect with tightening carbon accounting rules and buyer procurement mandates.
Calcined clay pozzolan is miniaturizing the clinker-to-cement ratio in blended formulations while maintaining early strength performance. Major giga-project concrete suppliers in Saudi Arabia are specifying LC3-type ternary blends for non-structural applications. This technology is compressing the premium gap between conventional Portland and low-carbon alternatives.
GSO technical regulations are mandating sulphate resistance testing and chloride permeability thresholds for coastal infrastructure concrete. Compliance is forcing reformulation of existing product lines and accelerated qualification testing. Saudi producers supplying Red Sea Project marine works are retooling grinding circuits to meet the new chemical envelope.
Long-term offtake agreements are displacing spot market purchases among government-backed developers. Direct sales contracts with Neom, Red Sea Global, and Qiddiya Investment Company now lock in five-year volume commitments with price escalation clauses. This concentration is most visible in Saudi Arabia, where three developers control over half of forecast cement consumption.
Gulf Corporation Council Cement Market Segmentation
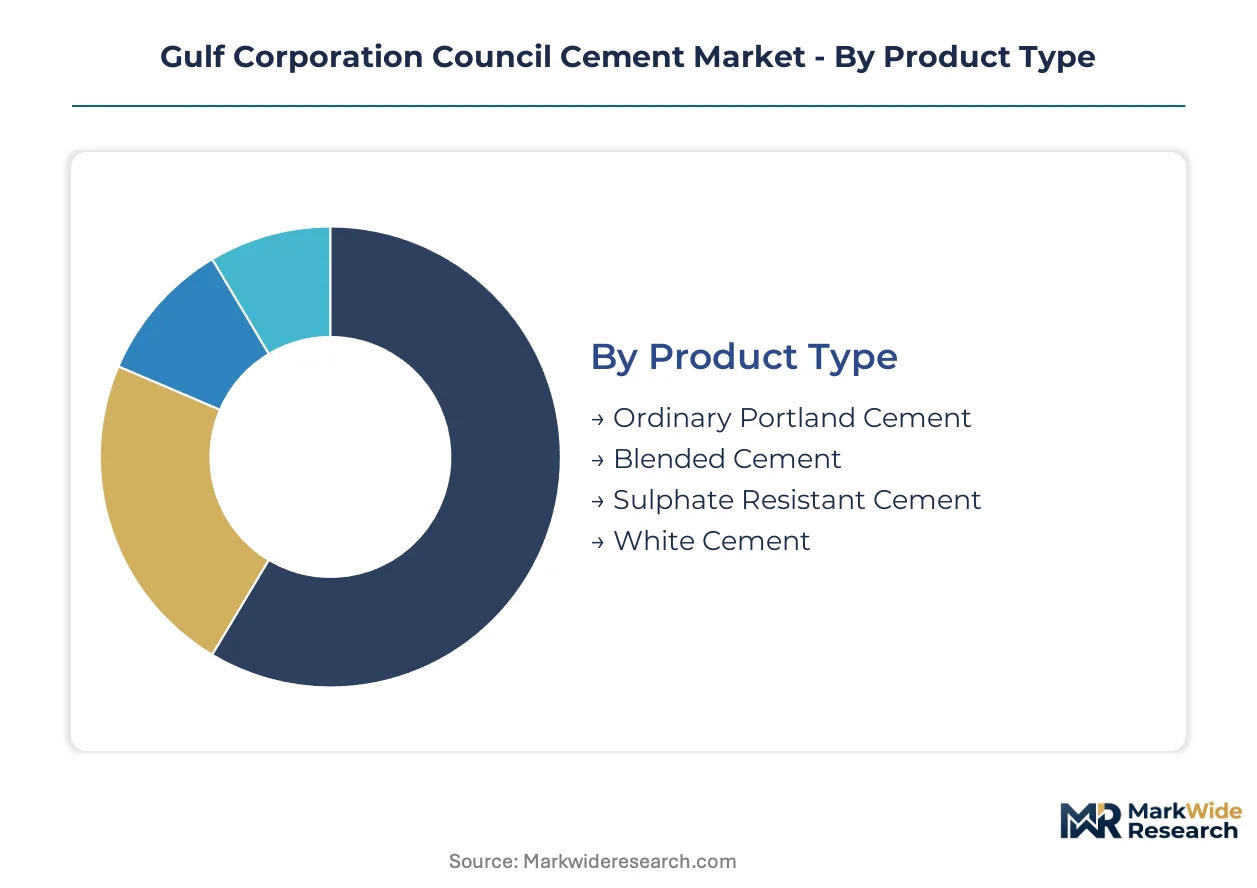
Channel configuration across the Gulf Corporation Council cement market determines which product grades reach which buyers. Procurement concentration around giga-projects and green building mandates is reshaping how segments map to revenue and margin pools.
Product Type:
Direct sales channels favor high-specification grades for infrastructure megaprojects, while retail and wholesale networks distribute commodity formulations for smaller-scale construction.
- Ordinary Portland Cement:Standard hydraulic binder manufactured from clinker and gypsum grinding, serving as the baseline specification for residential and commercial concrete across Saudi Arabia and UAE. Volume concentrates in mass housing developments and mid-rise commercial towers where cost sensitivity outweighs performance premiums.
- Blended Cement:Incorporates pozzolanic materials or limestone filler to reduce clinker factor and embodied carbon, qualifying suppliers for ESMA green procurement preferences and Neom sustainability mandates. Demand is accelerating fastest among government-backed developers with net-zero concrete targets.
- Sulphate Resistant Cement:Low C3A clinker formulation resisting chloride and sulphate attack in marine and saline soil conditions.
- White Cement:Iron-free clinker production for architectural and decorative concrete applications.
By volume, Ordinary Portland Cement leads. By growth pace, Blended Cement is climbing the fastest.
Application:
Cost tier stratification separates premium-specification concrete for signature infrastructure from economy-grade pours for standardized housing.
- Infrastructure Projects:Giga-project concrete demand for Neom, Red Sea Project, and Qiddiya is pulling specialty cement grades into mass production with multi-year offtake agreements. Saudi government-backed developers specify Grade 52.5N high-strength and low-carbon blended formulations for structural elements.
- Residential Construction:Mass housing programs across Riyadh and Jeddah drive commodity cement consumption through distributor networks serving smaller contractors.
- Commercial Buildings:High-rise towers and mixed-use developments in Dubai and Doha require mid-tier performance specifications with moderate sustainability credentials.
- Industrial Works:Factory floors, warehouses, and process facilities demand abrasion-resistant and chemically stable concrete formulations.
By margin contribution, Infrastructure Projects dominates. By contract volume, Residential Construction remains the baseline.
Distribution Channel:
Customer type determines channel selection — government developers bypass intermediaries while fragmented private contractors rely on retail and wholesale access.
- Direct Sales:Long-term offtake agreements with Neom, Red Sea Global, and Qiddiya Investment Company lock in five-year volume commitments with price escalation clauses, capturing the premium margin pool.
- Wholesale:Bulk procurement by mid-sized construction companies and regional contractors with project portfolios spanning multiple sites.
- Retail Outlets:Bagged cement sales to small contractors and individual builders through hardware and building material stores.
- Online Sales:Emerging digital procurement platforms for standardized product ordering with logistics coordination.
By revenue concentration, Direct Sales controls the largest share. By transaction count, Wholesale handles the greatest flow.
End User:
Supply concentration aligns with buyer scale — large government projects integrate directly with producers while fragmented private demand flows through distribution layers.
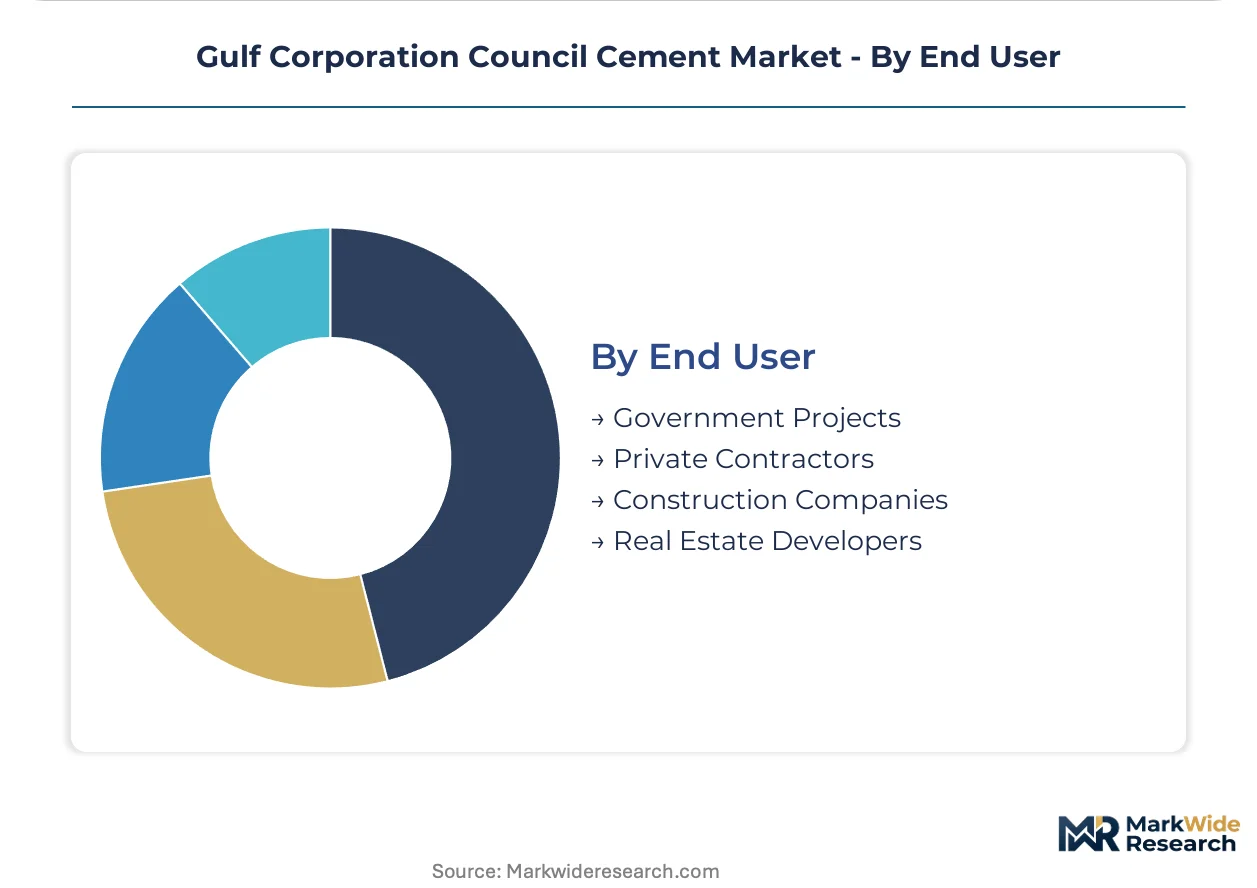
- Government Projects:Saudi Vision 2030 giga-developments and UAE federal infrastructure programs specify performance-grade cement with carbon accounting requirements and alternative fuel provenance documentation.
- Real Estate Developers:Master-planned community builders in Dubai, Riyadh, and Doha procure blended cement for green building certification compliance.
- Construction Companies:Tier-1 and Tier-2 contractors execute project-specific procurement with varying specification intensity.
- Private Contractors:Small and mid-sized builders serving residential renovation and commercial fit-out markets.
By specification stringency, Government Projects sets the benchmark. By procurement flexibility, Private Contractors maintains the widest optionality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi cement flows dominate intra-GCC trade corridors, with integrated producers supplying clinker and finished product to undercapacity markets in Oman and Bahrain. This export dynamic concentrates investment decisions in Riyadh and the Eastern Province while shaping procurement patterns across the peninsula.
Saudi Arabia
Neom, the Red Sea Project, and Qiddiya absorb over half of forecast GCC cement consumption through multi-year offtake agreements. SASO enforces Grade 52.5N compressive strength and alternative fuel utilization thresholds that determine product access. The Eastern Province cluster around Dammam and Jubail anchors clinker production with deepwater export terminals serving regional buyers.
United Arab Emirates
ESMA green building codes redirect product mix toward blended formulations with lower embodied carbon for Dubai and Abu Dhabi megaprojects. The Emirates Authority for Standardization and Metrology mandates sulphate resistance testing and chloride permeability thresholds for coastal infrastructure. Jebel Ali and Khalifa Port cement terminals handle bulk import and re-export flows to Oman and Qatar.
Qatar
Coastal and saline soil conditions drive specification intensity for sulphate-resistant formulations in Lusail and Doha infrastructure. Qatar National Cement Company competes on tailored chemistry for marine exposure zones. The North Field expansion and associated industrial zones concentrate demand in Ras Laffan and Mesaieed.
Oman
Duqm Special Economic Zone and port infrastructure lack integrated clinker capacity, creating import-substitution openings for Saudi and UAE producers. The Special Economic Zone Authority at Duqm offers land and logistics incentives for cement grinding and distribution terminals. Salalah and Sohar ports handle bulk cement flows from Jebel Ali and Jubail.
Kuwait
Residential construction and oilfield infrastructure sustain steady demand through distributor networks serving smaller contractors. The Public Authority for Industry regulates product standards and import licensing. The Shuaiba industrial area concentrates cement storage and bagging operations with re-export flexibility to southern Iraq.
Gulf Corporation Council Cement Market Competitive Landscape
Listed leaders compete with private specialists across capital access and project finance capability. The vendor base clusters around three tiers: integrated producers with captive limestone and clinker capacity, grinding-only operators dependent on imported clinker, and multinational joint ventures leveraging technology transfer. Strategic moves center on backward integration into quarry assets and long-term offtake negotiations with government-backed developers.
Within the integrated producer tier, Saudi Cement Company and Yanbu Cement Company exemplify quarry-to-kiln control that secures supply into giga-project zones. Qatar National Cement Company occupies a specialist position in sulphate-resistant formulations. Among multinational-backed operators, Lafarge Emirates Cement Company and Cemex UAE represent technology-licensed platforms serving UAE green building mandates.
| Leading Market Players |
|---|
| Saudi Cement Company |
| Yanbu Cement Company |
| Qatar National Cement Company |
| Oman Cement Company |
| Kuwait Cement Company |
| Gulf Cement Company |
| Emirates Steel Arkan |
| Lafarge Emirates Cement Company |
| Cemex UAE |
| Others |
Supply & Pricing Matrix
Captive limestone quarry economies in Saudi Arabia's Eastern Province concentrate clinker production capacity among three integrated producers, compressing price floors for commodity-grade cement while elevating premiums for Grade 52.5N high-strength formulations specified at Neom. Scale advantages at Saudi Cement Company and Yanbu Cement Company translate into direct-to-project pricing power that grinding-only operators in Oman and Bahrain cannot match.
Pricing Analysis
Clinker-factor technology gaps separate pricing tiers across the Gulf Corporation Council, with conventional Portland formulations commanding commodity rates while LC3-type calcined clay blends capture green procurement premiums at ESMA-compliant projects. Price differentiation rests on carbon intensity certification and alternative fuel provenance documentation rather than traditional brand positioning. Cost compression in standard-grade cement intensifies as Saudi overcapacity flows into import-dependent markets. Government-backed developers with multi-year offtake agreements exhibit lowest price sensitivity, while fragmented residential contractors in Kuwait and Oman remain most exposed to spot market volatility.
Supply Chain Analysis
Strategic limestone stockpiling preferences among Saudi integrated producers buffer against kiln fuel volatility, contrasting with just-in-time clinker import dependencies at Omani grinding terminals. Geographic supply concentration centers on Saudi Arabia, UAE, and Qatar, with the Eastern Province and Yanbu anchoring regional clinker production. Raw material sourcing draws from captive high-calcium limestone quarries, natural gas pipeline networks, and increasingly refuse-derived fuel streams. Single-source vulnerability runs through Saudi limestone reserves suitable for Grade 52.5N clinker. Distribution flows through dedicated pneumatic discharge terminals at giga-project sites, bypassing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gulf Corporation Council cement market functions as a regulatory-entrenchment defensive moat, where SASO certification timelines and alternative fuel qualification requirements create switching costs that protect incumbent positions against import competition.
For Market Incumbents: Compound quarry-to-kiln integration advantages by securing additional high-calcium limestone concessions in Saudi Arabia's Western Province before competitor entry. Accelerate alternative fuel combustion optimization to meet tightening SASO carbon intensity thresholds. Defend against geopolymer substitution trials in Qatar and UAE coastal zones by embedding long-term offtake clauses with Red Sea Global and Qiddiya Investment Company.
For New Entrants and Emerging Players: Carbon capture retrofit service gaps at aging Saudi kilns present white-space entry points where incumbents under-invest. Target Duqm Special Economic Zone grinding terminal development as the most penetrable geography, leveraging land and logistics incentives from the Special Economic Zone Authority. Pursue direct sales channel establishment through five-year offtake negotiations with Oman government infrastructure programs.
For Investors and Strategic Acquirers: Grinding-only operators with Jebel Ali or Salalah port access represent acquisition targets positioned for Saudi clinker import arbitrage. Long-term viability across the analysis window hinges on carbon capture retrofit execution and green procurement mandate compliance trajectories. Watch for alternative fuel utilization rate thresholds crossing materiality levels as the inflection signal for capacity repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Quarries | SASO Grade 52.5N specification hardening makes captive high-calcium reserves non-substitutable. |
| Alternative Fuel Kiln Retrofit | Refuse-derived fuel co-processing qualifies producers for Neom green procurement preferences. |
| Direct-to-Project Terminal Development | Pneumatic discharge infrastructure at Red Sea Project sites bypasses distributor margin capture. |
| Long-term Offtake Agreement Negotiation | Five-year volume commitments with Qiddiya Investment Company lock in price escalation clauses. |
| Carbon Capture Pilot Implementation | Saudi Energy Efficiency Center capital grants reduce retrofit capex for post-combustion systems. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cement plant managers, procurement leads at Neom and Red Sea Global, bulk logistics operators, and ESMA regulatory affairs specialists; and secondary validation through SASO technical regulation filings, GSO standardization documents, customs trade data, and SEC disclosures from listed producers. Bottom-up capacity and consumption modeling triangulated against top-down macroeconomic projections across Saudi Arabia, UAE, Qatar, Oman, and Kuwait.
Across the analysis window, the forecasting framework segmented volume and value outputs by product type, application channel, distribution mode, and end-user procurement scale. CAGRs derived from regression analysis of historical clinker production, giga-project concrete pour schedules, and green building code adoption curves. Industry-specific inputs incorporated alternative fuel utilization trajectories and carbon intensity benchmark evolution.
Forecasts assume regulatory continuity in SASO, ESMA, and GSO enforcement regimes; material policy shifts around embodied carbon limits or import licensing would require re-modeling. Revision becomes warranted when geopolymer substitution trial results cross commercialization thresholds or when Saudi limestone reserve depletion accelerates beyond replacement rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Modular Commercial Building System Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
I-Joist Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
Thailand Construction Chemicals Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
Japan Prefab Wood Building Market
Building & Construction Materials
External Wall Insulation Board Market
Building & Construction Materials
Aluminum Curtain Wall Market
Building & Construction Materials
Fiber Cement Rainscreen Panels Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
Oriented Strand Board (OSB) Market