
 Global Wall Putty Market | 2026-2036
Global Wall Putty Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wall Putty Market Outlook
Skilled applicator availability is rotating toward shortage in several manufacturing clusters, pushing producers to simplify product handling and reduce touch-labor intensity. Asian Paints leverages its captive distribution network across tier-2 and tier-3 Indian cities to sustain last-mile coverage for contractor segments. Birla White anchors the white cement-based putty segment with manufacturing scale that dominates bulk supply to northern Indian infrastructure projects. Sika AG competes on construction chemicals integration, extending its waterproof putty line through specification relationships with European engineering firms.
Wall putty is a cementitious or acrylic-based fine powder or paste applied over plastered surfaces to create smooth, absorbent substrates ready for paint or wallpaper, with particle sizes typically below 100 microns and binding strength measured by adhesion to concrete or brick backgrounds. Its primary commercial purpose is to eliminate surface irregularities, reduce paint consumption, and extend coating durability on interior and exterior walls. Interior putty occupies the largest volume share as residential repaint cycles shorten across tropical climates, while waterproof putty generates the strongest margin pool due to polymer modification and specialized hydrophobic additives. Eco-friendly formulations are expanding fastest as regulatory pressure and green building certifications reshape contractor procurement criteria across multiple geographies.
REACH in Europe, MEE VOC standards in China, and BIS certification requirements in India collectively constrain solvent-based formulations while accelerating water-based and low-emission product registrations. These frameworks raise compliance costs for smaller regional blenders but create market access advantages for multinationals with established testing and certification infrastructure. Stakeholders must monitor evolving chemical disclosure rules and building material procurement mandates to anticipate which formulation categories will face accelerated substitution or premium positioning.
Market Dynamics
Water-based formulation migration is compressing solvent-grade margins while expanding polymer-modified product lines across tropical construction belts. Regulatory disclosure requirements in Europe and China are accelerating R&D redirection toward low-VOC binders.
Growth Catalysts
- India's urban housing programs:Contractor-grade procurement volumes are scaling in tier-2 and tier-3 cities as government-subsidized residential projects specify pre-painted surface preparation standards.
- REACH compliance deadlines:European formulators are registering water-based alternatives ahead of chemical restriction phases, creating first-mover certification advantages for compliant producers.
- Polymer modification advances:Acrylic-PU hybrid binders are extending exterior-grade durability in Southeast Asian monsoon climates, opening specification opportunities in commercial facade contracts.
Market Restraints
- White cement supply concentration:Northern Indian clinker shortages are forcing putty manufacturers to absorb input volatility or reformulate around alternative binders.
- VOC enforcement fragmentation:China's MEE standards lack uniform provincial implementation, creating compliance cost uncertainty for multi-facility producers.
- Skilled applicator scarcity:Surface preparation certification gaps in Indonesian construction clusters are limiting uptake of premium-grade products requiring trained application.
Strategic Opportunities
- Vietnam's industrial corridor expansion:Factory and logistics park construction around Ho Chi Minh City and Hai Phong is generating specification demand for waterproof exterior grades.
- EU Green Deal procurement mandates:Public building renovation tenders are prioritizing EPD-certified materials, creating premium positioning for low-carbon putty formulations.
- E-commerce contractor channels:Direct-to-painter platforms in Indian metropolitan markets are disintermediating traditional distributor networks for standard-grade products.
Industry Challenges
- BIS certification timelines:Indian standard testing backlogs are delaying product launches by 8-14 months for reformulated water-based lines.
- Legacy inventory absorption:Solvent-grade stockpiles in distributor networks are complicating transition pricing for eco-friendly alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wall Putty Market |
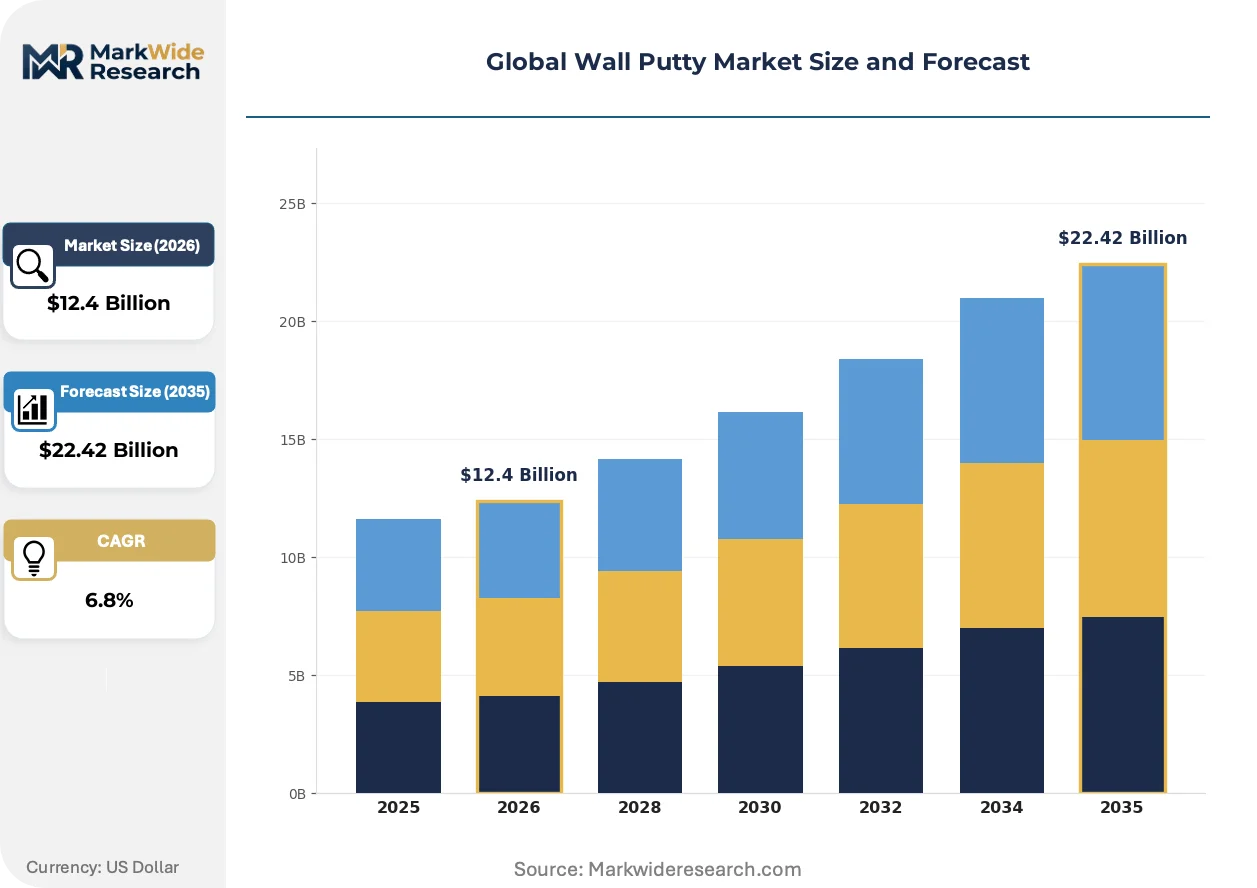
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Putty, Exterior Putty, Waterproof Putty, Textured Putty Application: Residential, Commercial, Industrial, Decorative Formulation: Water-Based, Oil-Based, Solvent-Based, Eco-Friendly End User: Contractors, DIY Enthusiasts, Builders, Architects |
| Companies Covered | Asian Paints, Birla White, Sika AG, Berger Paints, Nippon Paint, JK Cement, Saint-Gobain, Akzo Nobel, Pidilite Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wall Putty Market Strategic Shifts
Formulation chemistry is splitting along performance-versus-sustainability axes as regional regulatory clocks desynchronize. Product development pipelines are prioritizing binder systems that satisfy multiple certification regimes simultaneously.
Hybrid acrylic-silicone binder technology is bifurcating the premium segment from commodity cementitious grades. Large-scale commercial developers in Malaysia and Thailand are specifying these systems for 15-year facade warranties. The technology is compressing traditional white cement putty margins in specification-driven projects while opening polymer-compounder partnerships for chemical specialists.
China's MEE VOC emission standards are tightening disclosure thresholds for interior architectural coatings. Formulators must now submit complete substance inventories for products above 420 grams per liter. Water-based putty registrations are accelerating in Guangdong and Jiangsu provinces as manufacturers preempt stricter enforcement phases expected in coastal manufacturing zones.
Contractor purchasing behavior is consolidating around bundled construction chemical suppliers. Mid-sized painting crews in Indonesian and Philippine markets are shifting from single-product procurement to category-managed accounts with waterproofing and adhesive lines. This pattern is most visible in Jakarta and Manila metropolitan construction corridors where project scale justifies consolidated logistics arrangements.
Global Wall Putty Market Segmentation
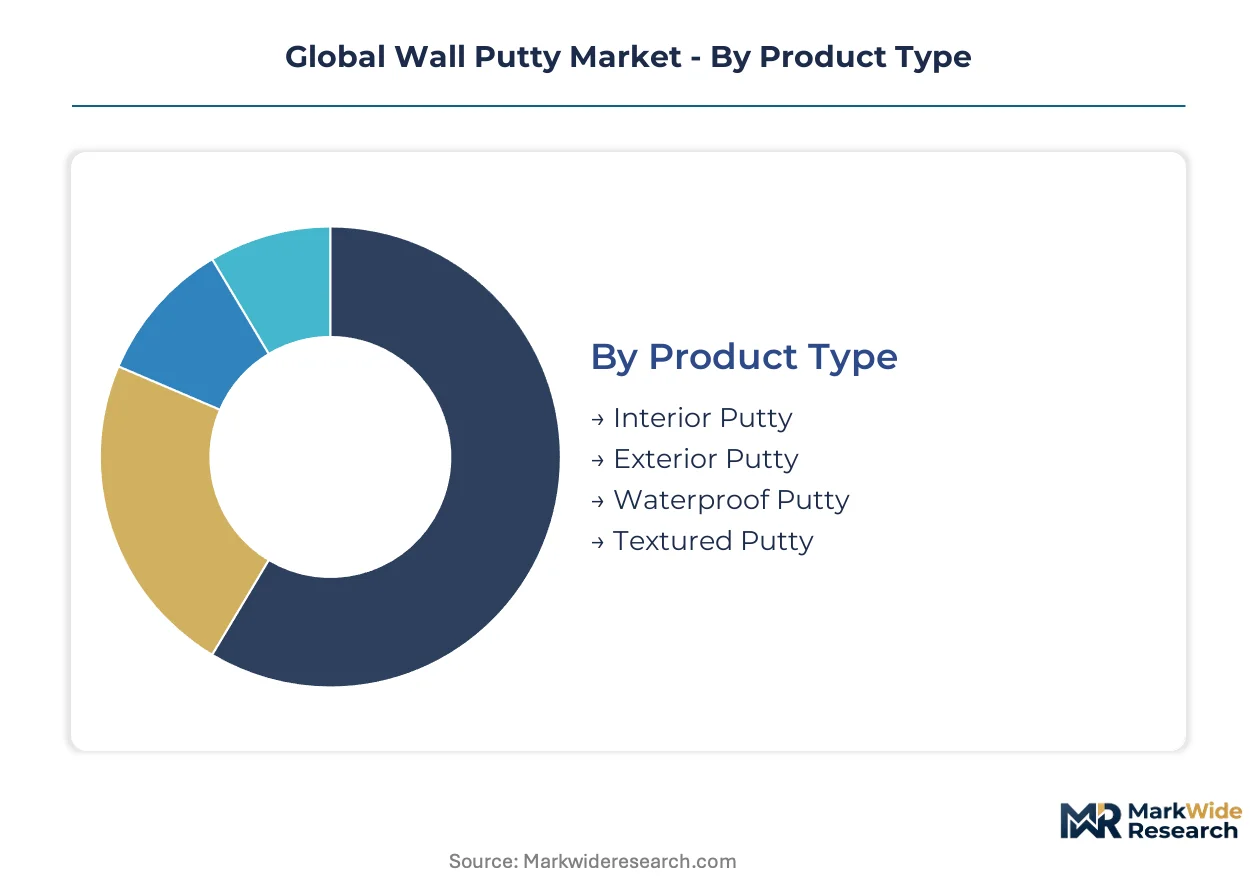
Wall putty segmentation reveals distinct demand corridors shaped by climate exposure, regulatory pressure, and contractor capability. Each category isolates procurement patterns that separate volume markets from premium specification channels.
Product Type:
Interior putty dominates domestic consumption across tropical housing belts, while waterproof and exterior grades drive export-led specification in commercial facade projects.
- Interior Putty:Cementitious or acrylic-based fine powders designed for smooth, absorbent substrates beneath paint or wallpaper. Demand concentrates in Indian tier-2 and tier-3 cities where government-subsidized residential projects mandate pre-painted surface preparation standards.
- Waterproof Putty:Polymer-modified formulations incorporating hydrophobic additives and acrylic-PU hybrid binders for monsoon-exposed surfaces. Southeast Asian commercial developers specify these systems for extended facade warranties in Ho Chi Minh City and Bangkok metropolitan construction corridors.
- Exterior Putty:Weather-resistant grades formulated for thermal cycling and UV exposure on building envelopes.
- Textured Putty:Decorative surface variants enabling patterned finishes for architectural accent walls.
Interior putty commands the established base. The steepest expansion runs through waterproof putty.
Application:
Cost tier stratification separates commodity residential repaint cycles from high-specification commercial and industrial contracts.
- Residential:Volume-driven segment absorbing interior-grade material through shortened repaint cycles across tropical climates. Contractor-grade procurement scales through direct-to-painter e-commerce platforms in Indian metropolitan markets.
- Commercial:Premium specification channel where bundled construction chemical suppliers capture category-managed accounts. Jakarta and Manila metropolitan corridors demonstrate consolidated logistics arrangements for waterproofing-adhesive-putty bundles.
- Industrial:Heavy-duty surface preparation for manufacturing facilities and logistics parks.
- Decorative:Aesthetic-focused applications in hospitality and retail interiors.
Residential absorbs the volume base. Commercial applications are climbing the fastest on bundled procurement trends.
Formulation:
Regulatory clocks across multiple geographies are forcing parallel migration paths toward low-emission binder systems.
- Water-Based:Low-VOC formulations registering accelerated approvals in Guangdong and Jiangsu provinces ahead of MEE enforcement phases. European formulators leverage REACH compliance deadlines to secure first-mover certification advantages.
- Eco-Friendly:EPD-certified and bio-based alternatives capturing EU Green Deal procurement mandates for public building renovation tenders. Green building certifications reshape contractor criteria across multiple geographies.
- Oil-Based:Legacy formulations facing compressed margins amid solvent-grade inventory absorption challenges.
- Solvent-Based:Declining category constrained by REACH, MEE VOC standards, and BIS certification requirements.
Water-based formulations hold the incumbent position. Eco-friendly alternatives gain share fastest on regulatory and certification tailwinds.
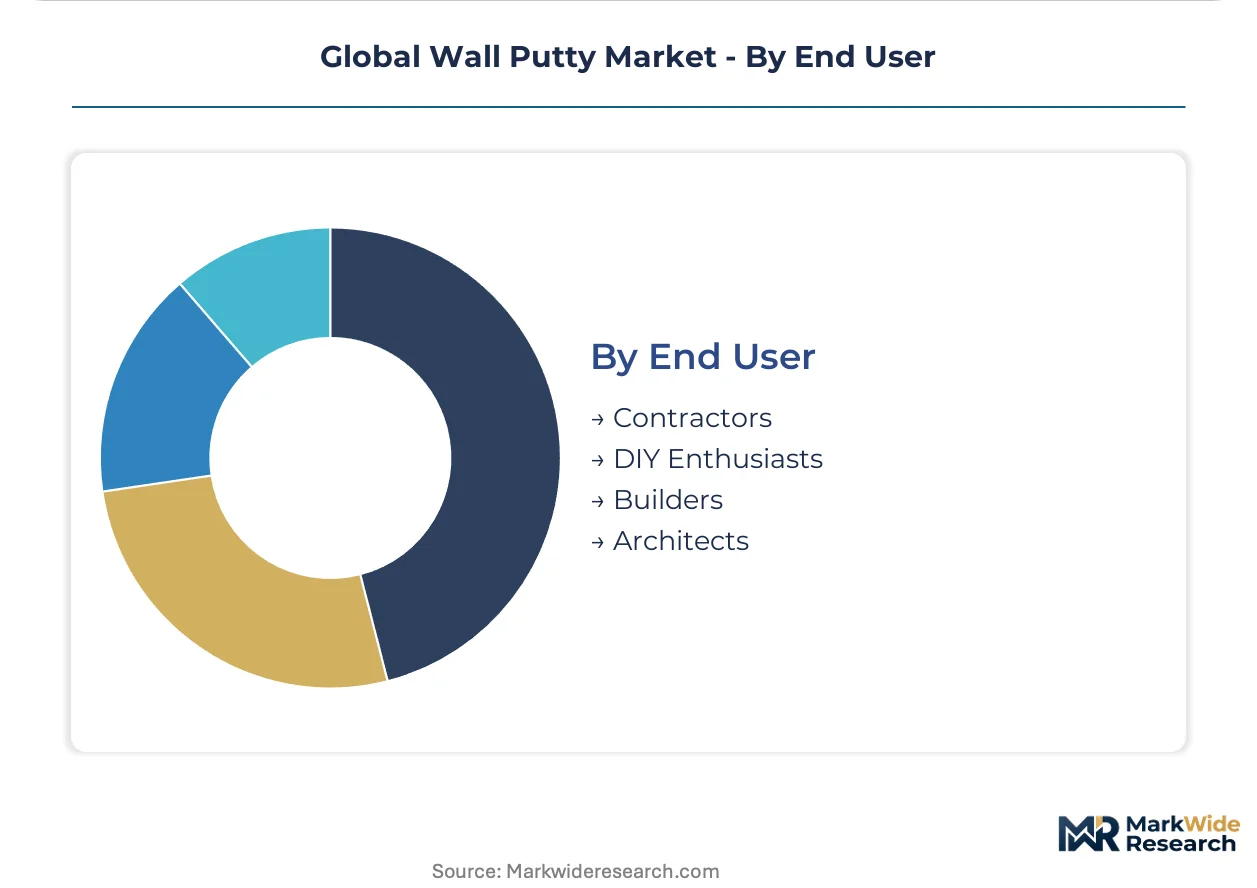
End User:
Customer capability divides the market between trained applicator networks and self-directed procurement channels.
- Contractors:Professional painting crews driving category-managed accounts with waterproofing and adhesive lines. Skilled applicator scarcity in Indonesian construction clusters limits uptake of premium grades requiring certified surface preparation.
- Builders:Large-scale developers specifying 15-year facade warranties through hybrid acrylic-silicone systems in Malaysia and Thailand.
- DIY Enthusiasts:Simplified handling requirements from producers responding to labor shortages in manufacturing clusters.
- Architects:Specification influencers prioritizing EPD-certified materials for green building compliance.
Contractors anchor the volume channel. Builder-direct procurement is expanding most quickly on large-scale commercial warranty requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification requirements anchor the dominant geography as India's urban housing programs reshape procurement patterns across tier-2 and tier-3 cities. REACH compliance deadlines and MEE VOC standards redirect formulation strategies in Europe and China respectively.
India
Contractor-grade procurement volumes scale through government-subsidized residential projects mandating pre-painted surface preparation standards. BIS certification timelines delay water-based product launches by 8-14 months, compressing reformulation windows. Northern Indian infrastructure projects absorb bulk white cement-based supply from dedicated manufacturing clusters around Delhi-NCR and Rajasthan.
China
MEE VOC emission standards tighten disclosure thresholds for interior architectural coatings above 420 grams per liter. Guangdong and Jiangsu provinces accelerate water-based putty registrations ahead of stricter enforcement phases expected in coastal manufacturing zones. Pearl River Delta formulators submit complete substance inventories to preempt regulatory restriction phases.
Germany
EU Green Deal procurement mandates prioritize EPD-certified materials for public building renovation tenders. REACH compliance deadlines create first-mover certification advantages for water-based alternatives ahead of chemical restriction phases. Engineering firms in Munich and Frankfurt metropolitan corridors specify waterproof putty lines through bundled construction chemical arrangements.
Vietnam
Industrial corridor expansion around Ho Chi Minh City and Hai Phong generates specification demand for waterproof exterior grades. Factory and logistics park construction absorbs polymer-modified formulations for monsoon-exposed commercial facades. Southern Vietnamese contractors consolidate procurement through category-managed accounts with waterproofing and adhesive suppliers.
Indonesia
Skilled applicator scarcity in Jakarta and Surabaya construction clusters limits uptake of premium grades requiring certified surface preparation. Bundled construction chemical procurement patterns consolidate around mid-sized painting crews shifting from single-product to category-managed accounts. Javanese manufacturing clusters face labor shortages pushing producers toward simplified product handling.
Global Wall Putty Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the wall putty market. White cement-based specialists dominate bulk supply to infrastructure projects through manufacturing scale advantages, while polymer-modified formulators capture premium specification channels through certification relationships. Three archetypes structure competition: captive distribution network operators, integrated construction chemical suppliers, and regional white cement blenders. Dominant competitive moves include strategic partnerships with engineering firms for specification capture and portfolio diversification into waterproofing-adhesive bundles.
Among Indian market anchors, Asian Paints and Birla White exemplify divergent archetypes within the same geography. Asian Paints occupies a position tied to captive distribution reach across tier-2 and tier-3 cities, while Birla White anchors the white cement-based segment through manufacturing concentration. Sika AG represents the integrated construction chemical supplier archetype, extending specification relationships through European engineering firm networks. These three companies illustrate how geographic origin and corporate structure map to distinct competitive positions without overlapping strategic territory.
| Leading Market Players |
|---|
| Asian Paints |
| Birla White |
| Sika AG |
| Berger Paints |
| Nippon Paint |
| JK Cement |
| Saint-Gobain |
| Akzo Nobel |
| Pidilite Industries |
| Others |
Value Chain & Pricing Dynamics
Sixty-day clinker inventory cycles in northern India anchor pricing power for white cement-based putty producers, compressing margin buffers for regional blenders while amplifying cost pass-through leverage for integrated manufacturers with captive limestone supply.
Pricing Analysis
Price spreads between Indian and Vietnamese contractor-grade putty exceed transport-adjusted raw material differentials, signaling brand premium capture in specification-driven projects. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and polymer modification intensity. Pricing pressure stems from white cement input volatility as Rajasthan clinker shortages force reformulation toward alternative binders. Small-scale painting crews in Indonesian tier-2 cities exhibit highest price sensitivity, while European engineering firms demonstrate lowest sensitivity due to warranty-backed specification requirements.
Supply Chain Analysis
Strategic stockpiling of hydrophobic additives dominates monsoon-exposed Southeast Asian markets, contrasting with just-in-tight raw material flows in European REACH-compliant production hubs. Manufacturing concentrates in India, China, and Vietnam, with each hub serving distinct formulation export corridors. Supply chains draw from white cement clinker, acrylic-PU hybrid binders, and silicone-based hydrophobic agents. Single-source vulnerability runs through northern Indian clinker kilns supplying bulk infrastructure projects. Distribution runs through bundled construction chemical suppliers capturing category-managed accounts in Jakarta and Manila metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified applicator shortages across Indonesian and Philippine construction clusters constrain premium product uptake, creating capability bottlenecks that separate volume-market suppliers from specification-grade competitors.
For Market Incumbents: Secure BIS certification pipelines ahead of water-based formulation mandates, compressing launch windows for reformulated lines. Anchor backward integration into white cement clinker supply to defend margin position against Rajasthan input volatility. Prioritize captive distribution network density across Indian tier-3 cities where contractor procurement consolidates. For New Entrants and Emerging Players: Lead with e-commerce direct-to-painter platforms in Indian metropolitan markets, disintermediating legacy distributor networks for standard-grade interior putty. Target Vietnam's industrial corridor expansion around Hai Phong for waterproof exterior grade penetration. Bundle waterproofing-adhesive-putty procurement relationships with mid-sized painting crews shifting from single-product to category-managed accounts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified construction chemical parents with underoptimized putty-specific manufacturing assets and weak specification relationships. Long-term viability hinges on polymer modification R&D capabilities and multi-certification registration infrastructure across REACH, MEE, and BIS regimes. Watch skilled applicator training program scale as inflection signal for premium-grade market penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Modification R&D Partnership | Acrylic-PU hybrid binders extend facade warranty terms for Ho Chi Minh City commercial developers. |
| Water-Based Formulation Registration | MEE compliance in Guangdong and Jiangsu provinces accelerates ahead of coastal enforcement phases. |
| Captive Distribution Network Expansion | Tier-3 Indian city coverage captures contractor-grade procurement from government-subsidized housing programs. |
| EPD Certification Investment | EU Green Deal procurement mandates prioritize low-carbon putty for public building renovation tenders. |
| Skilled Applicator Training Program | Surface preparation certification gaps in Indonesian clusters limit premium-grade product uptake. |
Study Parameters
The analysis maps interior-grade, waterproof, exterior-grade, and textured putty sub-sectors, each validated through contractor interviews, builder procurement directors, distributor channel managers, and polymer compounding specialists. Primary fieldwork combined with secondary validation from BIS registration databases, MEE disclosure filings, EU EPD certification records, and construction chemical trade flow data. Bottom-up volume modeling triangulated against top-down macro construction spending indicators.
Consistency checks validated volume and value outputs against external benchmarks including cement industry association reports and architectural coatings procurement surveys. The analytical framework segments by product type, application, formulation chemistry, and end-user capability across the projection horizon. CAGRs derived from polynomial trend fitting of historical consumption patterns adjusted for regulatory phase-in schedules and urban housing program implementation timelines. Forecast inputs incorporated monsoon intensity indices for Southeast Asian exterior-grade demand and clinker capacity utilization rates for Indian supply-side constraints.
Forecasts assume regulatory continuity in REACH, MEE, and BIS regimes; material policy shifts would require re-modeling of formulation migration timelines and certification cost burdens. Revision becomes warranted when white cement clinker supply disruptions or applicator training program scale crosses thresholds that alter premium-grade penetration trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Slimline Aluminum Window System Market
Building & Construction Materials
Acoustic Ceiling Tiles Market
Building & Construction Materials
Plastic Decking Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Global Metal-Faced Insulated Panels Market
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
North America Fabricated Metal Products Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
North America Metallic Barn Doors Market
Building & Construction Materials
Moisture Resistant Gypsum Board Market
Building & Construction Materials
Hollow Concrete Block Market
Building & Construction Materials
Global Steel Wire Rod Market
Building & Construction Materials
North America Residential Water Heater Market
Building & Construction Materials
Pocket Door Market
Building & Construction Materials
Temporary Storage Buildings Market
Building & Construction Materials
Sink Float Tank Market