
 Road Construction Machinery Market | 2026-2036
Road Construction Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Road Construction Machinery Market Analytics
Government agencies is redrawing procurement patterns in the road construction machinery sector as public infrastructure budgets expand across developed and emerging economies. Caterpillar Inc. leverages its integrated dealer network and aftermarket parts dominance to sustain recurring revenue streams in mature markets. XCMG Group anchors its competitive position through aggressive cost engineering and scale manufacturing serving Belt and Road corridors. SANY Group competes on electrification speed, positioning its battery-powered excavator line for municipal contracts with zero-emission mandates.
Road construction machinery encompasses self-propelled and towed equipment engineered to prepare subgrade, apply pavement layers, and achieve specified compaction densities through vibratory, static, or pneumatic force application; drum widths on asphalt pavers typically span 2.5 to 9.5 meters to match lane configurations and project scales. The primary commercial purpose centers on delivering finished road surfaces that meet international roughness index and structural number specifications for load-bearing capacity. Pavers and rollers capture disproportionate margin pools in highway construction applications where surface quality directly determines warranty exposure and lifecycle performance. Electric technology is gaining fastest traction in urban development sites where noise ordinances and indoor emission restrictions limit diesel deployment.
EPA Tier 4 Final standards in the United States and EU Stage V regulations in Europe are forcing engine redesigns and aftertreatment complexity that elevates equipment costs while opening market access for electric alternatives. China's MIIT and SAMR coordinate GB standard updates that align domestic manufacturers with dual carbon policy timelines, compressing the window for diesel-only product strategies. India's CEA and state pollution control boards are tightening construction equipment emission norms in the National Capital Region and Maharashtra. Stakeholders must monitor regulatory divergence across these jurisdictions to determine powertrain portfolio allocation and certification investment priorities.
Market Dynamics
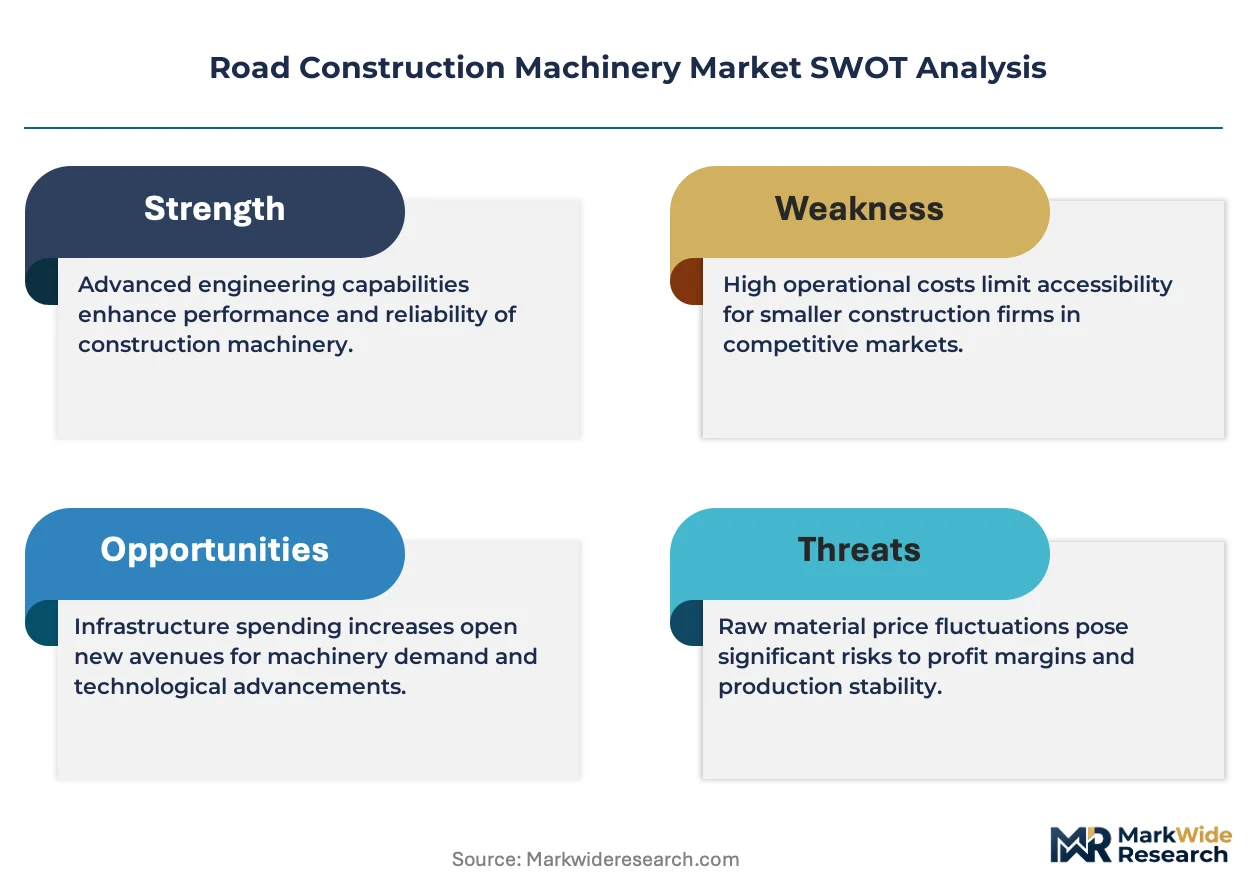
EPA Tier 4 Final and EU Stage V emission standards are compressing diesel equipment viability windows while accelerating electric powertrain substitution in urban construction zones. Fleet procurement departments now weight total cost of ownership against residual value risk as aftertreatment complexity elevates maintenance burdens.
Growth Catalysts
- Highway rehabilitation stimulus:Government agencies in the United States, India, and China are expanding capital allocations for interstate and national highway refurbishment programs, directly lifting paver and roller demand.
- EPA Tier 4 Final compliance deadlines:The regulation is forcing equipment retirement waves among aging municipal fleets, generating replacement pull for cleaner diesel and electric alternatives.
- Belt and Road corridor development:Central Asian and Southeast Asian infrastructure connectivity projects are concentrating equipment deployment along transnational road networks.
Market Restraints
- Steel and hydraulic component cost volatility:Input price swings compress margin stability for original equipment manufacturers dependent on commodity-exposed supply chains.
- Engine aftertreatment complexity:Diesel particulate filters and selective catalytic reduction systems elevate failure rates and service costs, extending payback periods for fleet operators.
- Electric powertrain energy density limitations:Battery weight and charge infrastructure gaps restrict all-electric equipment to short-radius urban sites, excluding highway and rural applications.
Strategic Opportunities
- India's National Infrastructure Pipeline:State-level road development authorities are tendering multi-year equipment leasing contracts with localized service requirements.
- Telematics-to-autonomy convergence:Machine control systems and fleet management platforms are merging, enabling outcome-based equipment utilization models.
- China's dual carbon policy timelines:MIIT production quotas and SAMR certification fast-tracks are creating preferential market access for battery-electric machinery.
Industry Challenges
- EPA and EU Stage V homologation timelines:Divergent certification requirements across jurisdictions extend product development cycles and fragment engineering resources.
- Electrification skill gaps:Service technician training for high-voltage systems and battery diagnostics lags equipment deployment rates, constraining aftermarket support capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Construction Machinery Market |
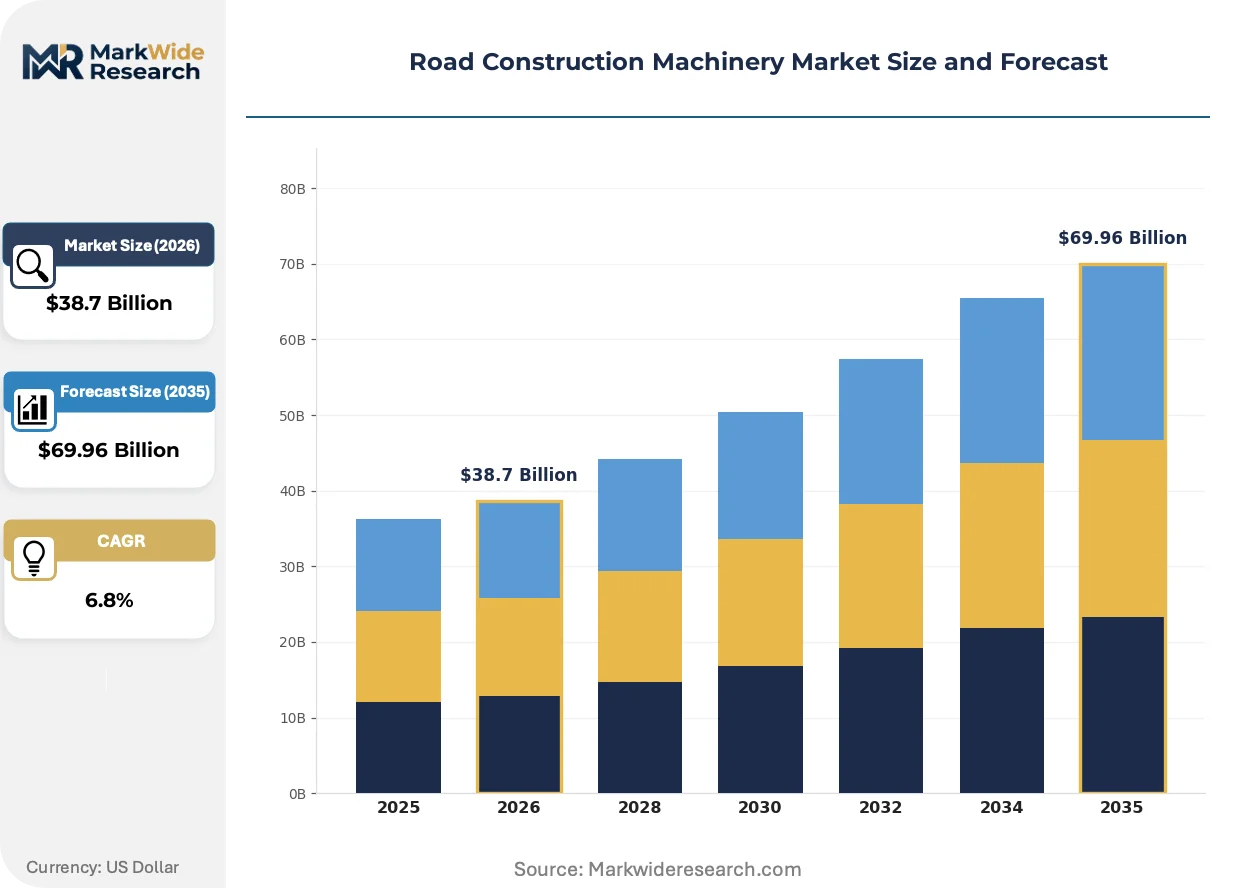
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Graders, Pavers, Rollers Application: Highway Construction, Urban Development, Road Maintenance, Infrastructure Renovation Technology: Hydraulic, Pneumatic, Electric, Diesel End User: Contractors, Government Agencies, Construction Companies, Engineering Firms |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., XCMG Group, SANY Group, Volvo Construction Equipment, Liebherr Group, John Deere, Wirtgen Group, JCB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Construction Machinery Market Evolving Landscape
Powertrain electrification, autonomous machine control, and connected fleet management are converging to redefine equipment utilization economics and operator productivity benchmarks across road construction sites.
Intelligent compaction systems integrating real-time density sensors with GPS mapping are miniaturizing quality assurance workflows. Municipal contractors in noise-restricted urban corridors are adopting these systems fastest, compressing traditional manual testing cycles and reducing warranty exposure on finished surfaces.
EU Stage V emission standards are mandating diesel particulate filter and selective catalytic reduction retrofits on existing equipment. The regulation is elevating total cost of ownership for legacy fleets, pushing European rental houses toward electric alternatives for urban contracts with zero-emission mandates.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-sized contractors. Rental channel partners are capturing aftermarket revenue streams through bundled maintenance and telematics subscriptions, with this shift most visible in Germany's fragmented municipal construction sector.
Road Construction Machinery Market Segmentation
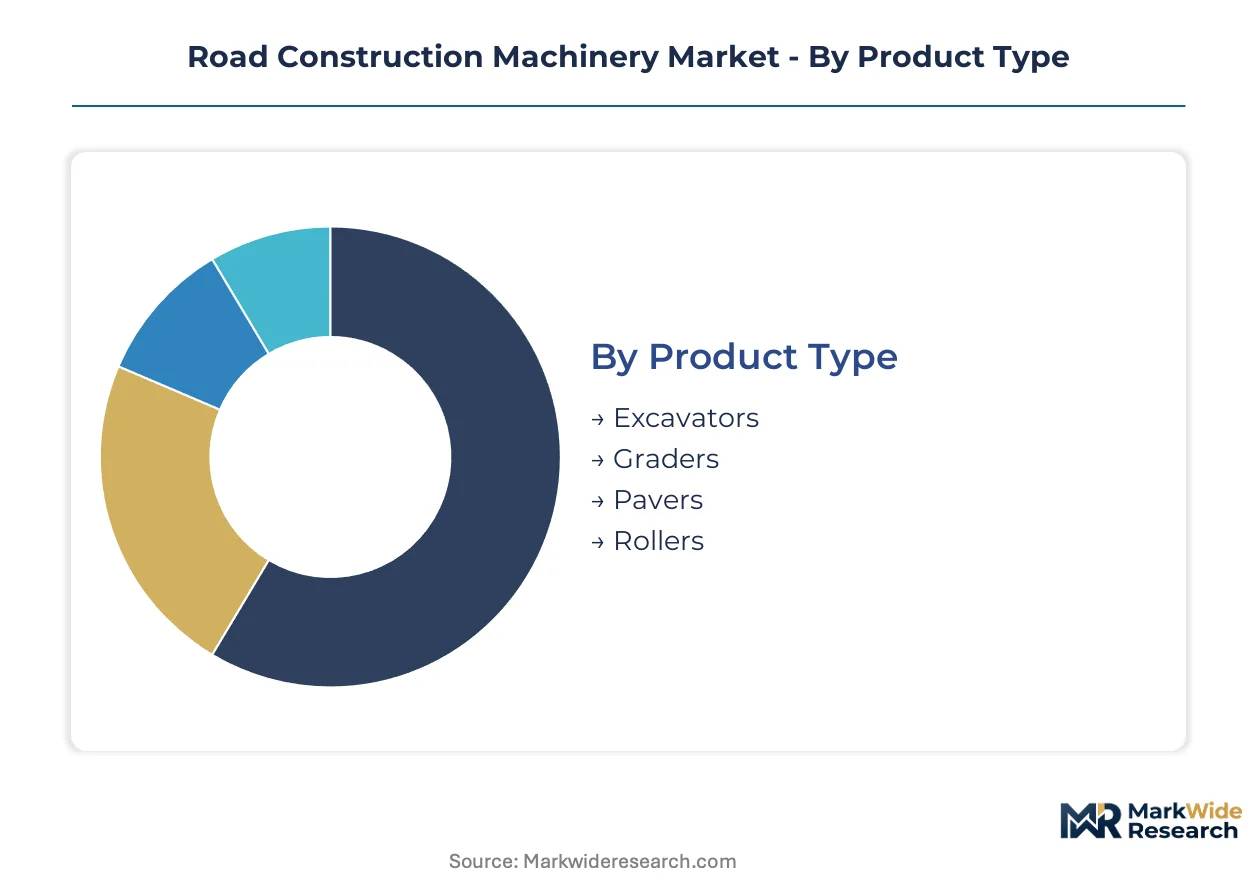
Segmentation in road construction machinery reveals how equipment specifications, project types, and regulatory pressures fragment procurement decisions across distinct customer workflows. Understanding these divides helps manufacturers align powertrain portfolios and service networks with where margin pools concentrate.
Product Type:
EPA Tier 4 Final and EU Stage V standards are forcing divergent engineering investments across equipment categories, with emission compliance costs hitting larger machines hardest while opening electric substitution windows for compact classes.
- Excavators:These machines combine boom, stick, and bucket assemblies with 360-degree rotation capability for trenching, material handling, and site preparation. Demand clusters in China's urban renewal zones and India's National Infrastructure Pipeline projects where municipal contracts now specify zero-emission capability for equipment below 10 metric tons. SANY Group's battery-powered excavator line targets this specification shift directly.
- Pavers:Self-propelled or towed units distribute and shape asphalt or concrete across variable widths, with screed systems controlling mat thickness and surface texture. Highway rehabilitation stimulus in the United States and Belt and Road corridor development in Central Asia concentrate demand for high-width pavers exceeding 8 meters, where surface quality warranties drive premium procurement.
- Graders:Articulated frame machines with moldboard attachments for fine grading and slope control.
- Rollers:Compaction equipment using vibratory, static, or pneumatic force to achieve specified density.
Pavers handle the majority of throughput in highway applications; excavators are climbing the fastest on share as electrification opens municipal market access.
Application:
Project scale and location dictate powertrain viability, with urban sites imposing noise and emission constraints that exclude diesel-only equipment from an expanding contract universe.
- Highway Construction:Interstate and national highway projects demand high-capacity pavers and tandem drum rollers capable of continuous operation across multi-kilometer segments. India's state road development authorities and China's provincial transport bureaus are tendering equipment-intensive contracts where machine availability clauses penalize downtime, favoring established fleet operators with maintenance infrastructure.
- Urban Development:Dense construction zones with noise ordinances and indoor emission restrictions are accelerating electric equipment deployment fastest. Municipal contractors in Germany's fragmented construction sector and China's tier-one cities are adopting battery-powered compact excavators and rollers to secure contracts with zero-emission mandates.
- Road Maintenance:Resurfacing, pothole repair, and shoulder restoration using smaller, more mobile equipment.
- Infrastructure Renovation:Bridge deck replacement, tunnel rehabilitation, and interchange upgrades in constrained workspaces.
Highway construction absorbs the largest equipment volumes; urban development is expanding most quickly as regulatory thresholds tighten.
Technology:
Powertrain selection now hinges on total cost of ownership calculations that weigh fuel price volatility, aftertreatment maintenance burdens, and residual value risk against capital premiums for electric alternatives.
- Electric:Battery-powered systems with onboard energy storage and regenerative capability, currently viable for compact excavators and rollers in short-radius applications. China's MIIT production quotas and SAMR certification fast-tracks are creating preferential market access for battery-electric machinery serving municipal contracts.
- Diesel:Compression-ignition engines with aftertreatment systems including diesel particulate filters and selective catalytic reduction. EPA Tier 4 Final compliance deadlines in the United States are forcing retirement waves among aging municipal fleets, generating replacement demand for cleaner diesel units where electric infrastructure remains absent.
- Hydraulic:Fluid power transmission systems for precise control of implement forces and speeds.
- Pneumatic:Compressed air systems for specialized compaction and material handling functions.
Diesel retains the dominant installed base; electric is gaining share fastest in urban geographies with charging infrastructure investment.
End User:
Procurement authority and contract structure shape equipment sourcing, with government agencies increasingly mandating emission standards that cascade through subcontractor tiers.
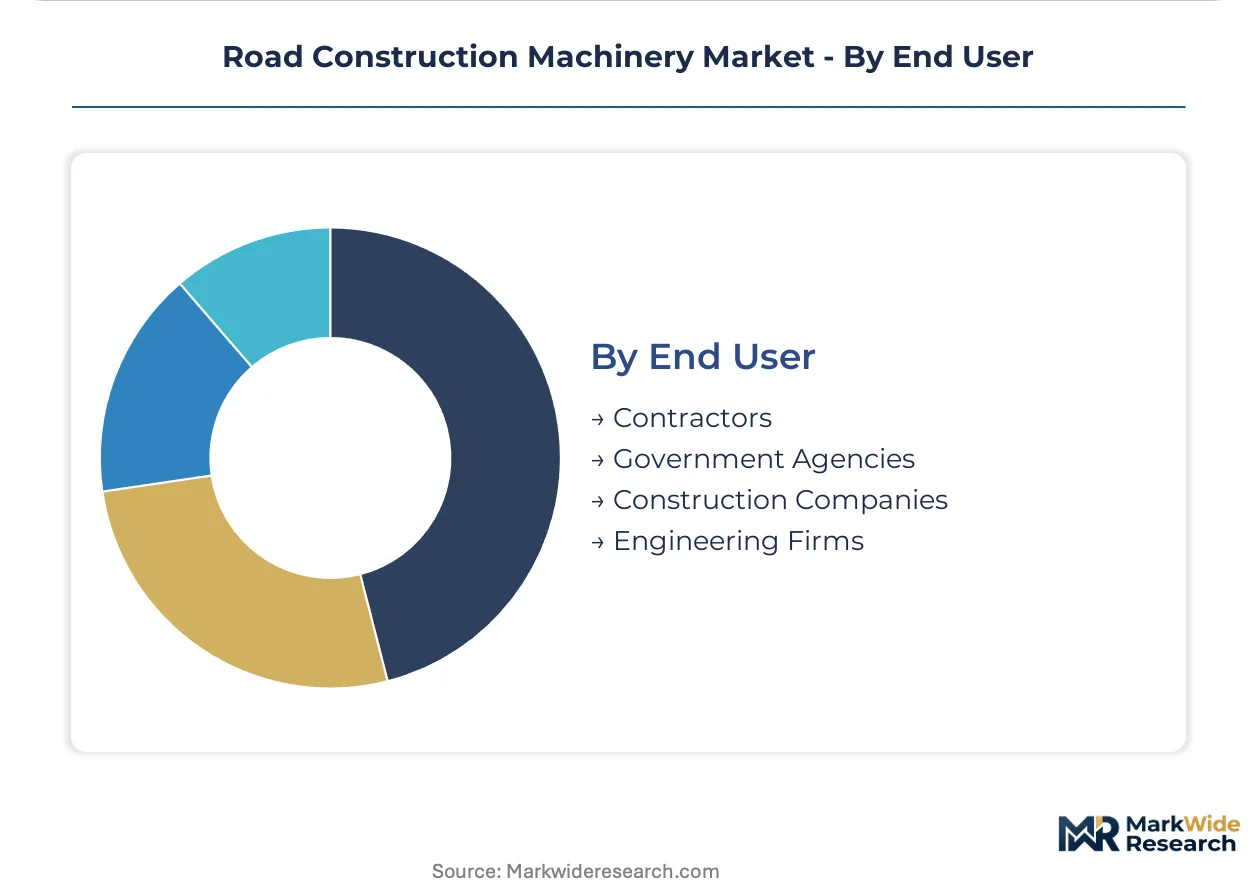
- Government Agencies:State and federal transport departments with fleet procurement authority and lease-back arrangements for highway projects. The United States Federal Highway Administration and India's National Highways Authority are expanding capital allocations for interstate refurbishment, directly lifting paver and roller demand through multi-year equipment contracts.
- Contractors:Private construction firms executing project work under tender or design-build arrangements. Equipment-as-a-service contracting is displacing capital purchase models among mid-sized contractors in Germany, with rental channel partners capturing aftermarket revenue through bundled maintenance and telematics subscriptions.
- Construction Companies:Integrated builders with captive equipment fleets and in-house maintenance capabilities.
- Engineering Firms:Design and project management consultancies specifying equipment performance requirements.
Government agencies direct the largest procurement volumes; contractors are shifting fastest toward service-based equipment access models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-engineered pavers and rollers to Central Asian Belt and Road corridor projects, while Chinese OEMs supply cost-optimized fleets to African and Southeast Asian infrastructure programs. Equipment trade flows concentrate on highway rehabilitation stimulus in mature economies and greenfield road networks in emerging markets.
United States
The Federal Highway Administration's Infrastructure Investment and Jobs Act allocations are accelerating interstate refurbishment contracts across Texas and California. EPA Tier 4 Final compliance deadlines are forcing municipal fleet retirements in the Midwest and Southeast. Equipment leasing volumes concentrate in Ohio and Pennsylvania where state transport departments tender multi-year maintenance contracts.
China
Provincial transport bureaus in Sichuan and Yunnan are expanding mountainous highway connectivity under western development programs. MIIT production quotas and SAMR certification fast-tracks are compressing diesel-only product windows for domestic manufacturers. Xuzhou and Changsha anchor equipment manufacturing clusters where battery-electric excavator output is scaling for municipal zero-emission mandates.
Germany
Bundesministerium für Verkehr und digitale Infrastruktur funding is channeling equipment procurement toward noise-restricted urban renewal zones in Berlin and Hamburg. EU Stage V regulations are elevating aftertreatment costs for diesel fleets, pushing rental houses toward electric alternatives. Bavaria's municipal construction sector leads adoption of equipment-as-a-service contracting with bundled telematics subscriptions.
India
The National Highways Authority of India is tendering equipment-intensive contracts for Delhi-Mumbai Expressway segments through Rajasthan and Gujarat. State pollution control boards in Maharashtra and Karnataka are tightening construction equipment emission norms for urban projects. Chennai and Pune manufacturing corridors are localizing component supply for cost-competitive domestic assembly.
Saudi Arabia
The Ministry of Transport's road network expansion under Vision 2030 is concentrating paver and roller deployment along Red Sea coastal corridors. SASO technical regulations are aligning import standards with EU emission benchmarks, filtering equipment sourcing toward Tier 4 Final-compliant suppliers. NEOM construction zones are specifying electric compact equipment for zero-emission site mandates.
Road Construction Machinery Market Competitive Landscape
Player mix skews toward integrated multinationals with captive financing arms and aftermarket parts networks. Market structure concentrates margin capture among three archetypes: full-line manufacturers with dealer density advantages, cost-engineered scale producers serving price-sensitive procurement, and electrification-first specialists targeting municipal zero-emission mandates. Dominant competitive moves include strategic partnerships for battery supply security and geographic expansion through localized assembly joint ventures.
Among full-line multinationals, Caterpillar Inc. and Volvo Construction Equipment exemplify archetypes built on integrated dealer networks and aftermarket recurring revenue. XCMG Group occupies a position representing cost-optimized scale manufacturing serving infrastructure corridors across Asia, Africa, and Latin America. These three anchors illustrate how competitive positioning diverges between premium-tier service bundling and volume-driven project economics.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| XCMG Group |
| SANY Group |
| Volvo Construction Equipment |
| Liebherr Group |
| John Deere |
| Wirtgen Group |
| JCB |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Chinese foundries producing hydraulic valve blocks and steel castings directly compresses margin floors for European and Japanese OEMs, while EPA Tier 4 Final aftertreatment complexity elevates price premiums for compliant engine modules. Scale asymmetries between integrated multinationals and regional assemblers concentrate pricing power among full-line manufacturers with captive parts networks.
Pricing Analysis
Next-generation electric powertrains command capital premiums of 40-60 percent above Tier 4 Final diesel equivalents, while prior-generation Stage IIIA equipment trades at distressed residuals in European rental auctions. Three-tier pricing structure across premium intelligent compaction systems, standard mechanical pavers, and economy towed rollers reflects after-sales service bundling and telematics integration depth. Cost compression in compact equipment tiers is intensifying because battery pack commoditization and Chinese motor-controller imports erode technology premiums. Municipal contractors with zero-emission mandates show lowest price sensitivity; mid-sized highway subcontractors in India and Southeast Asia exhibit highest elasticity.
Supply Chain Analysis
China, Germany, and Japan anchor precision manufacturing for hydraulic pumps, engine control modules, and vibratory drum assemblies. Steel plate and high-grade castings draw from integrated mills in Hebei and ThyssenKrupp operations; electronic components rest on semiconductor supply from Taiwan and South Korea. Single-source vulnerability concentrates in German-engineered screed control systems and Japanese variable-displacement pumps. Distribution runs through manufacturer-owned dealer networks in North America and Europe, shifting toward direct procurement by state transport departments in China and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-to-autonomy convergence is reconfiguring road construction machinery as a platform ecosystem where machine control data interoperability determines fleet lock-in. Equipment-as-a-service contracting and outcome-based utilization models accelerate this shift.
For Market Incumbents: Compound dealer network density with aftermarket parts dominance to capture recurring revenue from aging Tier 4 Final fleets facing aftertreatment failure cascades. Deepen backward integration into battery pack assembly and high-voltage motor production to defend margin position against Chinese electrification specialists with MIIT quota advantages. Prioritize certification investment for EU Stage V and emerging Indian CEA emission norms to maintain access to government procurement channels. For New Entrants and Emerging Players: Differentiate on battery-electric compact excavators and rollers for urban development contracts with zero-emission mandates in China's tier-one cities and Germany's noise-restricted zones. Target India's National Infrastructure Pipeline equipment leasing tenders where localized service requirements disadvantage distant incumbents. Pursue joint venture assembly in Chennai or Pune manufacturing corridors to satisfy domestic content thresholds and compress landed cost against imports. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electrification-first specialists with SAMR certification fast-tracks and proven municipal contract execution over legacy diesel-dependent portfolios. Acquisition target archetype: regional electric equipment assemblers with established battery supply agreements and state-level procurement relationships. Signal to watch is MIIT production quota allocation shifts and state pollution control board enforcement intensity in Indian urban corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL and BYD cell offtakes secure cost-competitive electric excavator production for municipal zero-emission contracts. |
| Telematics Platform Integration | GPS compaction density mapping merges with fleet management software to enable outcome-based equipment utilization contracting. |
| Localized Assembly Joint Venture | Pune and Chennai manufacturing partnerships satisfy Indian domestic content requirements for NHAI equipment leasing tenders. |
| Certification Fast-Track Investment | SAMR and CEA compliance acceleration opens preferential procurement access in Chinese and Indian urban development zones. |
| Aftermarket Service Network Expansion | High-voltage technician training centers address electrification skill gaps constraining battery-electric equipment deployment rates. |
Research Methodology
A standing panel of fleet procurement directors at state transport departments, aftermarket service managers at dealer networks, and plant engineers at hydraulic component foundries provided ongoing calibration across the study period. Primary interviews with OEM platform engineers and rental house operations heads combined with secondary validation from EPA compliance filings, EU Stage V homologation databases, and MIIT production quota disclosures. Bottom-up equipment shipment tracking and top-down infrastructure stimulus allocation analysis triangulated market sizing across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs against customs trade data for hydraulic component imports and provincial transport bureau tender announcements. The analytical framework modeled demand across product type, application, powertrain technology, and end-user procurement authority throughout the forecast period. CAGRs derived from equipment replacement cycle analysis, emission regulation compliance deadlines, and infrastructure investment pipeline visibility. Industry-specific inputs included Belt and Road corridor project databases and state-level road development authority capital expenditure plans.
Decision-makers should treat outputs as directional under assumptions of sustained infrastructure stimulus execution and emission regulation enforcement continuity; material deviation in steel price volatility or battery energy density improvement would warrant model refresh. Recalibration cycles align with material shifts in EPA and EU regulatory timelines and MIIT dual carbon policy implementation intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Colombia Metal Fabrication Equipment Market
Construction Equipment and Machinery
Wire Mesh Welding Machines Market
Construction Equipment and Machinery
Global Metal Embossing Machine Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Global Industrial Assembly Equipment Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
Computer Numerical Control Machines Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Construction Machinery Attachment Market
Construction Equipment and Machinery
Concrete Block Making Machines Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Universal Milling Machine Market
Construction Equipment and Machinery
Global Hydraulic Demolition Machine and Breaker Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Hydraulic Chainsaw Market