
 Architectural Acoustic Panels Market | 2026-2036
Architectural Acoustic Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Architectural Acoustic Panels Market Analysis
China is reconfiguring regional supply dynamics through expanded mineral wool and fiberglass manufacturing clusters serving domestic commercial construction. Saint-Gobain leverages integrated raw material access across multiple continents to sustain cost advantages in ceiling panel production. Armstrong World Industries anchors North American distribution through dedicated contractor channels and specification relationships with large architectural firms. Knauf Insulation competes on fire-rated panel systems that meet stringent building code requirements across European and Middle Eastern projects.
Architectural acoustic panels are engineered sound-absorbing assemblies, typically 25-50 mm thick, constructed from mineral wool, fiberglass, or recycled PET cores faced with acoustically transparent fabrics or perforated metal. These systems reduce reverberation time and improve speech intelligibility in enclosed spaces. Ceiling panels dominate installed value in commercial and educational buildings where suspended grid systems enable rapid retrofit without structural modification. Fabric-faced products command specification preference in healthcare and corporate interiors where aesthetic integration with interior design schemes drives selection criteria. Metal panels are gaining traction in transportation hubs and industrial facilities requiring washability and impact resistance alongside acoustic performance.
USGBC LEED v4.1, the WELL Building Standard, and the EU Green Deal framework collectively mandate low-emitting materials and enhanced indoor environmental quality that directly specify acoustic comfort metrics. Germany's DIN 18041 and the United Kingdom's BB93 standards codify minimum absorption coefficients for classrooms and open-plan offices, creating compliance-driven replacement cycles. Stakeholders must monitor evolving biophilic design requirements and embodied carbon disclosure rules that will reshape material selection criteria and supplier qualification protocols.
Market Dynamics
LEED v4.1 and the WELL Building Standard are compressing specification cycles by embedding acoustic comfort metrics directly into certification pathways, forcing manufacturers to pre-validate absorption coefficients and VOC emissions before design-stage engagement.
Growth Catalysts
- Workplace Noise Mandates:Germany's DIN 18041 standard mandates minimum absorption coefficients for open-plan offices, triggering systematic retrofit waves across existing commercial stock.
- Healthcare Construction:Hospital expansion projects in the United States specify fabric-faced panels to meet HIPAA speech privacy requirements in patient consultation zones.
- Recycled PET Core Technology:Circular material processing advances enable post-consumer plastic conversion into high-performance acoustic cores that satisfy EU Green Deal embodied carbon thresholds.
Market Restraints
- Mineral Wool Input Volatility:Basalt and slag supply disruptions from concentrated European smelter operations create raw material cost instability for dense-core panel production.
- Fire-Rating Compliance Friction:Divergent testing protocols between ASTM E84 in North America and EN 13501-1 in Europe force dual certification investments that extend product launch timelines.
- Metal Panel Substitution:Perforated aluminum systems with integrated acoustic backing are capturing specification share in transportation hubs where washability requirements dominate.
Strategic Opportunities
- Biophilic Integration:Living moss and wood-wool composite panels align with WELL Building Standard biophilic design credits, opening premium positioning in corporate wellness-focused developments.
- Modular Retrofit Channels:Direct-to-contractor digital platforms are bypassing traditional distribution layers in United Kingdom commercial refurbishment projects.
- CSRD Disclosure Tailwinds:Corporate Sustainability Reporting Directive requirements are elevating embodied carbon transparency as a procurement filter across European Union public buildings.
Industry Challenges
- Acoustic Engineering Talent Scarcity:Shortages of certified acousticians capable of translating reverberation modeling into specification-ready assemblies are extending project design phases.
- Legacy Grid Integration Complexity:Suspended ceiling retrofits in 1980s-era buildings require structural load assessments that delay panel installation and increase project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Architectural Acoustic Panels Market |
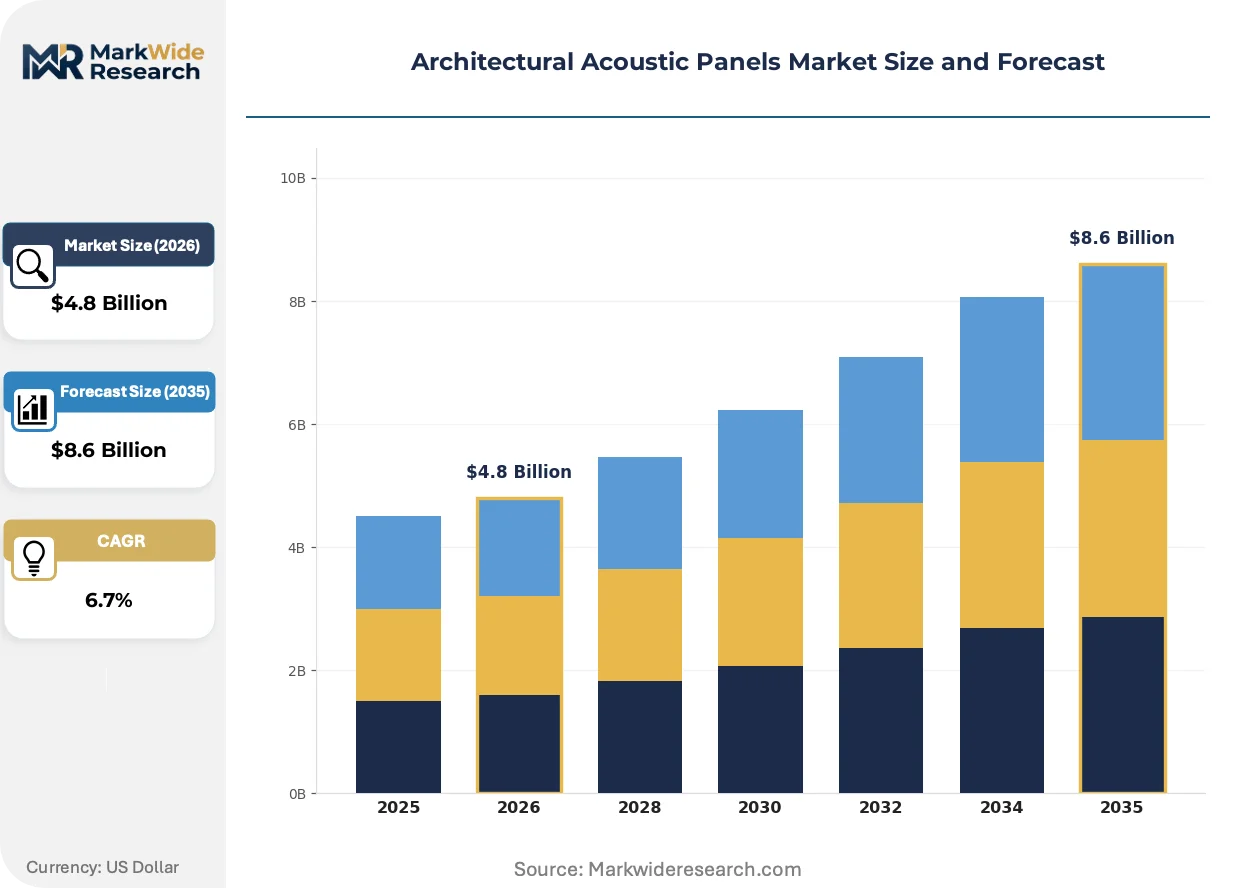
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Panels, Ceiling Panels, Baffles, Diffusers Material: Wood, Fabric, Foam, Metal End User: Commercial, Residential, Educational, Healthcare Installation Type: Suspended, Wall-mounted, Freestanding, Integrated |
| Companies Covered | Saint-Gobain, Armstrong World Industries, Knauf Insulation, Owens Corning, Rockfon, USG Corporation, Rockwool International, Kingspan Group, Ecophon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Architectural Acoustic Panels Market Emerging Trajectories
Digital specification tools and predictive acoustic modeling are compressing the design-to-installation timeline while elevating performance transparency as a competitive differentiator in commercial tender processes.
Micro-perforated metal facings with tuned cavity depths are virtualizing the traditional fabric-wrapped panel category by delivering equivalent absorption coefficients with enhanced durability and cleanability. Transportation authorities in Germany and the Netherlands are specifying these systems for rail station concourses where maintenance access is constrained. The technology is virtualizing specification conventions that previously prioritized aesthetic softness over lifecycle performance metrics.
The EU Green Deal framework is tightening embodied carbon disclosure requirements for construction products sold across member states, compelling manufacturers to publish Environmental Product Declarations with third-party verification. Panel producers with integrated recycling streams are capturing specification preference in French and Dutch public procurement. The regulation is accelerating material transparency as a gating factor for large-scale commercial and institutional projects.
Building owners are unbundling acoustic performance verification from general contractor scope, engaging independent commissioning agents to validate reverberation time post-installation. This pattern is displacing reliance on manufacturer-published absorption data in United States healthcare and education verticals. The shift is most pronounced in California and New York where municipal green building ordinances reference specific acoustic comfort thresholds.
Architectural Acoustic Panels Market Segmentation
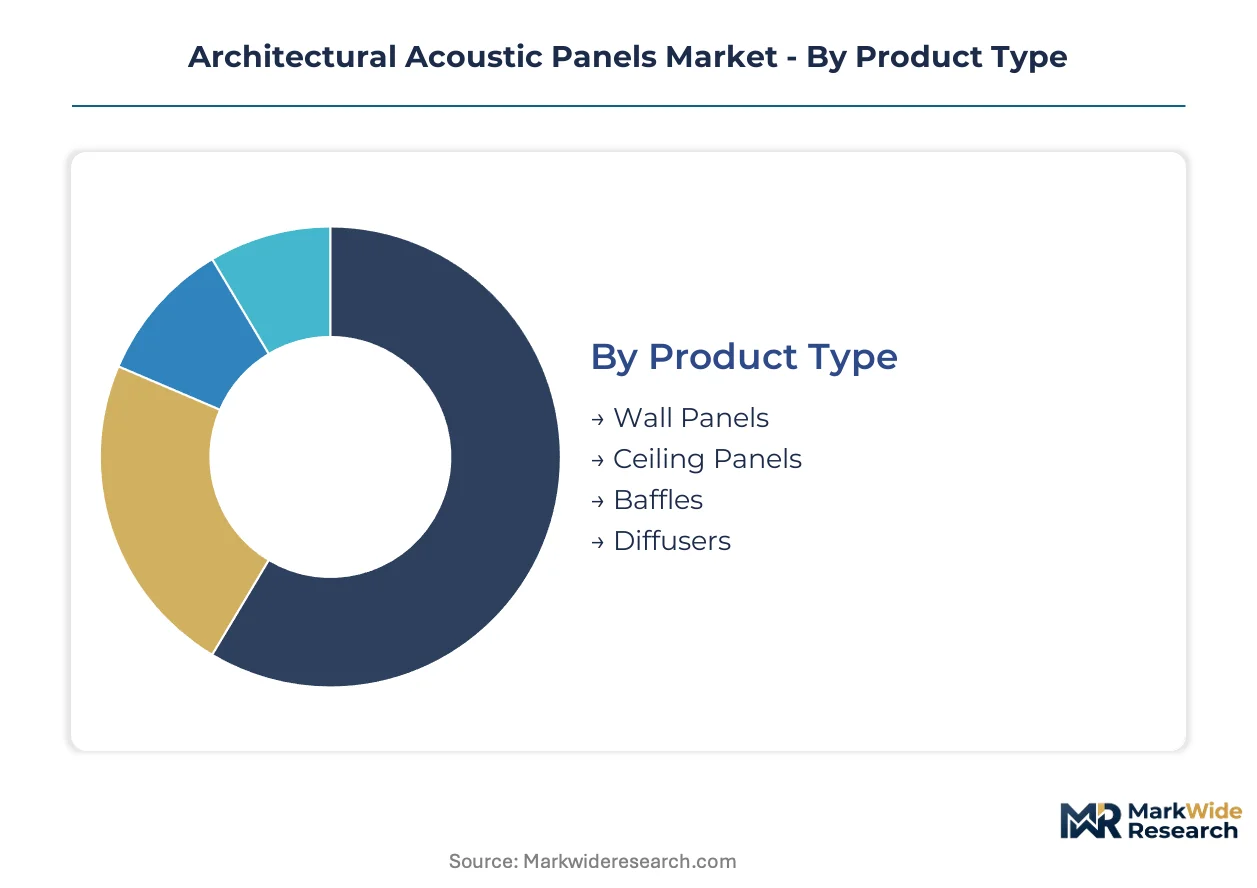
Architectural acoustic panels serve distinct performance requirements across building typologies, with specification criteria varying sharply between speech privacy mandates in healthcare and aesthetic integration demands in corporate interiors. Segmentation reveals how material selection and installation method directly determine project eligibility for LEED v4.1 and WELL Building Standard certification pathways.
Product Type:
Product configuration spans surface-mounted, overhead, and spatial acoustic interventions, each demanding different structural support and engineering validation.
- Ceiling Panels:Suspended grid-mounted assemblies, typically 600x600mm or 600x1200mm modules, dominate commercial retrofits where rapid installation without structural modification accelerates project timelines. DIN 18041 compliance in Germany drives systematic replacement of mineral wool ceiling stock in open-plan offices across Frankfurt and Munich.
- Wall Panels:Fabric-faced or perforated metal facings mounted on vertical substrates address reverberation in spaces where ceiling treatments prove insufficient. HIPAA speech privacy requirements in United States hospital consultation rooms specify wall-mounted absorption coefficients above 0.80 across the 500-2000 Hz octave bands.
- Baffles:Vertically suspended linear elements create absorption in high-ceiling atriums and transportation hubs where wall and ceiling surfaces are limited. Dutch rail station concourses specify aluminum-framed baffles with integrated lighting channels.
- Diffusers:Geometrically profiled surfaces scatter sound energy without absorption loss, preserving acoustic liveliness in performance venues and recording studios. JIS standards in Japan codify diffusion coefficient minimums for broadcast facility certification.
Established volume favors ceiling panels; emerging adoption favors baffles in transportation infrastructure.
Material:
Material selection balances fire performance, embodied carbon disclosure, and cleanability requirements that vary by jurisdiction and building code.
- Mineral Wool:Dense basalt or slag-based cores deliver Class A fire ratings and broadband absorption across 125-4000 Hz. EU Green Deal embodied carbon thresholds elevate specification preference for panels with recycled slag content in French public procurement.
- Fabric:Acoustically transparent textiles over fiberglass or recycled PET cores enable color-matched interior design integration. Corporate wellness projects in London and New York specify fabric-faced panels to satisfy WELL Building Standard biophilic design credits.
- Metal:Perforated aluminum or steel facings with tuned cavity depths provide washability and impact resistance. German transportation authorities specify micro-perforated metal systems for rail station concourses where maintenance access is constrained.
- Foam:Open-cell polyurethane or melamine cores offer lightweight installation in temporary or weight-sensitive applications. Fire rating limitations restrict foam to non-regulated spaces in most European jurisdictions under EN 13501-1.
Mineral wool retains specification dominance in code-driven verticals; metal is climbing the fastest in transportation and industrial segments.
End User:
End-use verticals impose distinct acoustic performance thresholds, with healthcare and education representing compliance-mandated replacement cycles.
- Commercial:Open-plan offices and corporate headquarters prioritize speech privacy and employee wellbeing metrics. LEED v4.1 acoustic comfort credits compress specification cycles by embedding absorption coefficient requirements directly into certification pathways.
- Healthcare:Hospitals and clinics demand HIPAA-compliant speech privacy and infection-control cleanability. United States hospital expansion projects specify fabric-faced panels with antimicrobial treatments in patient consultation zones.
- Educational:Classrooms and lecture halls require reverberation control for speech intelligibility under BB93 in the United Kingdom and DIN 18041 in Germany.
- Residential:Multi-family housing and home theaters represent discretionary specification with limited regulatory drivers. Premium positioning targets high-net-worth renovations in urban centers.
Healthcare and education generate compliance-driven replacement demand; residential remains price-sensitive with slower specification velocity.
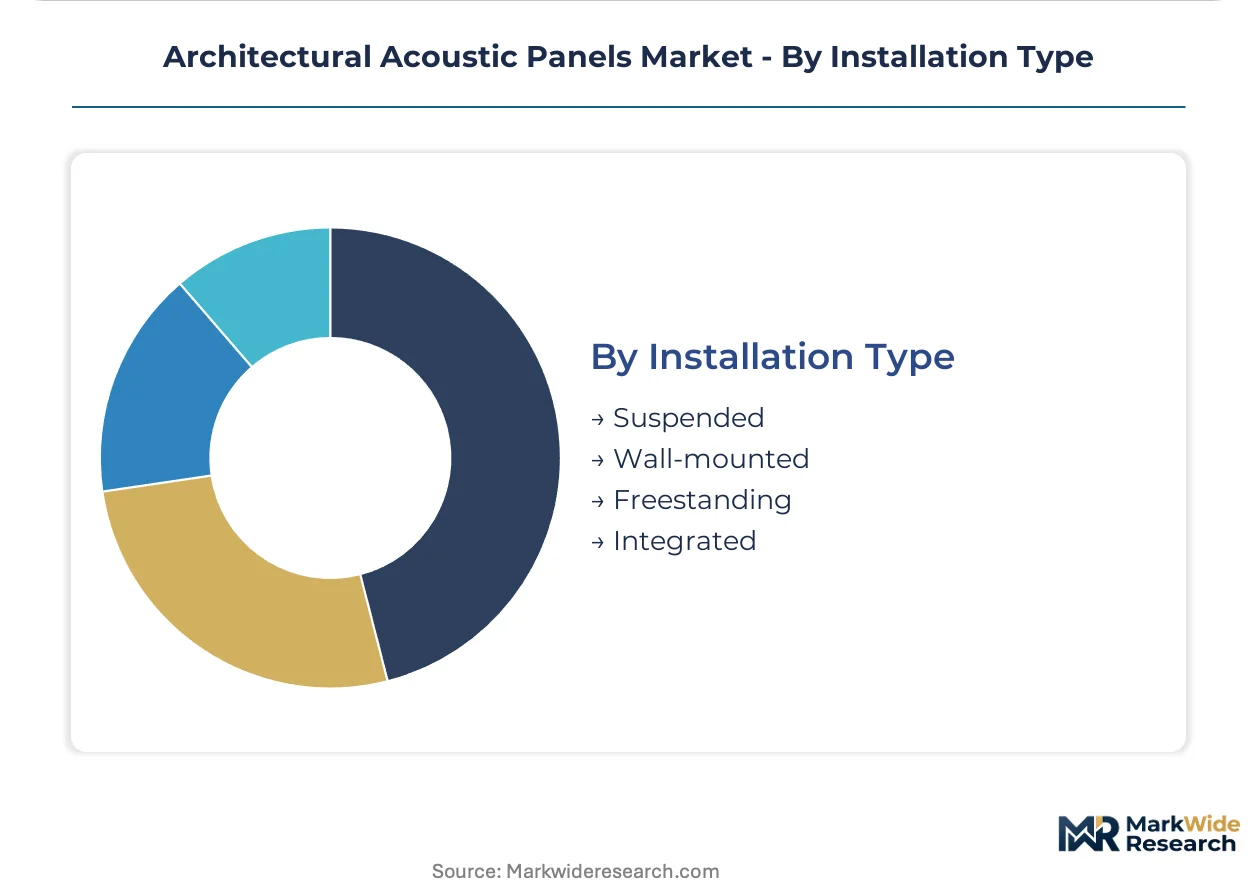
Installation Type:
Installation method determines project feasibility in retrofit versus new construction contexts, with structural load and access constraints governing selection.
- Suspended:Grid-mounted ceiling systems enable rapid retrofit without structural modification. United Kingdom commercial refurbishment projects leverage suspended installation for speed-to-occupancy advantages.
- Wall-mounted:Direct or track-mounted vertical installation addresses spaces where ceiling intervention is impractical. 1980s-era buildings in Germany require structural load assessments that delay wall-mounted panel installation.
- Freestanding:Modular partitions and acoustic furniture provide reconfigurable absorption in agile workplaces. WELL Building Standard flexibility credits support specification in corporate wellness developments.
- Integrated:Built-in architectural elements such as ceiling clouds or wall systems specified during design development. Premium positioning in signature commercial projects justifies extended lead times.
Suspended installation captures retrofit volume; integrated systems gain share in ground-up developments with extended design phases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DIN 18041 workplace noise mandates in Germany anchor specification demand across Europe, while LEED v4.1 acoustic comfort credits compress procurement cycles in North American commercial construction. Construction activity clusters in dense urban corridors where retrofit volume intersects with stringent indoor environmental quality regulations.
Germany
Frankfurt and Munich office stock undergoes systematic ceiling panel replacement to satisfy DIN 18041 absorption coefficient minimums for open-plan workspaces. The EU Green Deal framework elevates embodied carbon disclosure as a procurement filter for federal public buildings. Mineral wool manufacturing concentrates in North Rhine-Westphalia, where recycled slag integration meets circular material quotas.
United States
Hospital expansion projects in California and New York specify fabric-faced panels to achieve HIPAA-compliant speech privacy in patient consultation zones. Municipal green building ordinances in these states reference specific acoustic comfort thresholds that displace reliance on manufacturer-published data. Independent commissioning agents now validate reverberation time post-installation across healthcare and education verticals.
United Kingdom
BB93 standards codify minimum absorption coefficients for classrooms and lecture halls, triggering compliance-driven replacement cycles in aging educational infrastructure. Direct-to-contractor digital platforms bypass traditional distribution layers in commercial refurbishment projects across London and the Southeast. WELL Building Standard certification drives specification of biophilic-integrated panels in corporate wellness developments.
China
Expanded mineral wool and fiberglass manufacturing clusters in the Yangtze River Delta serve domestic commercial construction demand. MIIT industrial policy supports acoustic material production scale-up alongside green building material certification schemes. Urban rail station construction in Shanghai and Beijing specifies metal-faced systems where washability and durability dominate selection criteria.
Netherlands
Rail station concourse projects specify aluminum-framed baffles with integrated lighting channels, addressing high-ceiling absorption requirements where wall and ceiling surfaces are limited. CSRD disclosure requirements elevate embodied carbon transparency as a procurement filter for public buildings. Rotterdam and Amsterdam commercial developments prioritize modular retrofit channels to accelerate speed-to-occupancy.
Architectural Acoustic Panels Market Vendor Landscape
Capability concentration sits with integrated raw material players; scale advantage sits with distribution-anchored specialists. The vendor base organizes around three archetypes: mineral wool producers with captive basalt supply, fabric-faced panel specialists with specification relationships, and metal system fabricators with transportation infrastructure focus. Competitive moves center on dual certification investments for ASTM E84 and EN 13501-1 compliance, alongside backward integration into recycled PET core processing.
Within the integrated-material tier, Saint-Gobain leverages multi-continent raw material access to sustain cost advantages in ceiling panel production. Armstrong World Industries anchors North American distribution through dedicated contractor channels and specification relationships with large architectural firms. Knauf Insulation occupies a position in fire-rated panel systems that meet stringent building code requirements across European and Middle Eastern projects.
| Leading Market Players |
|---|
| Saint-Gobain |
| Armstrong World Industries |
| Knauf Insulation |
| Owens Corning |
| Rockfon |
| USG Corporation |
| Rockwool International |
| Kingspan Group |
| Ecophon |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp barge freight corridors transmit basalt and slag cost volatility directly into mineral wool panel pricing, compressing margins for producers without captive smelter access while amplifying price spreads between integrated and non-integrated suppliers serving German and Dutch specification markets.
Pricing Analysis
Price spreads between German-manufactured and Chinese-imported ceiling panels have widened as EU Green Deal embodied carbon disclosure requirements add compliance premiums to European-sourced product. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and fire-rating tier, with DIN 18041-compliant systems commanding sustained premiums. Cost compression in economy-grade mineral wool panels is intensifying because Yangtze River Delta capacity expansion feeds spot-market oversupply. Healthcare and education verticals show lowest price sensitivity due to HIPAA and BB93 compliance mandates; residential retrofit channels exhibit highest sensitivity with specification driven by contractor bid competition.
Supply Chain Analysis
Extended payment terms from Dutch and German rail infrastructure contractors now stretch to 90-120 days, forcing mid-tier panel fabricators toward supply-chain finance facilities anchored by receivables from Saint-Gobain and Armstrong distribution networks. Raw material sourcing concentrates in Germany, China, and Belgium, with dense-core mineral wool production drawing from North Rhine-Westphalia slag processing and Yangtze River Delta fiberglass mat manufacturing. Supply chain risk centers on single-source vulnerability for acoustically transparent fabric facings sourced from concentrated Italian textile producers. Distribution runs through specification-driven contractor channels in commercial construction, with direct-to-installer digital platforms gaining share in United Kingdom refurbishment markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent acoustic panel manufacturers face sustained substitution pressure from micro-perforated metal systems capturing transportation infrastructure specifications, requiring defensive repositioning around certification-anchored verticals where fabric-faced products retain irreplaceable performance attributes.
For Market Incumbents: Pre-empt metal panel substitution in healthcare and education verticals by accelerating antimicrobial fabric treatment R&D and embedding independent acoustic commissioning into standard service bundles. Secure DIN 18041 and BB93 pre-certification for recycled PET core lines before EU Green Deal disclosure rules harden procurement filters. Backward integration into basalt smelter partnerships or slag recycling streams defends margin position against mineral wool input volatility from European metallurgical supply concentration.
For New Entrants and Emerging Players: Establish a beachhead in modular freestanding acoustic furniture for agile workplace retrofit, where WELL Building Standard flexibility credits create specification velocity without fire-rating compliance friction. Target Netherlands and United Kingdom commercial refurbishment through direct-to-contractor digital platforms that bypass Armstrong and Saint-Gobain distribution layers. Lead with biophilic-integrated wood-wool or living moss systems that unlock premium positioning in corporate wellness developments ahead of incumbent product line extensions.
For Investors and Strategic Acquirers: Carve-out targets emerge from building materials conglomerates seeking to divest non-core acoustic panel divisions amid portfolio rationalization pressures. Long-term viability hinges on exposure to compliance-mandated replacement cycles in healthcare and education rather than discretionary commercial retrofit demand. Watch CSRD disclosure implementation velocity as the signal indicating when embodied carbon transparency becomes a gating factor large enough to reshape supplier qualification protocols and consolidation incentives.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | ASTM E84 and EN 13501-1 compliance unlocks transatlantic project eligibility for ceiling panel systems. |
| Recycled PET Core Processing Scale-Up | Post-consumer plastic conversion capability satisfies EU Green Deal thresholds for French public procurement. |
| Direct-to-Contractor Platform Launch | Digital bypass of traditional distribution accelerates speed-to-occupancy in United Kingdom commercial refurbishment. |
| Biophilic Product Line Extension | Living moss and wood-wool composites capture WELL Building Standard credits in corporate wellness developments. |
| Independent Commissioning Service Integration | Third-party reverberation validation displaces manufacturer data reliance in California and New York healthcare verticals. |
Methodological Framework
The analysis maps ceiling panel, wall panel, baffle, and diffuser sub-sectors, each validated through specification director interviews at architectural firms, procurement manager conversations at healthcare systems, contractor channel interviews, and regulatory affairs consultations at major manufacturers. Primary fieldwork combined with secondary validation from DIN standards documentation, USGBC LEED v4.1 technical guides, EU Green Deal construction product regulations, and trade flow data from German and Chinese customs authorities. Bottom-up installation volume estimates triangulated against top-down construction spending allocations across commercial, healthcare, and education verticals.
Assumptions held fixed include continued DIN 18041 enforcement intensity in Germany, sustained HIPAA speech privacy interpretation in United States healthcare, and EU Green Deal embodied carbon disclosure implementation trajectory. The analytical framework models product type, material composition, end-use vertical, and installation method dimensions across the projection horizon. CAGRs derived from segment-level demand elasticity analysis against construction output forecasts and regulatory compliance cycle timing. Industry-specific inputs include reverberation time modeling adoption rates and independent commissioning agent penetration in specification validation.
Sensitivities concentrate around mineral wool input cost volatility, divergent fire-rating testing protocol harmonization timelines, and metal panel substitution velocity in transportation infrastructure. Forecasts reflect these assumptions with explicit acknowledgment that regulatory enforcement intensity, raw material supply disruptions, or breakthroughs in alternative acoustic technologies would prompt revision. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Builder Hardware Market
Building & Construction Materials
China Oriented Strand Board Market
Building & Construction Materials
North America Steel Rebar Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Italy Prefab Wood Buildings Market
Building & Construction Materials
Metal Roofing Market
Building & Construction Materials
Branched Reinforced Fittings Market
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
Precast Concrete Market
Building & Construction Materials
Europe Geogrids Market
Building & Construction Materials
US Plywood Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
Glass Railing System Market
Building & Construction Materials
Asia-Pacific Particle Board Market
Building & Construction Materials
Roofing Shingles Market