
 Fire-Retardant Treated Wood Market | 2026-2036
Fire-Retardant Treated Wood Market Size, Share, and Industry Trends Forecast 2026-2036
Fire-Retardant Treated Wood Market Analysis
Consolidation among commercial contractors is recalibrating procurement volumes for fire-retardant treated wood across North America. Koppers leverages its integrated treatment chemical supply chain to sustain cost advantages in pressure-treated lumber. Hoover Treated Wood Products anchors its position through specialized distribution partnerships with large-scale builders. Lonza differentiates via technology leadership in halogen-free flame retardant formulations for coated wood applications.
Fire-retardant treated wood comprises lumber and engineered wood products impregnated or surface-coated with chemical formulations that reduce flame spread and smoke development, typically meeting ASTM E84 Class A or Class B surface burning characteristics. Its primary commercial purpose is to extend structural integrity during fire events in multi-story buildings and critical infrastructure. Pressure-treated lumber dominates volume flows due to its cost efficiency in residential and commercial framing, while fire-retardant plywood commands premium positioning in industrial facilities where code compliance demands higher fire ratings. Solid wood segments occupy niche applications in architectural millwork where builders prioritize natural aesthetics alongside safety certification.
The National Fire Protection Association (NFPA) and International Code Council (ICC) standards shape product testing requirements and market access across the United States, while EPA regulations govern chemical discharge from treatment facilities. California's Office of the State Fire Marshal maintains additional approval listings that filter which formulations enter wildland-urban interface construction zones. Stakeholders must monitor evolving chemical restriction proposals at the state level and assess backward integration into treatment chemical production as a hedge against supply concentration.
Market Dynamics
Consolidation among North American commercial contractors is compressing procurement timelines and concentrating volume flows toward suppliers with integrated treatment chemical capabilities. This structural shift is forcing mid-scale treaters to secure backward integration or exit pressure-treated lumber segments entirely.
Growth Catalysts
- ICC-ES Evaluation Reports:Updated acceptance criteria for fire-retardant wood in Type I and Type II construction are expanding addressable square footage in high-rise commercial developments across the United States.
- Wildland-urban interface construction:California's Chapter 7A building standards mandate ignition-resistant materials in designated fire hazard severity zones, creating dedicated demand for exterior-grade treated lumber.
- Cross-laminated timber adoption:Mass timber building codes in Washington, Oregon, and British Columbia are incorporating fire-retardant treatment requirements for exposed structural elements in multi-story projects.
Market Restraints
- Borate price volatility:Concentrated mining operations in Turkey and the United States create input cost instability for pressure-treatment formulations dependent on disodium octaborate tetrahydrate.
- Leaching performance limitations:Water-soluble retardants face technical barriers in exterior above-ground applications where rainfall exposure degrades fire performance ratings over service life.
- California Proposition 65 litigation exposure:Private enforcement actions targeting formaldehyde trace contaminants in treated wood products generate compliance defense costs and formulation reformulation expenses.
Strategic Opportunities
- Texas Hill Country wildfire corridor:Underpenetrated residential construction zones outside Austin and San Antonio are adopting California-style ignition-resistant material mandates, opening new geographic white space.
- Intumescent coating convergence:Combination systems pairing pressure-impregnated substrates with factory-applied intumescent topcoats are enabling Class A ratings in architectural millwork previously restricted to non-combustible materials.
- Direct-to-contractor digital platforms:Specialized e-procurement channels serving mid-size commercial builders are disintermediating traditional two-step distribution in treated wood categories.
Industry Challenges
- Certification timeline compression:California Office of the State Fire Marshal approval cycles for new formulations now exceed 18 months, delaying product commercialization and freezing R&D return timelines.
- Treatment facility capex intensity:EPA NPDES permit compliance for aqueous discharge and air emissions control requires seven-figure capital deployment for greenfield pressure-treatment plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire-Retardant Treated Wood Market |
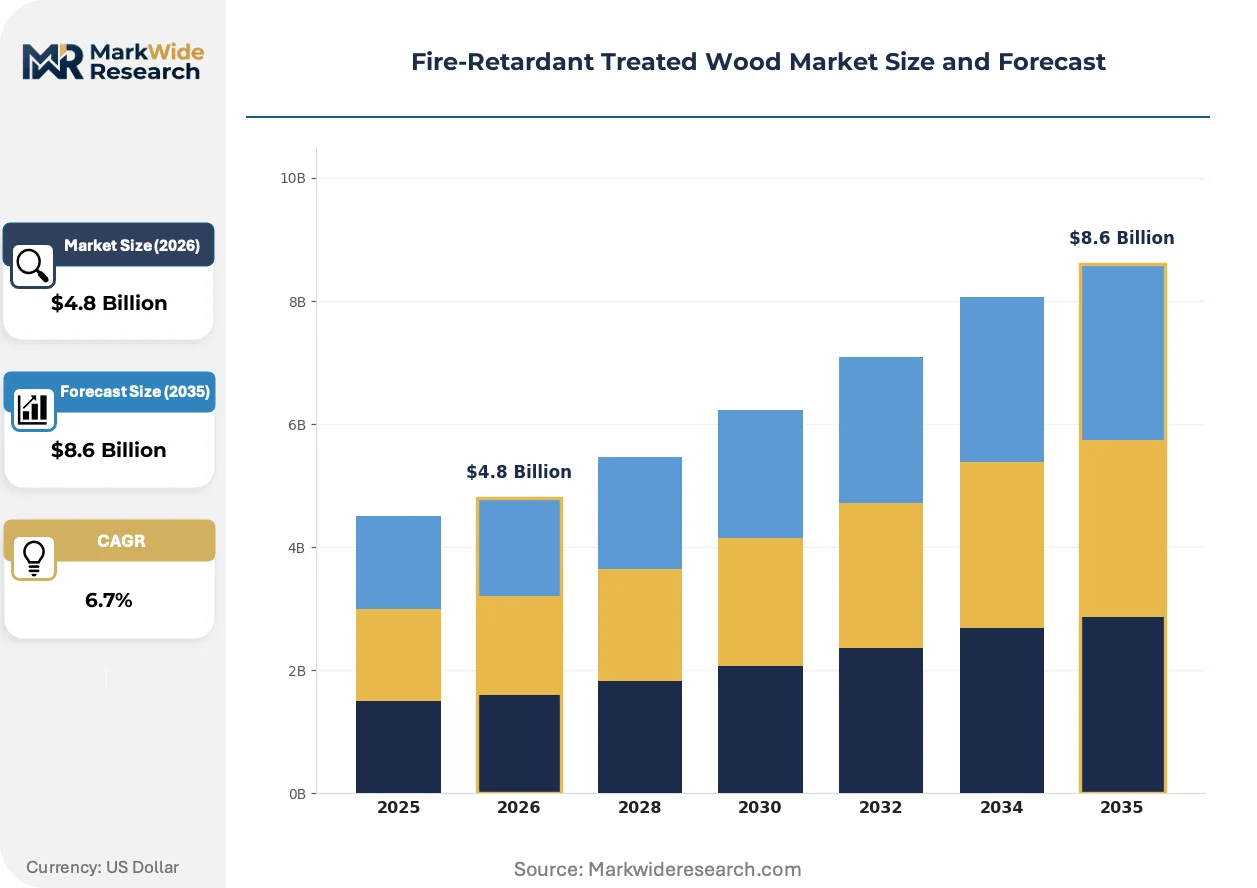
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Treated Lumber, Coated Wood, Fire-Retardant Plywood, Solid Wood Application: Commercial Buildings, Residential Structures, Industrial Facilities, Decking End User: Contractors, Architects, Builders, Retailers Distribution Channel: Direct Sales, Wholesale, Online Retail, Partnerships |
| Companies Covered | Viance, Koppers, Hoover Treated Wood Products, Lonza, Flameproof Companies, Weyerhaeuser, Foreco, Arxada, Metsä Wood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire-Retardant Treated Wood Market Emerging Trajectories
Automation and environmental chemistry are converging to reshape fire-retardant wood manufacturing. Treatment facilities are deploying sensor-driven process control while reformulating around halogen-free chemistries to meet tightening emissions standards.
Automated pressure-treatment monitoring systems are automating chemical penetration depth verification and retention uniformity across lumber batches. Commercial treaters in the Pacific Northwest are deploying these platforms to reduce manual inspection labor and compress cycle times. The technology is automating quality assurance protocols that previously required destructive sampling, enabling real-time process adjustments that reduce chemical over-treatment waste.
EPA TSCA Section 6 restrictions on persistent, bioaccumulative, and toxic substances are accelerating phase-outs of legacy brominated formulations in coated wood applications. Industrial facility maintenance contracts now specify halogen-free alternatives to preempt regulatory exposure. The policy shift is concentrating R&D investment in phosphorus-nitrogen intumescent systems for plywood and oriented strand board sheathing categories.
Specification-driven procurement is consolidating purchasing authority among national commercial builders with dedicated fire safety engineering staff. Regional distributors serving mid-market contractors are losing specification influence to manufacturer-direct technical sales teams. The pattern is most pronounced in Texas and Florida where large-scale multifamily developers maintain centralized material approval databases.
Fire-Retardant Treated Wood Market Segmentation
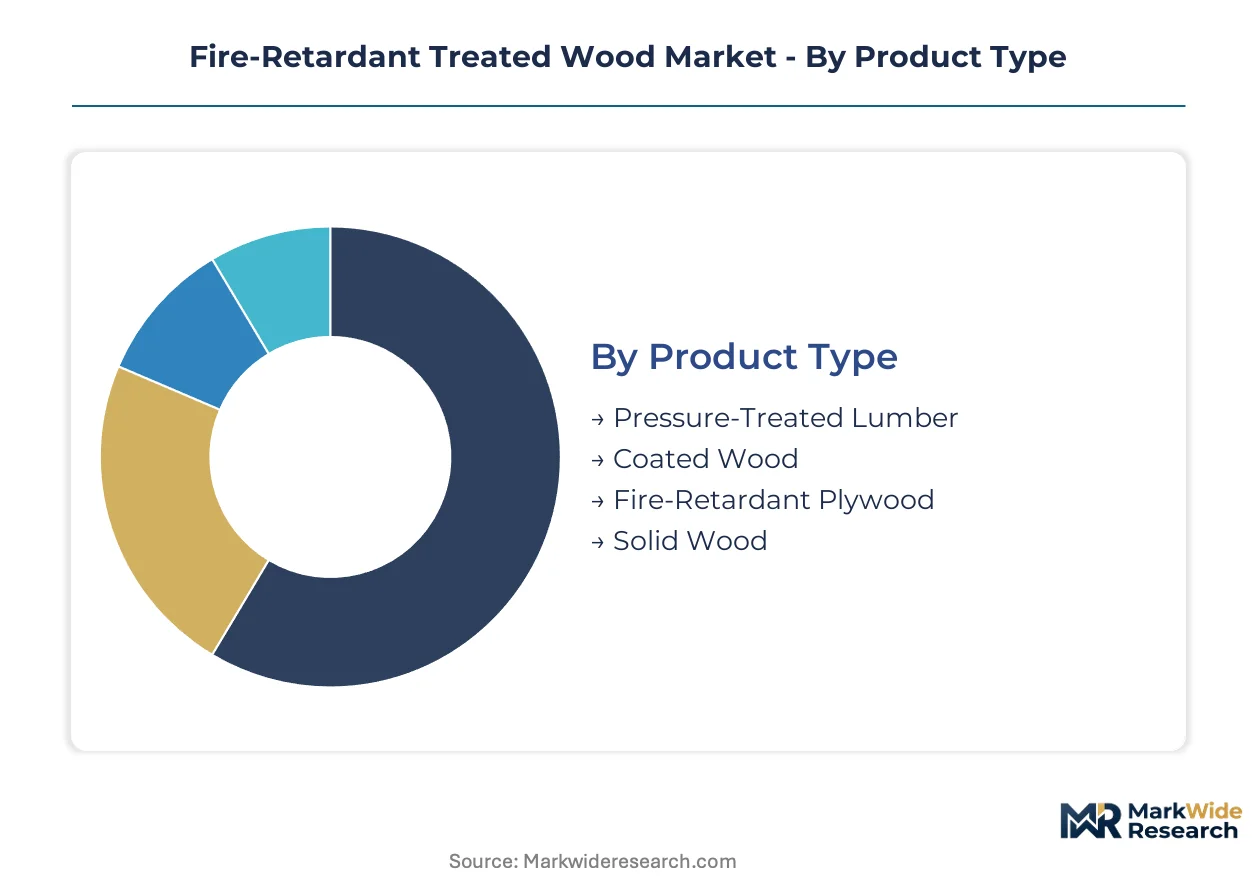
Fire-retardant treated wood procurement hinges on code compliance tiers, construction type, and supply chain access. Specification authority varies sharply across buyer categories, reshaping how manufacturers configure product portfolios and channel investments.
Product Type:
Buyers select pressure-treated lumber for cost efficiency in high-volume framing, while premium projects demand specialized formulations with enhanced durability ratings.
- Pressure-Treated Lumber:Lumber impregnated with aqueous chemical solutions under vacuum-pressure cycles to achieve specified retention levels per ASTM D5516. Demand concentrates in Texas and California multifamily construction where Type V-A building codes mandate treated framing in five-over-one podium structures. Contractors prioritize this segment for its compatibility with standard fastening systems and established distributor availability.
- Coated Wood:Surface-applied intumescent or non-intumescent coatings delivering Class A flame spread ratings on architectural millwork and exposed structural elements. Growth tilts toward Washington and Oregon mass timber projects where code officials require supplemental fire protection on cross-laminated timber surfaces visible in occupied spaces.
- Fire-Retardant Plywood:Engineered panels treated during manufacturing or post-manufacturing for roof and floor sheathing in industrial facilities requiring extended structural integrity during fire events.
- Solid Wood:Dimension lumber and heavy timber members treated for specialized applications including exterior columns and decorative beams in hospitality and institutional architecture.
Volume sits with pressure-treated lumber; growth tilts toward coated wood.
Application:
Code stringency varies by occupancy classification, with assembly and educational buildings facing the most rigorous fire performance mandates.
- Commercial Buildings:Office, retail, and hospitality structures requiring ASTM E84 Class A or Class B ratings on interior finish and structural elements per IBC Chapter 14. Demand clusters in California high-rise podium construction where Chapter 7A wildland-urban interface provisions overlap with standard commercial codes.
- Residential Structures:Single-family and multifamily housing in wildfire-prone zones specifying ignition-resistant materials for exterior walls and eaves. Texas Hill Country jurisdictions outside Austin are adopting California-style mandates, expanding addressable geography for exterior-grade treated lumber.
- Industrial Facilities:Manufacturing plants and warehouses requiring extended fire resistance ratings for insurance compliance and OSHA safety protocols.
- Decking:Exterior walking surfaces in wildland-urban interface zones where California Building Code Section R337 mandates ignition-resistant decking materials.
Commercial buildings absorb the highest treatment chemical volumes; residential structures in wildfire corridors are climbing the fastest.
End User:
Specification authority determines margin capture, with architects controlling premium product selection and contractors driving commodity volume.
- Contractors:Commercial general contractors and framing subcontractors purchasing treated lumber through established distribution relationships. National builders with centralized procurement departments are consolidating specification authority away from regional distributors.
- Architects:Design professionals selecting coated wood and specialty treatments for exposed structural elements and millwork where aesthetic performance intersects with code compliance.
- Builders:Production homebuilders and custom residential developers sourcing pressure-treated lumber for framing and sheathing in code-compliant assemblies.
- Retailers:Lumber yards and home improvement centers stocking commodity treated wood for repair, remodel, and do-it-yourself exterior projects.
Contractors move the most volume; architects command the steepest price premiums.
Distribution Channel:
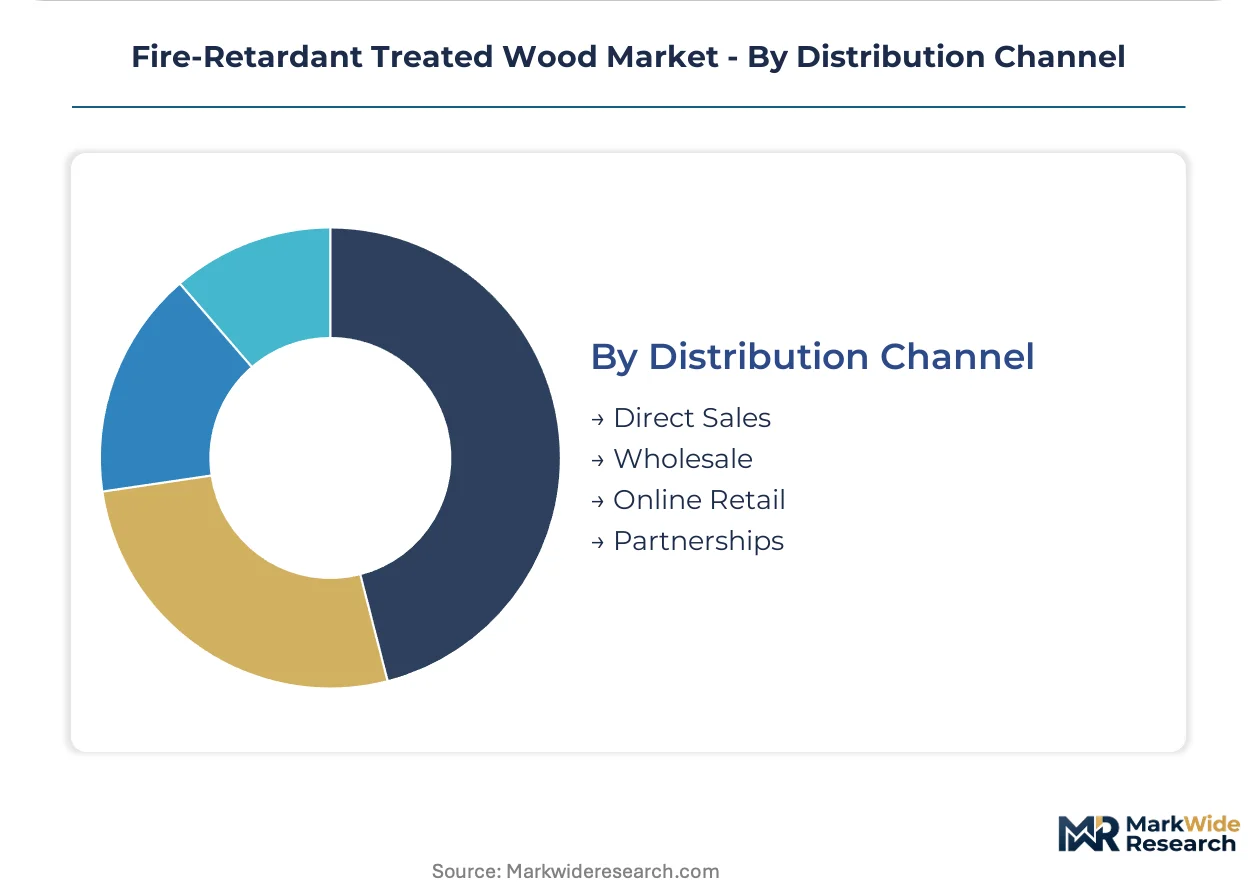
Channel selection reflects project scale and specification complexity, with large developments bypassing traditional two-step distribution.
- Direct Sales:Manufacturer-direct relationships with national commercial builders and mass timber general contractors requiring technical support and custom formulation approval. Direct channels are gaining share in Texas and Florida where large multifamily developers maintain centralized material databases.
- Wholesale:Two-step distribution through regional lumber yards serving mid-market contractors and local builders with standard pressure-treated products and established delivery logistics.
- Online Retail:Digital platforms offering treated wood for repair, remodel, and small-scale construction projects with freight delivery to jobsites or residential addresses.
- Partnerships:Strategic alliances between treaters and engineered wood manufacturers integrating fire-retardant requirements into cross-laminated timber and glulam product lines.
Wholesale retains volume dominance; direct sales are gaining share fastest in commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial construction activity concentrates in the United States, where wildfire-prone jurisdictions and stringent building codes generate the highest treatment chemical volumes. Secondary demand clusters in Germany and Australia reflect mass timber adoption and bushfire-resistant construction mandates.
United States
California's Chapter 7A building standards and Texas Hill Country wildfire ordinances drive exterior-grade pressure-treated lumber demand. The EPA governs chemical discharge from treatment facilities through NPDES permits. Construction in Los Angeles, San Diego, and Austin corridors absorbs premium volumes for multifamily podium structures.
Canada
Mass timber building codes in British Columbia and Ontario mandate fire-retardant treatments for exposed cross-laminated timber elements. Health Canada oversees chemical safety assessments for wood preservatives through the PMRA. Vancouver and Toronto metropolitan areas anchor specification-driven procurement for tall wood buildings.
Germany
Engineered wood adoption in commercial and institutional construction strengthens demand for coated fire-retardant systems. The ECHA REACH framework regulates chemical substances in wood treatment formulations. Industrial clusters in Bavaria and Baden-Württemberg concentrate manufacturing and specification authority for mass timber projects.
Australia
Bushfire attack level ratings in New South Wales and Victoria mandate ignition-resistant materials in designated bushfire-prone areas. The country's building codes board administers fire performance standards through the National Construction Code. Sydney and Melbourne construction corridors drive specification of treated timber for residential and commercial rebuilding programs.
United Kingdom
Retrofit fire safety programs for high-rise residential buildings expand demand for treated cladding and structural elements. Building Regulations Approved Document B governs fire performance requirements for timber construction. London and Southeast England concentrate refurbishment activity following post-Grenfell regulatory tightening.
Fire-Retardant Treated Wood Market Vendor Landscape
United States producers anchor the volume tier; European specialists hold differentiated positions in coated systems and engineered wood integration. The vendor base splits between integrated chemical-treatment operators and independent treaters sourcing formulations externally. Three archetypes dominate: backward-integrated chemical manufacturers, regional pressure-treatment specialists, and mass timber-integrated engineered wood suppliers. Competitive moves concentrate on strategic partnerships with national builders and geographic expansion into underpenetrated wildfire corridors.
Within the integrated chemical-treatment tier, Koppers and Lonza exemplify upstream control over formulation supply. Hoover Treated Wood Products occupies a position among specialized North American treaters with established distribution infrastructure. These anchors represent distinct strategic postures: captive chemical production versus treatment-scale specialization versus distribution partnership depth.
| Leading Market Players |
|---|
| Viance |
| Koppers |
| Hoover Treated Wood Products |
| Lonza |
| Flameproof Companies |
| Weyerhaeuser |
| Foreco |
| Arxada |
| Metsä Wood |
| Others |
Supply Flow & Price Mechanics
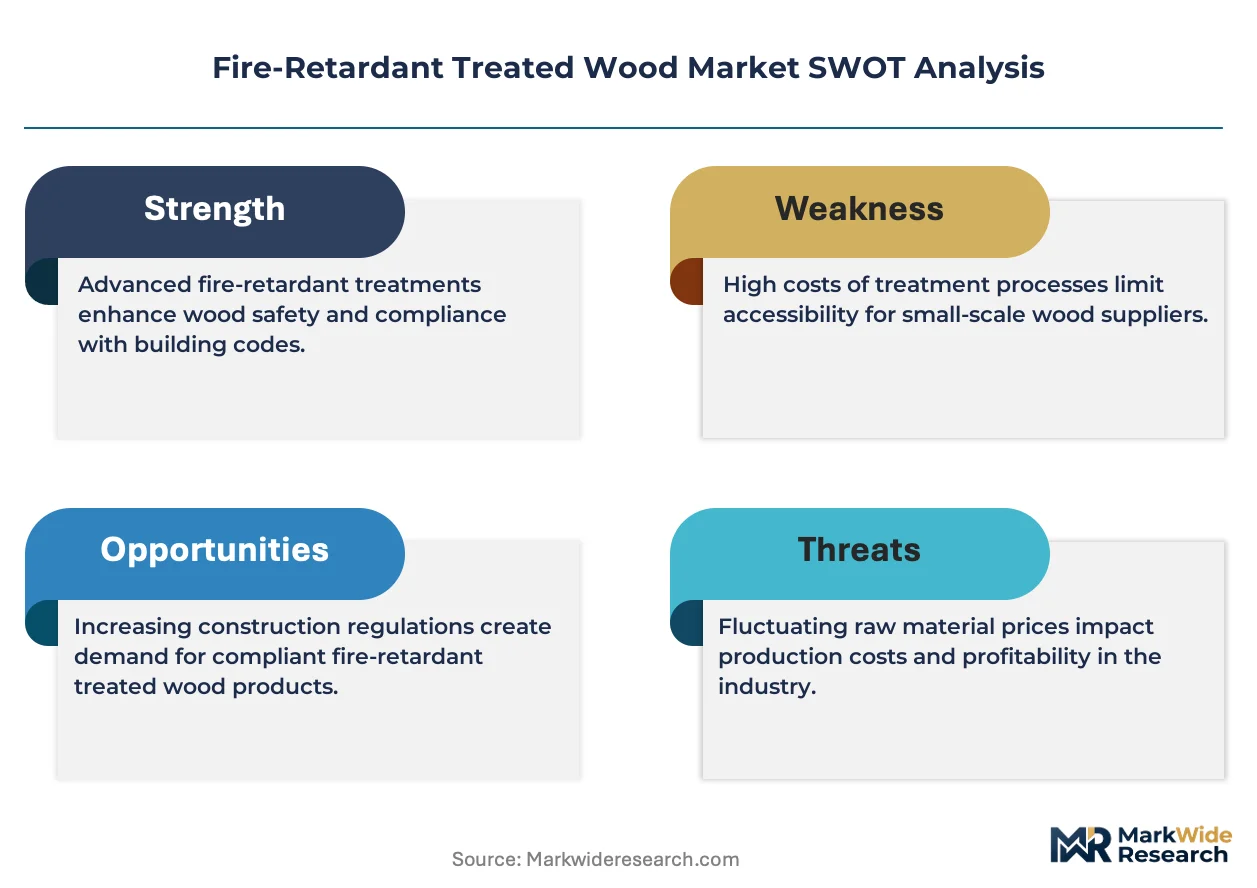
National commercial builders with centralized procurement departments command pricing leverage through volume commitments and specification authority, compressing margins for mid-scale treaters while rewarding integrated suppliers with captive chemical production. This buyer concentration enforces a contract-based pricing model where multi-year offtake agreements lock in treatment chemical costs against borate price volatility.
Pricing Analysis
Volume flows concentrate in pressure-treated lumber at commodity margins, while coated wood and specialty formulations capture premium returns through ASTM E84 Class A certification tiers. Price differentiation rests on retention uniformity guarantees and California Office of the State Fire Marshal approval status, with architects paying steepest premiums for documented ignition-resistant performance. Pricing pressure stems from borate input cost instability originating in Turkish and US mining concentration, squeezing treaters without backward integration into chemical supply. Regional distributors serving mid-market contractors exhibit highest price sensitivity, whereas national builders with dedicated fire safety engineering staff prioritize specification compliance over unit cost.
Supply Chain Analysis
Return flows of treated wood offcuts and end-of-life structural members from demolished buildings feed limited refurbishment channels, with most material entering landfill rather than remanufacturing streams. Supply concentrates in the United States, Turkey, and China, with borate extraction anchored in Anatolian mining districts and pressure-treatment capacity clustering in Texas and California. Raw material dependencies encompass disodium octaborate tetrahydrate, ammonium polyphosphate formulations, and southern yellow pine feedstock from US Southeast timberlands. Single-source vulnerability in Turkish borate supply creates exposure to geopolitical disruption and currency fluctuation. Distribution runs through two-step wholesale networks serving regional lumber yards, though direct sales channels gain share among national commercial builders maintaining centralized material approval databases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA NPDES permit scarcity constrains greenfield pressure-treatment capacity, propping pricing power for incumbent treaters with compliant facilities while forcing aspirants toward acquisition rather than organic entry.
For Market Incumbents: Hedge against borate cost volatility through backward integration into treatment chemical production or long-term offtake agreements with Turkish mining operators. Secure California Office of the State Fire Marshal pre-approval for next-generation halogen-free formulations before certification timeline compression freezes product pipelines. Channel control through direct sales teams targeting national commercial builders displaces vulnerable distributor relationships. For New Entrants and Emerging Players: Capture white space in Texas Hill Country wildfire corridors outside Austin and San Antonio where jurisdictions adopt California-style ignition-resistant mandates without established supplier relationships. Target mid-size multifamily developers lacking centralized procurement departments and dependent on regional lumber yards for specification guidance. Deploy digital procurement platforms disintermediating traditional two-step distribution to compress customer acquisition costs. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional pressure-treatment specialists with EPA-compliant facilities in underpenetrated wildfire corridors, particularly where owners face succession or capital constraints. Long-term viability hinges on positioning for mass timber code expansion across Pacific Northwest and British Columbia jurisdictions. Monitor ICC-ES Evaluation Report adoption rates for fire-retardant wood in Type I and Type II construction as inflection indicator for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Treatment Chemicals | Koppers and Lonza demonstrate how captive borate supply insulates margins against Turkish mining concentration. |
| California OSFM Pre-Approval Investment | Eighteen-month certification cycles reward early movers with formulation lock-in ahead of competitor entries. |
| Direct-to-Contractor Digital Platform Launch | Specialized e-procurement channels disintermediate traditional two-step distribution in Texas and Florida markets. |
| Halogen-Free Formulation R&D Pivot | EPA TSCA Section 6 restrictions on brominated compounds redirect R&D toward phosphorus-nitrogen intumescent systems. |
| Texas Hill Country Geographic Expansion | Underpenetrated wildfire corridors outside Austin adopt ignition-resistant mandates without incumbent supplier saturation. |
Methodological Framework
Independent corroboration across treatment facility operators, commercial general contractor procurement executives, and California Office of the State Fire Marshal officials underwrites the qualitative findings. Primary interviews encompassed plant managers at pressure-treatment facilities, fire protection engineers at national commercial builders, distribution channel partners at regional lumber yards, and technical R&D directors at formulation suppliers. Secondary validation drew from EPA NPDES permit databases, ICC-ES Evaluation Report filings, SEC 10-K disclosures from publicly traded wood products companies, and California Building Code Chapter 7A regulatory texts. Bottom-up volume estimates from treatment facility capacity utilization triangulated against top-down construction spending flows by building type.
Comparable-period anchoring to historical construction permit data and treatment chemical consumption trends established baseline calibration for projection modeling. The analytical framework segments by product type, application, end user, and distribution channel, with additional dimensioning by wildfire hazard severity zone and building code jurisdiction. CAGRs derive from regression analysis against macro construction indicators and regulatory adoption curves. Industry-specific forecast inputs include cross-laminated timber code expansion timelines and ICC-ES acceptance criteria updates for Type I and Type II construction.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to borate supply disruption, EPA chemical restriction expansion, and mass timber code adoption velocity. Practitioners should monitor ICC-ES Evaluation Report issuance rates, California OSFM approval queue lengths, and Texas Hill Country ordinance adoption patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Geofoam Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Vapor Barriers Market
Building & Construction Materials
Acoustic Plasterboard Market
Building & Construction Materials
North America Oriented Strand Board Market
Building & Construction Materials
Geogrid Market
Building & Construction Materials
Concrete Formwork System Market
Building & Construction Materials
Canada Asphalt Shingles Market
Building & Construction Materials
Artificial Wood Beams Market
Building & Construction Materials
Acoustic Doors Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
USA and Canada Fence Screen Market