
 Underfloor Air Distribution Systems Market | 2026-2036
Underfloor Air Distribution Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Underfloor Air Distribution Systems Market Outlook
Buyer concentration in the commercial office sector is decoupling from traditional HVAC procurement patterns as data center operators and educational institutions fragment demand across specialized specifications. Johnson Controls leverages its building automation integration to anchor large-scale campus deployments. Carrier Corporation sustains manufacturing scale advantages across metal duct fabrication. Price Industries differentiates through precision diffuser engineering for variable air volume configurations.
Underfloor air distribution systems deliver conditioned air through a pressurized plenum beneath a raised floor, typically operating at supply temperatures between 63°F and 66°F to exploit thermal stratification and reduce fan energy. The primary commercial purpose centers on improving thermal comfort while enabling individual zone control and reducing ventilation energy intensity versus overhead mixing systems. Metal product types dominate current specification sheets due to durability in high-traffic commercial environments, though composite materials are gaining traction in renovation projects where weight constraints limit structural modifications. Multi-zone system configurations command premium positioning as facility managers prioritize granular temperature management across open-plan and enclosed office hybrids.
ASHRAE Standard 62.1 ventilation requirements and the EPA's commercial building energy codes are reshaping product certification pathways for underfloor plenum assemblies. OSHA indoor air quality guidelines further constrain material selection for occupied spaces, particularly regarding composite off-gassing in educational institutions. Stakeholders must monitor evolving state-level stretch codes that exceed federal baselines and determine whether regional manufacturing partnerships or centralized distribution better serve fragmented specification environments.
Market Dynamics
Commercial office developers are decoupling from traditional overhead HVAC procurement as EPA energy efficiency standards and ASHRAE ventilation mandates force specification changes toward pressurized plenum architectures.
Growth Catalysts
- EPA Commercial Building Energy Codes:Federal efficiency standards are accelerating displacement of overhead mixing systems in new construction across Texas and California corridor developments.
- Data Center Cooling Demand:Operators require granular zone control and reduced fan energy intensity that underfloor configurations deliver versus conventional ducted approaches.
- Thermal Stratification Physics:Supply temperatures between 63°F and 66°F exploit natural convection patterns, cutting ventilation energy intensity in high-occupancy commercial environments.
Market Restraints
- Steel Input Volatility:Metal duct fabrication costs fluctuate with commodity pricing, compressing margins for manufacturers serving high-traffic commercial specifications.
- Structural Load Constraints:Raised floor plenum assemblies impose weight penalties that limit renovation applicability in legacy buildings without structural reinforcement.
- Overhead System Incumbency:Established contractor expertise and installed base in existing commercial stock slow displacement cycles despite efficiency advantages.
Strategic Opportunities
- Educational Institution Retrofit:K-12 and university campuses seek composite material solutions where weight constraints prohibit structural modifications for metal plenum installation.
- OSHA Indoor Air Quality Guidelines:Off-gassing restrictions on composite materials create certification pathways for low-emission metal assemblies in occupied learning environments.
- Building Automation Convergence:Integration with IoT-enabled zone controls enables predictive maintenance contracts and recurring revenue streams beyond hardware sales.
Industry Challenges
- Specialized Installation Labor:Pressurized plenum commissioning requires certified technicians familiar with underfloor air distribution physics, constraining deployment velocity.
- Multi-Zone Integration Complexity:Facility managers struggle to balance variable air volume configurations across open-plan and enclosed office hybrids without performance degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underfloor Air Distribution Systems Market |
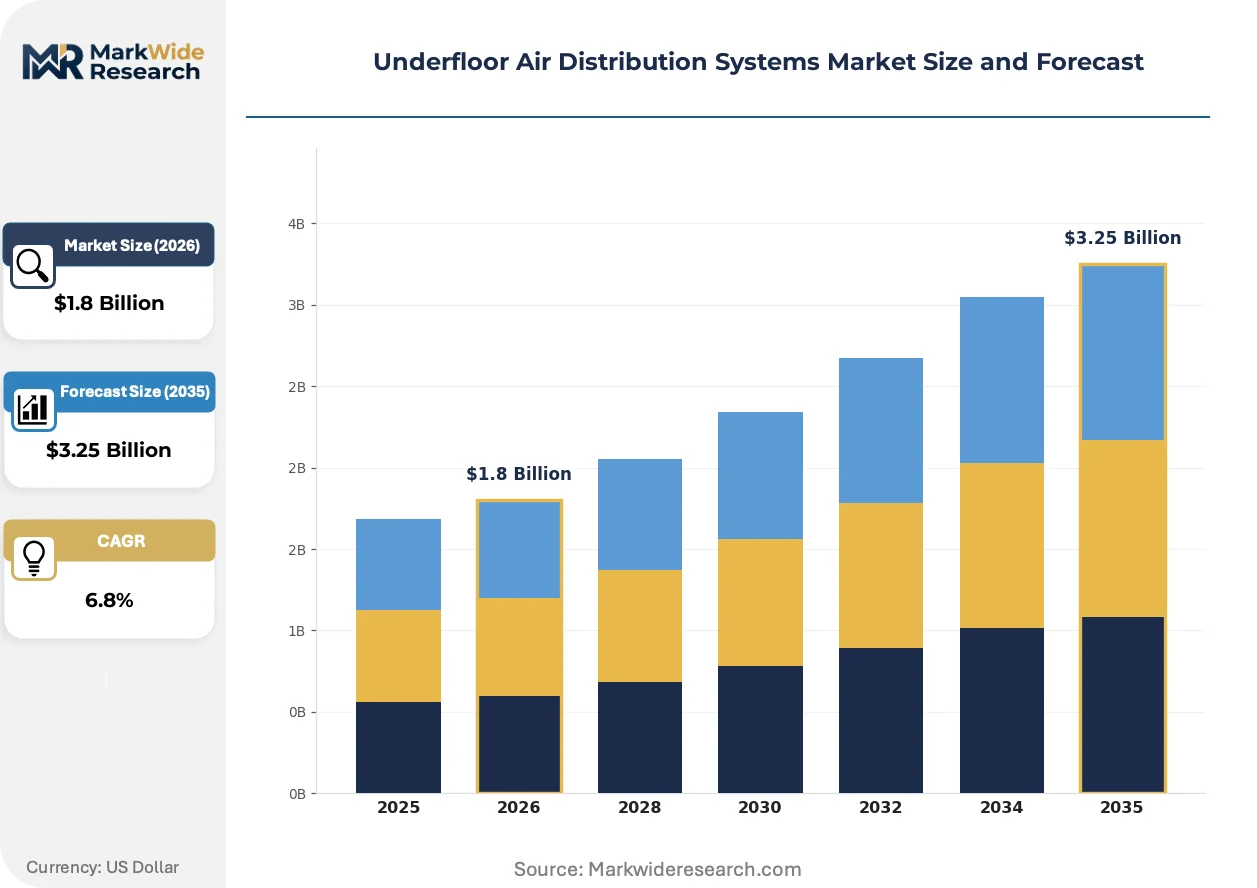
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal, Plastic, Composite, Wood Application: Commercial Offices, Retail Spaces, Data Centers, Educational Institutions Installation Method: New Construction, Renovation, Retrofit, Modular System Configuration: Single-Zone, Multi-Zone, Variable Air Volume, Constant Air Volume |
| Companies Covered | Johnson Controls, Carrier Corporation, Schneider Electric, Price Industries, TROX USA, Kingspan Group, DuctSox Corporation, AirFixture, Global IFS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underfloor Air Distribution Systems Market Strategic Shifts
Product engineering is pivoting toward precision diffuser architectures and composite material formulations as specification environments fragment across new construction and renovation verticals.
Variable geometry diffusers with integrated VAV controls are overtaking fixed-aperture designs in commercial office specifications. Building operators in Class A developments demand real-time airflow modulation responsive to occupancy sensors. This capability is overtaking static metal fabrication as the primary value anchor in competitive bidding.
ASHRAE Standard 62.1 ventilation requirements are tightening allowable air change rates in occupied commercial zones. The standard forces recalculation of supply air volumes and diffuser placement density in open-plan layouts. Educational institutions and healthcare-adjacent office complexes face the steepest compliance recalibration.
Performance-based maintenance contracts are displacing traditional equipment-only procurement in campus-scale deployments. Facility management firms bundle underfloor plenum monitoring with guaranteed energy outcomes. This shift concentrates in United States commercial developments where operating expense transparency drives lease negotiations.
Underfloor Air Distribution Systems Market Segmentation
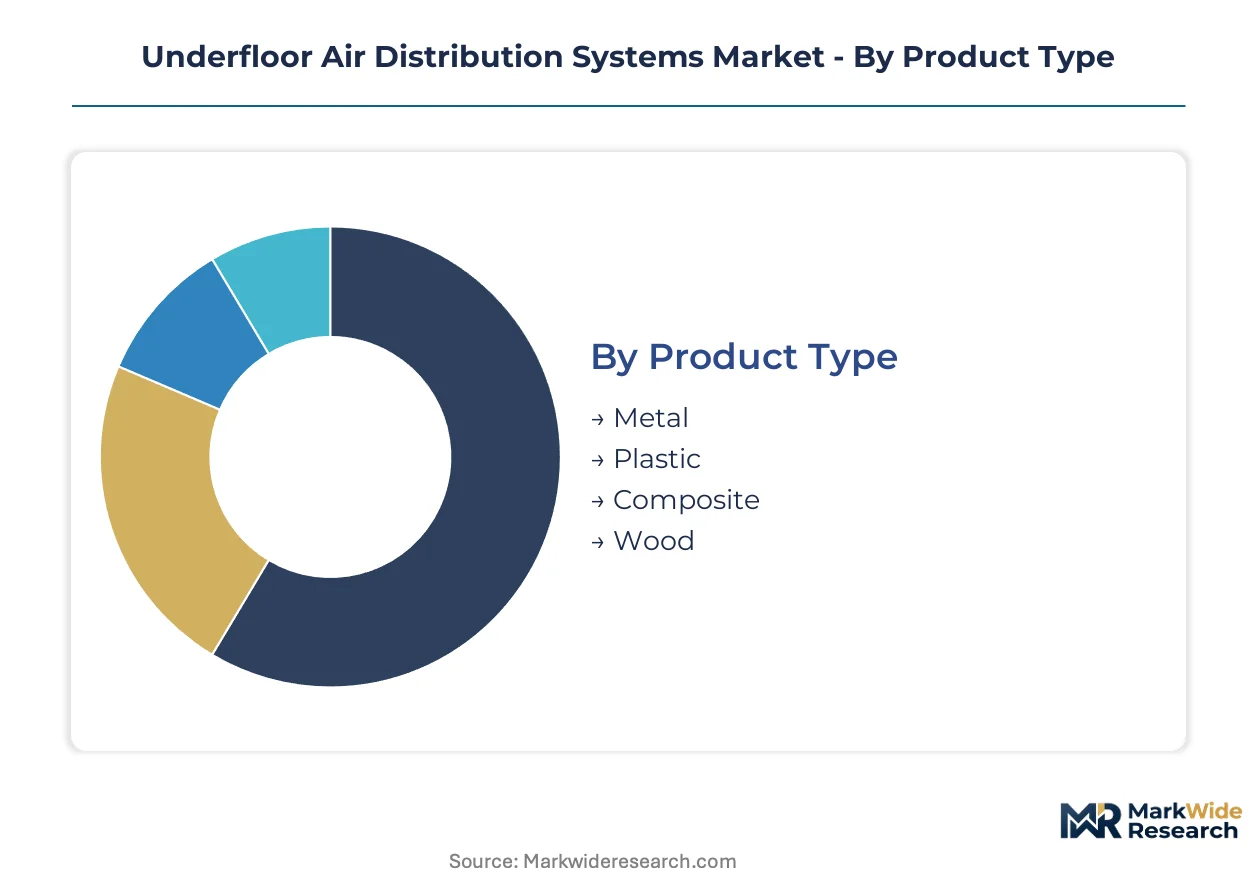
Specification fragmentation across new construction and renovation verticals demands granular segmentation to align material selection with structural constraints and regulatory compliance pathways. Procurement teams in commercial office and data center deployments prioritize distinct performance characteristics that cut across traditional product categories.
Product Type:
Durability requirements in high-traffic commercial environments drive material selection tradeoffs between lifecycle cost and installation feasibility.
- Metal:Galvanized steel and aluminum assemblies dominate Class A office specifications due to structural integrity under raised floor loads. Texas and California corridor developers specify metal plenums for EPA energy code compliance in new construction exceeding 100,000 square feet.
- Composite:Engineered polymer-fiber formulations reduce plenum weight by 40-60% versus steel alternatives, enabling renovation applicability where structural reinforcement is cost-prohibitive. Educational institutions in legacy buildings specify composite for OSHA indoor air quality compliance with low-emission certifications.
- Plastic:PVC and thermoplastic ducting serves modular deployment scenarios requiring rapid field assembly without specialized fabrication equipment.
- Wood:Treated lumber plenum assemblies retain niche specification in heritage building renovations where aesthetic integration with existing architectural elements overrides thermal efficiency optimization.
Volume sits with Metal; growth tilts toward Composite.
Application:
Tenant improvement allowances and lease structure transparency reshape capital allocation across end-use verticals with divergent occupancy patterns.
- Commercial Offices:Open-plan and hybrid enclosed layouts demand multi-zone configurations with individual temperature control. ASHRAE Standard 62.1 recalculations of supply air volumes per occupant density concentrate specification complexity in this vertical.
- Data Centers:Granular zone control requirements and reduced fan energy intensity position underfloor distribution as superior to overhead ducting for cooling density above 150 watts per square foot. Operators prioritize pressurized plenum architectures for server rack thermal management.
- Educational Institutions:K-12 and university campuses balance renovation feasibility against indoor air quality mandates, driving composite material adoption where structural load limits apply.
- Retail Spaces:Variable occupancy patterns and display reconfiguration frequency favor modular installation approaches with rapid diffuser relocation capability.
Revenue concentrates in Commercial Offices; expansion accelerates most quickly in Data Centers.
Installation Method:
Project delivery timelines and existing building stock condition determine procurement channel selection and contractor specialization requirements.
- New Construction:Integrated design-build contracts enable pressurized plenum optimization from structural framing phase, minimizing coordination penalties between MEP trades.
- Renovation:Structural assessment requirements and ceiling height preservation constraints limit applicability to buildings with sufficient floor-to-floor dimensions for raised floor assembly.
- Retrofit:Phased occupancy maintenance during installation demands modular component strategies that isolate construction zones from operational areas.
- Modular:Prefabricated plenum sections with factory-integrated diffusers compress field installation schedules for fast-track commercial developments.
Deployment volume clusters in New Construction; Retrofit approaches gain share fastest in urban infill markets.
System Configuration:
Building automation integration depth and energy outcome guarantees differentiate specification tiers across facility management procurement.
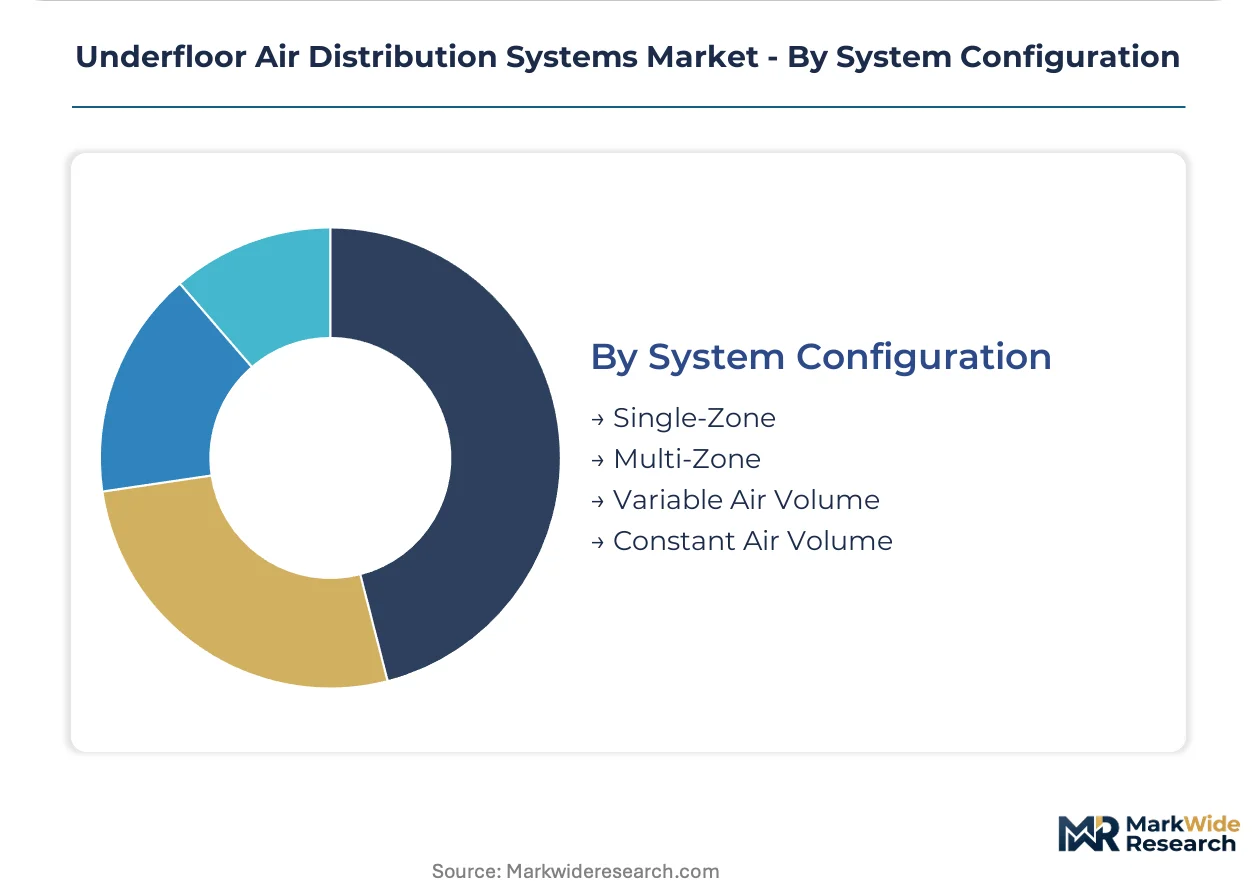
- Multi-Zone:Independent temperature control for 20-plus zones per floor plate enables granular response to occupancy sensor data and daylighting variation. Facility managers in Class A developments prioritize this configuration for operating expense transparency in lease negotiations.
- Variable Air Volume:Real-time airflow modulation through precision diffusers with integrated VAV controls displaces fixed-aperture designs in competitive bidding for campus-scale deployments.
- Single-Zone:Simplified control architecture serves small-footprint commercial spaces with uniform occupancy patterns and limited perimeter exposure.
- Constant Air Volume:Fixed supply rates retain specification in specialized applications requiring stable pressurization, such as cleanroom-adjacent office environments.
Specification volume flows to Multi-Zone; VAV configurations show the steepest expansion trajectory in building automation convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel feedstock availability in the Great Lakes region anchors North American metal duct fabrication capacity, while composite resin supply chains concentrate along the US Gulf Coast petrochemical corridor.
United States
Texas and California corridor developments drive specification volume as EPA commercial building energy codes displace overhead mixing systems in new construction exceeding 100,000 square feet. ASHRAE Standard 62.1 ventilation recalculations reshape diffuser placement density in open-plan commercial offices across Dallas-Fort Worth and Los Angeles metro areas.
Germany
Industrial facility modernization programs and data center cooling retrofits propel demand for precision VAV configurations. The EU Green Deal building renovation targets and F-Gas Regulation phase-down accelerate displacement of conventional HVAC in Frankfurt and Munich commercial districts.
China
Rapid commercial office construction in Yangtze River Delta and Pearl River Delta clusters creates specification volume for raised floor plenum systems. MIIT energy efficiency standards for public buildings and dual carbon goals constrain traditional overhead ducting in Shanghai and Shenzhen Class A developments.
United Arab Emirates
Sustainable city mandates and LEED certification requirements for new commercial stock position underfloor distribution as thermally efficient alternatives to conventional cooling. Dubai's Al Quoz industrial zone and Abu Dhabi Masdar City concentrate demonstration projects for pressurized plenum architectures.
Japan
Commercial building energy conservation standards and METI efficiency targets reshape HVAC procurement in Tokyo and Osaka central business districts. Kanto region developers specify multi-zone configurations to meet granular thermal comfort requirements in high-density office towers.
Underfloor Air Distribution Systems Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue building automation convergence and composite material specialization. The vendor base stratifies across three archetypes: integrated building technology conglomerates anchoring campus-scale deployments, precision engineering specialists dominating diffuser architecture, and regional fabricators serving renovation-weight-constrained verticals. Competitive moves concentrate on strategic partnerships with controls integrators and backward integration into metal coil processing to defend margin positions against steel input volatility.
Among diversified building technology conglomerates, Johnson Controls and Carrier Corporation exemplify scale-driven archetypes with captive distribution networks spanning North American specification channels. Schneider Electric occupies a position within the electrification-and-controls convergence tier, while Price Industries represents precision-engineering specialization in variable air volume diffuser configurations. TROX USA and Kingspan Group sit within regional fabrication archetypes with established specification relationships in European and Asia-Pacific commercial development corridors.
| Leading Market Players |
|---|
| Johnson Controls |
| Carrier Corporation |
| Schneider Electric |
| Price Industries |
| TROX USA |
| Kingspan Group |
| DuctSox Corporation |
| AirFixture |
| Global IFS |
| Others |
Value Chain & Pricing Dynamics
Family-owned metal fabrication specialists across the Great Lakes region anchor supply-side discipline through captive coil processing, translating steel feedstock proximity into pricing leverage against commodity volatility while composite resin producers along the US Gulf Coast petrochemical corridor compete on weight-reduction value propositions for renovation-constrained buyers.
Pricing Analysis
Volume concentrates in standardized metal duct assemblies where Carrier Corporation and Johnson Controls compete on manufacturing scale, while margins concentrate in precision VAV diffuser configurations where Price Industries commands premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates building automation-integrated multi-zone systems from basic single-zone metal plenums and modular plastic ducting for temporary deployments. Cost compression in standard metal tiers is intensifying because steel input volatility compresses fabricator margins without commensurate pass-through elasticity. Educational institutions and retail developers exhibit highest price sensitivity due to capital constraint structures, whereas data center operators prioritize energy outcome guarantees over unit cost.
Supply Chain Analysis
UL and ASHRAE certification gating constrains supplier qualification, with metal coil processing concentrated in the United States Great Lakes region, composite resin formulation in the US Gulf Coast corridor, and precision diffuser machining in Germany and Japan. Raw material dependencies center on galvanized steel coil, engineered polymer-fiber compounds, and aluminum extrusion stock. Single-source vulnerability runs through specialized VAV actuator suppliers serving precision diffuser integrators. Distribution runs through MEP contractor channels with certified commissioning technician requirements, limiting direct manufacturer penetration in fragmented specification environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as manufacturers pursue backward integration into metal coil processing to defend margin positions against steel commodity swings, while building automation convergence demands downstream controls partnerships.
For Market Incumbents: Lock in certified technician training pipelines to constrain deployment velocity for emerging competitors lacking commissioning infrastructure. Deepen captive supply of galvanized steel coil through Great Lakes regional partnerships to offset feedstock volatility compressing standard-tier margins. The threat of IoT-enabled building automation specialists disintermediating hardware relationships demands urgent controls integration investment. For New Entrants and Emerging Players: The premium-to-economy price gap in multi-zone VAV configurations presents white-space opportunity for mid-tier positioning with modular component strategies. Target educational institution renovation verticals where composite material specialization bypasses incumbent metal fabrication scale advantages. A go-to-market angle through performance-based energy outcome contracts differentiates against equipment-only procurement patterns. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision engineering specialists with ASHRAE certification pathways in Germany and Japan, where EU Green Deal building renovation targets and METI efficiency mandates accelerate displacement timelines. Long-term viability centers on building automation convergence capabilities rather than commodity metal fabrication scale. The signal to watch is OEM partnership announcements for factory-integrated diffuser modules in modular construction pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metal Coil Processing | Captive steel supply insulates margins from commodity volatility in EPA-regulated commercial developments. |
| Building Automation Platform Partnership | IoT convergence enables predictive maintenance contracts with recurring revenue beyond hardware sales. |
| Composite Material Certification Investment | Low-emission OSHA compliance opens educational institution renovation verticals weight-constrained for metal. |
| Certified Technician Training Network Expansion | Commissioning labor scarcity constrains deployment velocity for competitors lacking qualified installation channels. |
| Modular Prefabrication Capability Buildout | Factory-integrated diffuser sections compress field schedules for fast-track Texas and California corridor projects. |
Study Parameters
Multi-period observation of EPA energy code adoption timelines and ASHRAE Standard 62.1 ventilation recalculation patterns anchored the trend analysis, supplemented by interviews with MEP contractors, facility management directors, commercial developers, and building automation integrators. Secondary validation drew from EPA commercial building energy code filings, ASHRAE technical committee documentation, SEC 10-K disclosures from diversified building technology conglomerates, and state-level stretch code adoption tracking. Bottom-up project pipeline assessment triangulated against top-down regulatory mandate impact modeling.
Input-output matrices mapped product type, application vertical, installation method, and system configuration dimensions across the projection horizon, with CAGRs derived from regression analysis against regulatory compliance deadlines and construction permit velocity. Industry-specific forecast inputs incorporated steel commodity futures curves and building automation adoption rates in Class A commercial developments.
Inputs from MEP contractor interviews and state-level code adoption databases were available through the study window; gaps in proprietary building automation integration cost structures introduce uncertainty bands around convergence timeline assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Europe HVAC Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
Asia-Pacific Heating Equipment Market
HVAC Equipment
North America Air to Water Heat Pump Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
US Residential Heat Pump Market
HVAC Equipment
Linear Slot Diffuser Market
HVAC Equipment
Industrial Boiler Market
HVAC Equipment
US Compressed Air Treatment Equipment Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
North America Bus HVAC Market
HVAC Equipment
United Kingdom HVAC Market
HVAC Equipment
Fabric Air Ducts Market
HVAC Equipment
Scrubber Dryer Market
HVAC Equipment
Centrifugal Chillers Market
HVAC Equipment
Ventilation Fan Market