
 Finishing Lines Market | 2026-2036
Finishing Lines Market Size, Share, and Industry Trends Forecast 2026-2036
Finishing Lines Market Analysis
German finishing equipment builders is restructuring supply chains to offset energy cost volatility and shorten lead times for powder coating systems. Nordson Corporation leverages its melt-blowing and liquid finishing expertise to sustain pricing power in precision adhesive dispensing. Graco Inc. anchors North American market presence through high-pressure plural-component spray technology for protective coatings. Cefla Finishing Group S.p.A competes on integrated digital workflow platforms that connect sanding, spraying, and drying stages.
Finishing lines constitute integrated production systems that apply surface coatings, decorative films, or protective layers to manufactured substrates, typically operating at line speeds between 5 and 150 meters per minute depending on curing technology and substrate porosity. These systems serve primarily to enhance durability, aesthetic uniformity, and functional performance across consumer and industrial goods. Flexographic technology dominates packaging applications where high-volume label and flexible film production requires rapid changeover between color stations. Digital printing segments are expanding fastest among short-run packaging and personalized consumer goods where job lot sizes below five thousand units make rotary cylinder costs prohibitive. Metal substrate processing retains the densest margin pools due to pretreatment complexity, environmental compliance costs, and automotive qualification protocols.
EPA air quality standards and OSHA permissible exposure limits for isocyanates and volatile organic compounds constrain solvent-based system deployments across US manufacturing facilities. ECHA REACH annex XVII restrictions on chromium VI compounds and specific phthalate plasticizers redirect European coating formulation toward waterborne and UV-curable chemistries. China's MEE emission standards for industrial coating operations enforce concentration limits that accelerate electrocoating and powder system conversions. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded capital in non-compliant equipment configurations.
Market Dynamics
Automotive OEM qualification protocols and REACH chemical phase-outs are compressing equipment replacement cycles while concentrating procurement among vertically integrated system builders capable of delivering compliant turnkey installations.
Growth Catalysts
- China MEE emission enforcement:Concentration limits on industrial coating operations accelerate electrocoating and powder system conversions across Yangtze River Delta manufacturing clusters.
- Automotive lightweighting:Aluminum and composite substrate processing requires advanced pretreatment and curing lines as OEMs qualify new material stacks for electric vehicle platforms.
- UV-curable chemistry advances:Reduced energy consumption and instant curing properties drive adoption in furniture and flooring applications where throughput velocity determines margin.
Market Restraints
- Specialized component supply concentration:Precision gear pumps and high-voltage power supplies for electrostatic guns concentrate among German and Japanese suppliers, exposing lead time vulnerability.
- Isocyanate exposure compliance:OSHA permissible exposure limits for hexamethylene diisocyanate force costly ventilation upgrades and personal protective equipment protocols at US facilities.
- Waterborne system performance gaps:Humidity sensitivity and extended flash-off requirements limit waterborne coatings in high-throughput metal finishing where solvent-based systems retain process efficiency.
Strategic Opportunities
- India PLI scheme for manufacturing:Production-linked incentives for electronics and automotive component fabrication create first-mover advantage for finishing line vendors establishing local assembly.
- Digital-physical workflow convergence:Integration of automated optical inspection with real-time viscosity control enables closed-loop quality assurance in aerospace and medical device coating.
- Refurbishment service models:Performance-based maintenance contracts for aging solvent-based lines in Eastern European markets extend asset life while deferring capital expenditure.
Industry Challenges
- Control systems integration:Legacy programmable logic controllers in existing lines resist seamless connectivity with Industry 4.0 data architectures, forcing expensive rip-and-replace decisions.
- Multisubstrate process engineering:Lines configured for steel or aluminum require extensive retooling to handle carbon fiber reinforced polymers without contamination or cure incompatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finishing Lines Market |
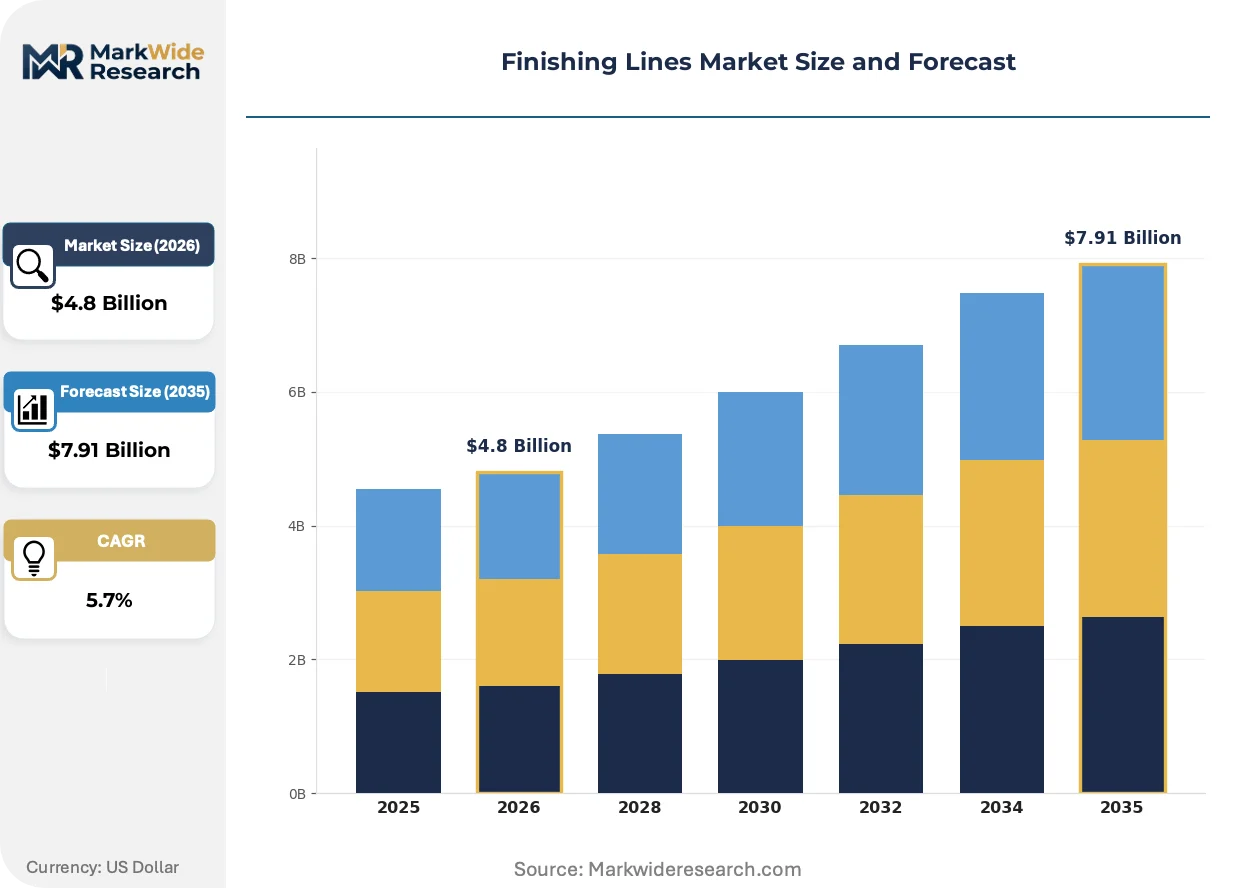
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Printers, Cutting Machines, Laminators, Packaging Equipment Technology: Flexographic, Gravure, Offset, Digital End User: Manufacturers, Retailers, Distributors, E-commerce Material: Plastic, Paper, Metal, Textile |
| Companies Covered | Graco Inc., J. Wagner GmbH, Nordson Corporation, Spray Equipment & Service Center Inc., Reliant Finishing Systems LLC, Blasdel Enterprises Inc., Finish Line Industries Inc., Global Finishing Solutions, Cefla Finishing Group S.p.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finishing Lines Market Emerging Trajectories
Surface finishing technology is converging around data-centric quality assurance and chemistry platforms that eliminate thermal curing, compressing both capital requirements and environmental footprint simultaneously.
Electrostatic rotary bell atomizers with integrated shaping air control are unifying transfer efficiency and film build consistency across automotive, appliance, and general industrial applications. Tier-one suppliers in Germany and Mexico are standardizing on these systems to reduce material waste and overspray reclamation costs. The technology is unifying what were previously separate manual touch-up and automated base coat operations into single-pass configurations.
ECHA REACH Annex XVII restrictions on chromium VI compounds and specific phthalate plasticizers are redirecting European coating formulation toward waterborne and UV-curable chemistries. Metal substrate processors face reformulation costs and requalification timelines that extend six to eighteen months for automotive approvals. German and Italian equipment builders are responding with modular curing sections that accommodate multiple chemistry types without full line reconstruction.
Short-run packaging converters are consolidating procurement around finishing lines with sub-ten-minute color change capability. Flexographic and digital hybrid configurations displace dedicated rotary cylinder investments where job lot sizes fragment below five thousand units. This pattern concentrates most visibly in China's Pearl River Delta flexible packaging corridor and among North American contract decorators serving craft beverage and specialty food brands.
Finishing Lines Market Segmentation
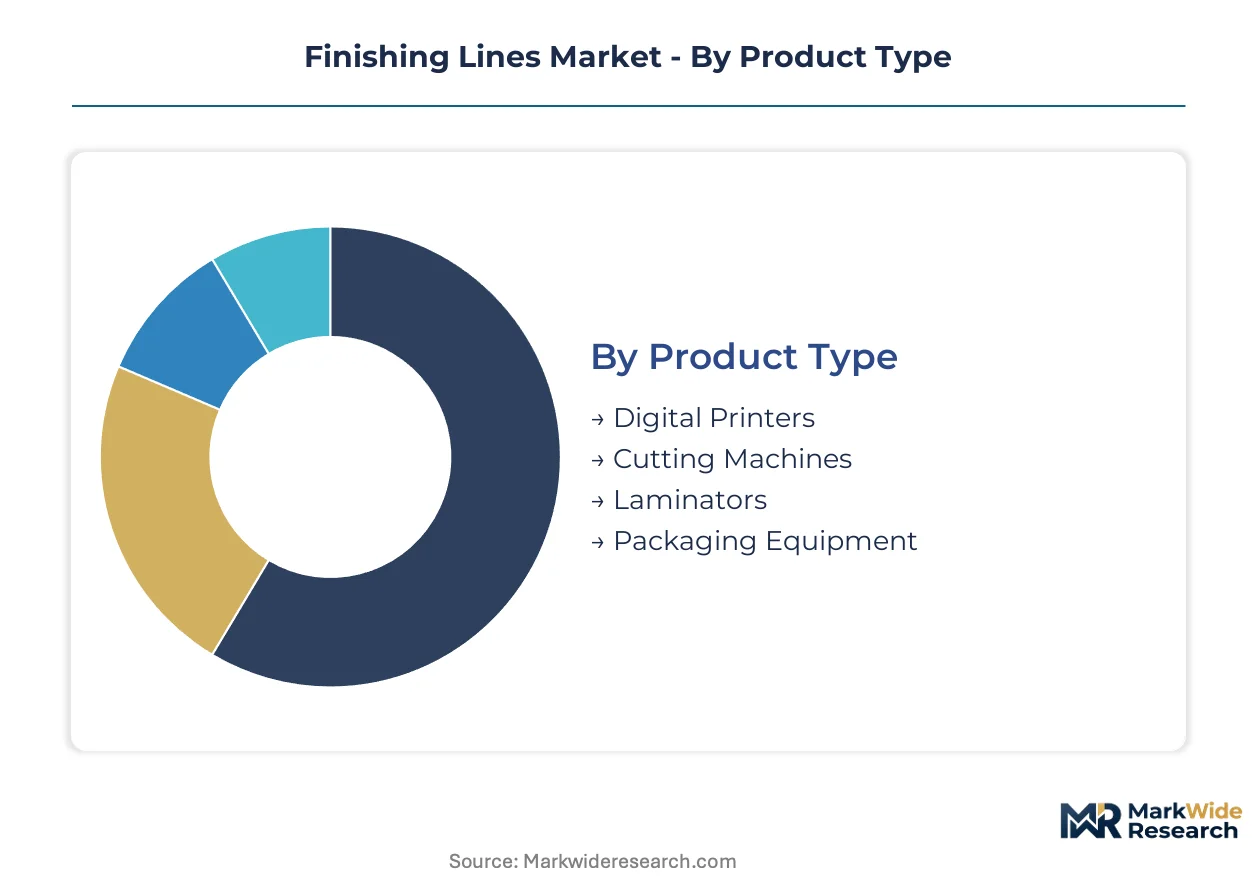
Finishing lines serve heterogeneous substrate classes and throughput requirements that fragment equipment specifications across chemistry compatibility, line speed, and curing energy profiles. Segmentation clarity determines vendor configuration decisions and capital allocation priorities.
Product Type:
Supply concentration for precision components—gear pumps, electrostatic power supplies, and automated conveyor systems—clusters among German and Japanese specialists, compressing lead times for integrated line deliveries.
- Digital Printers:Direct-to-substrate inkjet and toner systems eliminate rotary cylinder tooling costs. Demand concentrates in China's Pearl River Delta flexible packaging corridor and North American craft beverage contract decorators where job lots fragment below five thousand units.
- Cutting Machines:Rotary die and laser cutting modules integrate inline with printing stages for label and folding carton production. Automotive interior trim suppliers in Germany's Baden-Württemberg region drive specifications for kiss-cutting precision on adhesive-backed films.
- Laminators:Thermal and adhesive bonding systems apply protective or decorative films to printed substrates. Food packaging converters specify barrier-grade constructions.
- Packaging Equipment:Folder-gluers, case packers, and palletizing modules complete converting lines. E-commerce fulfillment centers demand right-size box forming to reduce dimensional weight shipping penalties.
Packaging Equipment absorbs the bulk of installed capacity; Digital Printers is expanding most quickly.
Technology:
Cost tier stratification separates high-volume rotary investments from digital configurations suited to short-run fragmentation and personalization requirements.
- Flexographic:Central impression cylinder and stack-type presses dominate high-volume label and flexible film production with rapid color change capability. China's Yangtze River Delta manufacturing clusters standardize on these systems for export-oriented food and consumer goods packaging.
- Gravure:Engraved cylinder technology delivers consistent ink density for long-run publication and decorative laminate printing. Publication gravure faces displacement from digital alternatives in developed markets.
- Offset:Sheet-fed and web offset configurations retain cost efficiency for folding carton and commercial printing above ten thousand impressions. Metal decorating lines for beverage cans employ UV-curable offset chemistries.
- Digital:Inkjet and electrophotographic systems eliminate makeready waste and enable versioned content. UV-curable inkjet is gaining share fastest in industrial decorative and functional coating applications where thermal curing stresses temperature-sensitive substrates.
Flexographic retains the greatest installed base; Digital is climbing the fastest as run lengths contract and personalization premiums justify unit cost differentials.
End User:
Customer type determines service intensity, with captive OEM operations demanding qualification documentation and aftermarket parts availability that contract decorators often bypass.
- Manufacturers:Automotive OEMs, appliance producers, and electronics assemblers operate captive finishing lines requiring ISO and customer-specific process approvals. German automotive OEM qualification protocols compress equipment replacement cycles.
- Retailers:Private label and store-brand producers contract finishing services to regional converters. Quality consistency requirements match branded goods specifications.
- Distributors:Industrial supply and maintenance coating operations specify portable and batch systems rather than continuous lines. Inventory velocity pressures drive just-in-time delivery contracts.
- E-commerce:Direct-to-consumer brands demand versioned packaging with variable data printing for personalization and supply chain traceability. Short-run flexibility outweighs unit cost minimization.
Manufacturers command the densest margin pools; E-commerce is gaining share fastest as direct-to-consumer channel expansion fragments order quantities.
Material:
Substrate porosity and thermal tolerance dictate pretreatment chemistry, curing energy, and line speed configurations that segment equipment architectures.
- Plastic:Polyethylene, polypropylene, and polyester films require corona or flame surface activation prior to coating or printing. Flexible packaging converters in China's coastal provinces drive demand for multi-layer barrier constructions.
- Paper:Uncoated and coated paperboard substrates serve folding carton and label applications. Sustainability pressures redirect specification toward recycled fiber content and waterborne coating compatibility.
- Metal:Steel and aluminum coil processing commands the highest system values due to pretreatment complexity, environmental compliance costs, and automotive qualification protocols. ECHA REACH Annex XVII chromium VI restrictions force reformulation and requalification timelines extending six to eighteen months.
- Textile:Fabric finishing applies softeners, water repellents, and digital prints to apparel and technical textiles. Low-tension handling requirements differentiate equipment from rigid substrate lines.
Metal retains the steepest capital intensity and margin structure; Plastic is expanding most quickly as flexible packaging consumption rises in emerging economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized steel and aluminum coil stock from Germany's Ruhr Valley and China's Ansteel Group supply the substrate foundation for finishing line deployments across automotive and appliance manufacturing corridors worldwide.
United States
Automotive OEMs in Michigan and Ohio are retrofitting solvent-based lines to meet EPA air quality standards for volatile organic compounds. OSHA permissible exposure limits for hexamethylene diisocyanate force ventilation upgrades at metal finishing facilities. Industrial coating operations concentrate in the Great Lakes manufacturing belt where Tier-one suppliers qualify new electrostatic systems.
Germany
Baden-Württemberg automotive interior trim suppliers drive specifications for precision adhesive-backed film processing. ECHA REACH Annex XVII restrictions on chromium VI compounds redirect coating formulation toward waterborne chemistries. Equipment builders in Bavaria and North Rhine-Westphalia are restructuring supply chains to offset energy cost volatility.
China
MEE emission standards enforce concentration limits that accelerate electrocoating conversions across Yangtze River Delta manufacturing clusters. Flexible packaging converters in the Pearl River Delta drive demand for sub-ten-minute color change capability. Domestic stainless steel coil supply from Baowu Group feeds continuous line installations.
Mexico
Automotive OEMs in Nuevo León and the Bajío Region are expanding automated coating installations for export-oriented assembly. Proximity to US qualification protocols compresses equipment approval timelines. Querétaro's aerospace supplier base demands closed-loop quality assurance for specialty coating applications.
India
Production-linked incentives for electronics and automotive component fabrication create procurement windows for finishing line vendors. BIS certification requirements for industrial equipment extend qualification periods. Tamil Nadu and Gujarat manufacturing corridors attract first-mover assembly operations for powder coating systems.
Finishing Lines Market Vendor Landscape
Global majors compete with regional champions across technology integration and aftermarket service density. The vendor base stratifies into three tiers: integrated system builders delivering turnkey installations, specialized component fabricators supplying precision pumps and power supplies, and regional service providers maintaining legacy solvent-based lines. Dominant competitive moves include backward integration into control software development and geographic expansion through local assembly partnerships.
Within the integrated system builder tier, Nordson Corporation and Graco Inc. occupy positions defined by precision fluid handling expertise, while Cefla Finishing Group S.p.A represents the European archetype of digital workflow integration. J. Wagner GmbH anchors German engineering credibility in portable and industrial spray technology. These named entities exemplify how specialization in melt-blowing, high-pressure plural-component systems, or multi-stage automation creates defensible positioning against commodity fabricators.
| Leading Market Players |
|---|
| Graco Inc. |
| J. Wagner GmbH |
| Nordson Corporation |
| Spray Equipment & Service Center Inc. |
| Reliant Finishing Systems LLC |
| Blasdel Enterprises Inc. |
| Finish Line Industries Inc. |
| Global Finishing Solutions |
| Cefla Finishing Group S.p.A |
| Others |
Supply Flow & Price Mechanics
Precision automation engineers in Bavaria and North Rhine-Westphalia command wage premiums that widen spreads between premium-tier integrated systems and economy-grade component bundles. Labor-cost differentials between German engineering centers and Eastern European assembly operations translate into three-tier pricing stratification across warranty coverage, software integration depth, and aftermarket service density.
Pricing Analysis
Warranty and service-bundling separates premium offerings from unbundled economy configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and vertical integration depth. Cost compression in economy tiers intensifies because Chinese domestic vendors compete on stripped-down electrostatic gun packages. Contract decorators in the Pearl River Delta exhibit highest price sensitivity; automotive OEMs in Baden-Württemberg prioritize qualification documentation over unit cost.
Supply Chain Analysis
Automotive qualification protocols gate entry for precision gear pump and high-voltage power supply vendors. Manufacturing concentrates in Germany, Japan, and China for electrostatic components, with Italy and Switzerland supplying conveyor automation modules. Component sourcing draws from specialty steel mills in the Ruhr Valley and rare-earth magnet processors in China's Inner Mongolia. Single-source vulnerability persists for semiconductor-controlled rectifiers in electrostatic power supplies. Distribution runs through OEM-direct channels for automotive qualification and regional distributor networks for general industrial retrofit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finishing lines operate as a cost-of-compliance market where ECHA REACH Annex XVII chromium VI restrictions erect barrier-to-entry moats for qualified system builders. Regulatory qualification timelines extending six to eighteen months protect incumbent margin structures from unqualified entrants.
For Market Incumbents: Acquire control software development capabilities to escape commodity hardware pricing. Backward integration into real-time viscosity monitoring and automated optical inspection systems defends against emerging digital-native entrants. Capacity addition in Tamil Nadu and Gujarat manufacturing corridors captures India PLI scheme procurement windows before qualification periods close. For New Entrants and Emerging Players: UV-curable inkjet retrofit modules offer technology-first wedge into short-run packaging converters. White-space targets include craft beverage contract decorators in North America and personalized consumer goods decorators serving e-commerce brands. Go-to-market through regional distributor partnerships bypasses direct automotive qualification barriers. For Investors and Strategic Acquirers: Re-rating potential sits with modular curing section specialists given ECHA chemistry flexibility requirements. Long-term viability centers on vendors capable of accommodating waterborne, UV-curable, and powder chemistries without full line reconstruction. Acquisition target archetype: German mid-cap equipment builders with captive software stacks. Signal to watch: automotive OEM lightweighting announcements accelerating aluminum and composite substrate processing line procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Software | Captures recurring revenue streams from real-time process optimization modules. |
| Green Manufacturing Transition | Aligns with MEE emission standards and REACH Annex XVII chemistry phase-outs. |
| Joint Venture with Regional Distributor | Accelerates market access in India's Tamil Nadu and Gujarat manufacturing corridors. |
| Long-term Supply Agreement | Secures precision gear pump allocation from German and Japanese component specialists. |
| Geographic Expansion via Local Assembly | Offsets energy cost volatility and shortens lead times for powder coating systems. |
Methodological Framework
Document review covered customs and trade data, SEC filings from listed equipment vendors, and ECHA regulatory guidance documents, complemented by interviews with plant engineers at automotive OEMs, procurement leads at flexible packaging converters, aftermarket service heads at regional distributors, and technical R&D directors at coating formulation suppliers. Secondary validation drew from MEE emission standard enforcement records, BIS certification databases, and production-linked incentive scheme announcements. Bottom-up line installation counts and top-down equipment value estimates were triangulated to establish market sizing.
Installed base projections and replacement cycle analysis across the modeling period generated volume and value outputs by product type, technology, end user, material substrate, and regional manufacturing cluster. CAGRs were derived from regression analysis against automotive production forecasts, packaging consumption indices, and regulatory enforcement timelines. Industry-specific inputs included electrocoating conversion rates tied to MEE emission audits and UV-curable chemistry adoption curves in furniture and flooring applications.
Several conditions sit outside the modeled scope, including speculative breakthroughs in room-temperature curing chemistries and unilateral tariff restructuring on German and Japanese precision components. Forecasts reflect assumptions around regulatory enforcement continuity and automotive qualification protocol stability. A model refresh is warranted upon material change in REACH Annex XVII substance restriction timelines or automotive OEM platform standardization announcements for electric vehicle architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Porcelain Tiles Market
Building & Construction Materials
Global Convertible Roof System Market
Building & Construction Materials
Roofing Shingles Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Autoclaved Aerated Concrete (AAC) Blocks Market
Building & Construction Materials
Vapor Barriers Market
Building & Construction Materials
Concrete Resurfacer Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
Australia Steel Rebar Market
Building & Construction Materials
Global Wood Cement Boards Market
Building & Construction Materials
Thailand Construction Chemicals Market
Building & Construction Materials
North America Plywood Market
Building & Construction Materials
Roofing Liners Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market