
 Foldable Houses Market | 2026-2036
Foldable Houses Market Size, Share, and Industry Trends Forecast 2026-2036
Foldable Houses Market Analysis
Buyer concentration among government agencies and humanitarian organizations is pivoting toward multi-year framework contracts rather than one-off purchases. Boxabl leverages its manufacturing scale to compete for federal housing contracts in the United States. Liv-Connected anchors its position through vertical integration into steel chassis production. Quick Smart House differentiates by specializing in rapid-deployment configurations for emergency response.
Foldable houses are transportable dwelling structures engineered for flat-pack shipment and on-site assembly, typically incorporating steel or composite material frames with insulated panel envelopes rated for structural wind and snow loads. Their primary commercial purpose is to deliver habitable space without conventional foundation requirements, serving disaster relief, workforce housing, and remote site operations. Modular units dominate current output volumes due to standardized production economics, while compact designs capture expanding margin pools from off-grid residential buyers seeking minimal-footprint dwellings. Steel-framed variants lead in institutional procurement channels where durability certification drives specification.
FEMA guidelines in the United States, EU Green Deal circularity requirements, and Japan's METI building energy standards collectively shape product compliance thresholds and market access conditions for foldable housing manufacturers. Japan's PMDA-adjacent structural assessment protocols for temporary medical facilities further extend regulatory scope into specialized deployment scenarios. Stakeholders must monitor evolving national building codes that increasingly distinguish foldable structures from traditional manufactured housing classifications.
Market Dynamics
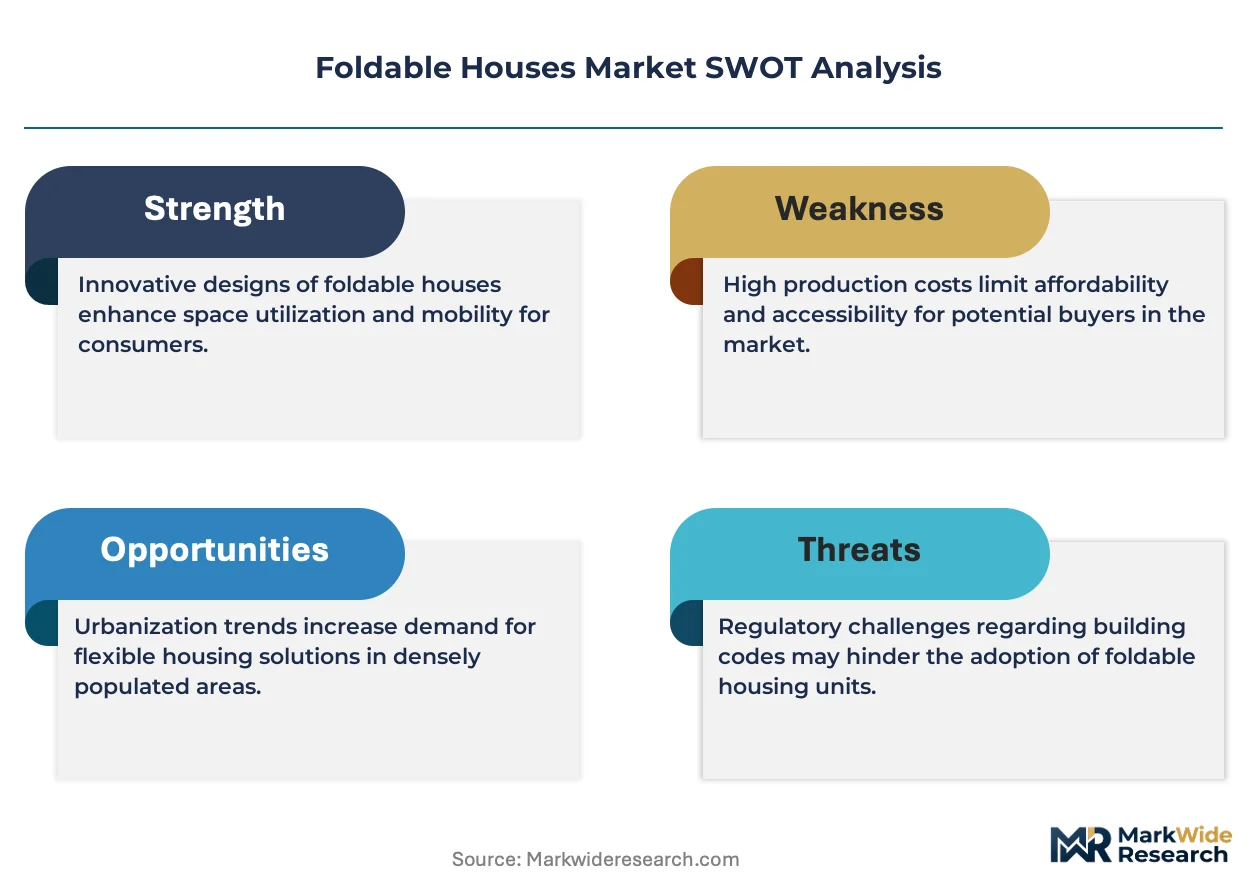
Government procurement concentration is compressing sales cycles toward multi-year framework agreements, while EU Green Deal circularity mandates force material specification changes across institutional channels.
Growth Catalysts
- EU Green Deal circularity mandates:Procurement requirements now prioritize recycled steel and composite content, opening specification windows for certified foldable housing suppliers in German and French public tenders.
- Disaster relief agencies:FEMA and UNHCR are consolidating emergency housing purchases into pre-positioned stock contracts, creating predictable demand baselines for rapid-deployment manufacturers.
- Remote workforce expansion:Mining and energy extraction operations in Australia and Canada are substituting foldable units for permanent construction in 18-36 month project cycles.
Market Restraints
- Steel price volatility:Galvanized steel coil fluctuations directly compress margins for chassis-dependent manufacturers, with no viable composite substitution at institutional load-rating thresholds.
- Foundation ambiguity:Local building code interpretation variance across US counties creates permitting friction that delays deployment and elevates compliance costs.
- Site-built construction substitution:Conventional modular construction retains cost advantages in non-emergency applications where speed carries no premium.
Strategic Opportunities
- Japan's METI building energy standards:Net-zero ready foldable configurations qualify for accelerated permitting and subsidized financing in prefectural housing programs.
- Off-grid residential segment:Solar-integrated compact designs command margin premiums from buyers in rural California and Texas seeking minimal-footprint dwellings outside utility infrastructure.
- Healthcare facility adjacency:PMDA-adjacent structural assessment protocols for temporary medical units extend addressable demand into specialized deployment scenarios beyond residential use.
Industry Challenges
- Certification timeline compression:Multiple jurisdiction load-testing requirements for wind and snow ratings extend product validation cycles, delaying revenue recognition.
- Installation labor scarcity:Flat-pack assembly demands skilled crews familiar with steel connection systems, creating bottlenecks in rapid-deployment scenarios where speed defines contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foldable Houses Market |
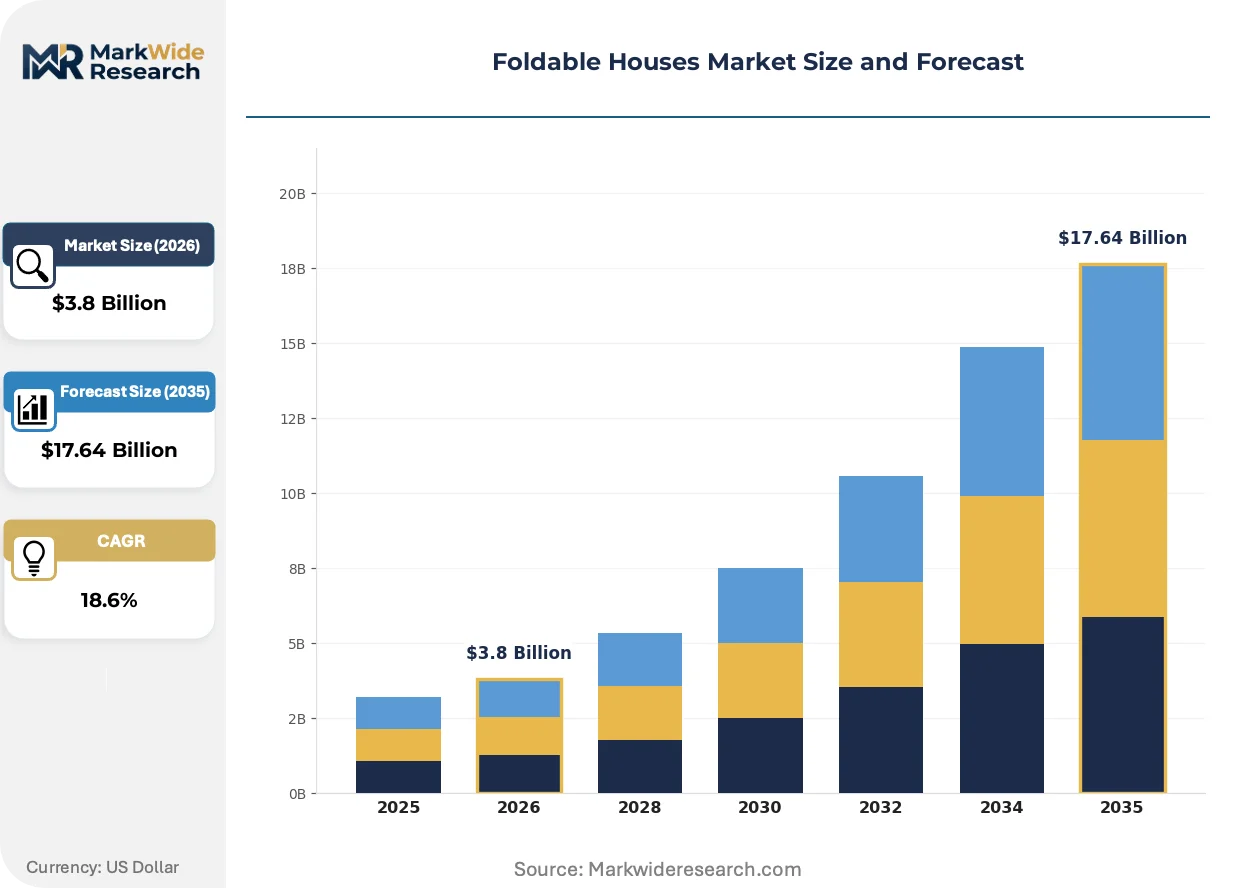
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Units, Prefabricated Structures, Mobile Homes, Compact Designs Material: Wood, Steel, Composite Materials, Insulated Panels End User: Residential Buyers, Commercial Developers, NGOs, Government Agencies Distribution Channel: Direct Sales, Online Retail, Distributors, Trade Shows |
| Companies Covered | Liv-Connected, Quick Smart House, Boxabl, Ecocapsule, Mighty Buildings, MODS International, NOMAD Micro Homes, Zip Kit Homes, Pallet Shelter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foldable Houses Market Emerging Trajectories
Digital fabrication and regulatory harmonization are converging to compress product development cycles and expand addressable use cases beyond traditional emergency response applications.
Robotic panel assembly is automating the production of insulated envelope components, cutting unit labor content by half in facilities serving German and Japanese markets. Institutional buyers now specify robot-welded chassis as a durability proxy, compressing qualification timelines for suppliers with automated lines. This technology diffusion is concentrating production economics among capital-intensive operators.
EU Green Deal circularity requirements are mandating recycled content thresholds and end-of-life material recovery plans for construction products sold into public procurement. Manufacturers must now document steel provenance and panel recyclability to maintain specification status in German federal housing tenders. The compliance burden falls heaviest on mid-scale producers lacking captive recycling partnerships.
Framework contracting is displacing spot purchasing across FEMA and major European disaster relief agencies, compressing supplier bases to pre-qualified vendors with proven rapid-deployment track records. Channel consolidation favors manufacturers with established logistics partnerships and regional staging inventory. This shift is most visible in US federal procurement, where multi-year awards now cover anticipatory stockpiling rather than reactive emergency orders.
Foldable Houses Market Segmentation
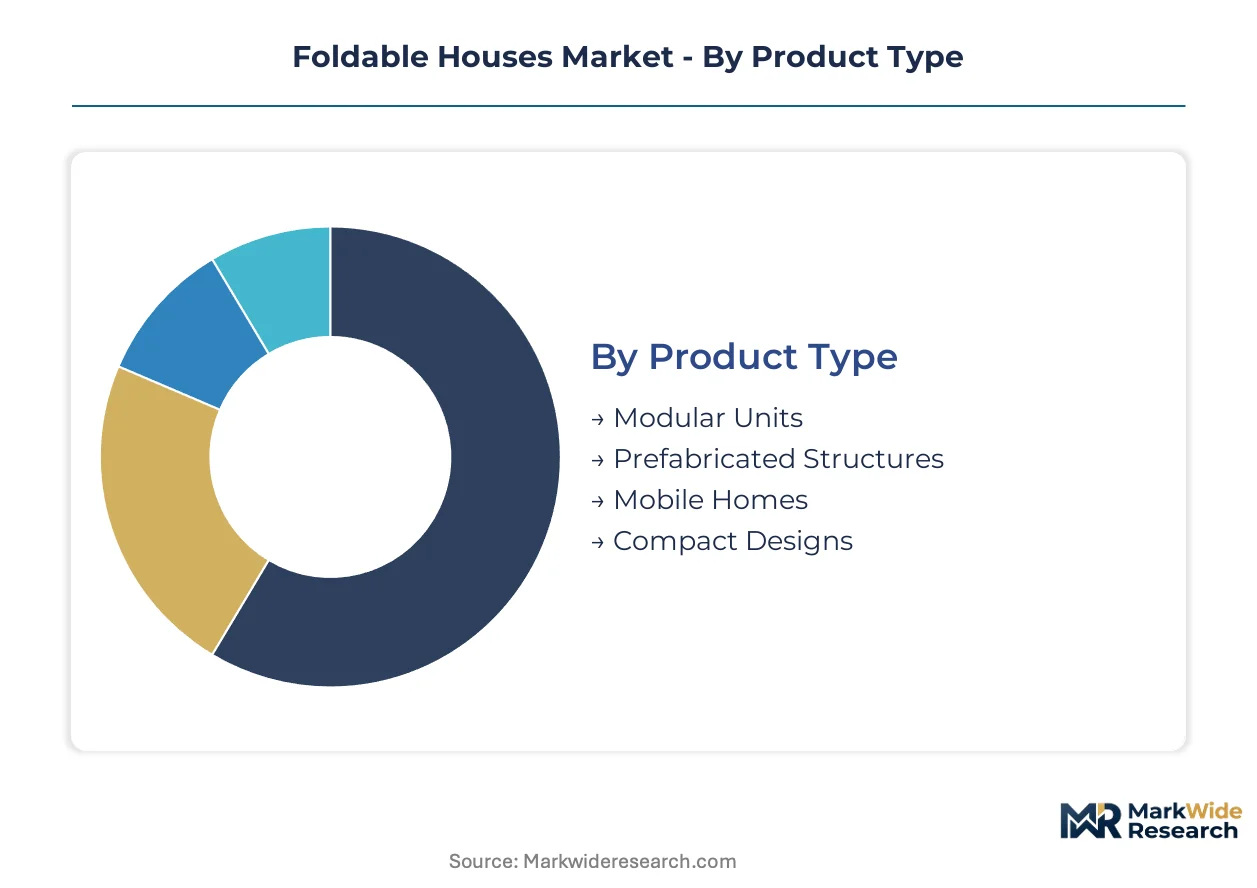
Foldable housing procurement splits sharply between standardized institutional orders and customized configurations for niche applications. Understanding where customization premiums apply versus scale economies dominates supplier strategy.
Product Type:
Standardization intensity varies dramatically across this category, from mass-produced modular cores to bespoke compact dwellings engineered for specific terrain constraints.
- Modular Units:Factory-assembled volumetric sections with integrated MEP systems enable crane-set installation in under 48 hours. Demand concentrates in German federal housing tenders and FEMA pre-positioned stock programs where interchangeability drives procurement scoring.
- Compact Designs:Footprint-optimized structures under 400 square feet target off-grid residential buyers in rural California and Texas. Solar-integrated configurations command substantial margin premiums where utility connection costs exceed $15,000.
- Prefabricated Structures:Panelized systems shipped flat-pack for on-site assembly serve remote workforce camps in Australian mining regions.
- Mobile Homes:Chassis-mounted units with highway transport certification appeal to seasonal agricultural labor housing in Spain and Italy.
Most installed capacity flows through Modular Units. Expansion is steepest in Compact Designs.
Material:
Cost tier positioning separates premium-specified materials from commodity alternatives in this category.
- Steel:Galvanized chassis and frame assemblies rated for seismic and wind loads dominate institutional procurement channels. METI building energy standards in Japan and EU Green Deal circularity mandates favor recycled-content steel with documented provenance.
- Composite Materials:Fiber-reinforced polymer panels deliver corrosion resistance for coastal and chemical-exposure deployments. Norwegian offshore energy operators specify composite-clad units for North Sea platform support facilities.
- Wood:Cross-laminated timber frames serve Scandinavian residential markets where biogenic carbon accounting improves project financing terms.
- Insulated Panels:Polyurethane-core or mineral-wool sandwich systems provide thermal envelopes required for net-zero ready configurations in French and German public housing.
Steel captures the largest share of institutional procurement volume. Composite Materials are gaining share fastest in specialized industrial applications.
End User:
Customer type determines contract structure, with framework agreements displacing spot purchasing among the largest buyers.
- Government Agencies:FEMA, UNHCR, and German federal procurement offices consolidate emergency housing into multi-year pre-positioned stock contracts. Rapid-deployment track records and logistics partnerships determine qualification status.
- NGOs:Humanitarian organizations prioritize total landed cost and local assembly speed over durability specifications for 12-24 month deployment cycles.
- Commercial Developers:Workforce housing operators in Australian mining and Canadian oil sands regions substitute foldable units for permanent construction in 18-36 month project windows.
- Residential Buyers:Individual purchasers in utility-free rural locations seek minimal-footprint dwellings with solar integration and rainwater harvesting systems.
Government Agencies account for the majority of contracted volume. Residential Buyers are expanding most quickly as off-grid lifestyle adoption spreads.
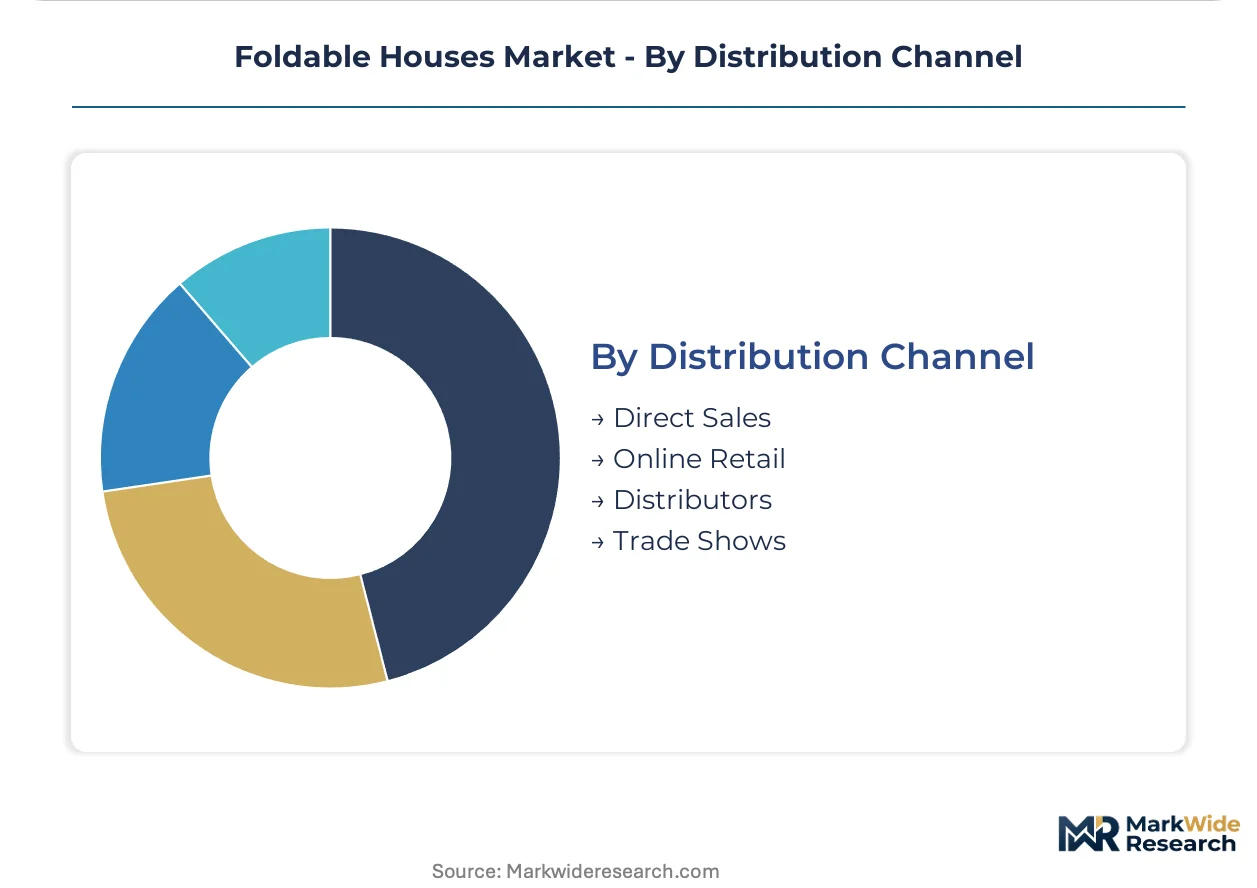
Distribution Channel:
Channel selection reflects buyer sophistication and deployment urgency requirements across customer segments.
- Direct Sales:Manufacturer-direct relationships dominate institutional procurement where specification compliance and staging inventory commitments require negotiated terms. Boxabl and comparable suppliers maintain dedicated federal contracting teams.
- Distributors:Regional stocking distributors serve commercial developers and smaller government buyers requiring shorter lead times than factory-direct orders allow.
- Online Retail:Configurator-based ordering with transparent pricing attracts residential buyers in North American and European markets.
- Trade Shows:Industry exhibitions remain critical for initial supplier qualification in institutional channels and for demonstrating assembly speed to procurement officials.
Direct Sales channels handle the largest contract value. Online Retail is climbing the fastest as residential buyer digital adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized steel fabrication workforces in Germany, Japan, and the United States anchor the concentrated production clusters serving institutional procurement channels. These three countries generate the bulk of certified rapid-deployment housing output, with secondary capacity emerging in Australia and France.
Germany
Federal housing tenders and disaster relief stockpiling programs drive sustained demand for modular units with documented recycled steel content. EU Green Deal circularity mandates require end-of-life material recovery plans, elevating compliance burdens on suppliers. The Ruhr industrial corridor hosts automated chassis welding facilities that serve cross-border procurement contracts.
Japan
Prefectural housing programs and temporary medical facility deployment create dual demand streams for net-zero ready configurations. METI building energy standards qualify compliant units for accelerated permitting and subsidized financing. The Chubu region around Nagoya concentrates precision steel fabrication capacity serving both domestic and export orders.
United States
FEMA pre-positioned stock contracts and rural off-grid residential buyers generate divergent demand profiles for rapid-deployment and compact dwelling segments. Local building code interpretation variance across counties creates permitting friction that delays deployment timelines. The Southwest and Mountain West states exhibit the fastest residential adoption curves for minimal-footprint solar-integrated units.
Australia
Remote mining and energy extraction operations substitute foldable units for permanent construction in 18-36 month project cycles. Western Australia and Queensland host the primary deployment sites for workforce camp configurations. Perth-based fabricators maintain staging inventory for rapid mobilization to Pilbara and Bowen Basin sites.
France
Public housing agencies prioritize net-zero ready configurations with polyurethane-core or mineral-wool thermal envelopes for energy compliance. National building codes increasingly distinguish foldable structures from traditional manufactured housing classifications. The Auvergne-Rhône-Alpes region hosts panel assembly facilities serving both domestic tenders and German cross-border demand.
Foldable Houses Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement channels, with government framework contracts favoring suppliers with proven rapid-deployment track records. The vendor base organizes into three tiers: capital-intensive operators with automated production lines, mid-scale regional fabricators, and niche specialists in compact off-grid configurations. Two dominant competitive moves define current positioning: backward integration into steel chassis production to control input costs, and strategic logistics partnerships to secure regional staging inventory commitments.
Among US-based fabricators, Boxabl occupies a position exemplifying scale-driven federal contracting specialization, while Liv-Connected anchors the tier of suppliers with captive steel production capabilities. Quick Smart House represents the rapid-deployment specialist archetype focused on emergency response configurations. These three entities collectively illustrate the strategic segmentation between manufacturing scale, upstream integration, and deployment speed as distinct competitive vectors.
| Leading Market Players |
|---|
| Liv-Connected |
| Quick Smart House |
| Boxabl |
| Ecocapsule |
| Mighty Buildings |
| MODS International |
| NOMAD Micro Homes |
| Zip Kit Homes |
| Pallet Shelter |
| Others |
Supply Flow & Price Mechanics
Government framework contract consolidation compresses pricing power toward volume-scaled suppliers with proven rapid-deployment track records. Steel-framed modular units command premium positioning against panelized alternatives where METI certification or EU Green Deal compliance gates institutional procurement access.
Pricing Analysis
Product-only versus full-service bundling splits the pricing landscape, with turnkey installation and staging inventory commitments commanding substantial premiums in FEMA and UNHCR tenders. Pricing stratifies across certified institutional-grade, compliant commercial-grade, and unbundled economy configurations, with recycled-content steel documentation and robot-welded chassis ratings as primary differentiation levers. Cost compression in economy-tier panelized systems intensifies as Chinese and Turkish fabricators enter European distributor channels. NGOs and humanitarian organizations exhibit highest price sensitivity, while German federal housing offices prioritize total lifecycle compliance cost over unit acquisition price.
Supply Chain Analysis
Galvanized steel coil supply rests on integrated mills in Germany, Japan, and South Korea, with secondary rolling capacity concentrated in the US Rust Belt and China's Hebei province. Polyurethane-core insulated panels draw from chemical producers in Belgium and the US Gulf Coast, while precision chassis welding equipment feeds from Japanese and German automation specialists. Single-source vulnerability in specialty-grade recycled steel with documented provenance threatens compliance continuity for EU Green Deal-mandated public tenders. Distribution runs through manufacturer-direct federal contracting teams for institutional buyers, regional stocking distributors for commercial developers, and configurator-based online retail for residential purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EU Green Deal circularity mandates and METI net-zero standards shift procurement scoring toward certified premium specifications. Framework contract consolidation favors suppliers with demonstrated rapid-deployment logistics and automated production scale.
For Market Incumbents: Anchor market position through backward integration into captive steel chassis production, insulating margin structures from galvanized coil volatility. Secure multi-year framework contract renewals by committing regional staging inventory adjacent to FEMA distribution hubs and German federal logistics nodes. Invest in robot-welded line certification to compress qualification timelines against mid-scale competitors lacking capital-intensive automation.
For New Entrants and Emerging Players: Enter via specialized compact configurations for off-grid residential buyers in rural California and Texas, where solar-integrated minimal-footprint designs command substantial margin premiums and incumbent presence remains thin. Target healthcare facility adjacency applications under Japan's PMDA-adjacent structural assessment protocols, leveraging lower certification barriers versus institutional residential procurement. Pursue direct-to-consumer digital configurators with transparent pricing to bypass distributor markups and accelerate residential buyer acquisition.
For Investors and Strategic Acquirers: Infrastructure and real estate investment trusts focused on workforce housing are the most active acquirer in this space, seeking deployable asset platforms for 18-36 month project cycles. Long-term viability hinges on regulatory permanence of circular construction mandates across the analysis window. Acquisition targets should demonstrate captive recycling partnerships or automated chassis welding capacity. The signal to watch is framework contract renewal rates among FEMA pre-positioned stock vendors as indicator of procurement channel consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Chassis Production | Captive supply of galvanized coil insulates margins from commodity volatility and secures EU Green Deal recycled-content documentation. |
| Regional Staging Inventory Commitment | Pre-positioned modular units near FEMA distribution hubs and German federal logistics nodes accelerate framework contract award timelines. |
| Robot-Welded Line Certification Investment | Automated chassis production compresses institutional buyer qualification cycles and serves as durability proxy in procurement scoring. |
| Net-Zero Ready Configuration Development | METI-compliant designs qualify for accelerated permitting and subsidized financing in Japanese prefectural housing programs. |
| Healthcare Facility Adjacency Certification | PMDA-adjacent structural assessment protocols extend addressable demand beyond residential into temporary medical unit deployment. |
Methodological Framework
Multiple input streams — executive interviews with foldable housing manufacturers, procurement officers at FEMA and German federal housing agencies, and site visits to automated chassis welding facilities — were reconciled against customs data for steel panel imports, SEC filings from publicly traded construction technology firms, and EU tender documentation for circular construction compliance requirements. Primary discussions with logistics coordinators at UNHCR, plant managers at Ruhr corridor fabrication sites, and category buyers at Australian mining workforce housing operators informed operational assumptions. Bottom-up unit shipment estimates by product type and material were triangulated against top-down construction spending allocation models.
Data-stream reconciliation applied across the projection horizon linked segment-level volume assumptions to regulatory compliance timelines, framework contract award patterns, and raw material cost trajectories. Modeled dimensions span product type, material specification, end-user category, and distribution channel, with additional granularity for certification tier and geographic deployment cluster. CAGRs were derived from fitted growth curves anchored to disclosed contract values and tracked installation volumes. Industry-specific inputs include EU Green Deal implementation pace, METI building energy standard revision cycles, and FEMA pre-positioned stock budget allocations.
The model holds under sustained government procurement concentration and stable steel price corridors; deviation in circular construction mandate enforcement intensity or galvanized coil supply disruption would shift volume and value trajectories. A small set of named triggers — framework contract cancellation rates, recycled steel provenance documentation rejections, and county-level building code reclassification — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Awning Market
Building & Construction Materials
Indonesia Ceramic Tiles Market
Building & Construction Materials
Asphalt Market
Building & Construction Materials
North America Freestanding Canopy Market
Building & Construction Materials
Education Building Design Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Brick Market
Building & Construction Materials
North America Concrete Sealer Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
Tile Backer Boards Market
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
US and Canada Corner Beads and Caps Market
Building & Construction Materials
Europe Geogrids Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
Hollow Concrete Block Market
Building & Construction Materials
Modular Commercial Building System Market