
 Point Fixing Glass Curtain Wall Market | 2026-2036
Point Fixing Glass Curtain Wall Market Size, Share, and Industry Trends Forecast 2026-2036
Point Fixing Glass Curtain Wall Market Insights
Real estate developers are unwinding reliance on speculative residential towers and redirecting capital toward trophy commercial assets with signature facades. Apogee Enterprises anchors North American project pipelines through captive fabrication capacity for oversized tempered lites. YKK Corporation leverages its hardware-to-systems integration to dominate Japanese institutional bids. Yuanda China Holdings Limited sustains cost leadership via in-house production of spider fittings and structural silicone glazing kits.
A point fixing glass curtain wall suspends glazing panels on discrete mechanical anchors rather than continuous framing, typically employing stainless steel spider fittings, patch plates, or tension cable nets with point-supported laminated glass rated for specified wind and live loads. The assembly transfers facade loads back to primary structure while maximizing optical transparency for commercial and civic architecture. Spider fittings and cable net systems command premium specification in hospitality establishments and sports complexes where uninterrupted sightlines define design intent. Tempered glass and insulated glass units occupy volume positions across standard commercial complexes, though laminated configurations capture margin in seismic zones and blast-rated institutional buildings.
China's GB standards and the EU's CE marking framework enforce divergent testing protocols for point-fixing hardware fatigue and glass fallout containment, fragmenting certification costs across export portfolios. The US FAA and municipal building codes in Dubai, Singapore, and London impose additional constraints on reflective glazing near flight paths and thermal performance in tropical climates. Stakeholders must monitor evolving energy codes in multiple jurisdictions that threaten to disqualify single-pane point-fixed systems from new construction eligibility.
Market Dynamics
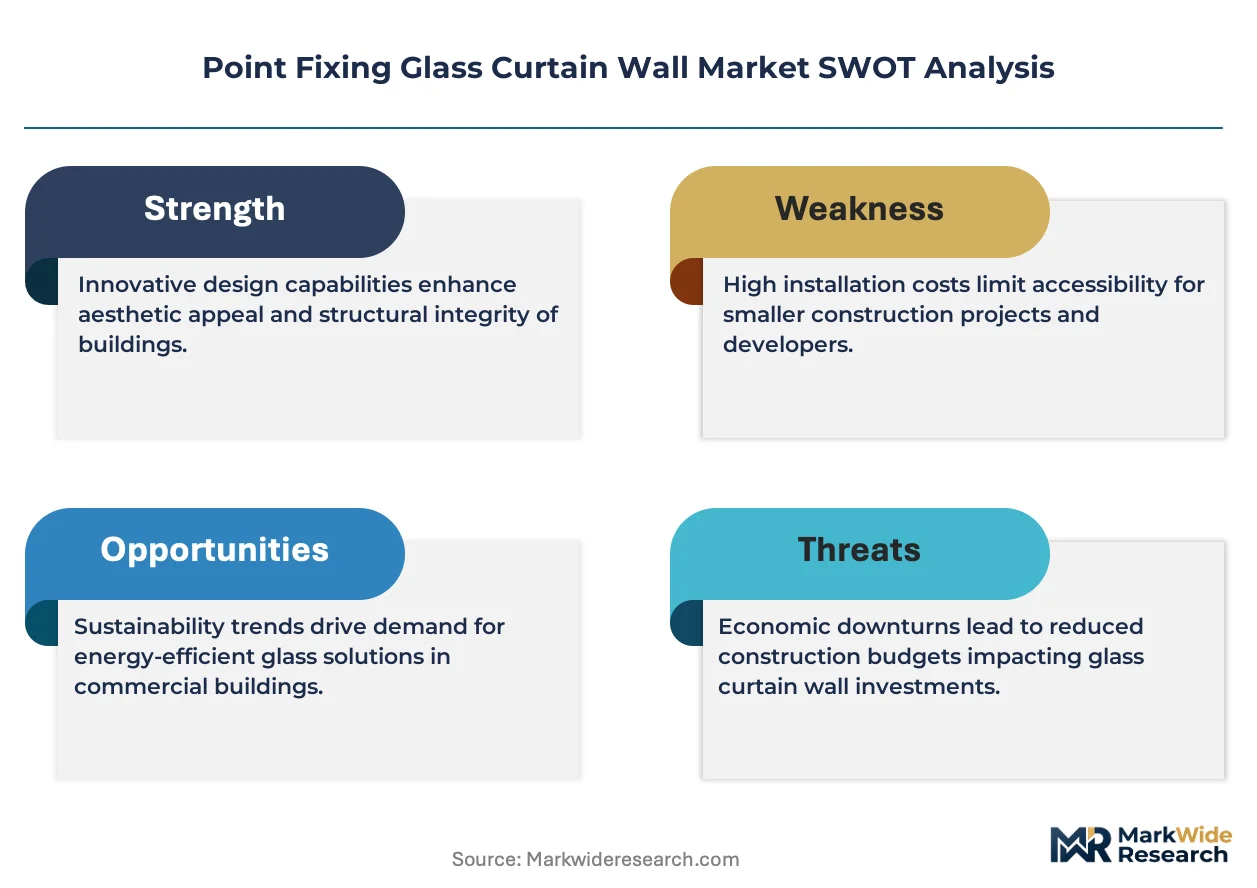
China's GB standards for wind load and seismic performance are compressing specification windows for point-fixing hardware, forcing manufacturers toward laminated insulated glass units with certified fatigue resistance.
Growth Catalysts
- Seismic code upgrades:China's GB 50011 and Japan's Building Standard Law now mandate point-fixed laminated glass in high-rise zones, pulling specification toward spider fitting systems with documented ductility.
- Supertall construction clusters:Shenzhen, Shanghai, and Beijing developers specify cable net facades for signature towers, concentrating demand for tensioned stainless steel hardware.
- Institutional trophy assets:Hospitality and sports complex owners prioritize uninterrupted sightlines, specifying patch plate and tension rod systems that maximize optical transparency.
Market Restraints
- Specialized glass supply concentration:Oversized tempered and heat-soaked lites require captive furnace capacity concentrated among three major fabricators, creating bottleneck risk.
- Stainless steel price volatility:Spider fittings and tension cables consume grade 316 alloy, exposing fabricators to nickel and molybdenum commodity swings.
- Structural silicone substitution:Unitized stick systems with continuous framing compete for mid-rise commercial work, compressing point-fixing addressable share in volume segments.
Strategic Opportunities
- Retrofit envelope modernization:Aging curtain wall stock in London, Singapore, and Dubai creates replacement demand for point-fixed glass systems with improved thermal performance.
- Photovoltaic glass convergence:Building-integrated PV laminates paired with spider fittings enable power-generating facades in European commercial bids.
- Performance-based procurement:Developers in the UAE and Saudi Arabia are shifting from component specification to whole-facade performance contracts, favoring integrated system suppliers.
Industry Challenges
- Structural engineer scarcity:Cable net and tension structure design requires specialized finite element modeling expertise concentrated among senior practitioners in Shanghai and Tokyo.
- Multi-jurisdiction certification timelines:Hardware fatigue testing under China's GB/T, Europe's CE marking, and Dubai's DCL protocols extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point Fixing Glass Curtain Wall Market |
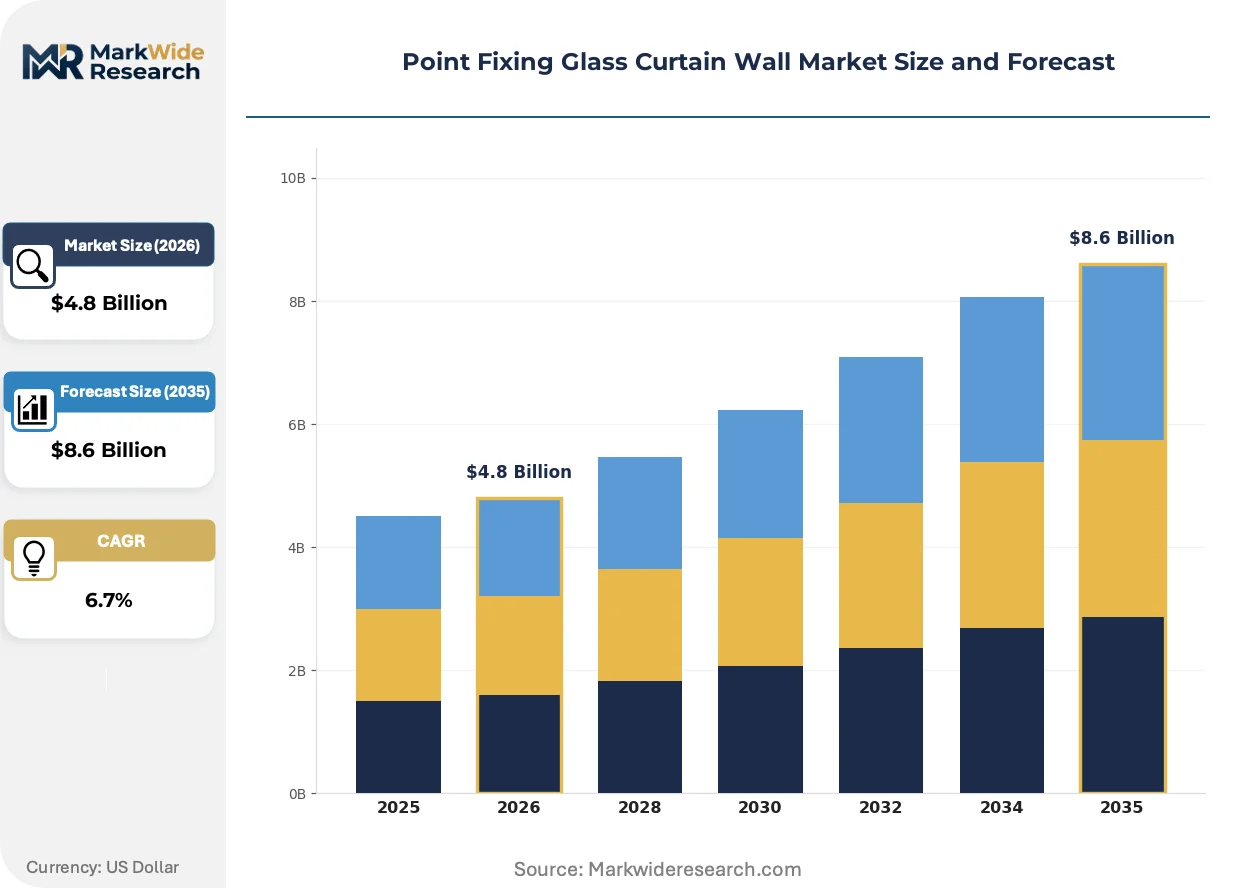
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spider Fittings, Patch Fittings, Bolt Fittings, Cable Net Systems, Structural Silicone Glazing Technology: Tempered Glass, Laminated Glass, Insulated Glass Units, Frosted Glass, Tinted Glass Application: Commercial Complexes, Institutional Buildings, Sports Complexes, Hospitality Establishments, Public Facilities End User: Architectural Firms, Construction Contractors, Facade Consultants, Real Estate Developers, Building Owners |
| Companies Covered | Apogee Enterprises, YKK Corporation, Enclos Corp, Oldcastle BuildingEnvelope, Kawneer, Schuco International KG, Yuanda China Holdings Limited, Permasteelisa, Benson Curtain Wall & Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point Fixing Glass Curtain Wall Market Trends and Innovations
Digital fabrication and material science are compressing hardware profiles while expanding glass span capabilities, reshaping how facade engineers balance transparency against structural redundancy.
Tensioned cable net systems are miniaturizing. These assemblies employ high-strength stainless steel strand arrays to suspend glazing without vertical mullions, enabling 15-meter clear spans. Five-star hospitality developers in Bangkok and Jakarta specify them for atrium enclosures. The technology is miniaturizing node hardware from 200mm to 80mm castings, reducing visual obstruction while maintaining code-compliant load paths.
China's GB 55015 energy efficiency standard now mandates thermal transmittance limits for envelope assemblies, disqualifying single-pane point-fixed configurations in new construction. Manufacturers respond with warm-edge spacer integration and low-emissivity coating specifications. High-latitude commercial towers in Harbin and Shenyang face the steepest compliance ramps.
Developer procurement teams now unbundle facade design from general contracting, engaging specialist consultants for performance specification. This disintermediation compresses traditional glazing subcontractor scope to installation-only. The pattern is most visible in Singapore and Hong Kong, where developer-led design-build entities retain envelope engineering in-house.
Point Fixing Glass Curtain Wall Market Segmentation
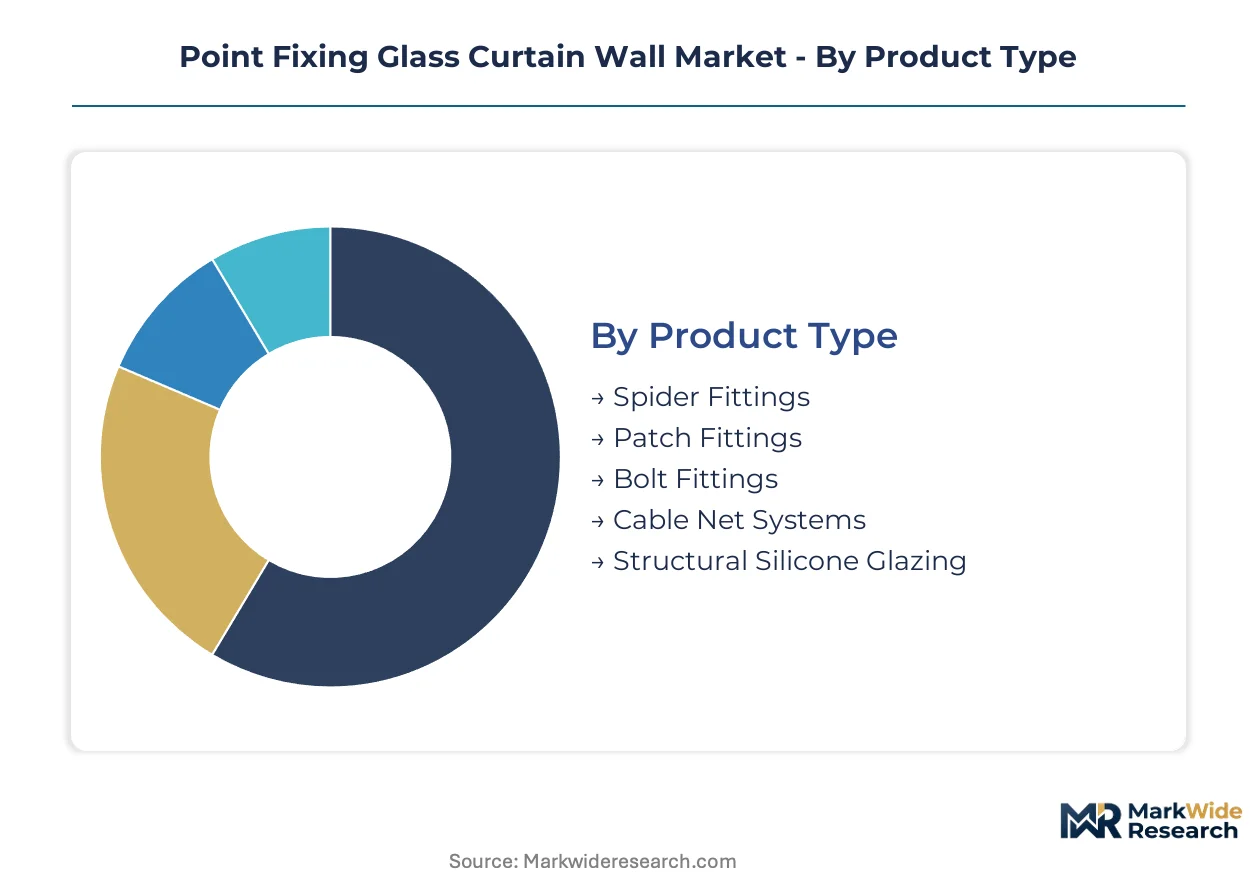
Point fixing glass curtain wall procurement fragments across hardware systems, glass technologies, and stakeholder workflows. Specification patterns diverge sharply between domestic trophy projects and export-driven volume contracts.
Product Type:
Spider fittings and cable net systems anchor domestic premium construction in China and Japan, while patch fittings and bolt hardware dominate Southeast Asian export shipments.
- Spider Fittings:Stainless steel castings with four or six arms suspend glazing panels at corner points, enabling uninterrupted sightlines. Shenzhen and Shanghai supertall towers specify these for atrium enclosures, driven by seismic code mandates for ductile connections under GB 50011.
- Cable Net Systems:Tensioned stainless steel strand arrays span up to 15 meters without vertical mullions, employing miniaturized 80mm node hardware. Bangkok and Jakarta hospitality developers specify these for signature facades, prioritizing optical transparency over structural redundancy.
- Patch Fittings:Surface-mounted plates secure glass through mechanical clamping, common in mid-rise commercial retrofits.
- Bolt Fittings:Through-bolt connections penetrate glass at drilled holes, specified where hardware concealment is secondary to load capacity.
- Structural Silicone Glazing:Adhesive bonding systems compete for projects where mechanical fixation is restricted by aesthetic or thermal performance requirements.
Spider fittings command the established base. The steepest expansion runs through cable net systems.
Technology:
Cost tiers separate monolithic tempered glass from premium laminated configurations, with thermal performance mandates reshaping specification toward insulated assemblies.
- Laminated Glass:Polyvinyl butyral interlayers bond multiple glass plies, containing fallout under blast or seismic events. China's GB standards now mandate laminated configurations in high-rise zones, pulling specification toward certified fatigue-resistant assemblies.
- Insulated Glass Units:Dual-pane assemblies with warm-edge spacers and low-emissivity coatings meet GB 55015 thermal transmittance limits. Harbin and Shenyang commercial towers face the steepest compliance ramps as single-pane point-fixed systems lose eligibility.
- Tempered Glass:Heat-treated monolithic lites occupy volume positions in standard commercial complexes where thermal performance requirements are less stringent.
- Frosted Glass:Acid-etched or sandblasted surfaces diffuse light for privacy-critical institutional applications.
- Tinted Glass:Body-colored substrates reduce solar gain in tropical climates, common in Singapore and Dubai specifications.
Insulated glass units are gaining share fastest. Laminated glass retains the premium tier.
Application:
Customer type dictates hardware complexity, with trophy asset developers funding cable net innovation while public procurement favors proven patch plate systems.
- Commercial Complexes:Office and retail towers in China's tier-one cities drive volume demand, specifying spider fittings for signature entrances and cable nets for atrium enclosures.
- Hospitality Establishments:Five-star hotel developers in Bangkok, Jakarta, and Dubai prioritize uninterrupted sightlines, specifying tension rod systems that maximize optical transparency.
- Sports Complexes:Arena and stadium projects employ long-span cable net facades where column-free viewing zones define design intent.
- Institutional Buildings:Government and cultural facilities specify blast-rated laminated assemblies with documented fallout containment.
- Public Facilities:Transit hubs and civic buildings balance durability against maintenance access constraints.
Commercial complexes anchor volume procurement. Hospitality establishments are climbing the fastest.
End User:
Procurement authority is shifting from general contractors toward specialist facade consultants and developer-led design-build entities.
- Real Estate Developers:Trophy asset sponsors in Singapore and Hong Kong now retain envelope engineering in-house, unbundling facade design from general contracting and compressing traditional glazing subcontractor scope.
- Facade Consultants:Specialist engineers perform finite element modeling for cable net and tension structures, with expertise concentrated among senior practitioners in Shanghai and Tokyo.
- Architectural Firms:Design practices specify hardware systems early in schematic phases, locking in transparency targets before structural engineering commences.
- Construction Contractors:General builders face scope compression to installation-only as developers disintermediate traditional glazing subcontractor relationships.
- Building Owners:Asset managers drive retrofit envelope modernization in London, Singapore, and Dubai, creating replacement demand for thermally improved point-fixed systems.
Real estate developers command procurement authority. Facade consultants are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spider fitting and cable net fabrication clusters concentrate in China's Yangtze and Pearl River Delta regions, with secondary capacity emerging in the UAE and Germany. Regulatory divergence across wind load, seismic, and thermal codes fragments certification pathways. Tier-one city construction booms in Asia-Pacific drive premium system specification.
China
Shenzhen, Shanghai, and Beijing supertall towers specify cable net facades for signature atrium enclosures. GB 50011 seismic mandates and GB 55015 thermal transmittance limits now disqualify single-pane point-fixed systems, pulling specification toward laminated insulated glass units with certified fatigue resistance. Yangtze River Delta fabricators dominate spider fitting production for domestic trophy assets.
United Arab Emirates
Dubai developer procurement teams unbundle facade design from general contracting, engaging specialist consultants for performance specification. Dubai Civil Defence and municipal building codes impose reflective glazing constraints near flight paths, complicating material selection. Performance-based procurement contracts favor integrated system suppliers for commercial tower envelopes.
Japan
Tokyo and Osaka institutional bids specify spider fittings with documented ductility under Building Standard Law seismic provisions. METI energy efficiency guidelines push envelope thermal performance upgrades in high-rise zones. Kanto region facade consultants concentrate finite element modeling expertise for tension structure design.
Germany
Frankfurt and Munich commercial retrofits create replacement demand for thermally improved point-fixed systems. CE marking framework enforces hardware fatigue testing protocols distinct from Asian certification regimes, extending product launch timelines. Bavaria-based fabricators serve Central European institutional bids with laminated glass assemblies.
Singapore
Developer-led design-build entities retain envelope engineering in-house, compressing traditional glazing subcontractor scope to installation-only. Tropical climate thermal performance codes mandate low-emissivity coatings and warm-edge spacer integration. Marina Bay and Orchard Road hospitality developments prioritize uninterrupted sightlines via tension rod systems.
Point Fixing Glass Curtain Wall Market Competitive Landscape
Concentration sits with vertically integrated fabricators controlling captive glass tempering capacity and in-house spider fitting production. The vendor base stratifies across three tiers: multinational system integrators with project management capabilities, regional specialists dominating domestic trophy bids, and installation-focused subcontractors facing scope compression. Competitive positioning hardens around M&A activity targeting facade engineering consultancies and capacity expansion into oversized heat-soaked glass furnaces.
Among North American fabricators, Apogee Enterprises anchors the integrated tier with captive fabrication capabilities. YKK Corporation exemplifies hardware-to-systems integration dominance in Japanese institutional markets. Yuanda China Holdings Limited occupies the cost-leadership position through in-house production of spider fittings and structural silicone glazing kits.
| Leading Market Players |
|---|
| Apogee Enterprises |
| YKK Corporation |
| Enclos Corp |
| Oldcastle BuildingEnvelope |
| Kawneer |
| Schuco International KG |
| Yuanda China Holdings Limited |
| Permasteelisa |
| Benson Curtain Wall & Glass |
| Others |
Pricing and Supply Chain Analysis
Captive heat-soaked glass furnace capacity concentrated among Yangtze River Delta fabricators creates scale thresholds that lock out smaller competitors while anchoring price floors for oversized tempered lites. This concentration amplifies procurement leverage for trophy asset developers in Shenzhen and Shanghai, compressing margins for installation-only subcontractors.
Pricing Analysis
Volume-discount tiering separates spider fitting systems for supertall towers from patch plate hardware for mid-rise commercial retrofits. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade under GB/T fatigue protocols and thermal performance under GB 55015. Price erosion runs through standard commercial segments as unitized stick systems compete for mid-rise envelopes. Public procurement teams in Southeast Asia exhibit highest price sensitivity, while Singapore developer-led design-build entities prioritize performance specification over unit cost.
Supply Chain Analysis
Strait of Malacca transit routes for Indonesian nickel and Australian molybdenum concentrate feed grade 316 stainless steel production for spider castings and tension cables. Manufacturing gravity centers on China's Jiangsu and Guangdong provinces, with secondary forging capacity in Japan's Kansai region and Germany's Bavaria cluster. Raw material sourcing draws from South African chromium, Philippine nickel laterite, and domestic Chinese ferroalloy production. Single-source vulnerability concentrates in oversized heat-soaked glass furnaces operated by three major fabricators. Distribution runs through developer-led design-build entities in Singapore and Hong Kong that unbundle facade specification from general contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The point fixing glass curtain wall market is recovering from cyclical trough conditions as China's tier-one city supertall construction accelerates and seismic code upgrades mandate laminated system replacement cycles.
For Market Incumbents: Fortify captive fabrication capacity for oversized tempered lites and heat-soaked glass units against bottleneck risk from concentrated furnace operators. Deepen backward integration into spider fitting castings and structural silicone glazing kits to defend margin position against stainless steel commodity volatility. Prioritize certification investment under Dubai Civil Defence and Singapore thermal performance codes to maintain specification access in premium trophy asset pipelines.
For New Entrants and Emerging Players: Differentiate on cable net system miniaturization and finite element modeling services for tension structure design. Target European commercial retrofit envelopes in Frankfurt and Munich where aging curtain wall stock creates replacement demand for thermally improved point-fixed systems. Pursue performance-based procurement contracts in UAE and Saudi Arabia that favor integrated system suppliers over component vendors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among facade engineering consultancies with retained envelope design mandates from Singapore and Hong Kong developer-led entities. Long-term viability hinges on exposure to seismic code upgrade cycles and energy efficiency mandate compliance ramps. Monitor GB 55015 thermal transmittance enforcement intensity as inflection indicator for insulated glass unit specification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Oversized heat-soaked glass furnace additions in Yangtze River Delta relieve supply bottleneck for supertall tower projects. |
| Backward Integration | In-house spider fitting production underwrites cost leadership against nickel and molybdenum commodity volatility. |
| Certification Investment | GB/T fatigue testing and CE marking acquisition accelerates product launch timelines for export portfolios. |
| Performance-Based Procurement | Whole-facade contracts in UAE favor integrated suppliers with structural engineering and installation capabilities. |
| Specialist Consultancy Acquisition | Facade engineering firms with finite element modeling expertise capture developer-led design-build mandates. |
Research Methodology
A standing panel of facade consultants, curtain wall procurement directors, structural engineers, and glass fabrication plant managers provided ongoing calibration against field conditions. Primary interviews with developer-led design-build entities in Singapore and Hong Kong, spider fitting manufacturers in Jiangsu province, and cable net system installers in Bangkok and Jakarta were cross-referenced against secondary validation from GB standards documentation, Dubai Civil Defence technical circulars, SEC filings of listed building envelope companies, and project development databases for supertall towers. Bottom-up unit economics for hardware systems and top-down construction spend allocation were triangulated to anchor volume estimates.
Consistency checks against external benchmarks validated projection outputs across the analysis window. The analytical framework modeled segmentation dimensions spanning hardware system type, glass technology tier, application vertical, and procurement authority archetype. CAGRs were derived from installed base growth, replacement cycle timing, and specification mix shifts toward laminated insulated glass units. Industry-specific forecast inputs incorporated GB 50011 seismic mandate enforcement trajectories and GB 55015 thermal transmittance compliance ramps in high-latitude Chinese cities.
Material uncertainties — nickel and molybdenum commodity swings, multi-jurisdiction certification timeline extensions, and structural engineer scarcity for tension structure design — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued supertall construction concentration in China's tier-one cities and sustained developer preference for optical transparency in hospitality and sports complex assets. Practitioners should keep alternative scenarios live as stainless steel price volatility and unitized stick system competitive displacement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Cross-Laminated Timber Market
Building & Construction Materials
Fire Rated Duct Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
Global Hydraulic Door Closer Market
Building & Construction Materials
GCC Concrete Blocks Market
Building & Construction Materials
Artificial Wood Beams Market
Building & Construction Materials
Porcelain Tiles Market
Building & Construction Materials
Plastic Door and Window Market
Building & Construction Materials
Cement Grinding Aids Market
Building & Construction Materials
China Oriented Strand Board Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market
Building & Construction Materials
GCC Ceramic Tiles Market
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
Balustrade Market