
 Friction Washer Market | 2026-2036
Friction Washer Market Size, Share, and Industry Trends Forecast 2026-2036
Friction Washer Market Analytics
Multi-source procurement for precision torque components is rebalancing as OEMs seek supply chain resilience against raw-material volatility. KSB SE & Co. KGaA anchors European demand through its specialized pump and valve adjacency, while Coperion leverages polymer processing expertise to compete in composite washer applications. Eaton Corporation differentiates through integrated motion-control portfolios that bundle friction washers with electromechanical systems.
A friction washer is a mechanical component engineered to generate controlled resistance between mating surfaces, typically manufactured from hardened steel, sintered bronze, or fiber-reinforced composites with specified coefficients of friction ranging from 0.15 to 0.45. These devices transmit torque, damp vibration, or maintain preload in bolted joints across industrial machinery, vehicle drivetrains, and power transmission equipment. Electric washers command the largest product-type share due to their compatibility with automated assembly systems, while pneumatic variants represent the fastest-growing segment as compressed-air infrastructure expands in Southeast Asian manufacturing hubs. Steel dominates material consumption for heavy-load applications, though aluminum and composite alternatives gain share where weight reduction governs design priorities in automotive and aerospace supply chains.
ISO 898-1 governs mechanical properties of carbon steel and alloy steel fasteners, directly specifying friction washer performance under preload conditions in international trade. The EPA regulates volatile organic compound emissions from coating and surface-treatment processes, pushing manufacturers toward aqueous cleaning and dry-deposition technologies that alter washer finishing economics. China's GB standards and the EU Machinery Directive impose additional conformity requirements that shape export-market access and product certification costs. Stakeholders must monitor evolving carbon-border adjustment mechanisms and material traceability mandates that will redefine competitive positioning in washer procurement decisions.
Market Dynamics
Automotive electrification is compressing replacement cycles for traditional friction washers while simultaneously opening specifications for lightweight composite variants in battery-electric drivetrains.
Growth Catalysts
- REACH compliance deadlines:European coating restrictions are accelerating aqueous surface-treatment adoption, expanding addressable demand for pre-treated washer suppliers certified to ECHA standards.
- Compressed-air infrastructure buildout:Southeast Asian manufacturing clusters are installing pneumatic assembly systems faster than electric alternatives, pulling pneumatic washer procurement ahead of historical baselines.
- Fiber-reinforced composites:Automotive weight-reduction mandates are displacing steel in torque-transmission applications where sintered bronze once dominated.
Market Restraints
- Alloy steel price volatility:Hardened steel feedstock costs swing with scrap-metal and energy markets, compressing margin predictability for high-volume stamped-washer producers.
- German supply concentration:Precision torque-component tooling and heat-treatment capacity clusters disproportionately in Baden-Württemberg and Bavaria, creating geographic vulnerability to energy-price shocks.
- Electromechanical substitution:Integrated torque-vectoring motors in electric vehicles are eliminating discrete friction interfaces in differential assemblies.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for automotive component manufacturing are attracting greenfield washer capacity to Tamil Nadu and Gujarat industrial corridors.
- GB standards alignment:Exporters achieving dual ISO 898-1 and GB/T 3098.1 certification unlock access to Chinese OEM supplier lists previously closed to single-standard manufacturers.
- Digital torque monitoring:Sensor-embedded smart washers that transmit preload data are converging with Industrial IoT platforms in predictive maintenance contracts.
Industry Challenges
- Heat-treatment skill scarcity:Vacuum carburizing and induction-hardening technician shortages in Midwest US manufacturing hubs are extending qualification timelines for new production lines.
- Dual-carbon traceability:Scope 3 emissions documentation requirements from EU importers are forcing tier-two suppliers to reconfigure metallurgical sourcing without mature certification infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Friction Washer Market |
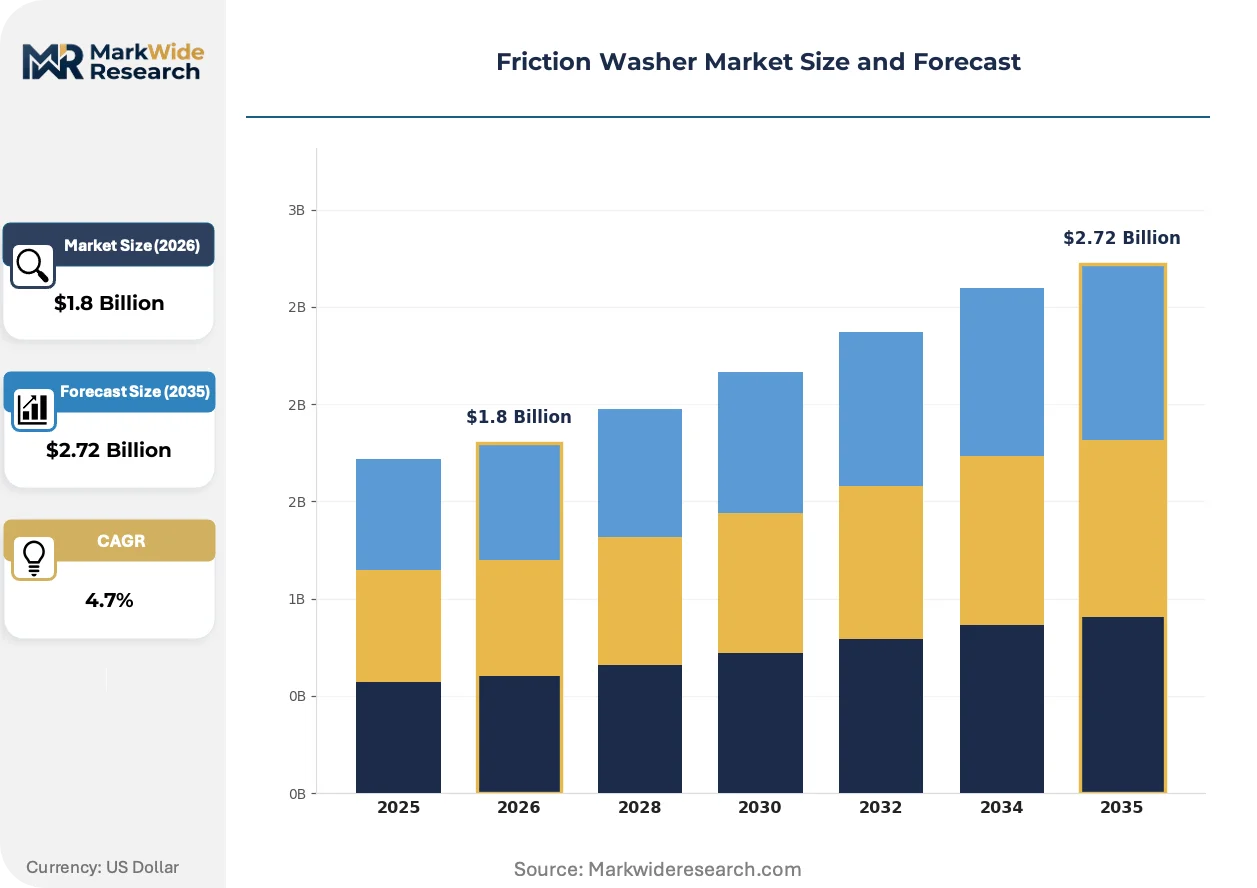
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Washers, Electric Washers, Pneumatic Washers, Hydraulic Washers End User: Manufacturing Facilities, Automotive Industry, Construction Sector, Food Processing Material: Steel, Aluminum, Plastic, Composite Application: Cleansing, Surface Preparation, Maintenance, Assembly |
| Companies Covered | Baldor Electric Company, KSB SE & Co. KGaA, Eaton Corporation, KraussMaffei Berstorff, Mitsubishi Heavy Industries, Bühler Group, Coperion, Schneider Electric, Maguire Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Friction Washer Market Evolving Landscape
Material science advances and assembly-automation demands are rewriting friction-washer specifications faster than historical revision cycles permitted.
Carbon-fiber-reinforced polyetheretherketone (PEEK) compounds are integrating into aerospace and high-performance automotive torque paths where thermal stability above 250°C is non-negotiable. Tier-one suppliers in Stuttgart and Detroit are qualifying these composites for transmission clutch packs at three-year replacement intervals rather than traditional ten-year steel baselines. The technology is integrating vibration-damping and corrosion immunity into single components that previously required multi-material stacks.
EPA volatile organic compound rules are eliminating solvent-based phosphate conversion coatings from US-sourced washers, forcing suppliers to adopt dry-film lubricant deposition or plasma electrolytic oxidation. Surface-finishing capital costs have risen accordingly, favoring suppliers with captive coating capacity over job-shop dependent competitors. Heavy-truck and off-highway equipment manufacturers in the Great Lakes region are most affected, with several converting to European-imported pre-coated blanks to bypass domestic treatment bottlenecks.
Automotive OEMs are consolidating supplier lists from thirty-plus friction-component vendors to six-to-eight strategic partners with full-stack torque-system capability. This consolidation is compressing quoting cycles and unbundling traditional aftermarket service obligations from original equipment contracts. German and Japanese automakers are furthest along this path, with Chinese EV manufacturers now replicating the model in their Ningbo and Xi'an supplier parks.
Friction Washer Market Segmentation
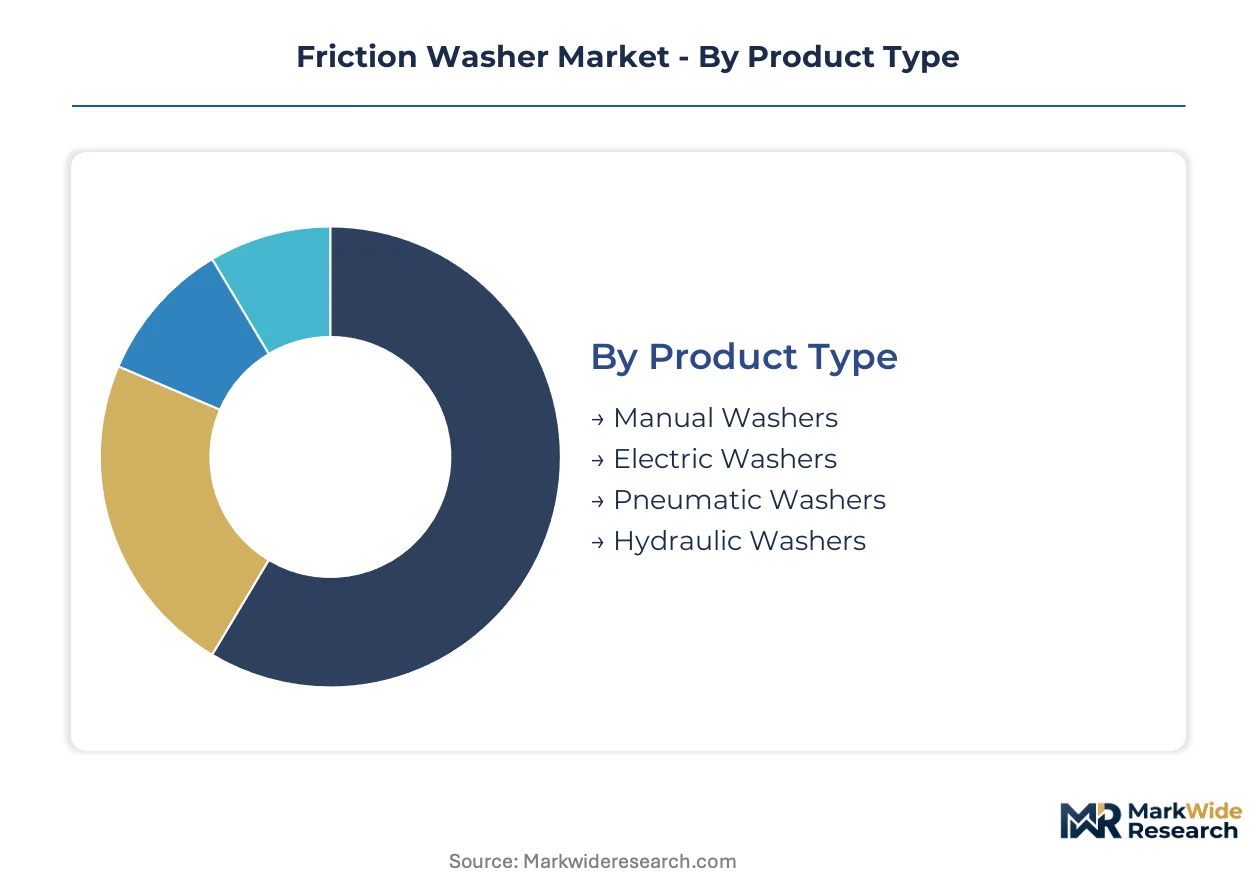
Friction washer procurement decisions diverge sharply across torque requirements, environmental exposure, and assembly automation levels. Specification engineers weight material fatigue limits against coating compliance costs when mapping washer categories to equipment platforms.
Product Type:
Automation integration depth determines capital allocation across powered and manual alternatives.
- Electric Washers:Servo-controlled torque delivery with programmable preload settings dominates automotive final-assembly lines in Germany and Michigan. Plant electrification mandates and precision repeatability requirements sustain procurement volume despite higher unit costs than pneumatic equivalents.
- Pneumatic Washers:Compressed-air actuation delivers higher power-to-weight ratios for heavy-equipment manufacturing in Thailand and Vietnam. Southeast Asian infrastructure buildout is pulling procurement ahead of historical baselines as factory automation accelerates in Ho Chi Minh City and Bangkok industrial zones.
- Manual Washers:Hand-torque tools persist in maintenance operations and low-volume custom fabrication where capital equipment amortization is impractical.
- Hydraulic Washers:Fluid-pressure systems serve mining and offshore applications requiring torque multiplication beyond pneumatic or electric capacity limits.
Volume sits with Electric Washers; growth tilts toward Pneumatic Washers.
End User:
Regulatory exposure and production scale separate capital-intensive OEMs from intermittent-maintenance operators.
- Automotive Industry:Just-in-time assembly demands ISO 898-1 certified washers with lot-traceable heat-treatment records. Battery-electric drivetrain redesigns are compressing replacement cycles while opening specifications for lightweight composite variants in Ningbo and Stuttgart supplier parks.
- Manufacturing Facilities:General industrial machinery maintenance generates steady aftermarket demand across Midwest US and Ruhr Valley metalworking clusters. Predictive maintenance contracts are embedding sensor-enabled smart washers that transmit preload data to Industrial IoT platforms.
- Construction Sector:Mobile equipment and temporary infrastructure projects favor rental-fleet compatibility and field-serviceability over precision specifications.
- Food Processing:Stainless-steel and polymer washers with FDA-compliant surface finishes serve washdown environments where corrosion resistance and contamination prevention override torque-density priorities.
Procurement scale clusters in Automotive Industry; specification evolution runs fastest in Manufacturing Facilities.
Material:
Load-bearing requirements and weight-reduction mandates create divergent sourcing economics across metallurgical and polymer alternatives.
- Steel:Hardened carbon and alloy grades dominate heavy-load power transmission where yield strength exceeds 800 MPa. Vacuum carburizing capacity constraints in Baden-Württemberg and Ohio are extending lead times for precision-grade washers.
- Composite:Carbon-fiber-reinforced PEEK compounds integrate into aerospace clutch packs and battery-electric drivetrains where thermal stability above 250°C is non-negotiable. Stuttgart and Detroit tier-one suppliers are qualifying these materials at three-year replacement intervals.
- Aluminum:Lightweight alloys serve automotive chassis and suspension applications where corrosion immunity and mass reduction govern design priorities.
- Plastic:Injection-molded polymer washers address low-torque consumer goods and electronics assembly where electrical isolation and cost minimization outweigh mechanical performance.
Steel commands installed base dominance; composites claim the steepest expansion trajectory.
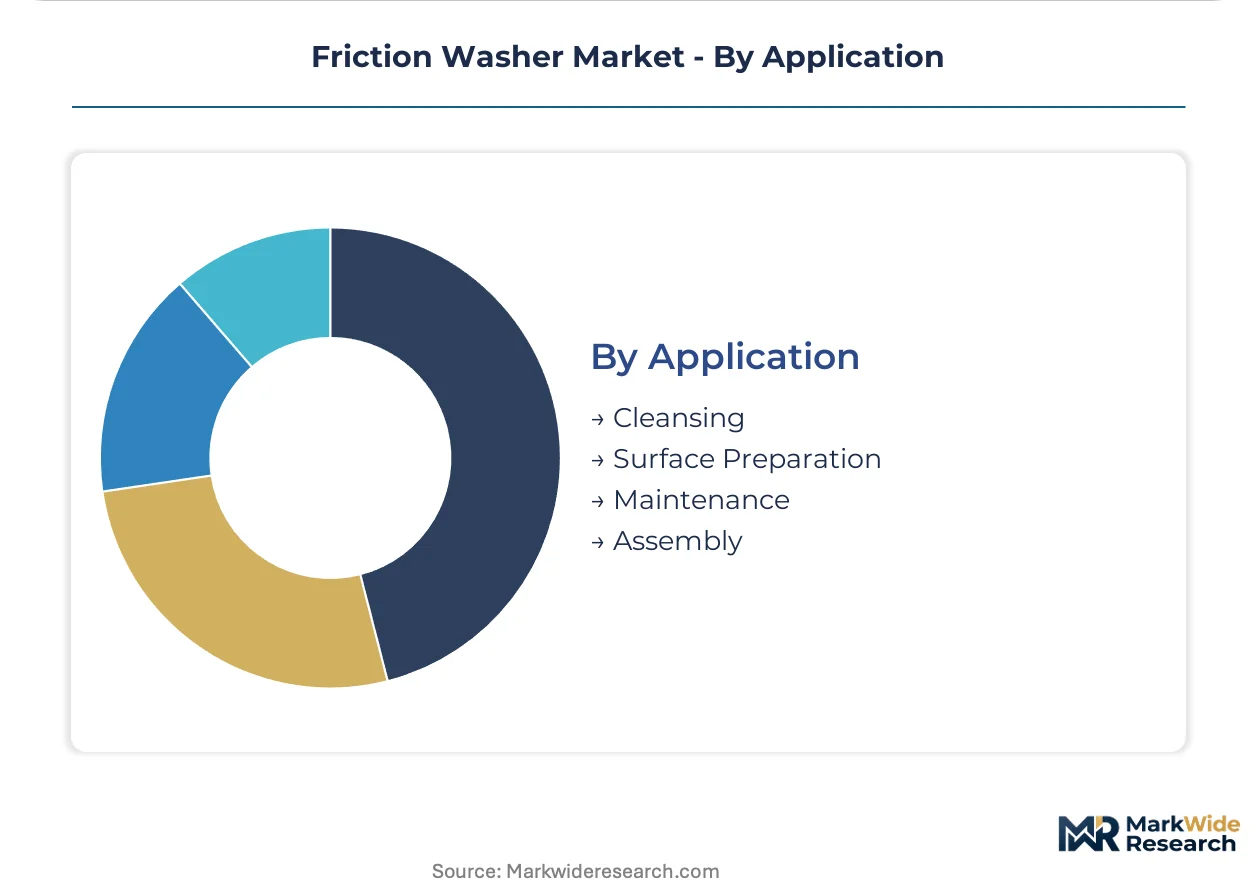
Application:
Process stage and contamination sensitivity determine surface-treatment and geometry specifications.
- Assembly:Precision torque control in automated fastening operations demands washers with calibrated friction coefficients and dimensional tolerances tighter than 0.05 mm. REACH-compliant coating restrictions are accelerating aqueous surface-treatment adoption for European-sourced components.
- Maintenance:Field-service replacement cycles favor interchangeable geometries and standardized preload specifications that minimize technician training and inventory complexity.
- Cleansing:High-pressure washing equipment requires corrosion-resistant washers with sealed bearing surfaces that prevent media ingress.
- Surface Preparation:Abrasive blasting and coating preparation tools utilize sacrificial washer designs that tolerate accelerated wear rates.
Assembly absorbs the largest washer volume; Cleansing applications post the fastest specification upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Friction washer procurement concentrates in three manufacturing powerhouses where automotive electrification and industrial automation are rewriting component specifications. Germany, China, and the United States absorb the dominant share of precision torque-component orders, though Southeast Asian infrastructure buildout is accelerating pneumatic washer adoption outside traditional demand centers.
Germany
Baden-Württemberg and Bavaria host precision heat-treatment clusters that supply Stuttgart automotive OEMs with vacuum-carburized steel washers. REACH compliance deadlines from ECHA are forcing aqueous surface-treatment conversions among coating suppliers in the Ruhr Valley. Tier-one drivetrain manufacturers in Munich are qualifying carbon-fiber-reinforced PEEK composites for three-year replacement cycles in battery-electric vehicles.
China
Ningbo and Xi'an supplier parks are replicating German OEM consolidation models, compressing vendor lists from thirty-plus friction-component suppliers to six-to-eight strategic partners. GB/T 3098.1 certification requirements from SAMR are creating dual-standard compliance costs for exporters seeking access to domestic OEM lists. MIIT industrial policy is channeling washer procurement toward local content targets in Yangtze River Delta manufacturing corridors.
United States
Michigan automotive final-assembly lines sustain electric washer volume despite higher unit costs than pneumatic alternatives. EPA volatile organic compound rules are eliminating solvent-based phosphate coatings, pushing Great Lakes heavy-truck manufacturers toward European-imported pre-coated blanks. Midwest vacuum carburizing technician shortages are extending qualification timelines for new production lines in Ohio manufacturing hubs.
Japan
Chubu and Kansai industrial regions maintain specialized torque-component tooling capacity serving precision machinery and robotics OEMs. METI carbon-neutrality roadmaps are pressuring heat-treatment facilities to shift from gas-fired to electric furnace operations. JIS standard alignment with ISO 898-1 is smoothing export certification for Osaka-based washer suppliers targeting Southeast Asian markets.
Vietnam
Ho Chi Minh City industrial zones are installing pneumatic assembly systems faster than electric alternatives, pulling washer procurement ahead of historical baselines. Compressed-air infrastructure buildout in Thai Nguyen and Binh Duong provinces is attracting contract manufacturing migration from China. Local content rules are gradually tightening, though GB standards familiarity among Chinese expatriate managers eases technical transitions.
Friction Washer Market Competitive Landscape
Supplier list consolidation dominates the current landscape as automotive OEMs compress vendor rosters from thirty-plus friction-component vendors to six-to-eight strategic partners with full-stack torque-system capability. The vendor base fragments between hardened-steel stampers serving heavy-load power transmission and composite specialists targeting aerospace and battery-electric drivetrains. Three archetypes occupy distinct competitive positions: integrated motion-control bundlers, polymer processing specialists leveraging composite expertise, and precision pump-and-valve adjacency players. M&A activity and captive coating capacity expansion represent the dominant competitive moves, as surface-finishing capital costs rise under EPA and REACH compliance pressures.
Among European-based industrial conglomerates, KSB SE & Co. KGaA and Eaton Corporation occupy positions within the integrated systems tier, while Coperion exemplifies the polymer processing specialist archetype. These three anchors represent contrasting strategic postures: pump-and-valve adjacency, motion-control bundling, and composite material science respectively. Their collective presence illustrates how washer procurement decisions increasingly favor suppliers with adjacent torque-system capabilities rather than standalone component vendors.
| Leading Market Players |
|---|
| Baldor Electric Company |
| KSB SE & Co. KGaA |
| Eaton Corporation |
| KraussMaffei Berstorff |
| Mitsubishi Heavy Industries |
| Bühler Group |
| Coperion |
| Schneider Electric |
| Maguire Products |
| Others |
Value Network & Pricing Analysis
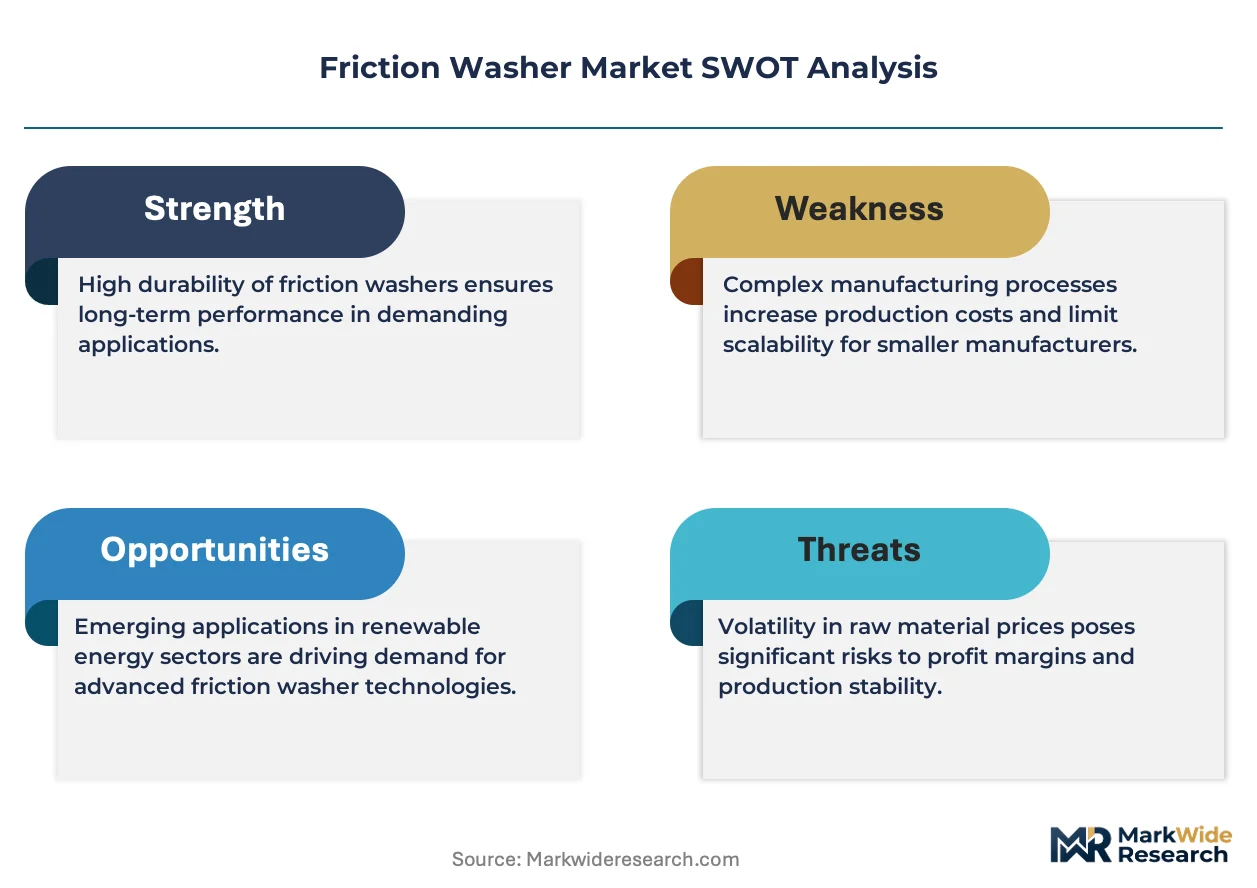
Alloy steel feedstock costs swing from Baden-Württemberg mills through to stamped-washer pricing tiers, compressing margin predictability for high-volume producers while REACH-compliant coating investments push premium-grade suppliers toward aqueous surface-treatment premiums.
Pricing Analysis
High-volume electric washer contracts trade at thin margins while precision composite variants capture premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates ISO 898-1 certified vacuum-carburized washers from untreated commodity stampings. Cost compression in standard-grade steel washers is intensifying because of scrap-metal volatility and energy-price exposure. Fleet maintenance operators in the Great Lakes region exhibit the highest price sensitivity, whereas Stuttgart OEMs prioritize lot-traceable heat-treatment records over unit cost.
Supply Chain Analysis
Hardened steel supply rests on German heat-treatment clusters in Baden-Württemberg and Bavaria, Chinese stamping capacity in Ningbo and Xi'an, and Midwest US vacuum carburizing facilities in Ohio. Carbon-fiber-reinforced PEEK compounds draw from polymer processing specialists in Stuttgart and Detroit. Single-source vulnerability concentrates in precision heat-treatment tooling where technician shortages extend qualification timelines. Distribution runs through Tier 1 drivetrain manufacturers consolidating vendor lists to six-to-eight strategic partners with full-stack torque-system capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The friction washer market sits in a technology-transition phase as carbon-fiber-reinforced PEEK composites displace sintered bronze and hardened steel in battery-electric drivetrain torque paths.
For Market Incumbents: Extend captive coating capacity to capture REACH and EPA compliance premiums before job-shop dependent competitors recover. Backward integration into vacuum carburizing equipment insulates against heat-treatment technician scarcity in Midwest US and German manufacturing hubs. Defensive consolidation around full-stack torque-system capability counters electromechanical substitution threats from integrated torque-vectoring motors. For New Entrants and Emerging Players: Capture pneumatic washer procurement acceleration in Ho Chi Minh City and Bangkok industrial zones where compressed-air infrastructure buildout outpaces electric automation adoption. White-space availability concentrates in sensor-embedded smart washers converging with Industrial IoT predictive maintenance contracts. Go-to-market positioning through GB/T 3098.1 certification unlocks access to Chinese OEM supplier lists previously closed to single-standard manufacturers. For Investors and Strategic Acquirers: Tier-one supplier consolidation from thirty-plus vendors to six-to-eight strategic partners is the leading indicator that polymer processing specialists with composite qualification capabilities will command acquisition premiums. Long-term viability favors suppliers with adjacent torque-system portfolios over standalone component vendors. Watch for carbon-border adjustment mechanism implementation signals that will reconfigure metallurgical sourcing economics for EU-bound exports.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Coating Capacity Expansion | REACH and EPA compliance investments favor in-house surface-treatment over job-shop dependency in Ruhr Valley and Great Lakes regions. |
| Composite Material Qualification | Carbon-fiber-reinforced PEEK approval for three-year replacement cycles opens battery-electric drivetrain specifications in Stuttgart and Detroit. |
| Dual-Standard Certification Investment | Simultaneous ISO 898-1 and GB/T 3098.1 compliance unlocks Chinese OEM supplier access for European and North American exporters. |
| Sensor-Embedded Smart Washer Development | Preload data transmission capability converges with Industrial IoT platforms in predictive maintenance contracts across Midwest US metalworking clusters. |
| Heat-Treatment Technician Pipeline Development | Vacuum carburizing and induction-hardening skill scarcity in Ohio and Baden-Württemberg threatens new production line qualification timelines. |
Research Methodology
Trade flow databases, SEC 10-K filings, and ECHA regulatory submissions formed the secondary backbone of this analysis. Primary interviews with Tier 1 automotive procurement directors, heat-treatment plant managers in Baden-Württemberg, polymer processing R&D leads, and aftermarket service heads validated segment sizing and growth assumptions. Bottom-up shipment data triangulated against top-down OEM production forecasts established volume baselines across electric, pneumatic, and manual washer categories.
Historical trendline analysis of washer procurement patterns across automotive electrification cycles informed the projection framework. Segmentation modeling incorporated product type, material grade, end-use industry, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from regression analysis of capital equipment replacement cycles and compressed-air infrastructure buildout trajectories. Battery-electric drivetrain redesign specifications and REACH compliance deadline impacts served as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon-border adjustment mechanism implementation and electromechanical substitution rates in differential assemblies. Forecasts reflect documented assumptions regarding alloy steel price volatility and heat-treatment capacity expansion. Scope 3 emissions documentation requirements and technician pipeline development warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Bottle Jack Market
Tools
Fiber Laser Cutting Machines Market
Tools
Manual Cutting Equipment Market
Tools
Hydraulic Torque Wrench Market
Tools
Power Press Machines Market
Tools
Handheld Pipe Cutter Market
Tools
Europe Stump Cutter/Grinder Market
Tools
Woodworking CNC Tools Market
Tools
Cordless Fillet Weld Grinder Market
Tools
Global Swaging Machine Market
Tools
Log Splitters Market
Tools
Sanding Machine Market
Tools
Mallets and Sledgehammers Market
Tools
Powder Compacting Pressers Market
Tools
Industrial Ladder Market
Tools
Wood-Burning Tool Market