
 Metal Roofing Market | 2026-2036
Metal Roofing Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Roofing Market Intelligence
Direct-to-contractor distribution through specialized building material suppliers is narrowing the path from factory to job site. Kingspan Group plc leverages its portfolio of insulated metal panels to serve the high-performance commercial building sector. Cornerstone Building Brands competes on manufacturing scale and a broad product offering across North America. Nucor Corporation positions itself with significant control over upstream steel production, influencing raw material costs.
Metal roofing consists of sheet metal products, such as panels or shingles, formed from materials like steel and aluminum. These systems, often featuring durable Kynar paint coatings and gauges between 22 and 29, provide long-term weather protection for a building's exterior. Steel remains the dominant material type due to its strength and cost advantages, while aluminum is preferred in coastal environments. The residential end-user segment is expanding rapidly as homeowners prioritize longevity and storm resistance over traditional materials.
Product acceptance is governed by building codes, such as the International Building Code in the United States, and performance standards for wind uplift and fire resistance. In Europe, CE marking under the Construction Products Regulation ensures products meet harmonized safety and performance criteria. Future material selection will increasingly balance initial installation cost against total lifecycle value and compliance with stricter energy efficiency mandates.
Market Dynamics
Heightened focus on building resilience against severe weather, coupled with stringent energy efficiency mandates, is the central force shaping the metal roofing market. This dual pressure accelerates the replacement of traditional materials with high-performance, long-lifecycle metal systems.
Growth Catalysts
- Energy Efficiency Standards:The US ENERGY STAR program and the EU Green Deal incentivize cool roofing technologies. These standards create demand for reflective metal roofs that lower building energy consumption.
- Residential Sector Modernization:Homeowners in storm-prone regions, particularly the coastal United States, are increasingly selecting metal roofing for its superior wind uplift and impact resistance. This trend displaces conventional asphalt shingles.
- Coating and Paint Innovations:Advances in Kynar paint and other PVDF coatings extend the aesthetic and functional lifespan of metal panels. These coatings offer superior color retention and resistance to chalking and fading, boosting consumer acceptance.
Market Restraints
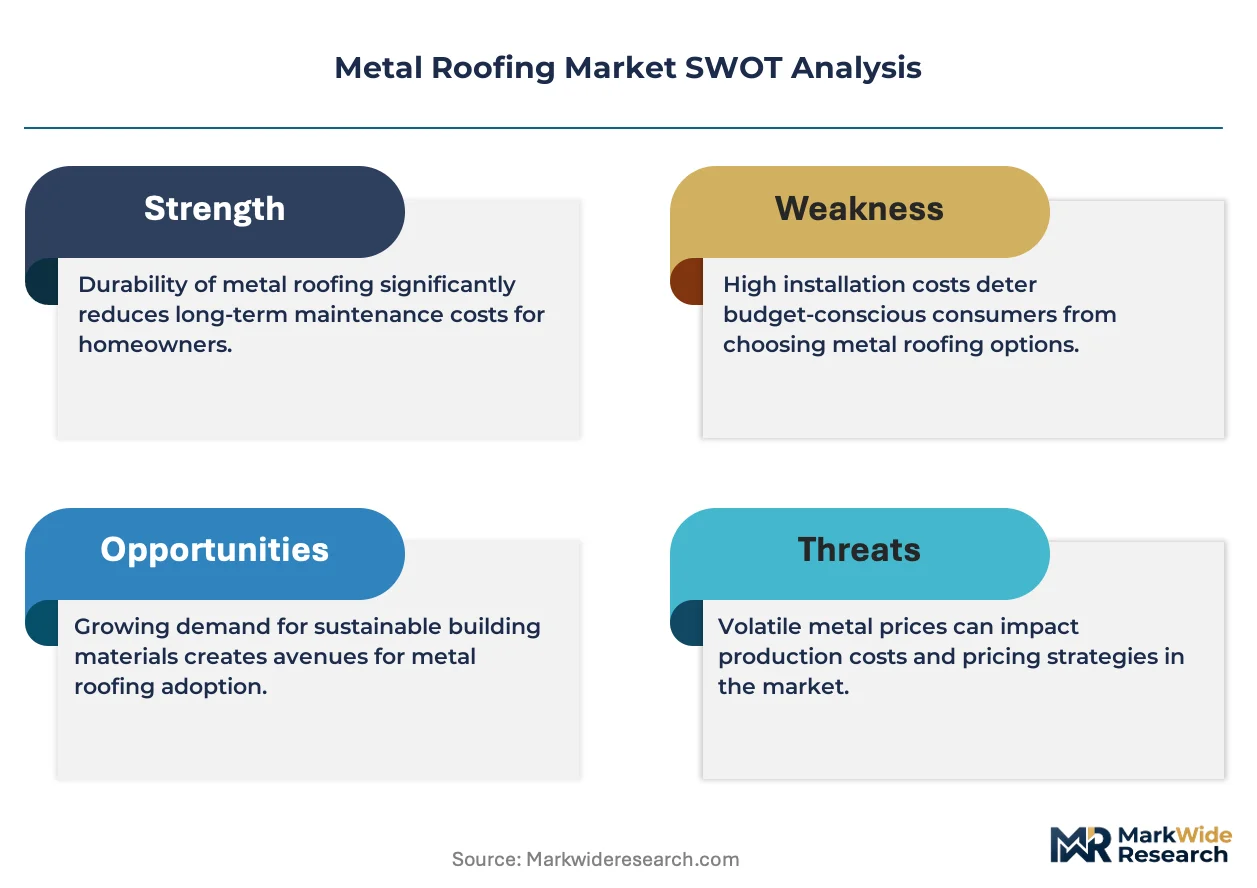
- High Initial Installation Cost:The upfront investment for metal roofing systems remains significantly higher than for traditional materials like asphalt shingles. This cost barrier can deter budget-conscious buyers in the residential segment.
- Raw Material Price Volatility:The market is highly sensitive to price fluctuations in commodity steel and aluminum. Unpredictable input costs create margin pressure for manufacturers and complicate project bidding for contractors.
- Skilled Labor Scarcity:Proper installation of metal roofing, especially standing seam systems, requires specialized training. A shortage of qualified installers can lead to project delays and limit market expansion in certain regions.
Strategic Opportunities
- Expansion in Developing Economies:Rapid urbanization and industrial construction in Southeast Asian countries present significant growth potential. These markets have low penetration rates for high-performance building envelopes.
- Integration with Solar Technology:The convergence of metal roofing with building-integrated photovoltaics creates a new product category. Manufacturers can develop systems where solar collection is seamlessly integrated into standing seam panels.
- Prefabricated and Modular Construction:The rise of off-site construction methods provides an opportunity for pre-cut, factory-finished metal roofing kits. These systems can accelerate installation times and improve quality control on job sites.
Industry Challenges
- Navigating Complex Building Codes:Manufacturers face the challenge of meeting a fragmented landscape of local and international building codes, such as the International Building Code. Testing and certification for wind uplift and fire resistance are costly.
- Distribution Channel Optimization:Reconfiguring supply chains to support the direct-to-contractor model requires significant investment in logistics and inventory management. This shift puts pressure on traditional two-step distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Roofing Market |
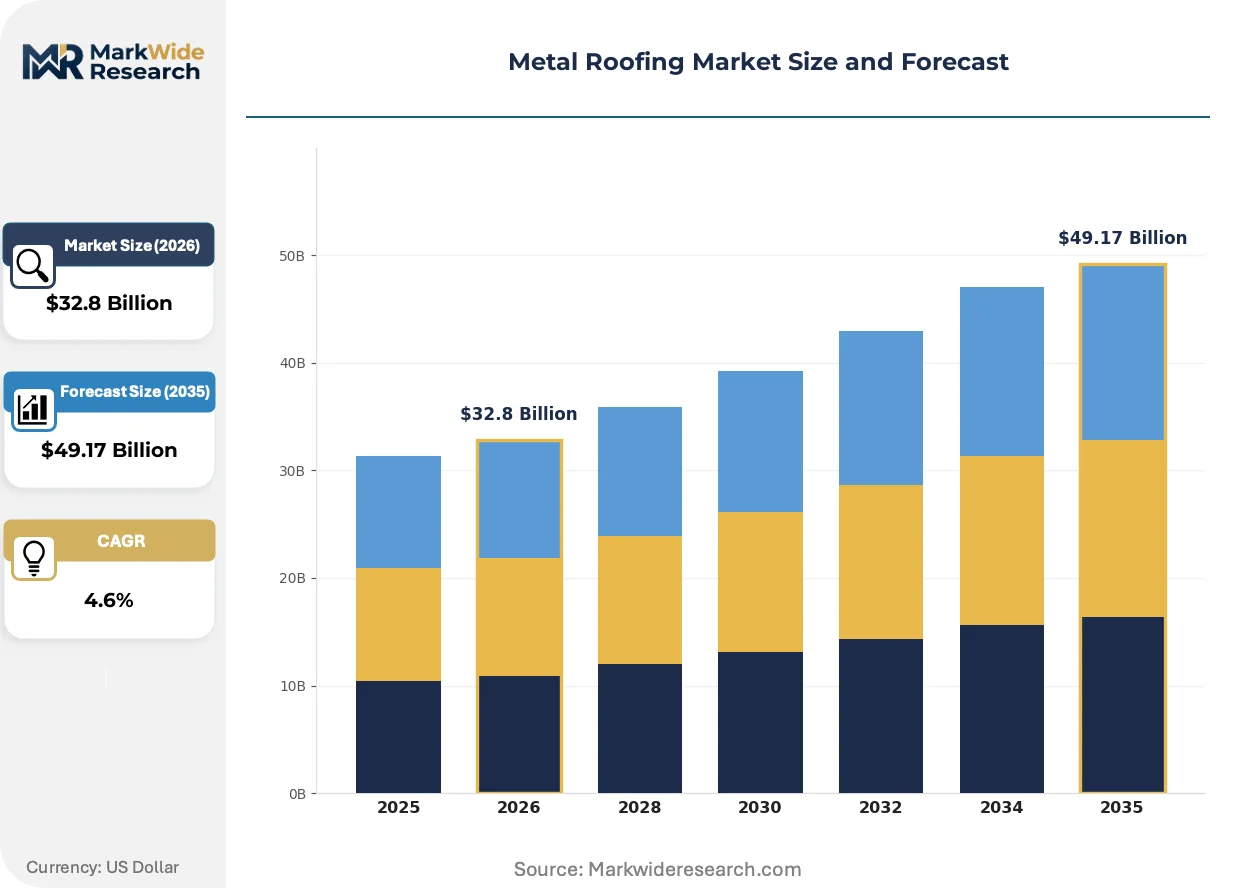
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Aluminum, Copper, Zinc Coating Type: Galvanized, Galvalume, Polymeric, Kynar Paint End User: Residential, Commercial, Industrial, Agricultural Installation Type: New Construction, Renovation, Retrofit, Repair |
| Companies Covered | Elevate (Formerly Firestone Building Products), Kingspan Group plc, Cornerstone Building Brands, Inc., Petersen Aluminum Corporation, Englert Inc., McElroy Metal, ATAS International, Inc., Berridge Manufacturing Co., Nucor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Roofing Market Strategic Shifts & Innovations
Product development is increasingly driven by lifecycle value and sustainability metrics, moving beyond simple weather protection. This evolution is compelling manufacturers to rethink material composition, regulatory compliance, and their direct engagement with end-users.
Insulated metal panels combine a rigid foam insulation core between two metal skins, providing a single-component solution for structure, insulation, and weather barrier. The commercial and industrial construction sectors are rapidly adopting these panels for their thermal performance and speed of installation. This technology is hybridizing the functions of separate building envelope components, compressing construction schedules and reducing on-site labor requirements.
The European Union's Construction Products Regulation and the associated CE marking mandate standardized performance declarations for construction materials, including metal roofing. This framework forces manufacturers to provide transparent data on characteristics like fire reaction and water tightness. As a result, product selection in the EU market is shifting toward systems with verified lifecycle assessments and clear compliance documentation, affecting all suppliers selling into the region.
A clear shift towards digital specification and procurement tools is changing how architects and contractors select metal roofing products. Online platforms and Building Information Modeling object libraries are supplementing or replacing traditional physical samples and paper-based catalogs, disintermediating some sales roles. This trend is most pronounced in North America and Europe, particularly within the commercial architecture and large-scale residential development sectors.
Metal Roofing Market Segmentation
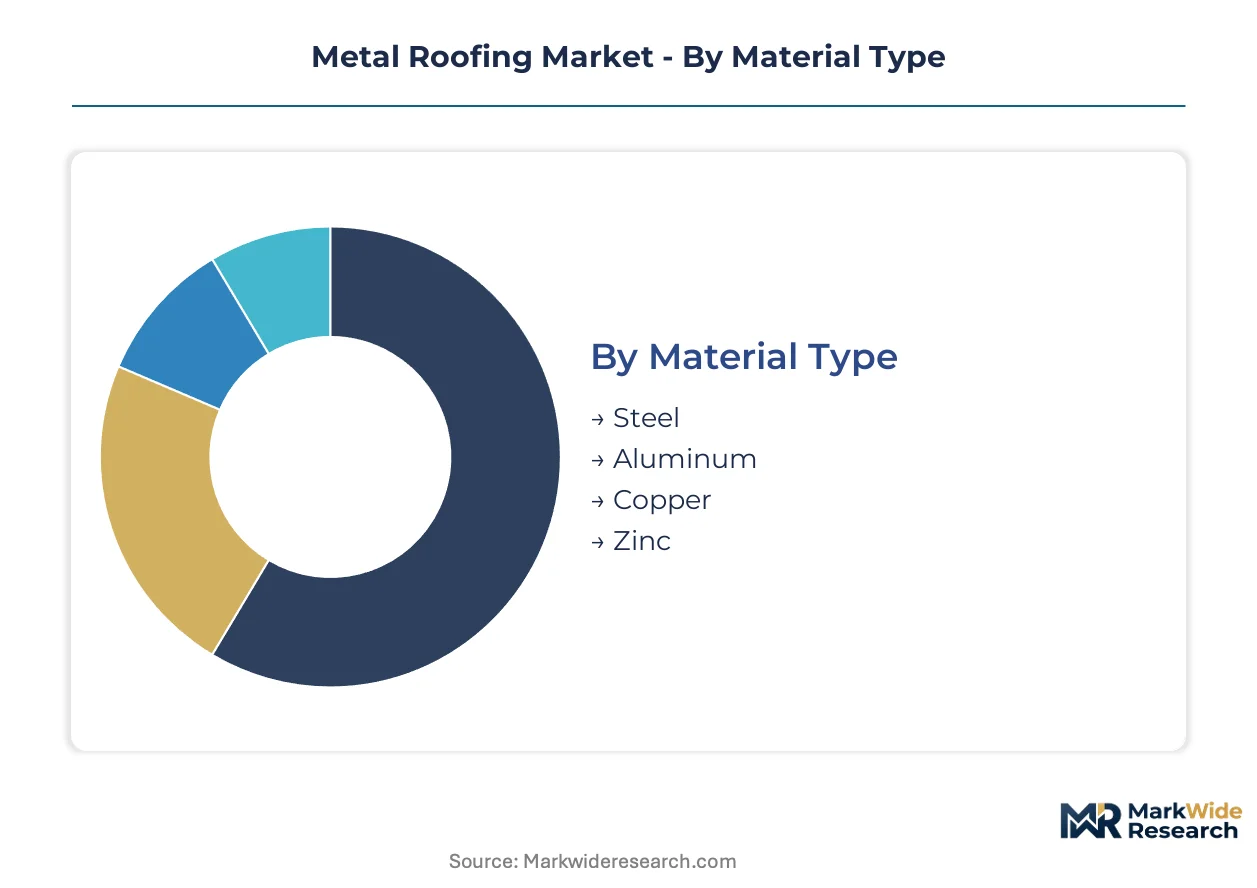
The metal roofing market's segmentation reveals the diverse material preferences, application demands, and installation dynamics influencing product development and market penetration. Understanding these distinct segments allows manufacturers to tailor offerings and distribution strategies effectively across different end-user groups.
Material Type:
The maturity spectrum of metal roofing materials ranges from established staples to niche, high-performance options.
- Steel:This material dominates the market due to its high strength-to-weight ratio, cost-effectiveness, and wide availability. Demand is concentrating in both residential and commercial sectors across North America, driven by its durability and impact resistance against severe weather events.
- Aluminum:Aluminum offers excellent corrosion resistance, particularly crucial in coastal environments where saltwater exposure is common. Homeowners in the US Gulf Coast and commercial developers in Southeast Asia prioritize aluminum for its lightweight properties and longevity.
- Copper:Copper roofing is a premium material known for its distinctive aesthetic, exceptional longevity, and natural patina development. Its demand is concentrated in high-end residential and architectural heritage projects, particularly in European urban centers.
- Zinc:Zinc provides superior self-healing properties and a long lifespan, making it a sustainable choice for specialized architectural designs. Its application often targets commercial and institutional buildings requiring minimal maintenance and unique visual appeal.
Steel handles the majority of throughput; Aluminum is the fastest mover on share.
Coating Type:
Application-specific demands dictate the choice of coating, influencing both performance and aesthetic lifespan.
- Galvanized:This coating involves hot-dipping steel in zinc, providing a sacrificial layer that protects the steel substrate from corrosion. It is a cost-effective solution widely used in agricultural and light commercial buildings in developing economies.
- Galvalume:A blend of zinc, aluminum, and silicon, Galvalume offers enhanced corrosion resistance and heat reflectivity compared to standard galvanized steel. Its demand is strong in residential roofing across the United States, valued for its extended lifespan and energy efficiency.
- Polymeric:Polymeric coatings, including polyesters and acrylics, provide a range of colors and decent weather resistance at a lower cost point. These are often specified for budget-conscious commercial projects and agricultural structures in temperate climates.
- Kynar Paint:Kynar (PVDF) coatings offer superior color retention, chalk resistance, and UV stability, ensuring long-term aesthetic appeal and performance. These premium coatings are predominantly chosen for high-performance commercial and upscale residential applications in regions with intense sun exposure.
Galvanized coatings hold a significant market presence; Kynar Paint is experiencing the steepest expansion trajectory due to performance requirements.
End User:
Customer type significantly influences material selection, installation requirements, and aesthetic preferences within the market.
- Residential:This segment includes single-family homes and multi-family dwellings, where homeowners prioritize longevity, storm resistance, and energy efficiency. Demand for metal roofing in this segment is particularly robust in storm-prone regions of the United States.
- Commercial:Commercial buildings, such as offices, retail spaces, and healthcare facilities, require durable, low-maintenance roofing systems with specific aesthetic and performance criteria. The adoption of insulated metal panels is prominent in new commercial construction across Europe.
- Industrial:Industrial facilities, including factories, warehouses, and manufacturing plants, demand robust roofing solutions capable of withstanding harsh conditions and providing thermal insulation. Steel roofing is a common choice for large-span industrial buildings in Asia-Pacific.
- Agricultural:Agricultural structures, such as barns, sheds, and livestock shelters, prioritize cost-effectiveness, ease of installation, and basic weather protection. Galvanized steel panels are widely used in rural areas for their durability and affordability.
The Residential segment drives considerable volume; the Commercial segment continues its stable expansion.
Installation Type:
Installation type reflects the market's response to existing infrastructure needs versus new development opportunities.
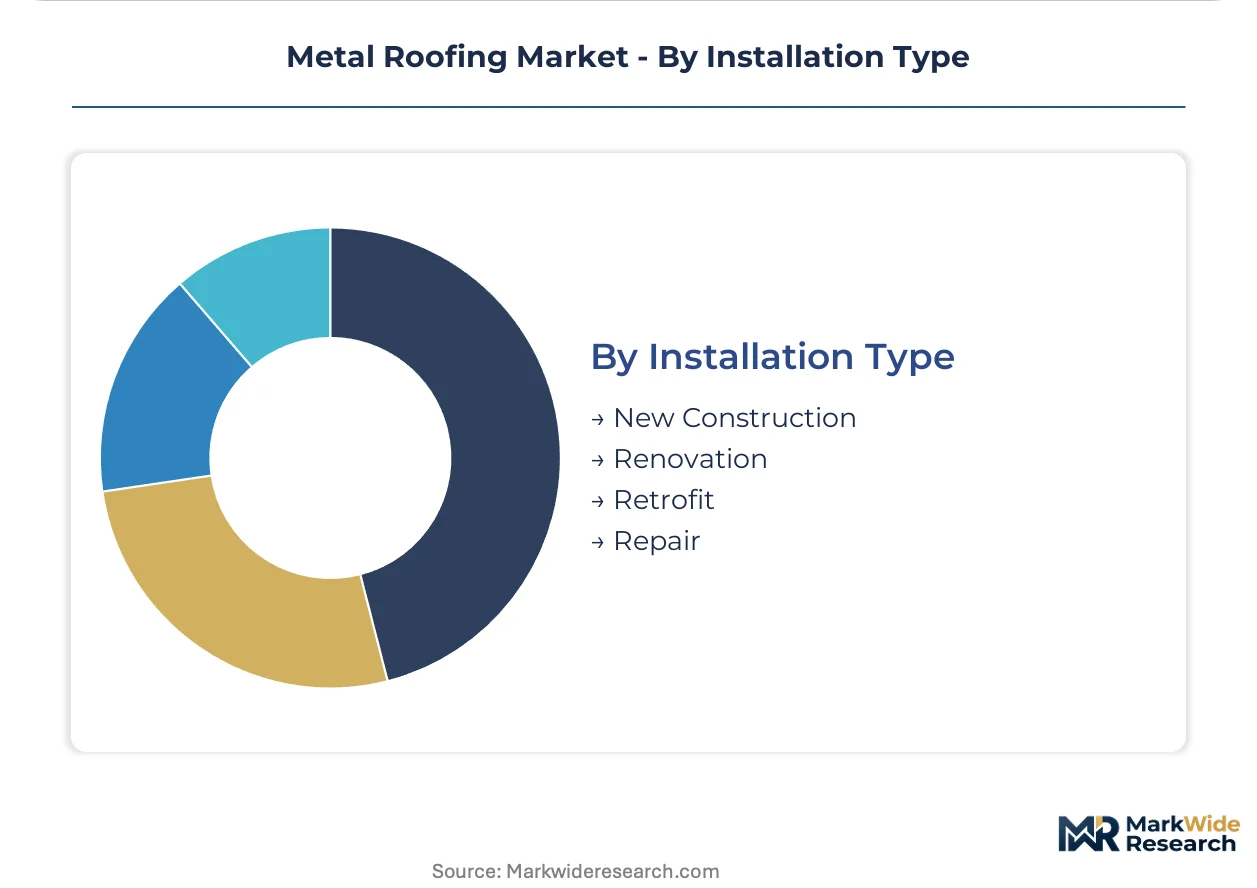
- New Construction:This segment involves the installation of metal roofing on newly built residential, commercial, and industrial structures. It benefits from modern architectural designs integrating advanced metal roofing systems for energy efficiency and aesthetics.
- Renovation:Renovation projects involve replacing existing roofs with new metal roofing systems, often driven by a desire for improved durability, energy performance, or aesthetic upgrades. This segment sees strong activity in older urban centers across Europe and North America.
- Retrofit:Retrofitting typically involves installing a new metal roof system over an existing, often deteriorated, roof without complete removal. This method is common for commercial and industrial buildings seeking to extend roof life and improve performance with minimal disruption.
- Repair:Repair activities address localized damage to existing metal roofing systems, ensuring the continued integrity and performance of the roof. This segment is driven by unexpected weather events and general wear and tear, particularly in regions with extreme climates.
New Construction and Renovation projects collectively shape the market's evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and the US ENERGY STAR program actively drive demand for reflective metal roofs. Building resilience against severe weather also accelerates the replacement of traditional materials with high-performance metal systems. These policies and environmental pressures shape global market dynamics for long-lifecycle metal roofing solutions.
United States
United States homeowners prioritize longevity and storm resistance, especially in severe weather zones. The US ENERGY STAR program actively incentivizes cool roofing technologies, driving demand for reflective metal roofs that lower building energy consumption. Coastal regions like Florida and Texas demonstrate high adoption rates for impact-resistant metal roofing systems, displacing traditional materials.
Germany
German commercial buildings require durable, low-maintenance roofing systems that meet stringent performance criteria. CE marking under the Construction Products Regulation ensures product compliance and harmonized safety standards across the European Union. Urban centers such as Munich and Berlin rapidly adopt insulated metal panels for their superior thermal performance and installation speed in new construction.
India
Indian industrial construction and rapid urbanization present significant growth potential for metal roofing solutions. The country's infrastructure development initiatives, including government-backed projects, support demand for robust and cost-effective roofing. Manufacturing hubs like Gujarat and Maharashtra increasingly specify steel roofing for large-span industrial facilities, prioritizing durability and affordability.
Australia
Australian coastal environments demand excellent corrosion resistance and robust performance from roofing materials. Building codes in regions prone to cyclones, particularly in Queensland, emphasize high wind uplift and impact resistance. Cities like Perth and Brisbane observe rising demand for lightweight aluminum roofing due to frequent saltwater exposure and extreme weather events.
Metal Roofing Market Key Industry Players
On the supply side, the industry is characterized by a mix of large, vertically integrated manufacturers and specialized regional fabricators. This tiered structure includes players focused on upstream material production, panel fabrication, and complete installation systems. Dominant competitive moves involve strategic partnerships for direct-to-contractor distribution and continuous portfolio diversification to meet evolving energy efficiency and aesthetic demands. Capacity expansion in high-growth segments also represents a significant competitive lever for market participants.
Among global and North American manufacturers, Kingspan Group plc exemplifies a strategic focus on high-performance insulated metal panels, primarily serving the commercial building sector with advanced thermal solutions. Cornerstone Building Brands, Inc. represents a scale-driven approach, offering a broad product portfolio and extensive manufacturing footprint across the North American market. Nucor Corporation occupies a unique position through its significant backward integration into upstream steel production, providing a competitive advantage in raw material cost control for its metal roofing product lines.
| Leading Market Players |
|---|
| Elevate (Formerly Firestone Building Products) |
| Kingspan Group plc |
| Cornerstone Building Brands, Inc. |
| Petersen Aluminum Corporation |
| Englert Inc. |
| McElroy Metal |
| ATAS International, Inc. |
| Berridge Manufacturing Co. |
| Nucor Corporation |
| Others |
Cost & Logistics Intelligence
Control over upstream steel production in North America directly influences raw material costs and downstream profit margins for metal roofing manufacturers. This concentration of raw material supply dictates pricing power and competitive dynamics across the value chain.
Pricing Analysis
Volume-discount tiering structures characterize metal roofing pricing, with significant differentiation across material types and coating specifications. Material composition, such as copper versus steel, alongside advanced Kynar paint coatings, drives premium pricing. Cost compression in the galvanized steel segment is intensifying due to commodity price volatility. Residential homeowners, particularly budget-conscious buyers, exhibit high price sensitivity to initial installation costs.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are increasingly critical for managing cash flow within the metal roofing supply chain. Raw material supply concentrates heavily in countries like the United States and China for steel and aluminum. The market depends on key inputs such as steel coils, aluminum sheets, and specialized PVDF resins. Raw material price volatility represents a significant structural risk. Distribution runs through a hybrid model combining direct-to-contractor channels with traditional two-step building material suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metal roofing market presents a defensive moat opportunity, underpinned by high switching costs associated with long-lifecycle building materials and stringent regulatory compliance.
For Market Incumbents: Insulate core market share by strengthening direct-to-contractor distribution networks, ensuring superior service delivery and project support. Invest in advanced coating R&D to counter the threat of emerging composite materials. Leverage existing control over upstream steel production to stabilize input costs against commodity price fluctuations.
For New Entrants and Emerging Players: Establish a beachhead in underserved residential renovation markets, particularly those prioritizing storm resistance and energy efficiency. Target niche architectural designs utilizing zinc or copper for unique visual appeal. Partner with modular construction firms to offer prefabricated roofing kits, accelerating market penetration.
For Investors and Strategic Acquirers: Capital is best deployed toward manufacturers demonstrating strong intellectual property in advanced coatings or integrated solar roofing systems. The market's long-term viability is sustained by increasing demand for resilience and energy efficiency over the next decade. Watch for accelerated adoption of building-integrated photovoltaics as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Direct-to-Contractor Channels | Streamlines supply, enhances customer relationships, and captures more value downstream. |
| Invest in Advanced PVDF Coating R&D | Extends product lifespan, improves aesthetic retention, and meets sustainability mandates. |
| Develop Prefabricated Metal Roofing Kits | Accelerates installation times, reduces on-site labor, and improves quality control. |
| Pursue Building-Integrated Photovoltaic Solutions | Creates new revenue streams and aligns with energy efficiency and sustainability goals. |
| Target Urban Renovation in Europe | Addresses aging infrastructure and demand for high-performance, long-lifecycle materials. |
Research Approach
A spread of perspectives from metal roofing manufacturers, specialized contractors, architects, and building code officials converged on the working assumptions for this analysis. This involved combining primary interviews with industry stakeholders and secondary validation through industry association reports and government energy efficiency programs. Bottom-up data collection was triangulated with top-down market sizing.
Demand-supply balance analysis underpinned the forecast framework across the analysis window, integrating growth catalysts with market restraints. Segmentation dimensions modeled included material type, coating type, end-user, installation type, and regional regulatory compliance. Compound annual growth rates were derived from historical trends, projected technology adoption, and regulatory impact, incorporating inputs like steel commodity prices and residential construction starts.
Stress conditions across raw material price volatility and building code revisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements and market dynamics. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Roofing Underlay Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
Building Insulation Materials Market
Building & Construction Materials
Europe Construction Repair and Rehabilitation Chemicals Market
Building & Construction Materials
US Terracotta Cladding Market
Building & Construction Materials
Steel Sandwich Panels Market
Building & Construction Materials
US Parking Deck Coatings Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
TMT Steel Bar Market
Building & Construction Materials
Global Convertible Roof System Market
Building & Construction Materials
Mosaic Tiles Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Commercial Glazing Market
Building & Construction Materials
Residential Elevator Market