
 Ground Engaging Tools (GET) Market | 2026-2036
Ground Engaging Tools (GET) Market Size, Share, and Industry Trends Forecast 2026-2036
Ground Engaging Tools (GET) Market Foresight
Australia's Pilbara mining corridor is fragmenting as new GET fabrication capacity comes online near Port Hedland and Karratha. Caterpillar Inc. leverages its integrated foundry-to-dealer network to secure long-term supply contracts with iron ore majors. Bradken anchors regional production through its Perth-based manufacturing footprint, while ESCO Corporation differentiates via proprietary metallurgy for high-abrasion bucket teeth.
Ground engaging tools are wear-resistant steel, alloy, carbide, or composite attachments—bucket teeth, blades, rippers, and cutting edges—mounted on excavators, loaders, and dozers to penetrate, cut, and move earth and rock. These components typically incorporate through-hardened boron steel or tungsten carbide overlays to withstand impact stresses exceeding 200,000 psi in mining duty cycles. Carbide-tipped tooth systems command premium positioning due to extended service intervals in basalt and iron ore applications. Composite-reinforced blades are gaining traction in agriculture and landscaping end uses where weight reduction and fuel efficiency offset higher unit costs.
EPA Tier 4 Final and EU Stage V emissions frameworks compel OEMs to design lighter GET assemblies that reduce engine load and fuel consumption. ISO 10265 and SAE J1179 standards govern attachment interchangeability and safety pinning, creating compliance barriers for non-certified suppliers. Stakeholders must monitor how China's GB standards for construction machinery and Australia's Mine Safety and Health regulations evolve around GET inspection intervals and failure reporting.
Market Dynamics
The GET sector is compressing replacement cycles as mining operators in Australia and Chile prioritize uptime over capital preservation, while emissions mandates force OEMs to engineer lighter, more durable assemblies that reduce engine load and fuel burn.
Growth Catalysts
- EPA Tier 4 Final compliance:US-based construction and mining equipment manufacturers must source lighter GET assemblies to meet engine load reduction targets, accelerating demand for boron steel and composite-reinforced designs.
- Iron ore extraction intensity:Australia's Pilbara region and Brazil's Carajás basin are driving accelerated tooth and ripper replacement as operators push equipment through harder rock formations.
- Carbide overlay metallurgy:Tungsten carbide-tipped bucket teeth now extend service intervals in basalt applications by multiples over through-hardened steel, justifying premium positioning in high-abrasion mining duty.
Market Restraints
- Scrap steel price volatility:Boron alloy feedstock costs fluctuate with global ferrous scrap markets, compressing foundry margins and forcing pass-through pricing to end-users.
- Foundry concentration in China:Over half of global GET casting capacity sits in Shandong and Hebei provinces, creating single-source vulnerability for non-integrated OEMs.
- Interchangeability compliance:ISO 10265 and SAE J1179 pinning standards erect technical barriers for uncertified suppliers attempting aftermarket entry.
Strategic Opportunities
- Western China infrastructure buildout:State-backed strip-mining and highway construction in Xinjiang and Gansu provinces require continuous GET replenishment, creating localized demand nodes distant from coastal supply chains.
- EU Stage V retrofit market:European contractors face mandatory engine upgrades that pair with lighter blade and ripper assemblies to achieve combined emissions and fuel efficiency targets.
- Telematics-integrated wear monitoring:Sensor-enabled tooth systems that transmit erosion data to fleet management platforms are collapsing traditional inspection intervals and enabling predictive replacement scheduling.
Industry Challenges
- Metallurgical talent scarcity:Foundries struggle to recruit engineers proficient in computational thermodynamics and solidification modeling for complex alloy GET castings.
- Certification timeline compression:SAE J1179 and ISO 10265 testing protocols require 12-18 months for new attachment designs, lagging behind product development cycles.
- Legacy fleet compatibility:New lightweight GET assemblies often require pin and adapter modifications to interface with decade-old excavator and loader mounting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ground Engaging Tools (GET) Market |
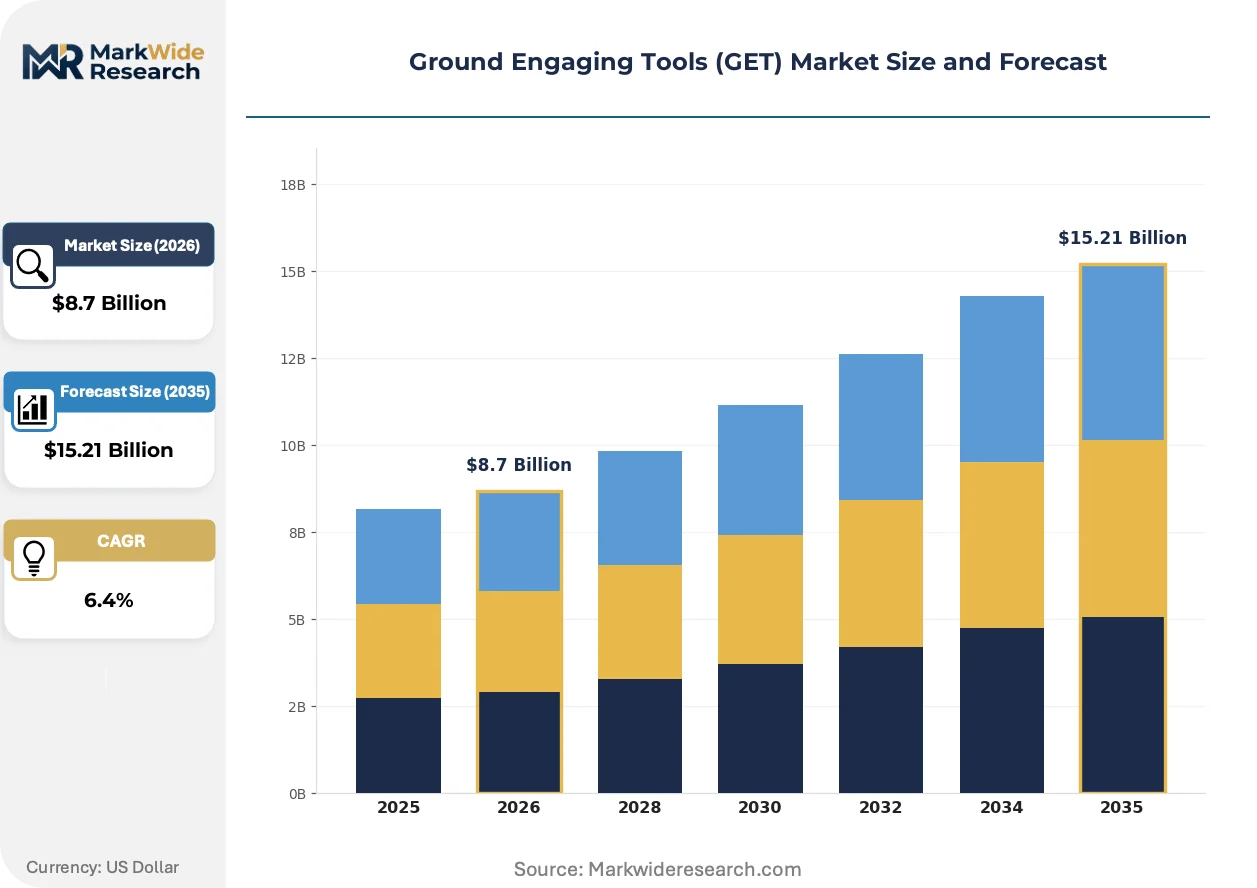
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bucket, Blade, Tooth, Ripper End User: Construction, Mining, Agriculture, Landscaping Material: Steel, Alloy, Carbide, Composite Application: Dirt Excavation, Material Handling, Tilling, Grading |
| Companies Covered | Liebherr-International AG, Bradken, Caterpillar Inc., AB Volvo, ESCO Corporation, Komatsu Ltd., Hitachi Construction Machinery Co., Ltd., John Deere, Sandvik AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ground Engaging Tools (GET) Market Shifts & Advancements
Active innovation in GET design centers on material substitution, regulatory-driven weight reduction, and predictive service models that transform component economics from reactive replacement to planned maintenance.
Carbide-tipped tooth systems with tungsten carbide overlays are collapsing the traditional trade-off between wear resistance and impact toughness in hard-rock mining applications. Australian iron ore operators now specify these assemblies for basalt and hematite extraction where conventional steel teeth fail within weeks. The technology is collapsing downtime costs and extending planned maintenance windows from quarterly to semi-annual intervals.
EU Stage V emissions frameworks mandate measurable reductions in engine load and fuel consumption across construction and mining equipment categories. OEMs respond by specifying aluminum-boron composite blades and hollow-section ripper shanks that cut attachment mass without sacrificing penetration geometry. German and Nordic contractors face the strictest enforcement timelines, driving accelerated specification of certified lightweight GET in new equipment procurement.
Equipment lessors and fleet operators now unbundle GET replacement from full-service maintenance contracts, opting for direct sourcing from foundries with certified interchangeability. This pattern concentrates procurement authority with technical buyers who prioritize metallurgical specifications over brand loyalty. The shift is most visible in Australia's mining contractor segment, where third-party maintenance providers negotiate volume supply agreements independent of OEM dealer networks.
Ground Engaging Tools (GET) Market Segmentation
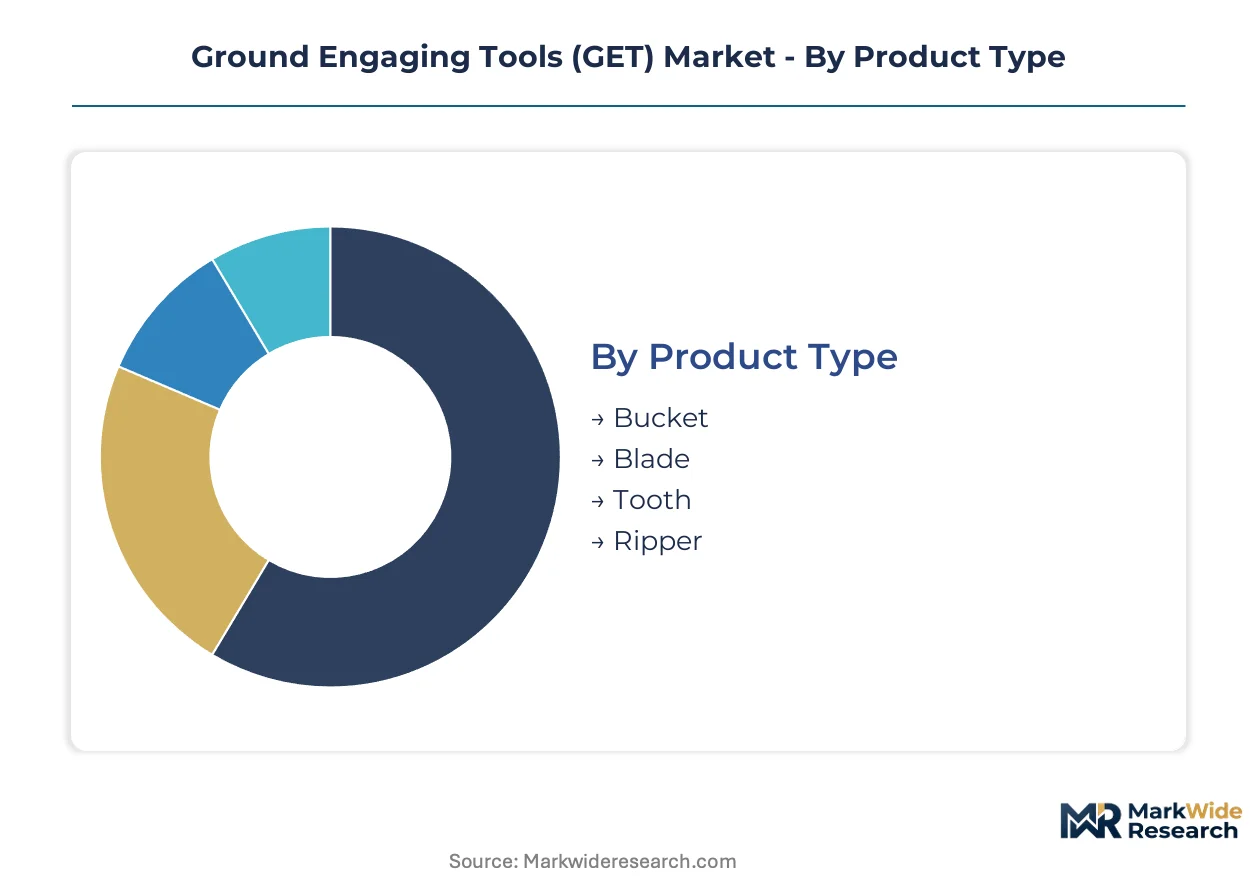
GET segmentation reveals how material science, duty cycle intensity, and regulatory load interact to determine procurement patterns. Technical buyers prioritize wear resistance metrics and interchangeability certification over brand alignment, fragmenting traditional supply relationships.
Product Type:
Cost tier differentiation separates consumable wear parts from structural attachments with extended service intervals.
- Bucket:Fabricated from through-hardened boron steel with reinforced corner gussets, these assemblies withstand impact stresses exceeding 200,000 psi in Australian iron ore extraction. Pilbara operators specify quick-attach coupler compatibility to minimize changeover downtime during 24-hour production cycles.
- Tooth:Carbide-tipped variants with tungsten carbide overlays now dominate basalt and hematite applications where conventional steel fails within weeks. The technology collapses replacement intervals from quarterly to semi-annual, justifying premium positioning in high-abrasion mining duty.
- Blade:Cutting edges range from standard carbon steel for general earthmoving to composite-reinforced designs specified under EU Stage V emissions frameworks.
- Ripper:Penetration shanks integrate hollow-section geometries that reduce mass without sacrificing rock-breaking geometry, increasingly specified for fuel efficiency compliance.
Bucket holds installed capacity. Tooth is rotating up the share rankings.
End User:
Application intensity determines metallurgical specification and replacement cadence across verticals.
- Mining:Iron ore extraction in Australia's Pilbara and Brazil's Carajás basin drives accelerated tooth and ripper replacement as operators push equipment through harder rock formations. EPA Tier 4 Final compliance mandates lighter bucket assemblies to reduce engine load.
- Construction:Highway and infrastructure projects in China's western provinces require continuous GET replenishment, creating localized demand nodes distant from coastal supply chains. State-backed strip-mining compounds procurement volume.
- Agriculture:Composite-reinforced blades gain traction where weight reduction and fuel efficiency offset higher unit costs in large-scale tillage operations.
- Landscaping:Light-duty carbon steel edges dominate residential and commercial grading applications with lower abrasion exposure.
Mining commands replacement frequency. Construction is climbing the fastest as infrastructure buildouts accelerate.
Material:
Performance tier stratification separates commodity feedstock from engineered metallurgy with proprietary solidification protocols.
- Carbide:Tungsten carbide overlays extend service intervals by multiples over through-hardened steel in basalt applications. Australian operators now specify these assemblies as standard for hematite extraction, collapsing downtime costs and extending planned maintenance windows.
- Composite:Aluminum-boron hybrid blades and hollow-section ripper shanks cut attachment mass without sacrificing penetration geometry. German contractors face the strictest EU Stage V enforcement timelines, driving accelerated specification.
- Steel:Standard carbon and boron grades retain dominance in general earthmoving and agriculture where duty cycles permit shorter service intervals.
- Alloy:Through-hardened formulations balance wear resistance with impact toughness in mixed-material excavation.
Steel maintains volume foundation. Carbide is gaining share fastest on mining specification shifts.
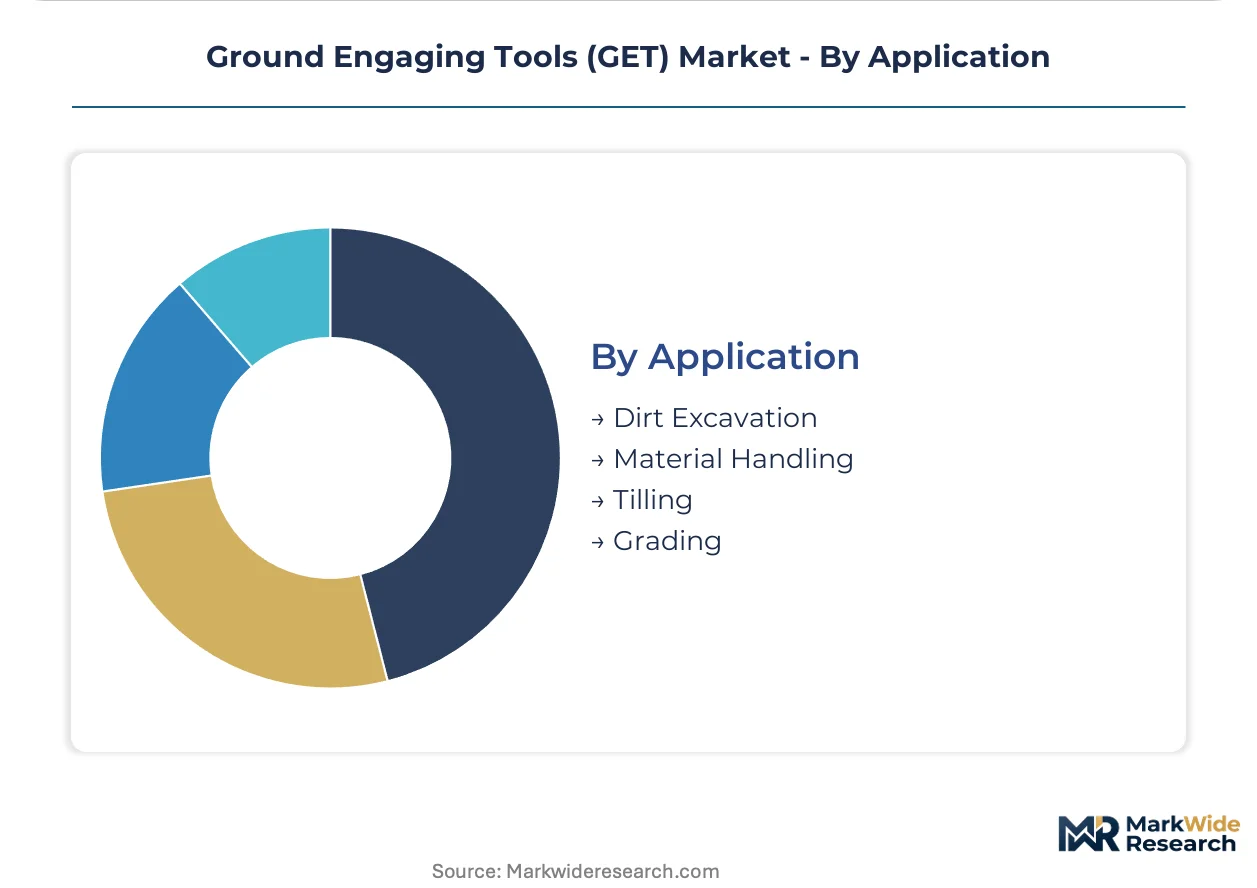
Application:
Operational function dictates geometry optimization and mounting interface requirements.
- Material Handling:High-cycle loading in strip-mining and quarry operations demands reinforced adapter systems with ISO 10265 pinning compliance. Bucket configurations prioritize capacity and discharge efficiency over penetration.
- Dirt Excavation:General-purpose tooth profiles with moderate abrasion resistance serve construction and utility trenching across varied soil conditions.
- Grading:Blade edge geometry varies from flat-carbon designs for finish work to curved-carbide configurations for aggressive material redistribution.
- Tilling:Agricultural ripper and blade assemblies emphasize soil fracture efficiency with replaceable wear points for seasonal maintenance cycles.
Material Handling anchors mining procurement. Dirt Excavation is rotating up the share rankings on infrastructure intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 4 Final and EU Stage V emissions standards are reshaping procurement patterns across mining and construction corridors. Regulatory load reduction mandates concentrate GET specification authority with technical buyers who prioritize certified interchangeability and metallurgical performance over traditional supply relationships.
Australia
Pilbara iron ore operators accelerate tooth and ripper replacement cycles as extraction intensity pushes equipment through basalt and hematite formations. The country's Mine Safety and Health regulations govern GET inspection intervals and failure reporting protocols. Perth-based manufacturing clusters near Karratha and Port Hedland fragment regional supply chains as new fabrication capacity comes online to serve iron ore majors.
China
State-backed infrastructure and strip-mining projects in Xinjiang and Gansu provinces require continuous GET replenishment, creating localized demand nodes distant from coastal foundries. GB standards for construction machinery govern attachment interchangeability and safety pinning requirements. Shandong and Hebei provinces concentrate over half of global GET casting capacity, creating single-source vulnerability for non-integrated equipment manufacturers.
United States
Construction and mining equipment manufacturers source lighter GET assemblies to meet EPA Tier 4 Final engine load reduction targets, accelerating demand for boron steel and composite-reinforced designs. SAE J1179 pinning standards erect technical barriers for uncertified aftermarket suppliers. Domestic foundries face margin compression from ferrous scrap price volatility, forcing pass-through pricing to end-users in Appalachian coal and Southwest copper extraction zones.
Germany
Contractors face mandatory EU Stage V engine upgrades that pair with lighter blade and ripper assemblies to achieve combined emissions and fuel efficiency targets. German and Nordic enforcement timelines drive accelerated specification of certified lightweight GET in new equipment procurement. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate precision foundry capacity for hollow-section ripper shanks and aluminum-boron composite blades.
Chile
Copper extraction intensity in the Atacama Desert drives accelerated bucket tooth replacement as operators prioritize uptime over capital preservation. National mining regulators enforce equipment safety standards that align with ISO 10265 attachment interchangeability protocols. Antofagasta and Calama sub-regions concentrate mining contractor activity, fragmenting traditional OEM dealer networks as third-party maintenance providers negotiate direct foundry supply agreements.
Ground Engaging Tools (GET) Market Competitive Landscape
Capability concentration sits with metallurgical specialists; scale advantage sits with integrated equipment manufacturers. The vendor base stratifies across three tiers: foundry-integrated OEMs controlling captive supply chains, independent specialists commanding premium positioning through proprietary alloy formulations, and regional fabricators competing on interchangeability certification and delivery velocity. Dominant competitive moves include backward integration into boron alloy feedstock sourcing and telematics-enabled wear monitoring partnerships that collapse traditional inspection intervals.
Within the integrated OEM tier, Caterpillar Inc. and Komatsu Ltd. occupy positions defined by foundry-to-dealer network control. Among independent specialists, ESCO Corporation exemplifies premium-tier positioning through proprietary metallurgy, while Bradken anchors regional production capacity through geographically concentrated manufacturing footprints. Liebherr-International AG and AB Volvo represent European equipment manufacturers with captive GET specification authority tied to engine emissions compliance programs.
| Leading Market Players |
|---|
| Liebherr-International AG |
| Bradken |
| Caterpillar Inc. |
| AB Volvo |
| ESCO Corporation |
| Komatsu Ltd. |
| Hitachi Construction Machinery Co., Ltd. |
| John Deere |
| Sandvik AB |
| Others |
Supply & Pricing Matrix
The Port Hedland-to-Pilbara freight corridor channels boron steel and tungsten carbide feedstock from Perth foundries to Australian iron ore operators, where transport cost layering compounds with foundry concentration in China's Shandong province to create geographic price spreads between coastal and inland procurement nodes.
Pricing Analysis
Price spreads between Australian mining contractors and European construction fleets exceed thirty percent on equivalent carbide-tipped tooth specifications. Three-tier pricing structure across premium, standard, and economy levels separates SAE J1179-certified assemblies from uncertified aftermarket alternatives, with ISO 10265 pinning compliance commanding additional margin. Cost compression in standard carbon steel grades is intensifying because scrap steel volatility forces foundry pass-through pricing. Mining contractors demonstrate lowest price sensitivity due to uptime premiums, while agricultural landscapers resist composite blade premiums despite fuel efficiency gains.
Supply Chain Analysis
Boron alloy feedstock draws from ferrous scrap markets in the United States, Australia, and Brazil, with tungsten carbide powder sourcing concentrated in Chinese and Russian mining operations. Hollow-section ripper shanks and aluminum-boron composite blades rest on precision extrusion capacity concentrated in Germany and Japan. Single-source vulnerability permeates the sector as over half of global GET casting capacity sits in Shandong and Hebei provinces. Distribution runs through OEM captive networks for integrated manufacturers and independent foundry-direct channels for third-party maintenance providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority is concentrating with technical buyers at Australian mining contractors and European fleet lessors who unbundle GET from full-service contracts, fragmenting traditional OEM dealer relationships and shifting price-setting power toward metallurgical specification.
For Market Incumbents: Pre-empt foundry-direct supply agreements by locking long-term boron alloy offtake contracts with Australian scrap processors and accelerating SAE J1179 certification timelines for adapter redesigns. Carbide overlay specialists threaten premium positioning through telematics-integrated wear monitoring partnerships that collapse inspection intervals. For New Entrants and Emerging Players: Establish a beachhead in Xinjiang and Gansu provinces where state-backed strip-mining projects require continuous GET replenishment distant from coastal supply chains. European EU Stage V retrofit markets present secondary penetration opportunity through lightweight composite blade specifications. Go-to-market execution should target third-party maintenance providers with certified interchangeability and delivery velocity messaging. For Investors and Strategic Acquirers: Carve-out targets emerge from construction equipment OEMs seeking to divest non-core GET foundry assets amid emissions compliance cost pressures. Long-term viability hinges on metallurgical IP durability and captive alloy sourcing rather than brand equity. Watch for inflection when telematics-enabled tooth systems achieve critical mass in predictive replacement scheduling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Alloy Feedstock | Perth-based scrap processing secures supply certainty for Pilbara mining contracts. |
| Telematics-Integrated Wear Monitoring Partnership | Sensor-enabled tooth systems transmit erosion data to collapse inspection intervals. |
| SAE J1179 Certification Acceleration | Compressed testing protocols enable faster aftermarket entry against incumbent networks. |
| Lightweight Composite Blade Manufacturing Scale-Up | Aluminum-boron hybrid production serves EU Stage V retrofit demand in German construction. |
| Direct Foundry Supply Agreement with Mining Contractors | Bypasses OEM dealer networks to capture procurement authority shift in Australia's Pilbara. |
Research Methodology
Desk research of foundry capacity databases, customs trade records, and SAE/ISO certification registries preceded structured interviews with maintenance directors at Australian iron ore operators, procurement leads at European construction equipment fleets, foundry operations managers in Shandong province, and aftermarket service heads at third-party mining contractors. Secondary validation drew from EPA compliance filings, EU Stage V enforcement timelines, and Australia's Mine Safety and Health inspection protocols. Bottom-up unit demand modeling triangulated against top-down equipment fleet analysis.
Assumptions held fixed include current emissions regulatory enforcement trajectories and existing SAE J1179 pinning standards, while variables tested included scrap steel price volatility bands and telematics adoption curves across mining contractor segments. Segmentation dimensions spanned product type, material metallurgy, end-use intensity, and regional regulatory cluster. CAGRs derived from regression analysis against equipment utilization rates and replacement cycle compression factors, with boron alloy cost pass-through elasticity and carbide overlay penetration rates serving as key industry-specific forecast inputs.
Sensitivities concentrate around Chinese foundry capacity utilization shifts and EPA Tier 4 Final enforcement acceleration. Forecasts reflect documented assumptions regarding emissions compliance timelines and alloy substitution economics. Cross-checking against equipment OEM parts revenue disclosures and foundry utilization surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Latin America Construction Equipment Market
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
Compressed Earth Block Machine Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Log Splitters Rental Market
Construction Equipment
Tray Dryers Market
Construction Equipment
Boom Cranes Market
Construction Equipment
Pile Cage Welding Machine Market
Construction Equipment
Excavation Equipment Market
Construction Equipment
Solar Pile Driving Equipment Market
Construction Equipment
Extrusion Machinery Market
Construction Equipment
Mobile Crushers and Screeners Market
Construction Equipment
Hydraulic Cylinders Market
Construction Equipment
Europe Air Compressor Market
Construction Equipment
Global Crane and Hoist Market
Construction Equipment
Shield Machines Market