
 Linear Slot Diffuser Market | 2026-2036
Linear Slot Diffuser Market Size, Share, and Industry Trends Forecast 2026-2036
Linear Slot Diffuser Market Insights
The capability gap between capital-heavy European engineering groups and smaller regional fabricators is collapsing as automated extrusion and coil-line production become standard. TROX GmbH leverages its German manufacturing base to sustain premium positioning in specification-driven commercial projects. Price Industries anchors North American distribution through extensive representative networks and quick-ship capabilities. Systemair AB competes on volume scale across mid-tier European and Asian construction markets.
A linear slot diffuser is an air distribution device featuring one or more narrow, continuous apertures designed to discharge conditioned air along a linear plane, typically manufactured from extruded aluminum with internal deflector blades that enable horizontal or vertical throw adjustment. Its primary purpose is to provide draft-free, architecturally minimal ventilation in commercial interiors where ceiling aesthetics must integrate with mechanical performance. Aluminum material configurations lead the specification market due to corrosion resistance, recyclability credentials, and compatibility with anodized or painted architectural finishes. Adjustable type variants represent the fastest-growing configuration as building operators prioritize post-occupancy airflow rebalancing without hardware replacement. Ceiling mounted installation dominates new commercial construction, though integrated ceiling-wall systems are gaining share in high-design hospitality and corporate interiors where visible mechanical elements are unacceptable.
ASHRAE Standard 62.1 ventilation requirements and the International Energy Conservation Code directly shape product development by mandating minimum outdoor air delivery rates and pressure-drop thresholds that diffuser geometry must satisfy. EPA ENERGY STAR for commercial buildings and evolving state-level stretch codes in California and New York further tighten the efficiency envelope for air distribution components. Stakeholders must monitor how embodied carbon disclosure rules and building performance standards in major metropolitan jurisdictions will reshape material selection and supplier qualification criteria.
Market Dynamics
Automated extrusion and coil-line production are collapsing the capability gap between capital-heavy engineering groups and regional fabricators, redistributing competitive advantage toward manufacturing scale rather than proprietary design heritage.
Growth Catalysts
- ASHRAE 62.1 ventilation mandates:North American commercial construction faces tightening outdoor air delivery requirements that favor adjustable linear slot diffusers capable of precise airflow rebalancing without hardware replacement.
- Hospitality sector specification:Large-scale mixed-use developments in the United Arab Emirates demand architecturally integrated climate systems where ceiling aesthetics and mechanical performance converge.
- Aluminum coil-line automation:Standardized extrusion processes enable mid-tier fabricators to match premium-grade corrosion resistance and anodized finish quality at compressed production cycles.
Market Restraints
- Primary aluminum price volatility:Raw material cost swings compress margin buffers for manufacturers without captive smelter arrangements or long-term commodity hedging contracts.
- European production concentration:German and Austrian engineering groups control high-specification tooling IP, creating supply bottlenecks for projects requiring custom blade geometries or specialized anodizing.
- Ceiling-integrated system substitution:Active chilled beam technology captures specification share in premium commercial interiors where thermal mass and radiant cooling reduce reliance on forced air distribution.
Strategic Opportunities
- Southeast Asian commercial office buildout:Singapore, Thailand, and Vietnam construction pipelines specify precision air distribution for tropical climate conditioning with minimal visible mechanical infrastructure.
- California Title 24 stretch code alignment:State-level energy efficiency thresholds create specification pull for low-pressure-drop diffuser geometries that reduce fan energy consumption in conditioned air delivery.
- BIM-to-fabrication workflow integration:Direct digital transfer from building information models to automated cutting and forming equipment collapses specification-to-delivery timelines for custom linear runs.
Industry Challenges
- Computational fluid dynamics expertise scarcity:Accurate throw pattern modeling for complex ceiling geometries requires specialized simulation talent that regional fabricators struggle to recruit and retain.
- Multi-jurisdiction certification lag:Projects spanning UAE, Saudi Arabia, and Qatar demand concurrent compliance with divergent national fire safety and pressure testing protocols that extend qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linear Slot Diffuser Market |
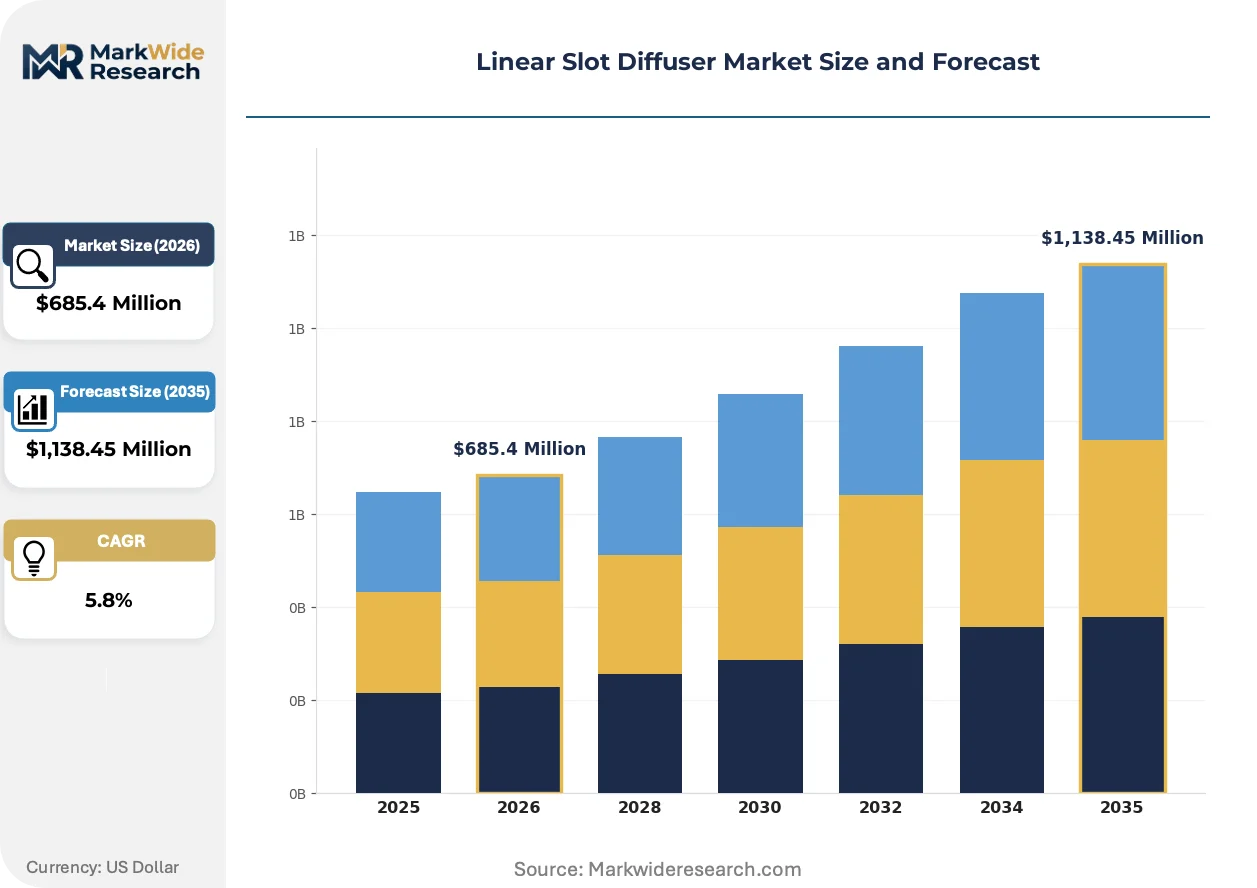
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Manual, Automatic, Adjustable, Fixed Material: Aluminum, Steel, Plastic, Composite Installation Method: Ceiling Mounted, Wall Mounted, Floor Mounted, Integrated Application: Commercial, Residential, Industrial, Retail |
| Companies Covered | Titus HVAC, TROX GmbH, Price Industries, Nailor Industries, Systemair AB, Krueger-HVAC, Lindab AB, Halton Group, Greenheck Fan Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linear Slot Diffuser Market Trends and Innovations
Digital fabrication workflows and performance-based building codes are resequencing how linear slot diffusers are specified, manufactured, and validated across commercial construction markets.
Micro-perforated aluminum facing technology is fragmenting the traditional distinction between architectural linear slots and acoustic ceiling systems. High-end corporate interiors in London and New York now specify integrated air distribution and sound absorption within single ceiling plane elements. This convergence compresses specification autonomy for standalone diffuser manufacturers while enabling systems contractors to capture margin previously allocated to separate acoustic treatment trades.
REACH regulation amendments on persistent organic pollutants are tightening surface treatment chemistry for architectural aluminum components sold across European Union member states. Anodizing shops serving HVAC fabricators face reformulation requirements for sealant chemistries and pretreatment baths. German and Italian manufacturers with in-house finishing lines are accelerating capital deployment toward chrome-free and low-VOC process alternatives ahead of enforcement deadlines.
Design-build procurement consolidation among North American general contractors is compressing distributor influence over final diffuser specification. Large construction management firms now mandate approved manufacturer lists with pre-negotiated pricing and single-source accountability, displacing traditional representative network relationships. This channel restructuring concentrates volume with suppliers capable of direct EDI integration and national quick-ship warehousing, most visible in Texas and California commercial office rollouts.
Linear Slot Diffuser Market Segmentation
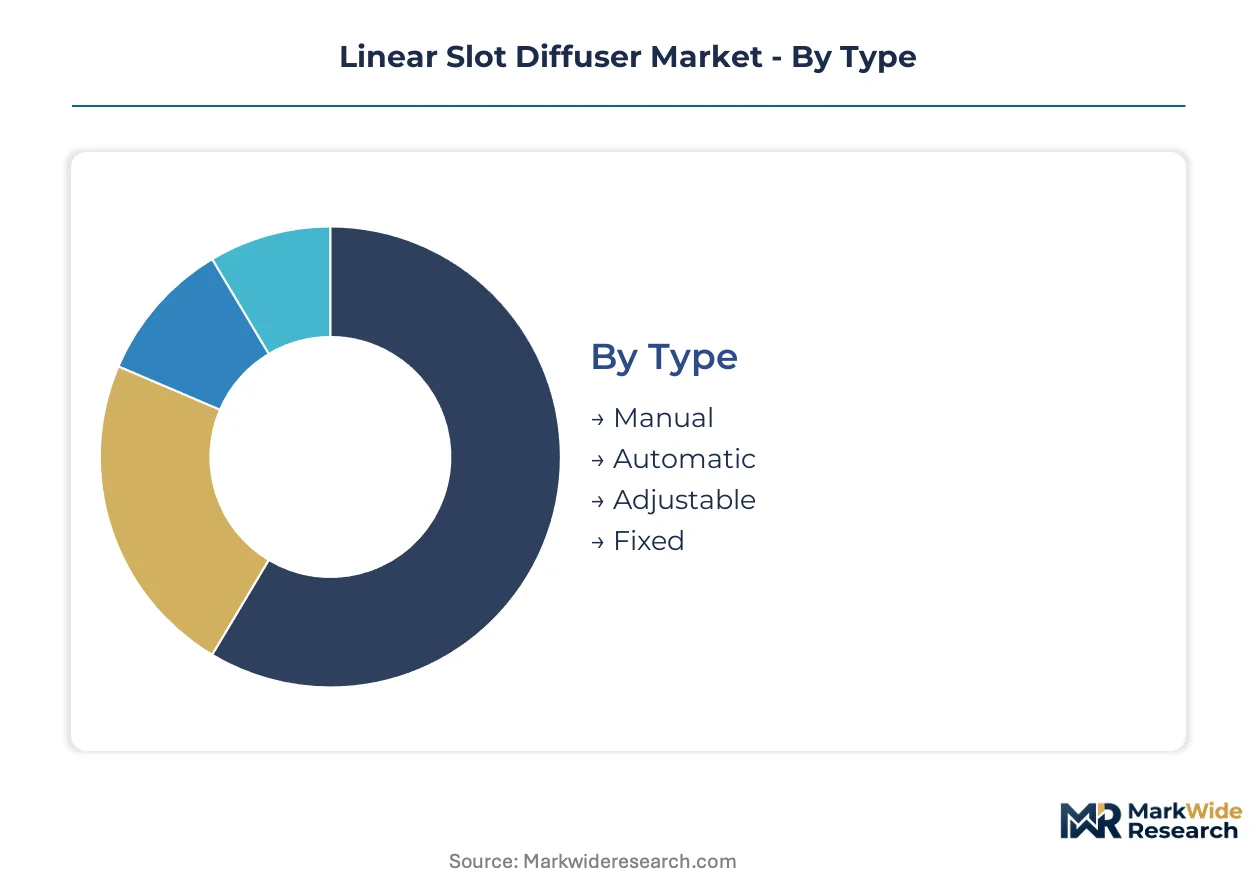
Linear slot diffuser procurement patterns diverge sharply across building types and installation contexts. Specification workflows, material certification requirements, and airflow performance standards create distinct demand clusters that manufacturers must address through targeted product architectures.
Type:
Adjustable and automatic variants dominate export-oriented specification in the United Arab Emirates and Saudi Arabia, while manual types retain strongholds in domestic North American renovation markets.
- Manual:Simple blade mechanisms allow field technicians to set throw patterns during initial commissioning without specialized tools. Demand concentrates in US commercial retrofit projects where budget constraints override post-occupancy flexibility requirements.
- Automatic:Motorized blade arrays respond to zone-level temperature or CO2 sensors, enabling real-time airflow modulation. Large-scale Singapore and Bangkok office developments specify these for precision tropical climate conditioning with minimal energy penalty.
- Adjustable:Tool-free blade repositioning enables facility managers to rebalance zones after tenant churn without hardware replacement. California Title 24 stretch code compliance increasingly mandates this capability for commercial buildings over 50,000 square feet.
- Fixed:Permanent blade geometry delivers lowest first-cost for spec-budget-sensitive hospitality rollouts in Vietnam and Thailand where architectural finish consistency outweighs operational flexibility.
Manual types hold the largest share; momentum sits with adjustable configurations.
Material:
Cost tiers separate specification markets, with premium corrosion-resistant grades commanding architectural-grade premiums while commodity alternatives serve volume construction.
- Aluminum:Extruded 6063-T5 alloy delivers anodized finish compatibility and full recyclability credentials for LEED and BREEAM submissions. UAE and Qatar megaprojects mandate this material for coastal humidity resistance and embodied carbon disclosure compliance.
- Steel:Powder-coated cold-rolled carbon steel serves budget-constrained US retail and warehouse distribution where visible ceiling infrastructure receives minimal architectural scrutiny.
- Plastic:Injection-molded ABS and polycarbonate blends reduce weight for suspended ceiling systems with limited structural capacity. Residential multi-family construction in Florida and Texas specifies these for humidity resistance at compressed price points.
- Composite:Glass-reinforced polymer formulations combine thermal insulation with corrosion immunity for aggressive chemical environments in pharmaceutical cleanrooms and food processing facilities.
Aluminum dominates specification value; composite materials are climbing fastest on specialized industrial demand.
Installation Method:
Volume concentration aligns with new construction cycles, though integrated systems capture disproportionate margin in high-design segments.
- Ceiling Mounted:T-bar and drywall flange variants constitute the standard specification for open-plan commercial offices across Germany, France, and the United Kingdom. German manufacturers TROX and Systemair anchor European supply through standardized module dimensions.
- Wall Mounted:Baseboard and high-wall configurations serve perimeter heating applications in Nordic residential markets and historic building retrofits where ceiling preservation is mandatory.
- Floor Mounted:Displacement ventilation applications in auditoriums and atrium spaces leverage thermal stratification principles. Limited specification volume concentrates in Scandinavian public infrastructure projects.
- Integrated:Custom linear runs fabricated into metal ceiling or millwork systems eliminate visible mechanical elements. London and New York corporate headquarters specify these for reception and executive zones where architectural minimalism commands premium pricing.
Ceiling mounted systems retain volume leadership; integrated installations show the steepest expansion trajectory on high-end commercial demand.
Application:
Customer type determines performance certification requirements and channel access, with commercial specification demanding extensive testing documentation unavailable to smaller fabricators.
- Commercial:Office, healthcare, and institutional buildings require ASHRAE 62.1 compliance documentation, pressure-drop testing, and acoustic performance ratings. US specification flows through Price Industries' representative network and similar channel structures.
- Residential:Single-family and multi-family housing prioritizes cost efficiency over precision airflow control. Big-box retail distribution and HVAC contractor direct purchasing dominate this segment.
- Industrial:Manufacturing and warehouse facilities tolerate higher air velocities and visible mechanical infrastructure. Corrosion-resistant aluminum specifications prevail in food processing and chemical handling environments.
- Retail:Branded store rollouts demand consistent aesthetic execution across multiple locations. Fast-fashion and quick-service restaurant chains specify standardized linear slot modules for rapid prototype replication.
Commercial applications command the largest specification value; retail rollout standardization is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering groups command premium pricing for specification-grade linear slot diffusers, while Southeast Asian fabricators compete on compressed production cycles for volume commercial construction. This pricing-power asymmetry shapes procurement patterns across major construction markets.
United States
Commercial office developments in Texas and California drive specification of adjustable linear slot diffusers for ASHRAE 62.1 compliance. EPA ENERGY STAR standards and California Title 24 stretch codes mandate low-pressure-drop geometries that reduce fan energy consumption. Dallas-Fort Worth and Houston construction corridors concentrate demand for quick-ship distribution capabilities.
Germany
Precision manufacturing heritage sustains premium positioning in architecturally integrated climate systems for commercial interiors. REACH regulation amendments on persistent organic pollutants tighten surface treatment chemistry for anodized aluminum components. Stuttgart and Munich engineering clusters anchor high-specification tooling IP for custom blade geometries.
United Arab Emirates
Large-scale hospitality and mixed-use projects in Dubai and Abu Dhabi require corrosion-resistant aluminum configurations for coastal humidity conditions. MOHAP building safety protocols and pressure testing standards govern fire safety certification timelines. Dubai Design District and Saadiyat Island developments concentrate specification for ceiling-integrated architectural minimalism.
Singapore
Tropical climate conditioning demands precision air distribution with minimal visible mechanical infrastructure in commercial office buildouts. BCA Green Mark certification and energy efficiency codes favor adjustable diffusers enabling post-occupancy zone rebalancing. Marina Bay and Jurong Lake District construction pipelines specify automatic variants for real-time airflow modulation.
China
GB standards for ventilation and air conditioning shape product development for commercial building applications. MIIT industrial policy and dual carbon goals accelerate specification of energy-efficient air distribution components. Yangtze River Delta manufacturing clusters, particularly Shanghai and Suzhou, concentrate automated extrusion capacity for standardized module production.
Linear Slot Diffuser Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the linear slot diffuser market. Premium specification workflows favor European engineering groups with proprietary tooling IP, while volume construction markets reward Asian fabricators with coil-line automation scale. Three strategic archetypes dominate: heritage German manufacturers, North American distribution-anchored suppliers, and automated Asian volume producers. Competitive moves concentrate on BIM-to-fabrication workflow integration and national quick-ship warehousing networks.
Among heritage European engineering groups, TROX GmbH and Systemair AB exemplify the premium-volume split in competitive positioning. TROX GmbH anchors specification-driven commercial projects through its German manufacturing base, while Systemair AB occupies a position across mid-tier European and Asian construction markets. Price Industries represents the North American distribution-anchored archetype, with representative networks sustaining market access. These three companies illustrate how geographic origin and corporate structure shape strategic options without determining specific market outcomes.
| Leading Market Players |
|---|
| Titus HVAC |
| TROX GmbH |
| Price Industries |
| Nailor Industries |
| Systemair AB |
| Krueger-HVAC |
| Lindab AB |
| Halton Group |
| Greenheck Fan Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term aluminum offtake agreements between extrusion houses and primary smelters lock in both raw material access and price visibility for German and Austrian engineering groups serving specification-grade commercial projects. These contractual structures insulate premium manufacturers from LME volatility while compressing margin buffers for regional fabricators without captive supply arrangements.
Pricing Analysis
Configured-to-order pricing for custom blade geometries and specialized anodized finishes commands substantial premiums over standard extruded modules. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and post-occupancy adjustability, with California Title 24 compliance tiers attracting least price-sensitive buyers. Cost compression in commodity aluminum segments is intensifying because coil-line automation enables mid-tier fabricators to match corrosion resistance benchmarks. US commercial retrofit contractors exhibit highest price sensitivity, while UAE hospitality developers prioritize architectural integration over unit economics.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes and port congestion at Rotterdam and Hamburg elevate inbound logistics costs for coil stock and anodizing chemicals. Manufacturing gravity centers on Germany, China, and the United Arab Emirates, with extruded 6063-T5 alloy and anodizing sealant chemistries drawing from captive European finishing lines and Yangtze River Delta smelter networks. Single-source vulnerability concentrates in high-specification tooling IP controlled by Stuttgart engineering clusters. Distribution runs through manufacturer-direct representative networks in North America and systems contractor channels in European commercial construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among North American design-build general contractors consolidating approved manufacturer lists with pre-negotiated pricing, fragmenting traditional distributor influence over final specification.
For Market Incumbents: Fortify specification-driven positioning by deepening captive anodizing capacity ahead of REACH amendment enforcement deadlines. Expand quick-ship warehousing footprints in Texas and California construction corridors to defend against emerging Asian fabricators with compressed production cycles. Channel control through EDI-integrated national distribution networks remains the critical lever against procurement consolidation. For New Entrants and Emerging Players: Anchor in Southeast Asian commercial office buildouts where precision air distribution demand outpaces established European supply capacity. Vietnam and Thailand hospitality rollouts present the most penetrable white space given budget sensitivity and limited architectural scrutiny. Lead with BIM-to-fabrication workflow integration to collapse specification-to-delivery timelines against legacy manufacturer lead times. For Investors and Strategic Acquirers: Capital is best deployed toward automated extrusion specialists with coil-line scale and REACH-compliant finishing infrastructure. Long-term viability over the next decade hinges on regulatory compliance positioning rather than pure manufacturing cost. Watch for California and New York stretch code enforcement acceleration as the primary inflection signal for adjustable diffuser specification pull.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anodizing | REACH-compliant finishing capacity secures specification access across EU commercial projects. |
| BIM-to-Fabrication Workflow Deployment | Direct digital transfer from building models collapses custom linear run delivery timelines. |
| Quick-Ship Warehouse Network Expansion | Texas and California stocking positions address design-build contractor consolidation demands. |
| Adjustable Diffuser Certification Investment | California Title 24 compliance documentation unlocks commercial buildings above 50,000 square feet. |
| Micro-Perforated Acoustic Integration | London and New York corporate headquarters specify converged air distribution and sound absorption. |
Research Methodology
Operator-level perspectives from HVAC contractors, facilities managers, MEP engineers, and commercial general contractor procurement leads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against ASHRAE standard documentation, EPA ENERGY STAR certification databases, and customs trade records for aluminum extrusion imports. Bottom-up triangulation across specification workflows and top-down validation against construction pipeline data ensured cross-verified demand estimates.
Sensitivity analysis tested volume and value outputs across adjustable type adoption rates, primary aluminum price scenarios, and regional construction cycle timing throughout the forecast period. Segmentation dimensions modeled include type configuration, material grade tier, installation method, end-use application, and regional regulatory cluster. CAGRs derived from installed base turnover analysis and new construction penetration assumptions, with specific inputs for ASHRAE 62.1 ventilation mandate adoption curves and REACH amendment compliance cost pass-through rates.
Decision-makers should treat outputs as directional under sustained commercial construction activity and stable aluminum supply conditions; material deviation would warrant model refresh. Specific risk factors include chilled beam technology substitution acceleration, Gulf Cooperation Council fire safety protocol divergence, and European energy cost volatility affecting anodizing operations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Europe Heat Pump Market
HVAC Equipment
India Chillers Market
HVAC Equipment
US HVAC Services Market
HVAC Equipment
Global Smart Vent Market
HVAC Equipment
Global Portable Air Conditioner Market
HVAC Equipment
North America Gas Water Heater Market
HVAC Equipment
Global Submerged Coil Heat Exchanger Market
HVAC Equipment
Air-Cooled Heat Exchangers Market
HVAC Equipment
Air Conditioning Systems Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
Europe Ventilation Equipment Market
HVAC Equipment
Air Volume Controllers Market
HVAC Equipment
High Pressure Heat Exchanger Market
HVAC Equipment
Commercial Water Heater Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market