
 Global Metal-Faced Insulated Panels Market | 2026-2036
Global Metal-Faced Insulated Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal-Faced Insulated Panels Market Foresight
Multi-source procurement among large envelope contractors is broadening as project owners seek supply resilience for complex cold storage and data center builds. Kingspan Group leverages its integrated insulation and facade technology portfolio to sustain specification rates across pharmaceutical manufacturing projects. Nucor Building Systems anchors its position through captive steel supply and in-house roll-forming capacity that controls cost volatility. Metl-Span competes on rapid-turn custom panel fabrication for modular data center deployments.
Metal-faced insulated panels consist of rigid insulating cores laminated between pre-coated steel or aluminum sheets, achieving thermal resistances from R-16 to R-48 depending on core thickness and material. These assemblies function as structural weather envelopes that reduce thermal bridging while supporting dead and live loads in single-span applications. Polyurethane and polyisocyanurate cores dominate margin pools due to superior R-value per inch and compatibility with continuous manufacturing lines. Mineral wool formulations occupy a defensible niche where fire resistance ratings exceed what polymer cores can deliver, particularly in European warehousing specifications driven by ECHA-reviewed flame retardant standards.
Building codes under the EU Green Deal, the U.S. Department of Energy envelope standards, and China's GB 50189 public building energy standard collectively tighten permissible U-values for commercial envelopes. These frameworks push specification toward thicker panels and higher-performance cores while creating compliance barriers for uncertified imports. Stakeholders must monitor divergence between regional fire test protocols and core material approvals, as misalignment between ASTM E84 and EN 13501 classifications threatens to fragment product portfolios and strand capital in single-market formulations.
Market Dynamics
EU Green Deal enforcement and U.S. Department of Energy envelope standards are compressing permissible U-values for commercial building envelopes, forcing specification upgrades toward thicker polyurethane-core panels and certified fire-rated assemblies that meet divergent ASTM E84 and EN 13501 test protocols.
Growth Catalysts
- EU Green Deal building retrofit mandates:Member states must renovate commercial stock to near-zero energy standards, accelerating replacement of legacy envelope systems with high-R-value metal-faced panels in German logistics hubs and Dutch cold storage corridors.
- Pharmaceutical manufacturing expansion:Biologics production facilities in the United States and China require ISO 14644 cleanroom envelopes with precise thermal stability, specifying mineral wool-cored panels for fire resistance alongside polymer cores for thermal performance.
- Polyisocyanurate core chemistry advances:Continuous lamination lines now produce thicker panels without delamination risk, enabling single-span roof applications up to 12 meters in Chinese data center construction.
Market Restraints
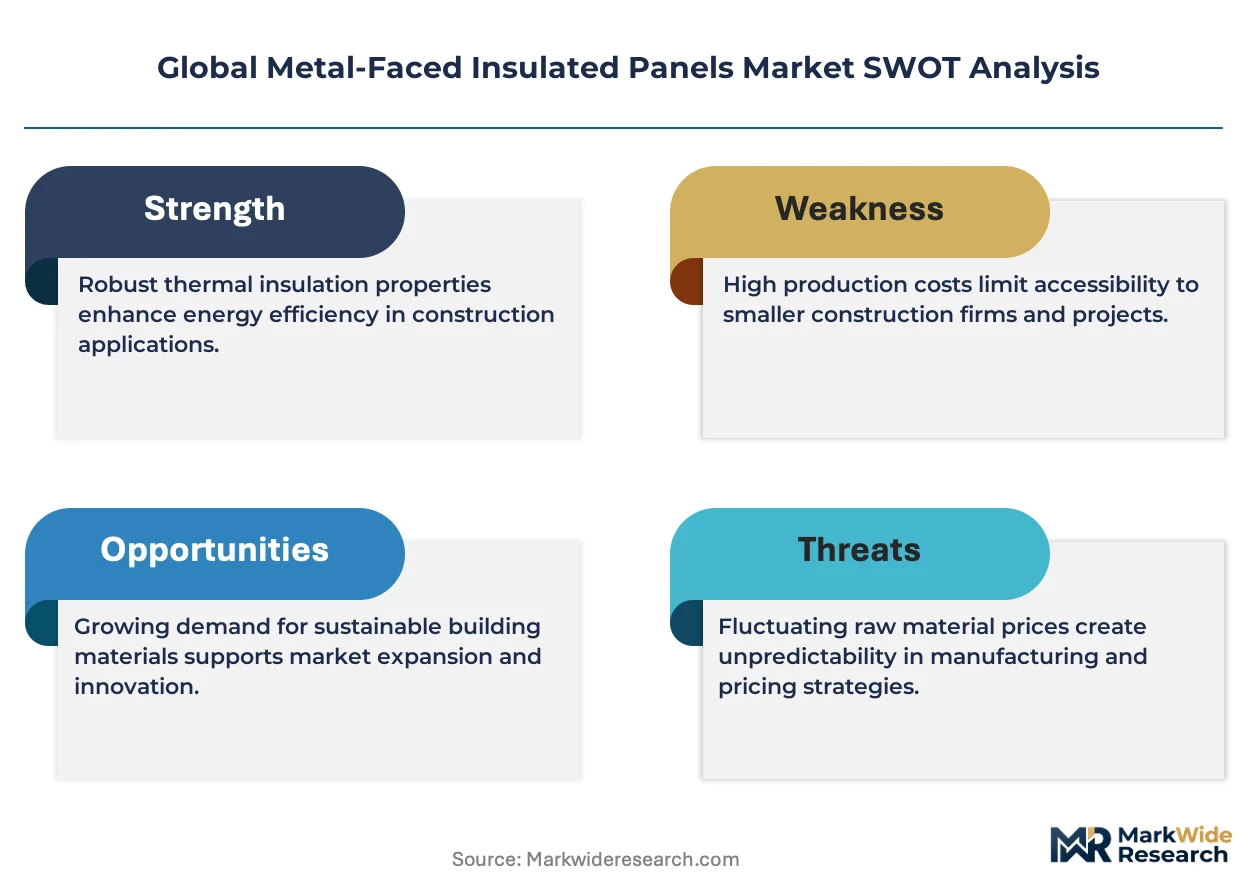
- Steel and aluminum input volatility:Pre-coated metal sheet costs fluctuate with Nucor and ArcelorMittal pricing cycles, compressing margin visibility for panel fabricators on fixed-price construction contracts.
- Core material supply concentration:Polyurethane and polyisocyanurate precursor production clusters in the U.S. Gulf Coast and Rhine-Ruhr corridor, exposing buyers to force majeure risks from BASF and Covestro facility outages.
- Fire test protocol fragmentation:Misalignment between ASTM E84 flame spread indices and EN 13501-1 reaction-to-fire classifications prevents product portfolio standardization, stranding R&D investment in single-market formulations.
Strategic Opportunities
- Indian cold chain infrastructure gaps:The country's national cold storage capacity operates at 25-30% of required volume per FSSAI estimates, creating specification windows for insulated envelope systems in pharmaceutical distribution hubs near Mumbai and Hyderabad.
- Modular data center deployment models:Hyperscale cloud providers in Northern Virginia and Frankfurt are procuring factory-built power modules with integrated thermal envelopes, shortening construction timelines from 18 months to 6 months.
- China GB 50189 public building energy standard tightening:Revised U-value requirements for commercial envelopes above 20,000 square meters are displacing conventional curtain wall systems with metal-faced panel rainscreen assemblies in Shanghai and Shenzhen office towers.
Industry Challenges
- Fire certification timeline compression:European warehousing specifications now require ECHA-reviewed flame retardant documentation and third-party EN 13501-1 testing, extending product qualification cycles by 8-12 months for new core formulations.
- Installation labor specialization gaps:Proper sealing of panel joints to prevent thermal bridging demands certified envelope contractor crews, with qualified teams concentrated in German and U.S. Midwest construction markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal-Faced Insulated Panels Market |
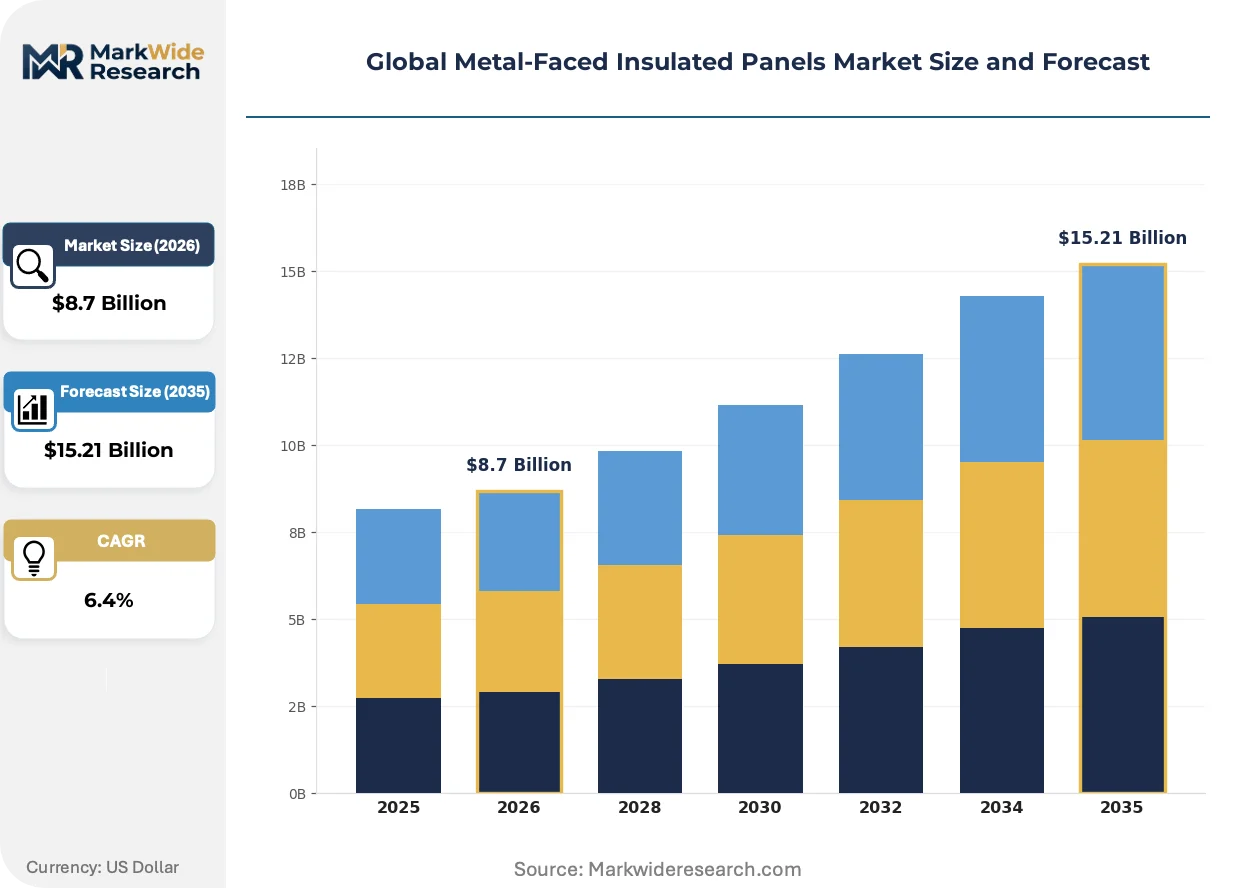
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Polyisocyanurate, Expanded Polystyrene, Mineral Wool, Phenolic Foam End User Industry: Cold Storage Facilities, Data Centers, Food Processing Units, Warehousing, Pharmaceutical Manufacturing Application: Wall Panels, Roofing Panels, Sandwich Panels, Partition Panels, Flooring Panels Installation Type: New Construction, Renovations, Modular Buildings, Prefabricated Structures, Temporary Facilities |
| Companies Covered | Kingspan Group, Nucor Building Systems, Metl-Span, CENTRIA, Cornerstone Building Brands, Owens Corning Insulating Systems, MBCI, ArcelorMittal, Green Span, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal-Faced Insulated Panels Market Shifts & Advancements
Active thermal envelope design is displacing passive specification approaches, with building owners demanding predictive performance modeling and real-time monitoring integration rather than static R-value compliance.
Phase-change material integration into polyurethane core formulations is integrating latent heat storage capacity directly into wall and roof assemblies. Pharmaceutical distribution facilities in Denmark and the Netherlands are specifying these panels to dampen temperature excursions during refrigeration system cycling. This technology is integrating thermal mass functionality into lightweight envelope systems that previously required separate mechanical buffering.
REACH restriction proposals on halogenated flame retardants are forcing core chemistry reformulation across European supply chains. Manufacturers must substitute phosphorus-based and intumescent alternatives while maintaining EN 13501-1 Class B-s1,d0 ratings. Cold storage specifications in Germany and France are driving accelerated qualification of mineral wool and modified polyisocyanurate cores that satisfy both thermal and revised safety criteria.
Direct procurement from panel fabricators is compressing traditional distributor channels for projects above 50,000 square meters. Data center developers in Northern Virginia and pharmaceutical contractors in Singapore are negotiating master service agreements that bypass regional stocking distributors. This pattern concentrates volume with manufacturers possessing in-house engineering services and captive steel supply arrangements.
Global Metal-Faced Insulated Panels Market Segmentation
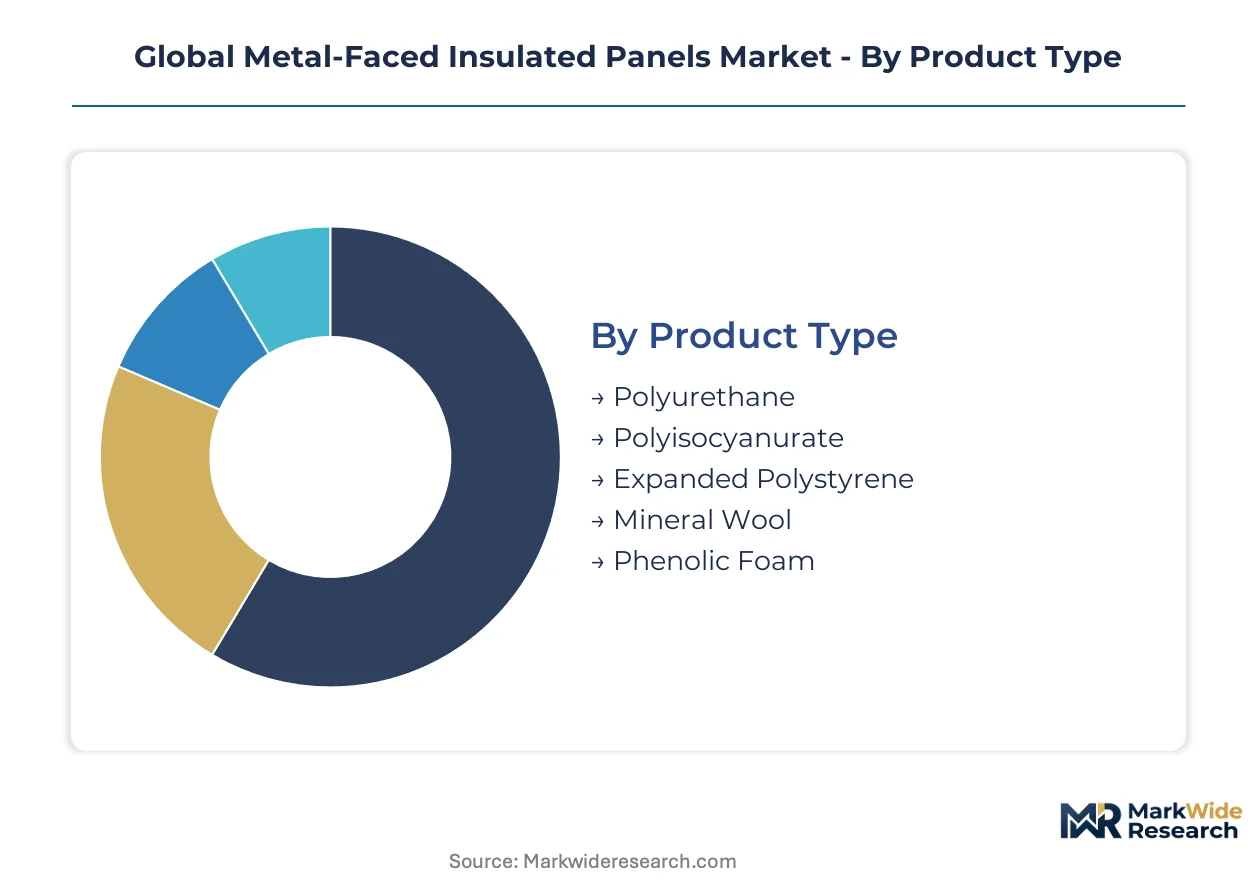
Segmentation in metal-faced insulated panels reflects divergent thermal performance requirements and regulatory constraints across end-use environments. Core chemistry selection and panel geometry determine compliance pathways for fire ratings, U-values, and structural spans in ways that fragment procurement patterns.
Product Type:
Polyurethane and polyisocyanurate formulations integrate into continuous lamination lines for high-volume production, while mineral wool and phenolic alternatives serve standalone specifications where fire resistance dominates thermal optimization.
- Polyurethane:Closed-cell polymer chemistry achieves R-values of 6.0-6.5 per inch through gas-filled cellular structure. Cold storage facilities in Germany and the Netherlands specify these cores for their superior thermal resistance in sub-zero envelope applications. REACH restrictions on halogenated flame retardants are forcing reformulation with phosphorus-based alternatives.
- Polyisocyanurate:Modified isocyanurate ring structures deliver enhanced dimensional stability and higher temperature tolerance than standard polyurethane. Data center developers in Northern Virginia and Frankfurt specify thicker polyiso-cored roof panels for single-span applications up to 12 meters. Continuous lamination advances have eliminated delamination risks in panels exceeding 200mm thickness.
- Expanded Polystyrene:Molded bead polystyrene cores offer cost-competitive thermal performance for budget-sensitive warehousing specifications in India and Southeast Asia.
- Mineral Wool:Inorganic fiber cores achieve EN 13501-1 Class A2-s1,d0 ratings required for European pharmaceutical manufacturing and high-bay warehousing.
- Phenolic Foam:Thermoset phenolic resin chemistry provides low smoke emission characteristics for rail infrastructure and tunnel applications in the United Kingdom and Japan.
Polyurethane leads volumes today; polyisocyanurate is gaining share fastest.
End User Industry:
Demand concentrates in facilities requiring precise thermal stability and stringent hygiene envelope standards, with procurement scale varying dramatically between mission-critical pharmaceutical environments and commodity warehousing.
- Cold Storage Facilities:Controlled-atmosphere warehouses and distribution centers for frozen and fresh food products require envelope systems maintaining -25°C to +4°C interior conditions. India's national cold chain gap—operating at 25-30% of required FSSAI-estimated capacity—is driving specification near Mumbai and Hyderabad pharmaceutical hubs.
- Data Centers:Hyperscale cloud facilities demand thermal envelopes supporting precision cooling efficiency and rapid deployment timelines. Modular power module integration in Northern Virginia and Frankfurt has compressed construction schedules from 18 months to 6 months through factory-built envelope assemblies.
- Food Processing Units:USDA and FDA-regulated facilities require washdown-compatible panel surfaces with antimicrobial coatings.
- Warehousing:General logistics specifications prioritize cost-optimized polyurethane cores for ambient storage in Chinese e-commerce fulfillment networks.
- Pharmaceutical Manufacturing:ISO 14644 cleanroom envelopes for biologics production combine mineral wool fire resistance with polymer-core thermal performance in United States and Chinese facilities.
Cold storage anchors procurement volumes today; data center specifications are expanding most quickly.
Application:
Panel geometry selection governs structural loading requirements and joint detailing complexity, with roofing applications demanding the most sophisticated thermal bridging mitigation.
- Wall Panels:Vertical envelope assemblies in Chinese office towers are displacing conventional curtain wall systems under tightened GB 50189 U-value requirements for buildings exceeding 20,000 square meters.
- Roofing Panels:Single-span roof assemblies bear dead loads, live loads, and environmental exposure without intermediate support. Thickness capabilities up to 250mm enable R-48 thermal resistance in Nordic distribution facilities.
- Sandwich Panels:Structural composite assemblies integrate insulation and weather protection in single components for rapid-erection industrial buildings.
- Partition Panels:Non-load-bearing interior divisions for cleanroom zoning and temperature segregation in pharmaceutical suites.
- Flooring Panels:Insulated floor assemblies for cold storage mezzanines and elevated work platforms in automated warehousing.
Wall panels dominate current specification; roofing panels are climbing the fastest.
Installation Type:
Construction methodology determines panel procurement channel and engineering support requirements, with factory-built approaches compressing field labor dependencies.
- New Construction:Greenfield industrial and commercial developments allow optimized envelope design from foundation integration. Direct procurement from fabricators for projects above 50,000 square meters is bypassing traditional distributor channels.
- Renovations:EU Green Deal commercial retrofit mandates across member states are accelerating replacement of legacy envelope systems in German logistics hubs and Dutch cold storage corridors.
- Modular Buildings:Factory-built power modules and cleanroom pods integrate thermal envelopes in controlled manufacturing environments.
- Prefabricated Structures:Pre-engineered metal building systems incorporate insulated panels as primary envelope components.
- Temporary Facilities:Rapid-deployment insulated enclosures for emergency cold storage and field hospitals.
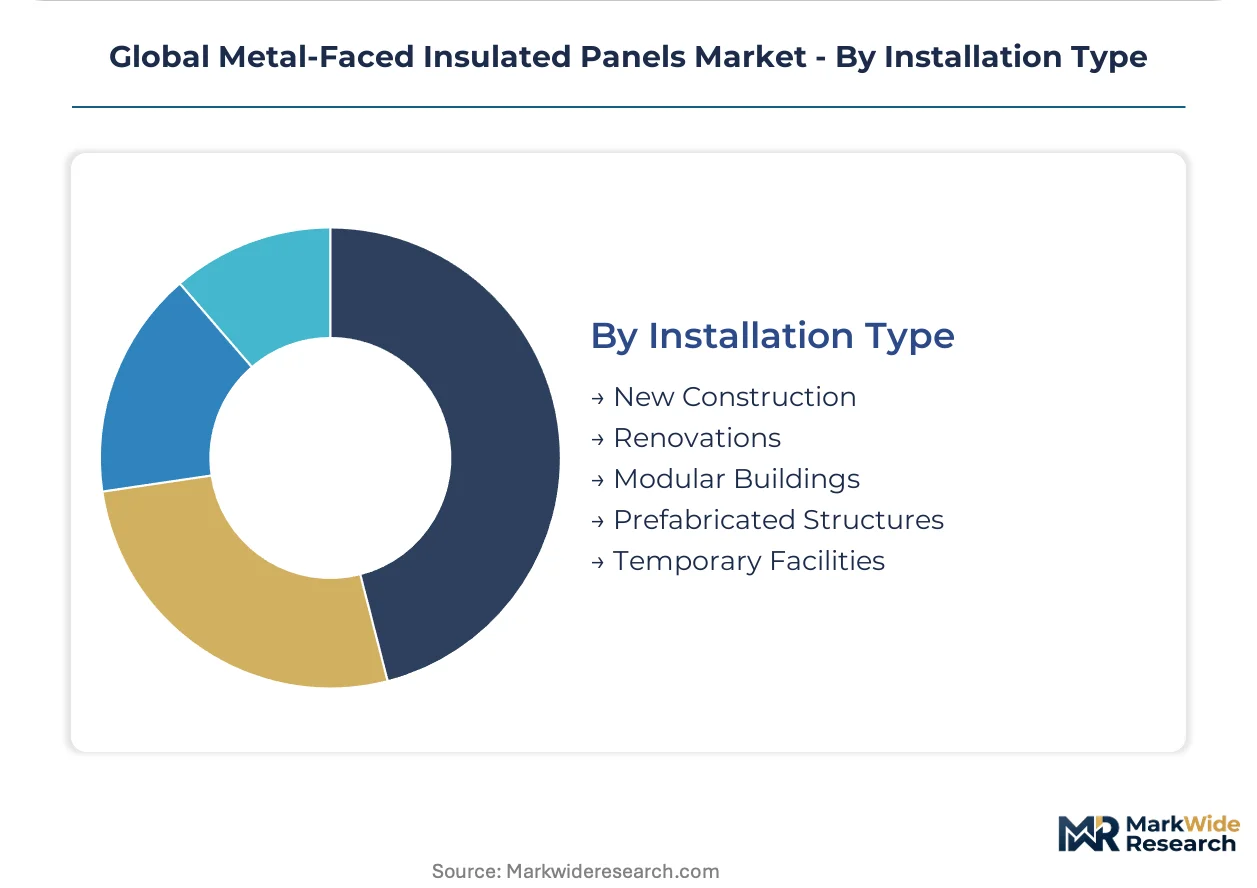
New construction commands the largest volume share; modular building approaches are seeing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German logistics hubs anchor procurement volumes for metal-faced insulated panels, with pharmaceutical manufacturing corridors in the United States and cold storage buildouts across China completing the dominant demand triangle.
United States
Biologics production facilities in Massachusetts and North Carolina require ISO 14644 cleanroom envelopes with precise thermal stability. FDA oversight of pharmaceutical manufacturing environments mandates validated envelope systems. Northern Virginia data center clusters specify factory-built power modules with integrated thermal envelopes, compressing construction timelines from eighteen months to six months.
Germany
EU Green Deal commercial retrofit mandates accelerate replacement of legacy envelope systems in Hamburg and Ruhr logistics corridors. ECHA-reviewed flame retardant documentation requirements extend product qualification cycles by eight to twelve months. Dutch-German cold storage corridors specify mineral wool-cored panels for EN 13501-1 Class A2-s1,d0 compliance alongside polymer cores for thermal performance.
China
Revised GB 50189 public building energy standards displace conventional curtain wall systems with metal-faced panel rainscreen assemblies in Shanghai and Shenzhen office towers above twenty thousand square meters. MIIT oversight of industrial facility construction drives specification toward certified fire-rated assemblies. Yangtze River Delta pharmaceutical manufacturing hubs demand combined mineral wool and polyurethane core solutions.
India
FSSAI-estimated national cold storage capacity operates at twenty-five to thirty percent of required volume, creating specification windows near Mumbai and Hyderabad pharmaceutical distribution hubs. CDSCO regulation of pharmaceutical manufacturing environments elevates envelope performance requirements. Western Maharashtra logistics corridors represent the primary concentration of emerging insulated envelope procurement.
Netherlands
Controlled-atmosphere pharmaceutical distribution facilities in Rotterdam and Utrecht specify phase-change material integrated panels to dampen temperature excursions during refrigeration system cycling. REACH restriction proposals on halogenated flame retardants force core chemistry reformulation across supply chains. Dutch cold storage specifications drive accelerated qualification of modified polyisocyanurate cores satisfying both thermal and revised safety criteria.
Global Metal-Faced Insulated Panels Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular data center and cold chain infrastructure specializations. The vendor base clusters around three archetypes: integrated insulation-facade technology portfolios, captive steel supply with in-house roll-forming capacity, and rapid-turn custom fabrication specialists. Scale-driven consolidation and direct procurement channel compression represent the dominant competitive moves, as project owners above fifty thousand square meters bypass traditional distributors.
Among Ireland-based building envelope specialists, Kingspan Group exemplifies integrated insulation and facade technology portfolios. Nucor Building Systems represents North American fabricators with steel supply integration. Metl-Span occupies a position among rapid-turn custom panel specialists serving modular deployment models.
| Leading Market Players |
|---|
| Kingspan Group |
| Nucor Building Systems |
| Metl-Span |
| CENTRIA |
| Cornerstone Building Brands |
| Owens Corning Insulating Systems |
| MBCI |
| ArcelorMittal |
| Green Span |
| Others |
Supply & Pricing Matrix
Pre-coated steel sheet indices from Nucor and ArcelorMittal cascade through metal-faced insulated panel supply chains, compressing margin visibility for fabricators on fixed-price construction contracts while concentrating pricing power with integrated producers possessing captive metallurgical supply.
Pricing Analysis
Input-cost pass-through from polyurethane and polyisocyanurate precursor markets governs panel pricing tiers. Three-tier pricing structure across premium, standard, and economy levels separates EN 13501-1 Class A2-certified mineral wool assemblies from polymer-core commodity specifications and budget-grade expanded polystyrene alternatives. Cost compression in standard-tier polyurethane panels is intensifying because BASF and Covestro facility outages expose buyers to force majeure premiums. Cold storage developers in India exhibit highest price sensitivity, while pharmaceutical manufacturers in Germany and the United States prioritize fire certification over unit economics.
Supply Chain Analysis
China's GB standards and India's domestic-content preferences for public infrastructure are reshaping sourcing patterns toward localized lamination capacity. Manufacturing gravity centers on Germany, the United States, and China, where continuous lamination lines achieve scale efficiencies. Polyisocyanurate production draws from U.S. Gulf Coast and Rhine-Ruhr corridor precursor clusters, creating single-source vulnerability to regional chemical plant disruptions. Distribution runs through direct procurement channels for projects above fifty thousand square meters, bypassing traditional regional stocking distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between European fire-certification premiums and Asian manufacturing cost bases offers structural margin capture for players with cross-regional production footprints.
For Market Incumbents: Deploy captive steel supply arrangements to defend margin position against pre-coated metal sheet volatility. Kingspan Group and Nucor Building Systems anchor competitive position through backward integration into metallurgical inputs and in-house roll-forming capacity. Counter emerging rapid-turn fabrication specialists by investing in EN 13501-1 Class A2-s1,d0 qualification pipelines that extend competitor product development timelines.
For New Entrants and Emerging Players: Begin with India's pharmaceutical distribution corridor near Mumbai and Hyderabad, where FSSAI-estimated cold storage undercapacity creates specification windows without entrenched incumbent relationships. Target modular data center envelope assemblies for hyperscale cloud providers in Northern Virginia and Frankfurt, where factory-built power module procurement compresses traditional construction channels. Establish direct procurement relationships with project owners above fifty thousand square meters to bypass distributor margin capture.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional fabricators possessing mineral wool lamination capability and pending EN 13501-1 Class A2 certifications. Five-to-ten year viability hinges on REACH-compliant flame retardant chemistry transitions. Acquisition focus: mid-cap specialists with captive steel supply and in-house engineering services. Signal to monitor: ECHA restriction proposals on halogenated flame retardants accelerating core chemistry reformulation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Supply | Nucor Building Systems controls pre-coated sheet cost volatility through captive metallurgical production. |
| Fire Certification Fast-Track Programs | Accelerated EN 13501-1 Class A2-s1,d0 qualification captures pharmaceutical manufacturing specifications in Germany. |
| Modular Data Center Partnerships | Factory-built power module integration with hyperscale cloud providers compresses construction timelines in Northern Virginia. |
| REACH-Compliant Chemistry Reformulation | Phosphorus-based flame retardant substitution maintains European market access under ECHA-reviewed standards. |
| Direct Procurement Channel Development | Master service agreements with project owners above fifty thousand square meters bypass distributor margin structures. |
Research Methodology
Multiple input streams — primary interviews with envelope contractors and pharmaceutical facility engineers, secondary validation through customs data and building permit databases, and technical specification analysis — were reconciled to construct market estimates. Conversations with cold storage developers, data center construction managers, and insulation procurement leads at major fabricators informed demand-side assumptions. Regulatory filings with ECHA, FDA, and China's MIIT provided compliance trajectory inputs. Bottom-up project pipeline analysis and top-down construction spending forecasts were cross-referenced for triangulation.
Historical shipment data from continuous lamination line operators were cross-referenced against panel fabricator panel input to establish baseline volumes. The analytical framework modeled demand across core chemistry, end-use industry, application geometry, and installation methodology over the projection horizon. CAGRs were derived from segmented growth rate analysis incorporating EU Green Deal retrofit mandates, pharmaceutical manufacturing expansion trajectories, and data center deployment acceleration. Forecast inputs included steel price index trajectories, REACH regulatory timeline assumptions, and regional building code adoption rates.
Several conditions sit outside the modeled scope, including force majeure events at BASF or Covestro precursor facilities, abrupt tariff modifications on pre-coated steel imports, and unanticipated ECHA flame retardant restriction acceleration. Forecasts reflect documented assumptions regarding regulatory implementation timelines and construction spending continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
Acoustic Insulation Market
Building & Construction Materials
Metal Grating Market
Building & Construction Materials
North America Cross-Laminated Timber Market
Building & Construction Materials
Gutter and Downspout Market
Building & Construction Materials
Artificial Bowling Surface Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
Asia-Pacific Ready-Mix Concrete Market
Building & Construction Materials
Concrete Conditioner Market
Building & Construction Materials
Building and Construction Sealants Market
Building & Construction Materials
Particleboard Market