
 Timber Construction Connectors Market | 2026-2036
Timber Construction Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Timber Construction Connectors Market Intelligence
The European Union's updated Construction Products Regulation (CPR) is restructuring market access requirements for timber connectors. This mandate for performance declaration and CE marking elevates compliance costs. Simpson Strong-Tie Company Inc. leverages its extensive testing and certification infrastructure to meet these standards. SFS Group AG competes on innovation in specialized fastening systems for mass timber, while Rothoblaas S.p.A. specializes in high-performance concealed connectors for aesthetic wood structures.
Timber construction connectors are engineered metal components designed to join wood elements and transfer structural loads like shear, tension, and compression. These parts are typically fabricated from galvanized or stainless steel to prevent corrosion. Steel materials dominate the market due to their strength-to-cost ratio and established manufacturing processes. Within applications, the residential segment holds a significant share, while commercial projects utilizing mass timber represent the fastest-growing opportunity for high-capacity connectors.
Product performance and safety are governed by a matrix of standards, including ISO guidelines for structural design and the CE marking framework in Europe. National building codes, such as the International Building Code (IBC) in the United States, dictate specific connector requirements for seismic and wind-load resistance. Vendor selection will increasingly hinge on the ability to provide documented proof of compliance with evolving carbon-accounting and life-cycle assessment criteria.
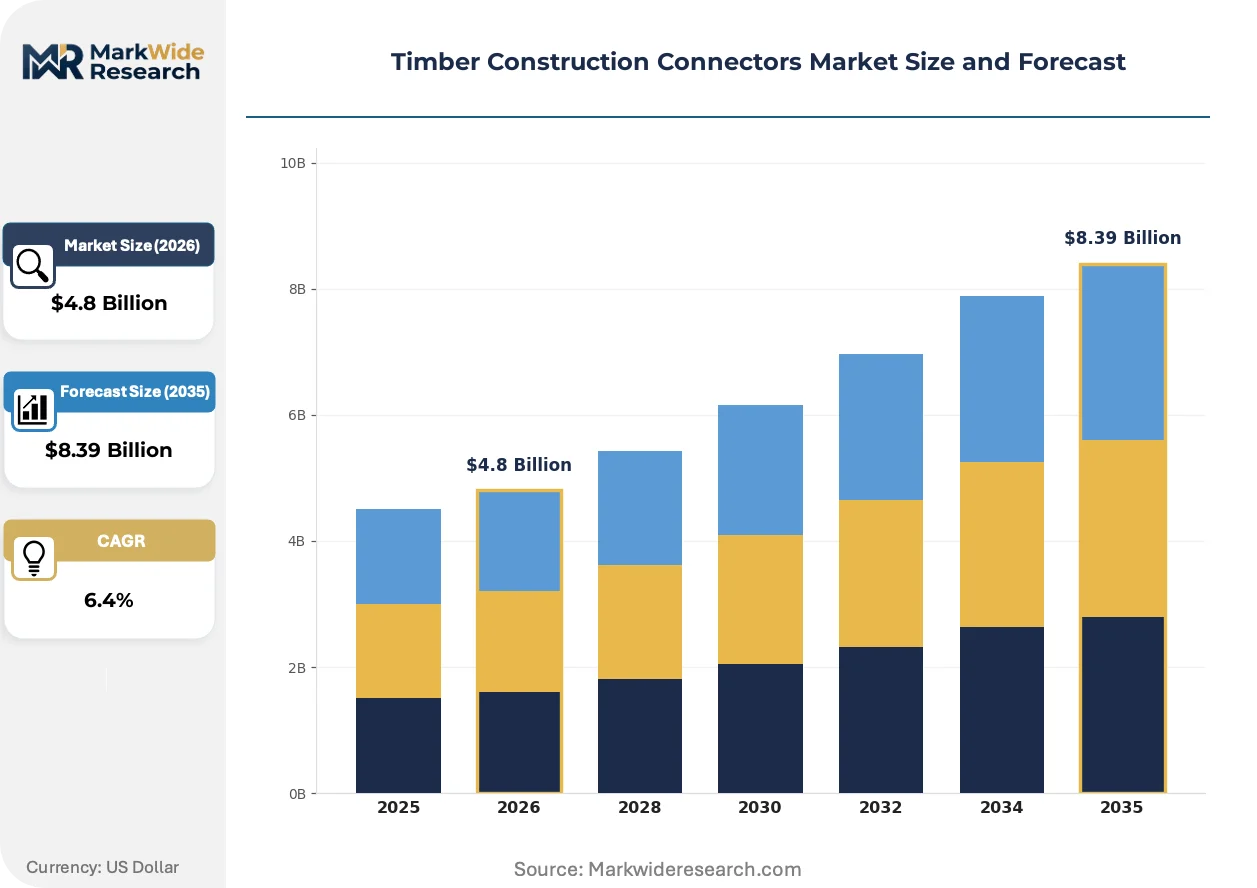
Market Dynamics
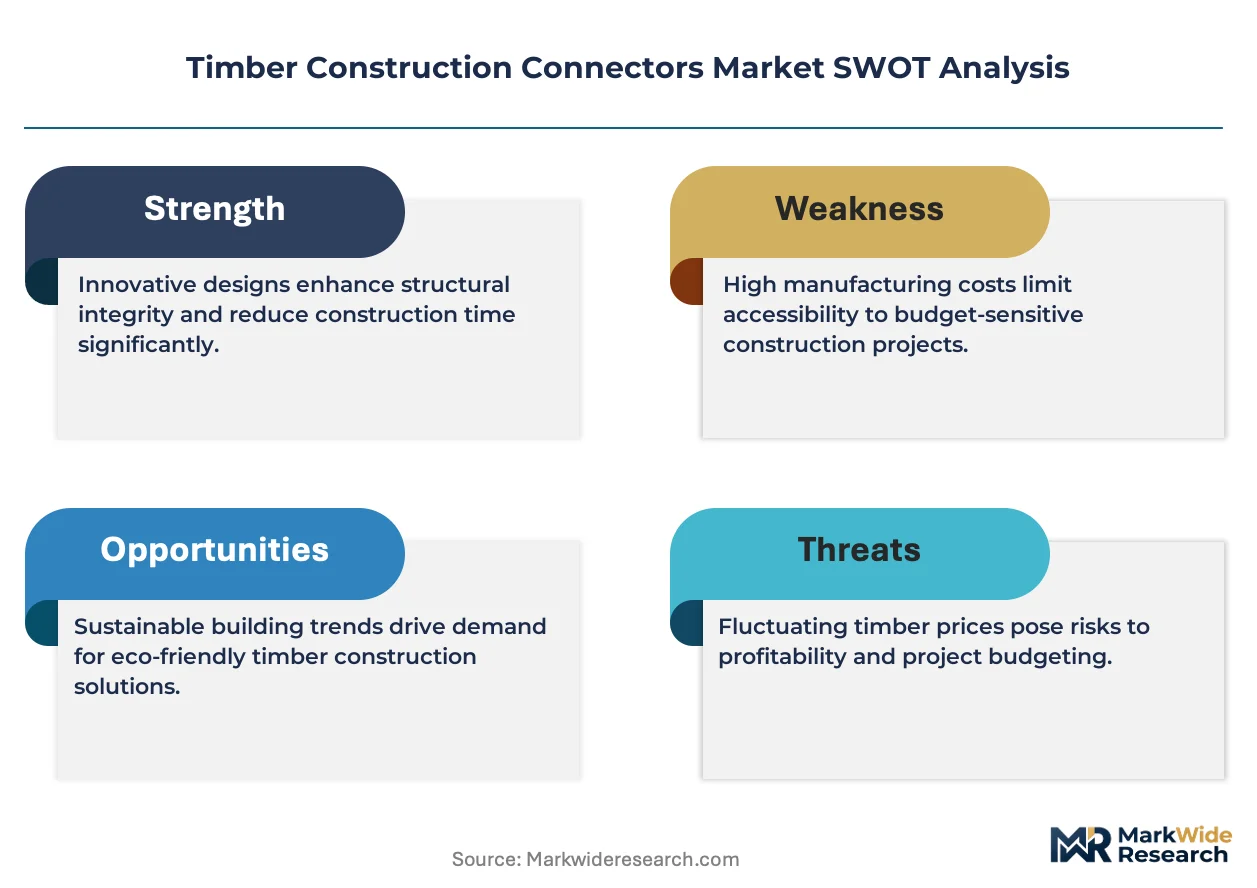
The expansion of mass timber construction into taller and more complex buildings is the central force shaping the connector market. This architectural and engineering shift demands a new class of high-capacity, fire-rated, and rigorously tested connectors, moving them from simple hardware to critical structural systems.
Growth Catalysts
- Building Code Modernization:Revisions to the International Building Code (IBC) that permit wood structures of greater height are directly stimulating demand for advanced connectors in the United States.
- Urban Densification Projects:The push for multi-story residential and mixed-use commercial buildings in dense urban centers favors timber construction for its speed and lower site impact, boosting connector volume.
- Sustainable Construction Mandates:Green building policies and strong forestry traditions in countries like Germany and Canada create a durable demand base for timber-based building solutions and their essential components.
Market Restraints
- Raw Material Price Volatility:The market is sensitive to price fluctuations in galvanized and stainless steel, the primary inputs for connector fabrication, which can compress manufacturer margins and impact project costs.
- Regulatory Compliance Costs:In Europe, the Construction Products Regulation (CPR) imposes stringent CE marking and performance declaration requirements, creating a significant cost and administrative barrier for non-compliant or smaller suppliers.
- Substitution from Hybrid Materials:While steel is dominant, the long-term development of high-strength structural adhesives and fiber-reinforced polymer (FRP) composites presents a potential substitution threat in specific, non-primary load-bearing applications.
Strategic Opportunities
- Geographic Expansion:Markets such as Australia and New Zealand, which are in the early stages of adopting mass timber building codes, offer significant growth potential for established connector manufacturers.
- Seismic Retrofitting Niche:A specialized market is emerging for connectors designed specifically for the seismic retrofitting and reinforcement of older timber-framed buildings, particularly in earthquake-prone regions.
- Digital Integration:The development of connectors with embedded sensors for structural health monitoring (SHM) creates an opportunity to provide data-driven services and move up the value chain.
Industry Challenges
- Specialized Labor Scarcity:A shortage of engineers, architects, and tradespeople skilled in mass timber design and assembly can slow the adoption rate of advanced timber systems and their corresponding connectors.
- Harmonization of Standards:Discrepancies between major international testing protocols, such as Europe's Eurocode 5 and North American standards, create design and specification complexities for global projects.
- Life-Cycle Data Requirements:The increasing demand for comprehensive Environmental Product Declarations (EPDs) and life-cycle assessment data adds an operational burden and cost layer to the manufacturing process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Timber Construction Connectors Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nail Plates, Steel Angles, Bolts, Connectors Material: Steel, Aluminum, Plastic, Composite Application: Residential, Commercial, Agricultural, Industrial Installation Type: Prefabricated, On-site, Modular, Custom |
| Companies Covered | SFS Group AG, Hilti AG, Simpson Strong-Tie Company Inc., Rothoblaas S.p.A., Fischerwerke GmbH & Co. KG, MiTek Industries, Inc., Adolf Würth GmbH & Co. KG, Knapp GmbH, Illinois Tool Works Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Timber Construction Connectors Market Strategic Shifts & Innovations
The market is being redefined by a convergence of architectural demand for aesthetics and engineering demand for performance data. This is transforming connectors from commodity hardware into sophisticated, pre-engineered systems integral to the design, assembly, and long-term monitoring of modern timber structures.
Concealed connectors are engineered metal components designed to be hidden within the wood elements they join. Architects specifying mass timber for high-value commercial and hospitality projects are driving their adoption to achieve clean, wood-only aesthetics. This preference for uninterrupted surfaces means concealed systems are overtaking traditional exposed steel plates and brackets in visually sensitive applications.
Europe's updated Construction Products Regulation (CPR) requires a formal Declaration of Performance for all construction products sold within the EU. This mandate forces manufacturers to provide extensive, verifiable data on key characteristics like load capacity, stiffness, and fire resistance. This regulatory shift primarily impacts suppliers seeking access to the European market, compelling significant investment in third-party testing and certification infrastructure.
A notable behavioral shift is occurring from component-level purchasing toward complete system specification. Instead of sourcing individual fasteners, large-scale general contractors and structural engineering firms increasingly procure fully integrated connector packages from a single vendor for an entire project. This trend is most visible in complex mass timber constructions in North America and Scandinavia, where it simplifies logistics and ensures system compatibility.
Timber Construction Connectors Market Segmentation
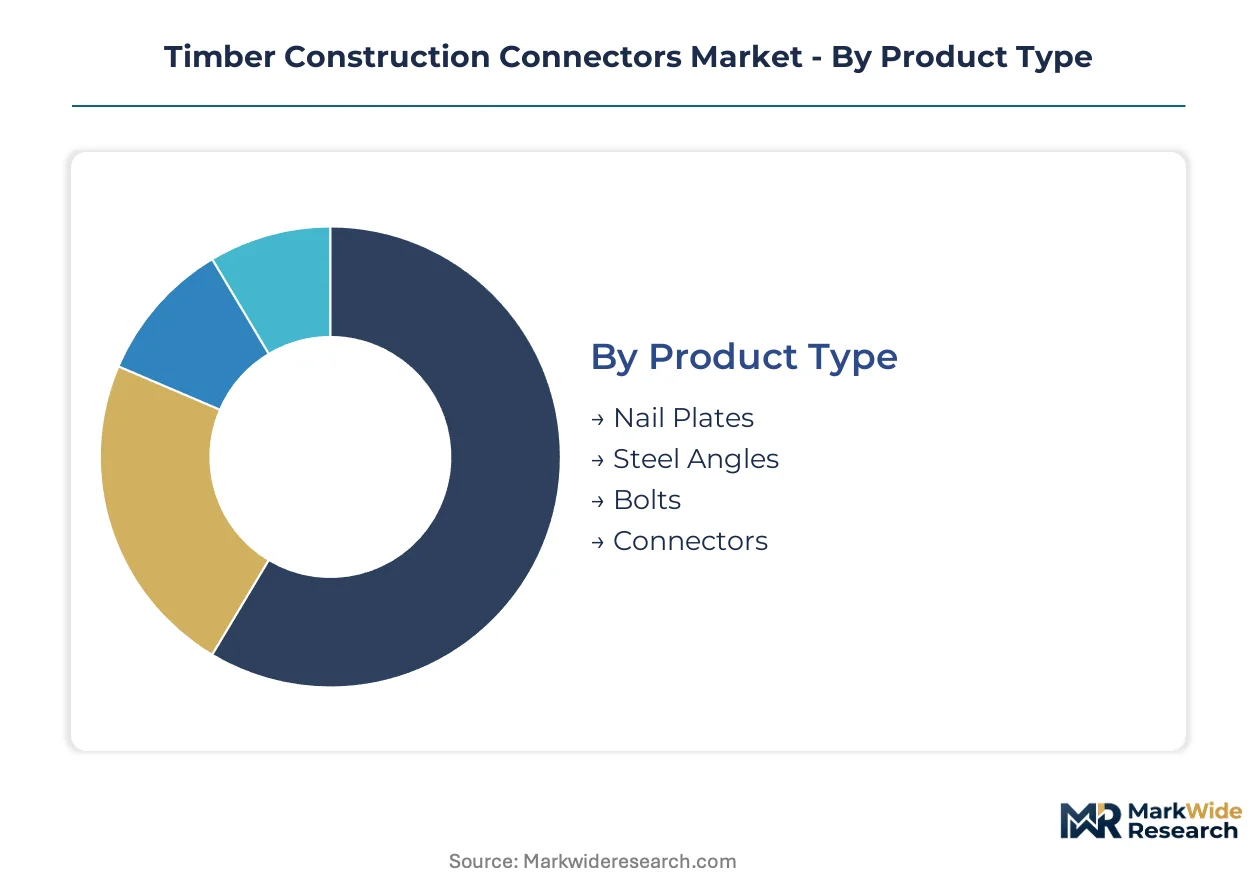
The timber construction connectors market exhibits diverse segmentation driven by varying structural demands, material properties, and application specifics. Understanding these distinctions helps manufacturers tailor product development and market strategies for specialized construction needs.
Product Type:
Buyers in the timber construction connectors market often prioritize specific design requirements and structural performance needs when selecting product types.
- Connectors:These engineered metal components transfer complex loads between timber elements, often featuring advanced geometries for high capacity and efficient force distribution in mass timber structures. Demand concentrates in multi-story residential and commercial buildings within North America, driven by evolving building codes.
- Nail Plates:Fabricated steel plates with integral teeth, nail plates are pressed into timber to provide structural connections, primarily in light-frame construction and truss assembly. Their demand is strong in prefabricated housing components due to their ease of installation and cost-effectiveness.
- Steel Angles:L-shaped metal components, steel angles provide simple, robust connections, typically fastened with bolts or screws to resist shear and tension forces.
- Bolts:Threaded fasteners used with nuts and washers, bolts create strong, demountable connections, particularly in heavy timber framing and large-span structures.
Connectors leads volumes today; Bolts is gaining share fastest.
Material:
The selection of material for timber connectors often depends on the required strength-to-weight ratio and corrosion resistance for a given project.
- Steel:Galvanized or stainless steel components dominate the market due to their superior strength, durability, and cost-effectiveness, widely used across all construction types. The material's established manufacturing processes support its widespread availability and application.
- Composite:These materials, often fiber-reinforced polymers, offer high strength-to-weight ratios and corrosion resistance, finding niche applications where traditional metals are unsuitable or for specialized aesthetic requirements. Their demand is growing in architecturally sensitive projects.
- Aluminum:Lighter than steel, aluminum connectors are chosen for applications where weight reduction is critical or for specific aesthetic considerations, though they offer lower strength.
- Plastic:Primarily used in non-load-bearing or light-duty applications, plastic connectors provide cost-effective solutions for secondary timber elements and non-structural joints.
Steel components maintain the largest market share; Composite materials are expanding most quickly.
Application:
End-use demand characteristics significantly influence the type and capacity of timber connectors specified for a project.
- Residential:This segment includes single-family homes, multi-story apartments, and townhouses, requiring a broad range of connectors for framing, roofing, and flooring systems. The segment holds a significant share due to the sheer volume of housing construction.
- Commercial:Encompassing office buildings, retail spaces, and institutional structures, the commercial segment increasingly utilizes mass timber, driving demand for high-capacity and fire-rated connectors. This application represents the fastest-growing opportunity.
- Agricultural:Connectors for agricultural buildings, such as barns, sheds, and storage facilities, prioritize durability and resistance to environmental factors.
- Industrial:This application involves connectors for heavy-duty timber structures in industrial facilities, requiring robust components capable of supporting significant loads.
Residential applications command the largest market volume; Commercial projects are seeing the steepest expansion trajectory.
Installation Type:
Construction methodology and project timelines dictate the preferred installation type for timber connectors.
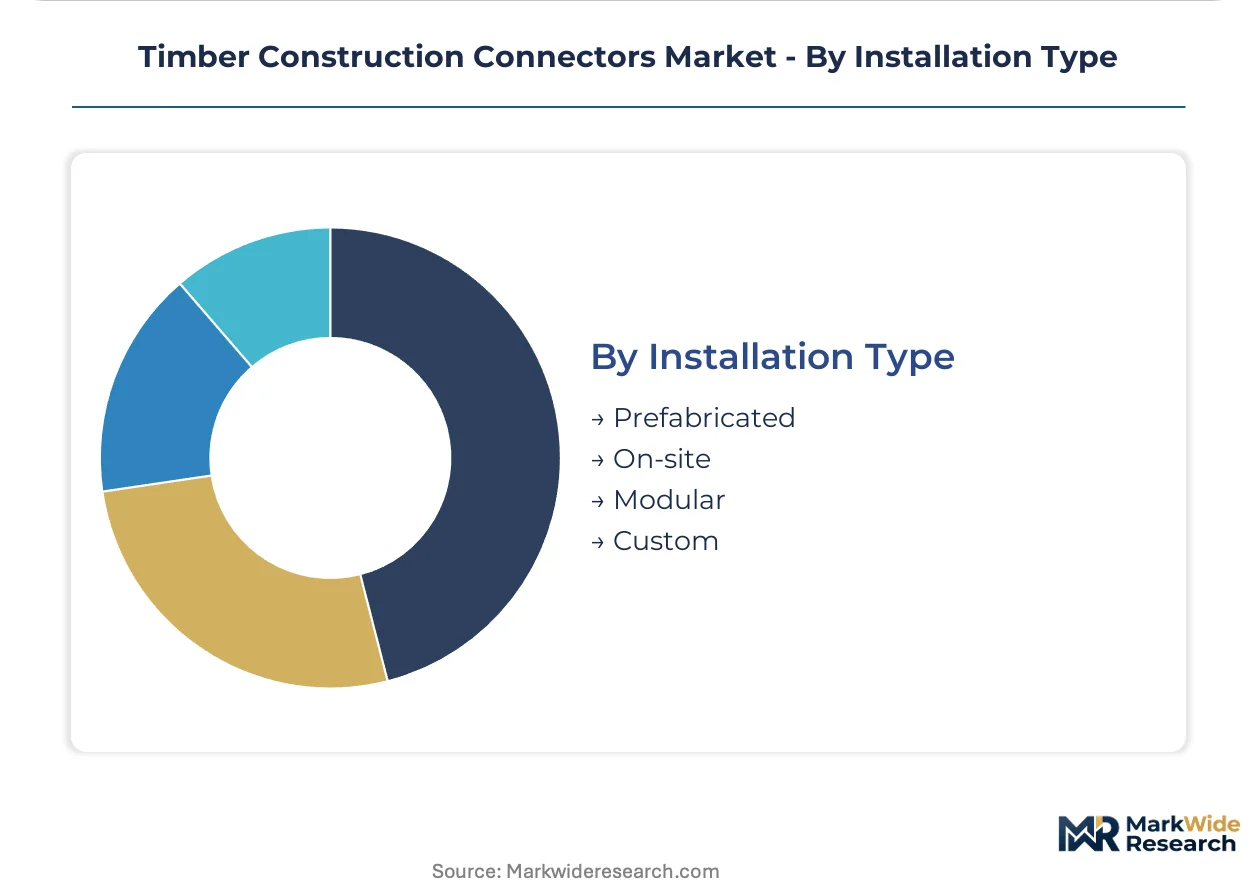
- Prefabricated:Connectors integrated into timber elements off-site, reducing on-site labor and accelerating construction schedules for modular and panelized timber systems. This method supports faster project delivery in urban densification projects.
- Modular:Connectors designed for joining pre-assembled timber modules, enabling rapid assembly of multi-story buildings with minimal on-site disruption. Europe's focus on off-site construction drives demand for these specialized connectors.
- On-site:Connectors installed directly at the construction site, common for traditional stick-built framing and custom timber structures where prefabrication is not feasible.
- Custom:Specialized connectors engineered for unique architectural designs or complex structural requirements, often involving bespoke fabrication and detailed engineering.
On-site installation remains prevalent for many projects; Modular construction methods exhibit the highest growth in adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Timber construction connectors first scaled in regions with abundant forest resources and early adoption of wood-based building traditions. Countries like Germany and Canada pioneered the use of engineered timber in construction, establishing foundational demand for specialized joining elements. This lineage continues to shape market development, particularly with the push for sustainable building practices.
Germany
Germany's demand for timber connectors stems from robust green building mandates and strong forestry traditions. The country's strict building codes, including Eurocode 5, emphasize performance and sustainability in timber structures. In cities like Freiburg, advanced timber construction projects drive demand for high-capacity, fire-rated connection systems.
Canada
Canada's market for timber connectors expands with its leadership in mass timber construction and sustainable urban development. Health Canada supports the use of wood in larger buildings, reflecting national green building policies. British Columbia around Vancouver acts as a hub for innovative mass timber projects, requiring specialized connectors.
United States
Demand in the United States is spurred by modernizing building codes and a push for urban densification. Revisions to the International Building Code (IBC) permit taller wood structures, directly impacting connector specifications. The Pacific Northwest sees significant activity in mass timber construction, necessitating advanced structural connections.
Australia
Australia presents a nascent but rapidly growing market for timber connectors, driven by evolving building regulations and sustainability goals. The country is in the early stages of adopting mass timber building codes, creating new opportunities for specialized products. Urban centers like Sydney are seeing an increase in hybrid timber projects, requiring robust, compliant connector solutions.
France
France's market for timber connectors grows from national commitments to sustainable construction and carbon reduction. The EU's Construction Products Regulation (CPR) significantly influences product requirements for connectors sold within France. The Île-de-France region, including Paris, showcases numerous timber construction projects, fueling demand for aesthetic, high-performance connections.
Timber Construction Connectors Market Key Industry Players
The competitive structure tilts toward specialized manufacturers capable of meeting stringent performance and compliance standards. The market segments into providers of commodity hardware and innovators offering sophisticated, pre-engineered systems. Strategic archetypes include global solution providers, niche specialists in mass timber, and regional suppliers focusing on cost-effectiveness. Geographic expansion and technology licensing represent dominant competitive moves among these players.
Specialists in high-performance and innovative fastening systems exemplify the premium tier. SFS Group AG, a Switzerland-based company, competes on innovation in specialized fastening systems for mass timber. Rothoblaas S.p.A., an Italian company, occupies a strong position with its expertise in high-performance concealed connectors for aesthetic wood structures. Simpson Strong-Tie Company Inc., a US-based entity, anchors the market with its extensive testing and certification infrastructure, meeting evolving compliance standards.
| Leading Market Players |
|---|
| SFS Group AG |
| Hilti AG |
| Simpson Strong-Tie Company Inc. |
| Rothoblaas S.p.A. |
| Fischerwerke GmbH & Co. KG |
| MiTek Industries, Inc. |
| Adolf Würth GmbH & Co. KG |
| Knapp GmbH |
| Illinois Tool Works Inc. |
| Others |
Cost & Logistics Intelligence
Steel commodity pricing, particularly for galvanized and stainless steel, directly influences the cost structure of timber connectors, cascading into tiered pricing for end-users. This volatility compresses manufacturer margins and impacts project budgets for construction firms.
Pricing Analysis
Project-based pricing dominates for complex mass timber structures, where integrated connector packages are specified. Price differentiation stems from certification levels, such as CE marking compliance, and specialized performance attributes like fire rating. Pricing pressure stems from raw material price volatility, compressing manufacturer margins for standard components. Commercial projects utilizing high-performance concealed connectors exhibit less price sensitivity, while residential and prefabricated housing segments are more cost-conscious.
Supply Chain Analysis
Single-source vulnerability sits with steel producers, particularly in major manufacturing regions such as China and India, given the dominance of galvanized and stainless steel as primary inputs. The market relies on a steady supply of these metals, making it susceptible to commodity price fluctuations. Regulatory restrictions, such as those imposed by the EU's Construction Products Regulation, represent a structural risk for non-compliant suppliers. Distribution runs through both direct sales to large contractors and established networks of construction material distributors for commodity items.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with revisions to the International Building Code directly stimulating demand for advanced connectors.
For Market Incumbents: Deepen investment in comprehensive testing and certification infrastructure to meet evolving global standards like CE marking and IBC. Expand product lines to include high-capacity, fire-rated connectors essential for mass timber applications. This counters the threat of substitution from hybrid materials and ensures compliance. Focus R&D on integrated systems that simplify installation and offer enhanced structural performance.
For New Entrants and Emerging Players: Capture niche opportunities in rapidly expanding mass timber markets, such as Australia and New Zealand, where building codes are still evolving. Target the specialized seismic retrofitting segment for older timber-framed buildings in earthquake-prone regions. A go-to-market angle focusing on digital integration, such as embedded sensors for structural health monitoring, provides data-driven services and differentiates offerings.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory compliance costs are high and specialized expertise in mass timber fastening systems is scarce. The long-term viability of this market is strong, driven by sustainable construction mandates and urban densification. Target acquisition archetypes include niche specialists in concealed connectors or firms with advanced digital integration capabilities. The signal to watch is the accelerated adoption of mass timber codes in new geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Certification Infrastructure | Ensures compliance with stringent regulations like the EU CPR, elevating market access for connectors. |
| Develop High-Capacity Fire-Rated Connectors | Addresses the critical demand for safe, robust connections in growing mass timber buildings. |
| Expand into Nascent Mass Timber Markets | Captures early-stage growth opportunities in regions like Australia with evolving building codes. |
| Integrate Digital Structural Health Monitoring | Creates value-added services and differentiates products through data-driven performance insights. |
| Acquire Concealed Connector Specialists | Meets architectural demand for aesthetic wood structures and clean, uninterrupted surfaces. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary validation. We engaged with structural engineers, architects, general contractors, and building code officials to gather first-hand perspectives. Secondary data sources included national building codes like the IBC and Eurocode 5, construction industry reports, and company financial filings, triangulating findings through bottom-up and top-down analyses.
The analytical framework anchored historical performance to comparable periods, projecting future trends across the modeling period. Segmentation dimensions modeled included product type, material, application, and installation type. Compound annual growth rates were derived through a weighted average of segment-specific growth drivers. Key industry-specific forecast inputs included mass timber adoption rates and regional building code revisions.
Raw material price volatility, regulatory shifts, and specialized labor scarcity are the dominant revision risks for market forecasts. These forecasts reflect underlying assumptions regarding construction activity and technological advancements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Concrete Sealer Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Ceiling Tiles Market
Building & Construction Materials
Global Prefab Wood Building Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
Education Building Design Market
Building & Construction Materials
Door Canopy Market
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
Door System Market
Building & Construction Materials
Traffic Road Marking Coatings Market
Building & Construction Materials
East Africa Gypsum Plaster Market
Building & Construction Materials
Building Vibration Isolation Market