
 Global Builder Hardware Market | 2026-2036
Global Builder Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Builder Hardware Market Analysis
Healthcare facility construction is shifting toward specialized access-control specifications, pulling demand toward antimicrobial hardware finishes and electronic locking systems. ASSA ABLOY dominates electromechanical locking technology for hospital environments across Scandinavia and North America. Masco Corporation anchors residential new-build channels through builder-direct programs in the United States. Stanley Black & Decker extends its position in smart-entry systems via Wi-Fi-enabled deadbolt platforms for multi-family developers.
Builder hardware encompasses mechanical and electromechanical fixtures—including locks, hinges, fasteners, and latches—fabricated from stainless steel, brass, aluminum, or engineered polymers to meet fire-rated, corrosion-resistant, or forced-entry-resistant performance criteria. These components secure structural openings, manage traffic flow, and satisfy life-safety codes in residential, commercial, and institutional buildings. Locks and latches command the largest share of product-type revenue due to code-mandated security upgrades in educational and government facilities. Surface-mounted installation methods lead volume in residential renovation where substrate preservation limits mortise routing, though mortise systems retain specification dominance in commercial steel-door applications. Stainless steel material demand outpaces brass in coastal and humid climates where salt corrosion degrades zinc-copper alloys.
The EU's Construction Products Regulation and CE marking framework mandate declared performance characteristics for fire-resistant and panic-exit hardware sold in member states. China's SAMR enforces GB standards for mechanical lock durability and cylinder security grades in domestic and imported products. India's BIS certification for door closers and panic bars is expanding from voluntary to compulsory scope, reshaping import compliance costs for foreign suppliers. Stakeholders must monitor regulatory divergence between electromagnetic compatibility requirements for smart locks in Europe under the Radio Equipment Directive versus FCC Part 15 rules in the United States, as dual-certification burdens will determine which product portfolios achieve cross-border scale.
Market Dynamics
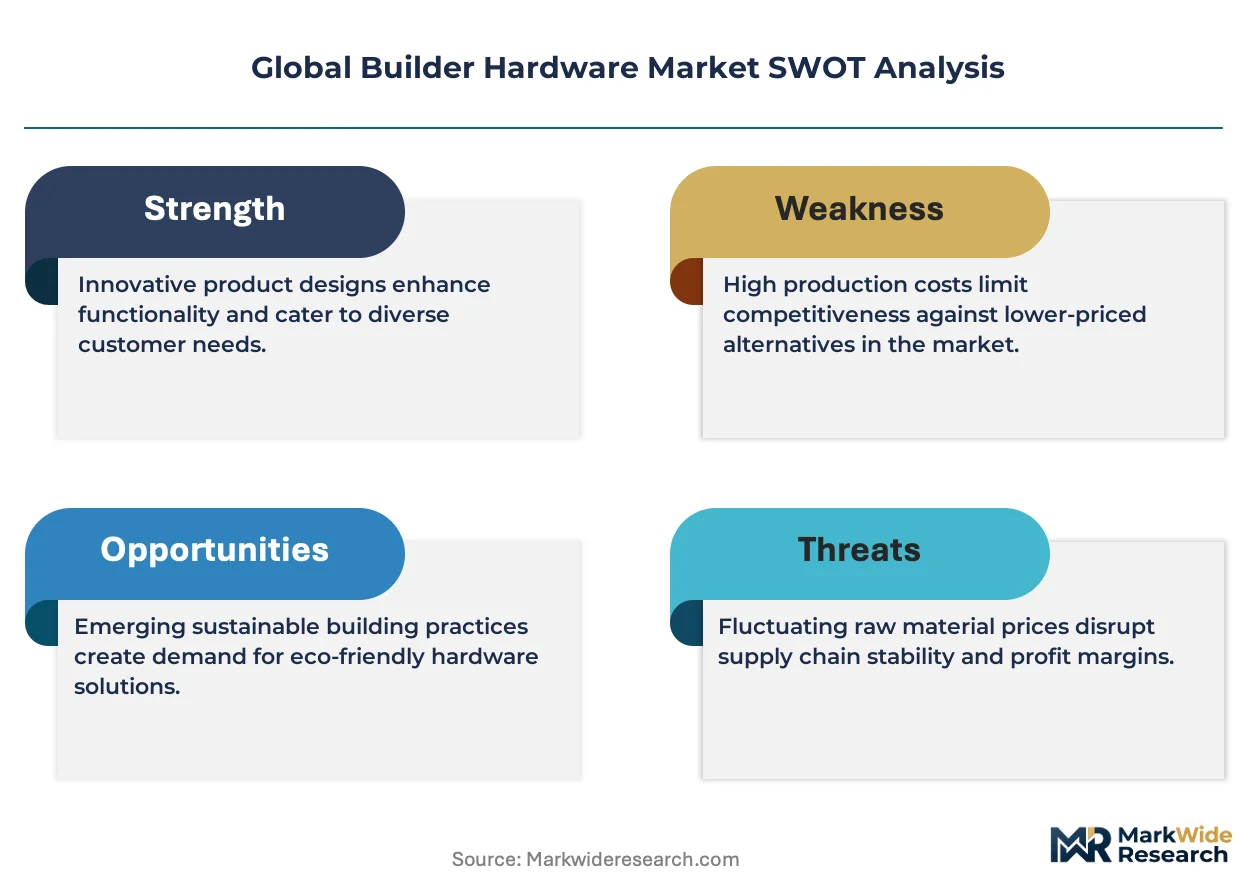
Retrofit-driven replacement cycles across aging residential stock in the United States, Germany, and Japan are compressing hardware refresh timelines while simultaneously elevating performance specifications for fire-rated and smart-locking systems.
Growth Catalysts
- Residential retrofit mandates:Energy-efficiency upgrade programs in Germany and France are triggering whole-window replacement waves that bundle hardware specification upgrades.
- CE marking expansion:The EU's Construction Products Regulation is extending declared-performance requirements to panic-exit devices, forcing specification-grade procurement across member states.
- Antimicrobial finishes:Healthcare facility construction specifications in the United States are mandating copper-alloy and ion-impregnated hardware surfaces for infection control compliance.
Market Restraints
- Zinc-copper alloy vulnerability:Brass hardware faces accelerated corrosion degradation in coastal United States and Australian markets, forcing material substitution to stainless steel.
- Electronics supply concentration:Wi-Fi and Bluetooth module sourcing for smart locks remains concentrated among Taiwanese and South Korean semiconductor fabricators.
- Dual-certification burden:Electromagnetic compatibility testing divergence between FCC Part 15 rules and the EU Radio Equipment Directive adds 14-18 weeks to product launch timelines.
Strategic Opportunities
- India urban corridor penetration:Commercial real estate expansion in Mumbai, Bangalore, and Hyderabad is creating first-mover advantage for specification-grade panic-bar and door-closer suppliers.
- Biometric-electromechanical convergence:Fingerprint-credential integration with battery-operated smart deadbolts is opening retrofit channels in Japanese and South Korean multi-family housing.
- BIS compulsory scope expansion:India's transition of door-closer and panic-bar certification from voluntary to mandatory status is reshaping import compliance barriers for foreign suppliers.
Industry Challenges
- Fire-rating certification timelines:UL 10C and EN 1634 testing protocols for multi-point locking systems require 6-9 month validation cycles that delay product commercialization.
- Legacy mortise interoperability:Smart-lock retrofits into pre-1980 commercial steel-door preparations face cylinder-backset and face-plate dimensional standardization gaps across Japanese, European, and North American legacy installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Builder Hardware Market |
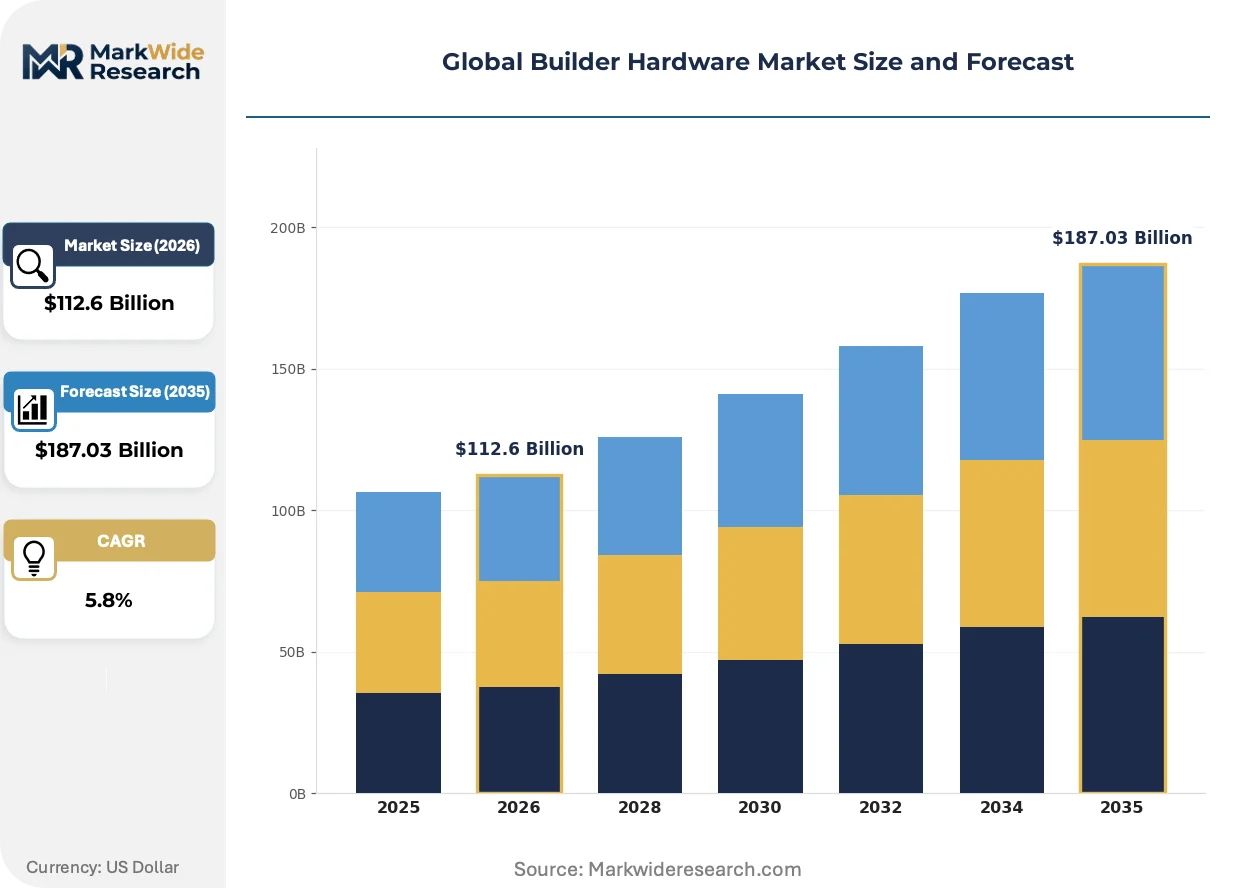
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $187.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Locks, Hinges, Fasteners, Latches Installation Method: Surface-Mounted, Mortise, Center-Set, Recessed Material: Stainless Steel, Brass, Aluminum, Plastic End User: Contractors, Builders, DIY Enthusiasts, Architects |
| Companies Covered | Saltus Window Fashions, Masco Corporation, ASSA ABLOY, Stanley Black & Decker, Fortune Brands Innovations, Allegion, Andersen Corporation, Saint-Gobain, Dormakaba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Builder Hardware Market Emerging Trajectories
Hardware functionality is migrating from purely mechanical security toward connected, data-generating building systems that integrate with facility management platforms and occupant-experience applications.
Bluetooth Low Energy credentialing is decentralizing access-control architecture by enabling smartphone-based entry without hardwired reader infrastructure. Multi-family developers in the United States and Nordic countries are adopting these systems for 40-60 unit properties where traditional wired access-control capex proves prohibitive. This shift is compressing the addressable market for standalone electronic keypads while expanding retrofit opportunity in 1990s-era apartment stock.
China's SAMR enforcement of GB standards for mechanical lock durability and cylinder security grades is tightening domestic-market entry barriers for imported products. The framework mandates 100,000-cycle endurance testing and pick-resistance grading that many mid-tier European and North American suppliers cannot satisfy without design overhaul. Domestic Chinese manufacturers with established GB certification are capturing specification share in government and educational facility procurement.
Builder-direct program consolidation is concentrating residential new-build hardware specification authority among the four largest United States production homebuilders. These buyers are unbundling hardware from lumber-yard packages and negotiating direct multi-year supply agreements that bypass traditional two-step distribution. The shift is visible most acutely in Texas and Florida markets where production housing volume exceeds 50,000 annual starts per metropolitan area.
Global Builder Hardware Market Segmentation
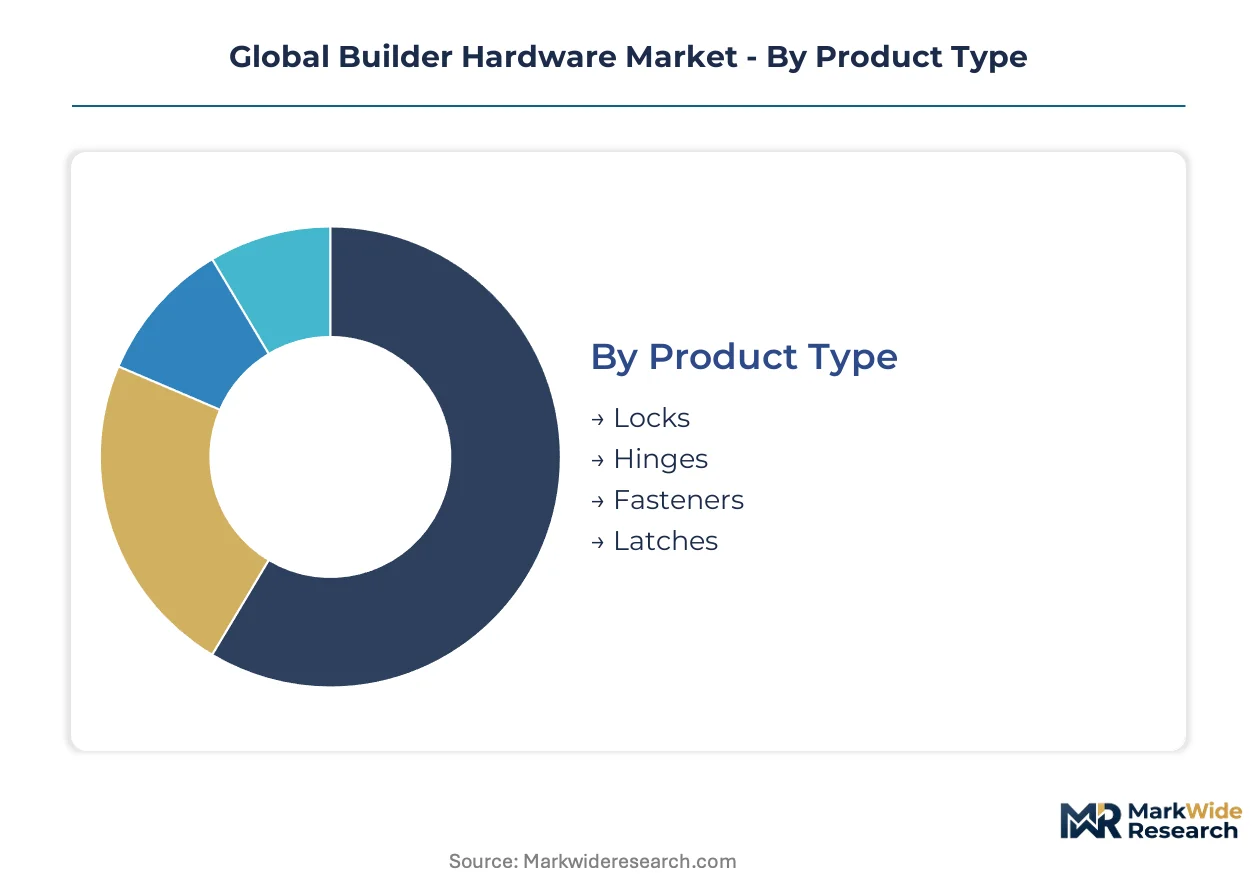
Builder hardware procurement splits across specification-grade commercial channels and price-sensitive residential retail. Material selection and installation complexity determine margin structures and distributor relationships. End-user type dictates whether products move through two-step distribution or direct-builder programs.
Product Type:
Security performance requirements and code compliance intensity drive specification authority in this category.
- Locks:Electromechanical and mechanical locking systems incorporate cylinder security grades and fire-rated latching mechanisms. Demand concentrates in educational and government facilities across the United States and Germany where forced-entry resistance mandates are tightening. ASSA ABLOY and dormakaba capture specification share through tested multi-point systems.
- Hinges:Ball-bearing and continuous hinge configurations manage door weight loads and fire-door integrity across high-traffic institutional corridors. Heavy-duty stainless steel variants dominate hospital and airport specifications in Scandinavia and Japan where 1 million-cycle endurance testing is standard.
- Fasteners:Structural anchoring hardware for door frames and hardware mounting includes expansion anchors and machine screws.
- Latches:Spring-loaded and deadlatch mechanisms secure residential and light commercial openings.
Volume sits with Locks; growth tilts toward Hinges as fire-rating requirements expand.
Installation Method:
Substrate preservation constraints and labor skill availability shape method selection in renovation versus new construction.
- Surface-Mounted:Exposed hardware attaches directly to door faces without mortise routing or cylinder preparation. This method dominates residential retrofit across aging housing stock in the United States and Germany where substrate preservation limits invasive cutting.
- Mortise:Recessed lock bodies and face-plates integrate into routed door preparations for commercial steel-door applications. Specifications in Japan and France retain mortise dominance for high-security institutional environments.
- Center-Set:Standardized bore spacing accommodates mid-grade residential locksets.
- Recessed:Flush-mounted hardware minimizes projection in corridor and clean-room environments.
Surface-Mounted commands renovation volume; Mortise retains new-build commercial specification authority.
Material:
Corrosion resistance and aesthetic finish durability determine lifecycle cost calculations for coastal and high-humidity deployments.
- Stainless Steel:Austenitic and ferritic grades deliver salt-spray resistance and antimicrobial surface properties. Coastal markets in Australia and the United States are displacing brass specifications due to accelerated zinc-copper alloy degradation.
- Brass:Zinc-copper alloys provide machining precision and traditional finish aesthetics. Interior applications in climate-controlled European commercial buildings sustain demand despite coastal vulnerability.
- Aluminum:Lightweight extrusions serve non-structural hardware and aesthetic trim applications.
- Plastic:Engineered polymers reduce weight and cost in residential light-duty latches and trim.
Stainless Steel is climbing the fastest on coastal corrosion failures; Brass retains interior specification share.
End User:
Procurement scale and technical specification authority determine channel access and pricing architecture.
- Contractors:Commercial general contractors and specialty door-hardware installers manage specification compliance and installation warranty. Large healthcare and education projects in the United States consolidate procurement through negotiated master agreements.
- Builders:Production homebuilders in Texas and Florida bypass distribution through direct supply programs. Volume concentration among the four largest United States builders is unbundling hardware from lumber-yard packages.
- DIY Enthusiasts:Retail consumers purchase replacement hardware through home improvement channels.
- Architects:Design professionals specify performance criteria and aesthetic finishes for institutional projects.
Builders drive residential volume concentration; Contractors retain commercial specification control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta and India's Delhi-Mumbai Industrial Corridor concentrate builder hardware manufacturing and specification-grade distribution. These zones attract multinational assembly operations through tax holidays and duty exemptions on imported stainless steel feedstock. The resulting production clusters serve both domestic retrofit waves and export markets across Southeast Asia and the Middle East.
United States
Production homebuilders in Texas and Florida are consolidating hardware procurement through direct supply agreements that bypass traditional distribution channels. The Department of Energy's weatherization assistance programs are accelerating window replacement cycles in the Northeast and Midwest. Miami-Dade County's hurricane-resistant building codes are driving specification-grade stainless steel hardware demand for impact-rated doors and windows.
Germany
Energy-efficiency retrofit mandates under the federal Building Energy Act are triggering whole-window replacement waves that bundle hardware specification upgrades. The federal government's BAFA subsidy program reimburses homeowners for high-performance door and window systems. Industrial clusters in North Rhine-Westphalia and Bavaria host specification-grade hinge and lock manufacturers serving hospital and airport infrastructure projects.
China
SAMR enforcement of GB standards for mechanical lock durability is tightening domestic-market entry barriers for imported products. The Yangtze River Delta special economic zone hosts electromechanical lock assembly operations serving government and educational facility procurement. Shanghai and Hangzhou urban renewal programs are driving smart-locking system adoption in multi-family residential towers.
India
BIS certification expansion for door closers and panic bars is reshaping import compliance costs for foreign suppliers. The Delhi-Mumbai Industrial Corridor is attracting specification-grade hardware distribution centers serving Mumbai, Bangalore, and Hyderabad commercial real estate expansion. Maharashtra's urban development authority is mandating fire-rated hardware in high-rise residential construction.
Japan
METI building energy standards are accelerating window hardware replacement in aging residential stock from the 1970s and 1980s. The Kanto region's multi-family housing developers are adopting biometric-electromechanical convergence systems for retrofit applications. Osaka's commercial district renewal is driving demand for heavy-duty stainless steel hinges in high-traffic institutional corridors.
Global Builder Hardware Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-grade commercial channels favoring tested brand portfolios while residential retail tolerates OEM sourcing. The market structures around three tiers: multinational electromechanical specialists with hospital and airport specification authority, regional stainless steel fabricators serving coastal corrosion-resistant applications, and volume-oriented suppliers capturing production homebuilder direct programs. Consolidation is accelerating through strategic acquisitions of smart-lock technology platforms and backward integration into semiconductor module sourcing.
Within the multinational electromechanical tier, ASSA ABLOY and dormakaba occupy positions anchored by fire-rated and access-control specification authority. Masco Corporation and Stanley Black & Decker exemplify the residential-scale archetype through builder-direct program consolidation. These named entities represent competitive positioning patterns rather than exhaustive market coverage, with each anchoring distinct channel strategies across commercial specification and production homebuilding segments.
| Leading Market Players |
|---|
| Saltus Window Fashions |
| Masco Corporation |
| ASSA ABLOY |
| Stanley Black & Decker |
| Fortune Brands Innovations |
| Allegion |
| Andersen Corporation |
| Saint-Gobain |
| Dormakaba |
| Others |
Supply Flow & Price Mechanics
Bluetooth Low Energy credentialing migration is compressing hardware cost structures while concentrating module sourcing among Taiwanese and South Korean semiconductor fabricators, creating asymmetric pricing power for suppliers controlling wireless connectivity components.
Pricing Analysis
Premium pricing attaches to short lead-time fulfillment for fire-rated multi-point locking systems, while spot inventory of standard-grade residential hardware trades at compressed margins. Three-tier pricing structure across specification-grade, builder-program, and retail-economy levels separates UL-certified commercial products from unbranded import alternatives. Cost compression in the residential retrofit tier is intensifying because production homebuilders negotiate multi-year direct supply agreements that bypass distributor markups. DIY enthusiasts exhibit highest price sensitivity, whereas healthcare facility procurement committees prioritize antimicrobial finish certification over unit cost.
Supply Chain Analysis
Direct-to-builder channels handle production homebuilder volume in Texas and Florida, while two-step distribution serves commercial specification-grade procurement through specialized door-hardware distributors. Manufacturing concentrates in China, Germany, and the United States, with the Yangtze River Delta and North Rhine-Westphalia hosting electromechanical assembly clusters. Stainless steel feedstock and zinc-copper alloy billets constitute primary raw material dependencies. Single-source vulnerability concentrates in Wi-Fi and Bluetooth module sourcing from Taiwanese fabricators. Distribution runs through lumber-yard bundles for residential renovation and direct specification for institutional new construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where China's SAMR enforcement of GB standards for mechanical lock durability creates a barrier-to-entry moat for certified domestic manufacturers.
For Market Incumbents: To counter brass corrosion degradation in coastal United States and Australian markets, accelerate stainless steel material substitution programs and secure captive supply of austenitic grade feedstock. Backward integration into semiconductor module sourcing mitigates Taiwan concentration risk for smart-lock portfolios. Investment in dual-certification testing infrastructure reduces FCC Part 15 and EU Radio Equipment Directive validation timelines by 10-12 weeks. For New Entrants and Emerging Players: India's BIS compulsory certification expansion for door closers and panic bars opens a window for specification-grade suppliers willing to absorb 18-24 month compliance onboarding cycles. Target Mumbai, Bangalore, and Hyderabad commercial real estate corridors where fire-rated hardware mandates are tightening. Go-to-market through local distribution partnerships with established MEP contractors bypasses import compliance complexity. For Investors and Strategic Acquirers: Re-rating potential sits with electromechanical specialists given biometric-credential convergence in Japanese and South Korean multi-family housing. Long-term viability favors platforms with hospital and airport specification authority anchored by tested fire-rated systems. Monitor smart-lock retrofit penetration rates in 1990s-era United States apartment stock as inflection signal for connected hardware adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Infrastructure Investment | Simultaneous FCC Part 15 and EU Radio Equipment Directive testing reduces product launch timelines for cross-border smart-lock portfolios. |
| Backward Integration into Semiconductor Sourcing | Captive supply of Wi-Fi modules from South Korean fabricators insulates against Taiwan concentration risk in electromechanical lock production. |
| BIS Certification Pre-Positioning | Early compliance investment ahead of India's mandatory door-closer and panic-bar standards captures first-mover advantage in Mumbai commercial corridors. |
| Antimicrobial Finish Specification Development | Copper-alloy and ion-impregnated surface technologies satisfy United States healthcare facility infection control procurement mandates. |
| Builder-Direct Program Consolidation | Multi-year supply agreements with Texas and Florida production homebuilders displace traditional two-step distribution in high-volume residential markets. |
Methodological Framework
Independent corroboration across specification-grade hardware distributors, production homebuilder procurement directors, and electromechanical lock engineering teams underwrites the qualitative findings. Primary interviews with fire-rating test laboratory managers, commercial general contractor estimators, and facility management technology officers combined with secondary validation from UL certification databases, SAMR GB standard filings, and BIS notification records. Bottom-up demand modeling across installation methods, material grades, and end-user channels triangulates against top-down construction spending forecasts.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product type, installation method, material composition, and end-user procurement authority, with regional regulatory cluster as an additional modeling layer. CAGRs derive from fitted trend extrapolation adjusted for retrofit cycle acceleration and smart-locking technology substitution elasticities. Forecast inputs incorporate construction permit data from United States metropolitan statistical areas and energy-efficiency retrofit subsidy uptake rates from German BAFA program disclosures.
The model assumes a particular technology adoption path; alternative pathways for biometric-electromechanical convergence would alter the outlook if fingerprint-credential integration encounters consumer privacy resistance. Forecasts reflect base-case assumptions regarding CE marking expansion scope and BIS compulsory certification timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
UPVC Doors and Windows Market
Building & Construction Materials
Drainage System Market
Building & Construction Materials
Acoustic Panel Market
Building & Construction Materials
TMT Steel Bar Market
Building & Construction Materials
Seal Coat Market
Building & Construction Materials
Ceiling Tiles Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
GCC Concrete Blocks Market
Building & Construction Materials
Calcium Sulphate Board Raised Access Floor Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
China Concrete Superplasticizer Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
Global Hydraulic Door Closer Market