
 Europe Geogrids Market | 2026-2036
Europe Geogrids Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Geogrids Market Analysis
Road construction is pivoting toward soil reinforcement applications across Europe's national highway programs. TENAX SPA dominates Italian infrastructure tenders through its specialized polypropylene geogrid formulations. Huesker Synthetic GmbH anchors German-speaking markets with captive supply of polyester-based solutions for rail embankments. Solmax extends its reach across Nordic markets through welded-installation product lines engineered for cold-climate performance.
Geogrids are planar polymeric structures manufactured from polyester, polypropylene, or glass fiber through extrusion, stretching, and welding processes, designed to interlock with granular fill and distribute loads across weak subgrades. Their primary commercial purpose is to reduce aggregate thickness in unpaved and paved roads while preventing lateral spreading of base materials. Polyester geogrids command margin pools in heavy-load applications due to superior creep resistance under sustained tension. Polypropylene variants compete aggressively in cost-sensitive road construction segments where installation speed outweighs long-term deformation tolerance. Glass fiber geogrids occupy specialized niches in asphalt overlay reinforcement where thermal stability and modulus compatibility with bituminous layers prove critical.
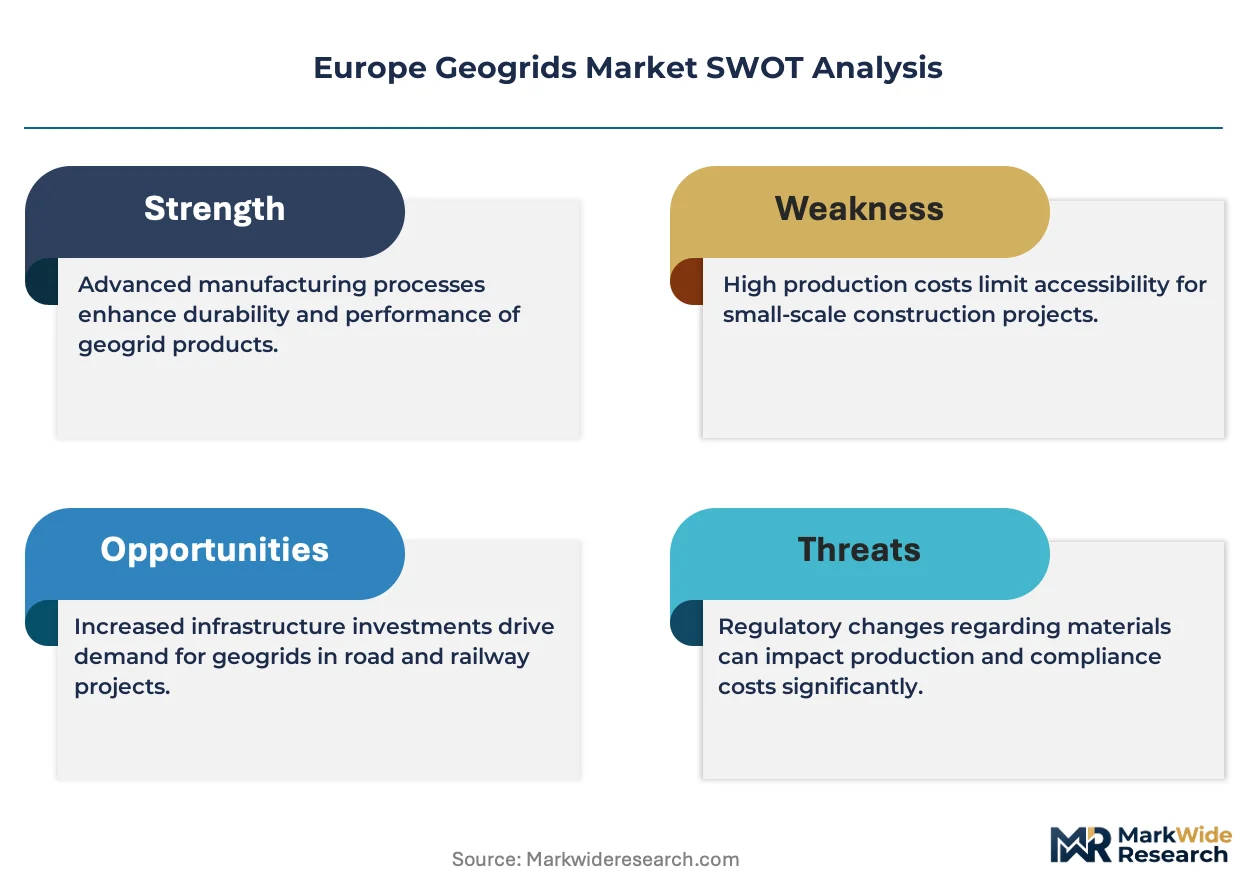
The EU Green Deal and updated CE marking requirements under the Construction Products Regulation shape product standards and market access across member states. ECHA's REACH framework governs chemical composition disclosures for polymer resins, while national transport agencies in Germany, France, and Poland enforce project-specific technical approvals that filter supplier eligibility. Stakeholders must monitor evolving EU taxonomy criteria for sustainable infrastructure financing, as green bond eligibility increasingly hinges on demonstrated carbon reduction in construction material supply chains.
Market Dynamics
EU cohesion fund disbursements for transport corridors are concentrating geogrid procurement authority into fewer national highway agencies, compressing supplier qualification timelines and favoring polymer formulations with pre-certified CE marking documentation.
Growth Catalysts
- EU Green Deal infrastructure taxonomy:Carbon reduction thresholds for construction materials are accelerating specification of engineered geosynthetics over quarried aggregate bases in German and Polish national road programs.
- Rail embankment stabilization:Deutsche Bahn and SNCF Réseau are expanding polyester geogrid deployment across high-speed line upgrades to mitigate differential settlement in soft soil zones.
- Cold-climate welding systems:Nordic contractors are specifying pre-welded geogrid panels that reduce installation labor hours in sub-zero construction windows.
Market Restraints
- Polypropylene resin price volatility:Feedstock fluctuations tied to propylene supply from European crackers are compressing margin pools for standard-grade road construction products.
- Glass fiber supply concentration:E-glass roving production clusters in Germany and Belgium create single-source vulnerability for asphalt reinforcement geogrids.
- ECHA REACH compliance burdens:Polymer additive disclosure requirements are extending product registration timelines by 8-14 months for non-EU resin suppliers.
Strategic Opportunities
- CEE highway corridors:Romania and Bulgaria are opening tender pipelines for EU-funded motorway segments with subgrade reinforcement specifications still in formulation.
- Photovoltaic farm access roads:Utility-scale solar developers in Spain and Italy are specifying biaxial geogrids for unpaved maintenance track construction.
- CSRD supply chain disclosure:The EU Corporate Sustainability Reporting Directive is creating preference for geogrid suppliers with verified recycled polymer content and Scope 3 carbon accounting.
Industry Challenges
- Geotechnical engineer scarcity:Design firms in France and Poland face capacity constraints for subgrade interaction modeling required in complex highway tender submissions.
- CE marking test protocol harmonization:Divergent national annexes under EN 13249 are forcing manufacturers to maintain multiple product certification tracks for cross-border projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Geogrids Market |
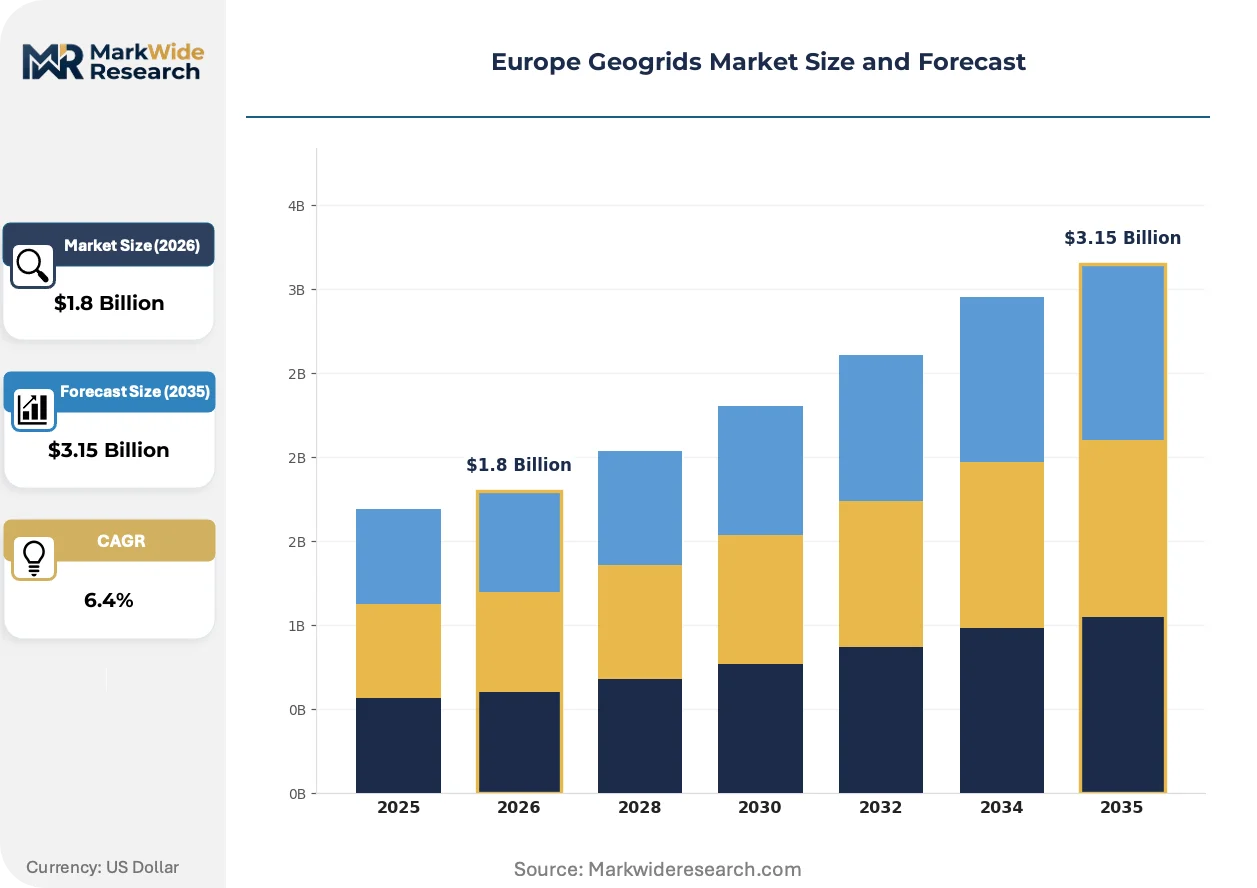
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: polyester, polypropylene, glass fiber, composite Application: soil reinforcement, road construction, retaining walls, drainage systems End User: construction, transportation, agriculture, mining Installation Method: mechanical, adhesive, welding, sewn |
| Companies Covered | Koninklijke Ten Cate, Solmax, TENAX SPA, Tensar International Corporation, Huesker Synthetic GmbH, Naue GmbH & Co. KG, Officine Maccaferri Spa, Sia Pietrucha Sp. Z O.O, TMP Geosynthetics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Geogrids Market Emerging Trajectories
Welded-installation geogrid systems are compressing project timelines across Europe's constrained construction seasons. Material science advances in recycled polymer feedstocks are reshaping supplier qualification criteria. Procurement centralization into national transport agencies is compressing the vendor base.
Multi-axial geogrid architectures are modularizing subgrade reinforcement design for irregular load distributions. French and Italian contractors are adopting these configurations for port container yard expansions and airport apron reconstruction. The technology is modularizing what were previously custom-engineered solutions into standardized product families with reduced lead times.
Updated CE marking requirements under the Construction Products Regulation are tightening mechanical property verification protocols. Manufacturers must now submit creep test data to notified bodies under accelerated aging conditions. Heavy-load polyester geogrids for rail applications face the steepest compliance cost increases as certification cycles extend.
Buyer concentration into centralized procurement frameworks is consolidating specification authority. Germany's Federal Ministry of Transport and Digital Infrastructure now mandates pre-approved geogrid product lists for Autobahn maintenance contracts. This behavioral shift is visible across Central European markets where national agencies are replacing decentralized municipal purchasing with framework agreements spanning 3-5 year horizons.
Europe Geogrids Market Segmentation
Geogrid specification decisions in Europe hinge on load-bearing requirements, subgrade conditions, and installation constraints. Procurement patterns diver sharply between heavy infrastructure agencies and decentralized civil contractors. Understanding segment interlocks reveals where margin pools concentrate and qualification barriers rise.
Product Type:
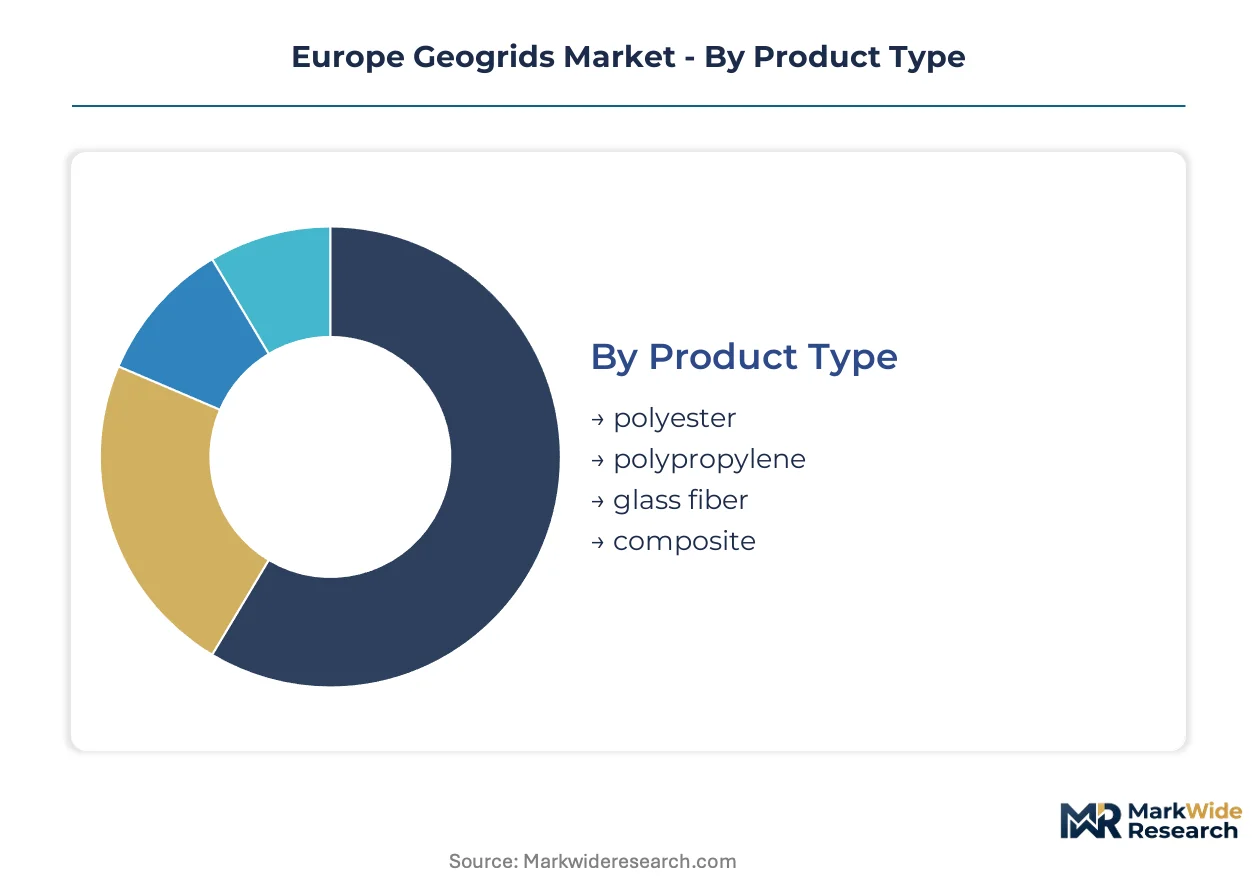
Buyers select polymer chemistry based on creep tolerance needs and project design life. German rail authorities and French highway agencies impose divergent performance thresholds that reshape supplier positioning.
- Polyester:High-tenacity PET yarns deliver superior creep resistance under sustained tensile loads. Deutsche Bahn and SNCF Réseau specify these formulations for high-speed rail embankments across soft soil corridors in northern Germany and the Paris basin. CE marking under EN 13249 requires accelerated creep testing that extends certification cycles for new entrants.
- Polypropylene:Extruded biaxial grids dominate cost-sensitive road construction where installation speed outweighs long-term deformation monitoring. Polish and Romanian national road programs specify these for EU-funded motorway segments with 20-year design horizons. Propylene feedstock volatility from European crackers compresses margin stability for manufacturers without captive resin supply.
- Glass fiber:E-glass rovings provide thermal stability and modulus compatibility with bituminous overlays. Specialized niche in German and Belgian asphalt reinforcement where thermal cycling resistance proves critical.
- Composite:Hybrid architectures combining polymer grids with nonwoven geotextiles address multi-function drainage and filtration. Emerging specification in French port container yard expansions requiring simultaneous reinforcement and separation.
Volume sits with polypropylene; growth tilts toward polyester as rail infrastructure budgets expand.
Application:
Application selection tracks subgrade failure mode and load distribution geometry. Central European highway agencies concentrate procurement authority around standardized reinforcement protocols.
- Soil reinforcement:Biaxial and multi-axial grids interlock with granular fill to distribute concentrated loads across weak subgrades. Demand concentrates in Poland and Romania where EU cohesion funds finance transport corridor upgrades across soft alluvial plains. ECHA REACH compliance for polymer additives extends supplier registration timelines.
- Road construction:Unpaved and paved road base stabilization represents the largest procurement volume by project count. German Autobahn maintenance contracts now mandate pre-approved product lists from the Federal Ministry of Transport. Specification tightening under EU Green Deal carbon thresholds accelerates substitution of quarried aggregate bases.
- Retaining walls:Uniaxial grids reinforce segmental block and wrapped-face structures in urban expansion zones. Italian and Spanish infrastructure programs specify these for hillside road widening projects.
- Drainage systems:Geogrid-geotextile composites prevent clogging in subsurface drainage layers. Nordic markets specify cold-climate welding-compatible configurations for sub-zero installation windows.
Procurement volume clusters in road construction; soil reinforcement climbs fastest as rail embankment specifications mature.
End User:
End-user concentration determines contract scale and qualification intensity. National transport agencies are displacing municipal purchasing with framework agreements spanning multi-year horizons.
- Construction:Civil engineering contractors execute the majority of geogrid installation volume across European infrastructure programs. Design-build contracts in France and Poland require geotechnical engineering capacity that filters vendor eligibility.
- Transportation:Deutsche Bahn, SNCF Réseau, and national highway agencies command the largest individual procurement volumes. Pre-approved product lists and technical approval frameworks compress the supplier base.
- Agriculture:Farm access roads and silage pad construction generate seasonal demand with lower specification intensity. Cost-sensitive segment where polypropylene biaxial grids dominate.
- Mining:Haul road stabilization for extractive operations in Scandinavia and Eastern Europe demands heavy-load polyester formulations. Project-specific durability requirements extend supplier qualification timelines.
Transportation agencies capture procurement volume; construction contractors represent the broadest addressable base.
Installation Method:
Installation technique selection balances labor cost, climate constraints, and quality assurance requirements. Nordic contractors are driving specification shifts that reshape product form factors.
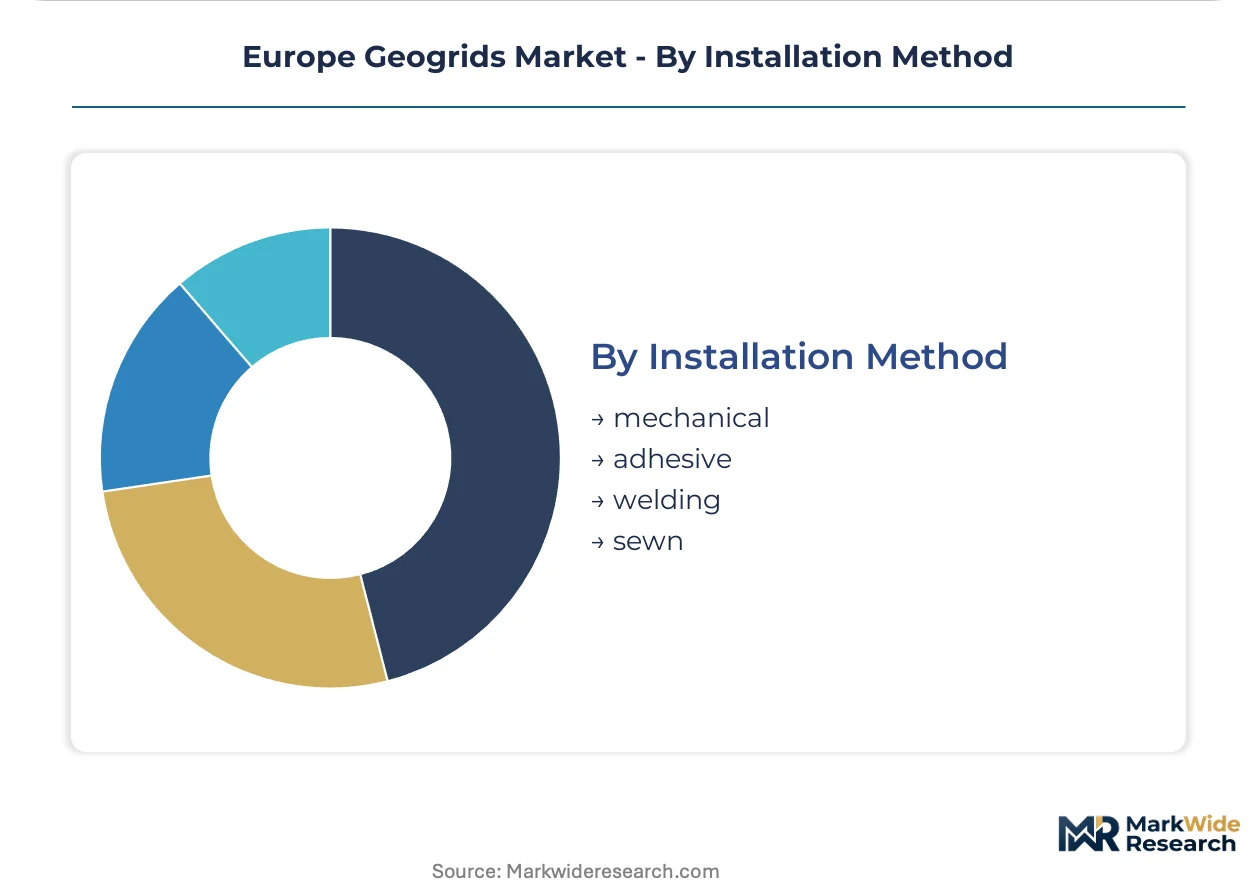
- Mechanical:Staple and stake anchoring dominates standard road construction where soil conditions permit. Lowest equipment requirement supports decentralized contractor adoption across Central Europe.
- Adhesive:Bituminous bonding systems specialize in asphalt overlay applications where thermal compatibility proves critical. Glass fiber grid deployment in German surface course reinforcement relies on these methods.
- Welding:Pre-welded panel systems compress installation labor hours in constrained construction seasons. Solmax and Nordic contractors are specifying these for sub-zero project windows where mechanical fastening proves unreliable. Fastest-expanding method as procurement centralization rewards standardized product families.
- Sewn:Stitching connections for composite geogrid-geotextile configurations in drainage and filtration applications. Specialized niche in French port and airport projects requiring multi-function performance.
Mechanical methods retain volume leadership; welding gains share fastest as cold-climate project specifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU cohesion fund disbursements are concentrating geogrid procurement authority into national highway agencies across Central and Eastern European transport corridors. The EU Green Deal infrastructure taxonomy accelerates specification of polymer-based soil stabilization over traditional aggregate bases. CE marking requirements under the Construction Products Regulation filter supplier eligibility through accelerated creep testing protocols.
Germany
Deutsche Bahn's high-speed rail embankment upgrades drive polyester geogrid demand across soft soil zones in northern Germany. The Federal Ministry of Transport mandates pre-approved product lists for Autobahn maintenance contracts under updated CE marking requirements. Manufacturing clusters in North Rhine-Westphalia supply rail-specific formulations with captive resin supply chains.
France
SNCF Réseau expands polyester geogrid deployment across the Paris basin for differential settlement mitigation. The EU Green Deal carbon thresholds accelerate substitution of quarried aggregates in national road programs. Port container yard expansions in Marseille-Fos and Le Havre specify multi-axial composite configurations for irregular load distributions.
Poland
National road programs specify polypropylene biaxial grids for EU-funded motorway segments across soft alluvial plains. ECHA REACH compliance requirements extend supplier registration timelines for polymer additive disclosures. Warsaw-based design firms face capacity constraints for subgrade interaction modeling in complex highway tenders.
Italy
TENAX SPA dominates infrastructure tenders through specialized polypropylene formulations for hillside road widening projects. The EU Corporate Sustainability Reporting Directive creates preference for suppliers with verified recycled polymer content. Northern Italian contractors adopt welded-installation systems for constrained construction seasons in Alpine regions.
Romania
EU-funded motorway tender pipelines are opening with subgrade reinforcement specifications still in formulation. National transport agencies are consolidating procurement authority away from decentralized municipal purchasing. Bucharest corridor projects concentrate demand for cost-sensitive polypropylene variants with 20-year design horizons.
Europe Geogrids Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with polymer chemistry expertise determining qualification for rail versus road applications. The supplier base compresses around CE marking certification holders as national agencies mandate pre-approved product lists. Three archetypes dominate: resin-integrated formulators, installation-system innovators, and composite technology specialists. Competitive moves center on backward integration into polymer supply and geographic expansion through cold-climate welding system distribution.
Among Italy-based specialists, TENAX SPA and Officine Maccaferri Spa occupy positions within the road construction tier, while Solmax anchors Nordic market penetration through welded-panel configurations. Huesker Synthetic GmbH represents the German-speaking rail embankment segment with polyester-based supply chains. These three exemplify how geographic origin and product-form specialization determine framework agreement eligibility across centralized procurement systems.
| Leading Market Players |
|---|
| Koninklijke Ten Cate |
| Solmax |
| TENAX SPA |
| Tensar International Corporation |
| Huesker Synthetic GmbH |
| Naue GmbH & Co. KG |
| Officine Maccaferri Spa |
| Sia Pietrucha Sp. Z O.O |
| TMP Geosynthetics |
| Others |
Supply Flow & Price Mechanics
Captive resin supply chains anchor pricing power for polyester geogrid manufacturers serving Deutsche Bahn and SNCF Réseau, while polypropylene-dependent road construction suppliers absorb feedstock volatility from European crackers without equivalent margin protection.
Pricing Analysis
Lead-time-driven pricing separates urgent project premiums from standard contract rates across Central European highway tenders. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking certification grade and volume commitment scale. Cost compression in standard-grade polypropylene biaxial grids is intensifying because propylene feedstock volatility erodes manufacturer margins. Municipal contractors in Poland and Romania exhibit highest price sensitivity, while rail infrastructure agencies in Germany and France prioritize creep resistance over unit cost.
Supply Chain Analysis
Polymer resin supply rests on petrochemical production clusters in Germany, Belgium, and the Netherlands. High-tenacity polyester yarns draw from captive spinning operations near rail corridor demand centers, while polypropylene pellets feed from crackers with exposure to naphtha and propane pricing. Single-source vulnerability concentrates in E-glass roving production for asphalt reinforcement applications. Distribution runs through national transport agency framework agreements that compress vendor eligibility timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU cohesion fund procurement centralization is forcing consolidation as pre-approved product list requirements filter out suppliers lacking CE marking documentation and captive resin supply chains.
For Market Incumbents: Cement framework agreement eligibility by accelerating backward integration into polymer resin supply and expanding welding-system distribution partnerships across Nordic markets. ECHA REACH compliance timelines for non-EU resin suppliers threaten substitute sourcing channels. Investment in accelerated creep testing capacity under EN 13249 protocols secures rail embankment qualification.
For New Entrants and Emerging Players: Design-build contractors in Poland and Romania represent the most penetrable channel partner type for qualification-light entry. Photovoltaic farm access roads in Spain and Italy offer specification windows still in formulation. Partner with cold-climate installation specialists to bypass mechanical anchoring expertise barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap resin-integrated formulators with CE marking certification depth and rail agency pre-approval status. Long-term viability hinges on positioning within EU taxonomy-aligned infrastructure financing flows. Watch CSRD supply chain disclosure adoption rates as the inflection signal for recycled polymer content preference.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Supply | Captive PET and PP supply insulates margin pools from European cracker feedstock volatility. |
| CE Marking Accelerated Creep Testing Investment | Extended certification cycles under EN 13249 filter competitor eligibility for Deutsche Bahn tenders. |
| Welded-Installation System Distribution Expansion | Nordic contractor partnerships compress project timelines in sub-zero construction windows. |
| Recycled Polymer Feedstock Qualification | CSRD-aligned Scope 3 carbon accounting meets EU Green Deal infrastructure taxonomy thresholds. |
| Multi-Axial Composite Product Line Development | Modular configurations address irregular load distributions in French port container yard expansions. |
Methodological Framework
Multi-period observation of EU cohesion fund disbursement patterns, CE marking certification timelines, and propylene feedstock pricing anchored the trend analysis, supplemented by interviews with geotechnical engineering directors at design firms, procurement leads at national transport agencies, plant managers at resin-integrated manufacturers, and technical sales heads at installation-system distributors. Secondary validation drew from ECHA REACH registration databases, EN 13249 test protocol documentation, EU Green Deal infrastructure taxonomy guidance, and national highway agency tender records. Bottom-up project pipeline assessment and top-down polymer consumption estimates were triangulated against framework agreement award data.
Input-output matrices modeled geogrid consumption across product chemistry, application load-bearing requirement, end-user procurement centralization level, and installation method climate constraint. Segmentation dimensions included polyester versus polypropylene versus glass fiber formulation, soil reinforcement versus road construction versus rail embankment application, and mechanical versus welded versus adhesive installation. CAGRs were derived from elasticity-adjusted demand projections tied to EU-funded transport corridor investment schedules and subgrade performance specification tightening trajectories.
Caveats apply where ECHA REACH polymer additive disclosure rule changes, EU taxonomy carbon threshold revisions, or propylene supply disruptions from European cracker maintenance cycles could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Residential Energy Efficient Windows Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
Modular Commercial Building System Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
Global Metal-Faced Insulated Panels Market
Building & Construction Materials
India UPVC Doors and Windows Market
Building & Construction Materials
PVC Window Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
Building Insulation Materials Market
Building & Construction Materials
North America Metallic Barn Doors Market
Building & Construction Materials
Europe Industrial Flooring Market
Building & Construction Materials
North America Balustrade Market
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
North America Prefab Wood Building Market