
 Acoustic Panel Market | 2026-2036
Acoustic Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Panel Market Analysis
Acoustic engineer shortages across North American and European construction markets is redrawing competitive boundaries for panel suppliers. Rockwool International A/S leverages its mineral wool expertise to dominate high-performance fire-rated installations. Knauf Insulation GmbH anchors Central European supply chains through captive gypsum and glass wool production. Saint-Gobain S.A. competes on multi-material breadth, spanning gypsum, mineral fiber, and emerging bio-based substrates.
An acoustic panel is a purpose-built sound-absorbing or diffusing element, typically constructed from mineral wool, fiberglass, foam, or recycled PET cores with facing layers of fabric, perforated metal, or wood veneer, engineered to achieve Noise Reduction Coefficient ratings between 0.70 and 1.05. These panels manage reverberation time and speech intelligibility in enclosed volumes. Ceiling panels command the largest installed base in commercial retrofits, while baffles are gaining share in exposed-structure spaces where wall mounting proves impractical. Fabric-faced systems lead on aesthetic customization and premium pricing, though PET-felt variants are displacing traditional fiberglass in sustainability-sensitive segments.
OSHA workplace noise exposure limits and the EU Green Deal's embodied carbon tracking are reshaping material specifications and supplier qualification requirements. ASTM E84 surface burning characteristics and ISO 11654 sound absorption classifications function as de facto market access filters in developed economies. Buyers must weigh certified fire performance against emerging circularity mandates as procurement criteria harden.
Market Dynamics
Workplace acoustics regulations are compressing specification cycles as OSHA noise exposure limits and EU embodied carbon tracking force rapid material substitutions toward recycled-content cores and certified fire-rated assemblies.
Growth Catalysts
- EU Green Deal embodied carbon mandates:Building product procurement in Germany and France now requires Environmental Product Declarations, pulling demand toward PET-felt and bio-based substrates with verified recycled content.
- Open-plan office proliferation:Corporate fit-outs across North America are absorbing fabric-wrapped ceiling panels and baffle systems to manage speech intelligibility in exposed-structure environments.
- Mineral wool fire performance:High-rise commercial construction in urban centers specifies non-combustible cores meeting ASTM E84 Class A surface burning characteristics for code compliance.
Market Restraints
- Glass wool raw material volatility:Energy-intensive mineral fiber production faces input cost pressure from natural gas and boron supply fluctuations concentrated in Turkish and South American extraction zones.
- Eastern European manufacturing concentration:Panel fabrication clusters in Poland and Romania create geographic supply risk for Western European buyers dependent on just-in-time logistics.
- Installation labor scarcity:Certified acoustic contractor shortages in North American construction markets extend project timelines and elevate on-site costs.
Strategic Opportunities
- Healthcare acoustics retrofit:Aging hospital infrastructure in the United States presents untapped demand for ceiling panel upgrades addressing HIPAA speech privacy requirements in patient zones.
- Digital specification platforms:BIM-integrated product libraries are compressing the architect-to-manufacturer channel, enabling direct material selection with embedded acoustic performance data.
- India commercial construction acceleration:BIS building codes adoption in Mumbai and Bangalore commercial towers is creating first-mover positioning for fire-rated mineral wool systems.
Industry Challenges
- Multi-certification burden:Suppliers must simultaneously maintain ISO 11654 sound absorption ratings, ASTM E84 fire classifications, and emerging circularity credentials, extending product development cycles.
- Legacy ceiling grid incompatibility:New panel dimensions and suspension systems require field adaptation in existing commercial buildings, elevating retrofit project complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Panel Market |
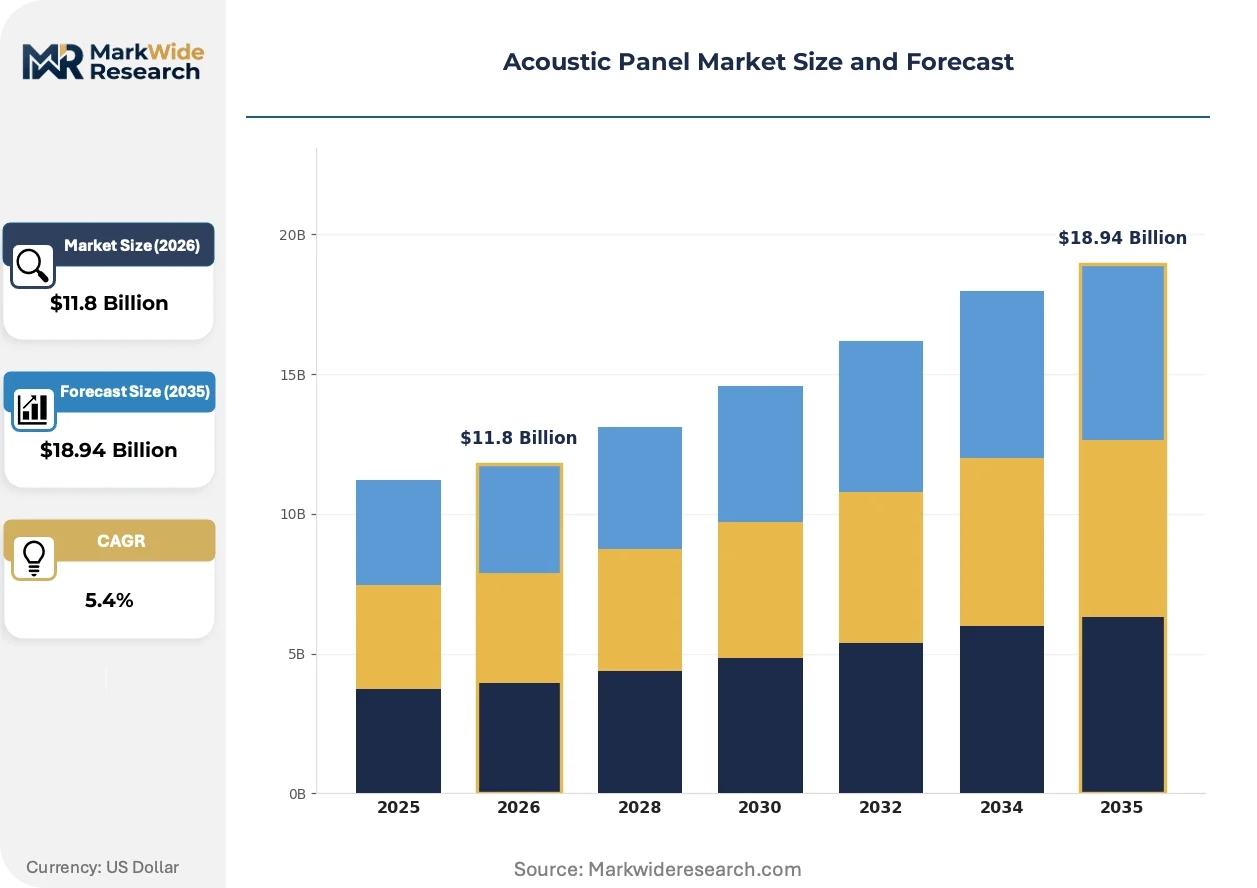
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Panels, Ceiling Panels, Baffles, Clouds Material: Foam, Fabric, Wood, Metal Application: Commercial Spaces, Residential Spaces, Studios, Auditoriums Installation Type: Fixed, Movable, Suspended, Integrated |
| Companies Covered | Rockwool International A/S, Knauf Insulation GmbH, BASF SE, BuzziSpace, Armstrong World Industries, Saint-Gobain S.A., USG Corporation, Beijing New Building Material (Group) Co., Ltd., Kingspan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Panel Market Emerging Trajectories
Material science convergence and digital specification tools are redrawing how acoustic performance is packaged, certified, and procured across commercial construction verticals.
Bio-based substrate development is fragmenting the traditional mineral wool and fiberglass duopoly. Mycelium and hemp-core panels achieve comparable Noise Reduction Coefficient ratings while satisfying EU Green Deal carbon tracking requirements. Specifiers in Nordic markets are piloting these materials in educational and cultural buildings, compressing the premium pricing gap against conventional systems.
OSHA workplace noise enforcement is tightening material qualification protocols. The agency's updated enforcement guidance on open-plan office exposure is compelling facility managers to document reverberation control measures. Corporate real estate teams in the United States are responding by embedding acoustic performance clauses in landlord workletter agreements, shifting liability upstream.
Architects are unbundling aesthetic customization from manufacturer catalogs. Direct-to-fabricator digital printing on PET-felt and fabric facings enables project-specific visual integration without premium branded systems. This pattern is most visible in North American tech sector fit-outs, where workplace design teams specify bespoke panel geometries through parametric design workflows rather than standard product lines.
Acoustic Panel Market Segmentation
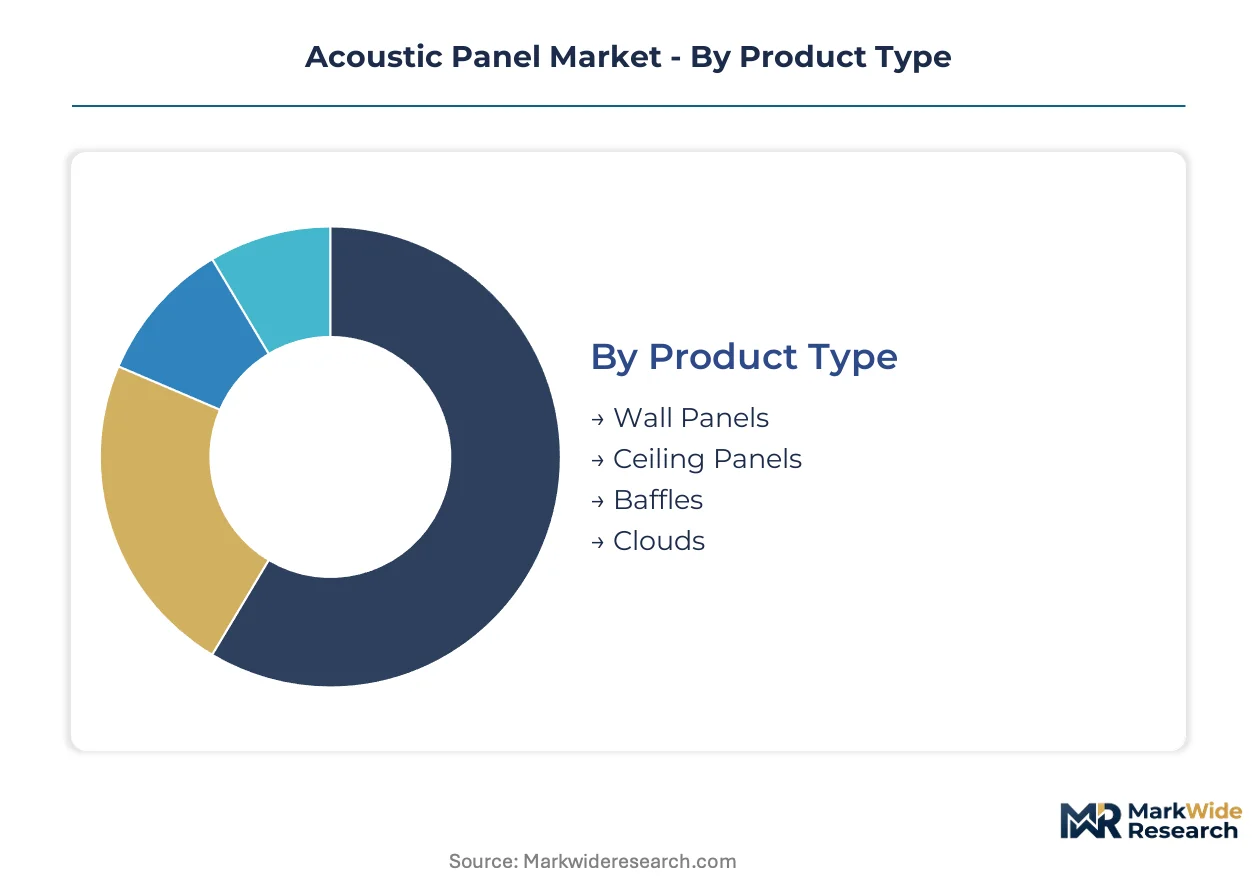
Acoustic panel segmentation reflects divergent specification pathways across construction channels. Architects route aesthetic-sensitive products through design-build contracts, while contractors push standardized systems through bid-build procurement. Material and installation choices cluster by building type and regulatory jurisdiction.
Product Type:
Channel mix varies sharply by mounting geometry. Ceiling panels and baffles flow through commercial drywall contractors, while wall panels and clouds concentrate in specialized acoustic subcontractor networks.
- Ceiling Panels:Modular tiles sized to standard T-bar grids dominate retrofit volumes. Germany absorbs substantial imports from Polish manufacturing clusters to satisfy stringent DIN 18041 building acoustics codes in office towers.
- Baffles:Suspended linear elements in exposed-structure spaces achieve comparable absorption without permanent wall penetration. Tech sector fit-outs in Austin and Seattle specify custom geometries through direct-fabricator digital workflows.
- Wall Panels:Vertical-mounted systems address speech privacy in healthcare and legal environments. HIPAA compliance drives specification in US hospital patient zones.
- Clouds:Horizontal floating assemblies manage reverberation in atria and circulation zones. Museums and cultural buildings in Nordic markets pilot bio-faced variants.
Ceiling panels dominate installed base. Baffles are where expansion concentrates.
Material:
Cost tiers separate specification pathways. Premium fabric and wood systems command design-led projects, while foam and metal concentrate in budget-driven volume applications.
- Fabric:Wrapped fiberglass or mineral wool cores with customizable facing enable aesthetic integration. Corporate headquarters in Chicago and London specify through interior designer channels at premium pricing.
- Wood:Perforated veneer or solid slat systems serve performance venues and executive environments. Acoustic performance depends on precise perforation geometry and cavity depth.
- Foam:Molded polyurethane or melamine systems target budget-conscious studio and educational markets. Fire rating limitations restrict deployment in commercial high-rises.
- Metal:Perforated aluminum or steel with acoustic backing withstands industrial and transportation environments. ASTM E84 Class A ratings anchor specification in US code-compliant construction.
Fabric leads specification frequency. Wood commands highest margin expansion.
Application:
Customer type determines procurement modality. Commercial spaces route through landlord workletters and tenant improvement allowances, while residential and studio applications favor direct consumer or small-contractor purchase.
- Commercial Spaces:Open-plan offices, co-working environments, and hospitality venues drive bulk procurement. OSHA workplace noise enforcement compels reverberation control documentation in US corporate real estate.
- Auditoriums:Performance and assembly venues demand precision-tuned systems addressing speech intelligibility metrics. Consultants specify through competitive bid processes with extended qualification requirements.
- Studios:Recording and broadcast environments prioritize broadband absorption and diffusion control. Proprietary room-tuning software influences product selection.
- Residential Spaces:Home theaters and multi-family common areas represent emerging demand. Distribution concentrates through online retailers and specialty acoustic dealers.
Commercial spaces anchor volume demand. Residential spaces are climbing the fastest.
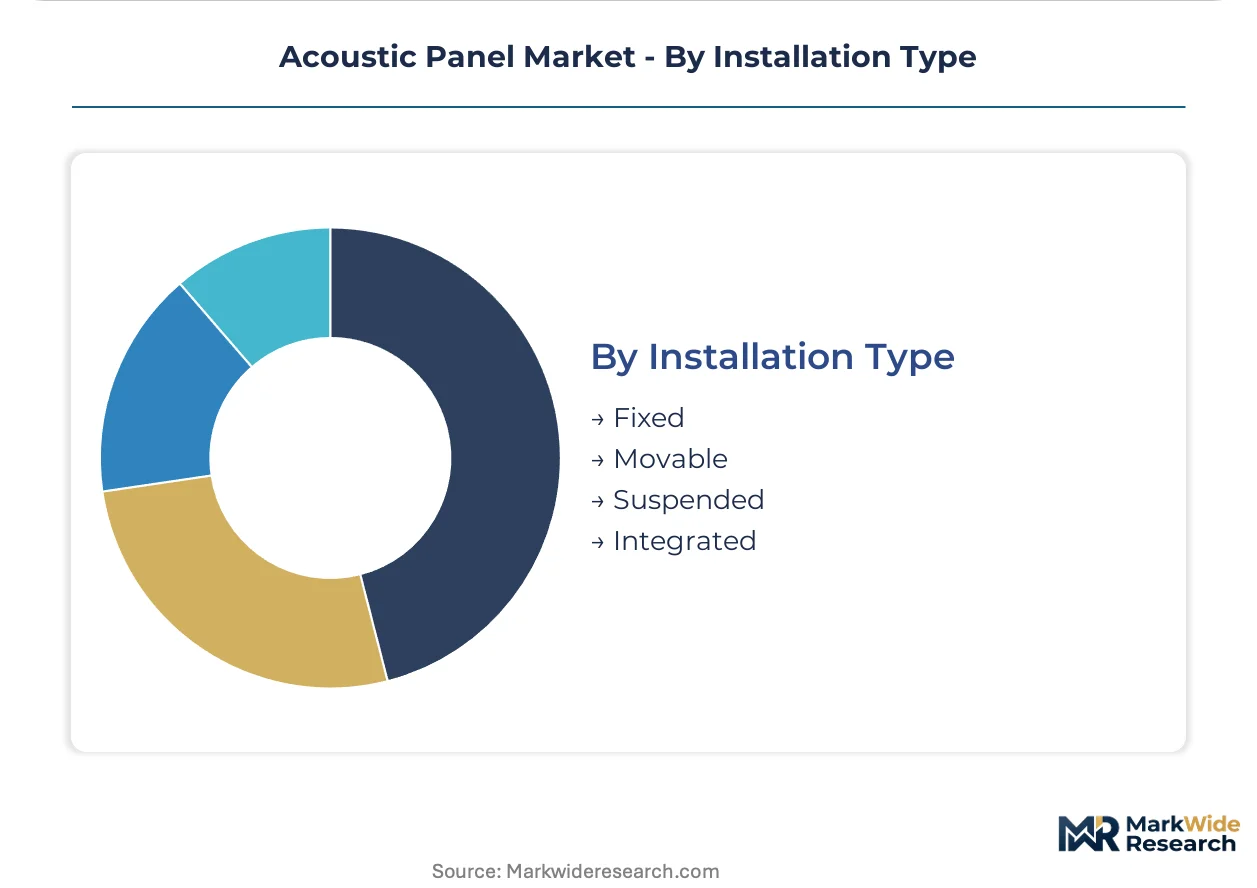
Installation Type:
Supply concentration in Eastern European fabrication clusters favors fixed and suspended systems with standardized hardware. Movable and integrated systems require localized installation labor, creating geographic fragmentation.
- Fixed:Permanent wall or ceiling mounting dominates code-compliant commercial construction. German and French procurement increasingly requires Environmental Product Declaration documentation under EU Green Deal mandates.
- Suspended:Cable or rod-hung systems enable exposed-structure aesthetics without permanent modification. Baffles and clouds concentrate in this category.
- Movable:Freestanding partitions and modular screens serve flexible workspace configurations. Corporate real estate teams in North American tech hubs specify for reconfigurable floor plates.
- Integrated:Built-in millwork or architectural finish systems demand coordination with general contractors. Premium residential and cultural buildings drive specification.
Fixed installation dominates current stock. Suspended systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany absorbs PET-felt and mineral wool systems at volumes unmatched elsewhere, driven by DIN 18041 building acoustics enforcement and dense commercial construction. The United States channels demand toward fabric-wrapped ceiling panels under OSHA workplace noise exposure protocols. China scales manufacturing capacity for standardized systems serving domestic fit-out markets.
United States
Corporate headquarters and tech sector campuses in Austin, Seattle, and Chicago drive specification of fabric-faced baffles and ceiling panels. OSHA's updated enforcement guidance on open-plan office noise exposure compels facility managers to document reverberation control measures. Manufacturing and distribution clusters concentrate in the Midwest and Southeast, supplying national retrofit volumes.
Germany
Stringent DIN 18041 building acoustics codes and commercial construction density pull imports from Polish and Romanian fabrication clusters. The EU Green Deal's embodied carbon tracking mandates Environmental Product Declarations for public procurement, favoring recycled-content PET-felt systems. Berlin and Frankfurt office towers anchor Western European demand concentration.
China
Accelerating commercial construction in Shanghai and Shenzhen generates volume demand for standardized ceiling panel systems. National building energy efficiency codes and GB standards for indoor environmental quality shape material specifications. Domestic manufacturing clusters in the Yangtze River Delta serve fit-out contractors across tier-one cities.
India
BIS building codes adoption in Mumbai and Bangalore commercial towers creates positioning opportunities for fire-rated mineral wool systems. The central government's PLI scheme for construction materials supports domestic manufacturing scale-up. Western and Southern metropolitan construction markets absorb initial volumes of code-compliant acoustic assemblies.
United Kingdom
London commercial retrofits and co-working space proliferation sustain demand for suspended baffle systems in exposed-structure environments. Building Regulations Part E acoustic performance standards govern material selection in new construction. Midlands-based distribution networks channel Eastern European imports to national fit-out contractors.
Acoustic Panel Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Mineral wool and glass wool producers leverage captive raw material supply to anchor high-performance fire-rated segments. Design-led fabricators compete on aesthetic customization and rapid-turn digital specification workflows. Competitive moves concentrate on portfolio diversification into bio-based substrates and strategic partnerships with BIM platform providers.
Among European-anchored material suppliers, Rockwool International A/S and Knauf Insulation GmbH exemplify the integrated archetype through mineral fiber expertise and captive production networks. Saint-Gobain S.A. occupies a multi-material position spanning gypsum, mineral fiber, and emerging substrate categories. Beijing New Building Material (Group) Co., Ltd. represents scale-driven Asian manufacturing capacity serving domestic and export markets.
| Leading Market Players |
|---|
| Rockwool International A/S |
| Knauf Insulation GmbH |
| BASF SE |
| BuzziSpace |
| Armstrong World Industries |
| Saint-Gobain S.A. |
| USG Corporation |
| Beijing New Building Material (Group) Co., Ltd. |
| Kingspan Group |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Polish and Romanian fabrication clusters shapes both supply concentration and price floors for Western European buyers. Mineral wool producers leverage captive raw material supply to maintain cost advantages against PET-felt entrants, while energy-intensive glass wool operations face input cost volatility that compresses margins across mid-tier suppliers.
Pricing Analysis
Long-term offtake agreements with major commercial fit-out contractors anchor pricing stability for volume mineral wool systems, while project-based procurement dominates aesthetic-sensitive fabric and wood installations. Price differentiation separates ASTM E84 Class A certified assemblies from standard-grade alternatives, with brand premiums concentrated in design-led corporate headquarters. Cost compression in fiberglass cores is intensifying because natural gas and boron supply fluctuations from Turkish extraction zones feed into energy-intensive production. Budget-conscious educational and studio buyers exhibit highest price sensitivity, whereas healthcare and high-rise commercial segments prioritize fire performance over unit cost.
Supply Chain Analysis
Poland and Romania anchor panel fabrication capacity serving Western European retrofit demand, while China scales standardized ceiling systems for domestic fit-out markets. Raw material flows draw from boron deposits in Turkey, recycled PET feedstock streams in Germany, and glass wool precursor supply from captive mineral fiber operations. Single-source vulnerability concentrates in Eastern European manufacturing clusters dependent on just-in-time logistics to German and French construction sites. Distribution runs through commercial drywall contractors for ceiling panels and specialized acoustic subcontractor networks for wall-mounted and custom geometries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across specification pathways creates niche opportunities as digital procurement tools compress traditional architect-to-manufacturer channels. BIM-integrated product libraries enable direct material selection, fragmenting volume concentration among integrated leaders.
For Market Incumbents: Shield core mineral wool positions by deepening captive supply of boron and glass wool precursors against PET-felt substitution pressure. Accelerate certification maintenance across ISO 11654, ASTM E84, and emerging EU Green Deal circularity credentials to extend product development lead times that disadvantage smaller competitors. Channel control through exclusive specification relationships with major commercial real estate teams anchors volume retention.
For New Entrants and Emerging Players: Lead with bio-based substrate development in Nordic educational and cultural building pilots where EU embodied carbon tracking creates first-mover positioning. Target direct-to-fabricator digital printing workflows for North American tech sector fit-outs, bypassing premium branded system markups through parametric design integration. White-space concentration in healthcare acoustics retrofit for HIPAA-compliant patient zones offers penetrable entry with specialized installation partnerships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors design-led fabricators with rapid-turn digital specification capabilities over scale-driven commodity producers. Acquisition target archetypes include PET-felt specialists with verified recycled-content supply chains and BIM platform integration partnerships. The signal to watch is OSHA enforcement guidance expansion beyond open-plan offices into additional commercial verticals, which would accelerate material substitution timelines and reward positioned substrate innovators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled PET Supply | Secures feedstock for EU Green Deal-compliant production at Romanian fabrication clusters. |
| BIM Platform Partnership | Compresses architect-to-manufacturer channel through embedded acoustic performance data libraries. |
| Healthcare Acoustics Certification Investment | Unlocks HIPAA-compliant patient zone retrofit demand in aging US hospital infrastructure. |
| Bio-Based Substrate Scale-Up | Captures Nordic educational and cultural building pilots with mycelium and hemp-core alternatives. |
| Long-Term Supply Agreement | Locks in volume commitments from corporate real estate teams under OSHA documentation requirements. |
Methodological Framework
A spread of perspectives from acoustic engineers, commercial drywall contractors, facilities managers at corporate headquarters, and procurement leads at hospital systems converged on the working assumptions. Primary interviews with specification consultants and specialized acoustic subcontractor networks combined with secondary validation from ASTM E84 fire classification databases, DIN 18041 building acoustics code filings, EU Environmental Product Declaration registries, and commercial construction permit data. Bottom-up project pipeline analysis and top-down material flow modeling triangulated volume estimates.
Segmentation dimensions modeled include product type, material substrate, installation geometry, application vertical, and regional regulatory cluster across the analysis window. CAGRs derived from installed base growth in commercial retrofits, new construction absorption rates, and material substitution elasticity coefficients. Industry-specific forecast inputs incorporated OSHA enforcement guidance trajectory and EU Green Deal embodied carbon mandate implementation pacing.
The analysis sits within stated boundaries; outcomes outside sustained commercial construction activity in Germany and the United States or accelerated PET-felt substitution rates would require recalibration. Forecasts reflect assumptions on regulatory enforcement timing and raw material supply stability. Recalibration cycles align with material shifts in OSHA workplace noise protocols and EU circularity credential adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Awning Market
Building & Construction Materials
Concrete Floating Floors System Market
Building & Construction Materials
Japan Concrete Conditioner Market
Building & Construction Materials
US Parking Deck Coatings Market
Building & Construction Materials
Germany Construction Chemicals Market
Building & Construction Materials
Porcelain Tiles Market
Building & Construction Materials
Calcium Sulphate Board Raised Access Floor Market
Building & Construction Materials
Floor Screeds Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
Construction Elastomers Market
Building & Construction Materials
Concrete Formwork System Market
Building & Construction Materials
Pervious Concrete Market
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
Sawn Timber Market
Building & Construction Materials
North America Insulated Concrete Form (ICF) Market