
 Door and Window Hardware Market | 2026-2036
Door and Window Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Door and Window Hardware Market Analysis
Specialty distributor networks serving mid-size contractors is narrowing as direct-to-fabricator digital platforms capture specification-driven volume. ASSA ABLOY leverages its electronic access control portfolio to anchor premium positioning across commercial retrofit channels. Hafele competes through deep kitchen and furniture hardware expertise that extends into architectural door systems for mixed-use developments. Dorma (dormakaba) specializes in automatic door and access solutions, dominating hospital and airport infrastructure segments where code compliance demands integrated hardware-software bundles.
Door and window hardware encompasses mechanical and electromechanical components—typically fabricated from extruded aluminum, stamped steel, or cast brass with zinc-alloy coatings—that enable opening, closing, securing, and sealing of fenestration assemblies in buildings and vehicles. These components must meet specified load ratings for cycle durability, corrosion resistance per ASTM B117 or EN 1670, and fire resistance ratings where egress codes apply. Steel and aluminum materials lead volume production due to cost scalability and recyclability, though brass retains margin concentration in heritage restoration and luxury residential applications where patina aesthetics command premium positioning. The retrofit installation segment is accelerating fastest as building energy audits trigger hardware replacement ahead of full envelope renovation, while new construction remains cyclically tied to housing starts and commercial lending conditions.
Building codes enforced by the International Code Council in the United States, the EU Construction Products Regulation with CE marking requirements, and China's GB standards administered by SAMR collectively mandate fire safety, accessibility, and thermal performance thresholds that determine product market access. EPA lead-safe renovation rules and REACH substance restrictions in Europe further constrain material formulations and surface treatments, pushing manufacturers toward chrome-free plating and low-VOC coating systems. Stakeholders must monitor evolving carbon disclosure obligations under CSRD and similar frameworks, as embodied carbon reporting begins to influence specification decisions for hardware in certified green buildings.
Market Dynamics
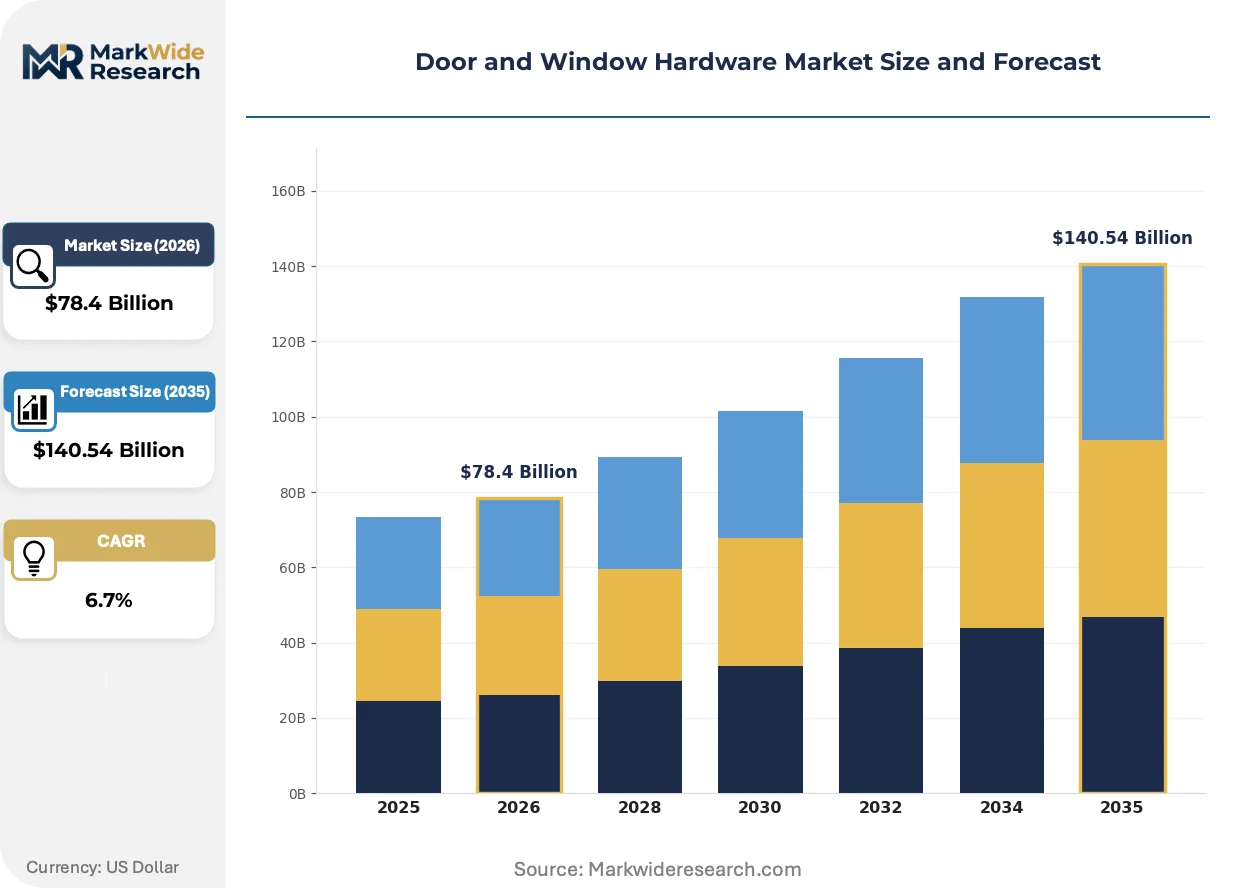
Retrofit-driven demand cycles are compressing replacement timelines for fenestration hardware as energy audits trigger component-level upgrades ahead of full building envelope renovations, while digital specification platforms displace traditional distributor networks serving mid-size fabricators.
Growth Catalysts
- EU Green Deal thermal mandates:Stringent energy efficiency requirements under the EU Construction Products Regulation are accelerating specification of thermally broken frames and multi-point locking mechanisms across Western European residential retrofit programs.
- Multi-point locking technology:Advanced locking systems delivering superior air-tightness and security ratings are capturing specification share in green building certification projects across Germany and California.
- Urban renewal concentration:Large-scale building renovation programs in China are driving premium hardware procurement for high-rise residential and mixed-use developments requiring fire-rated egress solutions.
Market Restraints
- Aluminum and zinc alloy input volatility:Price swings in extruded aluminum and die-cast zinc alloys compress margin stability for stamped steel and cast brass component manufacturers.
- REACH substance restrictions:ECHA limitations on hexavalent chromium plating and specific coating chemistries force costly formulation transitions for corrosion-resistant surface treatments.
- Electromechanical substitution pressure:Electronic access control systems threaten mechanical hardware volume in commercial retrofit channels where ASSA ABLOY and dormakaba bundle integrated hardware-software solutions.
Strategic Opportunities
- CSRD carbon disclosure tailwind:Corporate Sustainability Reporting Directive requirements are elevating embodied carbon transparency as a specification criterion for hardware in certified green buildings across the European Union.
- Heritage restoration premium segment:Patina-grade brass hardware commands margin concentration in conservation-area renovations across the United Kingdom and historic districts of Boston and Charleston.
- Direct-to-fabricator platforms:Digital specification and procurement channels are capturing volume from traditional specialty distributors serving mid-size window and door manufacturers.
Industry Challenges
- Chrome-free plating certification timelines:Transitioning corrosion-resistant surface treatments to trivalent chromium and alternative chemistries requires extended ASTM B117 and EN 1670 validation cycles that delay product launches.
- Fire-rated hardware-software integration complexity:Combining mechanical egress components with electronic access control demands coordination across disparate engineering disciplines and code compliance frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Door and Window Hardware Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $140.54 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Locks, Hinges, Handles, Bolts Material: Steel, Aluminum, Brass, Plastic Installation Type: New Construction, Retrofit, Commercial, Residential End User: Contractors, Architects, Homeowners, Retailers |
| Companies Covered | Dorma (dormakaba), Emtek, ASSA ABLOY, D&D Hardware, Baldwin, Schüco, Hafele, C.R. Laurence, Allegion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Door and Window Hardware Market Emerging Trajectories
Electromechanical convergence is restructuring competitive boundaries as mechanical hardware manufacturers face pressure to integrate sensor networks and access control software, while sustainability reporting obligations reshape material selection and supplier qualification protocols.
Thermally broken aluminum framing systems are collapsing the performance gap between traditional aluminum and uPVC fenestration solutions. Building envelope consultants in Germany and California are specifying these systems for retrofit projects requiring enhanced U-values without aesthetic compromise. The technology is collapsing price premiums that previously separated high-performance from standard-grade residential window hardware.
REACH substance restrictions and the EU Green Deal are forcing chrome-free plating adoption across European supply chains. Manufacturers serving the German market are reformulating zinc-alloy coatings to eliminate hexavalent chromium while maintaining EN 1670 corrosion resistance ratings. Italian and Spanish hardware producers are investing in trivalent chromium and zirconium-based pretreatment lines to retain CE marking eligibility.
Specification behavior is fragmenting as digital platforms enable fabricators to bypass traditional distributor networks. Mid-size window manufacturers in the United States are sourcing hardware directly through online configurators that automate load rating and fire code compliance verification. This channel shift is most visible in the Southeast and Southwest regions where contractor consolidation has reduced the viability of legacy specialty distributor relationships.
Door and Window Hardware Market Segmentation
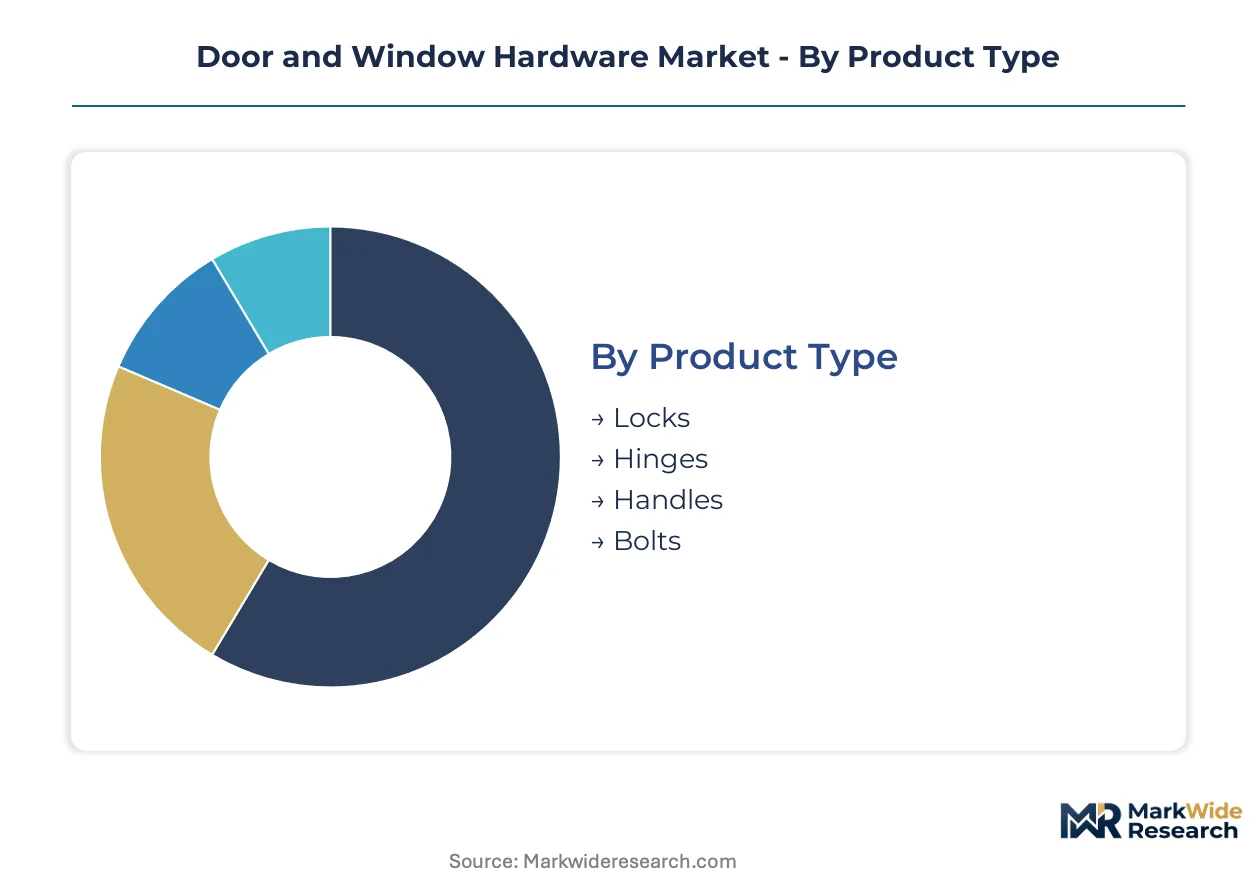
Hardware specification diverges sharply across building lifecycle stages and procurement channels. Material selection and installation method determine compliance pathways, pricing architecture, and distributor relationships for component suppliers.
Product Type:
Cost tier stratification separates specification-grade hardware from commodity alternatives in commercial and residential channels.
- Locks:Multi-point locking systems with thermal break compatibility command premium positioning in German and California retrofit programs where energy audits mandate air-tightness upgrades. Electromechanical convergence pressures mechanical lock volumes as ASSA ABLOY and dormakaba bundle integrated access control solutions in airport and hospital infrastructure.
- Hinges:Concealed bearing hinges rated for fire egress cycles dominate commercial specification in high-rise residential towers across China's urban renewal zones. Load rating certification per EN 1935 separates certified architectural grade from residential commodity alternatives.
- Handles:Lever handles meeting ADA and EN 1906 accessibility standards capture specification in public building retrofits.
- Bolts:Surface-mounted and flush bolts serve secondary security applications in heritage restoration projects.
Locks command the established base. The steepest expansion runs through hinges as fire-rated multi-story construction accelerates.
Material:
Application environment dictates corrosion resistance requirements, thermal performance, and aesthetic positioning across residential and commercial building types.
- Steel:Stamped and extruded steel components dominate volume production for standard-grade residential window hardware due to cost scalability and recyclability under EPA lead-safe renovation protocols. Cycle durability testing per ASTM E330 separates specification-grade from economy-tier alternatives in North American retrofit channels.
- Aluminum:Thermally broken aluminum framing systems collapse performance gaps with uPVC in German and California energy retrofit specifications. Extruded aluminum input volatility compresses margin stability for manufacturers serving price-sensitive new construction segments.
- Brass:Patina-grade cast brass retains margin concentration in conservation-area renovations across the United Kingdom and historic districts of Boston and Charleston.
- Plastic:Glass-reinforced nylon components serve economy residential applications where corrosion resistance outweighs load rating requirements.
Steel retains volume leadership. Aluminum is climbing the fastest as thermal break technology penetrates mid-market specification.
Installation Type:
Customer type and project funding mechanisms create divergent procurement behaviors across new construction and existing building modification.
- New Construction:Cyclical demand tied to housing starts and commercial lending conditions concentrates procurement through national fabricator relationships. Building envelope consultants specify integrated hardware-software bundles in mixed-use developments requiring fire-rated egress solutions.
- Retrofit:Energy audit triggers compress replacement timelines for fenestration hardware ahead of full envelope renovation across North American and Western European residential programs. Component-level upgrades dominate as building owners prioritize cost-effective thermal performance improvements.
- Commercial:Code compliance mandates for accessibility and fire safety drive specification of certified hardware in public and institutional buildings.
- Residential:Homeowner direct procurement through digital configurators displaces traditional distributor relationships in mid-market segments.
Retrofit channels are expanding most quickly. New construction maintains the revenue base despite cyclical volatility.
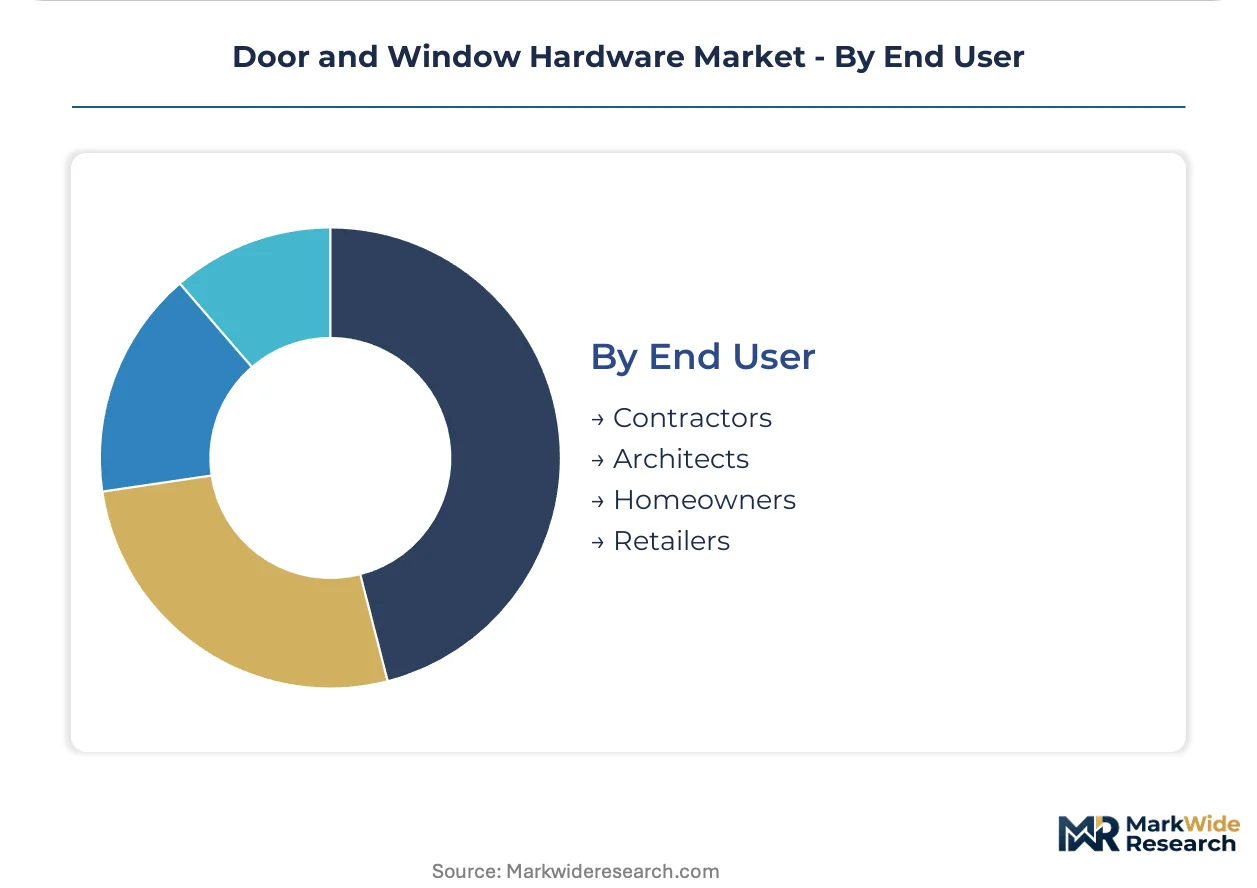
End User:
Procurement authority and technical specification capability determine channel strategy and pricing architecture for hardware suppliers.
- Contractors:Mid-size window and door fabricators in the United States Southeast and Southwest bypass legacy specialty distributors through direct-to-fabricator digital platforms that automate load rating and fire code compliance verification. Consolidation among contractor networks reduces distributor viability in these regions.
- Architects:Specification authority in green building certification projects drives premium hardware procurement for thermally broken frames and multi-point locking mechanisms. Embodied carbon reporting under CSRD elevates material transparency as a qualification criterion.
- Homeowners:Direct procurement through online configurators fragments traditional distribution in residential retrofit segments.
- Retailers:Big-box and specialty hardware retailers serve commodity replacement demand in residential maintenance applications.
Contractors anchor volume throughput. Architects are gaining specification influence fastest as building performance standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's role as the primary distribution hub for European fenestration hardware, channeling extruded aluminum and precision-machined components to fabrication clusters across the continent.
United States
Residential retrofit programs in California and Massachusetts accelerate multi-point locking specification as energy audits trigger component upgrades ahead of full envelope renovation. EPA lead-safe renovation rules constrain surface treatment formulations, pushing manufacturers toward chrome-free plating systems. Dallas-Fort Worth fabrication clusters concentrate specification-grade production for the Southwest contractor market.
Germany
Thermally broken aluminum framing dominates retrofit specification as the EU Green Deal mandates enhanced U-values across existing building stock. ECHA REACH restrictions on hexavalent chromium force coating reformulation for EN 1670 corrosion compliance. Stuttgart and Munich industrial corridors anchor premium hardware manufacturing for conservation-area renovations.
China
Urban renewal programs in tier-one cities drive fire-rated egress hardware procurement for high-rise residential tower refurbishment. SAMR-administered GB standards mandate accessibility and thermal performance thresholds for building envelope components. Yangtze River Delta manufacturing clusters supply volume production for domestic retrofit and export markets.
United Kingdom
Conservation-area renovation demand sustains patina-grade brass hardware margins across London and historic districts of Edinburgh. Building Regulations Part L thermal efficiency standards accelerate specification of thermally broken frames in residential retrofit. Midlands fabrication centers serve national distribution networks for certified architectural-grade components.
Door and Window Hardware Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in a structure that rewards specification authority and code compliance bundling. The vendor base organizes around three archetypes: multinational access control platforms, regional fenestration fabricators, and heritage restoration specialists. Consolidation pressure concentrates in the commercial retrofit channel where integrated hardware-software solutions displace standalone mechanical components. Strategic moves center on vertical integration into aluminum extrusion and direct-to-fabricator digital platform deployment.
Within the multinational platform tier, ASSA ABLOY and dormakaba occupy positions anchored by electronic access control portfolios that extend specification influence across airport and hospital infrastructure segments. Dormakaba's automatic door specialization exemplifies the integrated hardware-software archetype where code compliance demands bundle mechanical and electromechanical components. ASSA ABLOY represents the convergence play, leveraging access control expertise to capture premium positioning in commercial retrofit channels. Hafele sits within the component specialist tier, with kitchen and furniture hardware expertise extending into architectural door systems for mixed-use developments. These three players illustrate the competitive divergence between platform-scale bundling and focused component excellence.
| Leading Market Players |
|---|
| Dorma (dormakaba) |
| Emtek |
| ASSA ABLOY |
| D&D Hardware |
| Baldwin |
| Schüco |
| Hafele |
| C.R. Laurence |
| Allegion |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta extrusion capacity sets the floor for global aluminum hardware pricing, with throughput fluctuations at Ningbo and Shanghai ports transmitting directly to European and North American fabricator procurement costs. German and Italian manufacturers retain premium positioning through EN 1670 certification bundling, while Chinese volume producers compete on scale economies for standard-grade residential segments.
Pricing Analysis
Volume-discount tiering structures separate architectural-grade certification holders from commodity suppliers across the retrofit channel. Pricing stratifies across premium, standard, and economy tiers based on EN 1935 fire-rating certification and thermal break compatibility, with German fabricators showing least price sensitivity due to EU Green Deal mandate urgency. Cost compression in standard-grade stamped steel hinges is intensifying because of aluminum input volatility and REACH-driven plating reformulation costs.
Supply Chain Analysis
Extruded aluminum feedstock draws from Chinese smelter concentration, German precision-casting clusters, and Italian zinc-alloy coating specialists. Raw material dependencies center on aluminum billet, die-cast zinc alloys, and trivalent chromium pretreatment chemicals. Single-source vulnerability runs through Yangtze River Delta port congestion affecting just-in-time delivery to European fabricators. Distribution runs through direct-to-fabricator digital platforms displacing legacy specialty distributor networks in the United States Southeast and Southwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical access control substitution threatens mechanical hardware incumbents as ASSA ABLOY and dormakaba bundle integrated solutions across airport and hospital infrastructure, forcing component specialists to defend specification authority through code compliance anchoring.
For Market Incumbents: Insulate specification-grade positioning by deepening backward integration into aluminum extrusion capacity at Stuttgart and Munich industrial corridors, and accelerate chrome-free plating certification timelines ahead of ECHA enforcement waves. Threat exposure concentrates in commercial retrofit channels where electronic access control bundles displace standalone mechanical lock volumes.
For New Entrants and Emerging Players: Heritage restoration specialists in United Kingdom conservation areas and Boston historic districts represent the most penetrable entry point for patina-grade brass hardware margins, with direct-to-fabricator digital platform partnerships offering the cleanest go-to-market angle against entrenched distributor relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electromechanical platform integrators with software-anchored service contracts across hospital and airport infrastructure segments. Long-term viability favors targets with captive EN 1670 certification capabilities and established relationships with building envelope consultants specifying thermal break compatibility. Signal to monitor: CSRD carbon disclosure adoption rates among German and California architect communities as specification inflection trigger.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of thermally broken framing systems secures margin control against Ningbo port volatility. |
| Chrome-Free Plating Certification Investment | Trivalent chromium and zirconium pretreatment lines retain CE marking eligibility under ECHA REACH restrictions. |
| Direct-to-Fabricator Digital Platform Launch | Automated load rating verification displaces legacy specialty distributors in United States Southeast contractor markets. |
| Heritage Restoration Specialist Acquisition | Patina-grade brass capabilities capture conservation-area renovation premiums across United Kingdom and Charleston. |
| Electromechanical Convergence Partnership | Sensor network integration with mechanical egress components defends specification against dormakaba bundled solutions. |
Methodological Framework
Cross-validation between primary interviews with fenestration fabricators, building envelope consultants, and specialty distributor procurement heads and secondary validation through SEC 10-K filings, customs trade data, and EN standard certification databases anchors the qualitative findings. Bottom-up triangulation against top-down macroeconomic indicators ensures segmentation consistency across product type, material grade, and installation channel dimensions.
Calibration against historical replacement cycle data and energy audit trigger frequencies across German and California retrofit programs shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product category, material composition, installation type, and end-user procurement authority, with CAGRs derived from building permit trajectories and green building certification adoption curves. Industry-specific forecast inputs encompass aluminum LME price bands and ECHA regulatory timeline assumptions.
Stress conditions across aluminum input volatility, REACH substance restriction acceleration, and electromechanical substitution penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal enforcement continuity and SAMR GB standards harmonization pace. Quarterly review of building energy audit issuance rates and architect specification platform adoption metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Metal Grating Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
Glass Tiles Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Pocket Door Market
Building & Construction Materials
Global Cool Roofs Market
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
Acoustic Ceiling Tiles Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
North America Prefab Wood Building Market
Building & Construction Materials
Door Hardware Market
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
GCC Ceramic Tiles Market
Building & Construction Materials
Piping Systems Market