
 Glass Railing System Market | 2026-2036
Glass Railing System Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Railing System Market Insights
Tempered-glass specification upgrades is reorganizing procurement patterns across commercial and institutional projects. C.R. Laurence leverages its captive distribution network to dominate specification-grade hardware channels in North America. Q-railing sustains European market presence through precision-engineered modular clamping systems. VIVA Railings anchors high-rise residential demand with project-engineered custom fabrication capabilities.
A glass railing system integrates transparent or translucent barrier panels—typically tempered, laminated, or low-iron glass ranging from 10 mm to 21.5 mm in thickness—within metal or structural support frameworks to provide fall protection while preserving sightlines. Fabrication involves heat-strengthening or chemical toughening followed by edge polishing and drilling for point-fixed or channel-mounted hardware attachment. Frameless configurations command premium positioning in luxury residential and hospitality settings where uninterrupted views drive specification value. Semi-frameless and mounted variants capture volume share across mid-tier commercial and multi-family housing where cost-engineered safety compliance remains the primary selection criterion. Low-iron glass segments are gaining specification share as architects prioritize optical clarity and reduced green-edge tinting in high-visibility installations.
FDA guidelines for glass contact surfaces in food-service and hospitality settings intersect with ICC-ES acceptance criteria for structural glazing in commercial buildings, creating layered compliance obligations for manufacturers serving mixed-use developments. OSHA fall-protection thresholds for elevated work platforms indirectly shape installer training and temporary railing specifications during construction phases. Stakeholders must monitor evolving amendments to the International Building Code and regional energy-performance mandates that could alter glass thickness requirements and thermal-break hardware specifications in climate-sensitive jurisdictions.
Market Dynamics
Tempered-laminated glass specification upgrades under EN 12150 and ASTM E2358 are compressing supplier margins while elevating certification barriers for mid-tier fabricators serving luxury hospitality and coastal residential verticals.
Growth Catalysts
- Coastal Residential Construction:Florida, California, and Australia's Gold Coast are driving frameless balustrade demand for oceanfront properties where corrosion-resistant hardware and salt-spray testing protocols under ASTM B117 accelerate specification upgrades.
- EN 12150 Safety Mandates:European toughened-glass certification requirements are eliminating uncertified suppliers from specification channels and consolidating procurement toward accredited fabricators with in-house heat-soak testing capabilities.
- Low-Iron Glass Technology:Reduced green-edge tinting in high-visibility installations is commanding premium positioning among architects specifying infinity pools and rooftop terraces in Dubai and Singapore.
Market Restraints
- Silica Sand Input Volatility:High-purity silica supply concentration in limited geographic deposits creates raw material cost instability for domestic tempering facilities dependent on consistent chemical composition.
- Energy-Intensive Tempering:Natural gas and electricity price spikes in European manufacturing clusters are compressing margins for heat-strengthening operations with limited furnace efficiency upgrades.
- Aluminum Channel Substitution:Powder-coated metal railings with cable infill are capturing mid-tier multi-family housing specifications where cost-engineered safety compliance outweighs optical clarity requirements.
Strategic Opportunities
- Modular Clamping System Convergence:Precision-engineered stainless steel hardware combined with BIM-compatible specification tools is opening architect-direct channels bypassing traditional distributor markups.
- ICC-ES Acceptance Criteria Expansion:Mixed-use developments integrating food-service and hospitality functions are creating layered compliance service opportunities for manufacturers with dual FDA and structural glazing expertise.
- Retrofit Installation Services:Aging commercial building stock in legacy hospitality districts is generating demand for minimally invasive glass railing replacement with existing substrate anchoring systems.
Industry Challenges
- Glazier Certification Bottlenecks:OSHA fall-protection thresholds for elevated work platforms are extending project timelines as qualified installer availability constrains construction-phase temporary railing deployment.
- Thermal-Break Hardware Integration:Climate-sensitive jurisdictions are mandating thermally separated metal components that require re-engineered channel systems incompatible with legacy specification libraries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Railing System Market |
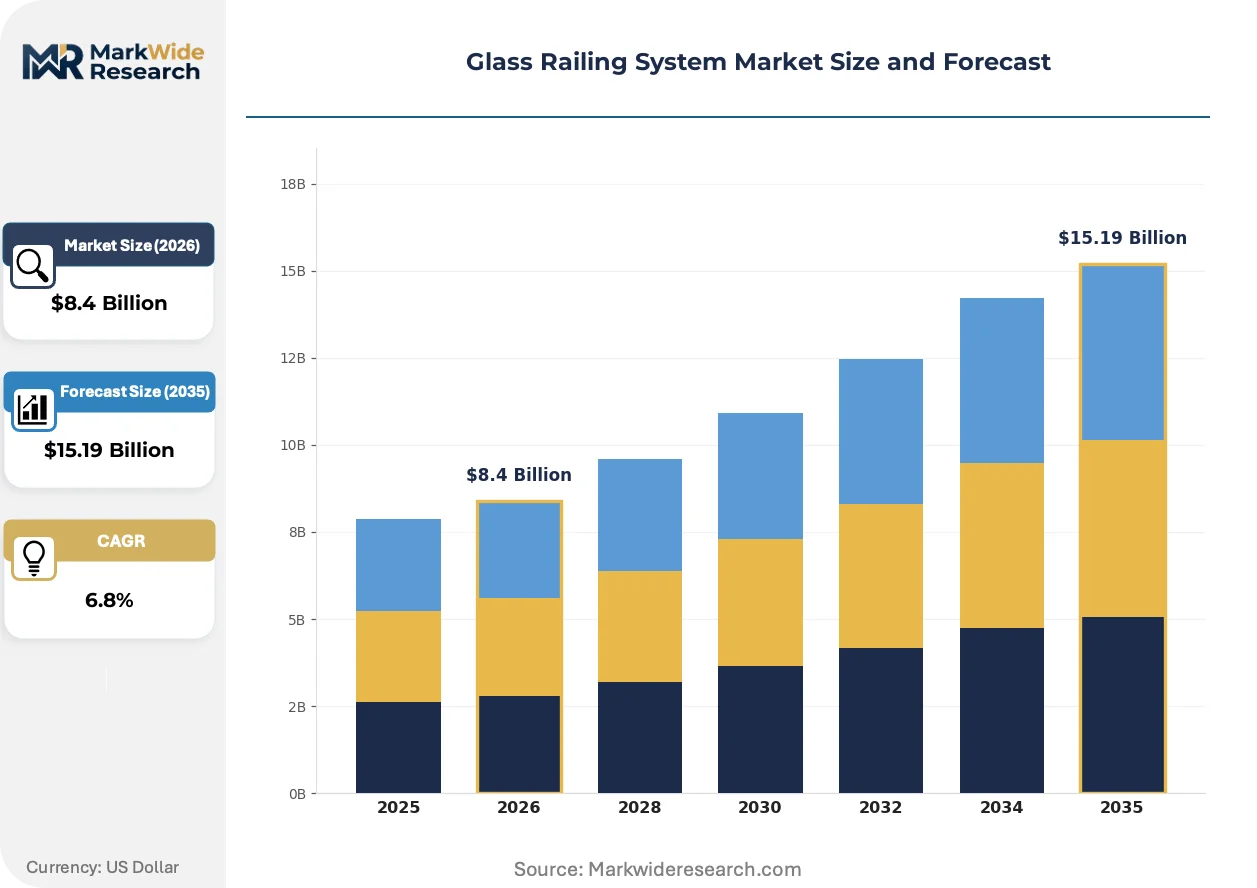
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frameless, Semi-Frameless, Mounted, Custom End User: Residential, Commercial, Industrial, Institutional Installation Type: Indoor, Outdoor, Balcony, Staircase Material: Tempered Glass, Laminated Glass, Low-Iron Glass, Others |
| Companies Covered | VIVA Railings, Vista Railing Systems, C.R. Laurence (CRL), Invisirail, Regal Ideas, Q-railing, Century Aluminum Railing, Greco Railings, The Wagner Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Railing System Market Trends and Innovations
Specification workflows are digitizing rapidly. Architects and developers now demand BIM-compatible hardware libraries and real-time structural calculation tools that compress design-to-fabrication cycles.
Smart glass integration with electrochromic and thermochromic layering is bifurcating the premium segment. Luxury hospitality developers in Dubai and Singapore are specifying dynamic tinting balustrades for rooftop terraces. This technology is compressing traditional static-glass specification values while creating new performance-tier pricing differentiation.
REACH chemical safety assessments are tightening restricted substance lists for coating systems used in structural glazing hardware. European fabricators are reformulating powder coatings and anodizing chemistries to maintain CE marking compliance. High-rise residential projects in Germany and the Netherlands are experiencing extended procurement cycles as suppliers validate alternative surface treatments.
Direct-to-fabricator specification is displacing traditional distributor channels for complex custom projects. Architects with parametric design capabilities are engaging project-engineered fabricators early in concept development. This pattern is most visible in Singapore's luxury residential tower market where sightline-preserving frameless configurations command specification priority over standard catalog offerings.
Glass Railing System Market Segmentation
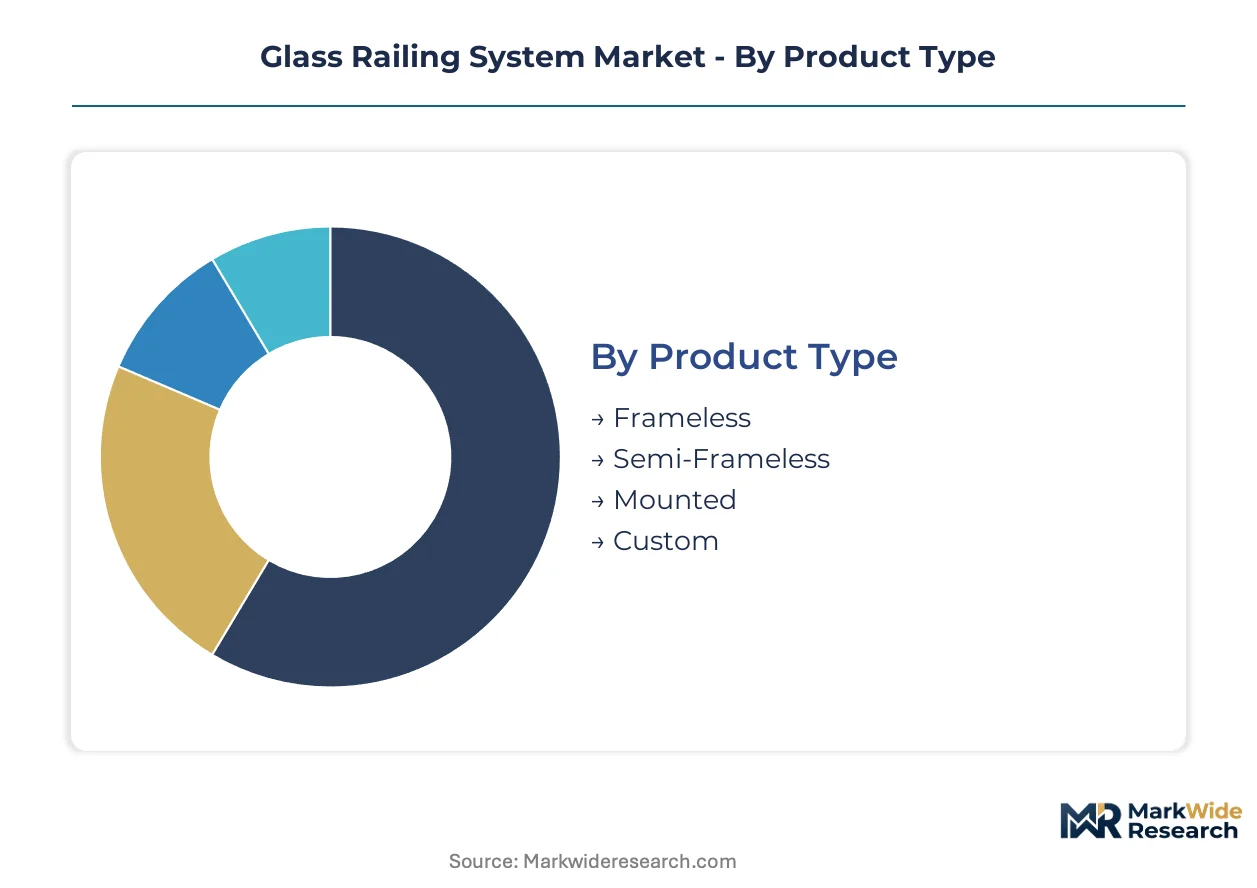
Glass railing procurement splits across specification-grade transparency requirements and cost-engineered safety compliance. Architects in luxury hospitality and multi-family housing select from distinct product tiers where optical clarity, structural certification, and installation environment dictate final specification.
Product Type:
Semi-frameless and mounted variants face intensifying substitution pressure from powder-coated metal railings with cable infill in mid-tier multi-family developments.
- Frameless:Uninterrupted sightlines through 10 mm to 21.5 mm tempered or laminated panels secured by precision-engineered point-fixed hardware. Demand concentrates in Dubai and Singapore luxury hospitality where infinity pools and rooftop terraces prioritize optical clarity over cost constraints.
- Semi-Frameless:Partial metal framing reduces hardware complexity while preserving visual openness. Florida and California coastal residential projects specify these for oceanfront balconies where salt-spray resistance under ASTM B117 testing governs hardware selection.
- Mounted:Channel-integrated base shoe systems simplify installation on existing substrates. Aging commercial building stock in legacy hospitality districts drives retrofit demand for minimally invasive replacement.
- Custom:Project-engineered fabrication accommodates non-standard geometries and parametric designs. Singapore luxury residential towers engage fabricators early in concept development for sightline-preserving configurations.
Mounted systems anchor the volume base while frameless configurations gain share at the steepest rate.
End User:
Commercial and institutional procurement concentrates in mixed-use developments where FDA food-service guidelines intersect with ICC-ES structural glazing criteria.
- Residential:Single-family oceanfront properties and high-rise condominiums specify corrosion-resistant hardware for balcony and terrace applications. Australia's Gold Coast drives frameless balustrade demand for coastal views.
- Commercial:Office atriums, retail mezzanines, and hospitality lobbies require EN 12150-certified tempered glass with documented heat-soak testing. Procurement consolidates toward accredited fabricators as certification barriers eliminate uncertified suppliers.
- Industrial:Elevated work platforms and manufacturing facilities prioritize OSHA fall-protection compliance over aesthetic considerations. Temporary railing deployment during construction phases extends project timelines due to qualified installer scarcity.
- Institutional:Museums, airports, and civic buildings demand low-iron glass with reduced green-edge tinting for high-visibility installations. REACH chemical safety assessments extend procurement cycles as fabricators reformulate coating systems.
Commercial applications dominate current specification value while institutional projects expand most quickly on compliance service bundling.
Installation Type:
Outdoor and balcony installations command premium positioning due to climate-exposed hardware requirements and salt-spray testing protocols.
- Indoor:Atrium dividers, stairwell enclosures, and mezzanine guards in climate-controlled environments. Lower hardware corrosion resistance requirements permit cost-engineered specification.
- Outdoor:Rooftop terraces, pool decks, and perimeter barriers exposed to precipitation and temperature cycling. Thermal-break hardware integration mandated in climate-sensitive jurisdictions requires re-engineered channel systems.
- Balcony:Residential multi-family and hospitality guest room extensions where fall-protection thresholds intersect with sightline preservation. Frameless configurations command specification priority in premium developments.
- Staircase:Continuous handrail integration with glass infill panels demands precise edge polishing and drilling for hardware attachment. BIM-compatible specification tools compress design-to-fabrication cycles for complex geometries.
Balcony installations generate the highest per-project specification value while staircase applications climb the fastest on parametric design adoption.
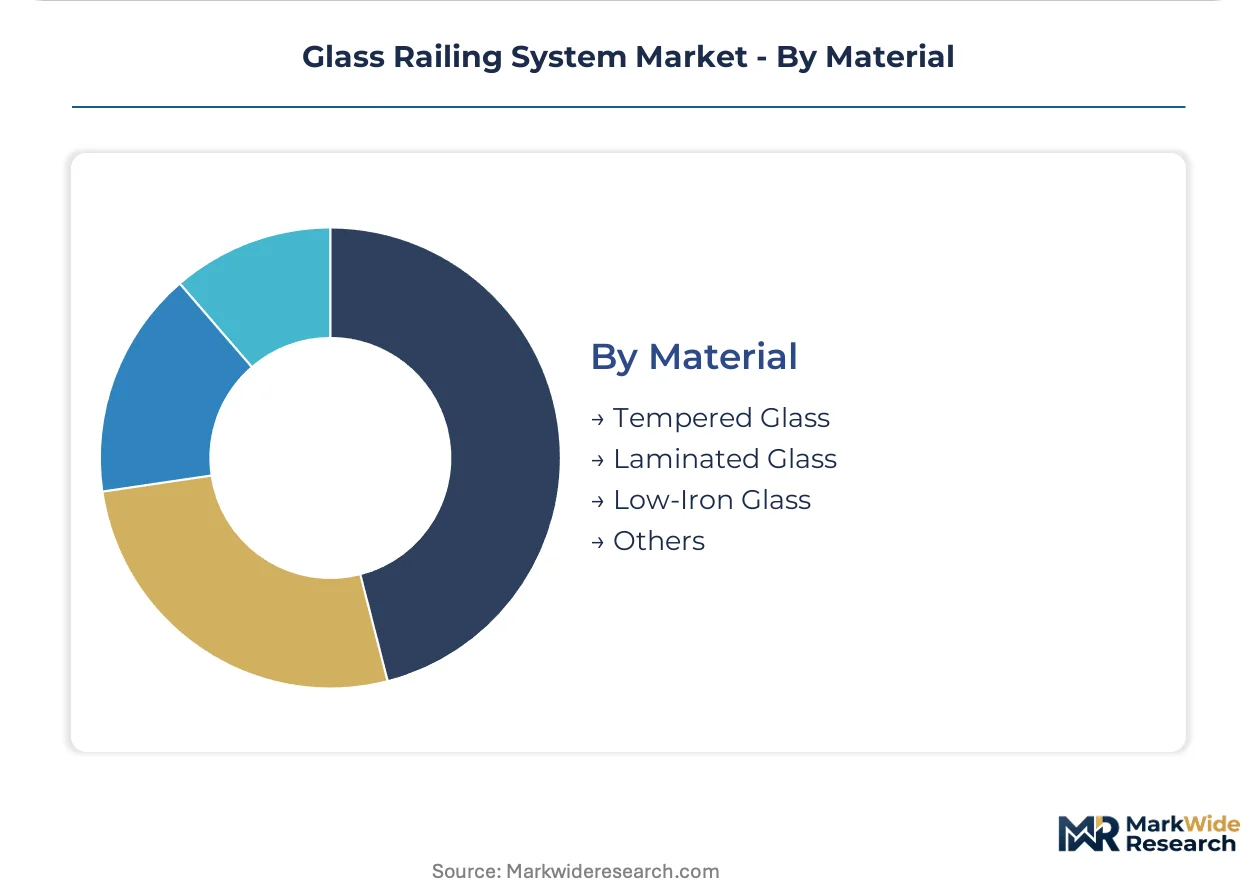
Material:
Low-iron glass technology is bifurcating the premium segment as electrochromic and thermochromic layering enables dynamic tinting capabilities.
- Tempered Glass:Heat-strengthened panels meeting EN 12150 and ASTM E2358 safety standards. European certification requirements compress supplier margins while elevating barriers for mid-tier fabricators.
- Laminated Glass:Interlayer-bonded panels providing post-breakage retention and acoustic dampening. Institutional and high-rise residential projects specify these for enhanced safety redundancy.
- Low-Iron Glass:Reduced iron oxide content eliminates green-edge tinting for maximum optical clarity. Dubai and Singapore luxury developers specify these for infinity pools and rooftop terraces where visibility drives value.
- Others:Chemically strengthened and specialty coated variants for unique performance requirements. Smart glass integration with dynamic tinting creates new pricing differentiation in the premium tier.
Tempered glass anchors the volume base while low-iron variants gain share at the steepest rate on architect specification priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established fabrication clusters with captive tempering capacity and certified distribution networks. The United States maintains net importer status for high-specification frameless systems while exporting standard tempered panels to Caribbean hospitality developments. European fabricators leverage CE marking reciprocity to capture Middle Eastern luxury project specifications.
United States
Coastal residential construction across Florida and California drives frameless balustrade imports from European certified fabricators. OSHA fall-protection thresholds for elevated work platforms constrain qualified installer availability and extend project timelines. Miami-Dade County's hurricane-rated building codes mandate laminated glass for balcony applications above six stories.
Germany
Industrial glazing clusters in Bavaria and North Rhine-Westphalia supply precision-engineered hardware across European mixed-use developments. REACH chemical safety assessments extend procurement cycles as fabricators reformulate powder coatings to maintain CE marking compliance. Stuttgart-based engineering consultancies specify low-iron glass for museum and airport installations requiring optical clarity.
United Arab Emirates
Dubai's luxury hospitality developers specify dynamic-tinting electrochromic balustrades for rooftop terraces and infinity pools. MOHAP construction product regulations intersect with international hospitality brand standards to create layered compliance requirements. Jumeirah Beach Residence and Downtown Dubai clusters concentrate specification-grade fabrication demand.
Australia
Gold Coast oceanfront properties drive corrosion-resistant hardware demand under salt-spray testing protocols. TGA-aligned state building codes mandate toughened-laminated safety standards for residential balcony applications above three meters. Sydney and Melbourne commercial districts generate retrofit demand for minimally invasive glass railing replacement.
Singapore
Luxury residential towers in Marina Bay and Orchard Road engage fabricators early in concept development for parametric frameless configurations. BCA structural glazing criteria enforce documented heat-soak testing for high-rise applications. Smart glass integration with thermochromic layering commands premium positioning among architect-specified developments.
Glass Railing System Market Competitive Landscape
Listed building-product conglomerates compete with private specialists across specification-grade channels and cost-engineered volume segments. The vendor base organizes around three tiers: integrated glass-hardware fabricators with captive tempering capacity, precision-engineered modular system specialists, and regional installation-service providers with project-engineered custom capabilities. Consolidation pressure concentrates among mid-tier fabricators lacking EN 12150 in-house certification. Strategic moves center on BIM-compatible specification tool deployment and architect-direct channel development bypassing traditional distributor markups.
Among North American building-product conglomerates, C.R. Laurence anchors specification-grade hardware distribution through captive channel control. European precision-engineered specialists include Q-railing with modular clamping system expertise. VIVA Railings occupies a position within the project-engineered custom fabrication tier serving high-rise residential demand. These three exemplify distinct competitive archetypes: integrated distribution control, precision modular engineering, and architect-direct custom fabrication.
| Leading Market Players |
|---|
| VIVA Railings |
| Vista Railing Systems |
| C.R. Laurence (CRL) |
| Invisirail |
| Regal Ideas |
| Q-railing |
| Century Aluminum Railing |
| Greco Railings |
| The Wagner Companies |
| Others |
Pricing and Supply Chain Analysis
Powder-coated metal railings with cable infill displacing glass in mid-tier multi-family housing simultaneously redraw procurement geography toward Midwestern U.S. metal fabrication clusters and compress pricing economics for standard tempered panels in cost-engineered safety segments.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade under EN 12150 and ASTM E2358 separates frameless architectural specifications from semi-frameless coastal residential and mounted retrofit tiers. Cost compression in standard tempered panels is intensifying because aluminum channel substitution captures volume share in multi-family housing. Commercial developers exhibit highest price sensitivity while luxury hospitality specifiers in Dubai and Singapore demonstrate minimal elasticity for optical clarity.
Supply Chain Analysis
Germany and the United Arab Emirates anchor precision-engineered hardware fabrication for specification-grade point-fixed systems. High-purity silica sand from limited geographic deposits and natural gas for tempering furnaces feed from concentrated upstream sources. Single-source vulnerability in European heat-soak testing capacity creates bottleneck risk for EN 12150 certification. Distribution runs through captive specification-grade channels controlled by integrated glass-hardware fabricators and architect-direct project-engineered fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among architect-led specification teams with parametric design capabilities, fragmenting traditional distributor influence and compressing markup capture across standard product tiers.
For Market Incumbents: Fortify certification barriers by investing in captive heat-soak testing capacity under EN 12150 standards. Deepen backward integration into high-purity silica sourcing to offset raw material volatility. Aluminum channel substitution in mid-tier housing represents the primary margin threat requiring tiered product portfolio response. For New Entrants and Emerging Players: Anchor in BIM-compatible specification tool deployment to bypass traditional hardware distributor markups. Retrofit installation services for aging commercial hospitality stock in Sydney and Melbourne offer the most penetrable white-space target. Early architect engagement during concept development unlocks project-engineered custom fabrication contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed modular clamping system specialists lacking in-house tempering capacity. Five-to-ten year viability hinges on consolidation of mid-tier fabricators unable to sustain EN 12150 certification investments. Monitor REACH chemical safety assessment compliance costs as the inflection signal for European coating system reformulation exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Soak Testing Certification Investment | EN 12150 accreditation eliminates uncertified competitors from specification channels in European mixed-use developments. |
| BIM-Compatible Hardware Library Deployment | Real-time structural calculation tools compress design-to-fabrication cycles for architect-direct engagement. |
| Modular Clamping System Convergence | Precision-engineered stainless steel hardware opens specification channels bypassing traditional distributor markups. |
| Retrofit Installation Service Expansion | Minimally invasive replacement with existing substrate anchoring captures aging commercial building stock demand. |
| Smart Glass Integration Partnership | Electrochromic layering capabilities command premium positioning in Dubai and Singapore luxury hospitality specifications. |
Research Methodology
Operator-level perspectives from glazing contractors, architectural specification consultants, hospitality procurement directors, and tempered glass plant managers anchored the qualitative base. Primary interviews combined with secondary validation from ICC-ES acceptance criteria documentation, ASTM standard revision records, and building permit databases. Customs data on silica sand imports and SEC filings from listed building-product conglomerates provided trade flow and capacity indicators. Bottom-up project pipeline analysis triangulated against top-down construction spending forecasts.
Sensitivity analysis across product type, end user, installation environment, and glass material grade informed the analytical framework over the projection horizon. CAGRs derived from segment-level volume build-ups incorporating EN 12150 certification adoption curves and low-iron glass specification share trajectories. Energy price scenarios for European tempering operations and coastal construction permit trends in Florida and California served as industry-specific forecast inputs.
Underlying assumptions cover sustained luxury hospitality development in Dubai and Singapore, with deviation risk concentrated in silica sand supply disruptions and REACH chemical safety assessment timeline extensions. Recalibration cycles align with material shifts in EN 12150 enforcement intensity and smart glass technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Technical Insulation Market
Building & Construction Materials
Global Elastic Rail Fasteners Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
Concrete Conditioner Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
Europe Green Buildings Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
Geofoam Market
Building & Construction Materials
GCC Concrete Blocks Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
Building and Construction Plastic Fasteners Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Sandwich Panel System Market
Building & Construction Materials
North America Metallic Barn Doors Market