
 Spain Architectural Coatings Market | 2026-2036
Spain Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Architectural Coatings Market Analytics
Residential renovation is decoupling from new-build construction as the primary volume driver. PPG Industries leverages its Iberian distribution network to sustain contractor loyalty across Andalusia and the Basque Country. AkzoNobel N.V. anchors premium positioning through its color-matching service infrastructure in Madrid and Barcelona showrooms. CIN S.A. dominates Portuguese-Spanish cross-border supply chains, while Jotun Group specializes in marine-adjacent architectural specifications along Mediterranean coastal developments.
Spain architectural coatings encompass liquid and powder formulations applied to building exteriors and interiors for protection, decoration, and functional performance, with water-based emulsions typically containing 30-60% solids by volume and VOC thresholds governed by EU Directive 2004/42/CE. These products shield substrates from UV degradation, moisture ingress, and thermal cycling while enabling aesthetic customization across diverse climatic zones from Galicia's Atlantic coast to Murcia's arid interior. Water-based emulsions lead volume due to regulatory pressure on solvent-borne alternatives, though nano-coatings represent the fastest-expanding technology segment as self-cleaning and anti-graffiti properties command contractor premiums. Residential application absorbs the largest share of formulation output, while institutional demand generates superior margin pools through extended warranty specifications and certified applicator networks.
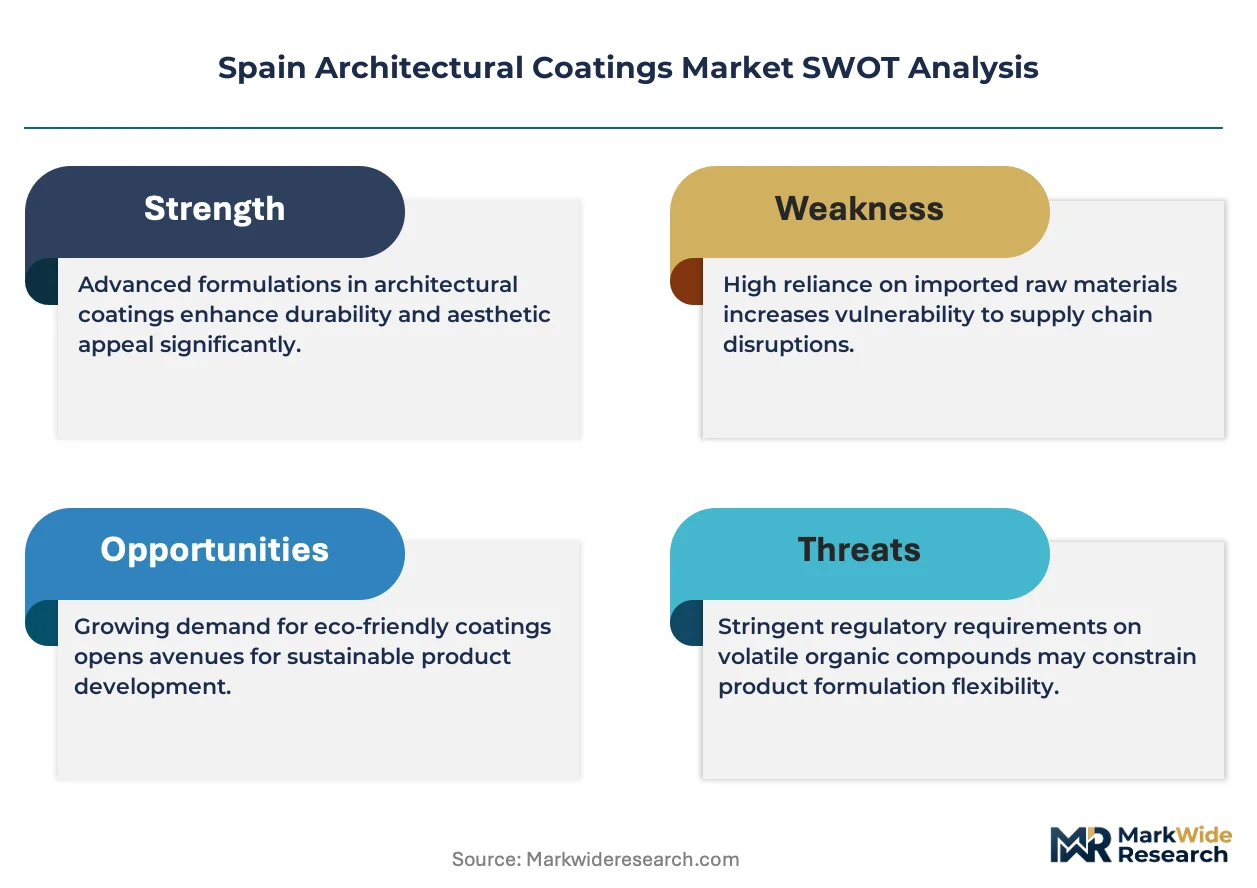
Spain's Ministry of Transport and Urban Agenda enforces CTE compliance for thermal transmittance and surface reflectance, compelling manufacturers to reformulate with infrared-reflective pigments and low-VOC binders. The EU Green Deal and REACH restrictions on hazardous substance content further constrain raw material sourcing, with ECHA evaluations of titanium dioxide nanoparticles creating additional registration burdens for nano-coating producers. Stakeholders must monitor upcoming revisions to Spanish building certification schemes and assess whether local production of bio-based alkyd resins can offset import dependency before committing capital to capacity expansion.
Market Dynamics
Spain's architectural coatings sector is pivoting around the Technical Building Code's thermal performance mandates, which force manufacturers to reformulate with infrared-reflective pigments and low-VOC binders. This regulatory pressure is compressing legacy solvent-borne production while accelerating water-based emulsion capacity expansion.
Growth Catalysts
- CTE thermal transmittance standards:Spain's Technical Building Code mandates stricter facade energy efficiency, pulling demand toward low-emissivity coatings that reduce building cooling loads.
- Multi-family housing permits:Catalonia and Madrid metropolitan corridor construction activity outpaces national averages, concentrating volume demand in high-density residential zones.
- Nano-coating technology:Self-cleaning and anti-graffiti surface treatments command contractor premiums across Mediterranean coastal developments.
Market Restraints
- Titanium dioxide nanoparticle registration:ECHA evaluations impose additional compliance burdens on nano-coating producers, extending time-to-market for innovative formulations.
- Bio-based alkyd resin import dependency:Limited domestic production of sustainable binders exposes formulators to raw material supply concentration from Northern European suppliers.
- REACH hazardous substance restrictions:The EU's chemical framework constrains raw material sourcing flexibility, forcing reformulation cycles that disrupt established product lines.
Strategic Opportunities
- Andalusian solar-exposure markets:High UV intensity across southern Spain creates premium demand for advanced UV-degradation protection in exterior coatings.
- Institutional warranty specifications:Extended performance guarantees and certified applicator networks generate superior margin pools in public building segments.
- Portuguese-Spanish cross-border supply optimization:Integrated Iberian distribution infrastructure enables logistics cost advantages for manufacturers with dual-market presence.
Industry Challenges
- Certified applicator network scaling:CTE compliance requires trained installation labor that remains scarce outside Madrid and Barcelona metropolitan cores.
- Dual formulation inventory management:Manufacturers must maintain parallel solvent-borne and water-based product lines during the multi-year transition window mandated by EU Directive 2004/42/CE.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Architectural Coatings Market |
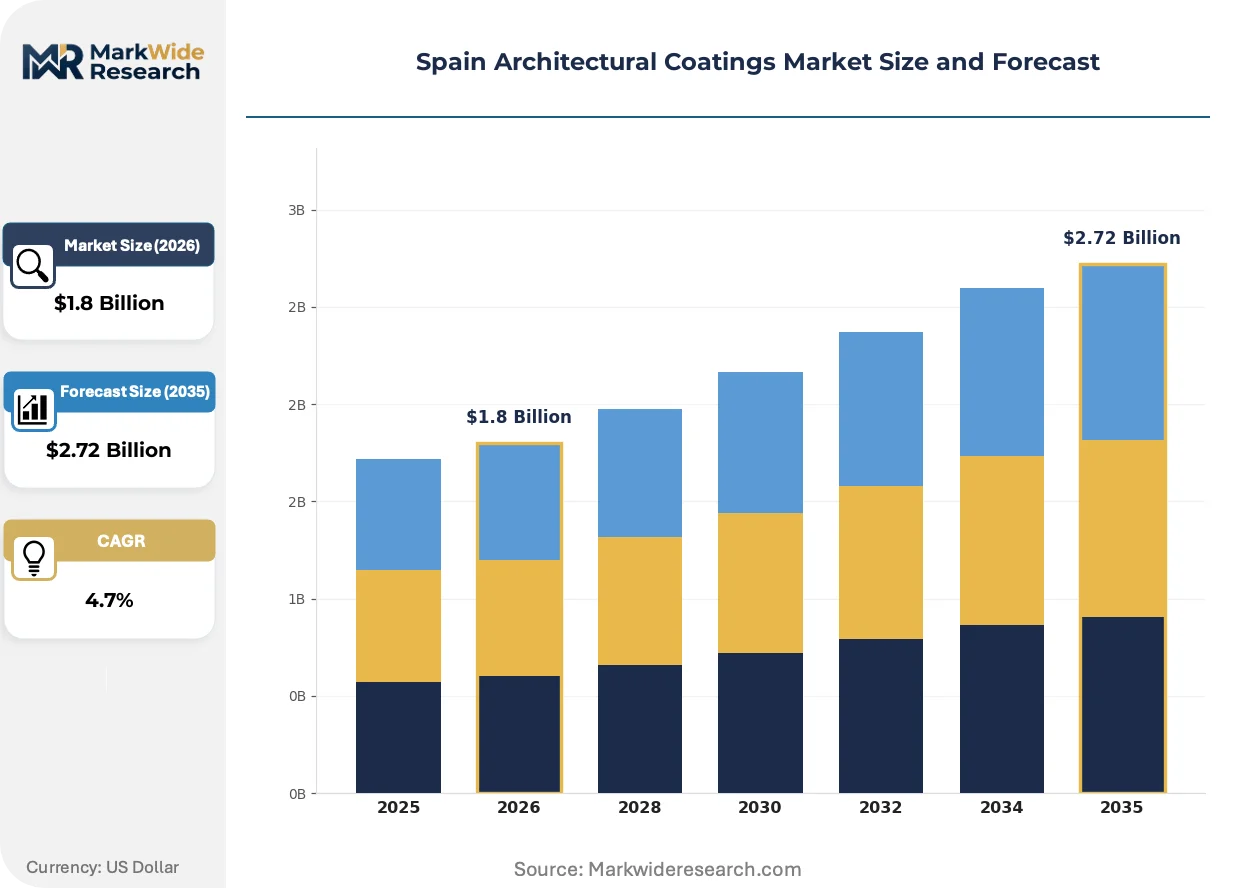
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsions, Solvent-Based, Powder Coatings, Water-Based Application: Residential, Commercial, Institutional, Infrastructure End User: Contractors, Builders, Architects, Homeowners Technology: Eco-Friendly, Nano-Coatings, Smart Coatings, Traditional Paints |
| Companies Covered | PPG Industries Inc., Jotun Group, AkzoNobel N.V., ULMA Architectural Solutions, The Barpimo Group, CIN S.A., Nippon Paint Holdings Co. Ltd., IVM Chemicals srl, DAW SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Architectural Coatings Market Evolving Landscape
Formulation chemistry and distribution models are undergoing parallel transformation as regulatory thresholds tighten and contractor purchasing patterns evolve. The sector is witnessing technology decentralization alongside channel restructuring.
Nano-engineered surface treatments are decentralizing quality control from factory to job site. These self-cleaning and anti-graffiti formulations enable facade maintenance reduction for property managers. Madrid and Barcelona commercial developers now specify nano-enhanced coatings for premium multi-family projects. The technology is compressing traditional repainting cycles while shifting performance accountability toward applicator skill rather than manufacturer batch consistency.
Spain's Ministry of Transport and Urban Agenda is tightening CTE enforcement for thermal transmittance and surface reflectance. This policy pressure compels manufacturers to integrate infrared-reflective pigments into standard product lines rather than premium tiers alone. Catalonia's building certification schemes are responding fastest, with Barcelona municipalities requiring pre-submittal coating performance documentation.
Contractor loyalty programs are fragmenting procurement concentration across Iberian distribution networks. PPG Industries leverages its Andalusian and Basque Country infrastructure to lock recurring specification decisions. Regional paint merchants now bundle technical support with volume commitments, displacing traditional merchant-wholesaler relationships. This pattern is most visible in Galicia's Atlantic coast markets where weathering severity demands localized formulation expertise.
Spain Architectural Coatings Market Segmentation
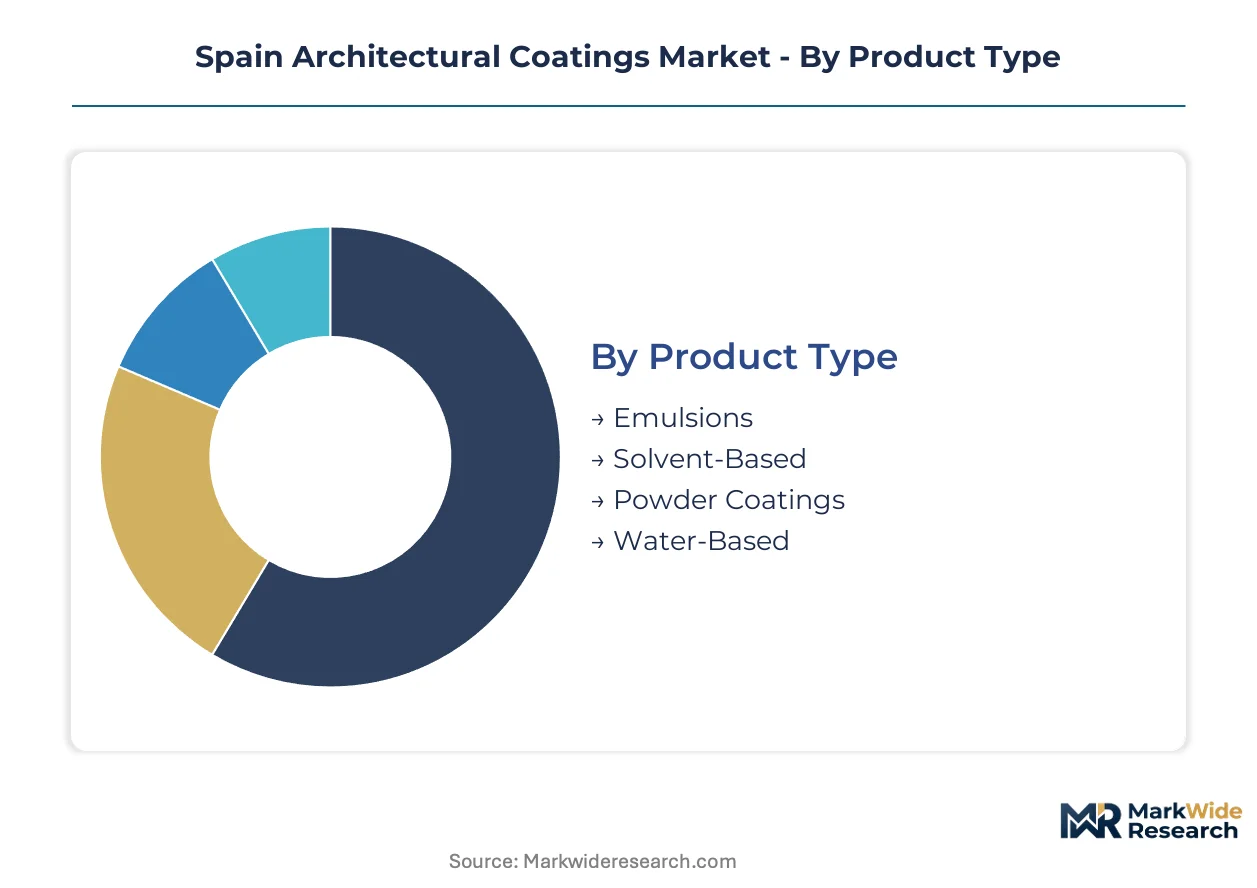
Architectural coatings in Spain fragment across formulation chemistry, project scale, and specification authority. Understanding where decision-making power sits within each dimension clarifies go-to-market priorities for manufacturers navigating CTE compliance pressures.
Product Type:
Formulation chemistry determines regulatory exposure and margin structure, with water-based systems commanding procurement attention as solvent-borne alternatives face phasedown.
- Water-Based:Acrylic and vinyl-acrylic emulsions carrying 30-60% solids by volume dominate new specification. Catalonia's municipal pre-submittal requirements for coating performance documentation accelerate displacement of legacy alternatives.
- Emulsions:Polymer-stabilized dispersions enable low-VOC compliance without sacrificing application latitude. Madrid metropolitan corridor multi-family developers specify these for interior wall systems where occupant safety certification matters.
- Solvent-Based:Alkyd and urethane systems persist in industrial-adjacent architectural applications requiring superior moisture resistance. REACH hazardous substance restrictions compress remaining volume to specialty restoration projects.
- Powder Coatings:Thermoset formulations applied via electrostatic spray serve metal substrate protection in institutional facades. Limited architectural penetration reflects substrate compatibility constraints rather than performance deficiency.
Volume sits with water-based systems; growth tilts toward emulsion technologies as CTE thermal performance mandates deepen formulation complexity.
Application:
Project typology dictates warranty requirements, batch sizing, and the balance between new construction and renovation demand.
- Residential:Single-family and multi-family housing absorbs the largest formulation output share. Energy-efficient facade upgrades in Andalusia and Murcia drive specification of infrared-reflective exterior systems.
- Commercial:Office, retail, and hospitality developments in Barcelona and Madrid command premium nano-coating specifications. Self-cleaning surface treatments reduce lifecycle maintenance costs for property managers.
- Institutional:Public buildings, healthcare facilities, and educational infrastructure generate superior margin pools through extended performance guarantees. Certified applicator networks remain scarce outside major metropolitan cores.
- Infrastructure:Transportation hubs, utilities, and public works projects specify heavy-duty protective systems. UV-degradation resistance priorities concentrate demand in Galicia's Atlantic coast exposure zones.
Residential renovation absorbs current volume; institutional certification requirements offer the steepest expansion trajectory for qualified suppliers.
End User:
Purchasing authority varies dramatically by project scale, with professional intermediaries dominating commercial and institutional channels while homeowners drive retail volume.
- Contractors:Application specialists control specification decisions in commercial and institutional segments. PPG Industries and AkzoNobel loyalty programs lock recurring procurement across Andalusia and the Basque Country.
- Builders:Volume homebuilders and multi-family developers prioritize cost-efficient compliance with CTE thermal transmittance standards. Cross-border Portuguese-Spanish supply chains enable logistics advantages for integrated manufacturers.
- Architects:Design professionals influence premium positioning through color-matching service requirements and performance documentation. Barcelona showrooms anchor specification authority for high-visibility commercial facades.
- Homeowners:Retail purchasers drive interior emulsion volume through merchant channels. Weathering severity in Galicia and UV exposure in southern Spain create localized formulation demand variation.
Professional intermediaries control margin-rich specification; direct homeowner purchases expand most quickly as renovation financing accessibility improves.
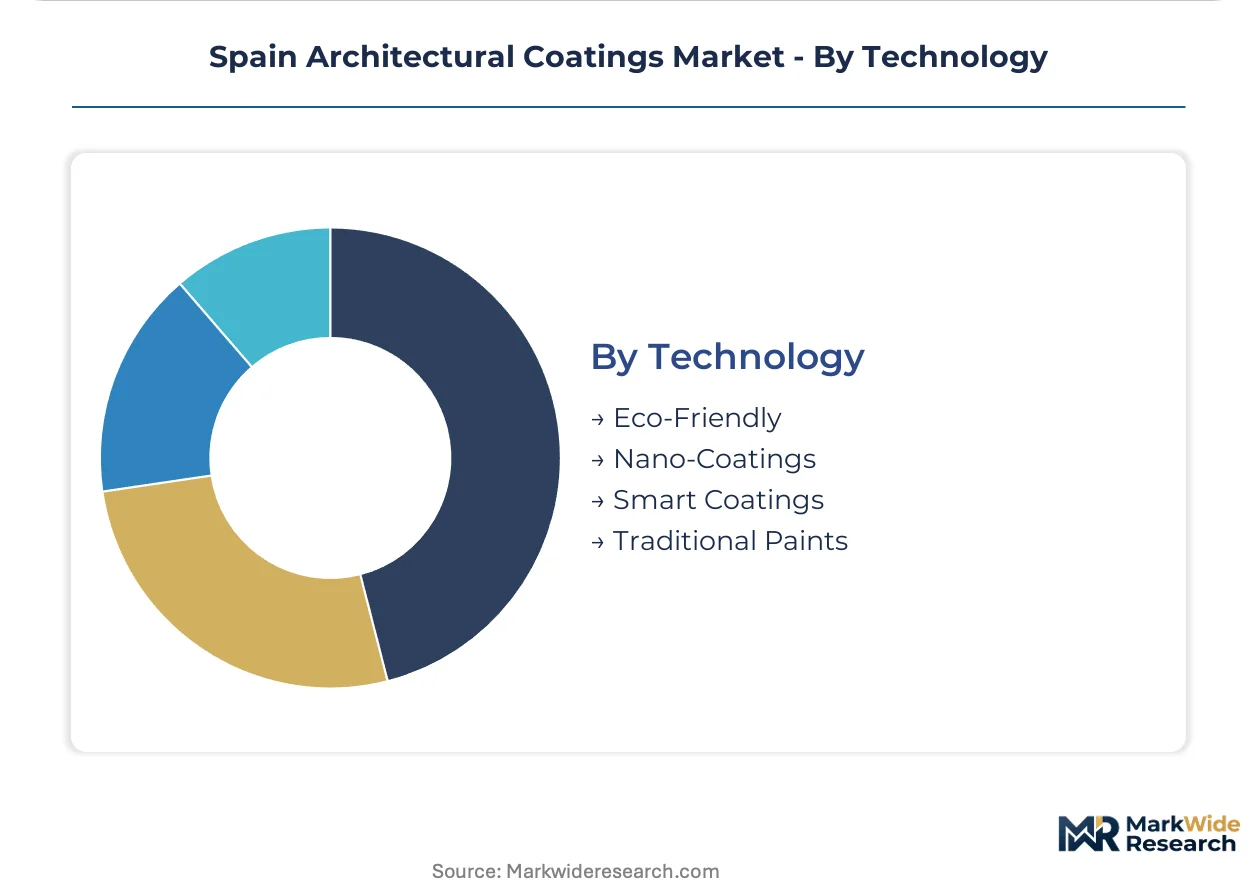
Technology:
Performance tier stratification separates commodity coverage from functional surface engineering, with regulatory pressure accelerating premium tier expansion.
- Eco-Friendly:Bio-based binders and low-VOC formulations respond to EU Green Deal procurement guidelines. Limited domestic alkyd resin production exposes formulators to Northern European supply concentration.
- Nano-Coatings:Self-cleaning and anti-graffiti surface treatments command contractor premiums across Mediterranean coastal developments. ECHA titanium dioxide nanoparticle evaluations impose registration burdens extending time-to-market.
- Smart Coatings:Thermochromic and photochromic formulations remain nascent in architectural applications. Thermal cycling durability testing under Spain's diverse climatic zones constrains immediate specification adoption.
- Traditional Paints:Conventional acrylic and alkyd systems serve cost-sensitive renovation segments. Water-based emulsion displacement compresses remaining volume to exterior wood and metal substrate protection.
Traditional formulations retain renovation volume; nano-engineered surfaces gain share fastest as facade maintenance reduction commands property manager attention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's Special Economic Zones for port logistics and industrial development accelerate coating formulation distribution across Iberian manufacturing corridors.
Madrid
Multi-family housing permits in the metropolitan corridor outpace national construction averages by substantial margins. The Technical Building Code enforces stricter thermal transmittance documentation for exterior facade systems. Alcobendas and Tres Cantos industrial parks host formulation blending facilities serving central Spain's renovation contractors.
Catalonia
Barcelona commercial developers specify nano-enhanced coatings for premium multi-family projects at accelerating rates. Municipal pre-submittal requirements for coating performance documentation compress project timelines. The Port of Barcelona logistics zone enables rapid distribution of water-based emulsions across Mediterranean coastal developments.
Andalusia
High UV intensity across southern Spain generates premium demand for advanced UV-degradation protection in exterior systems. Andalusian regional building codes align with CTE thermal performance mandates for energy-efficient facade upgrades. Seville and Málaga construction clusters concentrate residential renovation activity for infrared-reflective coating specifications.
Basque Country
Industrial-adjacent architectural applications requiring superior moisture resistance sustain solvent-borne formulation demand. Basque regional environmental regulations implement EU Directive 2004/42/CE VOC thresholds with accelerated compliance timelines. Bilbao metropolitan industrial zones anchor cross-border supply chain coordination with French Atlantic port infrastructure.
Valencia
Mediterranean coastal property managers prioritize self-cleaning surface treatments to reduce facade maintenance cycles. Valencia regional building certification schemes adopt CTE thermal reflectance standards ahead of national implementation schedules. The Port of Sagunto chemical logistics hub facilitates raw material receipt for emulsion manufacturers serving Levante construction markets.
Spain Architectural Coatings Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation complexity favoring integrated producers in premium tiers while private-label suppliers capture renovation volume. The vendor base concentrates around four to six established entities with Iberian distribution infrastructure, though nano-coating technology entry is fragmenting the high-performance segment. Two strategic archetypes dominate: multinational chemical conglomerates with color-matching service networks, and regional specialists with cross-border Portuguese-Spanish logistics integration. Competitive moves center on certified applicator network expansion and dual-formulation inventory management during the solvent-borne transition window.
Among multinational coating conglomerates, PPG Industries Inc., AkzoNobel N.V., and Jotun Group occupy positions exemplifying divergent Iberian market penetration strategies. PPG Industries leverages Andalusian and Basque Country infrastructure to anchor contractor loyalty programs across southern and northern Spain. AkzoNobel N.V. sits within the premium-service archetype through Madrid and Barcelona showroom-based color-matching capabilities. Jotun Group represents marine-adjacent architectural specialization, with Mediterranean coastal developments forming its specification concentration zone.
| Leading Market Players |
|---|
| PPG Industries Inc. |
| Jotun Group |
| AkzoNobel N.V. |
| ULMA Architectural Solutions |
| The Barpimo Group |
| CIN S.A. |
| Nippon Paint Holdings Co. Ltd. |
| IVM Chemicals srl |
| DAW SE |
| Others |
Value Network & Pricing Analysis
Water-based emulsion manufacturing transitions across Spanish formulation plants are compressing unit economics while redistributing margin pools toward bio-based binder suppliers in Northern Europe. This production-method shift simultaneously elevates working capital requirements for dual-formulation inventory and concentrates supply leverage among specialty chemical producers with REACH-compliant resin portfolios.
Pricing Analysis
Short-lead-time premiums for CTE-compliant infrared-reflective coatings command contractor markups of twenty to thirty percent above standard emulsion baselines, while spot inventory of legacy solvent-borne alkyd systems trades at distressed clearing levels. Three-tier pricing structure across premium nano-enhanced, standard water-based, and economy solvent-borne tiers separates specification-grade projects from cost-sensitive renovation volume. Price differentiation hinges on certification documentation depth and applicator network density rather than raw material cost alone. Pricing pressure stems from ECHA registration burdens on titanium dioxide nanoparticles, which extend commercialization timelines and compress development-stage returns. Homeowner-directed retail purchases exhibit highest price elasticity, while institutional procurement with extended warranty requirements demonstrates lowest sensitivity.
Supply Chain Analysis
Bio-based alkyd resin supply rests on German, Dutch, and Belgian specialty chemical producers with limited Iberian manufacturing presence. Raw material dependencies center on acrylic monomers, infrared-reflective pigments, and nano-grade titanium dioxide from Northern European and East Asian suppliers. Single-source vulnerability concentrates in REACH-compliant binder streams, where domestic Spanish production capacity remains underdeveloped. Distribution runs through Andalusian and Basque Country regional paint merchants with bundled technical support, displacing traditional merchant-wholesaler relationships across Galicia and Murcia construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's architectural coatings sector is becoming a vertical-integration race, with control over certified applicator networks and captive bio-based resin supply representing the decisive downstream and upstream levers respectively.
For Market Incumbents: Deepen backward integration into bio-based alkyd resin production or secure long-term offtake agreements with Northern European suppliers before REACH restrictions tighten further. Expand certified applicator training infrastructure beyond Madrid and Barcelona metropolitan cores to capture institutional warranty specifications in Valencia and Seville. Defend against nano-coating entrants by accelerating ECHA registration timelines for proprietary titanium dioxide formulations. For New Entrants and Emerging Players: The price-point gap between premium nano-enhanced coatings and economy water-based emulsions offers white-space targeting for mid-tier performance positioning. Focus initial penetration on Andalusian solar-exposure markets where UV-degradation specifications command measurable premiums. Partner with Portuguese-Spanish cross-border distributors to achieve logistics cost parity against established Iberian networks. For Investors and Strategic Acquirers: Exit pathways concentrate in trade-sale acquisition by multinational coating conglomerates seeking CTE-compliant formulation capabilities and Iberian distribution density. Long-term viability favors manufacturers with integrated water-based emulsion capacity and nano-coating registration pipelines. Watch ECHA titanium dioxide evaluation timelines as the critical inflection signal for nano-segment profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Applicator Network Expansion | CTE compliance documentation requirements concentrate specification authority with trained installation labor pools in Madrid and Barcelona corridors. |
| Backward Integration into Bio-Based Resins | Domestic alkyd production reduces import dependency on Northern European suppliers amid REACH hazardous substance restrictions. |
| Nano-Coating Registration Acceleration | ECHA titanium dioxide evaluation timelines determine first-mover positioning in self-cleaning and anti-graffiti premium tiers. |
| Cross-Border Portuguese-Spanish Logistics Integration | Dual-market presence enables cost advantages for manufacturers serving Levante and Algarve construction corridors simultaneously. |
| Infrared-Reflective Pigment R&D Investment | CTE thermal transmittance mandates pull demand toward low-emissivity formulations that reduce building cooling loads. |
Research Methodology
Spanish building permit databases, EU customs trade records for coating raw materials, and SEC filings of multinational chemical conglomerates formed the secondary backbone. Primary interviews with formulation plant managers, procurement leads at Andalusian multi-family developers, distribution channel partners, and certified applicator network coordinators validated demand assumptions. Bottom-up and top-down triangulation reconciled project-level specification data with national construction output statistics.
Bottom-up volume modeling aggregated individual project specifications across Catalonia, Madrid, Andalusia, and Basque Country metropolitan corridors, while top-down constraints applied national CTE compliance adoption curves. Segmentation dimensions included formulation chemistry, project typology, specification authority, and technology tier. CAGRs derived from regression analysis of permit issuance trends and renovation financing accessibility indices. Industry-specific inputs incorporated ECHA registration pipeline status and bio-based resin import volume fluctuations.
Inputs from Spanish Ministry of Transport and Urban Agenda construction statistics were available through the study window; gaps in real-time certified applicator network sizing introduce uncertainty bands around institutional segment forecasts. Forecasts reflect assumptions regarding CTE enforcement consistency and REACH implementation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Construction Glass Market
Building Materials
Concrete Market
Building Materials
Recycled Concrete Aggregates Market
Building Materials
India Concrete Admixtures Market
Building Materials
Natural Stone Slab Market
Building Materials
US Contract Glazing Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Blended Cement Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Steel Slag Market
Building Materials
United States White Cement Market
Building Materials
Long Steel Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Australia Architectural Coatings Market
Building Materials
Construction Coatings Market
Building Materials
Refractory Cement Market