
 Sawn and Profiled Wood Products Market | 2026-2036
Sawn and Profiled Wood Products Market Size, Share, and Industry Trends Forecast 2026-2036
Sawn and Profiled Wood Products Market Analytics
Market Context
Canadian softwood lumber producers is recalibrating output after British Columbia's beetle-kill harvest wind-down. West Fraser Timber Co. leverages its integrated pulp and lumber network across Alberta and the US South. Weyerhaeuser Company anchors its position through controlled timberland holdings in the Pacific Northwest. Stora Enso differentiates via cross-laminated timber and biobased material R&D in Nordic markets.
Technical Definition and Structural Segments
Sawn and profiled wood products encompass dimensional lumber, engineered boards, and machined profiles cut from logs then surfaced to precise tolerances for load-bearing or decorative applications. Moisture content, grade stamps, and dimensional stability determine fitness for structural frames, interior finishes, or industrial crating. Lumber dominates value flows in residential framing, while oriented strand board captures share in sheathing as mills achieve higher resin efficiency and faster press cycles. Appearance-grade veneer commands premium pricing in furniture and architectural millwork, whereas industrial-grade plywood serves concrete forming and transport packaging with thinner margin pools.
Regulatory Frame and Outlook
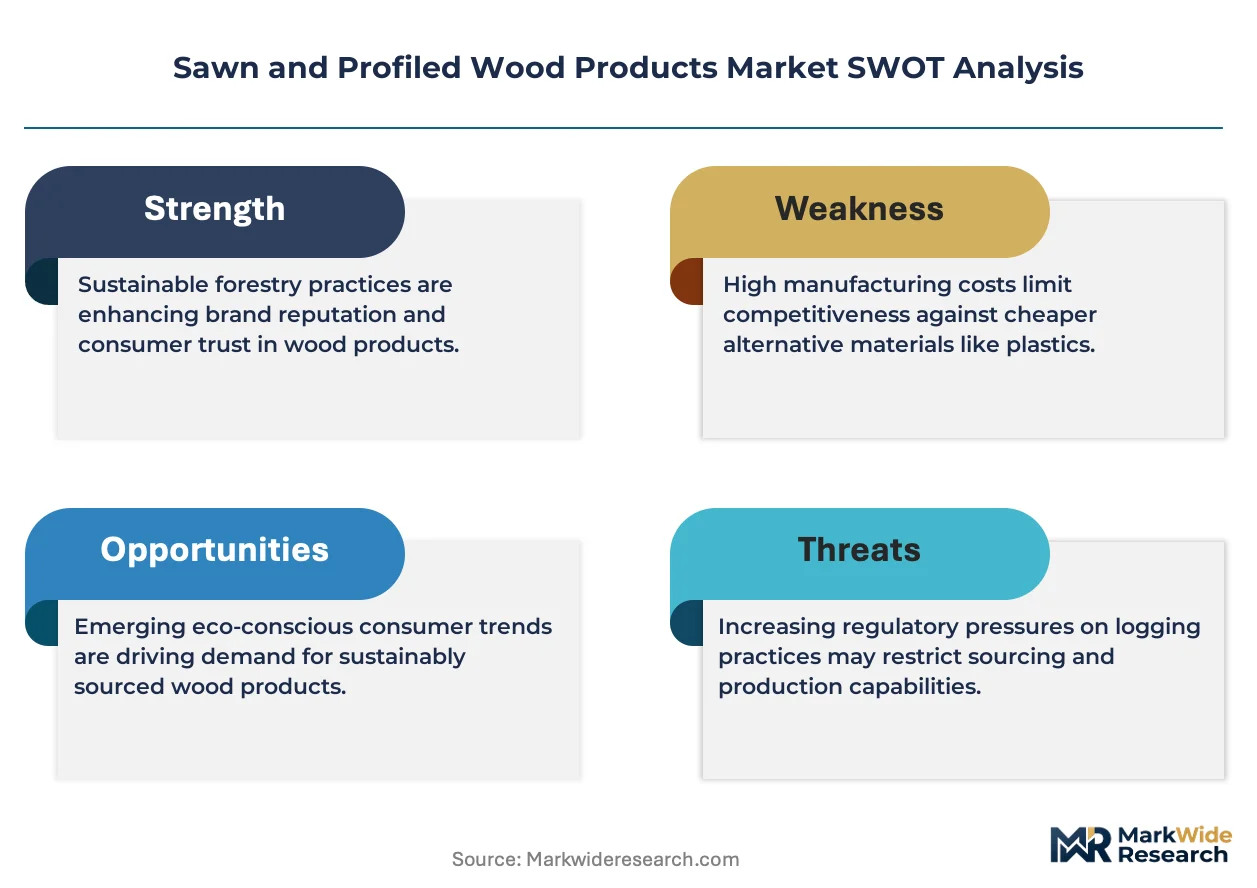
USDA grading rules, EPA treated-wood standards, and EU Timber Regulation enforcement shape product certification and market access across Atlantic trade corridors. The EU Deforestation Regulation and US Lacey Act amendments tighten chain-of-custody documentation, pressuring tropical hardwood substitution and certified-sourcing premiums. Stakeholders must monitor bioeconomy policy shifts and mass-timber building code adoptions that redirect structural demand toward engineered sawn products.
Market Dynamics
The EU Deforestation Regulation is compressing tropical hardwood sourcing channels while engineered wood substitution accelerates in residential framing across multiple geographies. This regulatory pivot is forcing mills to reconfigure supply chains toward certified temperate species and domestic plantation timber.
Growth Catalysts
- Mass-timber building codes:US jurisdictions adopting Type IV-C construction standards are expanding engineered lumber absorption in mid-rise commercial projects. Cross-laminated timber and glue-laminated beams gain structural approval in California, Washington, and Oregon.
- EU Green Deal bioeconomy incentives:Horizon Europe funding streams and national recovery plans are channeling capital toward Nordic sawmill automation and biobased material R&D clusters in Finland and Sweden.
- Carbon-conscious procurement mandates:Large-scale developers in Germany and the Netherlands are specifying EPD-certified structural timber for Scope 3 emission reductions, creating premium pull for Black Forest and Scandinavian sawn products.
Market Restraints
- Input cost volatility:Resin and adhesive prices fluctuate with petrochemical feedstock markets, compressing margins for OSB and engineered board producers dependent on phenol-formaldehyde chemistry.
- Supply concentration risk:British Columbia's beetle-kill harvest wind-down has removed millions of cubic meters of low-cost spruce-pine-fir from Pacific Rim trade flows, tightening North American softwood availability.
- Regulatory friction:The EU Deforestation Regulation's traceability requirements impose documentation burdens on tropical hardwood importers, extending lead times and raising compliance costs for African and Southeast Asian species.
Strategic Opportunities
- Underpenetrated modular construction:Japan's push for disaster-resilient housing and hotel sector expansion creates demand for precision-cut, moisture-controlled dimensional lumber from automated profiling lines.
- Regulatory tailwind:France's RE2020 environmental regulation mandates lifecycle carbon assessments for new buildings, advantaging locally sourced sawn timber over steel and concrete structural systems.
- Technology convergence:Robotics integration with computer vision grading systems is enabling real-time defect detection and automated sorting, opening service contracts to smaller sawmills lacking capital for full line upgrades.
Industry Challenges
- Certification timeline compression:Chain-of-custody audits for FSC and PEFC certification require 12-18 month implementation cycles, delaying market access for mills transitioning from conventional to verified sourcing.
- Skill gaps in automation operation:Sawmill technician roles now demand PLC programming and predictive maintenance competencies that legacy workforce pipelines do not supply, constraining line utilization rates.
Report Scope
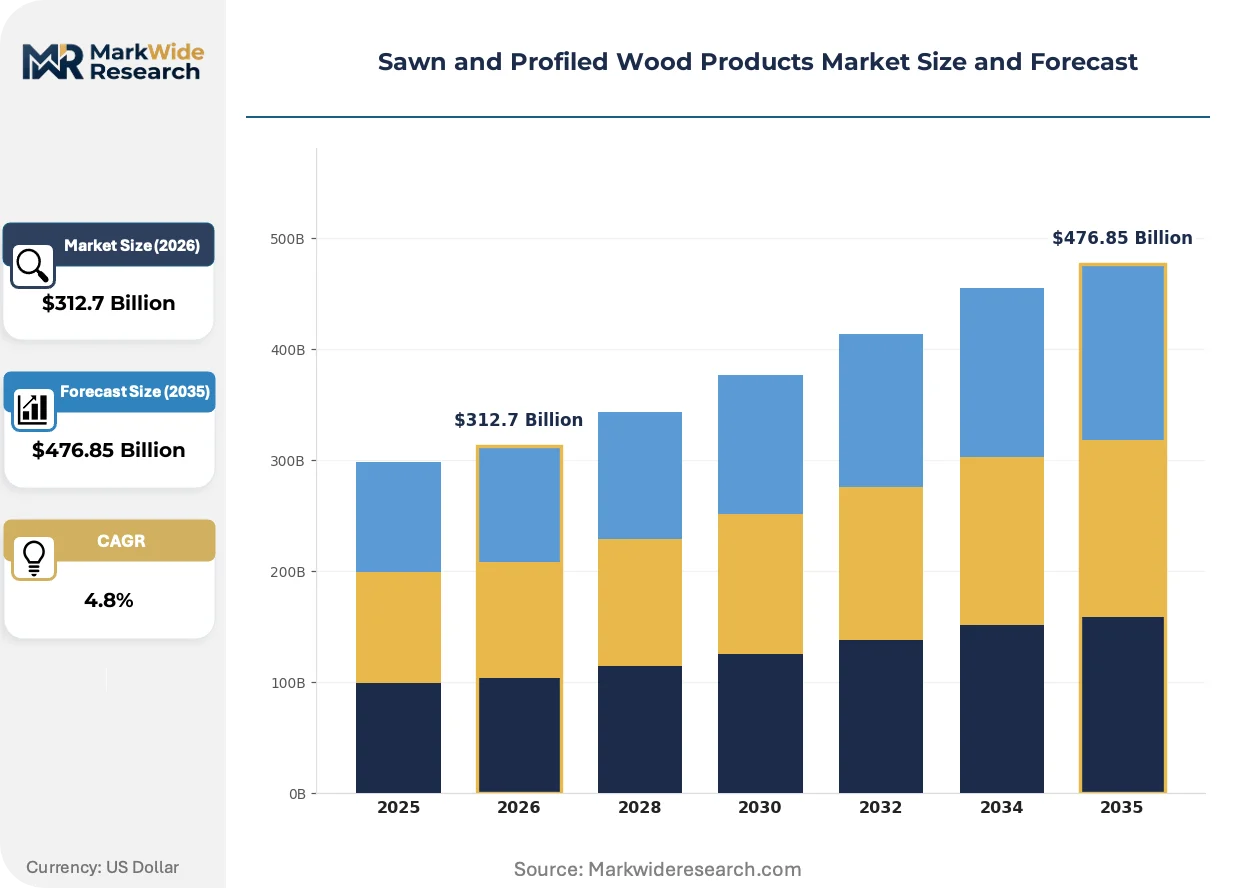
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sawn and Profiled Wood Products Market |
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $476.85 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lumber, Plywood, Veneer, Oriented Strand Board End User: Construction, Furniture, Flooring, Packaging Grade: Structural, Appearance, Industrial, Marine Technology: Sawmilling, Laminating, Drying, Treating |
| Companies Covered | West Fraser Timber Co., Weyerhaeuser Company, Stora Enso, Canfor Corporation, Georgia-Pacific, Interfor Corporation, Sierra Pacific Industries, UPM-Kymmene, Moelven Industrier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sawn and Profiled Wood Products Market Evolving Landscape
Automation and digitization are reconfiguring how sawmills convert logs to finished profiles, with implications for labor models, quality consistency, and capital deployment timelines. Three developments are reshaping competitive capabilities.
Robotic lumber handling and AI-driven moisture detection systems are electrifying traditional sawline workflows. German and Austrian equipment manufacturers are deploying these integrated systems across Central European mills. The technology is compressing labor requirements per thousand board feet while raising grade recovery rates.
REACH chemical restrictions and pending revisions to wood preservative authorizations are tightening biocide options for outdoor-grade lumber. European producers face reformulation costs for creosote alternatives and copper-based treatments. The pressure is accelerating heat-treatment and acetylation adoption for decking and cladding applications.
Builder procurement patterns are consolidating around integrated structural systems rather than commodity lumber purchases. US national homebuilders are negotiating direct mill relationships for pre-cut framing packages, bypassing traditional distribution yards. The shift is most visible in Texas and Florida markets where production housing volume concentrates.
Sawn and Profiled Wood Products Market Segmentation
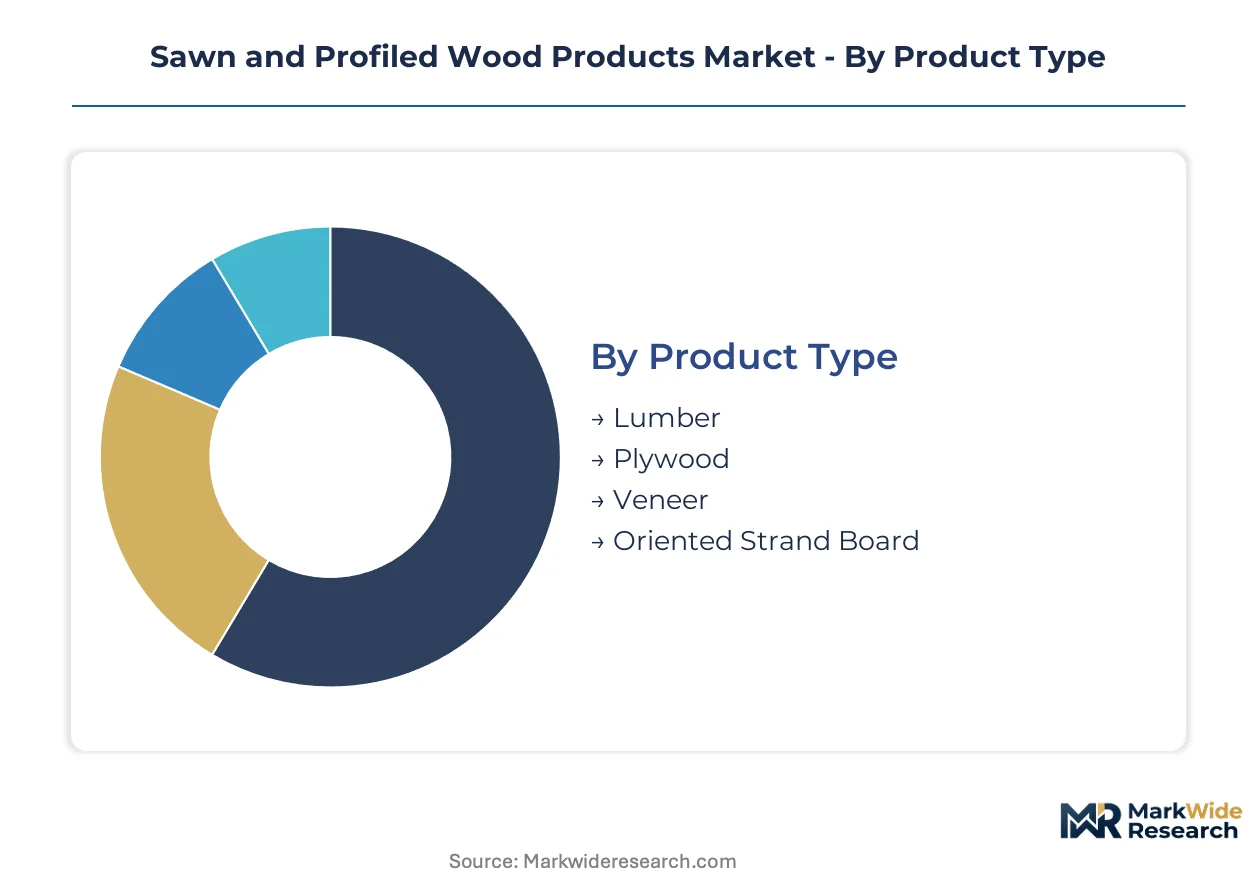
Segmentation in sawn and profiled wood products determines procurement specifications, certification requirements, and margin structures. Buyers prioritize dimensional tolerances, moisture content, and chain-of-custody documentation based on end-use application.
Product Type:
Cost tier separates commodity buyers from specification-driven purchasers seeking engineered performance.
- Lumber:Dimensional softwood and hardwood boards graded for structural integrity, moisture content, and warp resistance. Residential framing in the United States and Canada absorbs high volumes as builders substitute engineered lumber for steel studs in mid-rise construction.
- Plywood:Cross-laminated veneer sheets bonded with phenol-formaldehyde or soy-based adhesives, prized for shear strength and dimensional stability. Concrete forming and transport crating in Germany and Japan concentrate demand where reusable panel cycles justify premium pricing over OSB alternatives.
- Veneer:Thin rotary-cut or sliced sheets for decorative surfacing and plywood cores.
- Oriented Strand Board:Flake-based panels engineered for wall sheathing and roof decking with resin-optimized press cycles.
Volume sits with lumber; growth tilts toward oriented strand board.
End User:
Application determines grade specifications, certification thresholds, and supply chain documentation intensity.
- Construction:Structural framing, sheathing, and mass-timber systems for residential and commercial buildings. Cross-laminated timber projects in Washington, Oregon, and British Columbia are expanding engineered lumber absorption as Type IV-C building codes gain adoption.
- Furniture:Appearance-grade hardwoods and decorative veneers for cabinet, millwork, and fixture manufacturing. Precision-cut Black Forest sawn products serve Central European manufacturers demanding tight dimensional tolerances for automated assembly lines.
- Flooring:Tongue-and-groove profiled boards and engineered plank systems.
- Packaging:Industrial-grade softwood and plywood for crating, pallets, and transport protection.
Construction commands absolute volume; furniture claims the steepest expansion trajectory as carbon-conscious procurement mandates spread.
Grade:
Margin stratification follows certification burden and visual defect tolerance.
- Structural:Load-bearing lumber and engineered products graded for strength, stiffness, and connection capacity. US jurisdictions adopting mass-timber building codes are expanding absorption of EPD-certified structural timber as developers target Scope 3 emission reductions.
- Appearance:Clear, select, and premium grades with minimal knots and uniform color for visible applications. Architectural millwork in France and the Netherlands specifies FSC-certified appearance hardwoods to satisfy RE2020 lifecycle carbon assessment requirements.
- Industrial:Utility grades for crating, blocking, and non-structural applications.
- Marine:Pressure-treated or naturally durable species for waterfront and salt-exposure environments.
Structural grade dominates tonnage; appearance grade captures premium expansion as green procurement tightens.
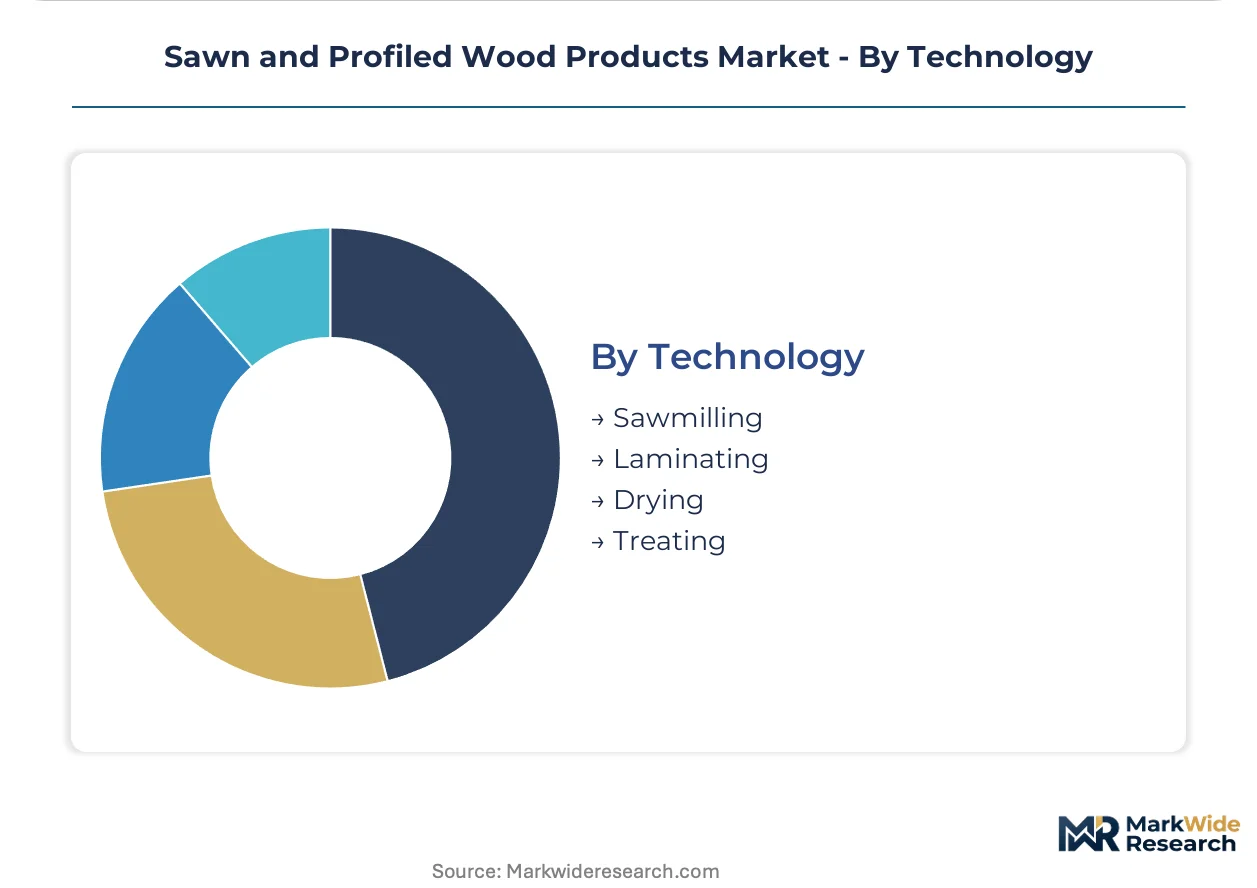
Technology:
Customer type differentiates capital-intensive integrated mills from specialized processors.
- Sawmilling:Primary log breakdown into dimensional lumber through bandsaw or circular saw systems. Automated profiling lines in Germany's Black Forest cluster serve furniture manufacturers with real-time defect detection and robotic sorting.
- Laminating:Adhesive bonding of veneers, strands, or solid sections into engineered products. Glue-laminated beam and cross-laminated timber capacity in Finland and Sweden is expanding through Horizon Europe bioeconomy funding streams.
- Drying:Kiln and air-drying processes to target moisture content for end-use stability.
- Treating:Chemical or thermal modification for decay resistance and dimensional stability.
Sawmilling anchors volume throughput; laminating is climbing the fastest as mass-timber codes proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
British Columbia's beetle-kill harvest wind-down has reshaped softwood flows across Pacific Rim trade corridors. Mills in Alberta and the US South now absorb displaced volume as coastal Canadian capacity contracts.
United States
Residential builders in Texas and Florida negotiate direct mill relationships for pre-cut framing packages, bypassing distribution yards. The EPA's treated-wood standards govern preservative formulations for outdoor applications. Automated profiling lines in the Pacific Northwest serve national homebuilders with moisture-controlled dimensional lumber.
Germany
France's RE2020 regulation mandates lifecycle carbon assessments for new buildings, pulling specification-grade sawn timber across the Rhine. The EU Deforestation Regulation tightens chain-of-custody documentation for tropical hardwood substitution. The Black Forest sawmilling cluster deploys real-time defect detection systems for Central European furniture manufacturers.
Canada
Alberta mills expand output as British Columbia's beetle-kill harvest concludes. Health Canada and the PMRA oversee wood preservative registrations for domestic and export markets. West Fraser Timber Co. leverages integrated pulp and lumber networks across Alberta and the US South.
Sweden
Horizon Europe bioeconomy funding streams channel capital toward glue-laminated beam and cross-laminated timber capacity expansion. The EU Green Deal incentivizes Nordic sawmill automation and biobased material R&D. Stora Enso anchors engineered wood innovation through controlled Nordic timberland holdings.
Japan
Disaster-resilient housing programs and hotel sector expansion drive demand for precision-cut dimensional lumber. METI building codes govern structural timber approvals for mid-rise construction. Automated profiling lines from European equipment manufacturers serve Japanese modular construction projects.
Sawn and Profiled Wood Products Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue mass-timber engineering and biobased material specialization. The vendor base clusters around integrated timberland owners, regional sawmill operators, and engineered wood technology developers. Three archetypes dominate: capital-intensive integrated forest products groups, automated specialty mills serving furniture and millwork, and Nordic biobased material innovators. Competitive moves concentrate on strategic timberland acquisitions and cross-laminated timber capacity expansion.
Among North American integrated producers, West Fraser Timber Co., Weyerhaeuser Company, and Canfor Corporation exemplify the timberland-anchored archetype. West Fraser Timber Co. represents the Alberta-US South operational model. Weyerhaeuser Company occupies a position tied to Pacific Northwest resource control. Canfor Corporation sits within the coastal British Columbia capacity base adjusting to beetle-kill harvest conclusions.
| Leading Market Players |
|---|
| West Fraser Timber Co. |
| Weyerhaeuser Company |
| Stora Enso |
| Canfor Corporation |
| Georgia-Pacific |
| Interfor Corporation |
| Sierra Pacific Industries |
| UPM-Kymmene |
| Moelven Industrier |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FSC-certified structural timber and commodity-grade dimensional lumber manifests in both price premiums and supply chain complexity. Buyers of certified Black Forest and Scandinavian sawn products absorb documentation costs and extended lead times, while commodity lumber flows through spot-market channels with minimal chain-of-custody overhead.
Pricing Analysis
Service-bundling separates integrated mill-direct contracts from unbundled distribution-yard purchases. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden, moisture control precision, and automated grading integration. Pricing pressure stems from resin and adhesive cost volatility in OSB and engineered board segments. National homebuilders in Texas and Florida demonstrate lowest price sensitivity through direct mill relationships, while regional contractors in spot markets exhibit highest sensitivity to dimensional lumber fluctuations.
Supply Chain Analysis
Dual-sourcing requirements from EU Deforestation Regulation compliance push tropical hardwood importers toward certified temperate species from Germany, Sweden, and Canada. Raw material flows draw from British Columbia residual spruce-pine-fir, Alberta plantation timber, and Nordic controlled forestlands. Single-source vulnerability concentrates in beetle-kill harvest wind-down regions. Distribution runs through integrated mill-direct channels for national builders and traditional lumberyard networks for regional contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sawn and profiled wood products sector sits in a technology-transition phase where AI-driven moisture detection and robotic grading systems displace manual inspection workflows.
For Market Incumbents: Anticipate margin compression from automated profiling line entrants by anchoring timberland control in Alberta and the US South. Invest in cross-laminated timber capacity expansion ahead of Type IV-C code adoptions in Washington and Oregon. Certification investment in FSC chain-of-custody systems defends access to RE2020-mandated French construction procurement. For New Entrants and Emerging Players: Begin with precision-cut dimensional lumber for Japan's disaster-resilient modular housing programs, where European equipment manufacturers lack direct service presence. Target white-space in automated grading service contracts for smaller Black Forest sawmills lacking capital for full line upgrades. Go-to-market leverage rests on PLC programming and predictive maintenance competency partnerships. For Investors and Strategic Acquirers: Exit pathways concentrate in Nordic biobased material innovators with Horizon Europe funding validation and controlled timberland positions. Long-term viability across the analysis window favors integrated producers with backward integration into pulp networks and captive adhesive supply. Watch mass-timber building code adoption velocity in California as inflection signal for engineered lumber demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Laminated Timber Capacity Expansion | Type IV-C code adoption in Washington and Oregon pulls structural approval for mid-rise commercial projects. |
| Automated Profiling Line Deployment | Robotic sorting and real-time defect detection compress labor requirements per thousand board feet in Black Forest mills. |
| FSC Chain-of-Custody Certification | RE2020 lifecycle carbon assessments in France mandate verified sourcing for architectural millwork specifications. |
| Backward Integration into Resin Supply | Phenol-formaldehyde cost volatility hedging secures margin stability for OSB and engineered board producers. |
| Direct Mill-Homebuilder Partnership | Pre-cut framing packages in Texas and Florida bypass distribution yards and capture procurement consolidation value. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with sawmill operations directors, timberland asset managers, furniture manufacturer procurement leads, and building code officials combined with secondary validation from USDA grading rule publications, EPA treated-wood standard databases, and EU Timber Regulation enforcement reports. Bottom-up volume modeling and top-down value triangulation cross-checked segment-level estimates.
Granularity-level modeling deployed product type, end-use application, grade tier, and technology segments across the projection horizon. CAGRs derived from log supply-demand balance projections, mass-timber code adoption curves, and substitution elasticity estimates for engineered lumber in residential framing. Industry-specific inputs incorporated British Columbia beetle-kill harvest wind-down trajectories and EU Deforestation Regulation compliance cost assumptions.
Underlying measurement precision varies by segment; automated profiling line penetration rates and cross-laminated timber capacity expansion carry tighter precision than tropical hardwood substitution elasticities. Forecasts reflect documented assumptions on resin price normalization and Nordic bioeconomy funding continuity. Deviation in Type IV-C building code adoption velocity or EU Deforestation Regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asphalt Market
Building & Construction Materials
Prefabricated Bathroom Modules Market
Building & Construction Materials
Red Brick Market
Building & Construction Materials
Asphalt Modifiers Market
Building & Construction Materials
Ball Iron Rods Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
Europe Construction Repair and Rehabilitation Chemicals Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
Tile Grout Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Garage Doors Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
United States Roofing Market