
 Asia-Pacific Particle Board Market | 2026-2036
Asia-Pacific Particle Board Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Particle Board Market Outlook
Southeast Asian particle board production capacity is consolidating around integrated forestry-plantation operators. Greenlam Industries Ltd leverages captive resin supply and laminate finishing lines to command premium positioning in India's decorative surfaces segment. CenturyPly sustains multi-brand distribution across tier-2 and tier-3 Indian cities through dedicated dealer networks. Bangkok Master Wood Co. Ltd anchors Thailand's supply to Japanese furniture OEMs with JIS-compliant emission controls.
Particle board comprises wood particles bonded with synthetic resin under heat and pressure, typically achieving densities of 600-800 kg per cubic meter for standard-grade panels. Manufacturers engineer these panels as substrate cores for laminated flooring, kitchen cabinetry, and ready-to-assemble furniture where dimensional stability outweighs solid timber costs. Melamine-faced product types dominate volume throughput across Asia-Pacific fabrication lines, though veneered grades capture disproportionate margin pools in high-end contract interiors. Raw particle board competes aggressively on price in India's mass housing segment where builders prioritize cost per square meter over surface finish quality.
India's BIS mandates formaldehyde emission limits under IS 17021, while China's GB standards enforce density and moisture-content thresholds through SAMR inspection protocols. Japan's JIS A 5908 certification creates a technical barrier for regional exporters serving METI-registered supply chains. Stakeholders must track evolving EUDR-equivalent due diligence requirements as European buyers extend compliance expectations to Asia-Pacific panel sourcing.
Market Dynamics
India's BIS formaldehyde emission standards are compressing the supplier base while Vietnam's manufacturing corridor draws capacity investment from furniture OEMs seeking JIS-compliant panel supply.
Growth Catalysts
- Residential construction acceleration:Southeast Asian housing starts are expanding procurement of engineered wood panels as urbanization drives kitchen cabinetry and ready-to-assemble furniture demand.
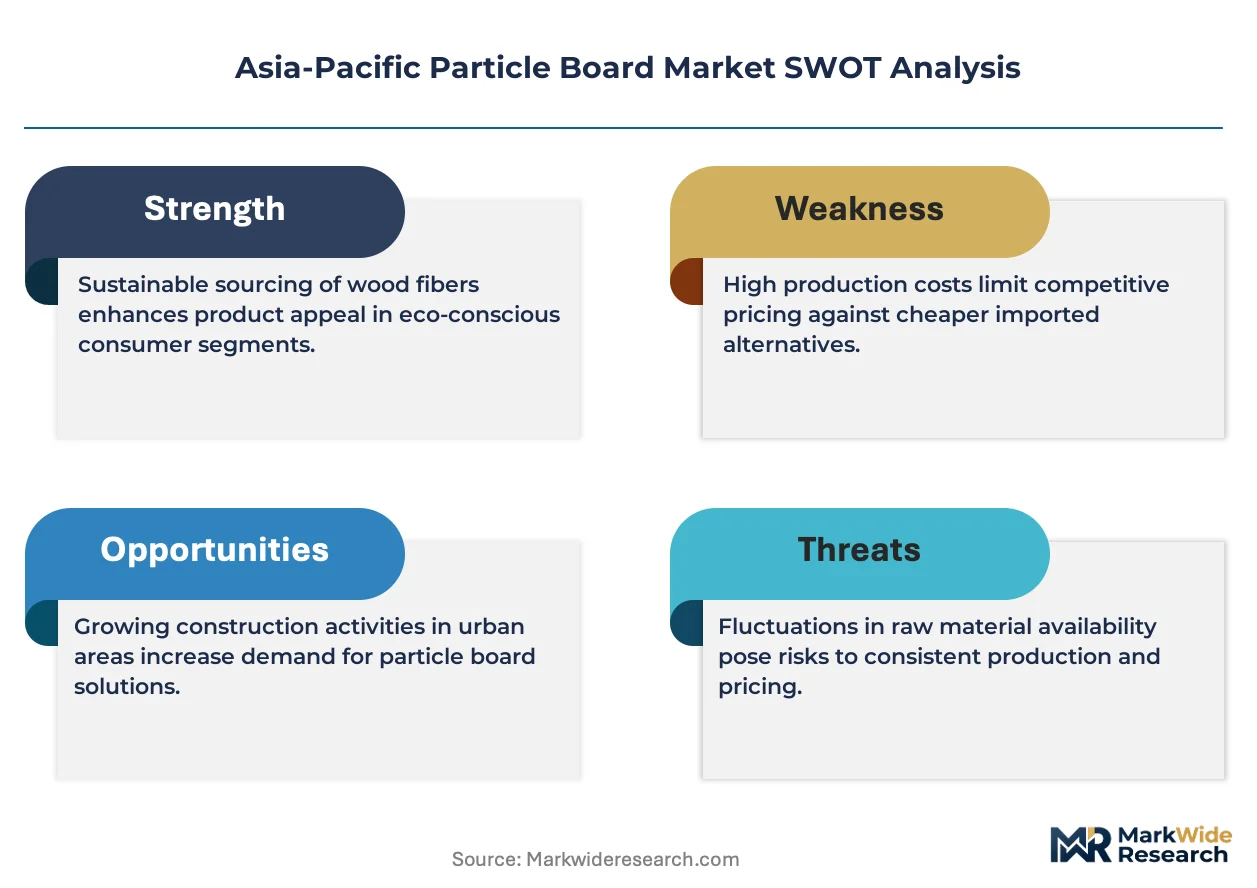
- BIS certification tightening:India's IS 17021 mandates are eliminating substandard producers and concentrating volume among certified manufacturers with captive resin and laminate finishing capabilities.
- Japanese OEM compliance sourcing:METI-registered supply chains are pulling Thailand and Vietnam facilities toward JIS A 5908 certification to serve furniture export contracts.
Market Restraints
- Urea-formaldehyde resin cost volatility:Petrochemical feedstock fluctuations compress margins for standard-grade panel producers without backward integration into chemical manufacturing.
- Supply concentration in Mekong Delta:Vietnam's particle board capacity clusters near Ho Chi Minh City, creating logistics vulnerability for buyers in northern ASEAN markets.
- Medium-density fiberboard substitution:MDF panels with superior machinability are displacing particle board in high-end kitchen cabinetry specifications across Indian metro markets.
Strategic Opportunities
- Indonesian archipelago penetration:Kalimantan and Sulawesi construction markets remain underpenetrated by certified panel distributors serving residential developers outside Java.
- EUDR-equivalent due diligence:European buyer compliance expectations are creating premium pricing tiers for Asia-Pacific mills with verified sustainable forestry chain-of-custody documentation.
- Melamine-faced panel convergence:Decorative surface lamination integrated with substrate production is unifying supply chains and capturing margin pools previously split between separate processors.
Industry Challenges
- Resin chemistry technical talent scarcity:Formulation expertise for low-emission adhesive systems remains concentrated among a narrow cohort of chemical engineers in Thailand and Malaysia.
- Continuous press line capex intensity:Modern particle board manufacturing requires substantial capital deployment for automated forming and pressing equipment with extended depreciation timelines.
- JIS A 5908 certification timeline compression:Japanese OEM qualification protocols demand extended testing cycles that delay revenue recognition for new facility ramp-ups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Particle Board Market |
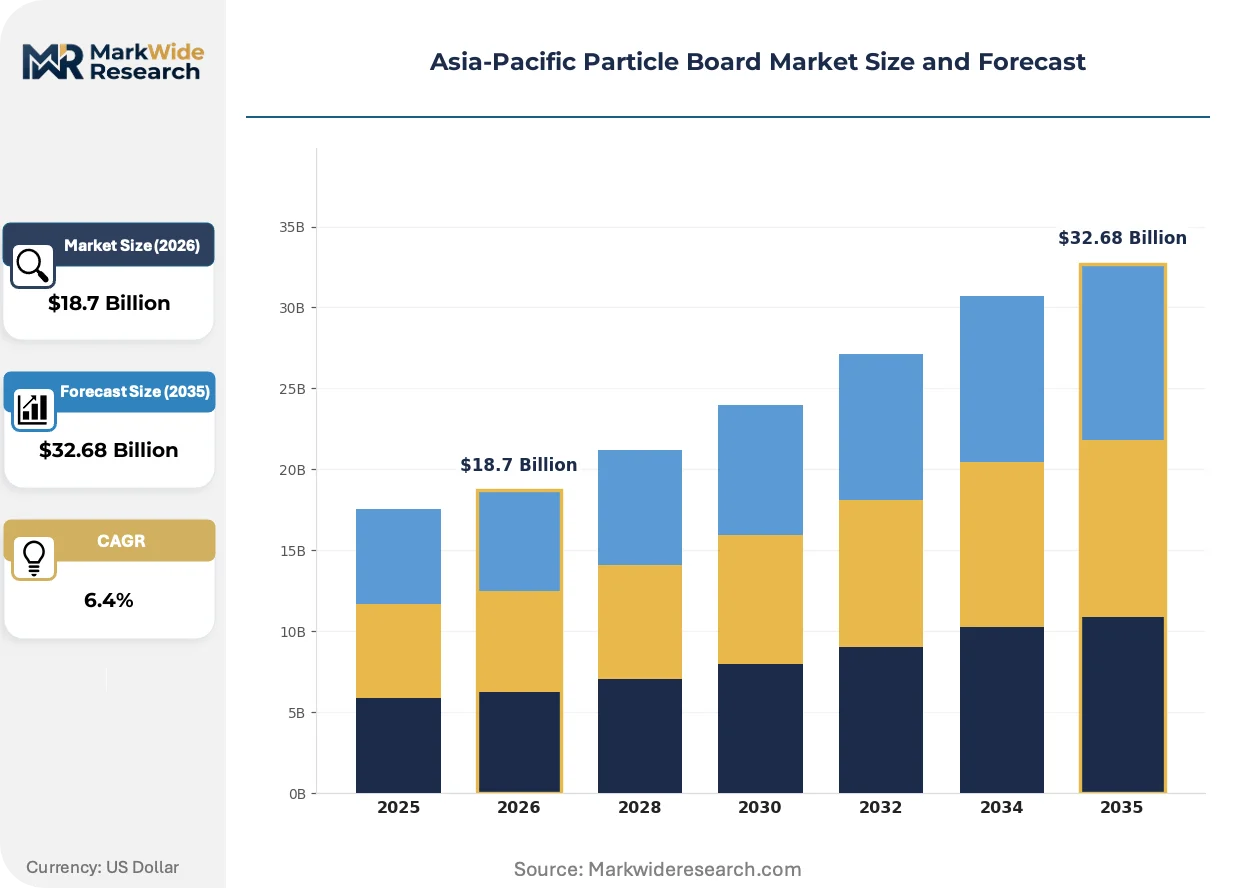
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Melamine Faced, Veneered, Raw, Laminated End User: Furniture Manufacturers, Construction, Interior Design, Cabinetry Thickness: 9mm, 12mm, 15mm, 18mm Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Greenlam Industries Ltd, Bangkok Master Wood Co. Ltd, CenturyPly, Green River Holding Co. Ltd, DareGlobal Wood, Fletcher Building, Wanhua Ecoboard Co Ltd, Foshan Jujian Yifang Trading Co. Ltd, Metro Particle Co Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Particle Board Market Strategic Shifts
Digital process control and sustainable chemistry are compressing emission profiles while reshaping procurement relationships between panel producers and furniture manufacturers across ASEAN supply chains.
Continuous press technology with real-time density profiling is unifying quality consistency across high-volume production runs. Malaysian and Thai facilities serving Japanese furniture OEMs are adopting these systems to maintain JIS A 5908 compliance with minimal batch variation. The technology is unifying previously fragmented quality tiers into standardized output streams that reduce downstream lamination waste.
China's GB standards enforcement through SAMR inspection protocols is tightening density and moisture-content thresholds for panel imports. Manufacturers serving cross-border trade are retrofitting drying lines and weight-control systems to avoid shipment detention at port. Indian producers exporting to China face the most acute compliance pressure as GB testing frequency intensifies in coastal customs zones.
Buyers are consolidating vendor relationships around integrated substrate-to-laminate suppliers capable of single-source accountability. Furniture OEMs in Vietnam's manufacturing corridor are reducing approved supplier lists from multiple raw panel and separate laminators toward captive finishing operations. This concentration is most visible in Ho Chi Minh City's industrial zones where Japanese and South Korean contract manufacturers dominate procurement decision-making.
Asia-Pacific Particle Board Market Segmentation
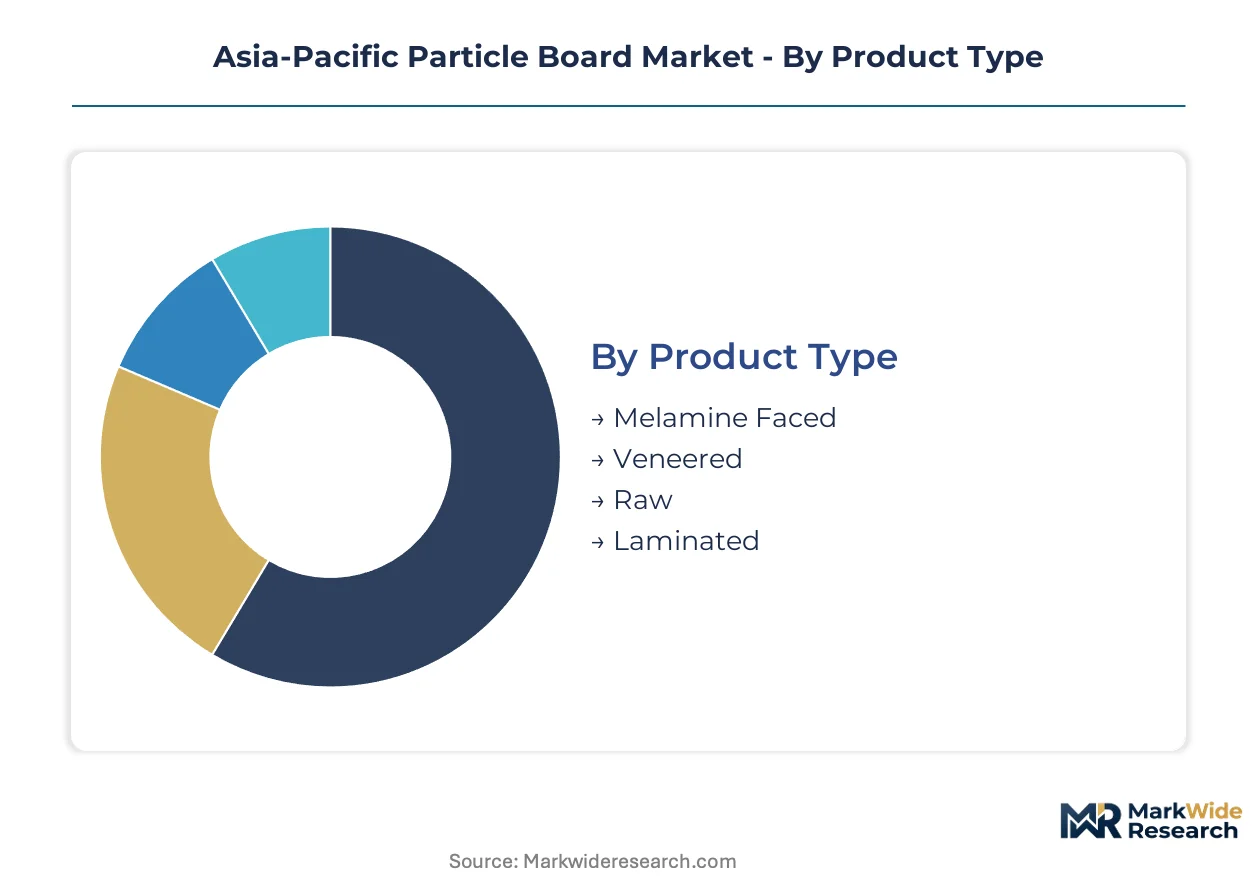
Particle board segmentation across Asia-Pacific reflects divergent cost-performance tradeoffs between commodity construction applications and precision-finished furniture manufacturing. Buyers in Vietnam's manufacturing corridor and India's tier-2 cities are fragmenting procurement patterns across multiple specification tiers simultaneously.
Product Type:
Volume throughput concentrates in surface-finished grades serving export furniture OEMs, while raw panels dominate India's mass housing cost calculations. Premium positioning requires integrated lamination capabilities that few regional mills possess.
- Melamine Faced:Thermoset resin-impregnated decorative paper bonded under heat and pressure creates scratch-resistant surfaces for kitchen cabinetry and ready-to-assemble furniture. Ho Chi Minh City's Japanese contract manufacturers specify these panels for METI-registered export supply chains requiring JIS A 5908 substrate compliance. Demand concentrates where single-source accountability reduces downstream processing waste.
- Veneered:Thin hardwood slices laminated to particle board cores deliver aesthetic warmth for high-end contract interiors and hospitality fit-outs. Bangkok Master Wood Co. Ltd anchors Thailand's supply to Japanese furniture OEMs with JIS-compliant emission controls and premium-grade veneer sourcing. Margin pools here exceed standard-grade panels by substantial multiples.
- Raw:Unfinished particle board competes aggressively on price per square meter in India's mass housing segment where builders prioritize structural substrate cost over surface quality. BIS IS 17021 certification mandates are compressing the supplier base for emission-compliant raw grades.
- Laminated:Post-formed decorative surfaces applied after panel manufacturing serve regional fabricators without captive finishing lines. Distribution runs through dedicated dealer networks in India's tier-3 cities where CenturyPly sustains multi-brand coverage.
Mature deployment sits with Melamine Faced panels. Newer deployment is concentrated in Veneered grades as Japanese OEM compliance sourcing pulls Thailand and Vietnam facilities toward premium finishing capabilities.
End User:
Furniture manufacturers command the largest procurement volumes, though construction sector purchasing is fragmenting across project-scale and retail distribution channels.
- Furniture Manufacturers:Engineered wood panel procurement is expanding across Southeast Asia as residential construction accelerates urbanization-driven demand for kitchen cabinetry and ready-to-assemble furniture. Greenlam Industries Ltd leverages captive resin supply and laminate finishing lines to serve this segment with premium positioning in India's decorative surfaces market.
- Construction:Builders specify raw particle board for interior partitioning and temporary formwork where dimensional stability outweighs solid timber costs. India's mass housing segment prioritizes cost per square meter, compressing margins for non-certified producers.
- Interior Design:Contract specifications for commercial fit-outs and hospitality projects demand veneered and custom-laminated grades with verified chain-of-custody documentation. EUDR-equivalent due diligence requirements from European buyers are creating premium pricing tiers for compliant mills.
- Cabinetry:Kitchen and storage system fabricators in Vietnam's manufacturing corridor are consolidating vendor relationships around integrated substrate-to-laminate suppliers. Medium-density fiberboard substitution is displacing particle board in high-end Indian metro market specifications.
Procurement concentration is deepest among Furniture Manufacturers. Construction sector purchasing is expanding most quickly as India's residential construction acceleration drives panel consumption.
Thickness:
Standardization around modular furniture dimensions has compressed the specification range, with 18mm panels commanding disproportionate volume share in cabinetry applications.
- 18mm:Structural rigidity for load-bearing cabinetry and shelving systems makes this the default specification for kitchen and wardrobe manufacturers across ASEAN. Real-time density profiling on continuous press lines maintains JIS A 5908 compliance consistency for Japanese OEM supply.
- 15mm:Intermediate thickness serves non-structural interior applications and cost-optimized furniture where weight reduction offsets stiffness requirements. Indian tier-2 city distributors stock this grade for mid-market residential projects.
- 12mm:Lightweight panels suit drawer bottoms, back panels, and ready-to-assemble furniture components where assembly hardware provides structural integrity. GB standards enforcement through SAMR inspection protocols is tightening density thresholds for cross-border trade in this specification.
- 9mm:Thinnest standard grade serves packaging, temporary protection, and low-cost interior surfacing applications. Margins here are most vulnerable to urea-formaldehyde resin cost volatility.
Volume leadership resides with 18mm panels. Thinnest grades are gaining share fastest in India's cost-sensitive mass housing segment.
Distribution Channel:
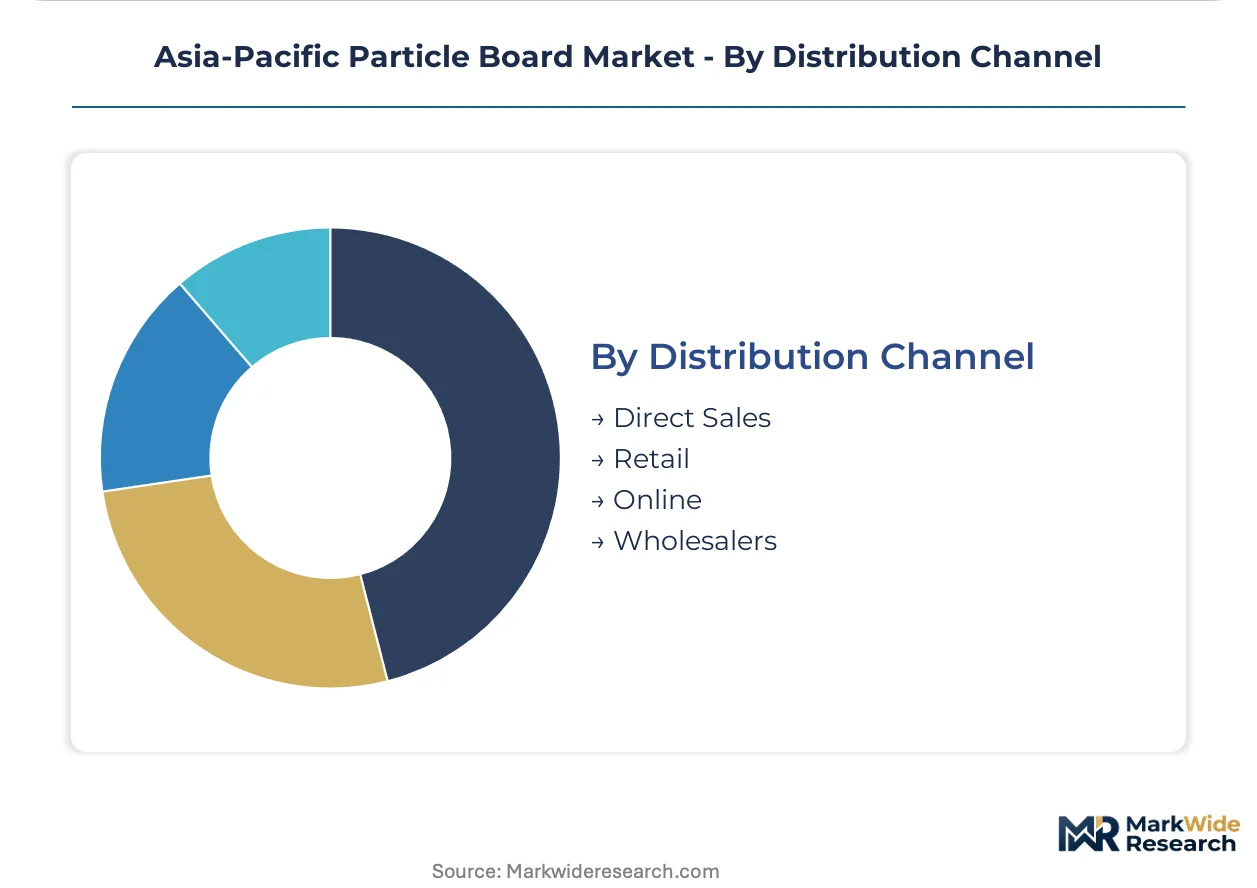
Channel selection correlates directly with buyer scale and certification requirements, fragmenting logistics patterns across the region.
- Direct Sales:Large furniture OEMs and construction developers procure certified volumes through mill-direct relationships enabling quality consistency and emission documentation. Vietnam's manufacturing corridor near Ho Chi Minh City exhibits the highest direct sales penetration.
- Retail:Builder merchants and specialty wood product stores serve small-scale fabricators and residential renovation contractors. India's tier-3 cities rely on this channel where CenturyPly's dedicated dealer networks dominate.
- Wholesalers:Regional distributors aggregate volumes for secondary markets in Indonesia's archipelago, including Kalimantan and Sulawesi construction markets underpenetrated by certified panel suppliers. Logistics vulnerability concentrates in Mekong Delta capacity clusters.
- Online:Digital procurement platforms are emerging for standardized grades and small-lot custom specifications, though physical inspection requirements limit penetration for emission-certified products.
Established procurement runs through Direct Sales. Online channels are climbing the fastest as digital process control enables remote quality verification for repeat buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rubberwood plantations across Thailand and Malaysia anchor raw material supply for Southeast Asian particle board fabrication. Plantation operators with captive chipping capacity command feedstock security that independent mills cannot replicate.
India
Residential construction acceleration in tier-2 and tier-3 cities is expanding procurement of engineered wood panels for kitchen cabinetry. BIS IS 17021 mandates are eliminating substandard producers and concentrating volume among certified manufacturers. Greenlam Industries Ltd leverages captive resin supply in India's decorative surfaces segment.
Vietnam
Furniture OEMs serving Japanese export contracts are pulling panel demand toward JIS A 5908 compliance. METI-registered supply chains require emission documentation that only integrated mills can provide. Manufacturing capacity clusters near Ho Chi Minh City, creating logistics concentration in the Mekong Delta.
Thailand
Rubberwood availability from southern plantation belts sustains substrate production for regional export markets. JIS A 5908 certification creates technical barriers for mills serving Japanese furniture OEMs. Bangkok Master Wood Co. Ltd anchors supply to METI-registered supply chains with compliant emission controls.
China
Cross-border panel trade faces tightening GB standards enforcement through SAMR inspection protocols. Density and moisture-content thresholds are compressing margins for exporters without retrofitted drying lines. Coastal customs zones are intensifying testing frequency for Indian producers.
Indonesia
Kalimantan and Sulawesi construction markets remain underpenetrated by certified panel distributors. Java-based mills dominate domestic supply while archipelago logistics fragment procurement patterns. European buyer EUDR-equivalent due diligence requirements are creating premium pricing tiers for mills with verified chain-of-custody documentation.
Asia-Pacific Particle Board Market Competitive Environment
Global majors compete with regional champions across certification tiers and integrated finishing capabilities. The vendor base stratifies between plantation-backed integrated operators and independent substrate specialists. Three archetypes dominate: captive-resin integrated producers, JIS-compliant export specialists, and multi-brand distribution networks. Consolidation is accelerating through backward integration into chemical manufacturing and geographic expansion into underpenetrated archipelago markets.
Among India-based fabricators, Greenlam Industries Ltd and CenturyPly exemplify divergent strategic positions. Greenlam Industries Ltd occupies a position within the captive-resin integrated tier, while CenturyPly anchors the multi-brand distribution archetype across secondary cities. Bangkok Master Wood Co. Ltd represents the JIS-compliant export specialist model serving METI-registered supply chains. These three companies illustrate how certification capabilities and supply chain configuration determine competitive positioning across the region.
| Leading Market Players |
|---|
| Greenlam Industries Ltd |
| Bangkok Master Wood Co. Ltd |
| CenturyPly |
| Green River Holding Co. Ltd |
| DareGlobal Wood |
| Fletcher Building |
| Wanhua Ecoboard Co Ltd |
| Foshan Jujian Yifang Trading Co. Ltd |
| Metro Particle Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Resin chemistry technical talent concentration in Thailand and Malaysia feeds labor-cost differentials that widen pricing spreads between JIS-certified premium grades and mass-market raw panels. Buyers in Vietnam's manufacturing corridor absorb premium positioning for emission-compliant substrates while India's tier-3 markets prioritize economy-grade procurement.
Pricing Analysis
Warranty-backed emission certification bundles separate premium tiers from unbundled commodity transactions. Three-tier pricing structure across premium, standard, and economy levels tracks JIS A 5908 compliance status and captive lamination capability. Pricing pressure stems from urea-formaldehyde resin feedstock volatility compressing margins for non-integrated producers. Construction developers in India's mass housing segment exhibit highest price sensitivity, while Japanese furniture OEMs prioritize certification consistency over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with petrochemical-derived adhesive supply tethered to regional resin manufacturing clusters in Thailand and Malaysia. Raw material procurement draws from rubberwood plantation belts in southern Thailand, urea-formaldehyde resin feedstocks, and melamine decorative paper imports. Logistics chokepoint risk concentrates in Mekong Delta capacity clusters serving northern ASEAN markets. Distribution runs through mill-direct relationships for certified volumes and dedicated dealer networks for secondary Indian cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous press line capital intensity creates a supply-constrained structure where certified capacity additions lag demand expansion, propping pricing power for integrated operators with captive resin supply.
For Market Incumbents: Lock in JIS A 5908 certification timelines ahead of competitor facility ramp-ups to defend share against emerging plantation-backed entrants. Deepen backward integration into chemical manufacturing to offset urea-formaldehyde resin cost volatility and sustain margin position. For New Entrants and Emerging Players: Capture underpenetrated archipelago demand in Kalimantan and Sulawesi construction markets where certified panel distributors remain scarce. Lead with EUDR-equivalent chain-of-custody documentation to access European buyer premium pricing tiers. For Investors and Strategic Acquirers: Re-rating potential sits with captive-resin integrated producers given BIS IS 17021 compliance mandates compressing India's supplier base toward certified manufacturers. Watch for JIS qualification protocol timeline compression as the inflection signal for capacity-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | Captive adhesive supply insulates margins from petrochemical feedstock volatility affecting standard-grade competitors. |
| JIS A 5908 Certification Investment | Japanese OEM procurement consolidation around METI-registered supply chains rewards compliant mills with contract lock-in. |
| Continuous Press Technology Deployment | Real-time density profiling unifies quality consistency for export furniture manufacturers demanding minimal batch variation. |
| Melamine-Facing Line Integration | Substrate-to-laminate unification captures margin pools previously split between separate panel and finishing processors. |
| EUDR-Equivalent Chain-of-Custody Documentation | Verified sustainable forestry credentials unlock premium pricing tiers from European buyers extending compliance expectations. |
Study Parameters
Document review covered customs trade databases, BIS certification registries, and JIS A 5908 testing records, complemented by interviews with particle board plant managers, furniture OEM procurement leads, resin formulation chemists, and plantation operations directors. Secondary validation drew from SAMR inspection protocol filings, METI supply chain registration data, and ASEAN forestry export statistics. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Segment-level outputs across product type, end user, thickness, and distribution channel dimensions were generated through the projection horizon. CAGRs were derived from regression analysis against residential construction starts, furniture export contract flows, and certification mandate implementation schedules. Model inputs incorporated continuous press line deployment timelines, BIS enforcement intensity gradients, and Japanese OEM supplier consolidation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to resin chemistry talent migration, EUDR-equivalent due diligence adoption curves, and MDF substitution rates in Indian metro cabinetry specifications. Forecasts reflect documented assumptions about regulatory enforcement continuity and plantation feedstock security. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
South Africa Wall Putty Market
Building & Construction Materials
Russia Cross Laminated Timber Market
Building & Construction Materials
Australia Steel Rebar Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
Mineral Wool Ceiling Tiles Market
Building & Construction Materials
India Faucet Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Composite Roof Shingle Market
Building & Construction Materials
Mexican Insulated Panels Market
Building & Construction Materials
Acoustic Doors Market
Building & Construction Materials
Cement Grinding Aids Market
Building & Construction Materials
Global Cool Roofs Market
Building & Construction Materials
Pervious Concrete Market
Building & Construction Materials
Slimline Aluminum Window System Market
Building & Construction Materials
Pipe Hanger Market