
 APET Film Market | 2026-2036
APET Film Market Size, Share, and Industry Trends Forecast 2026-2036
APET Film Market Analysis
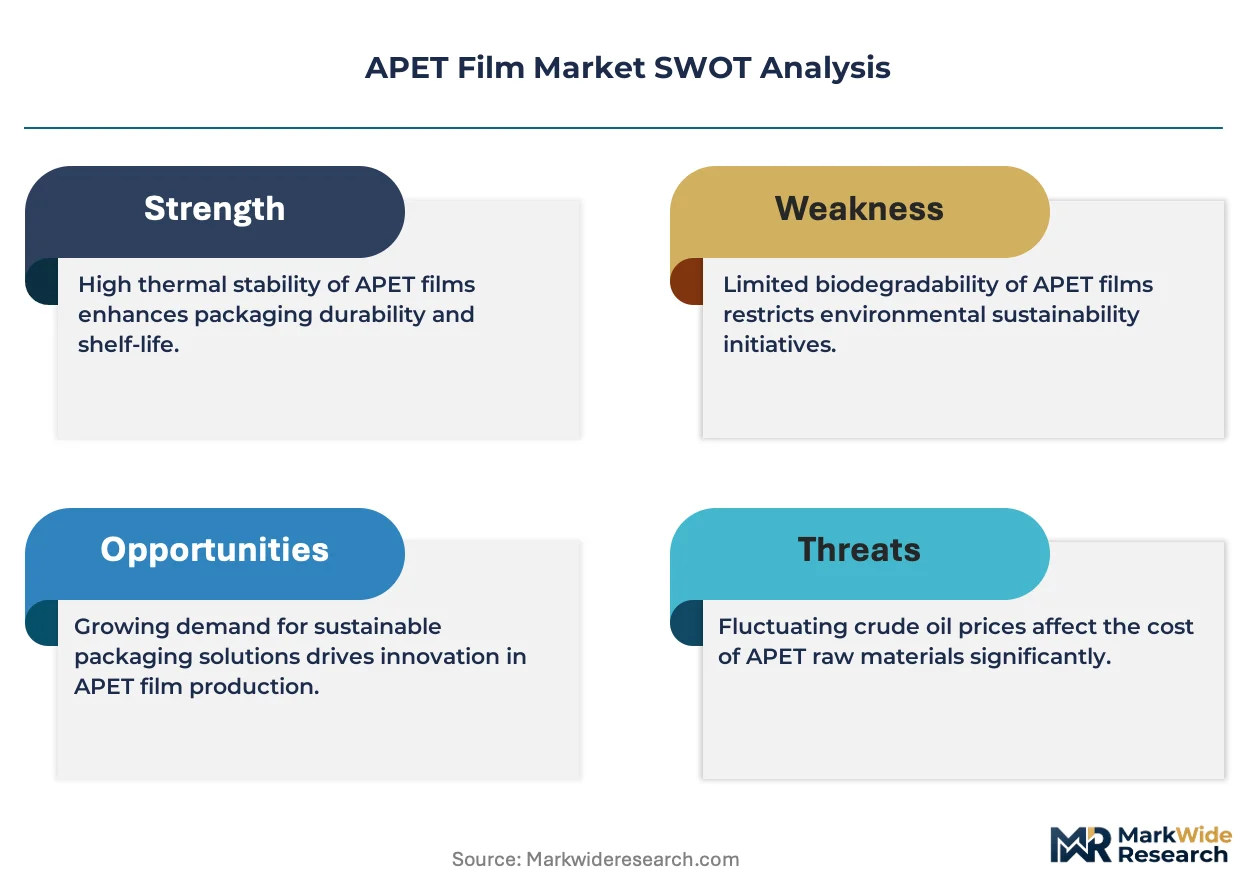
EU REACH compliance is recalibrating the cost-of-entry calculus for APET film converters serving European food-contact applications. Klöckner Pentaplast leverages captive extrusion capacity across multiple European sites to sustain margin control amid rising certification costs. Toray Plastics anchors North American supply through integrated resin-to-film operations that dominate medical-grade segments. DuPont Teijin Films differentiates via biaxial orientation expertise that leads high-barrier pharmaceutical packaging applications.
Amorphous polyethylene terephthalate (APET) film is a transparent, thermoformable polyester sheet produced by extruding PET resin followed by rapid quenching to suppress crystallization, yielding optical clarity with glass-transition temperatures near 75°C. The material serves primarily as a rigid, printable substrate for food-contact packaging, medical blister packs, and consumer-goods thermoforming where visual presentation and barrier performance matter. Roll-format APET occupies the largest volume share due to continuous-processing efficiency across downstream converting lines, while sheet formats command premium positioning in custom thermoforming runs for medical device trays. Blister packaging applications generate the deepest margin pools owing to pharmaceutical validation requirements and multi-layer lamination complexity that limit supplier substitution.
The European Chemicals Agency (ECHA) enforces REACH substance restrictions that shape monomer purity standards and additive migration limits for food-contact APET films. The FDA maintains parallel food-contact notification requirements that govern resin composition and recycling-content claims for US-bound exports. Germany's national packaging regulator, alongside ECHA, is tightening extended-producer-responsibility targets that force converters to document recyclability pathways. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across both jurisdictions, as fluorinated barrier coatings face phased elimination that will redirect R&D spending toward silicone-oxide or plasma-deposited alternatives.
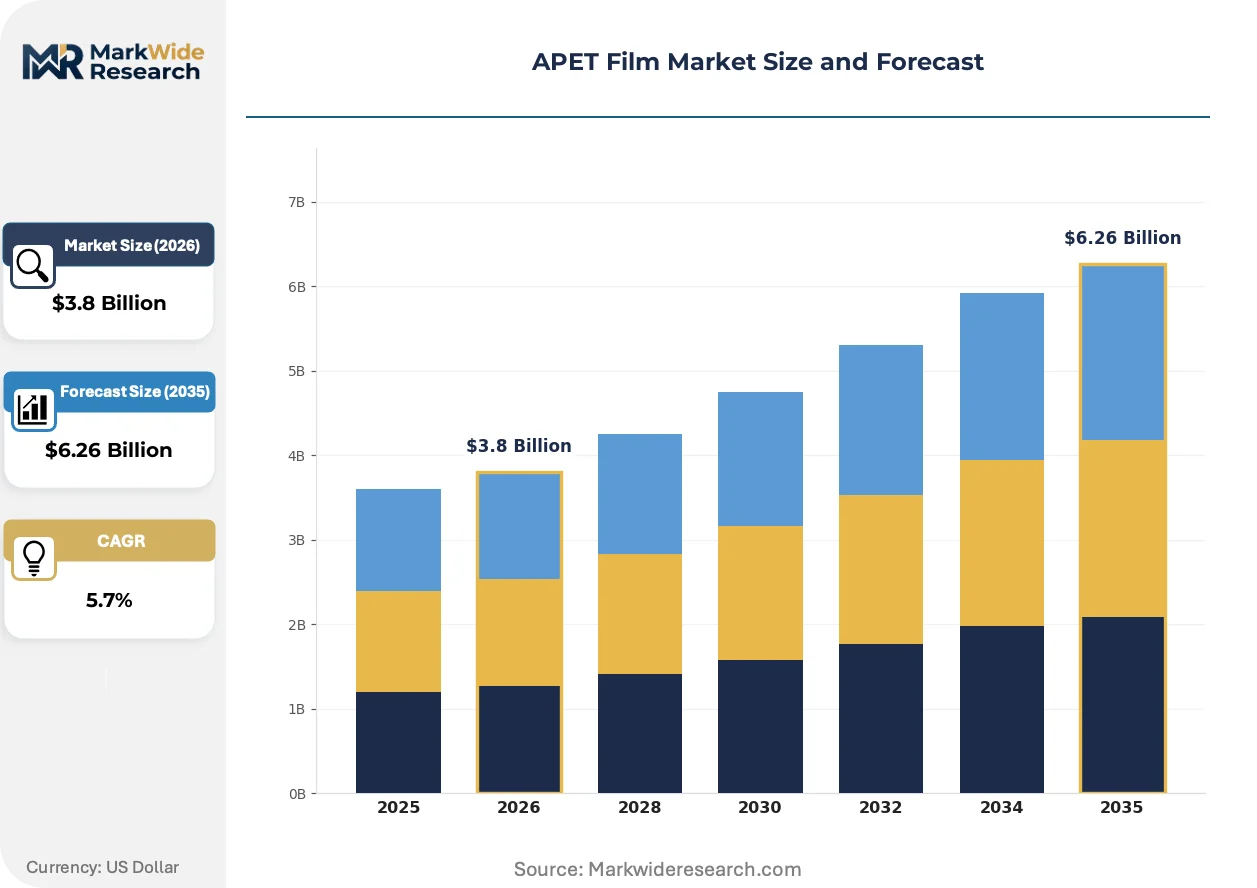
Market Dynamics
The EU Green Deal's single-use plastics directive is forcing a material substitution wave across European food packaging, compressing demand timelines for recyclable polyester films while redirecting converter capex toward circular-economy certification.
Growth Catalysts
- Fresh-protein tray demand:Food packaging buyers in Germany and France are expanding APET film specifications for modified-atmosphere packaging of poultry and seafood, driving volume through thermoforming clusters near Rotterdam and Hamburg logistics hubs.
- REACH compliance premiums:ECHA substance restrictions on monomer purity and additive migration are creating certified-supplier scarcity that rewards early-compliant converters with locked-in pharmaceutical blister contracts.
- Medical-grade validation:Sterile barrier packaging for implantable devices is electrifying demand for ultra-clean APET sheet with documented batch traceability, particularly among German and Swiss device manufacturers.
Market Restraints
- Ethylene glycol feedstock volatility:Purified terephthalic acid and monoethylene glycol prices swing with naphtha-cracker economics, compressing film extruder margins during upstream petrochemical tightness.
- Fluorinated barrier phase-out:Per- and polyfluoroalkyl substance restrictions under REACH and parallel US state laws are eliminating proven high-barrier coatings before silicone-oxide alternatives achieve cost parity.
- Crystallization control limits:APET's amorphous structure requires rapid quenching that caps line speeds versus crystallizable PET, constraining throughput at legacy extrusion assets.
Strategic Opportunities
- Indian food-export packaging:FSSAI food-contact regulations and DGFT export incentives are creating certified-film demand for seafood and spice shipments to EU and Gulf markets, with Mumbai and Kochi emerging as conversion hubs.
- Plasma-deposited barrier convergence:Silica-based vacuum coating is intersecting with APET substrate optimization to replace multi-layer laminations in pharmaceutical blisters, opening premium positioning for integrated film-coaters.
- Extended producer responsibility tailwinds:Germany's Verpackungsgesetz tightening and France's AGEC law are mandating minimum recycled content that favors APET's established mechanical recycling streams over competing polymers.
Industry Challenges
- Migration testing bottlenecks:ECHA food-contact notification queues and FDA equivalency determination backlogs are extending time-to-market for reformulated APET grades by 8-14 months.
- Thermoforming skill scarcity:Precision die design and crystallinity management expertise for medical-grade sheet production concentrates among aging workforces in southern Germany and northern Italy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APET Film Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat, Roll, Sheet, Others End User: Food Packaging, Medical Applications, Consumer Goods, Electronics Thickness: Below 200 Microns, 200-300 Microns, 300-400 Microns, Above 400 Microns Application: Blister Packaging, Lidding, Wrapping, Thermoforming |
| Companies Covered | Octal, Klöckner Pentaplast, Toray Plastics, DuPont Teijin Films, Polyplex Corporation, Amcor, Jindal Poly Films, Mitsubishi Polyester Film, Nan Ya Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APET Film Market Emerging Trajectories
Active barrier deposition technologies and circular-economy compliance architectures are restructuring competitive advantage in APET film, separating integrated resin-to-film operators from toll-dependent converters.
Silicon-oxide plasma-enhanced chemical vapor deposition is electrifying high-barrier APET film performance for pharmaceutical blister packs. Swiss and German packaging converters are qualifying these coatings at accelerated pace to replace fluorinated treatments ahead of regulatory deadlines. The technology is compressing the viable supplier base toward extrusion-coating integrators with captive vacuum deposition assets.
REACH Article 33 substance disclosure requirements are forcing granular supply-chain documentation for APET food-contact films. ECHA enforcement of SCIP database reporting for recycled-content claims is raising compliance costs for converters sourcing post-consumer PET flake. Medical-device packaging segments are responding fastest, with German and Dutch manufacturers demanding batch-level polymer genealogy certificates.
Brand-owner sustainability scorecards are redirecting procurement toward film suppliers with verified mass-balance certification. Retail grocery chains in France and Benelux are unbundling traditional resin-grade specifications in favor of carbon-footprint metrics and recyclability design-for-recycling ratings. This behavior is most visible in fresh-produce packaging, where Auchan and Carrefour purchasing teams have embedded lifecycle assessment thresholds into supplier qualification.
APET Film Market Segmentation
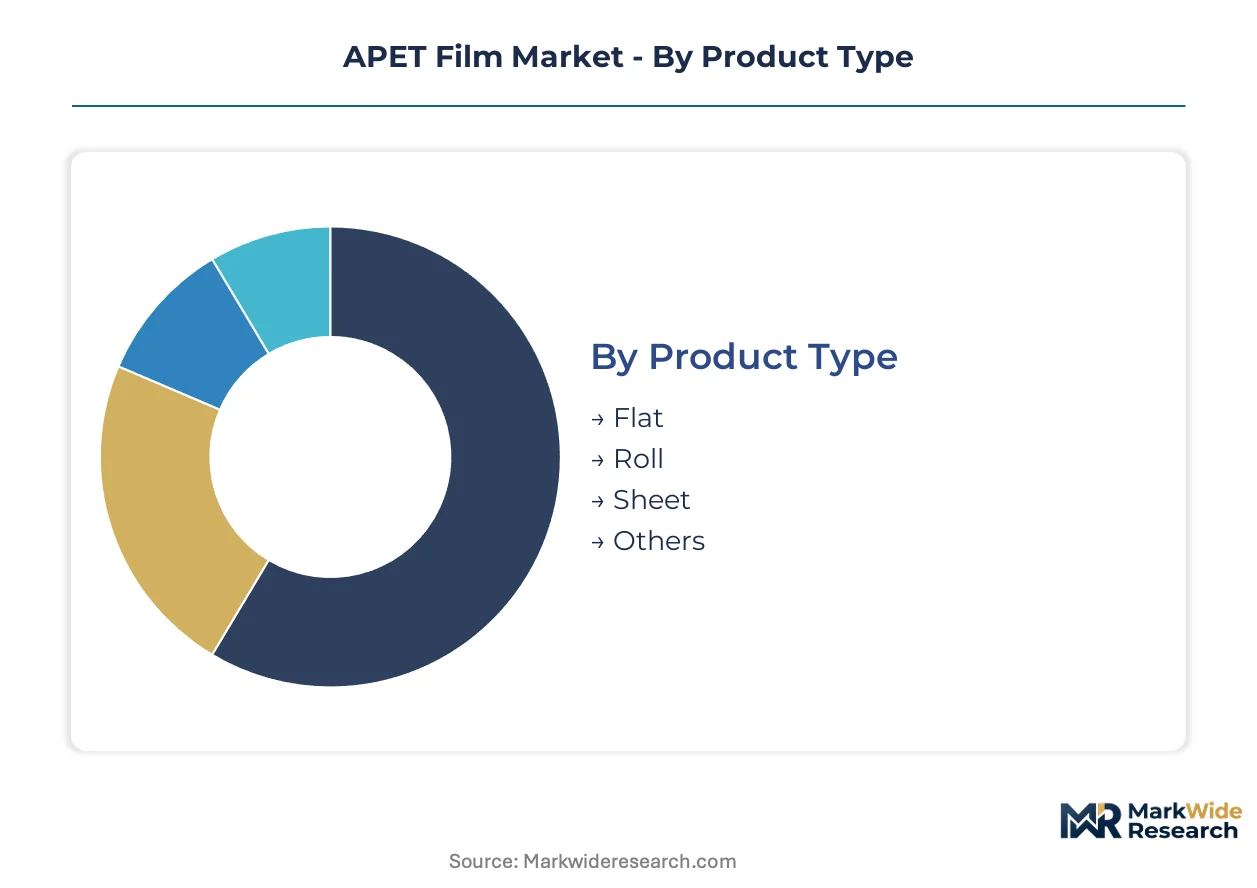
APET film demand fragments across format, thickness, and end-use specifications that dictate extrusion line configuration and margin capture. Converter specialization deepens as food-contact certification, medical validation, and barrier performance requirements diverge.
Product Type:
Roll formats dominate tonnage throughput while sheet commands premium positioning in custom runs.
- Roll:Continuous-web extrusion yields economies across high-volume food packaging lines. German thermoforming clusters near Hamburg and Rotterdam logistics hubs absorb the majority of European roll supply for modified-atmosphere protein trays.
- Sheet:Cut-to-size formats serve medical device manufacturers requiring batch traceability and sterile barrier validation. Swiss and German device makers specify ultra-clean sheet with documented polymer genealogy for implantable packaging.
- Flat:Precision-calendered formats target lidding applications where gauge uniformity controls seal integrity.
- Others:Specialty formats including perforated and pre-cut blanks serve niche converting operations.
Mature deployment sits with Roll. Newer deployment is concentrated in Sheet.
End User:
Food packaging absorbs volume while medical applications generate the deepest margin pools.
- Food Packaging:Modified-atmosphere trays for fresh protein and ready-meal containers drive specification expansion. French and German retail chains embed lifecycle assessment thresholds into supplier qualification, favoring APET's established recycling streams.
- Medical Applications:Sterile barrier systems for pharmaceutical blisters and device trays command validation premiums. ECHA substance restrictions on monomer purity create certified-supplier scarcity that locks in pharmaceutical contracts for early-compliant converters.
- Consumer Goods:Thermoformed display packaging and cosmetic trays leverage optical clarity for shelf presentation.
- Electronics:Anti-static formulations protect sensitive components during shipment and assembly.
Established demand concentrates in Food Packaging. Steepest expansion trajectory appears in Medical Applications.
Thickness:
Mid-range gauges balance structural performance with material efficiency across thermoforming applications.
- 200-300 Microns:Standard gauge for food trays and blister packs where rigidity meets downgauging pressure. European converters optimize this band for modified-atmosphere poultry and seafood packaging.
- Below 200 Microns:Ultra-thin formats serve lidding and wrapping where flexibility and seal response matter. Downgauging initiatives in French retail chains push specifications toward this minimum viable thickness.
- 300-400 Microns:Heavy-gauge sheet supports deep-draw thermoforming for medical device trays requiring dimensional stability.
- Above 400 Microns:Structural grades absorb impact in reusable shipping containers and industrial dunnage.
Volume leadership belongs to 200-300 Microns. Technology migration is accelerating Below 200 Microns.
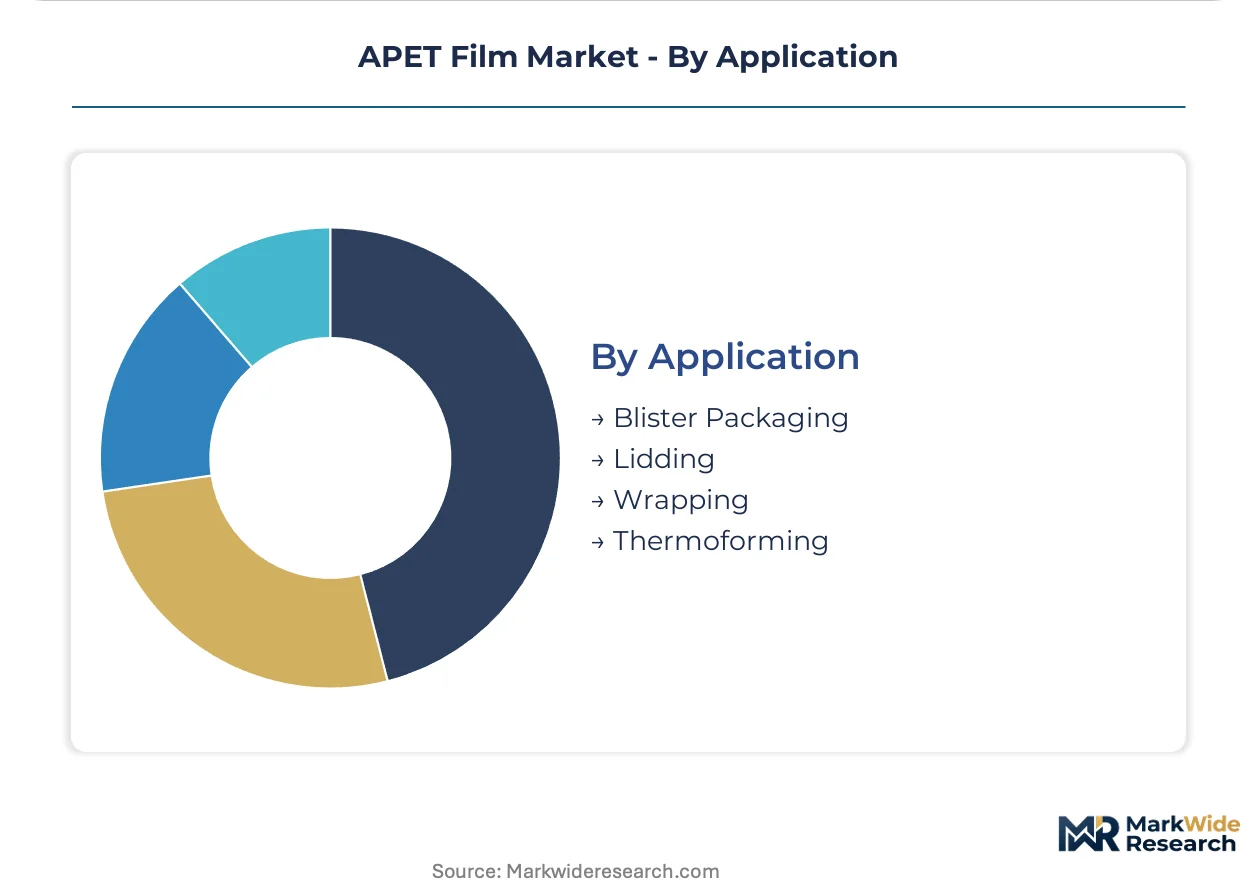
Application:
Barrier requirements and forming complexity separate commodity from specialty positioning.
- Blister Packaging:Multi-layer laminations with silicon-oxide or plasma-deposited barriers serve pharmaceutical validation requirements. Swiss and German converters qualify these systems to replace fluorinated coatings ahead of REACH deadlines.
- Thermoforming:Vacuum and pressure forming of protein trays and ready-meal containers consumes the largest tonnage share. German thermoforming clusters leverage proximity to resin extrusion and logistics infrastructure.
- Lidding:Peelable and weld-seal formulations control package atmosphere and consumer access.
- Wrapping:Stretch and shrink applications protect palletized goods and consumer products.
Process maturity centers on Thermoforming. Technical innovation is clustering in Blister Packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate Indian APET film conversion capacity for seafood export packaging. German industrial parks near Hamburg anchor European thermoforming clusters. Chinese coastal provinces dominate resin-to-film integration.
United States
Medical-grade blister packaging and sterile barrier systems drive specification expansion. FDA food-contact notification requirements govern resin composition for pharmaceutical exports. Massachusetts and North Carolina device manufacturers source ultra-clean sheet with documented batch traceability.
Germany
Modified-atmosphere protein trays and ready-meal containers absorb premium roll-format supply. Verpackungsgesetz tightening mandates minimum recycled content documentation. Hamburg-Rotterdam logistics corridors host thermoforming clusters serving French and Benelux retail chains.
China
Downstream electronics packaging and consumer-goods thermoforming sustain volume demand. GB standards for food-contact plastics shape monomer purity requirements. Yangtze River Delta extrusion assets supply both domestic appliance manufacturers and Southeast Asian converters.
India
FSSAI-compliant food-contact films for spice and seafood exports generate certified-film demand. DGFT export incentives accelerate conversion hub development. Mumbai and Kochi clusters serve EU and Gulf market specifications with increasing regulatory sophistication.
Switzerland
Implantable device packaging and pharmaceutical validation requirements command sterile barrier premiums. Swissmedic medical device regulations enforce polymer genealogy documentation. Basel-Zurich corridor manufacturers specify ultra-clean sheet with plasma-deposited barrier compatibility.
APET Film Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across resin-to-film integration tiers. Market structure concentrates around three strategic archetypes: integrated petrochemical-to-film operators, captive extrusion specialists with downstream thermoforming partnerships, and toll-dependent converters serving regional packaging markets. Dominant competitive moves include backward integration into resin purification assets and strategic partnerships with medical device OEMs for sterile barrier validation.
Within the integrated operator tier, Klöckner Pentaplast and Toray Plastics exemplify geographic diversification strategies that balance European regulatory compliance with North American medical-grade positioning. DuPont Teijin Films occupies a specialist position anchored by biaxial orientation expertise. These three entities represent contrasting approaches to barrier technology transitions as fluorinated coatings face phased elimination.
| Leading Market Players |
|---|
| Octal |
| Klöckner Pentaplast |
| Toray Plastics |
| DuPont Teijin Films |
| Polyplex Corporation |
| Amcor |
| Jindal Poly Films |
| Mitsubishi Polyester Film |
| Nan Ya Plastics Corporation |
| Others |
Supply Flow & Price Mechanics
Purified terephthalic acid and monoethylene glycol spot indices cascade through APET film converters into three distinct pricing tiers that separate pharmaceutical-grade certified supply from commodity food-packaging rolls. Buyers facing REACH compliance deadlines absorb premium markups for documented batch traceability, while spot purchasers of standard-grade inventory capture modest discounts against contract benchmarks.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent separate emergency pharmaceutical orders from standard-contract food-packaging volumes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with ECHA-compliant medical-grade sheet commanding the top tier. Cost compression in commodity roll formats is intensifying because German thermoforming clusters are consolidating procurement through preferred-supplier agreements. Food-packaging buyers at French retail chains exhibit highest price sensitivity, while Swiss device manufacturers show minimal elasticity for sterile barrier validation.
Supply Chain Analysis
Regional distribution centers in Hamburg, Rotterdam, and Mumbai anchor hub-and-spoke patterns that feed thermoforming clusters and medical-device manufacturers. Resin-to-film integration concentrates in China, Germany, and the United States, with purified terephthalic acid supply drawing from naphtha-cracker economics in the Middle East and Asia. Single-source vulnerability sits with fluorinated barrier coating chemistries facing REACH phase-out deadlines. Distribution runs through converter-direct relationships for medical-grade sheet and distributor networks for commodity roll supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
APET film is navigating a technology-transition phase as silicon-oxide plasma deposition displaces fluorinated barrier coatings across pharmaceutical packaging applications.
For Market Incumbents: Anticipate margin compression in commodity food-packaging grades as Chinese resin-to-film operators expand European export capacity. Backward integration into post-consumer PET flake purification assets secures recycled-content compliance ahead of Germany's Verpackungsgesetz tightening. Captive vacuum deposition capacity for silicon-oxide barriers locks in pharmaceutical contract renewals against toll-dependent competitors. For New Entrants and Emerging Players: India's FSSAI food-contact regulations open a window for certified-film production serving seafood and spice export corridors to EU and Gulf markets. Mumbai and Kochi conversion hubs offer the most penetrable geography given DGFT export incentives and limited incumbent certification depth. A co-manufacturing partnership with established European converters accelerates REACH compliance without capital-intensive extrusion asset builds. For Investors and Strategic Acquirers: Distressed-cycle entries favor toll-dependent converters with stranded fluorinated coating assets in southern Germany and northern Italy. Long-term viability hinges on plasma-deposition retrofit capability and medical-device OEM validation relationships. Watch silicon-oxide coating qualification rates at Swiss and German pharmaceutical packagers as the inflection indicator for barrier technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma-Deposition Capacity Buildout | Captive silicon-oxide coating assets at Klöckner Pentaplast secure pharmaceutical blister contracts ahead of REACH deadlines. |
| Post-Consumer PET Integration | In-house flake purification operations satisfy Germany's Verpackungsgesetz recycled-content mandates for food-contact applications. |
| Medical-Device OEM Partnership | Sterile barrier validation relationships with Swiss implantable device manufacturers generate multi-year contract lock-in. |
| Indian Export Hub Development | FSSAI-certified conversion capacity in Mumbai captures DGFT incentives for seafood shipments to European retail chains. |
| Fluorinated Coating Phase-Out | Accelerated R&D redirection toward silicone-oxide alternatives limits regulatory stranded-asset exposure across European operations. |
Methodological Framework
Trade databases, ECHA regulatory filings, and petrochemical price benchmarks formed the secondary backbone for this analysis. Primary interviews with extrusion plant managers, pharmaceutical packaging procurement leads, medical-device regulatory affairs directors, and thermoforming cluster operators combined with secondary validation. Bottom-up and top-down triangulation cross-checked volume estimates against resin consumption patterns and end-use application splits.
Bottom-up modeling of extrusion line capacity and utilization rates anchored the analytical lens, with top-down cross-validation against polymer consumption surveys. Segmentation dimensions spanned format type, thickness band, end-use industry, barrier technology tier, and regional production hub. CAGRs derived from regression analysis of historical pricing elasticity and substitution dynamics across the projection horizon. Forecast inputs incorporated REACH compliance cost trajectories and silicon-oxide coating adoption curves.
The model assumes a particular technology adoption path for plasma-deposited barriers; alternative pathways for multi-layer coextrusion would alter the outlook for coating equipment suppliers. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
MDO-PE Films Market
Poly film
Global BOPP Films Market
Poly film
Polypropylene Packaging Films Market
Poly film
US Cleanroom Film and Bags Market
Poly film
Mexico Plastic Packaging Films Market
Poly film
Polyethylene Film Market
Poly film
Wrap Around Label Films Market
Poly film
Timber Wrap Films Market
Poly film
Isotropic Film Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
Polyester Film Market
Poly film
Indonesia Plastic Packaging Films Market
Poly film
Nylon Films Market
Poly film
Latin America Polypropylene (PP) Packaging Film Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
North America Plastic Film Packaging Market