
 Polypropylene Packaging Films Market | 2026-2036
Polypropylene Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Polypropylene Packaging Films Market Intelligence
Maintenance contracts for extrusion line calibration and die refurbishment is consolidating around film producers seeking uptime guarantees rather than capital replacement cycles. Jindal Poly Films Ltd leverages captive resin sourcing across its integrated complexes to sustain margin stability. UFlex Ltd anchors its position through specialized metallization capabilities that differentiate commodity grades. Cosmo Films Ltd dominates the optical and label-grade segment with precision coating lines.
Polypropylene packaging films are thermoplastic olefin sheets extruded from isotactic polypropylene resin, typically ranging from 8 to 80 microns in thickness, engineered for moisture barrier, optical clarity, and heat-seal functionality across automated packaging lines. Stretch films command the largest volume position in industrial palletization, while flexible films capture expanding share in single-serve food pouches where downgauging reduces material intensity. Medical packaging applications generate premium pricing due to sterilization-grade compliance and lot-traceability requirements that exceed standard film specifications.
FDA food-contact regulations in the United States, EU REACH substance restrictions, and India's BIS certification mandates for food-grade plastics collectively elevate compliance costs for non-specialized converters. The EU Green Deal's packaging waste directives are forcing reformulation toward higher recycled content thresholds without sacrificing seal integrity. Stakeholders must monitor polymer recycling infrastructure buildouts and regulatory timing to align capacity investments with verified feedstock availability.
Market Dynamics
Converters are restructuring around REACH and F-Gas compliance timelines, forcing simultaneous reformulation of extrusion chemistries and validation of recycled-content feedstocks without interrupting seal-integrity specifications for food-contact applications.
Growth Catalysts
- Modified-atmosphere packaging:Food processors are specifying biaxially oriented PP films for extended shelf-life meat and produce applications, driving volume through automated thermoforming lines.
- EU Green Deal packaging directives:Mandatory recycled-content thresholds are accelerating investment in chemical recycling infrastructure capable of processing post-consumer polypropylene into food-grade resin.
- Mumbai-Ahmedabad industrial corridor:India's western manufacturing belt is concentrating new blown-film capacity to serve domestic FMCG demand and export-oriented pharmaceutical packaging.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking margins and PDH unit economics create margin compression for non-integrated converters without captive propylene supply.
- Specialized metallization equipment scarcity:Vacuum deposition chambers for high-barrier films require 18-24 month lead times from European and Japanese equipment builders.
- Polyethylene substitution in stretch films:Linear low-density polyethylene maintains cost advantage in industrial palletization, limiting PP stretch film penetration.
Strategic Opportunities
- Pharmaceutical serialization compliance:Track-and-trace mandates from FDA and EMA are creating demand for printable, tamper-evident PP lidding films with embedded authentication features.
- Digital printing compatibility:Corona-treated PP substrates for water-based inkjet systems are capturing share from solvent-based flexographic workflows in short-run label applications.
- India BIS certification expansion:Mandatory IS 9845 standards for food-contact plastics are consolidating domestic supply around certified converters with testing laboratory partnerships.
Industry Challenges
- Multi-layer coextrusion expertise gap:Seven-layer and nine-layer barrier film production requires operators skilled in rheology control and interlayer adhesion optimization.
- Legacy gravure cylinder inventory:Converters maintaining solvent-based printing lines face stranded asset risk as brand owners mandate VOC emissions reductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polypropylene Packaging Films Market |
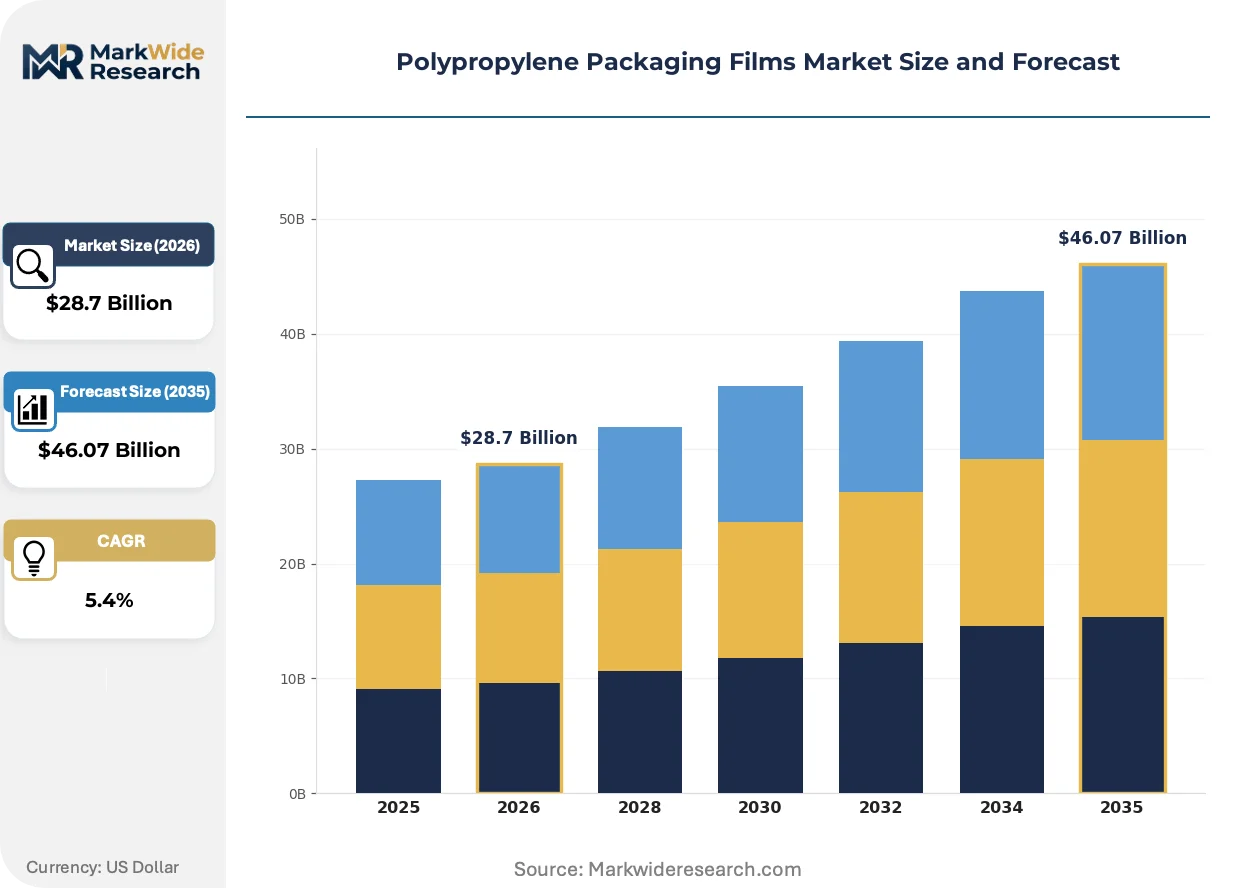
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $46.07 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Films, Shrink Films, Rigid Films, Flexible Films End User: Food Packaging, Beverage Packaging, Personal Care, Electronics Thickness: Thin, Medium, Heavy, Ultra-Heavy Application: Retail Packaging, Industrial Packaging, Medical Packaging, Agricultural Packaging |
| Companies Covered | Jindal Poly Films Ltd, UFlex Ltd, Cosmo Films Ltd, Amcor PLC, Berry Global Inc, Polyplex Corporation Ltd, SABIC, Borealis AG, SRF Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polypropylene Packaging Films Market Strategic Shifts & Innovations
Extrusion technology and regulatory chemistry are converging to enable thinner, higher-performing films while compliance frameworks force simultaneous verification of sustainability claims and functional performance.
Digital printing pretreatment systems are decentralizing short-run packaging production by enabling direct-to-film inkjet workflows without plate-making delays. Regional converters serving craft food brands and private-label retailers are adopting these systems to compress turnaround times from weeks to days. This capability is decentralizing volume away from centralized gravure houses toward distributed, on-demand production networks.
REACH substance restrictions on perfluorinated compounds are forcing reformulation of heat-seal layers and slip additives in European-sourced films. ECHA evaluations of long-chain fluorinated substances have triggered substitution programs across converter R&D departments. Medical and food-contact grades are experiencing the most intensive reformulation cycles as manufacturers validate alternative chemistries against sterilization and migration limits.
Brand-owner sustainability scorecards are compressing supplier qualification cycles and elevating recycled-content verification requirements. Major FMCG companies are unbundling film procurement from legacy converter relationships to source certified circular grades through independent auditors. This pattern is most visible in European and North American markets where Extended Producer Responsibility frameworks assign explicit recycling targets to packaging producers.
Polypropylene Packaging Films Market Segmentation
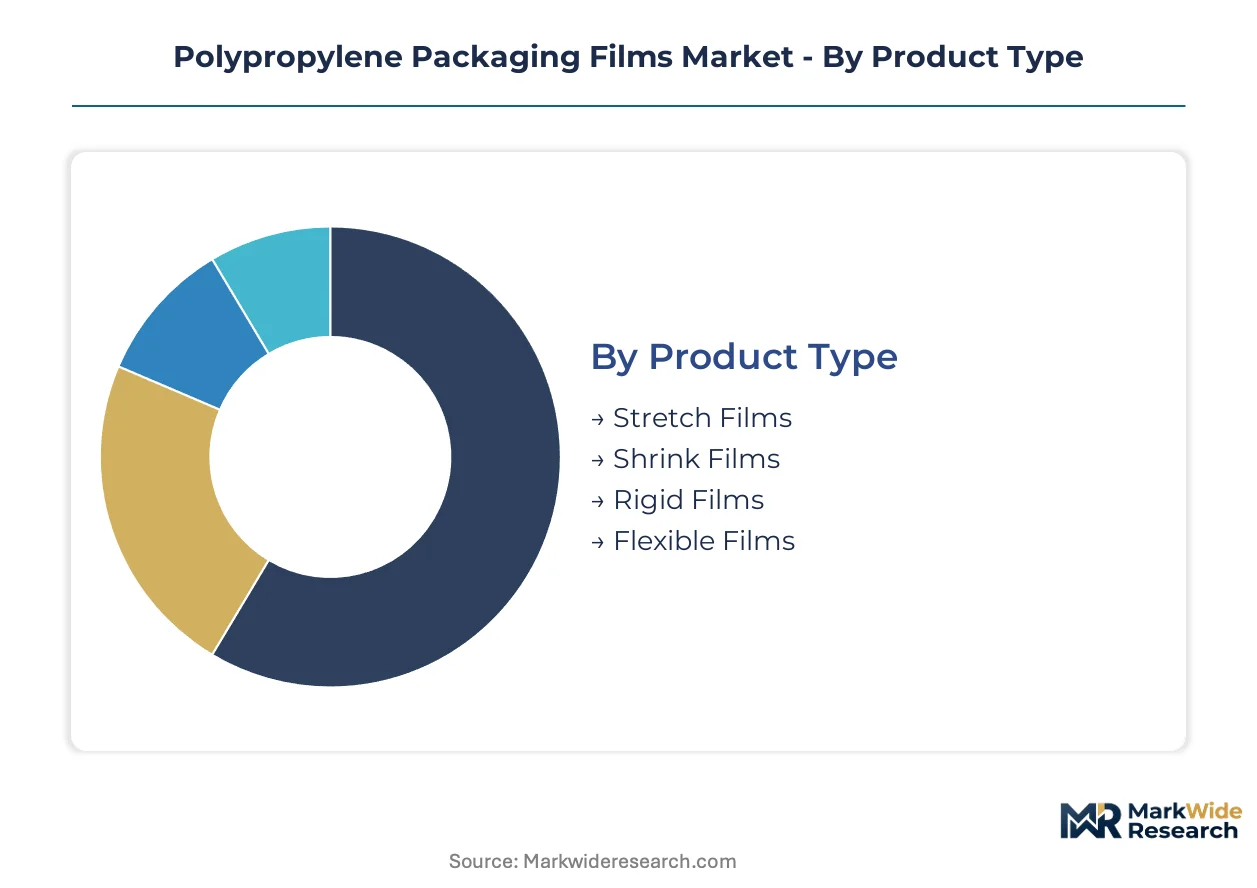
Polypropylene packaging films serve divergent performance requirements across food preservation, industrial logistics, and sterile medical environments. Each segment demands distinct barrier specifications, thickness tolerances, and regulatory compliance profiles that reshape converter specialization and capital allocation decisions.
Product Type:
Buyers in this category differentiate primarily by load-bearing requirements and heat-shrink compatibility rather than resin grade alone.
- Stretch Films:Linear low-density polyethylene dominates industrial palletization due to superior elongation recovery, though PP variants penetrate high-temperature warehouse applications where load stability exceeds 40°C. Demand concentrates in automated distribution centers across Germany and the United States where machine-wrap consistency reduces damage claims.
- Flexible Films:Biaxially oriented PP films enable downgauged pouches for single-serve snacks and retort applications, with Indian converters expanding metallization capacity to serve domestic FMCG brands. FDA and EU food-contact compliance requirements elevate entry barriers for non-specialized producers.
- Shrink Films:Cross-linked PP grades deliver controlled shrink force for multi-pack collation of beverages and personal care products, competing against PVC in European markets where REACH substance restrictions accelerate substitution.
- Rigid Films:Thermoforming-grade PP sheet serves modified-atmosphere trays for fresh protein, with thickness calibration critical for seal-bar compatibility across high-speed packaging lines.
Stretch films lead volumes today; flexible films are gaining share fastest.
End User:
Margin structures vary sharply across this category, with medical and pharmaceutical applications commanding certification premiums unavailable in commodity food segments.
- Food Packaging:Modified-atmosphere specifications for meat and produce drive biaxially oriented film demand through automated thermoforming lines. EU Green Deal recycled-content mandates are forcing reformulation of heat-seal layers without compromising oxygen barrier performance.
- Medical Packaging:Sterilization-grade films for autoclave and gamma-irradiation applications require lot-traceability systems and migration testing that exceed standard specifications. FDA and EMA track-and-trace mandates are embedding authentication features into printable lidding structures.
- Beverage Packaging:Shrink-labelling and collation films for bottled water and carbonated drinks compete on clarity and printability, with digital inkjet compatibility emerging as a procurement differentiator for short-run craft brands.
- Electronics:Anti-static PP films protect semiconductors and displays during shipment, with cleanroom manufacturing requirements limiting qualified converter pools in Taiwan and South Korea.
- Personal Care:Flow-wrap and stand-up pouch films for cosmetics and hygiene products prioritize haptic surface finish and fragrance barrier properties over oxygen transmission rates.
Food packaging anchors volume concentration; medical packaging delivers the steepest margin expansion trajectory.
Thickness:
Equipment calibration and resin throughput economics divide this category, with ultra-heavy grades requiring specialized extrusion screws and cooling configurations.
- Thin:8-20 micron biaxially oriented films for label and overwrap applications maximize yield per kilogram but demand precise tension control to prevent web breaks at high line speeds.
- Medium:20-40 micron cast and blown films balance puncture resistance with material efficiency in general-purpose pouch and bag applications across Indian and Southeast Asian converters.
- Heavy:40-60 micron grades serve industrial stretch and shrink applications where load containment overrides downgauging incentives.
- Ultra-Heavy:60-80 micron thermoforming sheet and deep-draw rigid packaging require specialized die design and plug-assist tooling for uniform wall distribution in medical tray production.
Medium thickness dominates current procurement volumes; ultra-heavy grades are climbing fastest on pharmaceutical serialization compliance requirements.
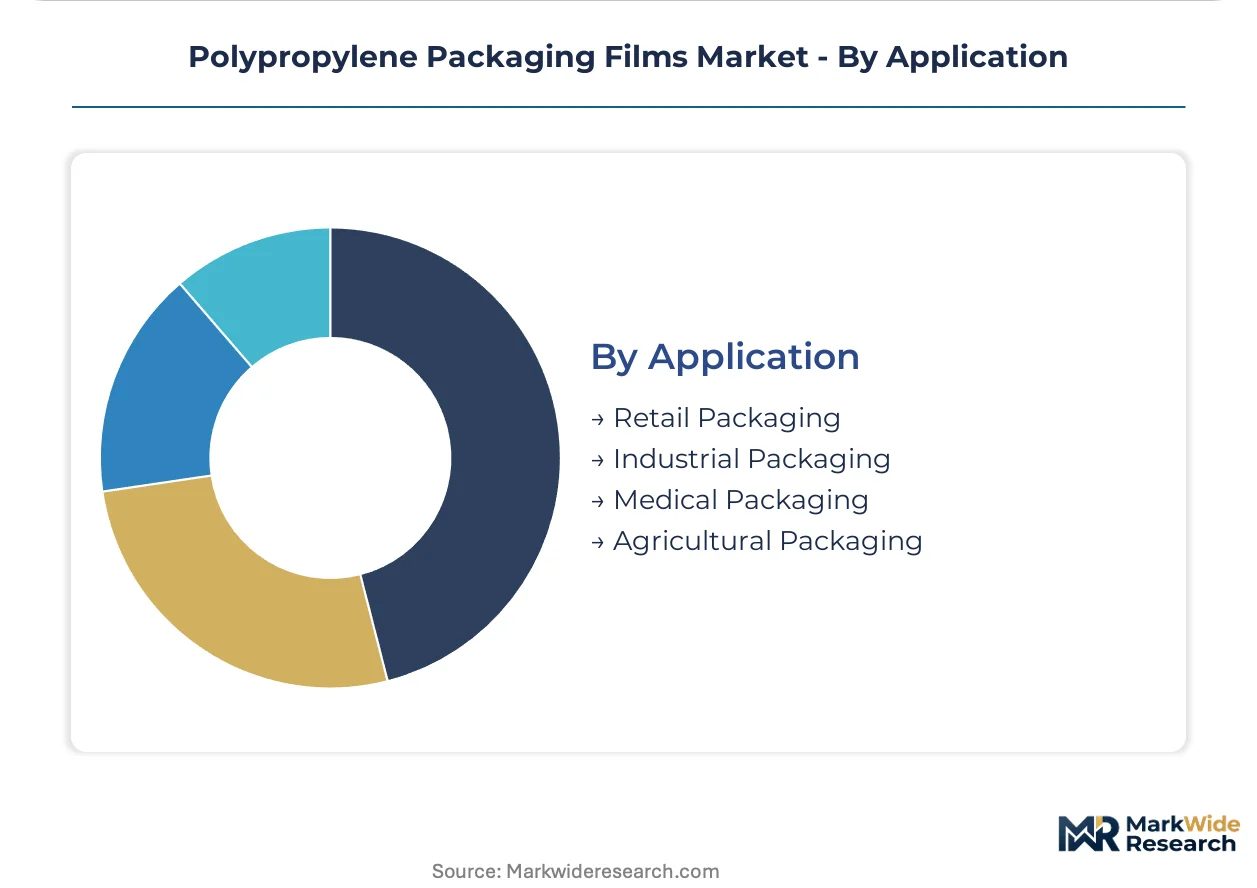
Application:
Regulatory intensity and customer concentration shape competitive dynamics here, with medical and agricultural segments presenting opposite margin and volume profiles.
- Industrial Packaging:Stretch wrap and unitizing films for palletized goods prioritize tear propagation resistance and cling balance over optical properties, with procurement centralized at large logistics operators.
- Retail Packaging:Printed laminations and pre-made pouches for supermarket display demand corona-treated surfaces compatible with water-based inkjet systems, decentralizing production toward regional converters.
- Medical Packaging:Sterile barrier systems for surgical instruments and pharmaceutical devices require validated sealing windows and particulate control that restrict qualified supplier bases.
- Agricultural Packaging:Mulch films and crop protection sheets utilize UV-stabilized PP grades with controlled degradation profiles, with demand clustering in Gujarat and Maharashtra's vegetable cultivation belts.
Industrial packaging maintains volume leadership; retail packaging is expanding most quickly on digital printing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's western industrial corridor generates denser converter activity than Germany's Rhine-Ruhr belt, though both regions face divergent regulatory pressures on extrusion chemistry reformulation.
United States
Food processors in Wisconsin and California are specifying biaxially oriented PP films for modified-atmosphere meat packaging. FDA food-contact regulations and EPA emissions standards elevate compliance costs for non-integrated converters. The Midwest manufacturing belt around Chicago concentrates stretch film production for automated distribution centers serving e-commerce logistics operators.
Germany
Automotive component suppliers in Bavaria demand anti-static PP films for semiconductor shipment protection. EU F-Gas Regulation and REACH substance restrictions on perfluorinated compounds force heat-seal layer reformulation. The Rhine-Ruhr industrial region hosts specialized metallization equipment builders with 18-24 month lead times for vacuum deposition chambers.
India
Domestic FMCG brands in Maharashtra and Gujarat are expanding orders for metallized flexible films in single-serve snack applications. BIS certification mandates under IS 9845 standards consolidate supply around certified converters with testing laboratory partnerships. The Mumbai-Ahmedabad corridor concentrates new blown-film capacity serving pharmaceutical export packaging demand.
China
Electronics manufacturers in the Yangtze River Delta procure anti-static films for display panel shipment protection. GB standards for food-contact plastics and MIIT industrial policy guide converter investment toward higher recycled content thresholds. The Pearl River Delta maintains optical-grade film production for label and overwrap export markets.
Japan
Precision equipment makers in the Kanto region specify ultra-clean PP films for cleanroom semiconductor packaging. METI energy efficiency standards and JIS quality certifications shape extrusion line upgrade cycles. The Osaka-Kobe industrial zone concentrates medical-grade film production for autoclave sterilization applications.
Polypropylene Packaging Films Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated resin producers capturing margin stability through captive feedstock control while independent converters compete on metallization and coating specialization. The vendor base organizes around three archetypes: resin-integrated film producers, equipment-integrated specialty converters, and regional toll manufacturers serving FMCG brand owners. Dominant competitive moves include backward integration into resin production and strategic partnerships with chemical recycling technology licensors to secure food-grade recycled feedstock validation.
Among India-based integrated producers, Jindal Poly Films Ltd and UFlex Ltd exemplify contrasting specialization strategies within the same geographic cluster, with the former representing resin-integration archetypes and the latter occupying equipment-differentiated positions in metallization capabilities. Cosmo Films Ltd anchors the precision coating specialization tier alongside these domestic competitors. European resin science specialists Borealis AG and SABIC represent upstream-controlled archetypes that supply converter networks across multiple continents.
| Leading Market Players |
|---|
| Jindal Poly Films Ltd |
| UFlex Ltd |
| Cosmo Films Ltd |
| Amcor PLC |
| Berry Global Inc |
| Polyplex Corporation Ltd |
| SABIC |
| Borealis AG |
| SRF Limited |
| Others |
Cost & Logistics Intelligence
Propylene monomer costs cascade from naphtha-cracking margins and PDH unit economics through converter pricing tiers, with integrated producers capturing margin stability while non-integrated competitors face volatile feedstock pass-through pressures across food-grade and industrial film segments.
Pricing Analysis
Capacity additions in India's western corridor are reshaping price floors for medium-thickness flexible films. Three-tier pricing structure across premium, standard, and economy levels separates metallized barrier grades from commodity cast films and recycled-content tiers. Cost compression in standard-grade segments is intensifying because polyethylene substitution in stretch applications limits PP volume leverage. Food-contact certified converters show least price sensitivity; industrial palletization buyers exhibit highest.
Supply Chain Analysis
Direct-to-FMCG channels handle high-volume contract demand while distributor networks serve regional craft brands and short-run label converters. Resin supply concentrates in Saudi Arabia, South Korea, and India; equipment fabrication anchors in Germany and Japan. Raw material dependencies span isotactic polypropylene resin, metallization aluminum wire, and corona-treatment ceramic electrodes. Single-source vulnerability runs through European vacuum deposition chamber builders. Distribution runs through converter-direct relationships for certified medical grades and fragmented toll-manufacturer networks for commodity industrial films.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical serialization compliance and chemical recycling feedstock validation, where premium pricing for certified circular grades offsets standard-grade compression.
For Market Incumbents: Extend backward integration into propylene supply or captive resin production to defend against PDH margin volatility. Secure long-term offtake agreements with chemical recycling technology licensors before food-grade recycled content mandates tighten. Reinforce position through BIS certification laboratory partnerships in India to consolidate domestic share. For New Entrants and Emerging Players: Digital printing pretreatment systems offer a technology-first wedge into short-run label and craft food packaging segments where gravure cylinder inventory strands legacy competitors. Target India's pharmaceutical export corridor for metallized lidding films with embedded track-and-trace features. Pursue toll-manufacturer partnerships with established FMCG brand owners to bypass capital-intensive extrusion line investments. For Investors and Strategic Acquirers: Consolidation pressure builds where chemical recycling feedstock validation capabilities separate qualified converters from stranded commodity producers. Five-to-ten year viability favors equipment-integrated specialists with metallization or precision coating differentiation over pure resin-integrated volume players. Monitor ECHA substance restriction timelines as inflection indicators for reformulation cost spikes and qualification cycle extensions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Captive resin sourcing insulates margin stability against naphtha-cracking volatility. |
| Chemical Recycling Feedstock Partnership | Food-grade recycled content validation secures EU Green Deal compliance positioning. |
| Digital Printing Pretreatment System Deployment | Corona-treated substrates capture share from solvent-based flexographic workflows. |
| BIS Certification Laboratory Partnership | IS 9845 compliance consolidates supply around certified converters in India. |
| Metallization Capacity Expansion | Vacuum deposition chambers differentiate barrier grades in modified-atmosphere packaging. |
Research Approach
Multiple input streams — extrusion line operator interviews, resin procurement manager surveys, and regulatory filing analysis — were reconciled against secondary validation. Primary engagement spanned plant managers at integrated film producers, procurement leads at FMCG brand owners, technical R&D directors at metallization equipment builders, and distribution channel partners across India and Germany. Secondary sources encompassed customs and trade data for propylene derivative flows, BIS certification registries, ECHA substance restriction evaluations, and SEC filings from listed packaging converters. Bottom-up capacity modeling and top-down demand segmentation were triangulated for cross-verification.
Data-stream reconciliation anchored volume projections to extrusion line utilization rates and resin consumption patterns across the analysis window. Segmentation dimensions modeled include product type, end-use industry, thickness tier, and regional regulatory cluster. CAGRs were derived from slope analysis of historical trajectory against capacity buildout schedules and substitution elasticity estimates. Industry-specific forecast inputs incorporated REACH reformulation timelines and BIS certification expansion rates.
The model holds under stable propylene feedstock availability and current regulatory enforcement intensity; deviation in naphtha-cracking margins or accelerated ECHA restriction timelines would shift trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Mexico Plastic Packaging Films Market
Poly film
Colourless Polyimide Films Market
Poly film
Resealable Films Market
Poly film
Polyethylene Terephthalate (PET) Shrink Films Market
Poly film
Polyvinyl Alcohol (PVA) Films Market
Poly film
India Plastic Packaging Film Market
Poly film
Nylon Films Market
Poly film
US Cleanroom Film and Bags Market
Poly film
China BOPP Film Market
Poly film
PVC Films Market
Poly film
North America Shrink and Stretch Film Market
Poly film
Bi-Axially Oriented Polypropylene (BOPP) Market
Poly film
Middle East and Africa Plastic Packaging Films Market
Poly film
Italy Plastic Packaging Films Market
Poly film
PVC Cling Film Market
Poly film
PCR Lidding Films Market