
 Wrap Around Label Films Market | 2026-2036
Wrap Around Label Films Market Size, Share, and Industry Trends Forecast 2026-2036
Wrap Around Label Films Market Analytics
Market Context with Strategic Players
The split between premium shrink sleeve films and commodity stretch labels is restructuring procurement patterns across beverage and personal care supply chains. Avery Dennison leverages its materials science portfolio to dominate specification-driven segments in North American beverage packaging. Dow Inc. sustains cost leadership in polyethylene substrates through backward integration into resin production. Taghleef Industries specializes in biaxially oriented polypropylene films that serve European cosmetics brand owners seeking high-clarity decoration.
Technical Definition and Structural Segments
Wrap around label films are engineered polymer substrates—typically 30 to 50 micrometers thick—designed to conform to container contours through heat shrinkage, elastic stretch, or adhesive bonding, primarily enabling full-body product decoration, tamper evidence, and regulatory compliance printing. Shrink sleeve films lead value generation due to their 360-degree print real estate and compatibility with complex container geometries in premium beverage and cosmetics applications. Polypropylene substrates represent the fastest-expanding material category as converters seek lower density alternatives to PVC with comparable clarity and print receptivity.
Regulatory Frame and Forward-Looking Close
The EU's Packaging and Packaging Waste Regulation and the US FDA's food contact substance notifications shape material selection and multi-layer film recyclability requirements across export-oriented supply chains. REACH restrictions on phthalate plasticizers and emerging state-level extended producer responsibility laws in California and New York are accelerating PVC displacement in favor of PET and polyolefin alternatives. Stakeholders must monitor polymer traceability mandates and recyclability certification schemes to align product development with evolving market access conditions.
Market Dynamics
Material substitution pressures from REACH phthalate restrictions and the EU's Packaging and Packaging Waste Regulation are compressing PVC's dominance while accelerating PET and polyolefin qualification cycles across converter supply chains.
Growth Catalysts
- Shrink Sleeve Adoption:Beverage brand owners specify 360-degree decoration formats for tamper evidence and premium shelf differentiation in carbonated soft drinks and craft spirits.
- REACH Plasticizer Bans:ECHA restrictions on ortho-phthalates in food contact applications force PVC displacement toward PET-G and OPS substrates in European export supply chains.
- German Cosmetics Cluster:High-clarity film demand concentrates around Düsseldorf and Hamburg packaging hubs serving premium skincare and fragrance houses.
Market Restraints
- Resin Price Volatility:Ethylene and propylene feedstock swings compress converter margins on polyethylene and polypropylene label films.
- Multi-Material Recyclability:Adhesive layers and inks complicate mechanical recycling streams under EU Packaging and Packaging Waste Regulation sorting mandates.
- Substrate Thickness Floor:Downgauging limits for shrink sleeve films constrain material cost reduction below 30-micrometer thresholds without print quality degradation.
Strategic Opportunities
- Indian Beverage Expansion:FSSAI-compliant food contact films face underpenetrated demand from domestic bottled water and juice brand owners modernizing packaging lines.
- Digital Printing Convergence:UV inkjet and water-based flexo technologies enable short-run customization for craft beverage microbreweries and regional cosmetics startups.
- California EPR Laws:Extended producer responsibility frameworks create specification premiums for mono-material recyclable films in wine and spirits export packaging.
Industry Challenges
- Color Management Expertise:Converters lack skilled prepress technicians capable of calibrating expanded gamut printing across shrinkage-variable substrates.
- Film Certification Timelines:FDA food contact substance notifications and EU compliance documentation extend new substrate qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wrap Around Label Films Market |
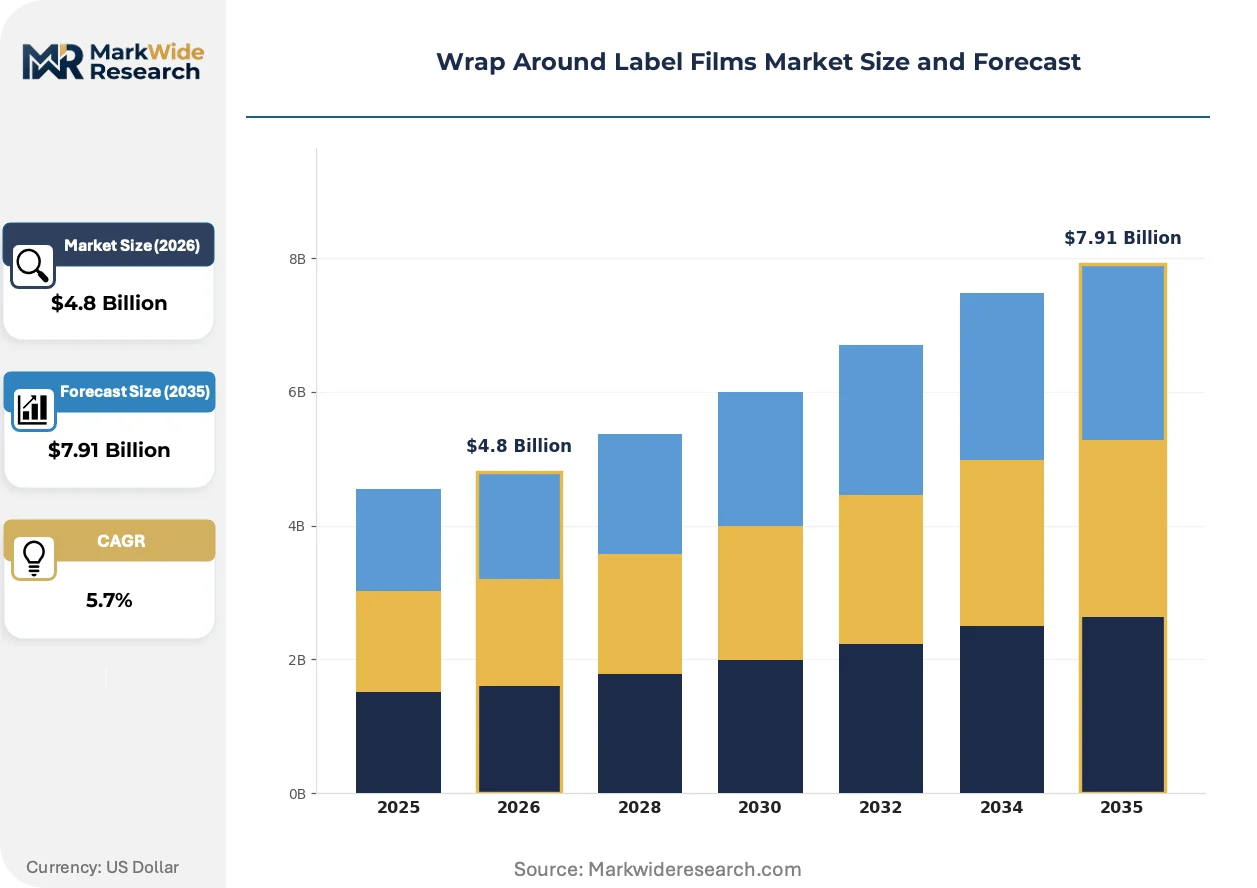
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive, Shrink Sleeve, Stretch Sleeve, In-Mold Material: Polypropylene, Polyethylene, PVC, PET Application: Food & Beverage, Cosmetics, Pharmaceuticals, Household End User: Manufacturers, Retailers, Distributors, Brand Owners |
| Companies Covered | Dow Inc., Avery Dennison, CCL Industries, Mondi, Amcor, Taghleef Industries, ExxonMobil, Huhtamaki, Toray Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wrap Around Label Films Market Evolving Landscape
Active differentiation in wrap around label films centers on sustainability credentialing and print technology migration, with substrate chemistry and decoration method selection increasingly tied to regulatory compliance rather than purely aesthetic outcomes.
Water-based ink systems is electrifying flexographic and gravure printing workflows by eliminating solvent recovery infrastructure requirements. Mid-size converters in North American beverage supply chains are retrofitting presses to capture California and New York state air quality mandates. This technology is compressing capital barriers for regional players while elevating print quality parity with solvent-based alternatives.
EU Green Deal packaging targets are mandating minimum recycled content thresholds and design-for-recycling protocols across export-oriented supply chains. The European Commission's delegated acts under the Packaging and Packaging Waste Regulation specify recyclability performance grades that determine market access. German and French brand owners are accelerating mono-material PET sleeve specifications to secure AAA recyclability ratings.
Direct-to-brand converter relationships are displacing traditional distributor-mediated procurement in premium beverage and cosmetics segments. Specialty film producers are establishing technical service partnerships with mid-size brand owners for co-development of substrate-print-process combinations. This pattern concentrates most visibly in California wine country and Northeast US craft spirits corridors where batch customization commands price premiums.
Wrap Around Label Films Market Segmentation
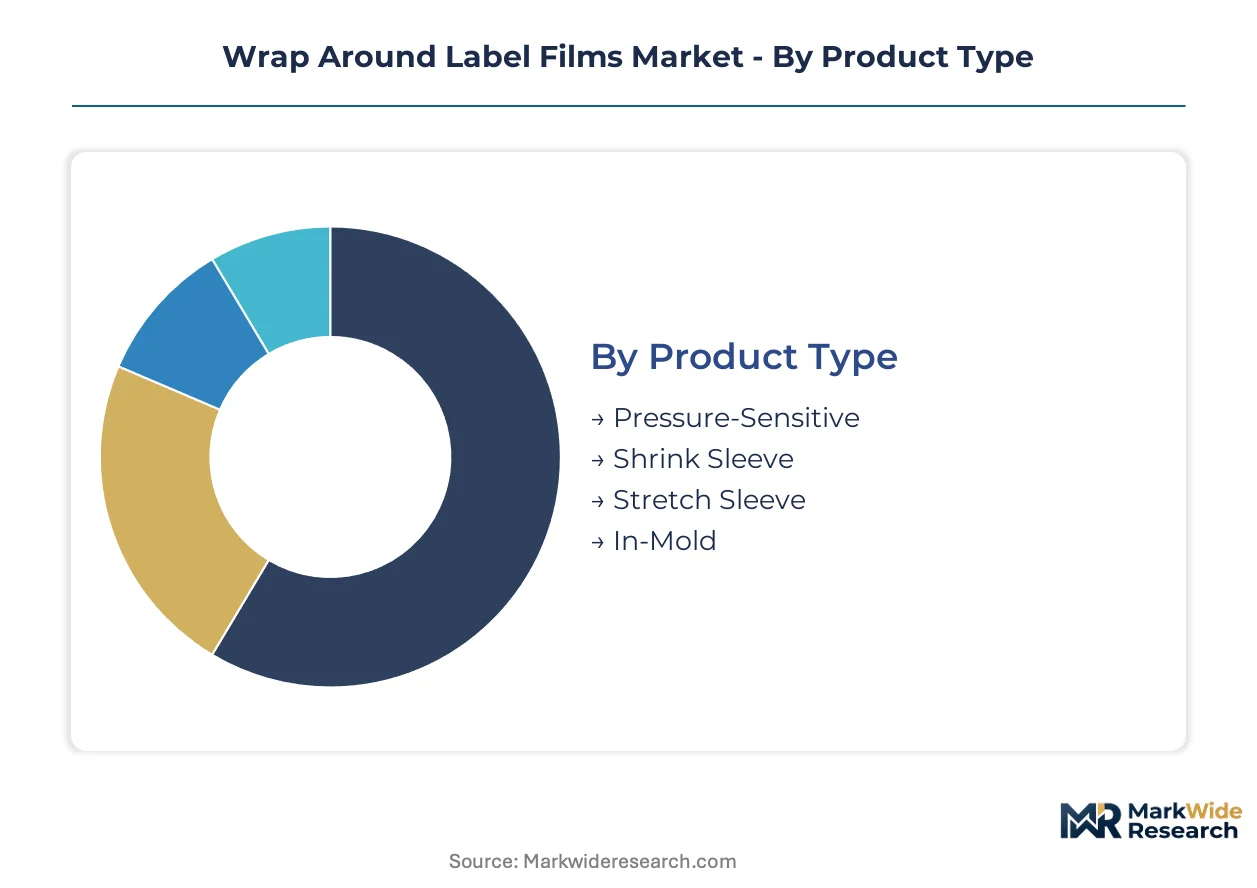
Segmentation in wrap around label films reveals how capital deployment, regulatory compliance, and decoration requirements split procurement budgets across converter supply chains. Understanding these fault lines exposes where specification power concentrates and where substrate substitution creates margin pressure.
Product Type:
Capital intensity varies sharply across these four formats, with shrink sleeve lines demanding extrusion, orientation, and slitting investments that stretch into eight-figure dollar commitments for world-scale capacity.
- Shrink Sleeve:Heat-activated films ranging 30-50 micrometers that conform to complex container geometries through controlled shrinkage. Beverage brand owners in Germany and California specify these for 360-degree decoration and tamper-evident seals on premium spirits and craft carbonated drinks. REACH phthalate restrictions and EU Packaging and Packaging Waste Regulation recyclability mandates accelerate PET-G and OPS displacement of legacy PVC formulations.
- Pressure-Sensitive:Adhesive-coated films applied without heat activation, relying on release liners and face stock combinations for flat or gently curved substrates. Food manufacturers in the US leverage these for high-speed labeling lines where thermal sensitivity of container contents prohibits shrink tunnel exposure.
- Stretch Sleeve:Elastic films that cling through mechanical tension rather than heat shrinkage, eliminating energy-intensive tunnel equipment. Logistics operators favor these for pallet-level identification and secondary packaging bundling.
- In-Mold:Pre-printed films inserted into injection molding tools for fusion with container walls during formation. Automotive and durable goods applications dominate, with cosmetics houses testing integration for premium fragrance bottles.
Shrink sleeve absorbs the bulk of installed capacity; stretch sleeve is expanding most quickly.
Material:
Density and clarity specifications drive procurement decisions, with lower-density alternatives capturing share as freight costs and sustainability scoring intensify.
- Polypropylene:Biaxially oriented grades deliver exceptional optical clarity at 0.90 g/cm³ density, reducing transport costs versus PVC. European cosmetics brand owners cluster specifications around Düsseldorf and Hamburg packaging hubs. ECHA REACH compliance documentation and EU Green Deal recycled content thresholds accelerate qualification cycles.
- PVC:Legacy substrate with established shrinkage control and print receptivity, now compressed by ortho-phthalate plasticizer bans in food contact applications. Remains entrenched in industrial labeling where regulatory exposure is limited.
- Polyethylene:Linear low-density formulations offer cost positioning and moisture resistance for household and industrial applications. Dow Inc. and other resin-integrated producers exploit backward integration into ethylene production.
- PET:Glycol-modified PET-G variants provide controlled shrinkage for high-definition graphics on contoured bottles. California wine exporters specify mono-material PET sleeves to secure AAA recyclability ratings under extended producer responsibility frameworks.
Polypropylene captures the steepest expansion trajectory as converters qualify lower-density alternatives; PVC retains residual share in non-food segments.
Application:
End-use concentration determines specification intensity, with premium beverage and cosmetics applications driving substrate innovation while commodity household segments prioritize unit cost.
- Food & Beverage:Dominant demand concentration spanning carbonated soft drinks, bottled water, craft spirits, and functional beverages. FDA food contact substance notifications and FSSAI compliance requirements in India shape material selection timelines.
- Cosmetics:High-clarity requirements and small-batch customization needs concentrate in German, French, and Northeast US packaging corridors. Digital printing convergence enables regional craft brand launches with shorter runs.
- Pharmaceuticals:Tamper evidence and serialization mandates drive specification, with regulatory documentation burdens extending qualification cycles.
- Household:Cleaners, detergents, and air care products prioritize chemical resistance and cost efficiency over optical properties.
Food and beverage commands the largest share of converter throughput; cosmetics is gaining share fastest on premiumization trends.
End User:
Procurement authority fragmentation creates divergent sales motions, from technical co-development with brand owners to price-driven distributor negotiations.
- Brand Owners:Direct specification of substrate-print-process combinations, particularly in California wine country and US craft spirits corridors where batch customization commands premiums. These relationships displace traditional distributor mediation.
- Manufacturers:Contract packagers and co-manufacturers executing brand owner specifications with limited autonomy over material selection.
- Retailers:Private label programs with standardized specifications and volume-driven procurement, concentrated in mass-market beverage and household segments.
- Distributors:Inventory-carrying intermediaries serving fragmented regional converters with commodity grades and technical support.
Brand owners absorb the bulk of strategic attention from specialty film producers; manufacturers are expanding most quickly as co-packing consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf anchors specification intensity for wrap around label films, serving German cosmetics houses and beverage exporters navigating EU Packaging and Packaging Waste Regulation recyclability mandates. The market's geographic footprint reflects premium packaging cluster concentration and regulatory jurisdiction layering.
Germany
Beverage brand owners in Hamburg and Düsseldorf specify high-clarity shrink sleeve films for craft spirits and functional water segments. ECHA REACH restrictions on ortho-phthalate plasticizers accelerate PET-G and OPS substrate displacement of legacy PVC formulations. The Rhine-Ruhr packaging corridor concentrates converter capacity serving premium skincare and fragrance houses.
United States
California wine exporters and Northeast craft spirits distillers drive demand for mono-material recyclable sleeves under state extended producer responsibility frameworks. FDA food contact substance notification requirements shape substrate qualification timelines for domestic beverage lines. Sonoma County and Finger Lakes packaging hubs specialize in short-run digital printing for batch-customized labels.
India
FSSAI-compliant food contact films face underpenetrated demand from domestic bottled water and juice brand owners modernizing packaging infrastructure. The country's central food safety regulator mandates migration testing protocols that extend foreign substrate qualification cycles. Maharashtra and Gujarat industrial corridors concentrate converter investment serving regional beverage distribution networks.
China
Carbonated soft drink manufacturers specify shrink sleeve formats for 360-degree decoration on complex bottle geometries. SAMR food contact material regulations and GB standards compliance documentation shape import substitution strategies for domestic film producers. Yangtze River Delta packaging clusters integrate digital printing workflows for regional brand customization.
France
Luxury fragrance houses and champagne exporters drive high-clarity film specifications for premium shelf differentiation. ANSM cosmetic packaging regulations and EU Green Deal recycled content thresholds accelerate mono-material qualification. Île-de-France packaging corridors concentrate technical service partnerships between film producers and brand owners.
Wrap Around Label Films Market Competitive Landscape
Capital-heavy resin-integrated producers compete with asset-light specialty film designers for specification authority across converter supply chains. The market structure fragments across three tiers: multinational chemical conglomerates with captive ethylene and propylene supply, regional converters with backward integration into film extrusion, and technology-focused specialists in biaxially oriented substrates. Strategic archetypes include resin-integrated cost leaders, specification-driven materials scientists, and digital printing workflow enablers. Dominant competitive moves encompass capacity expansion in lower-density polypropylene grades and technical co-development partnerships with premium beverage brand owners.
Among resin-integrated conglomerates, Dow Inc. and ExxonMobil occupy positions defined by upstream control over ethylene and propylene feedstocks. Avery Dennison represents the specification-driven archetype, anchoring North American beverage packaging segments through materials science capabilities. Taghleef Industries exemplifies the European specialist model, with biaxially oriented polypropylene film production serving cosmetics brand owners seeking high-clarity decoration substrates. These three companies illustrate how competitive positioning fragments across feedstock control, technical specification authority, and regional cluster proximity.
| Leading Market Players |
|---|
| Dow Inc. |
| Avery Dennison |
| CCL Industries |
| Mondi |
| Amcor |
| Taghleef Industries |
| ExxonMobil |
| Huhtamaki |
| Toray Industries |
| Others |
Value Network & Pricing Analysis
Water-based ink retrofitting across North American converter lines simultaneously compresses capital barriers for regional players and concentrates specification power among resin-integrated conglomerates with captive ethylene supply. This technology migration reshapes cost economics by eliminating solvent recovery infrastructure while tethering margin performance to feedstock volatility in polyethylene and polypropylene substrates.
Pricing Analysis
AAA recyclability ratings under EU extended producer responsibility frameworks anchor value-based pricing for mono-material PET sleeves. Three-tier pricing structure across premium, standard, and economy levels separates certified food-contact grades from industrial labeling commodities. Cost compression in commodity polyethylene films is intensifying because Dow Inc. and ExxonMobil exploit upstream control over ethylene production. Brand owners in California wine country show least price sensitivity for batch-customized digital print runs, while mass-market beverage retailers exhibit highest sensitivity to unit substrate costs.
Supply Chain Analysis
Propylene feedstock draws from Gulf Coast petrochemical complexes, German Rhine-Ruhr industrial corridors, and Middle Eastern export hubs. Biaxially oriented polypropylene films, glycol-modified PET-G substrates, and ortho-phthalate-free PVC alternatives constitute critical input dependencies. Single-source vulnerability concentrates around ECHA REACH compliance documentation for European export supply chains. Distribution runs through converter-direct technical partnerships in premium beverage segments and inventory-carrying distributors serving fragmented regional players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around resin-integrated producers with captive feedstock supply, as REACH plasticizer bans and EU recyclability mandates force qualification-intensive investments that weaker players cannot sustain.
For Market Incumbents: Cement specification authority in German cosmetics corridors through technical co-development partnerships with Düsseldorf and Hamburg packaging hubs. Expand backward integration into propylene production to defend margin position against feedstock volatility. Prioritize mono-material PET-G certification investments to capture AAA recyclability premiums under EU Packaging and Packaging Waste Regulation mandates. For New Entrants and Emerging Players: Digital printing workflow integration offers a technology-first wedge into California wine country and Northeast US craft spirits corridors where batch customization commands price premiums. Target underpenetrated Indian beverage converters in Maharashtra and Gujarat seeking FSSAI-compliant food contact films. Lead with short-run flexibility and rapid substrate qualification timelines rather than scale economics. For Investors and Strategic Acquirers: Exit pathways concentrate in resin-integrated conglomerates seeking biaxially oriented polypropylene capabilities. Long-term viability favors producers with demonstrated EU compliance documentation and established technical service relationships. Watch for ECHA delegated acts on polymer traceability mandates as inflection indicators for qualification-intensive consolidation waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Production | Dow Inc. and ExxonMobil lock in cost positioning against feedstock volatility in label film substrates. |
| Mono-Material PET-G Certification Investment | Specialty film producers secure AAA recyclability ratings under EU extended producer responsibility frameworks. |
| Digital Printing Workflow Partnership | Converters capture California and New York state air quality mandates while enabling craft brand customization. |
| Technical Co-Development with Brand Owners | Film producers displace distributor mediation in Sonoma County and Finger Lakes packaging corridors. |
| FSSAI Compliance Qualification for Indian Market | Foreign substrate producers overcome extended migration testing protocols in Maharashtra beverage distribution networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with film extrusion plant managers, beverage brand owner procurement leads, converter technical directors, and ECHA regulatory affairs specialists. FDA food contact substance notifications, EU Packaging and Packaging Waste Regulation delegated acts, FSSAI compliance documentation, and SEC 10-K disclosures from resin-integrated producers provided validation benchmarks. Bottom-up substrate volume modeling triangulated against top-down end-use consumption estimates.
Reconciliation of production capacity databases with import-export trade statistics generated volume and value outputs across the projection horizon. Segmentation dimensions spanned shrink sleeve versus stretch sleeve formats, polypropylene versus PET-G versus polyethylene material grades, food and beverage versus cosmetics versus pharmaceutical applications, and brand owner versus manufacturer versus retailer procurement authority. CAGRs derived from regression analysis of historical substrate qualification cycles and forward-looking regulatory compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA REACH restriction expansions and California extended producer responsibility enforcement accelerations. A small set of named triggers warrants ongoing watch: polymer traceability mandate delegated acts, FSSAI foreign substrate approval timelines, and propylene feedstock price volatility spikes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Thermoforming Films Market
Poly film
Isotropic Film Market
Poly film
Foamed Polypropylene Films Market
Poly film
Tube Laminating Films Market
Poly film
US Cleanroom Film and Bags Market
Poly film
Polyethylene Furanoate Films Market
Poly film
Soft Touch Lamination Film Market
Poly film
Starch-Based Plastic Films Market
Poly film
Bopet Films Market
Poly film
Soft Touch Film Market
Poly film
PCR Lidding Films Market
Poly film
North America Polyimide Films Market
Poly film
Poly Coated Kraft Paper Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Shrink Bundling Films Market