
 Peelable Lid Stock Market | 2026-2036
Peelable Lid Stock Market Size, Share, and Industry Trends Forecast 2026-2036
Peelable Lid Stock Market Analytics
Fresh food retailers is collapsing as the dominant buyer archetype for standard lidding films while pharmaceutical contract packers gain share in high-barrier formats. Amcor leverages its multi-layer coextrusion capabilities to serve temperature-sensitive drug packaging. Berry Global sustains manufacturing scale across North American dairy and protein tray applications. Constantia Flexibles anchors European fresh food demand through specialized printing and forming webs.
Peelable lid stock denotes a multi-layer laminate engineered for controlled delamination, typically incorporating sealant layers of ionomer or modified polyethylene with peel strengths between 300 and 800 grams per inch for clean consumer opening. The material functions as a hermetic closure for rigid trays and cups, preserving shelf life while eliminating the need for secondary tools. Composite structures currently occupy the highest value tier due to their oxygen barrier and puncture resistance in retort applications. Tray sealing dominates unit volume across food service and retail channels, though vacuum packaging configurations are expanding fastest in premium protein and ready-meal segments.
The FDA regulates direct food contact layers under 21 CFR 177 with specific migration limits for additives and adjuvants, while the EU's MDR and forthcoming PPWR reshape material compliance obligations for medical and food applications respectively. ISO 11607 standards for sterile barrier systems further constrain substrate selection in pharmaceutical peelable formats. Stakeholders must monitor how California's SB 54 implementation timeline and the EU's recycled content mandates alter substrate economics before committing to capital-intensive line conversions.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is compressing converter margins while forcing substrate transitions toward mono-material and fiber-based laminates that sacrifice barrier performance for recyclability compliance.
Growth Catalysts
- Retort protein trays:Single-serve meat and seafood formats in North America and Western Europe are expanding oxygen-barrier lid consumption for shelf-stable convenience meals.
- EU Green Deal implementation:Member-state recycled content mandates are accelerating investment in chemically recycled polyolefin sealant layers compatible with existing tray sealing equipment.
- Pharmaceutical serialization:Track-and-trace requirements under the EU's MDR are elevating demand for tamper-evident peelable formats with integrated authentication features.
Market Restraints
- Ethylene-vinyl alcohol resin pricing:EVOH barrier layer costs have exhibited volatility tied to ethylene feedstock fluctuations, squeezing converter margins on high-performance laminates.
- German converter concentration:Tray sealing film capacity clusters in Baden-Württemberg and Bavaria, creating geographic supply risk for southern European food processors.
- Aluminum foil substitution ceiling:Fiber-based lids cannot replicate foil's light and oxygen barrier below 50 microns, limiting penetration in ambient dairy.
Strategic Opportunities
- Indian ready-meal modernization:Urban cold chain expansion in Mumbai and Delhi is enabling retort tray adoption where boil-in-bag formats previously dominated.
- Laser-scored easy-open:Precision ablation technology is converging with mono-material PP structures to deliver controlled peel without multi-layer delamination complexity.
- California SB 54 compliance services:Packaging as a service models are emerging to manage substrate qualification and Extended Producer Responsibility reporting for mid-sized food brands.
Industry Challenges
- Multi-layer coextrusion technician scarcity:Experienced operators capable of tuning Ziegler-Natta catalyst systems for peel-strength consistency are retiring faster than training programs replace them.
- ISO 11607-1 validation timelines:Pharmaceutical peelable formats require 18-24 month sterile barrier qualification cycles that delay revenue recognition for new substrate launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peelable Lid Stock Market |
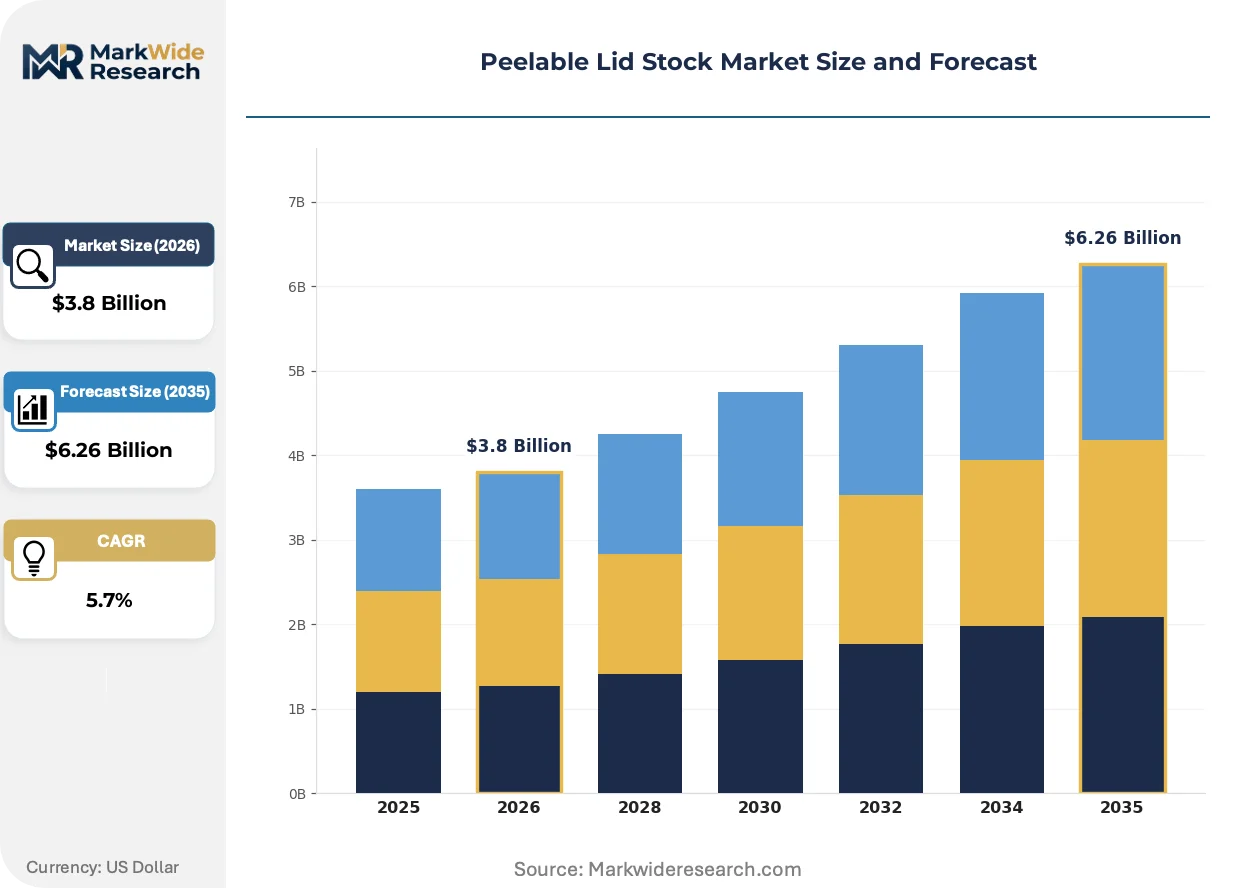
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Aluminum, Composite, Paper End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Packing Type: Tray Sealing, Vacuum Packaging, Rigid Containers, Flexible Packs Thickness: Thin, Medium, Heavy, Extra Heavy |
| Companies Covered | Berry Global, Constantia Flexibles, Amcor, Toray Plastics, DuPont Teijin Films, ProAmpac, Uflex Limited, Winpak Ltd, Sealed Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peelable Lid Stock Market Evolving Landscape
Material science advances and regulatory compliance tooling are restructuring how converters design, qualify, and commercialize peelable lid formats across food and pharmaceutical end-uses.
Water-based acrylic adhesive coatings are decomposing the traditional solvent-laminated structure for medium-barrier dairy applications. German dairy processors are piloting these formats at commercial scale for yogurt and fresh cheese cups. The technology is decomposing incumbent solvent-based systems by eliminating volatile organic compound emissions while maintaining seal integrity across refrigerated distribution.
REACH restrictions on per- and polyfluoroalkyl substances are compelling sealant layer reformulation across European converter operations. The industrial consequence is accelerated qualification of silicone-modified polyethylene alternatives that trade some hot-tack strength for regulatory compliance. Medical device packaging in Ireland and the Netherlands is experiencing the most acute reformulation pressure due to MDR sterilization validation requirements.
Direct-to-retailer specification consolidation is compressing the number of approved substrate variants that brand owners maintain. North American protein tray buyers are reducing qualified lid suppliers from twelve to four per manufacturing site to simplify inventory and auditing overhead. This concentration is most visible in the upper Midwest, where automated tray sealing lines run 24-hour operations with minimal changeover tolerance.
Peelable Lid Stock Market Segmentation
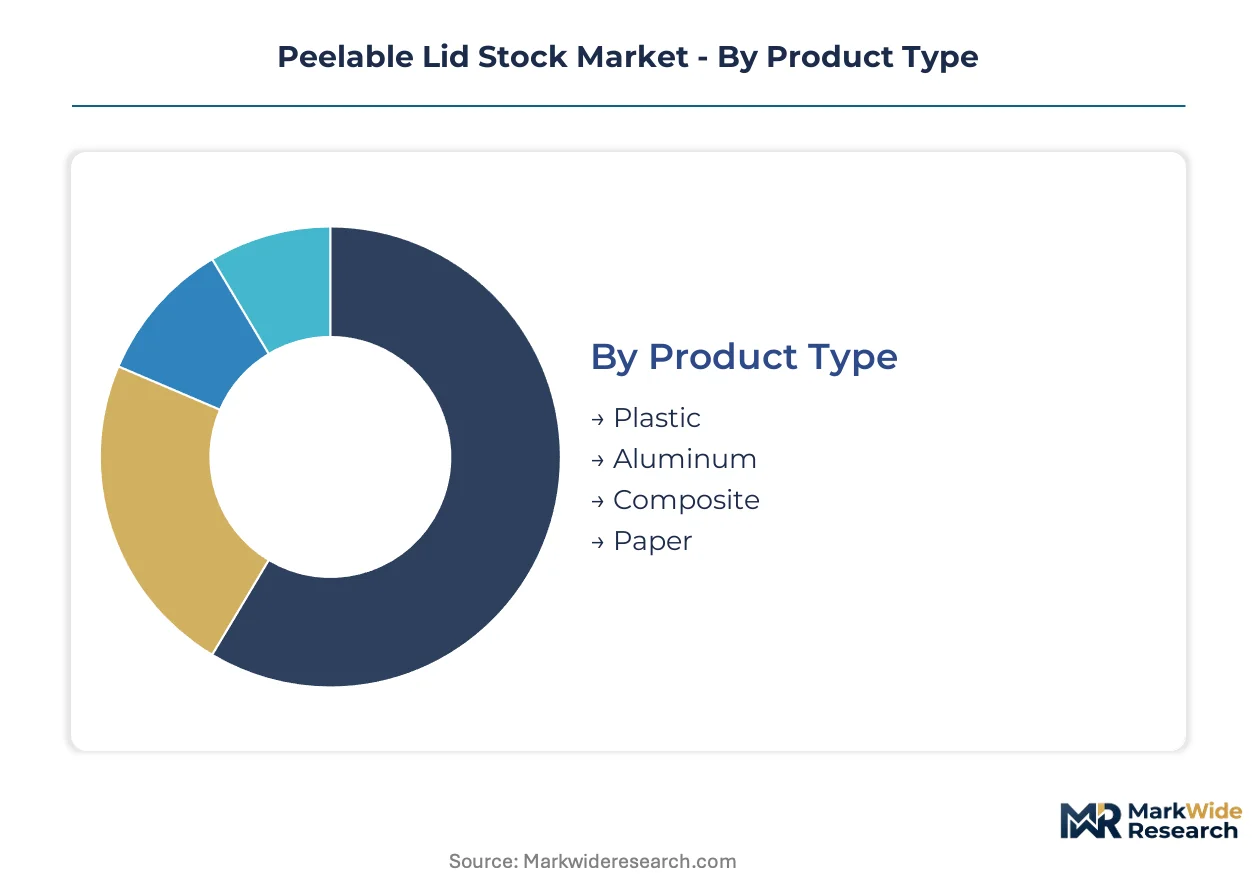
Peelable lid stock segmentation reflects divergent technical requirements across food safety, pharmaceutical sterility, and sustainability compliance. Material selection and forming method determine barrier performance, recyclability eligibility, and capital equipment compatibility for converters.
Product Type:
FDA 21 CFR 177 migration limits and EU REACH substance restrictions are fragmenting substrate approval pathways, forcing parallel qualification tracks for food-contact and medical-grade formats.
- Plastic:Multi-layer coextrusions of ionomer-modified polyethylene dominate refrigerated dairy and fresh produce. German yogurt processors are accelerating mono-material polypropylene adoption to satisfy EU Packaging and Packaging Waste Regulation recyclability mandates without sacrificing heat-seal performance.
- Composite:Aluminum-oxide-coated polyethylene terephthalate structures provide oxygen transmission rates below 0.1 cc/m²/day for retort protein trays. North American single-serve meat processors specify these laminates for shelf-stable convenience meals requiring 12-month ambient distribution.
- Aluminum:Foil-based lids deliver absolute light and oxygen barrier below 50 microns for ambient dairy and infant formula. EFSA is reviewing aluminum migration thresholds that may constrain thickness reduction strategies.
- Paper:Fiber-based barrier coatings from silicone and plant-derived waxes serve fresh bakery and dry goods where moisture resistance exceeds oxygen sensitivity. Swedish and Finnish retailers are piloting these formats for private-label sustainability commitments.
Plastic handles the majority of throughput; paper is gaining share fastest on sustainability-driven specification switches.
End User:
Customer procurement patterns diverge sharply between high-volume food automation and low-volume pharmaceutical validation cycles.
- Food & Beverage:Tray sealing lines running 24-hour operations in the upper Midwest demand peel strength consistency between 300 and 800 grams per inch for clean consumer opening without tool assistance. Direct-to-retailer consolidation is compressing approved supplier lists from twelve to four per manufacturing site.
- Pharmaceuticals:ISO 11607-1 sterile barrier systems require 18-24 month qualification timelines for new substrate launches. Irish and Dutch contract packers face acute reformulation pressure from EU MDR sterilization validation requirements combined with REACH PFAS restrictions.
- Cosmetics:Premium skincare jars utilize peelable membranes for tamper evidence and oxidation protection of active ingredients. Korean beauty brands are specifying holographic authentication layers integrated into sealant structures.
- Household Products:Wet wipe canisters and laundry pod containers employ medium-barrier laminates with child-resistant opening features. California SB 54 extended producer responsibility rules are elevating substrate documentation burdens for mid-sized brands.
Food and Beverage commands absolute volume; Pharmaceuticals climbs the fastest on serialization and authentication specification upgrades.
Packing Type:
Equipment capital intensity and changeover tolerance shape format selection across retail and food service channels.
- Tray Sealing:Rotary and inline sealers dominate unit volume across North American protein and European fresh produce. Baden-Württemberg converter clusters supply automated lines with minimal tolerance for material lot variation.
- Vacuum Packaging:Thermoformed barrier webs with peelable lids are expanding fastest in premium protein and ready-meal segments. Japanese convenience store chains are driving adoption of gas-flushed configurations for extended chilled shelf life.
- Rigid Containers:Injection-molded polypropylene cups with heat-sealed membranes serve yogurt and fresh cheese. Water-based acrylic adhesive coatings are displacing solvent-laminated structures in German dairy trials.
- Flexible Packs:Stand-up pouches with peelable spouts and resealable membranes address on-the-go consumption. Indian urban cold chain expansion in Mumbai and Delhi is enabling retort flexible formats where boil-in-bag previously dominated.
Tray Sealing carries the bulk of installed base; Vacuum Packaging shows steepest expansion trajectory on premium protein specification growth.
Thickness:
Calender control and extrusion die precision determine barrier-mass economics and forming behavior.
- Thin:Sub-40 micron structures serve cost-sensitive ambient dairy with reduced aluminum or metallized film content. EVOH barrier layer cost volatility is squeezing converter margins on these specifications.
- Medium:40-80 micron laminates balance puncture resistance and seal integrity for refrigerated distribution. This tier captures the majority of European fresh food and North American protein applications.
- Heavy:80-120 micron constructions accommodate aggressive forming and deep-draw tray geometries. Retort applications in single-serve seafood specify heavy calipers for thermal processing survivability.
- Extra Heavy:Above-120 micron formats address pharmaceutical vial lidding and industrial chemical containment where mechanical abuse resistance outweighs material cost. ISO 11607 validation timelines constrain new substrate entry in this tier.
Medium thickness manages most unit volume; Extra Heavy expands most quickly on pharmaceutical barrier system upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites continental Europe's import dependency for EVOH barrier resins and ionomer sealant raw materials. German rail corridors distribute these inputs to converter clusters in the south. This infrastructure shapes how regional supply chains respond to EU Packaging and Packaging Waste Regulation compliance deadlines.
Germany
Food packaging automation rates in Baden-Württemberg and Bavaria outpace European peers, driving specification consolidation among dairy and protein processors. The EU Green Deal's recycled content mandates are accelerating chemically recycled polyolefin trials at commercial scale. Converter capacity concentrates around Stuttgart and Munich, where 24-hour tray sealing operations demand peel strength consistency between 300 and 800 grams per inch.
United States
Retort protein tray demand from single-serve meat and seafood processors is expanding oxygen-barrier lid consumption across the upper Midwest. California SB 54 implementation timelines are elevating substrate documentation burdens for mid-sized food brands. Chicago-area converter clusters supply automated lines with minimal tolerance for material lot variation.
India
Urban cold chain expansion in Mumbai and Delhi is enabling retort tray adoption where boil-in-bag formats previously dominated ready-meal segments. The FSSAI's evolving food contact material standards are creating parallel qualification tracks for imported versus domestically produced laminates. Gujarat-based converters are scaling water-based acrylic adhesive coating capacity for yogurt cup applications.
Japan
Convenience store chains are driving gas-flushed vacuum packaging configurations for extended chilled shelf life in premium protein segments. METI's plastic resource circulation policies are pressuring converters toward mono-material structures. The Nagoya industrial corridor hosts specialized forming web operations serving pharmaceutical and food-grade peelable formats.
Netherlands
Irish and Dutch pharmaceutical contract packers face acute reformulation pressure from EU MDR sterilization validation requirements combined with REACH PFAS restrictions. The Port of Rotterdam's chemical recycling infrastructure is positioning the country as a hub for circular polyolefin sealant production. Eindhoven-region converters specialize in laser-scored easy-open technologies converging with mono-material PP structures.
Peelable Lid Stock Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and validation timeline dimensions. The market structure tiers between scale-driven multi-layer coextrusion operators and niche sterile barrier qualification specialists. Three archetypes dominate: integrated resin-to-lid converters, specialized pharmaceutical barrier validators, and regional dairy-focused formulators. M&A activity concentrates on acquiring sterile barrier validation capabilities, while capacity expansion targets chemically recycled feedstock integration.
Within the integrated converter tier, Amcor and Berry Global exemplify scale-driven positions, with the latter sustaining manufacturing footprint across North American dairy and protein tray applications. Constantia Flexibles anchors European fresh food demand through specialized printing and forming web capabilities. These three entities represent distinct geographic and technical anchoring strategies rather than overlapping competitive postures.
| Leading Market Players |
|---|
| Berry Global |
| Constantia Flexibles |
| Amcor |
| Toray Plastics |
| DuPont Teijin Films |
| ProAmpac |
| Uflex Limited |
| Winpak Ltd |
| Sealed Air |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day EVOH resin order lead times concentrate pricing power among German and Dutch converters with Port of Rotterdam access, while spot buyers in southern Europe absorb volatility premiums. This inventory asymmetry rewards integrated producers with captive sealant extrusion and punishes tray sealing specialists dependent on merchant ionomer supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by barrier performance and validation burden. Premium tiers command spreads for ISO 11607-1 qualified sterile barrier formats and retort-grade oxygen transmission specifications. Cost compression in standard dairy lidding intensifies as water-based acrylic coatings displace solvent-laminated incumbents. Protein processors in the upper Midwest exhibit lowest price sensitivity due to automation lock-in and changeover intolerance, while Indian yogurt converters drive hardest bargain on medium-barrier specifications.
Supply Chain Analysis
Rotterdam-Antwerp chemical corridors control merchant EVOH and ionomer feedstock flows into European converter clusters. Raw material sourcing draws from Saudi ethylene crackers, Japanese metallocene catalyst producers, and Korean biaxially oriented film operations. Single-source vulnerability concentrates in Ziegler-Natta catalyst systems for peel-strength consistency, where retiring technician cohorts outpace training pipeline replacement. Distribution runs through converter direct contracts with dairy and protein processors, bypassing distributor intermediaries for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peelable lid stock is approaching a platform-economics inflection as mono-material PP structures and laser-scored easy-open technologies force interoperability choices across tray sealing equipment fleets. Converters must now bet on which substrate-technology pairing achieves critical mass with OEMs.
For Market Incumbents: Secure sterile barrier validation capabilities through acquisition of Irish or Dutch pharmaceutical contract packers facing REACH PFAS reformulation pressure. Deepen backward integration into chemically recycled polyolefin feedstock to insulate margin position from virgin resin volatility and satisfy EU Green Deal recycled content mandates.
For New Entrants and Emerging Players: Lead with water-based acrylic adhesive coating capacity targeting German dairy processors piloting solvent-free transitions. Target Indian ready-meal modernization in Mumbai and Delhi, where cold chain expansion enables retort tray substitution for boil-in-bag formats without incumbent equipment lock-in.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging parents with underperforming lid stock divisions lacking pharmaceutical validation depth. Long-term viability favors converters with dual food-pharma qualification infrastructure and captive chemical recycling feedstock access. Watch laser-scored mono-material PP adoption rates in Japanese convenience store chains as inflection signal for technology winner-take-all dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Feedstock Integration | Secures EU PPWR compliance while maintaining sealant performance in existing tray sealing equipment. |
| Sterile Barrier Validation Acquisition | Compresses 18-24 month ISO 11607-1 qualification timelines through inherited regulatory dossiers. |
| Laser-Scored Easy-Open Technology Deployment | Enables mono-material PP structures to replicate controlled peel without multi-layer delamination complexity. |
| Water-Based Acrylic Coating Scale-Up | Eliminates VOC emissions for German dairy trials while matching solvent-laminated seal integrity. |
| Indian Cold Chain Partnership | Captures retort tray adoption in Mumbai and Delhi as urban logistics infrastructure matures. |
Research Methodology
The analysis maps multi-layer coextrusion, aluminum-oxide-coated PET, foil-based barrier, and fiber-based coating sub-sectors, each validated through converter operations directors, dairy processor procurement leads, pharmaceutical contract packer regulatory affairs managers, and tray sealing equipment OEM technical specialists. Primary interview findings triangulate against secondary sources including FDA 21 CFR 177 migration limit filings, EU ECHA REACH substance restriction updates, German dairy industry association sustainability reports, and customs data on EVOH resin import flows. Bottom-up substrate demand modeling reconciles with top-down packaging value chain sizing.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. The analytical framework segments by material type, end-use application, packaging format, thickness tier, and regional regulatory cluster. CAGRs derive from installed tray sealing equipment base expansion, retort protein tray adoption curves, and pharmaceutical serialization mandate implementation pacing. Forecast inputs incorporate EU PPWR recycled content mandate timelines and California SB 54 extended producer responsibility rulemaking.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal implementation, stable ethylene feedstock pricing, and technician training pipeline recovery would require recalibration. Forecasts reflect assumptions on regulatory enforcement intensity and substrate qualification cycle durations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Twist Dispensing Closures Market
Caps and Closures
Latin America Metal Caps and Closures Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
United Kingdom Plastic Caps and Closures Market
Caps and Closures
Crown Caps Market
Caps and Closures
Global Aluminum Caps for Packaging Market
Caps and Closures
Bag Closures Market
Caps and Closures
Sleeve Rubber Stoppers Market
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
Fez Caps Market
Caps and Closures
PET Dome Lids Market
Caps and Closures
Lug Caps Market
Caps and Closures
Box Latch Market
Caps and Closures
Nordic Plastic Caps and Closures Market
Caps and Closures
China Plastic Caps and Closures Market