
 Latin America Polypropylene (PP) Packaging Film Market | 2026-2036
Latin America Polypropylene (PP) Packaging Film Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Polypropylene (PP) Packaging Film Market Foresight
Multi-source procurement among Latin American converters is expanding as resin volatility and currency fluctuation expose single-source vulnerabilities. Braskem Idesa leverages its integrated petrochemical position in Mexico to secure captive propylene feedstock for film-grade output. Toray do Brasil Ltda anchors the high-clarity BOPP segment through specialized tenter-frame technology adapted to tropical humidity conditions. Vitopel do Brasil competes on medium-gauge shrink film for regional beverage bundling applications.
Latin America Polypropylene (PP) Packaging Film denotes thermoplastic olefin films extruded from isotactic polypropylene homopolymer or random copolymer resins, typically manufactured via tenter-frame biaxial orientation or cast extrusion to achieve thicknesses between 8 and 50 microns with controlled haze and seal-initiation temperatures. These films serve as barrier layers, print substrates, and heat-sealable webs for unitization, protection, and shelf-display of packaged goods across temperature-variable supply chains. BOPP film commands the largest value share due to its stiffness-to-thickness ratio and metallization compatibility, though stretch film growth outpaces it in pallet-wrapping applications driven by logistics modernization. Food packaging dominates end-user demand as processors adopt form-fill-seal formats for proteins, baked goods, and fresh produce, while pharmaceutical-grade specifications concentrate margin pools with barrier-coated and sterilizable variants.
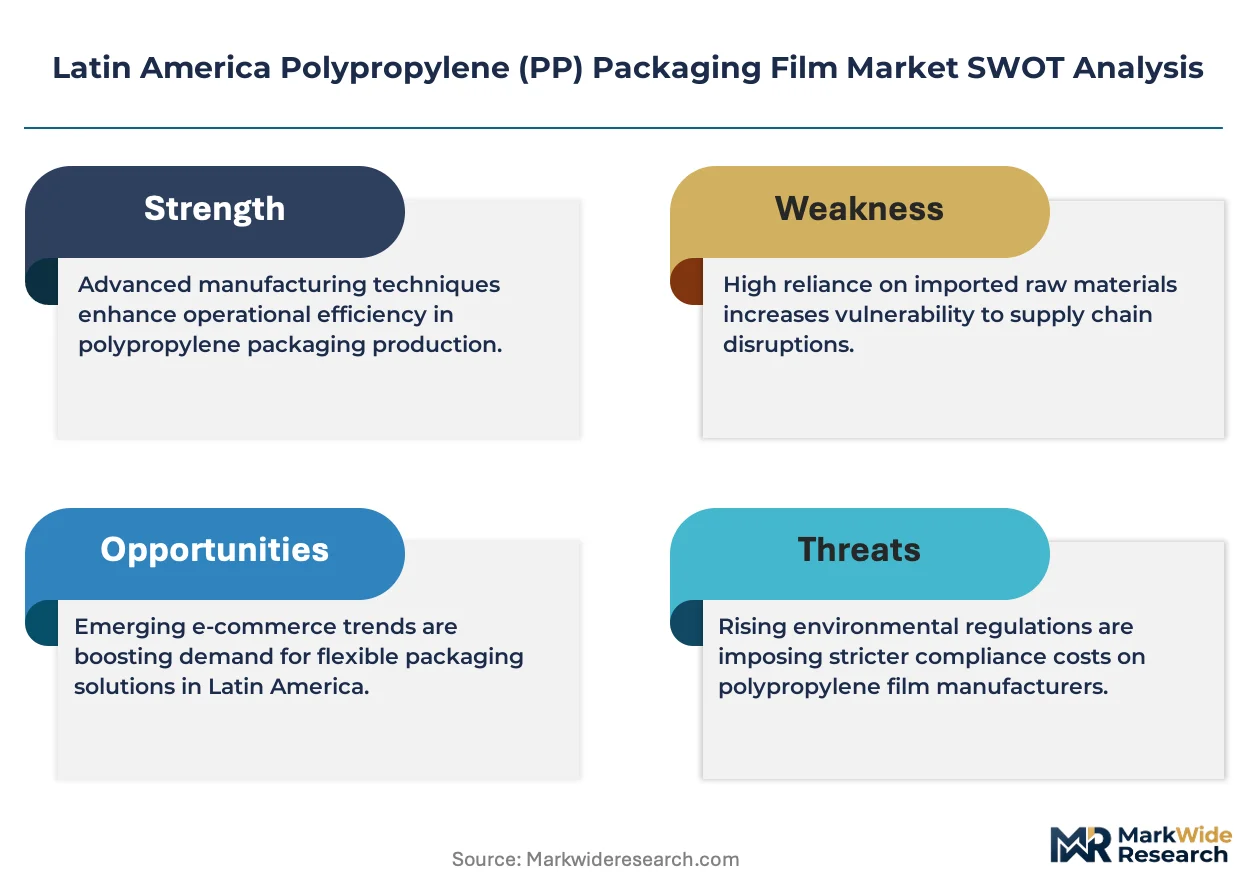
Brazil's ANVISA regulates food-contact migration limits for polypropylene films under Resolução RDC No. 326, compelling converters to maintain batch-level compliance documentation for retail-ready packaging. Mexico's COFEPRIS aligns with US FDA 21 CFR 177.1520 for cross-border food packaging, while Argentina's ANMAT enforces equivalent phytosanitary certification for agricultural film exports. Stakeholders must monitor pending Mercosur harmonization of polymer recycling content mandates, as post-consumer recycled PP integration requirements would reshape resin sourcing strategies and extrusion equipment specifications across the regional supply base.
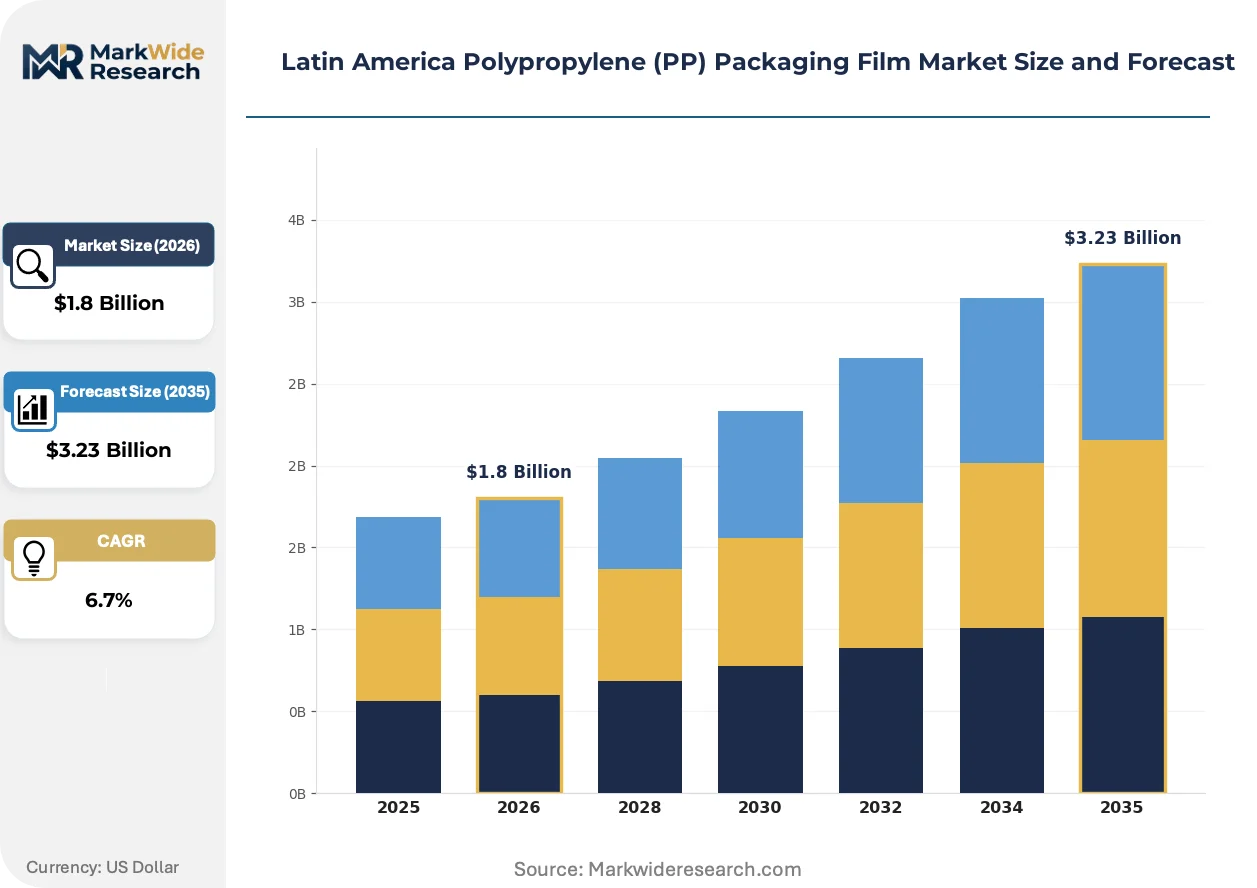
Market Dynamics
The Latin America Polypropylene (PP) Packaging Film Market is undergoing structural recalibration as Brazil's ANVISA tightens food-contact migration limits under Resolução RDC No. 326, forcing converters to rebuild supply chains around certified resin streams and batch-level documentation systems.
Growth Catalysts
- ANVISA Compliance Mandate:Brazil's food-contact material regulations are redirecting procurement toward certified suppliers with documented traceability, elevating technical barriers that favor established converters.
- Flexible Format Conversion:Food processors across São Paulo state's industrial corridor are abandoning rigid packaging for form-fill-seal films, absorbing larger BOPP volumes for proteins and fresh produce.
- Metallization Compatibility:Biaxially oriented polypropylene's stiffness-to-thickness ratio enables high-barrier metallized layers, unlocking premium shelf-display applications in temperature-variable Mercosur supply chains.
Market Restraints
- Propylene Feedstock Volatility:Resin price swings expose converters with single-source procurement, particularly those dependent on imported homopolymer grades during currency devaluation cycles.
- Mercosur Harmonization Uncertainty:Pending polymer recycling content mandates threaten to reshape extrusion equipment specifications and resin sourcing strategies before technical standards finalize.
- Cast Film Substitution:Lower-clarity cast polypropylene competes on price for non-barrier applications, compressing margins in medium-gauge segments where optical properties matter less.
Strategic Opportunities
- Post-Consumer Recycled Integration:Early adoption of rPP-compatible extrusion lines positions suppliers ahead of anticipated Mercosur mandates for circular content in retail-ready packaging.
- Pharmaceutical-Grade Barrier Coatings:Sterilizable and high-barrier variants command premium margin pools as Argentina's ANMAT enforces phytosanitary certification for medical film exports.
- Stretch Film Logistics Modernization:Pallet-wrapping applications outpace BOPP growth as distribution centers in Mexico adopt machine-grade stretch films for unitization efficiency.
Industry Challenges
- Tenter-Frame Technical Talent:Specialized operators capable of calibrating biaxial orientation lines for tropical humidity conditions remain concentrated at Toray do Brasil's established facilities.
- Dual Certification Timelines:Converters serving cross-border food packaging must simultaneously satisfy Brazil's ANVISA and Mexico's COFEPRIS documentation requirements, extending qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Polypropylene (PP) Packaging Film Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoformed, Stretch Film, Shrink Film, BOPP End User: Food Packaging, Pharmaceutical, Consumer Goods, Electronics Thickness: Lightweight, Medium, Heavyweight, Ultra-thin Application: Wraps, Bags, Pouches, Labels |
| Companies Covered | Borealis AG, Braskem Idesa, Chevron Phillips Chemical Company LLC, Celanese Corporation, Alpek S A B de C V, Toray do Brasil Ltda, Opp Film (Oben Holding Group), Vitopel do Brasil, Innovia Films, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Polypropylene (PP) Packaging Film Market Shifts & Advancements
Extrusion technology and regulatory compliance frameworks are converging to reshape competitive positioning across Latin American flexible packaging. Converters are investing in equipment flexibility and documentation systems that anticipate rather than react to policy shifts.
Digital printing integration with BOPP substrates is modularizing short-run packaging economics. Regional beverage and snack brands in Mexico are adopting digitally printed shrink sleeves for seasonal promotions, collapsing minimum order quantities from hundreds of thousands to tens of thousands of units. This compression is fragmenting volume concentration previously captured by rotogravure houses.
ANVISA's Resolução RDC No. 326 migration limits are forcing resin specification upgrades across Brazil's converting base. Batch-level compliance documentation now travels with film rolls from extrusion through slitting, creating audit trails that retailers increasingly demand. São Paulo state processors bear the heaviest compliance burden as they supply both domestic retail and Mercosur export channels.
Buyer concentration among multinational food processors is consolidating supplier qualification lists. Procurement teams at protein packers and baked goods manufacturers are reducing approved vendor counts from dozens to single-digit panels, privileging converters with integrated resin sourcing and in-house laboratory testing. This consolidation is most visible in Brazil's São Paulo industrial corridor where qualifying as a strategic supplier now requires capital investment in barrier coating capabilities.
Latin America Polypropylene (PP) Packaging Film Market Segmentation
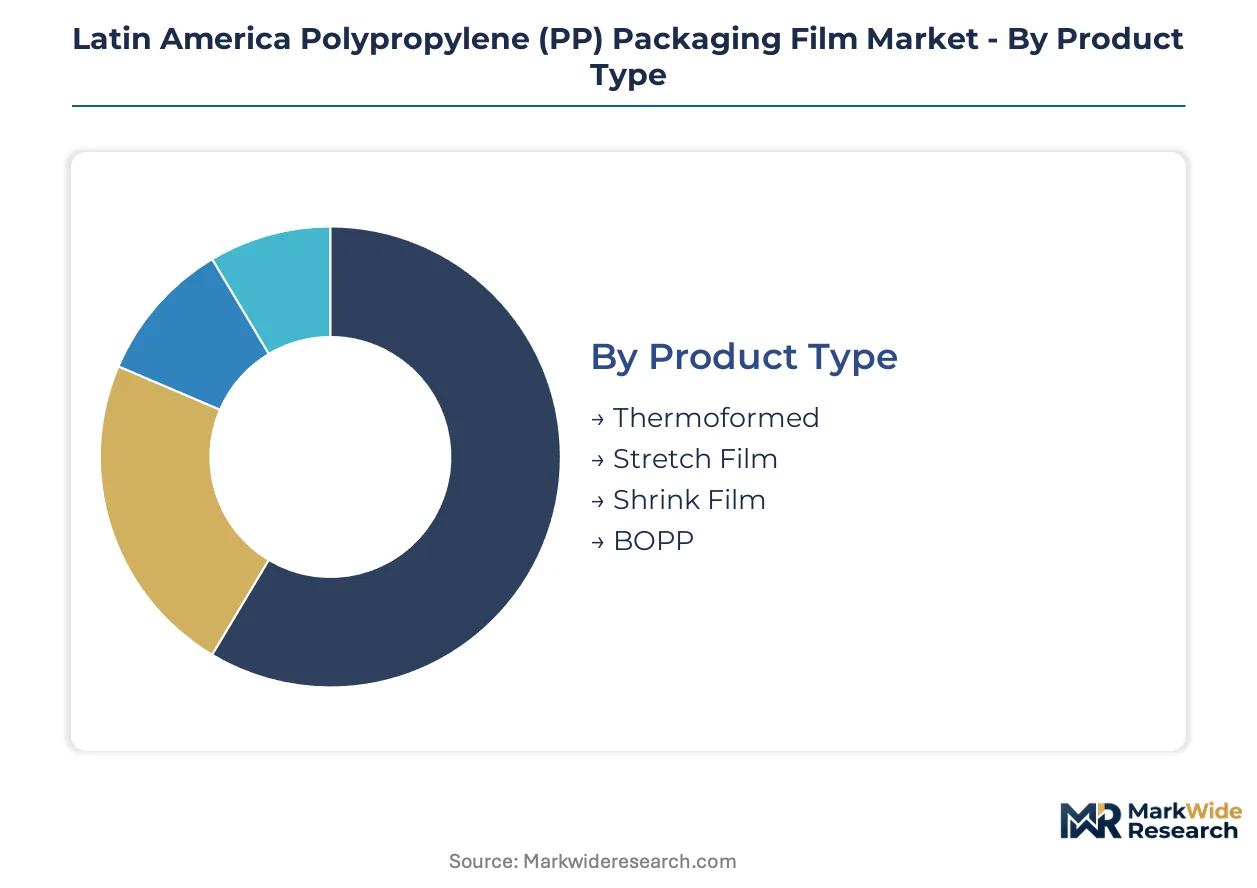
Converters across Latin America configure extrusion assets around specific film architectures that match end-use performance requirements. Equipment investment cycles and regulatory compliance burdens are segmenting procurement patterns as processors rationalize supplier panels.
Product Type:
Equipment upgrade cycles are concentrating capacity in film formats that justify tenter-frame capital outlays through volume commitment and margin stability.
- BOPP:Biaxially oriented polypropylene achieves stiffness-to-thickness ratios through sequential machine-direction and transverse-direction stretching. São Paulo state processors absorb the largest volumes for protein and fresh produce form-fill-seal applications where metallization compatibility unlocks premium shelf-display economics.
- Shrink Film:Oriented polypropylene formulations with controlled shrink initiation temperatures serve beverage bundling and multi-pack unitization across Brazil's industrial corridor. Regional bottlers specify medium-gauge specifications that balance pallet stability with material yield.
- Stretch Film:Cast extrusion lines produce machine-grade formulations for pallet-wrapping logistics modernization in Mexican distribution centers.
- Thermoformed:Sheet-fed and roll-fed formats compete with rigid trays in protein and dairy packaging where depth-draw capability matters.
BOPP sits at the top of the volume ranking, with stretch film climbing the fastest as logistics operators automate pallet unitization.
End User:
Margin concentration varies sharply by end-use certification burden and barrier performance requirements.
- Food Packaging:ANVISA Resolução RDC No. 326 migration limits compel batch-level documentation from extrusion through slitting. São Paulo converters serving Mercosur export channels bear the heaviest compliance investment as retailers demand audit trails.
- Pharmaceutical:Sterilizable and high-barrier coated variants command premium positioning under Argentina's ANMAT phytosanitary certification requirements for medical film exports.
- Consumer Goods:Digitally printed shrink sleeves for seasonal promotions are collapsing minimum order quantities from rotogravure-scale volumes to short-run economics.
- Electronics:Anti-static formulations serve component packaging with controlled surface resistivity for sensitive semiconductor shipments.
Food packaging absorbs the largest film tonnage, with pharmaceutical applications expanding most quickly as barrier coating capabilities concentrate among qualified suppliers.
Thickness:
Gauge specification directly determines extrusion line configuration and resin throughput economics.
- Medium:20-35 micron specifications dominate beverage bundling and general-purpose overwrap where optical clarity requirements are moderate. Brazilian converters optimize tenter-frame output around this gauge band for volume throughput.
- Lightweight:Sub-20 micron films serve label and flexible pouch applications where yield per resin kilogram drives procurement decisions. Mexican processors specify these gauges for cost-sensitive snack packaging.
- Heavyweight:Above-35 micron constructions provide puncture resistance for protein trays and industrial textile wrapping.
- Ultra-thin:Sub-12 micron developments target source reduction mandates though technical challenges remain in maintaining tear resistance.
Medium gauge commands the largest installed capacity base, with lightweight specifications gaining share fastest as downgauging pressures intensify across price-sensitive end-uses.
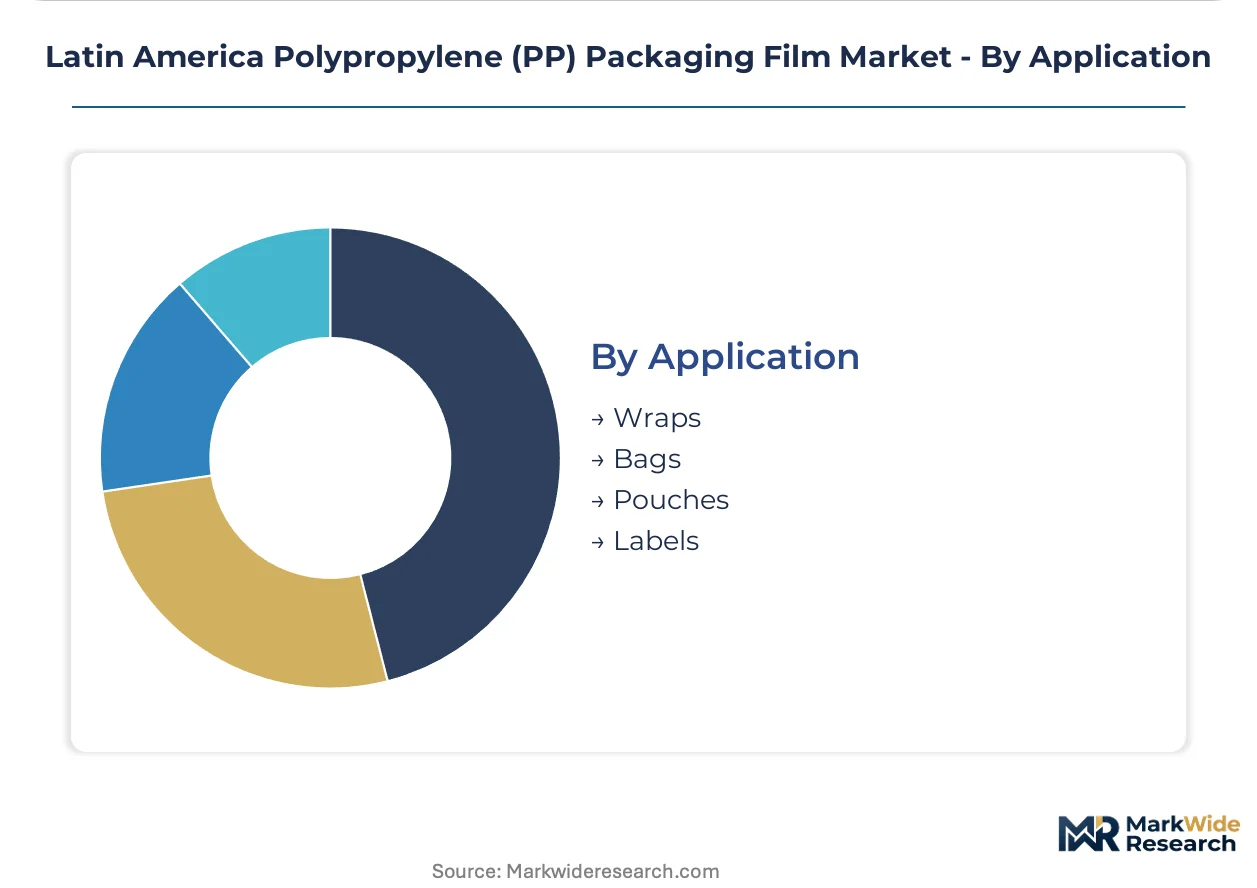
Application:
Format selection tracks packaging machinery installed base and shelf-display requirements across retail channels.
- Pouches:Stand-up and flat pouch constructions absorb BOPP and metallized film laminates for premium snack and pet food presentation. Brazilian processors invest in pouch-making lines that integrate with existing extrusion capacity.
- Wraps:Flow-wrap and overwrap formats serve bakery and confectionery with high-speed form-fill-seal compatibility. São Paulo state bakeries specify these for automated packaging lines.
- Bags:Wicketed and side-seal configurations compete with polyethylene in produce and bulk goods where stiffness aids stacking.
- Labels:Pressure-sensitive and shrink-sleeve substrates require specialized surface treatment and print receptivity coatings.
Pouch applications lead by value contribution, with wrap formats expanding most quickly as bakery automation penetrates mid-tier Brazilian processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's industrial corridor anchors Latin American polypropylene packaging film demand, with converting clusters serving both Brazilian domestic consumption and Mercosur export channels through integrated extrusion and metallization capabilities.
Brazil
Food processors across São Paulo's industrial belt are abandoning rigid formats for flexible BOPP films in protein and fresh produce packaging. ANVISA's Resolução RDC No. 326 migration limits compel batch-level compliance documentation from extrusion through slitting. São Paulo state converters bear the heaviest certification burden as they supply both domestic retail and cross-border Mercosur channels.
Mexico
Distribution centers in Mexican logistics hubs are automating pallet unitization with machine-grade stretch films, outpacing BOPP growth rates in this application segment. COFEPRIS aligns food-contact regulations with US FDA 21 CFR 177.1520 for cross-border packaging integration. Braskem Idesa leverages its integrated petrochemical position to secure captive propylene feedstock for film-grade output.
Argentina
Pharmaceutical-grade barrier films command premium positioning as ANMAT enforces phytosanitary certification for medical film exports. Buenos Aires province converters specialize in sterilizable and high-barrier coated variants for regional healthcare supply chains. Agricultural film exporters face equivalent phytosanitary requirements that concentrate margin pools among qualified suppliers.
Chile
Fresh produce export logistics drive demand for breathable BOPP films with controlled atmosphere properties for fruit shipment to North American and Asian markets. Santiago Metropolitan Region packaging distributors serve mining sector supply chains with industrial wrapping applications. Valparaíso port infrastructure supports film import distribution for regional converting operations.
Colombia
Bogotá's converting sector processes medium-gauge shrink films for beverage bundling applications serving Andean regional markets. Antioquia department industrial zones host growing flexible packaging operations targeting domestic snack food processors. Coffee export packaging requirements sustain specialized high-clarity film demand for premium product presentation.
Latin America Polypropylene (PP) Packaging Film Market Competitive Landscape
Global majors compete with regional champions across resin integration and regulatory certification dimensions. The market structures around three tiers: integrated petrochemical producers with captive feedstock, specialized film converters with tenter-frame expertise, and regional distributors with logistics optimization capabilities. Dominant competitive moves include backward integration into propylene supply and strategic partnerships with food processors for co-developed barrier specifications.
Among integrated petrochemical players, Braskem Idesa anchors the resin-integrated tier with Mexican production base advantages. Toray do Brasil Ltda and Vitopel do Brasil occupy positions within the specialized converting segment, with the former representing high-clarity BOPP capability and the latter exemplifying medium-gauge shrink film focus for beverage applications. These three names illustrate how competitive positioning stratifies across feedstock control, technical specialization, and end-use targeting.
| Leading Market Players |
|---|
| Borealis AG |
| Braskem Idesa |
| Chevron Phillips Chemical Company LLC |
| Celanese Corporation |
| Alpek S A B de C V |
| Toray do Brasil Ltda |
| Opp Film (Oben Holding Group) |
| Vitopel do Brasil |
| Innovia Films |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap converters across Brazil's São Paulo state industrial corridor anchor supply discipline through multi-generational relationships with resin distributors, translating feedstock cost transparency into pricing power that shields margins during propylene volatility cycles while exposing gaps in documentation-heavy ANVISA compliance tiers.
Pricing Analysis
Propylene monomer cost pass-through dominates film-grade polypropylene pricing, with Braskem Idesa's integrated Mexican production anchoring contract-based long-term offtake structures that stabilize input costs against spot resin swings. Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-certified barrier-coated films from general-purpose shrink wraps and commodity cast extrusion grades. Cost compression in medium-gauge beverage bundling intensifies as cast film substitutes erode optical-grade premiums. Regional snack food processors exhibit highest price sensitivity, while pharmaceutical-grade sterilizable variants command inelastic demand under ANMAT certification requirements.
Supply Chain Analysis
Polypropylene resin supply rests on Brazilian and Mexican petrochemical complexes, with propylene feedstock drawing from regional naphtha crackers and imported homopolymer grades. Tenter-frame biaxial orientation equipment, metallization chambers, and barrier coating lines constitute critical component dependencies. Single-source vulnerability concentrates in tropical-humidity-calibrated tenter-frame operators, where Toray do Brasil's specialized technical talent limits rapid capacity replication. Distribution runs through São Paulo state converting clusters serving Mercosur export channels, with secondary hub operations in Mexico City and Buenos Aires provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America Polypropylene (PP) Packaging Film Market functions as a geographic-arbitrage play where Mexico's COFEPRIS-FDA alignment enables cross-border food packaging integration at lower compliance cost than Brazil's ANVISA documentation burdens.
For Market Incumbents: Deepen backward integration into propylene supply through long-term offtake agreements with Braskem Idesa or equivalent integrated producers, insulating against resin volatility that exposes single-source converters. Invest in in-house barrier coating laboratories to defend qualification status as multinational food processors consolidate supplier panels from dozens to single-digit strategic vendors. For New Entrants and Emerging Players: Mid-tier Brazilian bakery automation represents an underserved buyer archetype seeking flow-wrap formats with shorter lead times than established rotogravure houses provide. Target lightweight sub-20 micron specifications for Mexican snack packaging where downgauging pressures outpace incumbent technical adaptation. Pursue digital printing partnerships to capture seasonal promotion volumes with collapsed minimum order quantities. For Investors and Strategic Acquirers: Integrated petrochemical producers represent the most active acquirer in this space, seeking tenter-frame expertise to complete downstream film-grade capabilities. The five-to-ten year viability window favors converters with early rPP-compatible extrusion lines ahead of anticipated Mercosur circular content mandates. Monitor ANVISA batch-level documentation enforcement intensity as the inflection signal separating qualified premium suppliers from margin-compressed commodity players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Braskem Idesa's captive feedstock model demonstrates margin stability during currency devaluation cycles. |
| Barrier Coating Capability Investment | ANMAT-certified sterilizable films command premium positioning in Argentine pharmaceutical export channels. |
| rPP-Compatible Extrusion Line Adoption | Early equipment positioning anticipates Mercosur harmonized recycling content mandates. |
| Digital Printing Integration | Mexican beverage brands adopt shrink sleeves for seasonal promotions with tenfold order-quantity compression. |
| Tropical Humidity Tenter-Frame Calibration | Toray do Brasil's specialized operator concentration creates technical moats in high-clarity BOPP segments. |
Research Methodology
Coverage spans Brazil, Mexico, Argentina, Chile, and Colombia, with primary inputs from each market combining extrusion plant managers, procurement leads at multinational food processors, distribution channel partners, and regulatory affairs specialists with secondary validation through ANVISA resolutions, COFEPRIS alignments, customs and trade data, and SEC filings from petrochemical producers. Bottom-up resin throughput estimates triangulate against top-down packaging film consumption models.
Granularity-level framing applies country-specific regulatory cluster modeling alongside product-type segmentation by BOPP, shrink film, stretch film, and thermoformed architectures, with end-use splits across food packaging, pharmaceutical, consumer goods, and electronics applications. CAGRs derive from volume-demand build-ups across the projection horizon, incorporating propylene feedstock cost trajectories and flexible-format conversion rates in protein and fresh produce packaging.
Underlying measurement precision varies by segment; food packaging and BOPP film carry tighter precision than emerging stretch film logistics applications. Forecasts reflect assumptions around ANVISA enforcement intensity, Mercosur recycling mandate timelines, and propylene supply stability. Regulatory harmonization delays, currency devaluation severity, and cast film substitution acceleration warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Germany Plastic Packaging Films Market
Poly film
Silicone Release Films Market
Poly film
Polyethylene Terephthalate (PET) Shrink Films Market
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Hexacomb Packaging Market
Poly film
Polymer Waterproof Rolls Market
Poly film
Egypt Plastic Packaging Films Market
Poly film
Bio-PET Film Market
Poly film
Spain Plastic Packaging Films Market
Poly film
Soft Touch Lamination Film Market
Poly film
Global EVOH Films for Packaging Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
APET Film Market
Poly film
Light Reflective Film Market
Poly film
PP Laminating Films Market
Poly film
Poly Coated Paper Market