
 Electron High Barrier Packaging Film Market | 2026-2036
Electron High Barrier Packaging Film Market Size, Share, and Industry Trends Forecast 2026-2036
Electron High Barrier Packaging Film Market Foresight
REACH compliance is rebalancing the cost-of-entry calculus for European suppliers while simultaneously creating tiered compliance premiums across export markets. Amcor leverages its multi-site certification network to sustain cross-regional supply continuity. Toppan Printing anchors its position through specialized metallization capabilities that dominate electronics-grade barrier specifications. Mondi Group competes on renewable-content integration, differentiating its film portfolio against conventional petrochemical alternatives.
Electron high barrier packaging film denotes multilayer polymer structures engineered to achieve oxygen transmission rates below 0.1 cc/m²/day, typically incorporating metallized or ceramic-coated substrates through vacuum deposition processes. These films preserve shelf stability and prevent moisture ingress for sensitive contents across extended distribution cycles. Polyester formulations lead in pharmaceutical blister applications where dimensional stability and thermal resistance command premium positioning, while polyethylene growth concentrates in food flexible pouches driven by cost-efficient sealing performance. Blown film production retains dominance in high-volume food packaging, though extrusion coating gains traction in medical supply applications requiring precise coating weight control for sterile barrier validation.
The European Chemicals Agency enforces REACH substance restrictions that limit certain phthalate plasticizers in food-contact layers, directly redirecting formulation R&D toward non-migratory alternatives. FDA food-contact notification requirements in the United States impose parallel compliance burdens, particularly for multilayer structures incorporating recycled content streams. China's GB standards and the National Medical Products Administration pharmaceutical packaging directives add further specification complexity for suppliers serving cross-border medical device manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation specialization or unified global platforms deliver superior compliance economics.
Market Dynamics
REACH substance restrictions on phthalate plasticizers are forcing immediate reformulation across European supply chains while simultaneously creating compliance arbitrage opportunities for certified multi-site producers serving cross-border medical device manufacturers.
Growth Catalysts
- Pharmaceutical serialization mandates:The EU MDR and FDA UDI requirements for medical device traceability are expanding demand for tamper-evident barrier films in sterile packaging applications.
- China's dual carbon goals:NMPA pharmaceutical packaging directives are accelerating domestic substitution of imported high-barrier films with locally certified alternatives.
- Metallization process advances:Vacuum deposition equipment improvements are reducing oxygen transmission rate variability in electronics-grade specifications below 0.05 cc/m²/day thresholds.
Market Restraints
- Ethylene-vinyl alcohol resin concentration:Three Japanese and Korean suppliers control over 70% of global EVOH supply for coextruded barrier layers, creating input cost volatility exposure.
- REACH compliance cost escalation:ECHA substance notification requirements for novel polymer additives are extending certification timelines by 18-24 months for European market entry.
- Aluminum foil substitution:Rigid metalized laminates retain cost advantages in ambient-stable pharmaceutical applications, limiting flexible film penetration in legacy blister formats.
Strategic Opportunities
- India's medical device PLI scheme:CDSCO and DGFT import substitution incentives are creating localized demand for domestic barrier film certification to serve cardiac stent and orthopedic implant packaging.
- Mono-material recyclability:EFSA food-contact approvals for single-polymer barrier structures are enabling circular economy positioning against multilayer competitors in European retail channels.
- AI-driven coating control:Machine vision integration with vacuum deposition lines is rewriting quality assurance economics for small-batch pharmaceutical contract manufacturing.
Industry Challenges
- Vacuum metallization technician scarcity:Specialized plasma physics expertise for ceramic coating optimization commands 40% wage premiums in German and Swiss packaging clusters.
- Multilayer extrusion asset intensity:Seven-layer blown film lines with inline metallization require capital commitments exceeding 25 million euros, constraining mid-scale producer expansion.
- Cross-jurisdiction certification synchronization:Divergent FDA food-contact notification and EFSA scientific opinion timelines create inventory stranding risks for unified global formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electron High Barrier Packaging Film Market |
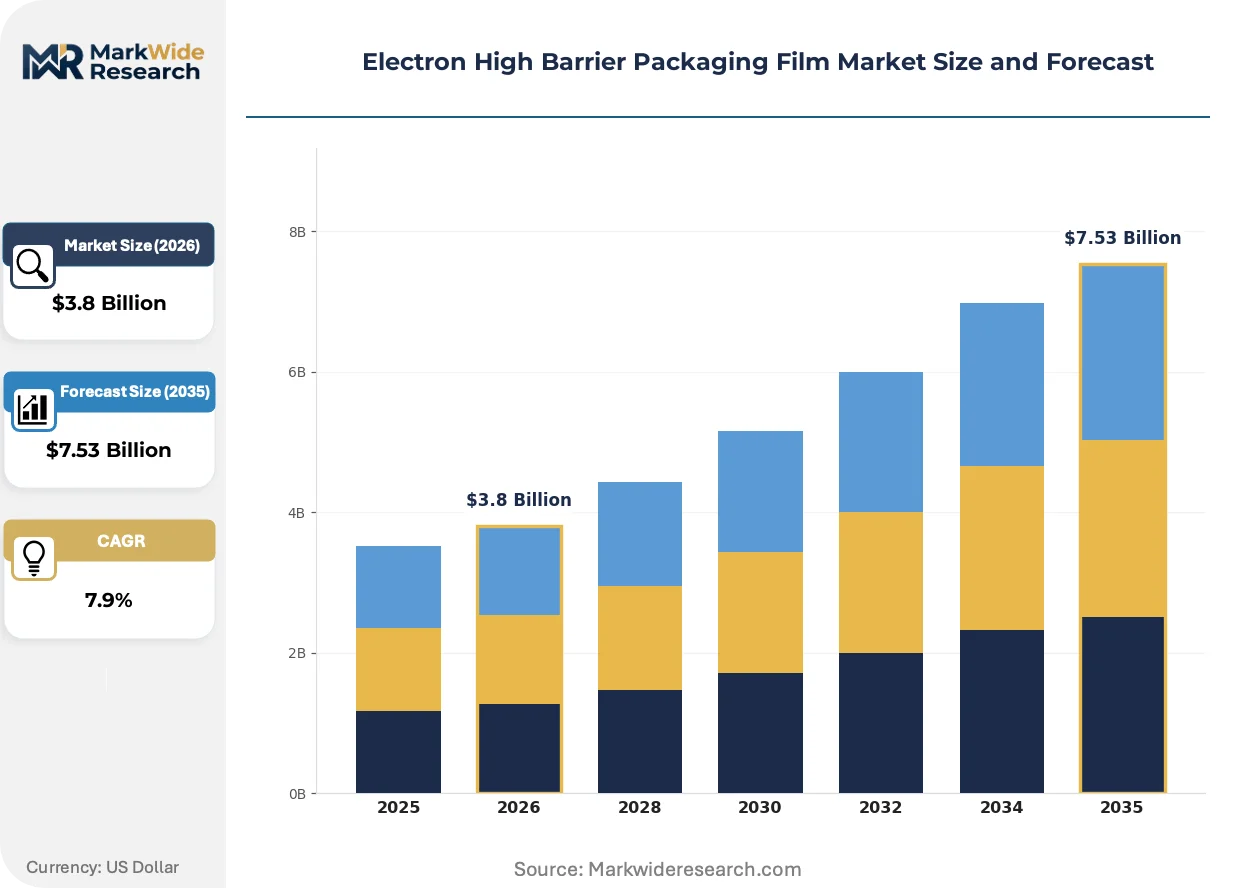
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyester, Polyethylene, Polyvinyl Chloride, Nylon Application: Food Packaging, Medical Supplies, Electronics, Industrial Products End User: Pharmaceutical Companies, Food Manufacturers, Electronics Firms, E-Commerce Production Technique: Blown Film, Cast Film, Extrusion Coating, Lamination |
| Companies Covered | Amcor, Toppan Printing, Dai Nippon Printing, DuPont Teijin Films, Toray Industries, Sealed Air Corporation, Mondi Group, Mitsubishi Chemical, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electron High Barrier Packaging Film Market Shifts & Advancements
Active barrier technologies and regulatory chemistry constraints are converging to reshape material selection criteria, with sustainability verification now competing against functional performance as the primary specification driver in premium segments.
Silicon oxide (SiOx) and aluminum oxide (AlOx) ceramic coatings applied through plasma-enhanced chemical vapor deposition are rewriting the oxygen barrier economics of transparent flexible packaging. Pharmaceutical contract manufacturers in Germany and Switzerland are adopting these transparent alternatives at triple-digit annual rates for light-sensitive biologics. The technology is compressing market share for metallized films in applications where metal detection compatibility and microwaveability command specification premiums.
ECHA's 2023 restriction proposal on per- and polyfluoroalkyl substances (PFAS) in food-contact materials is forcing immediate R&D redirection toward fluorine-free barrier chemistries. Multilayer film producers serving European retail brands are accelerating validation of bio-based polyamide alternatives and graphene-enhanced polyethylene formulations. The medical device segment faces the steepest compliance cliff, with sterile barrier validation cycles requiring 24-36 month lead times for material substitutions.
Brand-led sustainability scorecards are consolidating supplier relationships around certified circular content providers with third-party chain-of-custody documentation. Major North American food retailers are unbundling packaging procurement from finished goods contracts, creating direct relationships with specialized barrier film converters. This channel restructuring is most visible in California and Washington state markets, where extended producer responsibility legislation mandates post-consumer recycled content minimums for flexible plastic packaging.
Electron High Barrier Packaging Film Market Segmentation
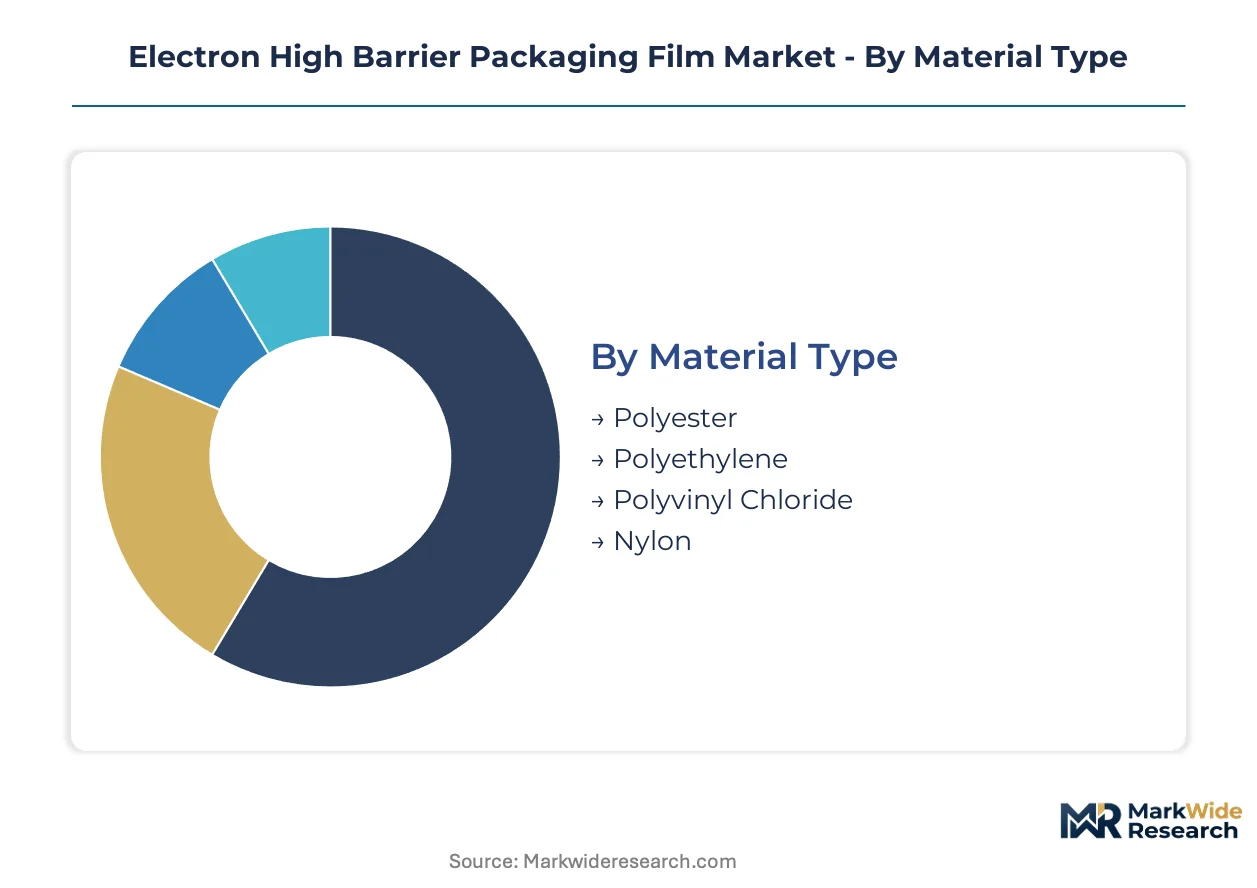
Segmentation in electron high barrier packaging film markets reveals how certification requirements, barrier performance thresholds, and production economics partition demand across material grades and end-use specifications. Understanding these divisions exposes where formulation R&D investments concentrate and which customer procurement patterns drive volume.
Material Type:
FDA food-contact notification and EFSA scientific opinion requirements vary sharply across polymer chemistries, with some materials facing mandatory migration testing while others qualify for streamlined pre-market assessments.
- Polyester:Biaxially oriented polyethylene terephthalate structures deliver dimensional stability and thermal resistance above 200°C, supporting pharmaceutical blister packs and electronics-grade moisture barriers. Demand concentrates in German and Swiss pharmaceutical clusters where FDA-compliant polyester formulations command premium positioning for sterile barrier validation.
- Polyethylene:Linear low-density and high-density variants enable cost-efficient heat sealing in flexible food pouches, though EVOH coextrusion requirements for oxygen barrier functionality add formulation complexity. Chinese food manufacturers are expanding procurement of metallized polyethylene structures for ready-to-eat meal formats under GB standards compliance.
- Polyvinyl Chloride:Rigid calendered PVC retains legacy penetration in pharmaceutical blister applications where thermoformability and clarity specifications dominate, though REACH phthalate restrictions are forcing rapid plasticizer substitution toward non-migratory alternatives.
- Nylon:Polyamide 6 and 6,6 grades provide puncture resistance and oxygen barrier performance in vacuum-packaged meat and cheese applications, with bio-based nylon variants gaining traction in European retail channels under circular content mandates.
Leading the category by volume: Polyethylene. Growing fastest: Polyester.
Application:
End-use specifications determine barrier performance tiers, with oxygen transmission rate thresholds ranging from 0.5 cc/m²/day in ambient food storage to below 0.05 cc/m²/day in electronics moisture protection.
- Food Packaging:Modified atmosphere packaging for fresh proteins and ready-to-eat meals drives blown film demand, with California and Washington state extended producer responsibility rules mandating post-consumer recycled content minimums that reshape material selection criteria.
- Medical Supplies:Sterile barrier systems for surgical instruments and diagnostic devices require validated sealing integrity and particulate control, with EU MDR traceability mandates expanding tamper-evident film specifications across German and French medical device clusters.
- Electronics:Vacuum-deposited ceramic coatings on flexible substrates protect semiconductors and displays from moisture ingress during extended supply chain cycles, with specifications tightening below 0.05 cc/m²/day in Japanese and Korean electronics manufacturing hubs.
- Industrial Products:Corrosion-inhibiting barrier films for automotive components and machinery parts emphasize UV stability and mechanical durability over oxygen barrier precision, serving distributed manufacturing networks with less stringent regulatory compliance burdens.
Food Packaging generates the highest absolute volume. Electronics exhibits the steepest expansion trajectory.
End User:
Procurement scale and technical specification authority concentrate differently across customer types, with some end users dictating formulation standards that cascade through converter tiers.
- Pharmaceutical Companies:Serialization mandates from FDA UDI and EU MDR requirements are expanding demand for tamper-evident barrier films with integrated authentication features, with validation cycles spanning 24-36 months for material substitutions.
- Food Manufacturers:Major North American retailers are unbundling packaging procurement from finished goods contracts, creating direct relationships with specialized barrier film converters and consolidating supplier relationships around certified circular content providers.
- Electronics Firms:Semiconductor and display manufacturers specify ceramic-coated transparent alternatives to metallized films where metal detection compatibility and microwaveability command premium positioning, with adoption rates climbing fastest in German and Swiss contract manufacturing.
- E-Commerce:Protective packaging for high-value consumer electronics emphasizes puncture resistance and moisture protection through lightweight multilayer structures, with volume scaling alongside cross-border direct-to-consumer shipment growth.
Pharmaceutical Companies anchor premium pricing tiers. E-Commerce is gaining share fastest.
Production Technique:
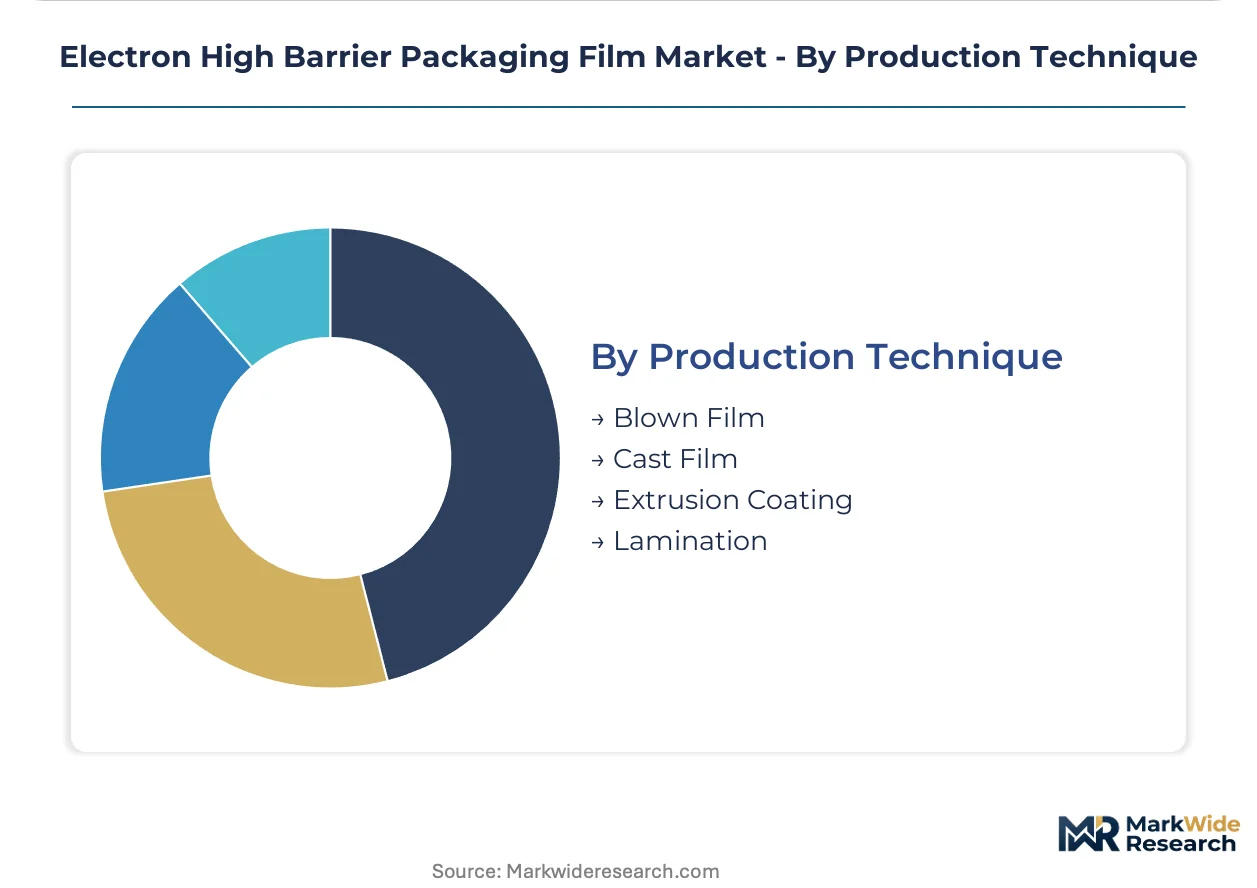
Capital intensity and batch size flexibility vary dramatically across manufacturing methods, with seven-layer blown film lines requiring 25 million euro commitments while extrusion coating enables smaller-scale pharmaceutical contract manufacturing.
- Blown Film:Tubular extrusion with inline metallization dominates high-volume food packaging production, though EVOH resin supply concentration among Japanese and Korean suppliers creates input cost volatility exposure for European and North American converters.
- Cast Film:Chill-roll extrusion delivers superior optical clarity and gauge uniformity for pharmaceutical blister applications where visual inspection requirements mandate defect-free substrates, with production gravitating toward established medical packaging clusters.
- Extrusion Coating:Precise coating weight control enables sterile barrier validation for medical supply applications, with machine vision integration rewriting quality assurance economics for small-batch pharmaceutical contract manufacturing.
- Lamination:Adhesive and extrusion lamination processes bond dissimilar substrates to achieve combined barrier properties, though multilayer structures face recyclability challenges under emerging extended producer responsibility frameworks.
Blown Film retains volume leadership. Extrusion Coating is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and Germany concentrate the highest-value procurement for electron high barrier packaging films, with electronics manufacturing clusters in East Asia and pharmaceutical packaging hubs in Central Europe driving premium specification demand.
China
Domestic substitution of imported high-barrier films accelerates under NMPA pharmaceutical packaging directives tied to dual carbon goals. GB standards compliance requirements reshape material selection for food-contact layers in ready-to-eat meal packaging. Yangtze River Delta electronics manufacturers specify ceramic-coated transparent films below 0.05 cc/m²/day oxygen transmission rates for semiconductor moisture protection.
Germany
Pharmaceutical blister packs and sterile barrier systems dominate procurement from Baden-Württemberg and Bavaria medical device clusters. ECHA REACH substance restrictions on phthalate plasticizers force immediate reformulation toward non-migratory alternatives in food-contact layers. Stuttgart-area converters specialize in seven-layer blown film lines with inline metallization for EU MDR-compliant tamper-evident packaging.
United States
FDA food-contact notification requirements impose parallel compliance burdens for multilayer structures incorporating recycled content streams. California and Washington state extended producer responsibility legislation mandates post-consumer recycled content minimums for flexible plastic packaging. Major retailers unbundle packaging procurement from finished goods contracts, creating direct relationships with specialized barrier film converters.
Japan
Electronics-grade barrier specifications below 0.05 cc/m²/day concentrate demand from METI-supported semiconductor and display manufacturing hubs. PMDA pharmaceutical packaging directives align with international sterile barrier validation standards for export-oriented medical device manufacturers. Vacuum deposition equipment improvements reduce oxygen transmission rate variability in Kansai and Chubu regional production clusters.
India
CDSCO and DGFT import substitution incentives under the medical device PLI scheme create localized demand for domestic barrier film certification. Cardiac stent and orthopedic implant packaging requirements drive sterile barrier validation investments in Maharashtra and Gujarat pharmaceutical manufacturing zones. BIS standards compliance emerges as a procurement filter for multinational medical device contract manufacturers.
Electron High Barrier Packaging Film Market Competitive Landscape
Japanese and Korean producers anchor the premium electronics-grade tier; European specialists hold pharmaceutical certification advantages through multi-site REACH compliance networks. The vendor base splits between integrated multinationals with captive resin supply and specialized converters focused on sterile barrier validation. Three archetypes dominate: metallization technology leaders, renewable-content integrators, and regional certification specialists. Capacity expansion and portfolio diversification toward mono-material recyclability represent the dominant competitive moves.
Within the premium-tier vector, Amcor exemplifies multi-site certification architecture sustaining cross-regional supply continuity. Toppan Printing and Dai Nippon Printing occupy positions as metallization technology anchors dominating electronics-grade barrier specifications. Mondi Group represents the renewable-content integration archetype, differentiating against conventional petrochemical alternatives through certified circular content positioning.
| Leading Market Players |
|---|
| Amcor |
| Toppan Printing |
| Dai Nippon Printing |
| DuPont Teijin Films |
| Toray Industries |
| Sealed Air Corporation |
| Mondi Group |
| Mitsubishi Chemical |
| Berry Global |
| Others |
Supply & Pricing Matrix
Japanese and Korean resin producers operating as sovereign-backed specialists anchor upstream supply discipline, translating concentrated EVOH ownership into sustained input cost premiums that cascade through converter pricing tiers across European and North American markets.
Pricing Analysis
Short lead-time premiums separate urgent pharmaceutical contract orders from standard food-packaging procurement cycles. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA-compliant sterile barrier films commanding substantial markups over general-purpose food-contact grades. Cost compression in standard-tier polyethylene films is intensifying because Chinese domestic substitution expands metallized film capacity. Food manufacturers exhibit highest price sensitivity, while pharmaceutical serialization mandates render electronics-grade buyers least responsive to marginal cost shifts.
Supply Chain Analysis
India's medical device PLI scheme and China's dual carbon goals are reshaping sourcing patterns through domestic-content mandates that redirect procurement toward certified local converters. Raw material supply draws from Japanese and Korean EVOH resin producers, German vacuum deposition equipment manufacturers, and Chinese metallized film converters. Single-source vulnerability concentrates in ceramic coating precursor chemicals sourced through limited German and Swiss specialty chemical channels. Distribution runs through converter-tier relationships with direct retailer unbundling in California and Washington state markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized vacuum metallization capacity scarcity props pricing across premium electronics and pharmaceutical grades, constraining volume expansion regardless of downstream demand pull.
For Market Incumbents: Anchor sterile barrier validation leadership through backward integration into EVOH coextrusion capacity in Baden-Württemberg and Bavaria clusters. Expand multi-site REACH certification networks to capture cross-border medical device manufacturer procurement consolidating around compliant single-source suppliers. Ceramic coating substitution threats from SiOx and AlOx transparent alternatives demand accelerated R&D in fluorine-free barrier chemistries to defend premium positioning.
For New Entrants and Emerging Players: Small-batch pharmaceutical contract manufacturers in Maharashtra and Gujarat pharmaceutical zones represent an underserved buyer archetype lacking domestic sterile barrier validation capabilities. India's cardiac stent and orthopedic implant packaging requirements under CDSCO directives offer the most penetrable entry vector. Machine vision-integrated extrusion coating lines enable quality assurance economics competitive with established German and Swiss converters.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European converters with stranded REACH certification investments and underutilized seven-layer blown film assets. Long-term viability centers on mono-material recyclability positioning against multilayer incumbents as EFSA approvals expand. ECHA PFAS restriction implementation timelines signal inflection points for fluorine-free chemistry validation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Coextrusion | Captive resin supply insulates Japanese and Korean input cost volatility for European converters. |
| Multi-Site REACH Certification Network | Cross-regional compliance continuity sustains medical device manufacturer supplier consolidation. |
| Machine Vision Integration with Vacuum Deposition | AI-driven coating control rewrites quality assurance economics for small-batch pharmaceutical manufacturing. |
| Fluorine-Free Barrier Chemistry Validation | ECHA PFAS restrictions force R&D redirection toward bio-based polyamide and graphene-enhanced alternatives. |
| Mono-Material Recyclability Certification | EFSA single-polymer approvals enable circular economy positioning against multilayer competitors in European retail. |
Research Methodology
Document review covered customs and trade flow databases, SEC and European exchange filings from packaging converters, ECHA substance restriction proposals, and FDA food-contact notification records, complemented by interviews with vacuum metallization equipment engineers, pharmaceutical packaging procurement managers at German medical device clusters, food manufacturer supply chain directors, and ceramic coating R&D leads at Japanese electronics materials suppliers. Bottom-up volume modeling from converter capacity utilization and top-down demand triangulation from end-use procurement patterns were cross-validated.
Historical capacity expansion patterns were cross-referenced against expert panel input from equipment manufacturers and resin suppliers. Segmentation dimensions modeled include material chemistry grade, barrier performance tier, production technique capital intensity, and regional regulatory cluster. CAGRs were derived from supply-demand balance projections incorporating EVOH resin availability constraints and certification timeline bottlenecks. Industry-specific inputs encompass vacuum deposition equipment lead times and sterile barrier validation cycle durations.
Revisions become necessary when ECHA substance restriction timelines accelerate, EFSA mono-material approval scopes expand, or NMPA domestic substitution mandates intensify beyond current dual carbon goal trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market
Packaging Barrier Films
Barrier Shrink Bags Market
Packaging Barrier Films
Global Metalized Barrier Films Market
Packaging Barrier Films
Global Air Bubble Film Machines Market
Packaging Barrier Films
Non Heat Sealable Film Market
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Flow Pack Films Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
USA Barrier Coated Paper Market
Packaging Barrier Films
Barrier Films Market
Packaging Barrier Films
Global Shrink Films Market
Packaging Barrier Films
Transport Protection Film Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
Aluminum Oxide Coated Films Market
Packaging Barrier Films
Global Micro-Perforated Films Market