
 Timber Wrap Films Market | 2026-2036
Timber Wrap Films Market Size, Share, and Industry Trends Forecast 2026-2036
Timber Wrap Films Market Outlook
Scandinavian polyethylene resin producers is rebalancing supply commitments toward specialty grades for timber protection. Trioplast Industrier AB leverages its Nordic manufacturing base to sustain consistent delivery to Baltic Sea ports. Berry Global Inc. competes through vertical integration into resin compounding, while Mondi Group differentiates via kraft-paper hybrid structures for moisture-sensitive hardwoods.
Timber wrap films are multi-layer polyolefin sheets, typically 80–200 microns thick, engineered to block ultraviolet degradation and moisture ingress during outdoor lumber storage and ocean transit. Their primary purpose is to preserve dimensional stability and grade classification of sawn timber from mill to end-user. Laminated films command margin pools due to superior puncture resistance in rough-handling environments, while stretch films represent the fastest-growing category as automated wrapping systems penetrate mid-sized sawmill operations. BOPP films occupy a mature niche for high-clarity branding applications on premium-grade exports.
The EPA governs volatile organic compound emissions from film extrusion facilities in the United States, while REACH restricts certain phthalate plasticizers in European-sourced products. The EU Green Deal accelerates demand for bio-based and recyclable alternatives, reshaping converter R&D priorities. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to invest in chemical recycling partnerships or mechanical film-to-film loop infrastructure.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing converter margins while forcing rapid material transitions toward recyclable multi-layer structures, reshaping capital allocation across extrusion operations.
Growth Catalysts
- Export-Driven Demand Concentration:Softwood shipments from the Pacific Northwest to Asian construction markets sustain high-volume film procurement. Sawmills in Oregon and Washington maintain dedicated wrapping lines for containerized lumber.
- REACH Compliance Migration:European converters are phasing out phthalate plasticizers ahead of restricted substance deadlines. Baltic Sea processors source specialty polyethylene grades from Scandinavian resin producers to meet specification.
- Automated Wrapping Penetration:Mid-sized sawmill operations in the US South are installing stretch film systems previously limited to tier-one processors. Equipment suppliers report shortened payback periods on robotic wrapping cells.
Market Restraints
- Resin Supply Concentration:Nordic polyethylene producers command pricing leverage over Baltic and North Sea converters. Long-term supply agreements now carry force majeure clauses tied to cracker maintenance cycles.
- Technical Performance Trade-offs:Mono-material structures meeting EU recyclability targets sacrifice puncture resistance versus laminated alternatives. Rough-handling environments expose films to tear propagation during port transfers.
- EPA Emission Controls:Volatile organic compound limits on extrusion facilities in the United States require thermal oxidizer investments. Smaller converters face compliance cost disadvantages against integrated competitors.
Strategic Opportunities
- Bio-Based Material White Space:The EU Green Deal creates procurement preference for films incorporating renewable feedstocks. Converters with certified bio-polyethylene supply chains access premium tender pools in Germany and France.
- Kraft-Paper Hybrid Expansion:Moisture-sensitive hardwood exporters in Southeast Asia specify paper-laminate structures for tropical transit conditions. Mondi Group's Nordic manufacturing base positions for regional supply expansion.
- Direct Mill-to-Port Distribution:Bypassing traditional distributor networks, film converters are establishing consignment inventory at Baltic Sea and Pacific Northwest port terminals. Channel compression captures margin previously allocated to intermediaries.
Industry Challenges
- Multi-Laminate Recycling Infrastructure Gap:Chemical recycling partnerships require capital commitments ahead of proven film-to-film loop economics. Converters face stranded asset risk on mechanical recycling lines unable to process adhesive-bonded structures.
- Extended Producer Responsibility Timeline Compression:EU member states are implementing divergent EPR fee structures ahead of harmonized 2025 targets. Compliance teams must navigate national registry systems with incompatible reporting formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Timber Wrap Films Market |
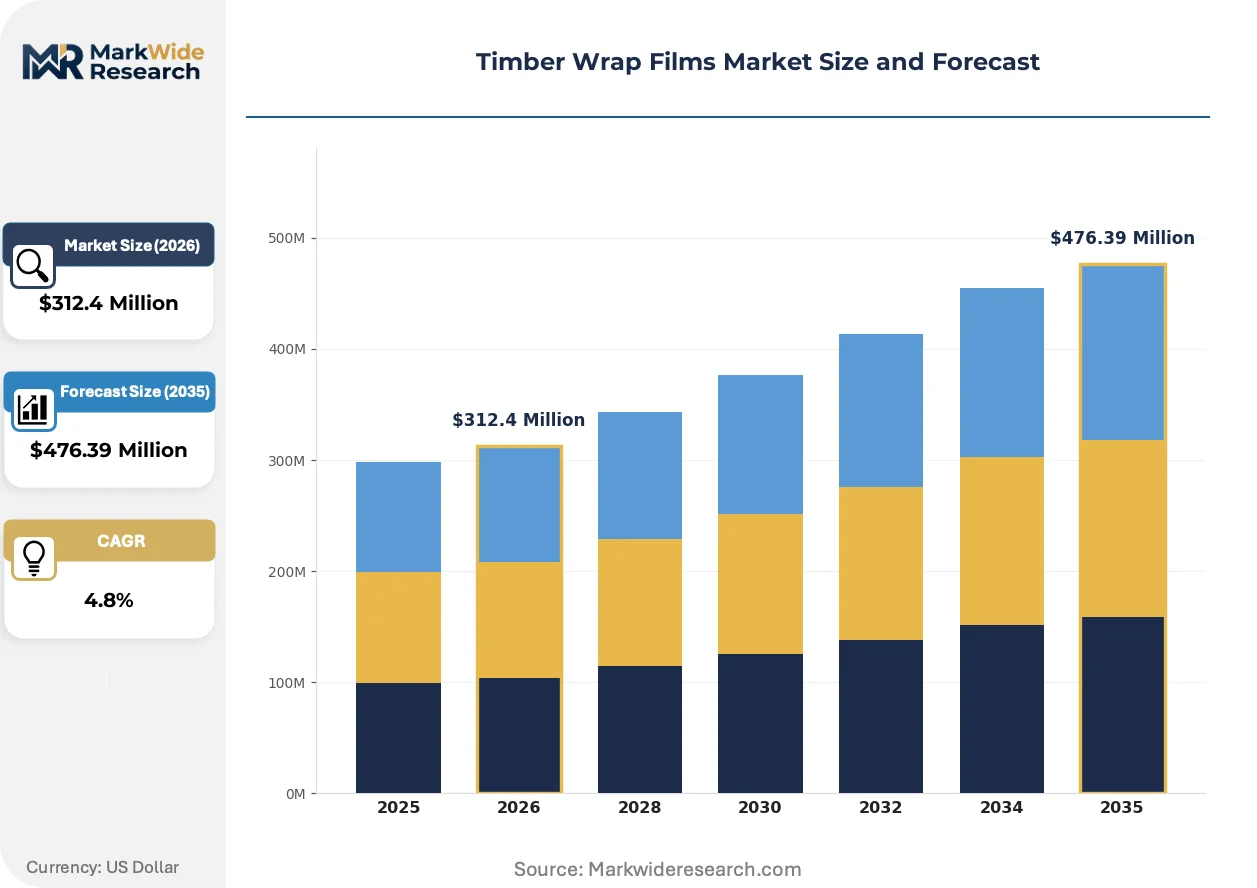
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Laminated Films, Stretch Films, Shrink Films, BOPP Films End User: Construction, Furniture Manufacturing, Packaging, Transportation Thickness: Thin Films, Medium Films, Thick Films, Ultra-Thin Films Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Multifab Packaging, Scott Lumber Packaging, Trioplast Industrier AB, Berry Global Inc., InterWrap Inc., Intertape Polymer Group, Flexoplas Packaging Ltd, Mondi Group, Inteplast Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Timber Wrap Films Market Strategic Shifts
Material science advances and regulatory compression are forcing simultaneous transitions in film architecture, recycling infrastructure, and procurement protocols across timber protection applications.
Co-extruded barrier films with embedded oxygen scavengers are extending storage life for tropical hardwoods in high-humidity conditions. Southeast Asian sawmills specify these structures for teak and meranti shipments to European distributors. The technology is converging with RFID-enabled inventory tracking, enabling condition-monitoring through ocean transit and reducing claims for moisture-induced dimensional instability.
REACH restrictions on phthalate plasticizers are accelerating migration to bio-based and non-phthalate alternatives in European-sourced products. German and French converters reformulate masterbatches to maintain elasticity specifications under tightened substance regulations. Laminated film segments face disproportionate compliance burden as adhesive systems undergo toxicological re-evaluation.
Consolidated buying groups among North American lumber exporters are compressing supplier margins through multi-year framework agreements. Previously fragmented procurement across individual sawmills is centralizing under cooperative purchasing entities in the Pacific Northwest. British Columbia and Alberta operations show parallel behavior, with regional buying consortiums extracting volume-based pricing concessions from film distributors.
Timber Wrap Films Market Segmentation
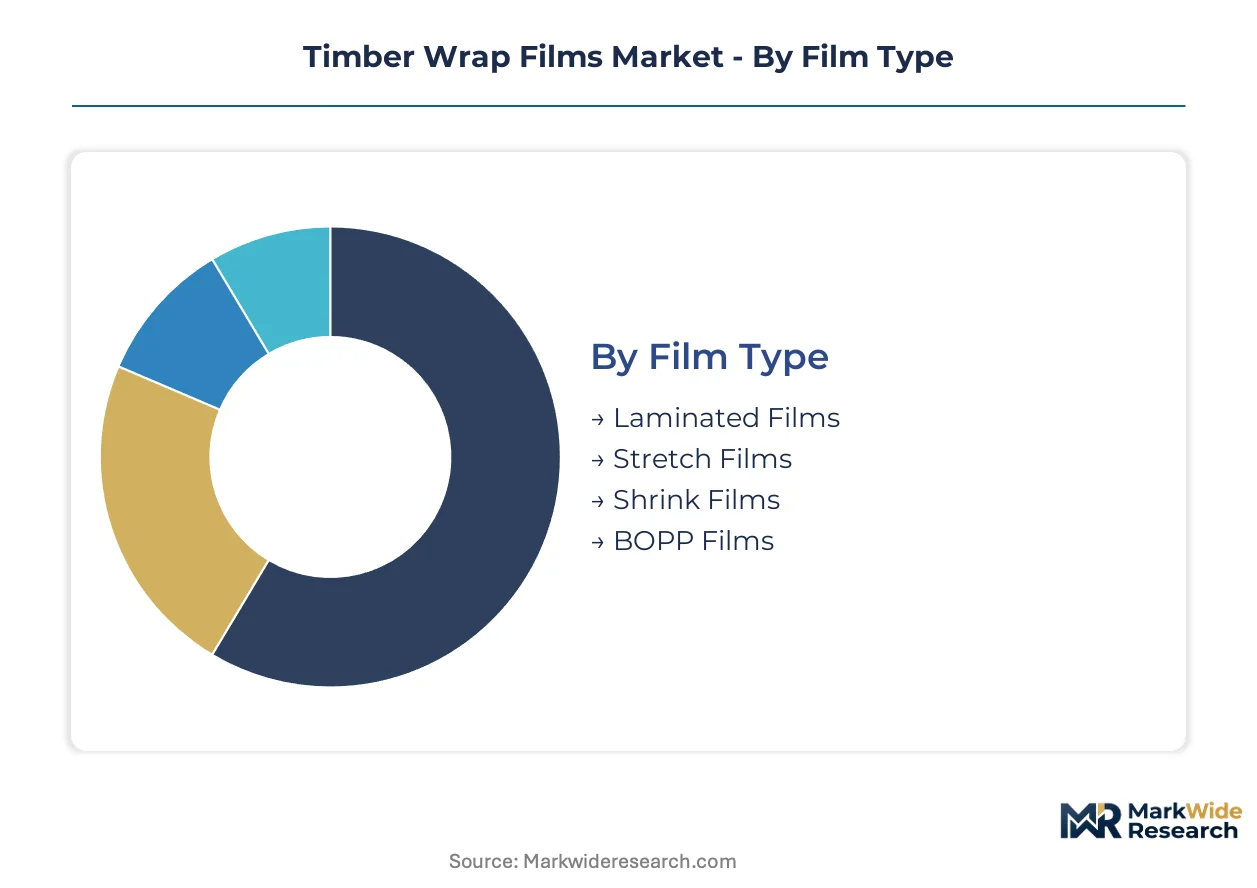
Timber wrap films serve distinct performance requirements across film architectures, end-use applications, and supply chain configurations. Segmentation reveals where converter capacity concentrates and which specifications command procurement priority from sawmill operators.
Film Type:
Supply concentration among Nordic extruders favors multi-layer structures with proven outdoor durability records.
- Laminated Films:Multi-layer polyolefin constructions with adhesive-bonded barrier layers deliver superior puncture resistance for rough-handling port environments. Pacific Northwest softwood exporters specify these structures for containerized shipments to Asian construction markets, accepting premium pricing for reduced transit damage claims.
- Stretch Films:Linear low-density polyethylene formulations enable automated wrapping systems with pre-stretch ratios exceeding 250%. Mid-sized sawmill operations in the US South are installing robotic wrapping cells previously limited to tier-one processors, shortening equipment payback periods.
- Shrink Films:Cross-linked polyolefin compositions provide tight conforming protection for irregular lumber bundles.
- BOPP Films:Biaxially oriented polypropylene structures serve high-clarity branding applications on premium-grade hardwood exports.
Laminated films absorb the bulk of installed capacity; stretch films are expanding most quickly.
End User:
Application-driven specifications diverge sharply between outdoor storage durability and controlled-environment handling.
- Construction:Sawn timber bound for residential and commercial building projects requires UV-stabilized films preventing dimensional degradation during extended yard storage. Scandinavian sawmills serving Baltic Sea export routes specify enhanced antioxidant packages for northern latitude solar exposure conditions.
- Furniture Manufacturing:Moisture-sensitive hardwoods destined for millwork and cabinetry applications demand vapor barrier performance. Kraft-paper hybrid structures from Nordic manufacturing bases address tropical transit humidity for teak and meranti shipments.
- Packaging:Secondary protective layers for finished wood products prioritize clarity and printability.
- Transportation:Intermodal logistics providers specify tear-resistant formulations for repeated handling cycles.
Construction absorbs the bulk of installed capacity; furniture manufacturing is climbing the fastest.
Thickness:
Specification bands align directly with handling intensity and storage duration requirements.
- Thick Films:Gauges exceeding 150 microns provide structural rigidity for open-yard storage exceeding six-month durations. British Columbia coastal sawmills deploy these specifications for inventory buffering against volatile Asian export demand cycles.
- Medium Films:100–150 micron structures balance material cost against protection performance for standard ocean transit. Oregon and Washington processors specify this band for containerized softwood shipments with typical 30–45 day transit windows.
- Thin Films:Sub-100 micron specifications serve short-haul domestic distribution with minimal handling.
- Ultra-Thin Films:Sub-80 micron experimental grades target sustainability metrics through resin reduction.
Medium films absorb the bulk of installed capacity; thick films are gaining share fastest.
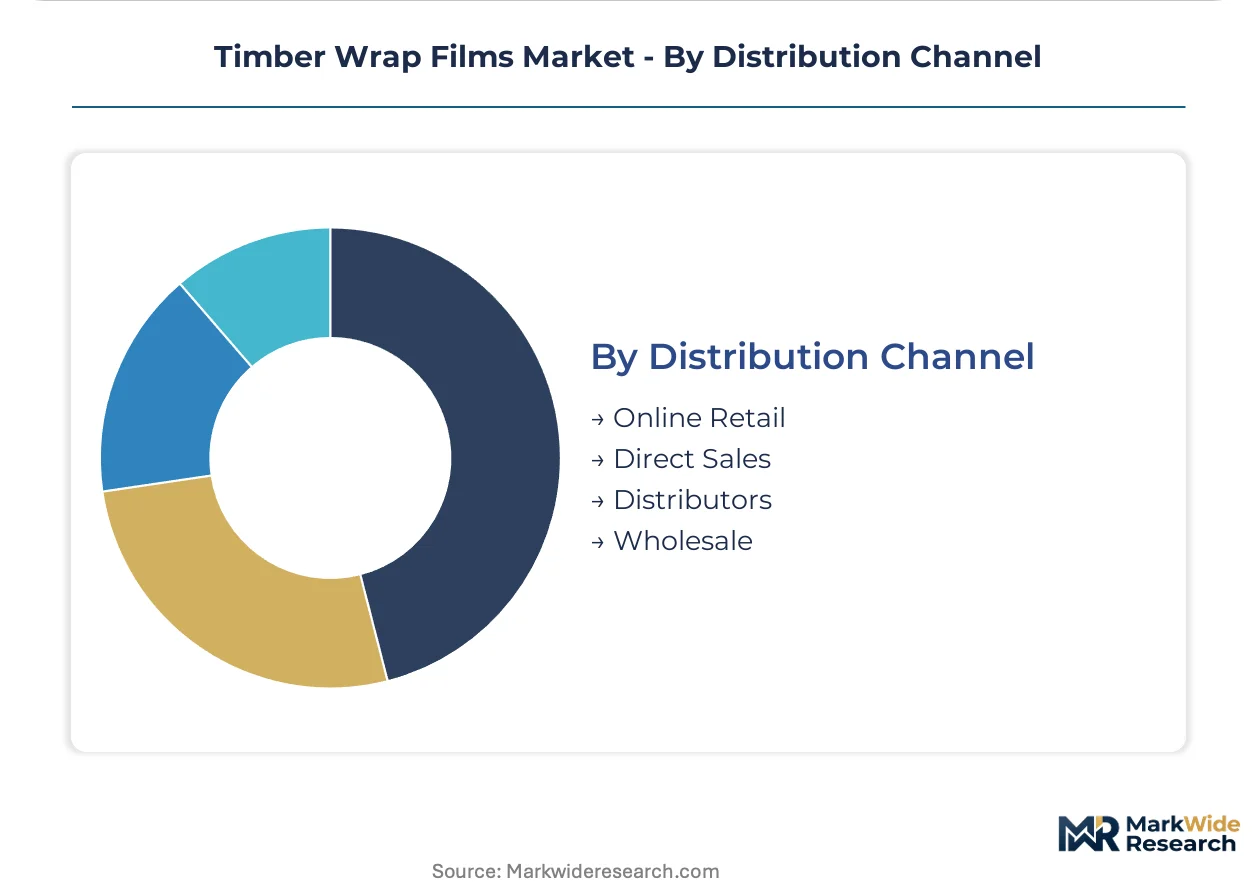
Distribution Channel:
Channel configuration determines working capital intensity and margin capture for converter operations.
- Direct Sales:Mill-to-converter relationships eliminate distributor markups for high-volume Pacific Northwest sawmill cooperatives. Consolidated buying groups in Oregon and Washington extract multi-year framework pricing through centralized procurement entities.
- Distributors:Regional inventory positioning serves fragmented mid-sized sawmill bases with irregular order patterns. Baltic Sea port terminals host consignment stock bypassing traditional wholesale networks.
- Online Retail:E-commerce platforms address maintenance replenishment for small-scale woodworking operations.
- Wholesale:Bulk aggregation channels serve secondary processors with standardized specification requirements.
Direct sales absorb the bulk of installed capacity; distributor relationships are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nordic polyethylene resin localities anchor regional supply chains for timber protection films. Baltic Sea and Pacific Northwest manufacturing clusters serve distinct export corridors with specialized film architectures.
United States
Pacific Northwest softwood exports to Asian construction markets drive high-volume film procurement from Oregon and Washington sawmills. EPA volatile organic compound limits on extrusion facilities require thermal oxidizer investments that disadvantage smaller converters. Automated wrapping systems penetrate mid-sized sawmill operations across the US South, shortening equipment payback periods.
Sweden
Scandinavian resin producers rebalance supply commitments toward specialty grades for timber protection applications. REACH restrictions on phthalate plasticizers accelerate migration to bio-based alternatives in Swedish-sourced products. Trioplast Industrier AB leverages its Nordic manufacturing base to sustain consistent delivery to Baltic Sea ports serving continental European markets.
Germany
EU Green Deal procurement preferences create premium tender pools for films incorporating renewable feedstocks. German converters reformulate masterbatches to maintain elasticity specifications under tightened substance regulations. Industrial clusters along the Rhine corridor develop chemical recycling partnerships to address multi-laminate processing gaps.
Canada
British Columbia coastal sawmills deploy thick-gauge specifications exceeding 150 microns for inventory buffering against volatile Asian export demand cycles. Health Canada and PMRA guidelines influence additive package selections for films serving cross-border lumber shipments. Alberta operations show parallel procurement centralization behavior with regional buying consortiums extracting volume-based pricing concessions.
China
Dual carbon goals reshape converter R&D priorities toward recyclable film architectures for domestic timber processing. MIIT standards and GB regulations govern industrial packaging material specifications in coastal manufacturing zones. Yangtze River Delta extrusion facilities expand capacity to serve Southeast Asian hardwood export corridors.
Timber Wrap Films Market Competitive Environment
Global majors compete with regional champions across resin supply, extrusion capacity, and distribution reach. The vendor base fragments between integrated polyolefin producers, specialty film converters, and paper-hybrid innovators. Three archetypes dominate: Nordic resin-integrated extruders, North American scale-driven distributors, and European sustainability-focused material scientists. Capacity expansion and backward integration into resin compounding represent the dominant competitive moves.
Among Nordic manufacturing specialists, Trioplast Industrier AB and Mondi Group exemplify regional anchoring strategies. Berry Global Inc. occupies a position among North American integrated players with captive supply chain control. These three entities represent distinct competitive vectors: geographic proximity to Baltic timber flows, kraft-paper hybrid innovation for moisture-sensitive applications, and vertical integration into resin formulation.
| Leading Market Players |
|---|
| Multifab Packaging |
| Scott Lumber Packaging |
| Trioplast Industrier AB |
| Berry Global Inc. |
| InterWrap Inc. |
| Intertape Polymer Group |
| Flexoplas Packaging Ltd |
| Mondi Group |
| Inteplast Group |
| Others |
Value Chain & Pricing Dynamics
Performance-grade certification divergence between laminated barrier films and commodity stretch wraps manifests in both procurement premiums and supply chain positioning. Premium structures command 40-60% price elevation over standard grades, reflecting specialized resin compounding and extended warranty coverage against moisture ingress claims.
Pricing Analysis
Warranty bundling separates premium film tiers from unbundled commodity supply. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Pricing pressure stems from consolidated buying groups in the Pacific Northwest extracting multi-year framework concessions. Small-scale woodworking operations exhibit highest price sensitivity; tier-one softwood exporters prioritize performance guarantees over unit cost.
Supply Chain Analysis
Workforce availability constraints in Nordic extrusion hubs and US Gulf Coast resin corridors shape manufacturing capacity allocation. Supply concentrates in Sweden, Germany, and the United States, with polyethylene resin feedstock drawing from North Sea and Appalachian petrochemical complexes. Single-source vulnerability runs through Baltic Sea port terminal access for Scandinavian converters. Distribution runs through direct mill-to-port consignment inventory bypassing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty-grade resin capacity bottlenecks in Scandinavian production corridors prop pricing power for converters with secured supply agreements. This supply-constrained structure favors incumbents with backward integration and long-term offtake arrangements.
For Market Incumbents: Anticipate margin compression from REACH-compliant reformulation costs by securing captive bio-polyethylene supply chains. Prioritize chemical recycling partnerships to address multi-laminate processing gaps before mechanical recycling assets strand. Defend position through kraft-paper hybrid capacity expansion for moisture-sensitive hardwood segments.
For New Entrants and Emerging Players: Capture white space in automated wrapping system integration services for mid-sized US South sawmills. Target bio-based film procurement pools created by EU Green Deal tender preferences. Enter through equipment-financing bundles that lower capital barriers for robotic wrapping cell adoption.
For Investors and Strategic Acquirers: Re-rating potential sits with Nordic resin-integrated converters given EU Packaging and Packaging Waste Regulation compliance premiums. Long-term viability favors upstream-controlled players with proven film-to-film loop partnerships. Watch chemical recycling facility commissioning announcements as inflection indicators for stranded asset risk resolution.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply from Scandinavian crackers insulates against force majeure pricing volatility. |
| Chemical Recycling Partnership | Multi-laminate processing capability addresses EU Extended Producer Responsibility compliance requirements. |
| Kraft-Paper Hybrid Capacity Expansion | Mondi Group's Nordic manufacturing base demonstrates premium positioning for tropical transit conditions. |
| Direct Mill-to-Port Distribution | Consignment inventory at Baltic Sea terminals captures margin previously allocated to distributor intermediaries. |
| Automated Wrapping System Integration | Robotic cell deployment shortens payback periods for mid-sized sawmill operations in the US South. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with sawmill procurement directors, extrusion plant managers, resin supply specialists, and port logistics coordinators combined with Nordic timber export statistics and EPA emission disclosure documents. Bottom-up volume modeling and top-down value triangulation validated segment-level estimates across film architectures and end-use applications.
Data-stream reconciliation between resin production capacity disclosures and sawmill wrapping equipment installation records established forecast parameters. Segmentation dimensions modeled include film type, end-use industry, thickness specification, and distribution channel configuration across the analysis window. CAGRs derived from shipment volume trajectories and unit pricing indices, with Baltic Sea export corridor flows and US Pacific Northwest softwood shipment data serving as industry-specific calibration inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU member state EPR implementation divergence and chemical recycling facility commissioning delays. Forecasts reflect assumptions regarding resin supply continuity and regulatory timeline adherence. Material deviation in REACH substance restriction enforcement or Nordic cracker maintenance scheduling warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Japan Plastic Packaging Film Market
Poly film
Polyethylene Cast Film Market
Poly film
Starch-Based Plastic Films Market
Poly film
North America Polyimide Films Market
Poly film
Global PVDC Coated Films Market
Poly film
Latin America Polypropylene (PP) Packaging Film Market
Poly film
Twist Wrap Film Market
Poly film
Chocolate Wrapping Films Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
Recyclable Lidding Films Market
Poly film
Light Reflective Film Market
Poly film
Global BOPP Films Market
Poly film
Polyurethane (PU) Film Market
Poly film
Co Extruded Films Market
Poly film
Bundling Film Market
Poly film
PVC Films Market