
 Mexico Plastic Packaging Films Market | 2026-2036
Mexico Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Plastic Packaging Films Market Insights
Fresh produce exporters is redrawing procurement patterns across the Mexico plastic packaging films landscape. Berry Global Inc leverages vertical integration across resin conversion and film finishing to capture value at multiple stages. FLEX AMERICAS SA de CV anchors its position through geographic dominance in central Mexico manufacturing corridors. Amcor plc differentiates via R&D intensity in high-barrier structures for perishable exports.
Plastic packaging films are thin, flexible polymer substrates typically ranging from 8 to 150 microns in gauge, extruded or cast from polyethylene, polypropylene, or nylon resins to provide moisture and gas barrier protection for goods in transit and storage. Stretch film leads volume consumption across Mexican logistics networks due to palletization demand in automotive and agricultural supply chains. Barrier film commands premium positioning as food processors require extended shelf-life for export-grade meat and produce shipments. Polyethylene dominates material selection for cost-sensitive applications while polypropylene gains ground in clarity-driven consumer goods segments.
SEMARNAT enforces federal environmental standards governing recyclability and extended producer responsibility for plastic packaging materials circulating in Mexican commerce. NOM-252-SSA1-2011 sets specific labeling and material identification requirements that directly shape converter product design decisions. COFEPRIS regulates food-contact film safety for domestic and export-bound packaging. Stakeholders must monitor evolving state-level waste management legislation and the trajectory of chemical recycling infrastructure investments to anticipate resin cost and availability shifts.
Market Dynamics
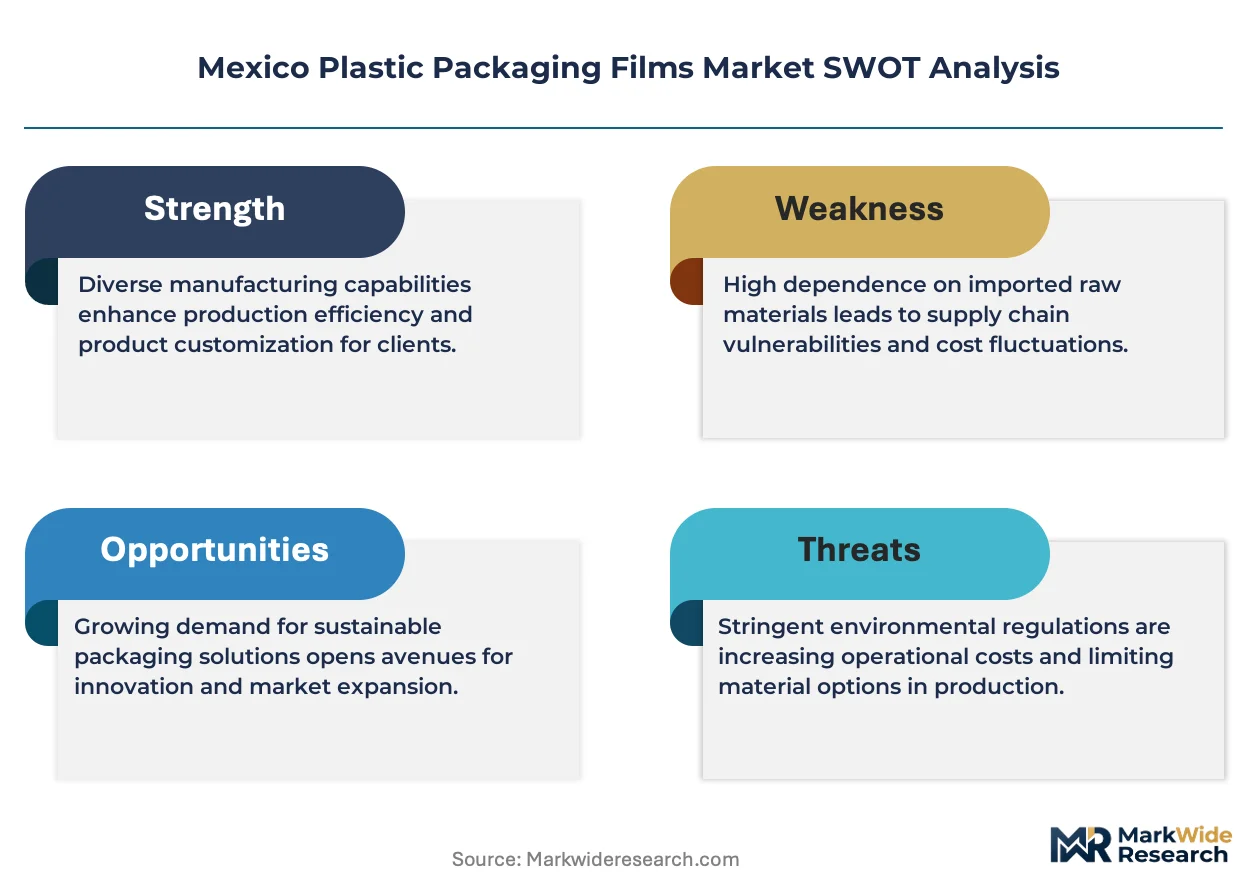
SEMARNAT's recyclability mandates are compressing converter design cycles, forcing rapid abandonment of multi-layer laminates in favor of mono-material structures that align with Mexico's emerging extended producer responsibility framework.
Growth Catalysts
- Bajío Manufacturing Corridor Concentration:Querétaro and Guanajuato host dense clusters of automotive and food processing plants, creating localized demand spikes for stretch and barrier films.
- NOM-252-SSA1-2011 Labeling Standards:Material identification requirements are standardizing converter outputs, reducing downstream sorting costs and unlocking circular economy partnerships.
- Cold-Chain Logistics Modernization:Perishable exporters are adopting high-barrier films as refrigerated transport networks expand across Sinaloa and Jalisco agricultural zones.
Market Restraints
- Polyethylene Resin Price Volatility:Feedstock fluctuations tied to Pemex refining capacity constrain margin predictability for cost-sensitive packaging tiers.
- Multi-Material Recycling Infrastructure Gap:Mexico's mechanical recycling base lacks capacity to process legacy laminated structures, stranding existing film inventories.
- Substitution by Fiber-Based Packaging:Paperboard and molded pulp formats are capturing premium fresh produce segments where moisture sensitivity permits.
Strategic Opportunities
- Chemical Recycling Scale-Up:Pyrolysis and depolymerization investments in Veracruz and Tamaulipas promise feedstock flexibility beyond mechanical recycling limits.
- Medical-Grade Film Export Channels:COFEPRIS-certified cleanroom production can access US pharmaceutical packaging demand under FDA-recognized equivalency pathways.
- State-Level EPR Preparations:Jalisco and Nuevo León are drafting producer responsibility frameworks that reward early mono-material adopters with fee discounts.
Industry Challenges
- Mono-Material Barrier Performance Gaps:Replacing ethylene vinyl alcohol and nylon layers with single-resin alternatives sacrifices oxygen transmission rates for meat and cheese applications.
- Retrofitting Extrusion Lines:Legacy cast film equipment requires substantial capital outlays to process recycled content feedstocks without gauge inconsistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Plastic Packaging Films Market |
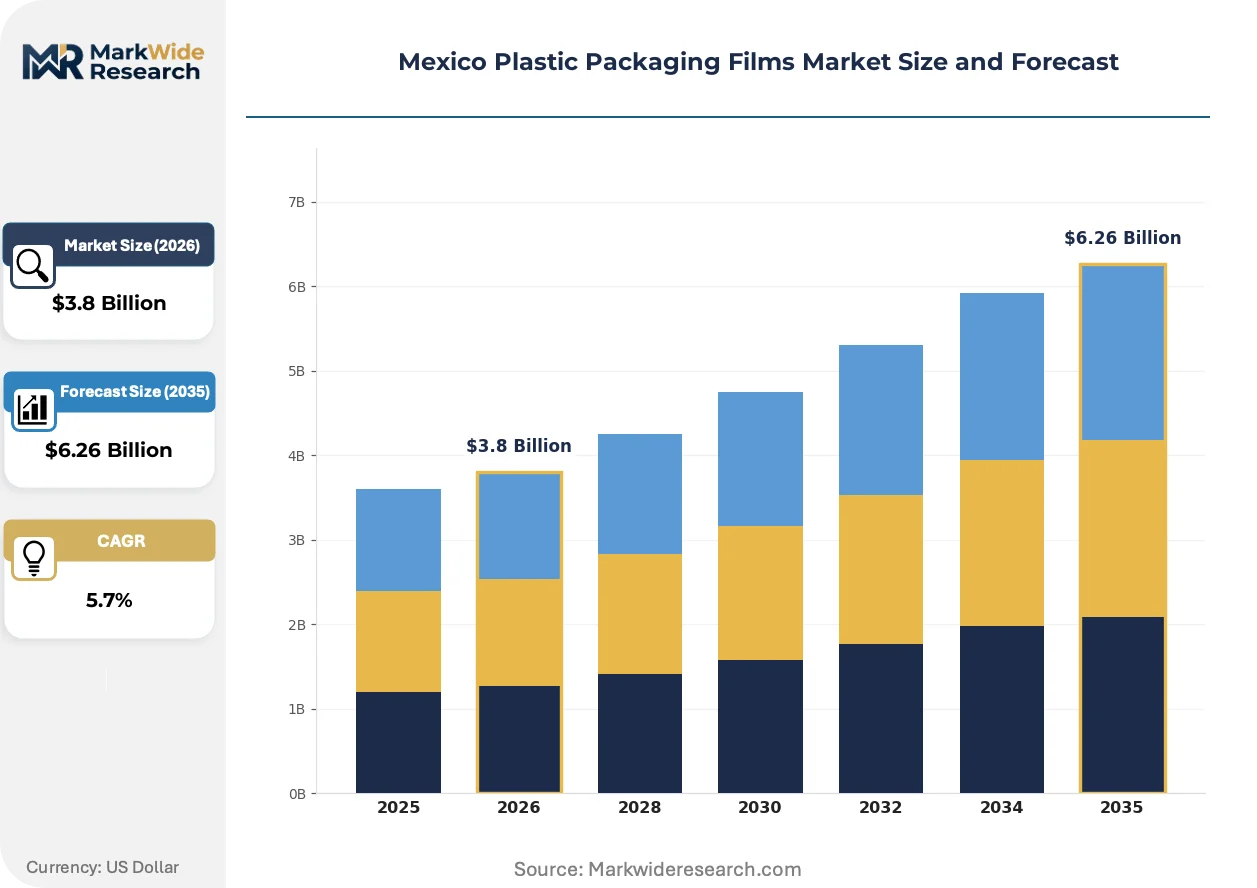
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Film, Shrink Film, Barrier Film, Rigid Film End User: Food Industry, Consumer Goods, Healthcare, Electronics Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Nylon Form: Roll Stock, Bags, Pouches, Sheets |
| Companies Covered | Berry Global Inc, FLEX AMERICAS SA de CV, Taghleef Industries Group, Innovia Films, Amcor plc, Poly Rafia SA de CV, Evertis de México SA de CV, Cosmo Films Ltd, PLAMI SA de CV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Plastic Packaging Films Market Trends and Innovations
Active and intelligent packaging functionalities are penetrating Mexican export corridors, with oxygen-scavenging and humidity-indicating films commanding premium positioning in perishable supply chains.
Thin-gauge high-density polyethylene stretch film is miniaturizing pallet wrap consumption across automotive component logistics. Tier-one suppliers in Aguascalientes and San Luis Potosí are specifying 12-micron formulations down from 20-micron standards. This compression is reducing resin throughput per pallet while demanding enhanced puncture resistance from metallocene catalyst formulations.
SEMARNAT's 2024 technical guidelines on recyclable packaging design are accelerating mono-material adoption among converters serving Walmart de México and Chedraui private label programs. The regulation eliminates ambiguous "recyclable" claims and mandates third-party certification for circularity assertions. Food-contact film producers are reformulating barrier layers to maintain COFEPRIS compliance without aluminum oxide metallization.
Direct procurement relationships between berry exporters and film converters are displacing traditional distributor intermediaries in Guanajuato and Michoacán. Driscoll's Mexico and similar operators are negotiating specification-locked supply agreements that guarantee seasonal volume commitments. This channel compression is most visible in clamshell and overwrap segments for avocado and blackberry export grades.
Mexico Plastic Packaging Films Market Segmentation
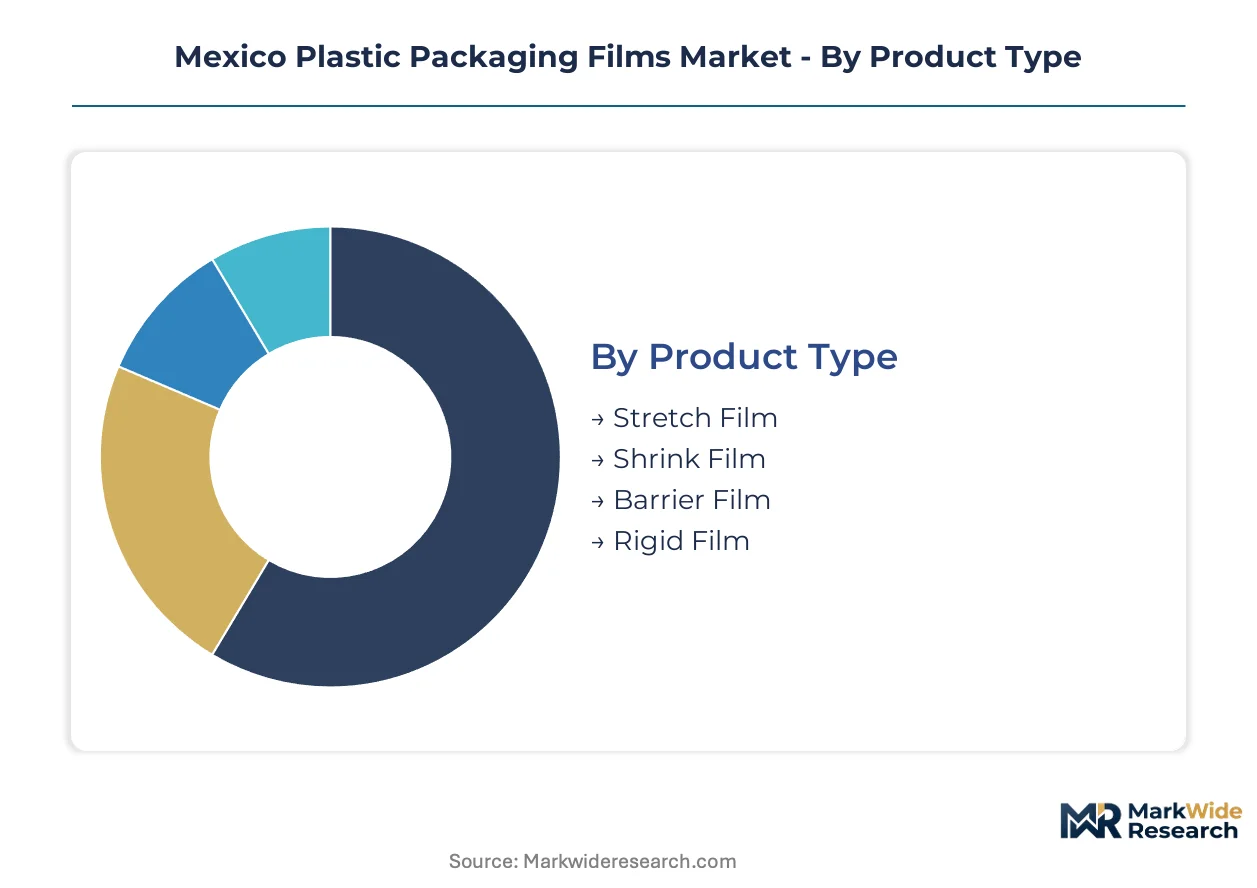
Segmentation in Mexico's plastic packaging films market reveals how resin chemistry, functional performance, and end-use specifications create distinct margin pools. Converters align extrusion capabilities with specific demand corridors rather than pursuing undifferentiated volume.
Product Type:
Stretch film captures the widest margin pool through automotive and agricultural logistics density in the Bajío corridor. Barrier film commands premium positioning via export-grade food preservation requirements.
- Stretch Film:Linear low-density polyethylene formulations dominate palletization demand across Querétaro automotive plants and Sinaloa produce distribution centers. Cold-chain expansion in Jalisco berry exports is accelerating 12-micron high-density specifications.
- Barrier Film:Multi-layer coextrusions incorporating ethylene vinyl alcohol or nylon deliver oxygen transmission rates below 1 cc/m²/day for meat and cheese exports. SEMARNAT's mono-material mandates are forcing rapid reformulation of these structures.
- Shrink Film:Polyolefin formulations serve retail display packaging for consumer goods manufacturers in Mexico State.
- Rigid Film:Thermoformable polyethylene terephthalate and polystyrene substrates target clamshell produce containers in Michoacán avocado packing houses.
Stretch film holds installed capacity. Barrier film is rotating up the share rankings.
End User:
Food industry procurement concentrates 60% of volume through direct converter relationships, while healthcare applications unlock export certification premiums.
- Food Industry:Processors of meat, dairy, and fresh produce specify high-barrier structures for export-grade shelf life. Driscoll's Mexico and similar operators negotiate specification-locked supply agreements bypassing traditional distributors.
- Healthcare:COFEPRIS-certified cleanroom production of medical-grade films accesses US pharmaceutical demand under FDA-recognized equivalency pathways. Sterility requirements command 3-4x pricing multiples over commodity tiers.
- Consumer Goods:Clarity-driven polypropylene formats serve personal care and household product segments in Mexico City metropolitan retail corridors.
- Electronics:Anti-static polyethylene formulations protect semiconductor components manufactured in Guadalajara technology parks.
Food industry applications anchor volume throughput. Healthcare certification is climbing the fastest toward margin leadership.
Material:
Resin selection stratifies across cost sensitivity, barrier performance, and recyclability compliance with NOM-252-SSA1-2011 identification requirements.
- Polyethylene:Linear low-density and high-density grades span stretch film logistics and retail carryout bags. Pemex refining capacity constraints introduce feedstock price volatility that compresses margin predictability.
- Polypropylene:Biaxially oriented formulations deliver optical clarity for consumer goods labels and overwrap. Cast film lines in Guanajuato are retrofitting for this resin's higher melt strength requirements.
- Polyvinyl Chloride:Shrink film applications persist in pharmaceutical blister packs despite environmental scrutiny.
- Nylon:Polyamide barrier layers face displacement pressure as converters pursue mono-material designs compliant with SEMARNAT recyclability mandates.
Polyethylene maintains the deepest installed base. Polypropylene is expanding most quickly in clarity-driven segments.
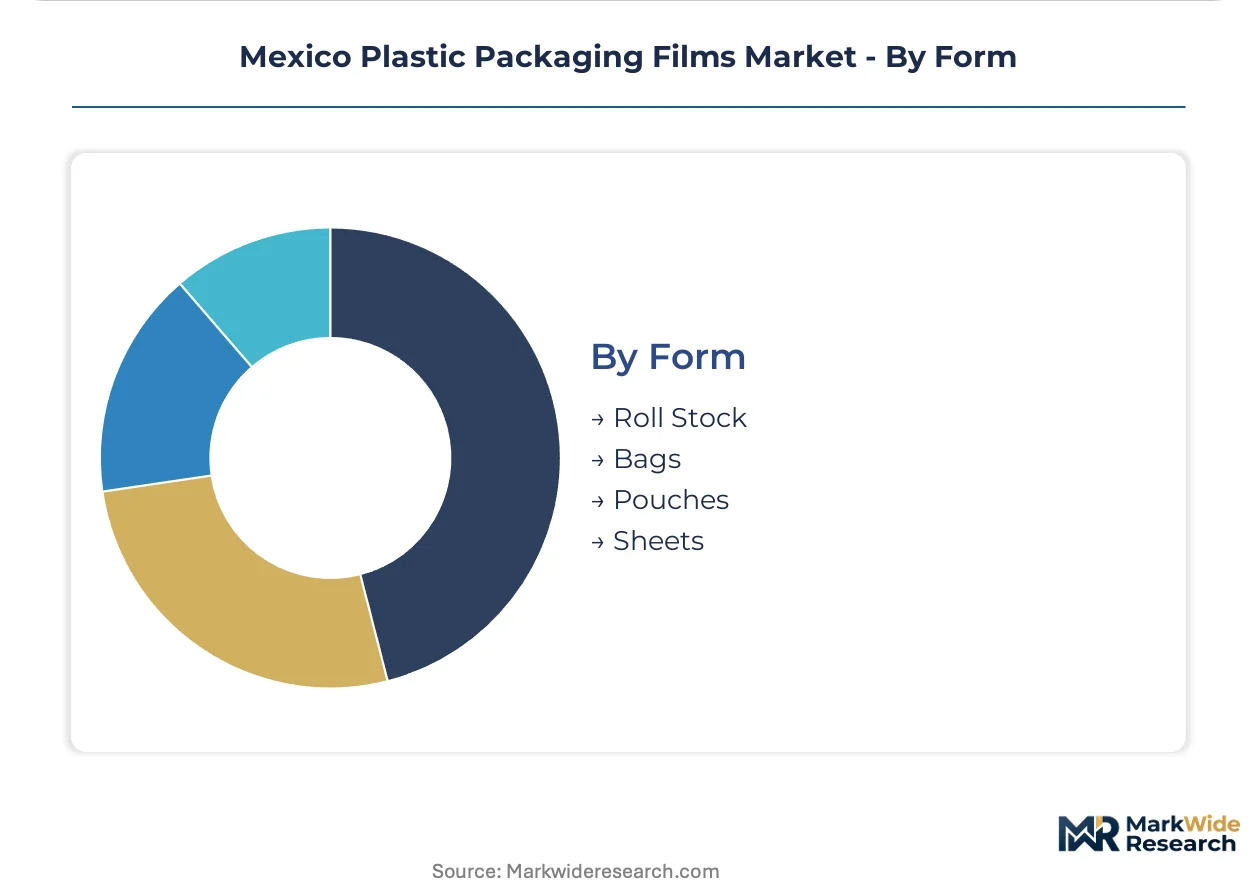
Form:
Physical configuration determines downstream conversion economics and customer touchpoint intensity across the value chain.
- Roll Stock:Unwound substrate supplied to contract converters and in-house form-fill-seal operations. Berry exporters in Guanajuato increasingly specify roll stock dimensions matched to automated packing line speeds.
- Bags:Pre-formed polyethylene sacks serve agricultural bulk commodity packaging in Sonora and Chihuahua grain handling facilities.
- Pouches:Stand-up and flat formats target retail-ready food packaging with zipper and spout fitment integration.
- Sheets:Cut-to-size thermoforming blanks supply Michoacán avocado clamshell manufacturers.
Roll stock commands the broadest converter relationships. Pouches are gaining share fastest in retail-ready formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's plastic packaging films sector channels output toward US fresh produce retail networks and Canadian food processing chains, with cross-border logistics infrastructure dictating regional production placement.
Bajío Region
Querétaro and Guanajuato concentrate automotive component palletization and berry export packaging demand. SEMARNAT's recyclability guidelines are accelerating mono-material line conversions in Irapuato film plants. Berry exporters in Celaya negotiate direct supply agreements bypassing traditional distribution tiers.
Nuevo León
Monterrey anchors northern Mexico's stretch film consumption through manufacturing logistics and cross-border warehousing. State-level extended producer responsibility drafts are rewarding early mono-material adopters with fee discounts. Chemical recycling pilot investments in Apodaca promise feedstock flexibility beyond mechanical processing limits.
Jalisco
Guadalajara's technology parks drive anti-static film demand for semiconductor component protection. Cold-chain modernization across Sinaloa-Jalisco agricultural corridors is expanding high-barrier specifications for blackberry and raspberry exports. COFEPRIS-certified converters in Tlaquepaque access US pharmaceutical packaging channels.
Mexico City Metro
The metropolitan zone concentrates consumer goods clarity packaging and healthcare film certification activity. NOM-252-SSA1-2011 labeling enforcement is standardizing material identification across contract converter operations in Toluca. Retail-ready pouch formats are displacing rigid alternatives in Mexico State personal care segments.
Northern Border States
Chihuahua and Sonora host agricultural bulk commodity packaging for grain handling and produce distribution. Pemex refining capacity constraints introduce polyethylene feedstock volatility that compresses margin predictability. Maquiladora operations in Ciudad Juárez specify thin-gauge stretch formulations for cross-border component logistics.
Mexico Plastic Packaging Films Market Competitive Landscape
Player mix skews toward integrated resin-to-film converters and regional specialists with geographic lock-in. Market structure tilts consolidated at the top tier with fragmentation across mid-scale operations serving specific industrial corridors. Two archetypes dominate: vertically integrated multinationals capturing value at multiple production stages, and corridor-anchored specialists leveraging proximity to Bajío automotive and agricultural demand clusters. Capacity expansion and mono-material line retrofitting represent the dominant competitive moves as SEMARNAT compliance deadlines approach.
Among the integrated multinational tier, Berry Global Inc and Amcor plc occupy positions exemplifying upstream control over resin conversion and downstream film finishing. FLEX AMERICAS SA de CV anchors the geographic-specialist archetype through manufacturing presence in central Mexico corridors. These three entities represent contrasting strategic postures: global scale with captive supply chains versus regional density with specification-locked customer relationships.
| Leading Market Players |
|---|
| Berry Global Inc |
| FLEX AMERICAS SA de CV |
| Taghleef Industries Group |
| Innovia Films |
| Amcor plc |
| Poly Rafia SA de CV |
| Evertis de México SA de CV |
| Cosmo Films Ltd |
| PLAMI SA de CV |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day resin inventory cycles at Bajío converters compress margin buffers when Pemex polyethylene supply tightens, concentrating pricing power among integrated producers with captive resin security. This lead-time vulnerability shapes how converters negotiate specification-locked contracts with automotive and produce exporters across Querétaro and Guanajuato.
Pricing Analysis
Current-generation mono-material barrier formulations command 15-20% premia over legacy multi-layer laminates, while next-generation chemical-recycling-compatible grades sit at prototype pricing. Three-tier pricing structure across premium, standard, and economy levels separates COFEPRIS-certified medical grades from commodity stretch film and agricultural bulk packaging. Cost compression in standard-tier polyethylene runs through Pemex refining volatility and import parity fluctuations. Agricultural cooperatives in Sinaloa exhibit highest price sensitivity, while pharmaceutical exporters absorb premia for FDA-recognized equivalency pathways.
Supply Chain Analysis
Veracruz petrochemical corridor transit underwrites resin feedstock security for central Mexico film extrusion, with Gulf Coast US and Colombian polyethylene imports providing swing supply. Raw material dependencies center on ethylene feedstock from Pemex refineries, metallocene catalysts from specialty chemical suppliers, and masterbatch additives for barrier functionality. Single-source vulnerability concentrates in Pemex domestic resin allocation during turnaround seasons. Distribution runs through direct converter relationships with Bajío automotive plants and specification-locked supply agreements with berry exporters bypassing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SEMARNAT's mono-material mandates fragment converter capabilities, creating acquisition opportunities for specialists with barrier reformulation expertise and chemical recycling feedstock access. This regulatory-driven capability gap rewards early movers who bridge performance gaps in meat and cheese oxygen transmission rates.
For Market Incumbents: Secure backward integration into pyrolysis feedstock streams in Veracruz and Tamaulipas before chemical recycling capacity tightens. Lock in multi-year resin offtake agreements with Pemex to buffer refining volatility, while retrofitting Irapuato and Celaya lines for mono-material barrier production to defend against emerging specialists with EPR fee discounts in Jalisco and Nuevo León. For New Entrants and Emerging Players: Anchor in medical-grade film cleanroom production in Tlaquepaque and Guadalajara technology corridors, where COFEPRIS-FDA equivalency commands 3-4x pricing multiples. Target underpenetrated pharmaceutical blister pack and sterile barrier segments with US export certification, leveraging white-space in active packaging functionalities for perishable exporters in Sinaloa-Jalisco corridors. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mono-material retrofitting capital requirements and EPR compliance complexity will strand mid-scale converters without barrier R&D depth. Target acquisition archetype: corridor-anchored specialists with 50-150 employee scale, installed mono-material capacity, and specification-locked relationships with Driscoll's Mexico or similar export-grade produce operators. Watch chemical recycling offtake pricing in Veracruz as the inflection signal for feedstock cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Line Retrofitting | SEMARNAT compliance deadlines force rapid abandonment of multi-layer laminates in favor of recyclable structures. |
| Chemical Recycling Scale-Up | Pyrolysis investments in Veracruz and Tamaulipas promise feedstock flexibility beyond mechanical recycling limits for converters. |
| Medical-Grade Certification Investment | COFEPRIS cleanroom production unlocks US pharmaceutical demand under FDA-recognized equivalency pathways. |
| Direct Procurement Relationship Lock-In | Berry exporters in Guanajuato and Michoacán negotiate specification-locked agreements bypassing distributor intermediaries. |
| State-Level EPR Early Adoption | Jalisco and Nuevo León producer responsibility frameworks reward mono-material adopters with fee discounts. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with film extrusion plant managers, procurement leads at automotive OEMs and produce exporters, distribution channel partners, and SEMARNAT regulatory affairs specialists; and secondary validation through customs and trade data, SEC filings of integrated multinationals, NOM-252-SSA1-2011 regulatory documentation, and automotive production databases. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators across the Mexican plastics value chain.
Across the analysis window, the quantitative framework modeled volume and value trajectories by product type, material chemistry, end-use industry, and regional production cluster. CAGRs derived from segment-level growth drivers including cold-chain logistics expansion, mono-material substitution rates, and export certification penetration. Industry-specific forecast inputs incorporated Pemex refining capacity utilization assumptions and chemical recycling infrastructure build-out timelines in Gulf Coast states.
Material uncertainties — resin price volatility tied to Pemex operational stability, state-level EPR implementation pacing, and chemical recycling yield rates — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory compliance deadlines and substitution elasticity in barrier applications. Practitioners should keep alternative scenarios live as SEMARNAT technical guidelines evolve and US-Mexico agricultural trade flows adjust.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Waste Wrap Film Market
Poly film
PET Lidding Films Market
Poly film
Latin America Polypropylene (PP) Packaging Film Market
Poly film
Polyethylene Cast Film Market
Poly film
Global BOPET Packaging Films Market
Poly film
Laminated Packaging Films Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market
Poly film
Laminating Film Market
Poly film
Polypropylene Packaging Films Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Bopet Films Market
Poly film
Polytetrafluoroethylene (PTFE) Films Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Polyimide Films and Tapes Market
Poly film
PCR Bubble Films Market
Poly film
Global Thermoplastic Films Market