
 Alu Alu Cold Blister Films Market | 2026-2036
Alu Alu Cold Blister Films Market Size, Share, and Industry Trends Forecast 2026-2036
Alu Alu Cold Blister Films Market Outlook
Subscription-based technical support and predictive maintenance contracts for cold-form blister lines is expanding what packaging converters sell beyond commodity film rolls. Amcor leverages its global pharmaceutical certification network to sustain premium positioning in high-barrier laminate supply. Constantia Flexibles anchors European demand through dedicated healthcare film facilities in Germany and Austria. ACG Group dominates South Asian pharmaceutical packaging with integrated film-to-machine offerings that reduce customer qualification cycles.
Alu Alu cold blister films are multi-layer laminates typically comprising aluminum foil, polyvinyl chloride, and polyvinylidene chloride, cold-formed into cavity pockets without heat to protect hygroscopic and oxygen-sensitive dosage forms. The manufacturing process employs deep-draw stamping at 25-30°C to preserve drug stability across tropical distribution chains. Barrier-grade composite films lead the product type landscape because pharmaceutical companies prioritize WVTR specifications below 0.01 g/m²/day for chronic therapies in humid climates. Among end users, contract manufacturers represent the fastest-growing demand pool as Big Pharma outsources primary packaging to qualified third parties with dedicated isolator lines and existing regulatory filings.
FDA's Container Closure System guidance and EU MDR traceability requirements shape film specifications by mandating extractables documentation and lot-level serialization compatibility. India's CDSCO enforces stability testing protocols that favor alu alu configurations over PVC blisters for humidity zone IV markets. Stakeholders must monitor evolving pharmacopeial standards for elemental impurities and migration limits, as regulatory divergence between FDA, EMA, and emerging market agencies will determine which laminate constructions qualify for multi-region product registrations without redundant stability studies.
Market Dynamics
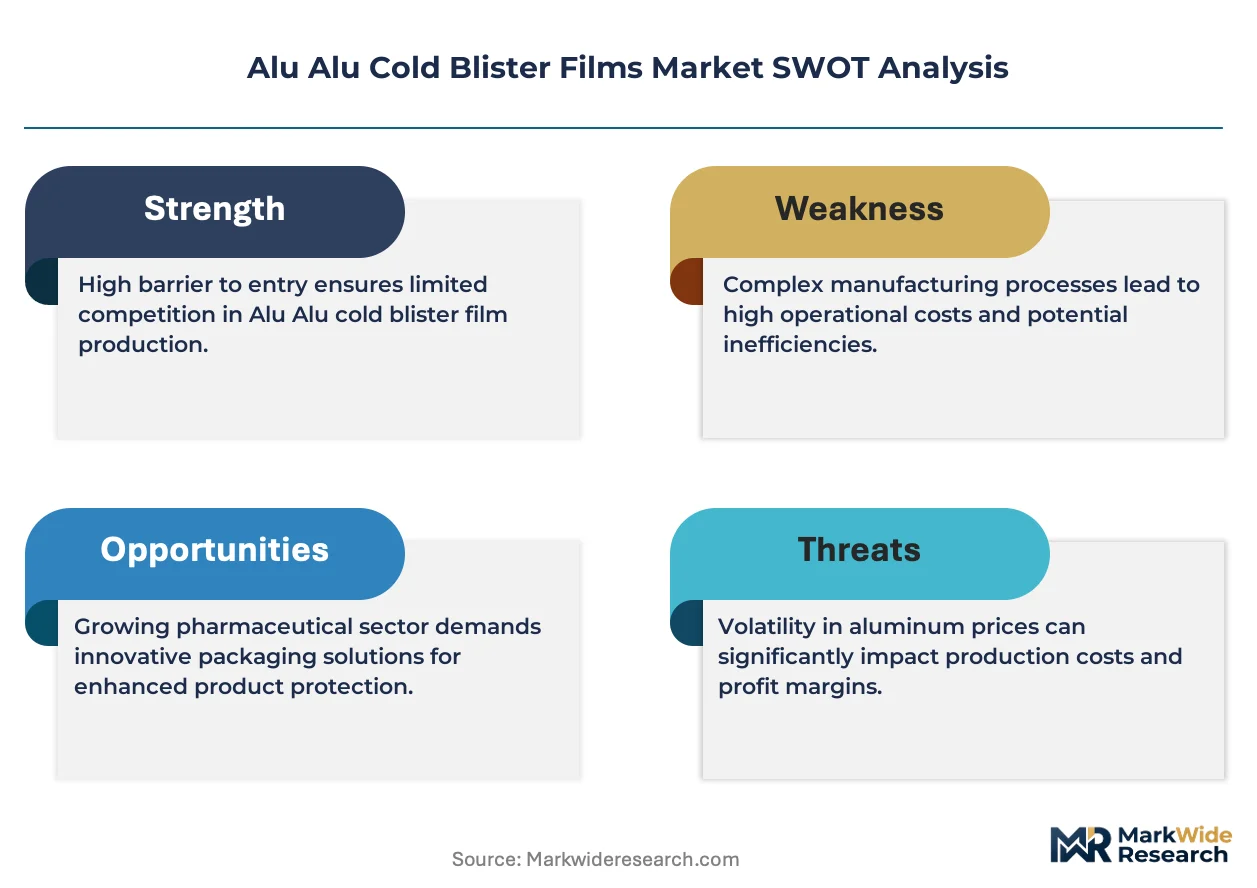
Pharmaceutical contract manufacturers in India and Southeast Asia are expanding cold-form blister packaging lines to meet EU MDR and FDA stability requirements for moisture-sensitive drugs. This regulatory convergence is compressing qualification cycles and reshaping supplier relationships across the value chain.
Growth Catalysts
- EU MDR traceability mandates:Lot-level serialization compatibility requirements are forcing pharmaceutical packagers to upgrade to barrier-grade alu alu laminates with documented extractables profiles.
- Chronic therapy expansion:Cardiovascular and diabetes drug portfolios in humidity zone IV markets require WVTR specifications below 0.01 g/m²/day that only cold-form aluminum constructions deliver.
- Deep-draw stamping automation:Servo-controlled forming at 25-30°C preserves API stability while enabling faster line speeds than thermoformed alternatives.
Market Restraints
- Aluminum foil supply concentration:Rolling mill capacity for pharmaceutical-grade foil concentrates in China and Russia, exposing converters to geopolitical supply interruptions.
- PVDC resin cost volatility:Vinylidene chloride monomer pricing fluctuates with chlor-alkali chain economics, compressing laminate margins unpredictably.
- Thermoformed barrier substitutes:High-barrier cyclic olefin polymer (COP) blisters from Mitsui Chemicals and TOPAS Advanced Polymers threaten alu alu share in ophthalmic and biologic applications.
Strategic Opportunities
- Sub-Saharan Africa pharmaceutical growth:WHO prequalification programs for HIV and tuberculosis therapies create demand for tropical-stability packaging without established local supply.
- Cell and gene therapy packaging:Cryogenic storage requirements for CAR-T doses are converging with modified alu alu constructions incorporating fluoropolymer cold-flow layers.
- India PLI scheme for medical devices:Domestic manufacturing incentives are attracting cold-form film investments to serve ASEAN export markets from Gujarat and Maharashtra clusters.
Industry Challenges
- Isolator line qualification timelines:FDA Container Closure System guidance demands 12-18 month stability studies for each new laminate configuration, delaying revenue recognition.
- Elemental impurities testing capacity:USP <232> and ICH Q3D implementation requires ICP-MS instrumentation that mid-tier converters struggle to finance.
- Multi-region regulatory divergence:EMA, FDA, and CDSCO pharmacopeial standards for migration limits lack harmonization, forcing redundant formulation work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alu Alu Cold Blister Films Market |
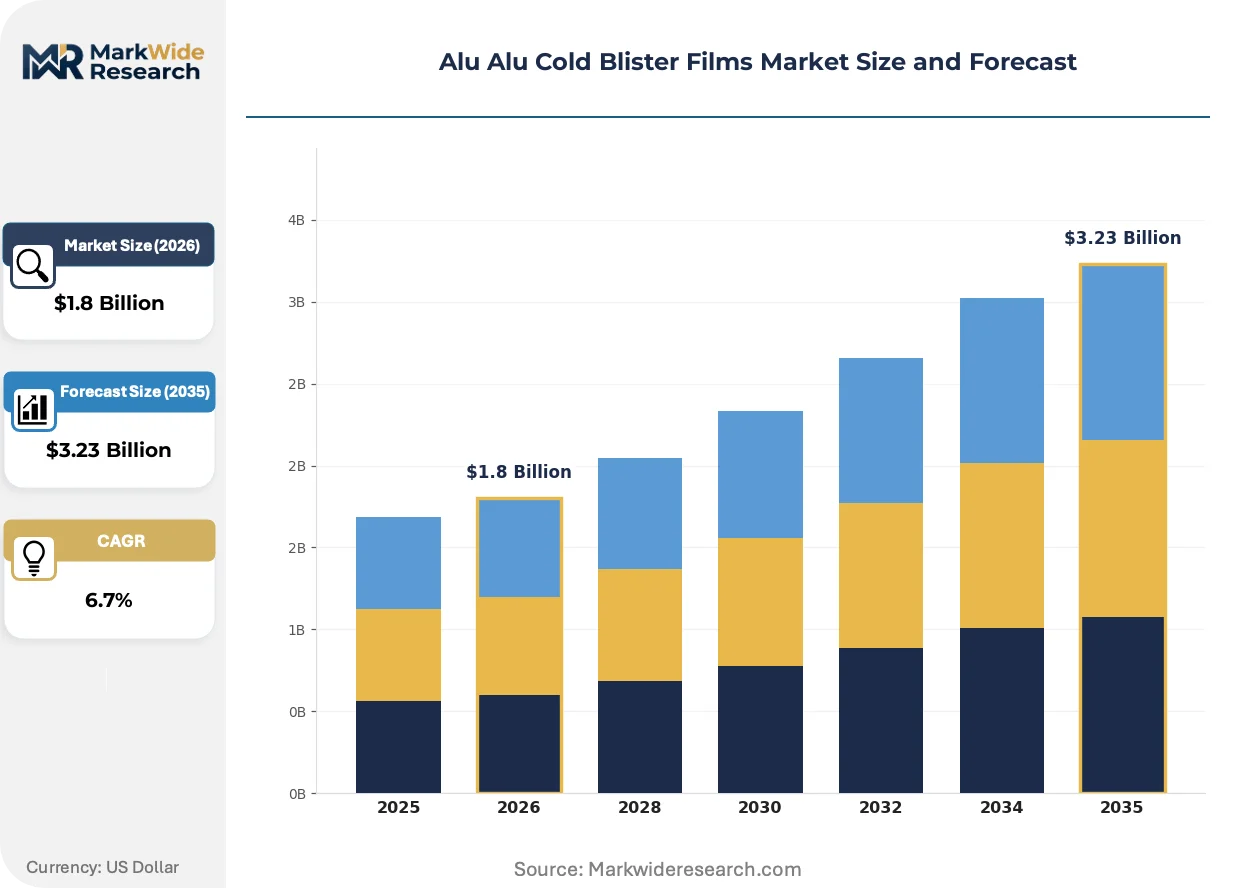
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Films, Flexible Films, Composite Films, Barrier Films Application: Pharmaceuticals, Nutraceuticals, Medical Devices, Consumer Goods End User: Contract Manufacturers, Pharmaceutical Companies, Packaging Firms, Healthcare Providers Material: Aluminum Foil, PVC, PVDC, PET |
| Companies Covered | Amcor, Constantia Flexibles, Uflex, Tekni-Plex, Winpak, ACG Group, Bilcare, Aluflexpack, Essentra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alu Alu Cold Blister Films Market Strategic Shifts
Cold-form blister manufacturing is experiencing material science convergence and regulatory digitization that are redefining competitive differentiation beyond commodity film specifications. These shifts favor integrated suppliers with certification depth.
Laser-etched aluminum foil with embedded serialization codes is converging with blockchain track-and-trace platforms to create tamper-evident, digitally verifiable packaging. Large pharmaceutical contract manufacturers in Germany and Switzerland are mandating this capability for high-value chronic therapies. The technology is converging with existing cold-form lines through retrofittable print stations, compressing the timeline for regulatory compliance without full line replacement.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances (PFAS) are forcing laminate reformulation away from fluoropolymer-based cold-flow aids. European healthcare film specialists are accelerating PVDC-PVC coextrusion development to maintain forming performance without PFAS lubricants. Barrier-grade composite films containing these reformulated layers are entering qualification with EMA now, ahead of anticipated 2025 enforcement deadlines.
Subscription-based technical support contracts are displacing transactional spare parts purchasing for cold-form blister lines. Indian and Southeast Asian contract manufacturers are bundling predictive maintenance with film supply agreements to minimize isolator downtime. This procurement model compression is most visible in Mumbai and Hyderabad, where ACG Group and Uhlmann have established dedicated service hubs adjacent to pharmaceutical clusters.
Alu Alu Cold Blister Films Market Segmentation
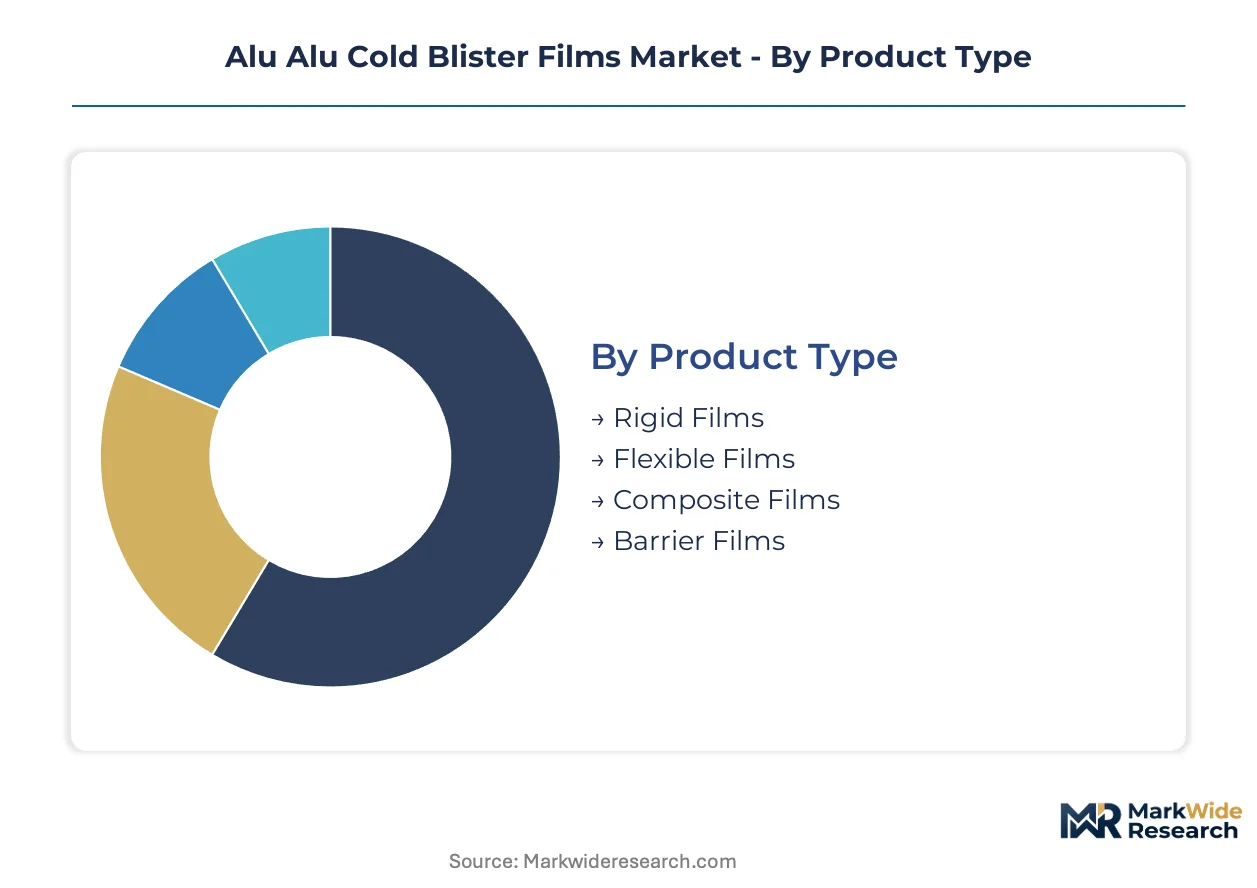
Segmentation in alu alu cold blister films determines qualification pathways and capital allocation for pharmaceutical packaging investments. Film specifications vary sharply across moisture sensitivity requirements, forming depth needs, and regulatory filing territories. Understanding these divides separates commodity converters from certified healthcare suppliers.
Product Type:
Capital intensity escalates with barrier complexity and laminate layer count, separating established healthcare specialists from generalist film producers.
- Barrier Films:Multi-layer aluminum-PVC-PVDC constructions achieving WVTR below 0.01 g/m²/day dominate chronic therapy packaging in humidity zone IV markets. Indian contract manufacturers in Hyderabad and Mumbai are prioritizing these specifications for EU MDR-compliant exports to Germany and France.
- Composite Films:Engineered laminates combining aluminum foil with polymer substrates balance forming depth against seal integrity for standard oral solid doses. Demand concentrates among mid-tier pharmaceutical companies in Maharashtra and Gujarat seeking tropical stability without premium barrier pricing.
- Flexible Films:Reduced-gauge constructions for shallow-draw applications with lower aluminum content.
- Rigid Films:High-stiffness alternatives for deep-draw cavities requiring dimensional stability.
Most installed capacity flows through Barrier Films. Expansion is steepest in Composite Films.
Application:
Regulatory filing requirements and stability study burdens create divergent margin profiles across end-use categories.
- Pharmaceuticals:Primary packaging for oral solid doses, biologics, and moisture-sensitive APIs demands full extractables documentation and lot-level serialization compatibility. FDA Container Closure System guidance and EU MDR traceability mandates are compressing qualification cycles for cardiovascular and diabetes therapies distributed across humid climates.
- Nutraceuticals:Probiotic and enzyme formulations with moderate moisture sensitivity utilize alu alu configurations without full pharmaceutical certification. Growth is accelerating in Maharashtra and Karnataka where domestic wellness brands are upgrading from PVC blisters for premium positioning.
- Medical Devices:Sterile barrier applications for implantable components and diagnostic consumables.
- Consumer Goods:Battery and electronics packaging leveraging aluminum moisture protection.
Pharmaceuticals absorb the majority of qualified capacity. Nutraceuticals are gaining share fastest.
End User:
Procurement scale and technical service requirements segment the customer base between integrated majors and specialized converters.
- Contract Manufacturers:Third-party packagers with dedicated isolator lines and existing regulatory filings represent the steepest demand trajectory. CDSCO stability protocols and ASEAN export requirements are driving capacity additions at facilities in Gujarat, Telangana, and Tamil Nadu serving Big Pharma outsourcing contracts.
- Pharmaceutical Companies:In-house packaging operations at research-intensive firms maintain captive film specifications for pipeline assets.
- Packaging Firms:Generalist converters without pharmaceutical isolator qualifications.
- Healthcare Providers:Hospital pharmacy repackaging and clinical trial material operations.
Contract Manufacturers command the largest volume commitments. Pharmaceutical Companies show the fastest adoption of predictive maintenance bundling.
Material:
Raw material sourcing concentration and resin chemistry volatility define supply risk profiles across laminate constructions.
- PVDC:Vinylidene chloride copolymers deliver the critical moisture barrier layer in high-performance alu alu configurations. Chlor-alkali chain economics create margin pressure unpredictability that converters in India and Southeast Asia hedge through long-term monomer contracts.
- Aluminum Foil:Pharmaceutical-grade rolled products from 20-30 micron gauges form the structural and barrier core. Rolling mill capacity concentrates in China and Russia, exposing qualified converters to geopolitical supply interruption risks.
- PVC:Polyvinyl chloride substrates provide forming pliability and heat-seal compatibility.
- PET:Polyester alternatives for specialized optical and dimensional stability requirements.
PVDC laminates carry the highest qualification burden. Aluminum Foil supply expansion is most constrained.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and India deploy divergent strategies for pharmaceutical packaging compliance, with German converters prioritizing EMA serialization mandates while Indian facilities scale isolator capacity for FDA and EU MDR exports.
Germany
Bavarian and Baden-Württemberg pharmaceutical clusters drive demand for laser-etched serialization films that satisfy EU MDR traceability requirements. EMA pharmacopeial standards for elemental impurities force converters to maintain ICP-MS testing laboratories. Heidelberg and Stuttgart host dedicated healthcare film facilities where Constantia Flexibles anchors European barrier-grade laminate supply.
India
Hyderabad and Mumbai contract manufacturers expand cold-form blister lines to meet CDSCO stability protocols for humidity zone IV markets. The PLI scheme for medical devices attracts film investments to Gujarat and Maharashtra clusters serving ASEAN export demand. Telangana and Tamil Nadu isolator facilities qualify laminates for Big Pharma outsourcing contracts with 12-18 month FDA Container Closure System studies.
United States
New Jersey and Massachusetts pharmaceutical corridors prioritize WVTR specifications below 0.01 g/m²/day for cardiovascular and diabetes therapies distributed across humid climates. FDA guidance on extractables documentation compresses qualification cycles for barrier-grade composite films. Puerto Rico and North Carolina packaging hubs integrate predictive maintenance contracts to minimize isolator downtime.
Switzerland
Basel and Zurich pharmaceutical manufacturing bases demand tamper-evident packaging with blockchain track-and-trace compatibility for high-value chronic therapies. Swissmedic pharmacopeial standards align with EMA migration limits, enabling multi-region product registrations without redundant stability studies. Swiss contract manufacturers mandate laser-etched aluminum foil retrofits on existing cold-form lines.
China
Shanghai and Jiangsu pharmaceutical packaging zones source pharmaceutical-grade aluminum foil from domestic rolling mills concentrated in Shandong and Henan provinces. NMPA stability testing protocols favor alu alu configurations over PVC blisters for tropical distribution chains. Yangtze River Delta converters face supply interruption exposure from geopolitical concentration in upstream foil capacity.
Alu Alu Cold Blister Films Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated film-to-machine suppliers capturing premium positioning in qualified healthcare markets while commodity converters compete on volume in standard oral solid dose applications. The vendor base organizes around three strategic archetypes: global certification networks sustaining multi-region regulatory filings, regional healthcare specialists with dedicated isolator line partnerships, and integrated machinery-film bundlers compressing customer qualification timelines. Capacity expansion and predictive maintenance service contracts represent the dominant competitive moves, as pharmaceutical packagers prioritize uptime guarantees over transactional film procurement.
Within the global certification tier, Amcor leverages its pharmaceutical qualification depth across multiple regulatory jurisdictions, while Constantia Flexibles anchors European demand through dedicated healthcare film infrastructure. ACG Group exemplifies the integrated machinery-film archetype with bundled offerings that reduce isolator line qualification burdens for Indian and Southeast Asian contract manufacturers. These three entities represent distinct strategic positions: certification breadth, regional healthcare specialization, and vertical service integration.
| Leading Market Players |
|---|
| Amcor |
| Constantia Flexibles |
| Uflex |
| Tekni-Plex |
| Winpak |
| ACG Group |
| Bilcare |
| Aluflexpack |
| Essentra |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade aluminum foil rolling costs transmit downstream through laminate pricing tiers, with 20-30 micron gauge premiums accumulating at each conversion stage from Chinese and Russian mill outputs to EU MDR-qualified converter margins in Germany and India.
Pricing Analysis
Capacity additions in Gujarat and Maharashtra are reshaping price floors for standard composite films serving ASEAN nutraceutical exporters. Three-tier pricing structure across barrier-grade, composite, and flexible film levels separates CDSCO-qualified pharmaceutical laminates from wellness-grade alternatives. Cost compression in shallow-draw flexible films is intensifying because Indian domestic rolling mill investments lag specialty gauge demand. Contract manufacturers with bundled predictive maintenance agreements show the least price sensitivity; commodity converters without isolator qualifications face the most.
Supply Chain Analysis
Container freight rates from Shanghai to Mumbai and Hamburg determine working capital cycles for PVDC resin shipments originating from chlor-alkali complexes in China and the United States. Pharmaceutical-grade aluminum foil supply concentrates in China, Russia, and domestic Indian rolling capacity. Laminate production draws from vinylidene chloride monomer, polyvinyl chloride substrates, and cold-flow aid chemistries. Single-source vulnerability in pharmaceutical foil gauges exposes converters to geopolitical interruption. Distribution runs through qualified converter inventories to contract manufacturer isolator lines with 12-18 month qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in alu alu cold blister films rests on PVDC-PVC coextrusion cost-downs and the shift toward subscription-based technical service premiums that displace transactional film procurement.
For Market Incumbents: Extend certification depth across FDA, EMA, and CDSCO jurisdictions to defend against high-barrier cyclic olefin polymer substitutes from Mitsui Chemicals and TOPAS Advanced Polymers. Backward integration into pharmaceutical-grade foil rolling capacity in India mitigates Chinese supply concentration risk. Predictive maintenance contract penetration in Hyderabad and Mumbai isolator clusters secures recurring revenue attachment. For New Entrants and Emerging Players: Capture WHO prequalification demand for HIV and tuberculosis therapies in Sub-Saharan Africa where established converter presence remains thin. The most penetrable white space sits in cryogenic-modified alu alu constructions for cell and gene therapy packaging. A go-to-market angle bundling fluoropolymer cold-flow layer qualification with CAR-T storage compatibility documentation accelerates regulatory acceptance. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier converters lack ICP-MS instrumentation for USP elemental impurities testing. Long-term viability favors vertically integrated film-to-machine suppliers with existing pharmaceutical isolator partnerships. Acquisition targets display bundled service revenue exceeding thirty percent of total sales and active qualification studies across multiple regulatory jurisdictions. The signal to watch is REACH Annex XVII PFAS enforcement timelines accelerating laminate reformulation capex demands.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pharmaceutical Foil Rolling | Captive gauge supply from Indian mills reduces Chinese concentration exposure for CDSCO-qualified converters. |
| PFAS-Free Laminate Reformulation | PVDC-PVC coextrusion development ahead of REACH Annex XVII deadlines preserves EMA qualification pathways. |
| Predictive Maintenance Service Bundling | Subscription contracts with Hyderabad isolator operators displace transactional spare parts purchasing. |
| Cryogenic Cold-Flow Layer Qualification | Fluoropolymer-modified constructions access CAR-T therapy packaging with cryogenic storage requirements. |
| Multi-Region Certification Investment | Simultaneous FDA Container Closure System and EU MDR filings compress revenue recognition timelines. |
Study Parameters
Coverage spans Germany, India, the United States, Switzerland, and China, with primary inputs from each pharmaceutical packaging cluster. Interviews with cold-form line engineers, regulatory affairs specialists at contract manufacturers, pharmaceutical packaging procurement directors, and healthcare film R&D leads combined with secondary validation from FDA Container Closure System guidance documents, EMA pharmacopeial standards, CDSCO stability protocols, and customs trade data. Bottom-up laminate demand modeling triangulated against top-down pharmaceutical packaging capex disclosures.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects in barrier-grade versus composite film segments. Segmentation dimensions modeled include product barrier tier, application regulatory intensity, end-user procurement scale, and regional qualification cluster. CAGRs derived from laminate consumption per oral solid dose unit applied to prescription volume forecasts. Industry-specific inputs incorporated WVTR specification evolution and isolator line installation rates.
Underlying measurement precision varies by segment; pharmaceutical applications with established FDA filings carry tighter precision than emerging nutraceutical conversions. Forecasts reflect assumptions about regulatory harmonization timelines and chlor-alkali chain economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Healthcare Blister Packaging Market
Blister Packaging
Carded Blister Packaging Market
Blister Packaging
Global Cold Form Blister Packaging Market
Blister Packaging
Blister Pack Pharmaceutical Products Market
Blister Packaging
Ampoules and Blister Packaging Market
Blister Packaging
Blister Packaging Equipment Market
Blister Packaging
High Barrier Pharmaceutical Packaging Films for Blister Market
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
Middle East and Africa Pharmaceutical Blister Packaging Market
Blister Packaging
Middle East and Africa Blister Packaging Market
Blister Packaging
Latin America Pharmaceutical Blister Packaging Market
Blister Packaging
Liquid Blister Pack Market
Blister Packaging
PVC Blister Packs Market
Blister Packaging
Pharma Blister Packaging Machines Market
Blister Packaging
Blister Packs Market
Blister Packaging
North America Pharmaceutical Blister Packaging Market