
 Isotropic Film Market | 2026-2036
Isotropic Film Market Size, Share, and Industry Trends Forecast 2026-2036
Isotropic Film Market Insights
Modular film-to-substrate bonding configurations is realigning procurement patterns across display and automotive tiers. Toray Industries leverages captive polymer synthesis to sustain cost discipline in thermal film grades. DuPont Teijin Films anchors North American supply through integrated PET resin operations. Mitsubishi Chemical Group differentiates via nanocomposite R&D pipelines targeting optical clarity thresholds.
Isotropic film denotes a substrate exhibiting uniform refractive index and mechanical properties in all planar directions, typically manufactured through biaxial stretching or solvent casting to achieve 0.5-2.0% haze values for optical transmission. These films serve as base layers in liquid-crystal displays, photovoltaic backsheets, and medical diagnostic strips where directional consistency prevents image distortion or thermal gradient failure. Thermal films lead volume absorption due to mature electronics cooling architectures, while nanocomposite technology captures fastest expansion as OLED and micro-LED fabrication demands sub-micron planar uniformity. Biodegradable technology occupies a nascent but regulated niche as the EU Green Deal tightens end-of-life mandates for consumer electronics packaging.
REACH and RoHS frameworks in Europe restrict halogenated flame retardants in film substrates, compelling reformulation of laminated and pressure-sensitive grades. The EPA and FDA in the United States enforce separate toxicity and biocompatibility thresholds that fragment qualification protocols for medical device versus industrial applications. Stakeholders must monitor divergence between EU chemical hazard classifications and U.S. risk-assessment methodologies when scaling cross-border substrate certification.
Market Dynamics
Biaxial stretching equipment upgrades across East Asian substrate producers are compressing planar uniformity tolerances below 0.3% haze, forcing mid-tier converters to absorb capital costs or exit optical-grade supply.
Growth Catalysts
- Micro-LED fabrication ramp:Display panel manufacturers in South Korea and Taiwan are qualifying sub-micron isotropic substrates for next-generation emitters, pulling thermal-grade film demand into optical purity tiers.
- EU Green Deal packaging mandates:Biodegradable film formulations are capturing regulated share in consumer electronics end-of-life streams as Brussels tightens recyclability thresholds for laminated substrates.
- Automotive HUD proliferation:Germany's tier-one suppliers are specifying isotropic base layers for head-up display stacks, extending film consumption beyond traditional electronics into vehicle cockpit systems.
Market Restraints
- Petrochemical feedstock volatility:Purified terephthalic acid and ethylene glycol pricing swings compress margin predictability for PET-based film extruders.
- East Asian supply concentration:South Korea and Japan control 70% of biaxial stretching capacity for sub-1.0% haze grades, creating geographic chokepoint risk.
- Halogenated flame retardant substitution:REACH and RoHS restrictions on brominated compounds force reformulation of pressure-sensitive adhesive laminates without mature non-halogen alternatives.
Strategic Opportunities
- India electronics manufacturing:PLI scheme subsidies for display and semiconductor fabs are attracting substrate qualification programs away from saturated East Asian supplier lists.
- Medical diagnostic strip expansion:FDA biocompatibility pathways for isotropic film substrates in point-of-care devices open margin-rich volumes outside commodity electronics pricing.
- Solvent casting technology convergence:Nanocomposite dispersion methods from optical film production are migrating into biodegradable polymer research, enabling premium positioning against conventional extrusion.
Industry Challenges
- Metrology talent scarcity:Interferometric haze measurement and birefringence mapping require specialized technicians that polymer science programs are not producing at scale.
- Cross-border certification friction:Divergent EU hazard classifications versus U.S. EPA risk-assessment methodologies force dual-track qualification timelines for medical and industrial grades.
- Legacy equipment retrofit costs:Converting single-axis stretching lines to biaxial configurations demands capital commitments that family-owned converters cannot finance independently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isotropic Film Market |
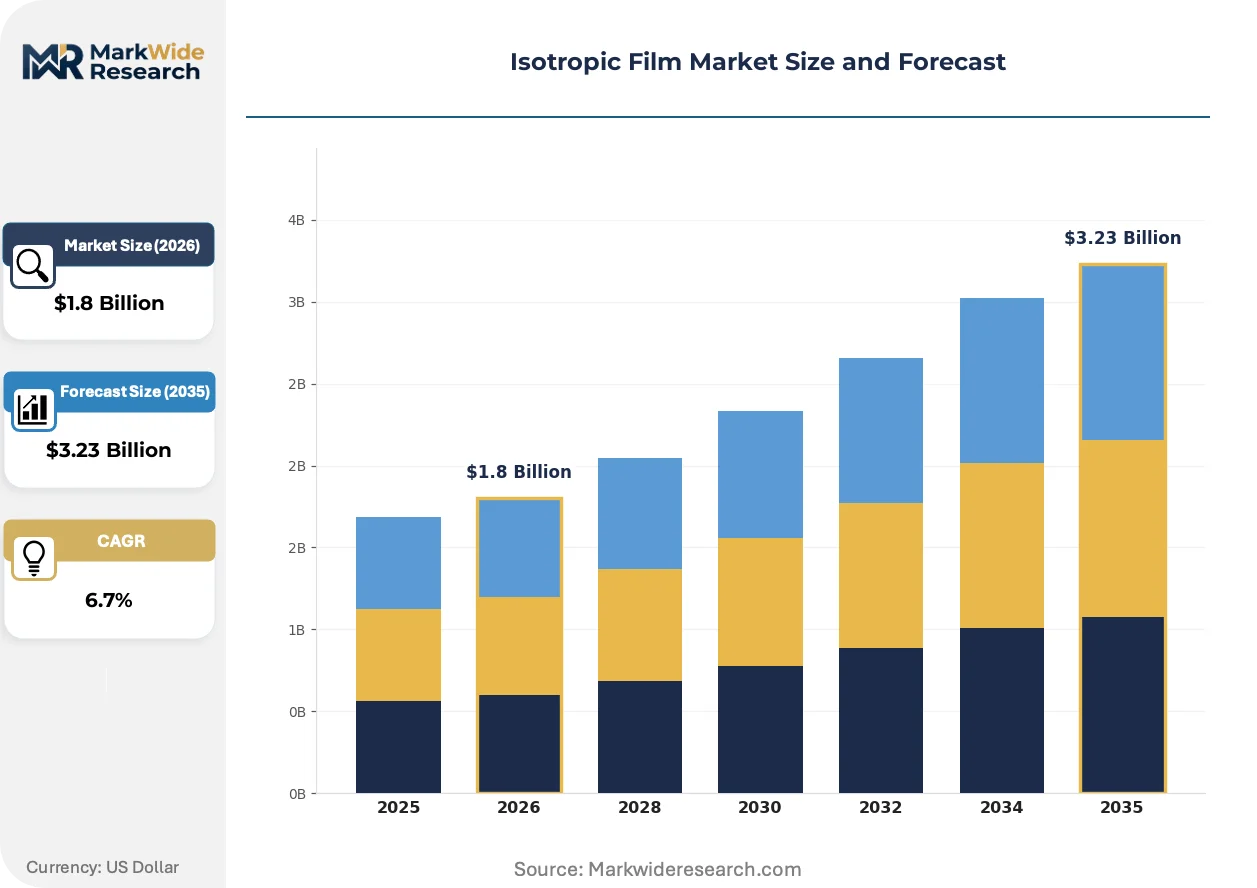
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Films, Pressure-Sensitive Films, Adhesive Films, Laminated Films Technology: Polymer-Based, Metal-Coated, Nanocomposite, Biodegradable End User: Packaging Industry, Automotive Manufacturers, Electronics Sector, Medical Devices Application: Reflective Surface, Optical Devices, Insulation, Protective Coatings |
| Companies Covered | Toray Industries, DuPont Teijin Films, Mitsubishi Chemical Group, Polyplex Corporation, BASF SE, Kuraray Co., Ltd., Jindal Poly Films, 3M, Kolon Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isotropic Film Market Trends and Innovations
Substrate planar uniformity specifications are tightening faster than equipment depreciation cycles, compressing technology refresh windows and favoring capital-rich producers with captive resin operations.
Nanocomposite silica dispersion in solvent-cast films is electrifying optical clarity benchmarks for micro-LED and OLED backplanes. Korean display manufacturers are accelerating qualification timelines from 18 to 9 months to secure supply ahead of capacity constraints. This compression is electrifying tier-two converters into equipment upgrade decisions they cannot defer without losing panel maker approval status.
REACH authorization requirements for halogenated flame retardants are forcing laminated grade reformulations across European electronics supply chains. ECHA's 2025 sunset dates for legacy chemistries are compressing alternative development timelines. Medical device film suppliers are responding fastest, leveraging existing FDA biocompatibility dossiers to pivot industrial grades toward safer additive packages.
Direct substrate procurement from resin producers is displacing distributor intermediaries in high-volume thermal film categories. Panel manufacturers in Taiwan and automotive tiers in Germany are consolidating purchase orders to capture volume pricing and technical service integration. South Korea's display cluster exhibits this pattern most acutely, with Samsung Display and LG Display operating vendor-managed inventory programs that bypass traditional converter channels entirely.
Isotropic Film Market Segmentation
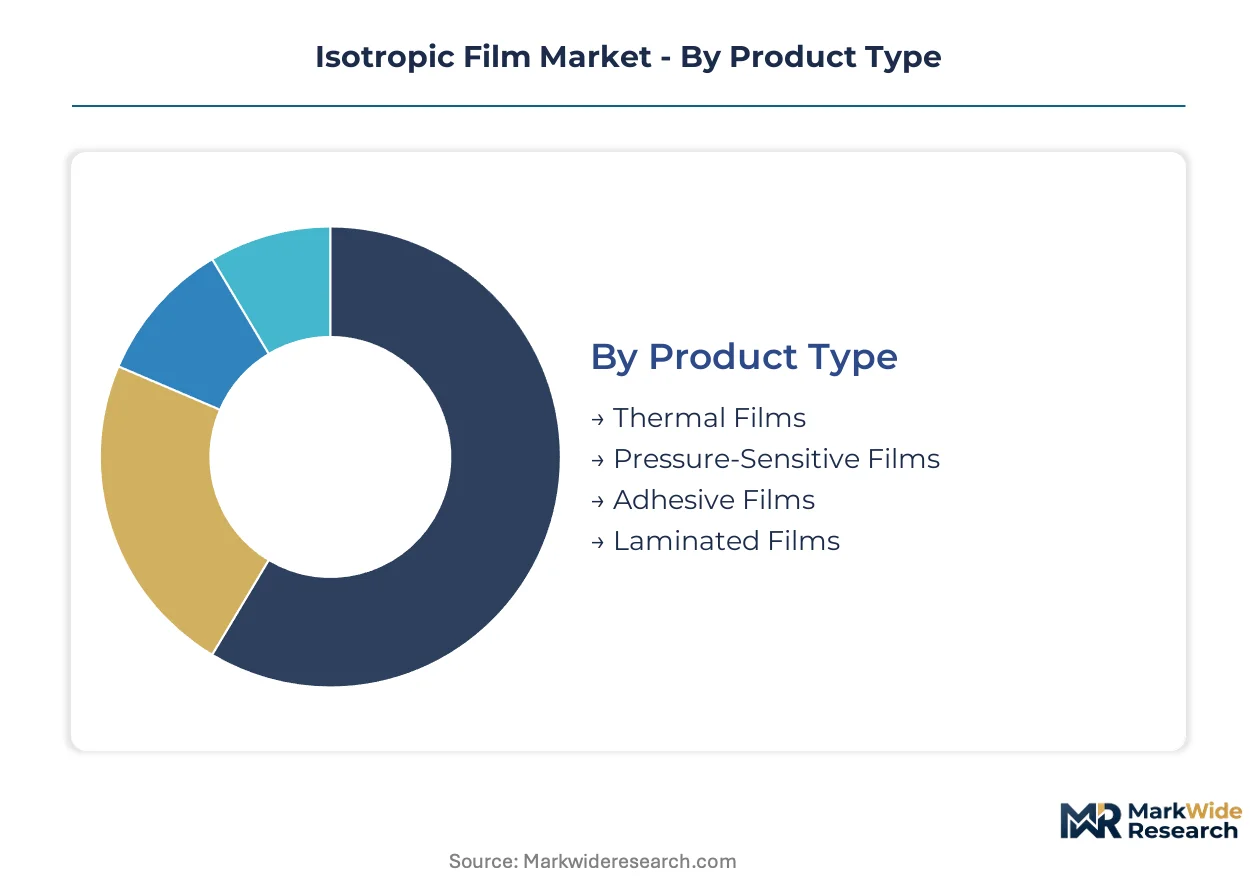
Isotropic film specifications diverge sharply across thermal management, optical clarity, and regulatory compliance requirements. Each segment carries distinct capital intensity and qualification timelines that reshape procurement patterns among display manufacturers and automotive tiers.
Product Type:
Equipment upgrade cycles for biaxial stretching lines are forcing converters to specialize around performance tiers rather than maintaining broad product portfolios.
- Thermal Films:PET and PEN substrates engineered for heat dissipation in display backlights and power electronics. Samsung Display and LG Display in South Korea consume the majority of sub-1.0% haze thermal grades for OLED panels, pulling supply into vendor-managed inventory arrangements that bypass traditional distribution.
- Pressure-Sensitive Films:Acrylic and silicone adhesive layers laminated to isotropic bases for temporary bonding in semiconductor fabrication. Taiwan's wafer processing fabs are qualifying these films for advanced packaging steps, though REACH restrictions on halogenated chemistries are compressing formulation timelines.
- Adhesive Films:Structural bonding layers for automotive HUD stacks and medical device assembly.
- Laminated Films:Multi-layer constructions combining barrier and optical functions for photovoltaic backsheets.
Volume placements concentrate in Thermal Films; the faster expansion belongs to Pressure-Sensitive Films as semiconductor packaging demand accelerates.
Technology:
Cost tiers separate commodity extrusion from premium solvent-cast processes, with nanocomposite grades commanding multiples over standard polymer formulations.
- Polymer-Based:Biaxially stretched PET and COP substrates serving as the volume foundation for display and electronics applications. South Korean and Japanese producers control the majority of sub-0.3% haze capacity, creating geographic supply concentration that panel makers manage through long-term offtake agreements.
- Nanocomposite:Silica-dispersed solvent-cast films achieving planar uniformity below 0.1% haze for micro-LED backplanes. Korean display manufacturers have compressed qualification timelines to secure supply ahead of capacity constraints, electrifying equipment upgrade decisions among tier-two converters.
- Metal-Coated:Vacuum-deposited aluminum or silver layers for reflective and EMI shielding functions.
- Biodegradable:PLA and PHA formulations responding to EU Green Deal packaging mandates for consumer electronics end-of-life streams.
Revenue concentrates in Polymer-Based grades; Nanocomposite technology is climbing the fastest as OLED and micro-LED fabrication demands sub-micron planar uniformity.
End User:
Customer type determines margin structure, with medical device qualifications offering premium pricing outside commodity electronics cycles.
- Electronics Sector:Display panel manufacturers and semiconductor fabs consuming thermal and optical-grade substrates for backlight units, touch sensors, and wafer processing. Taiwan and South Korea anchor demand, with direct procurement from resin producers displacing distributor intermediaries in high-volume categories.
- Medical Devices:Diagnostic strip and point-of-care device manufacturers requiring FDA biocompatibility certification. These applications open margin-rich volumes outside commodity pricing, with existing FDA dossiers enabling fastest pivot from industrial grades toward safer additive packages.
- Automotive Manufacturers:Tier-one suppliers in Germany specifying isotropic base layers for head-up display stacks and interior lighting.
- Packaging Industry:Consumer electronics and pharmaceutical blister pack applications facing tightening recyclability thresholds.
Shipment volumes concentrate in Electronics Sector demand; Medical Devices deliver the steepest expansion trajectory as point-of-care diagnostic adoption broadens.
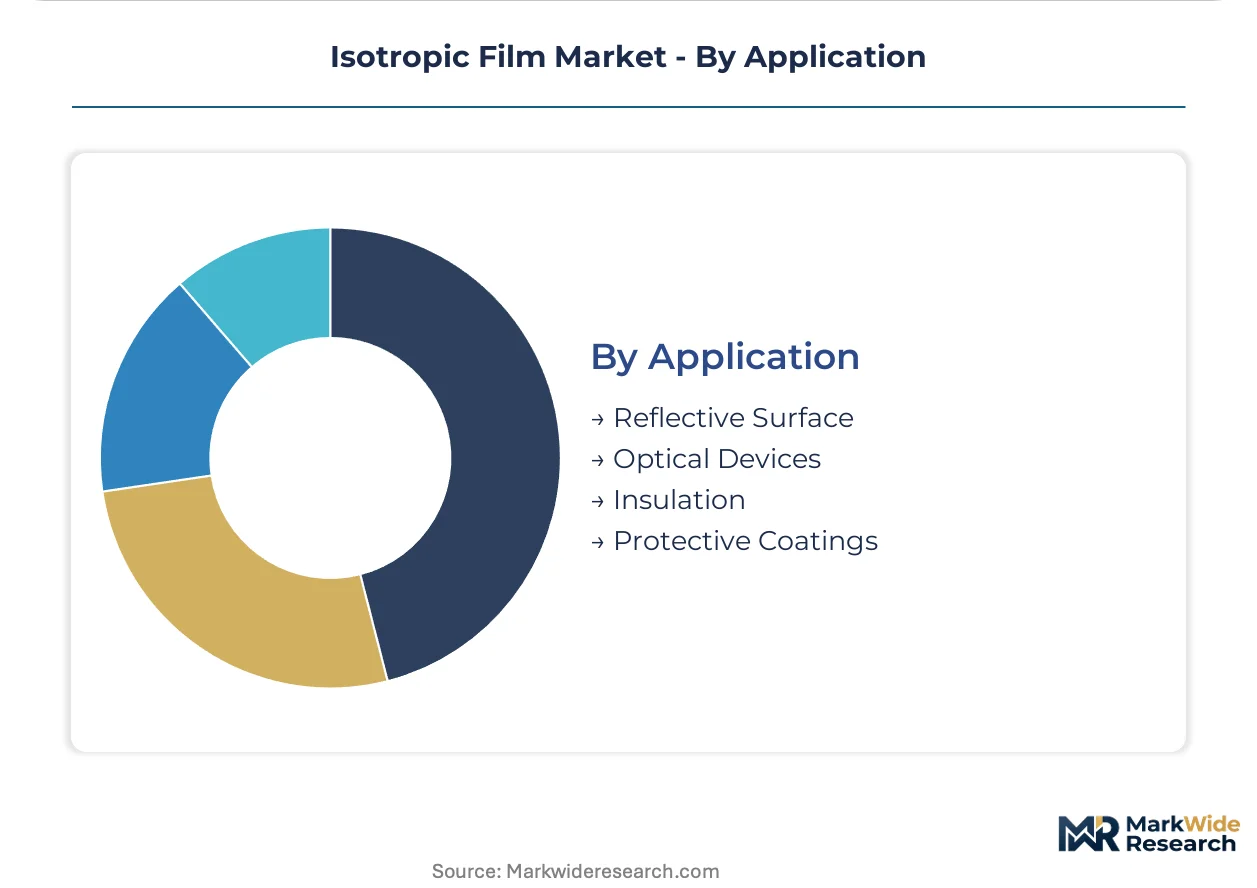
Application:
Maturity gradients separate established insulation and coating functions from emerging optical device requirements with tighter specification windows.
- Optical Devices:Polarizer substrates, waveguide layers, and micro-LED backplanes requiring sub-micron thickness tolerance and sub-0.3% haze. Biaxial stretching equipment upgrades across East Asian producers are compressing planar uniformity tolerances, forcing mid-tier converters to absorb capital costs or exit supply.
- Reflective Surface:Head-up display combiners and lighting reflectors in automotive cockpit systems. Germany's tier-one suppliers are extending film consumption beyond traditional electronics into vehicle systems, with HUD proliferation pulling optical-grade specifications into automotive supply chains.
- Insulation:Thermal barrier layers for battery packs and power electronics.
- Protective Coatings:Scratch-resistant and chemical barrier films for display covers and touch panels.
Volume concentrates in Reflective Surface applications; Optical Devices are gaining share fastest as micro-LED fabrication ramps displace legacy LCD architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in East Asia while consumption spreads across display and automotive hubs in Germany, South Korea, and the United States. This geographic split creates supply chain vulnerabilities that panel manufacturers manage through long-term offtake agreements and vendor-managed inventory programs.
South Korea
Samsung Display and LG Display consume the majority of sub-1.0% haze thermal grades for OLED panels. MFDS biocompatibility pathways enable fastest pivot toward medical-grade formulations. The Gyeonggi-do cluster around Suwon and Paju anchors biaxial stretching capacity that panel makers access through direct procurement channels bypassing traditional converters.
Germany
Tier-one automotive suppliers specify isotropic base layers for head-up display stacks and interior lighting systems. REACH authorization requirements for halogenated flame retardants compress reformulation timelines for laminated grades. The Baden-Württemberg corridor from Stuttgart to Karlsruhe concentrates HUD component engineering that pulls optical specifications into vehicle cockpit supply chains.
United States
Medical device manufacturers drive FDA biocompatibility qualification for diagnostic strip substrates outside commodity electronics pricing. EPA toxicity thresholds fragment qualification protocols between industrial and medical applications. The Pacific Northwest and Greater Boston corridors host point-of-care device startups expanding film consumption in regulated healthcare segments.
Japan
Equipment manufacturers supply precision biaxial stretching lines that compress planar uniformity tolerances below 0.3% haze. METI technology roadmaps prioritize nanocomposite dispersion methods for next-generation display backplanes. The Chubu region around Nagoya anchors machinery production that East Asian converters depend on for optical-grade capacity upgrades.
Taiwan
Wafer processing fabs qualify pressure-sensitive adhesive films for advanced semiconductor packaging steps. The Hsinchu Science Park concentration of foundries and OSATs pulls substrate demand into 3D integration and fan-out wafer-level packaging applications.
Isotropic Film Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across thermal management, optical clarity, and medical-grade tiers. The vendor base stratifies into three strategic archetypes: resin-integrated producers with captive polymer synthesis, equipment-integrated converters controlling biaxial stretching capacity, and formulation specialists pivoting toward biodegradable and nanocomposite grades. Dominant competitive moves include direct substrate procurement relationships displacing distributor intermediaries, and equipment upgrade partnerships between machinery suppliers and tier-two converters facing qualification timeline compression.
Among Japan-based chemical conglomerates, Toray Industries and Mitsubishi Chemical Group exemplify resin-integrated archetypes with upstream control over polymer synthesis. DuPont Teijin Films anchors North American positioning through integrated PET resin operations. These three occupy positions across the thermal-optical grade spectrum where captive supply chains sustain cost discipline against feedstock volatility.
| Leading Market Players |
|---|
| Toray Industries |
| DuPont Teijin Films |
| Mitsubishi Chemical Group |
| Polyplex Corporation |
| BASF SE |
| Kuraray Co., Ltd. |
| Jindal Poly Films |
| 3M |
| Kolon Industries |
| Others |
Pricing and Supply Chain Analysis
Specialized interferometric haze measurement technicians concentrated in Japan's Chubu region command wage premiums that propagate through optical-grade film pricing, widening spreads between premium nanocomposite tiers and commodity thermal grades sourced from lower-labor-cost extrusion hubs.
Pricing Analysis
Margin tightening in optical-grade tiers reflects biaxial stretching equipment upgrade costs that South Korean and Japanese producers pass through to display panel manufacturers. Three-tier pricing structure across premium nanocomposite, standard optical, and economy thermal levels separates sub-0.3% haze qualifications from commodity backlight applications. Cost-down pressure on mid-tier converters accelerates because Samsung Display and LG Display consolidate purchase orders for direct procurement volume discounts. Medical device manufacturers exhibit lowest price sensitivity due to FDA biocompatibility certification requirements that lock in qualified suppliers.
Supply Chain Analysis
Dual-sourcing mandates from Taiwan's wafer processing fabs and Germany's automotive tier-ones compel substrate producers to qualify secondary biaxial stretching lines in Japan and South Korea. Raw material dependencies on purified terephthalic acid and ethylene glycol from petrochemical complexes in South Korea and Japan tether margin predictability to feedstock volatility. Single-source vulnerability concentrates in sub-0.3% haze capacity controlled by Toray Industries and Mitsubishi Chemical Group. Distribution runs through vendor-managed inventory programs that Samsung Display and LG Display operate directly with resin-integrated producers, bypassing traditional converter intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
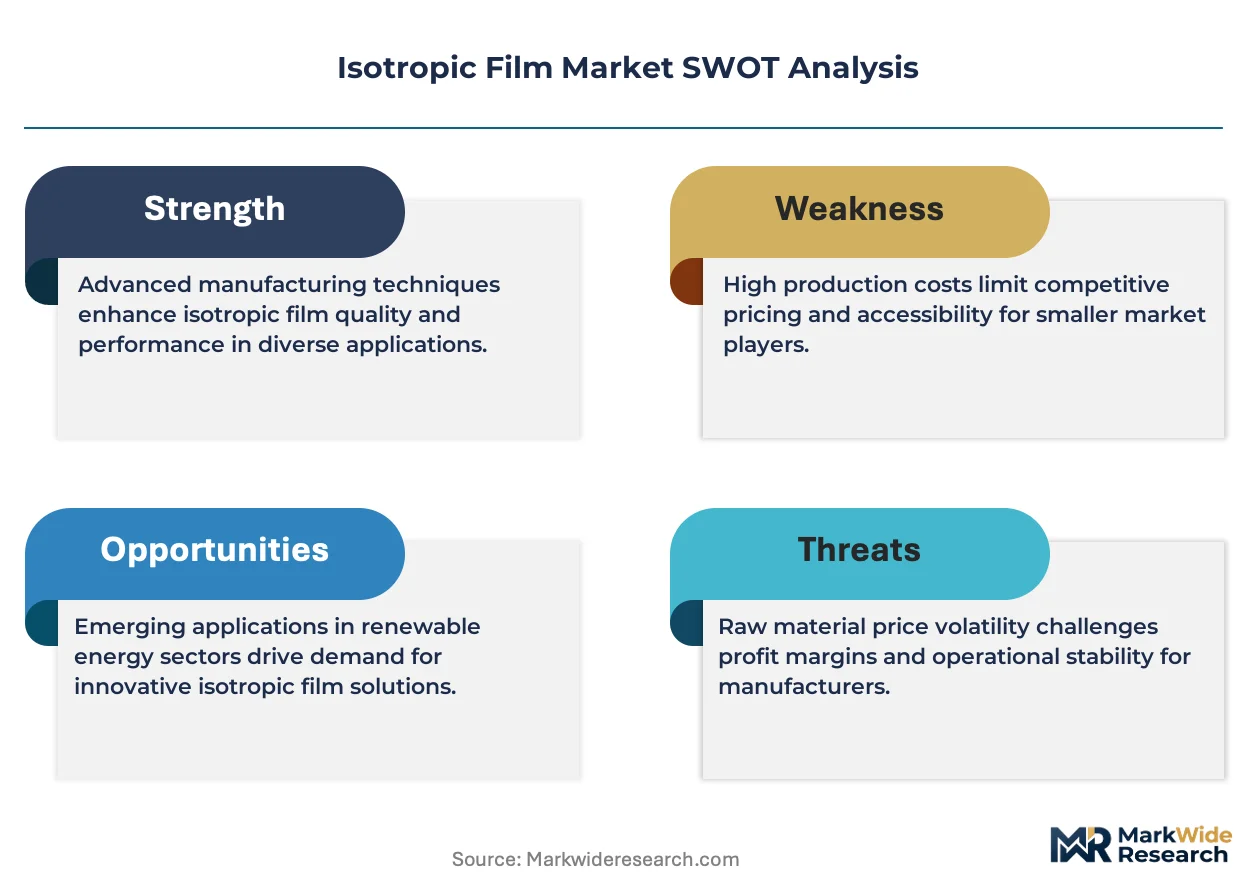
REACH authorization timelines for halogenated flame retardants erect a cost-of-compliance barrier that rewards incumbent film suppliers with existing ECHA dossiers and punishes late entrants facing compressed reformulation deadlines.
For Market Incumbents: Anticipate nanocomposite qualification timeline compression from Korean display manufacturers by securing captive silica dispersion partnerships before equipment capacity constraints harden. Defend optical-grade positioning through backward integration into biaxial stretching machinery supply relationships with Japan's Chubu equipment cluster. Counter emerging biodegradable film entrants by leveraging existing FDA biocompatibility pathways to pivot industrial grades toward medical device applications. For New Entrants and Emerging Players: Direct-to-device-manufacturer digital qualification platforms offer route-around access to point-of-care diagnostic startups in the United States Pacific Northwest corridor. Target India's PLI-subsidized display and semiconductor fabs as the most penetrable geography for substrate qualification programs outside saturated East Asian supplier lists. Lead with solvent casting technology convergence pitches that bridge nanocomposite optical clarity with biodegradable polymer research to differentiate from conventional extrusion incumbents. For Investors and Strategic Acquirers: The window for entry favors equipment-integrated converters with sub-0.3% haze capacity in South Korea or Japan. Long-term viability rests on positioning ahead of micro-LED fabrication ramp demand inflection. Watch for biaxial stretching line order backlogs at Japanese machinery producers as the signal that panel manufacturer qualification compression has triggered irreversible capacity expansion commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Toray Industries sustains cost discipline against PTA and ethylene glycol feedstock volatility through captive resin operations. |
| Equipment Upgrade Partnership | Tier-two converters secure Japanese machinery supplier technical service integration to meet Samsung Display's compressed qualification timelines. |
| Biodegradable Formulation Pivot | PLA and PHA film producers capture EU Green Deal packaging mandate share ahead of Brussels recyclability threshold enforcement. |
| Medical Device Certification Investment | FDA biocompatibility dossiers enable fastest pivot from industrial grades toward margin-rich point-of-care diagnostic strip applications. |
| Direct Procurement Channel Establishment | Vendor-managed inventory programs with LG Display bypass traditional converter intermediaries in high-volume thermal film categories. |
Research Methodology
Document review covered customs and trade data from South Korea and Japan, SEC 10-K filings from resin-integrated producers, and ECHA REACH authorization databases, complemented by interviews with biaxial stretching equipment engineers, display panel procurement managers, medical device regulatory affairs leads, and automotive tier-one substrate specification engineers. Bottom-up demand modeling from individual application segments triangulated against top-down value chain analysis from purified terephthalic acid feedstock through laminated film conversion.
Historical capacity utilization patterns from Japanese machinery producers cross-referenced against panel manufacturer qualification timeline inputs from South Korea and Taiwan. Segmentation dimensions modeled include film grade tier, fabrication technology, end-use sector, and regional regulatory cluster. CAGRs derived from equipment order backlogs and long-term offtake agreement disclosures. Forecast inputs incorporated micro-LED fabrication ramp schedules and EU Green Deal packaging mandate implementation trajectories.
The model holds under stable petrochemical feedstock pricing and REACH authorization timeline adherence; deviation in biaxial stretching equipment delivery delays or ECHA sunset date acceleration would shift capacity expansion assumptions materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Poland Plastic Packaging Films Market
Poly film
LDPE Films Market
Poly film
Nylon Films Market
Poly film
Starch-Based Plastic Films Market
Poly film
Polyethylene Furanoate Films Market
Poly film
India BOPP Films Market
Poly film
India Plastic Packaging Film Market
Poly film
Poly Coated Paper Market
Poly film
Polyvinyl Alcohol (PVA) Films Market
Poly film
Multi-Layer Blown Films Market
Poly film
Polysaccharide Films Market
Poly film
Cleanroom Film and Bags Market
Poly film
North America Polyimide Films Market
Poly film
Lidding Films Market
Poly film
UAE Plastic Packaging Films Market
Poly film
Resealable Films Market